

World Acceptance: Underwriting and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
World Acceptance Strategy Analysis Bundle
World Acceptance refers here to WORLD ACCEPTANCE CORP., the SEC reporting company classified as a Personal Credit Institution. The business context for this bundle centres on consumer lending: assessing how loans are positioned, distributed and managed for borrowers, including the role that repeat customers, responsible borrowing communication and possible loan-linked insurance arrangements can play in the customer experience and operating model.
In its 10-Q filed August 6, 2026, WORLD ACCEPTANCE CORP. reported revenue of USD 139.2 million and GAAP net income of USD 6.1 million for April 1 through June 30, 2026. Those quarterly figures make questions about portfolio priorities, lending economics and regulatory pressures especially practical to examine; they do not indicate that the downloadable analysis files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending products, borrower groups or delivery routes deserve attention when growth potential must be weighed against relative market share?
The World Acceptance BCG Matrix provides a disciplined way to compare potential portfolio areas rather than assuming that all lending activity merits the same resources. It uses market growth and relative market share to frame possible Stars, Cash Cows, Question Marks and Dogs. For a personal-credit business, the useful comparison may involve loan types, repeat-borrower propositions, branch-led service or digital acquisition activity. The purpose is not to assign an unverified quadrant, but to make the evidence required for a resource-priority discussion visible.
- Portfolio logic. Compare where demand, competitive position, servicing effort and credit risk may point in different directions.
- Capital attention. Consider how higher-growth opportunities could affect underwriting capacity, collections resources and compliance oversight.
- Structured comparison. Use the Excel framework to organize candidate areas and the Word analysis to interpret the assumptions behind each comparison.
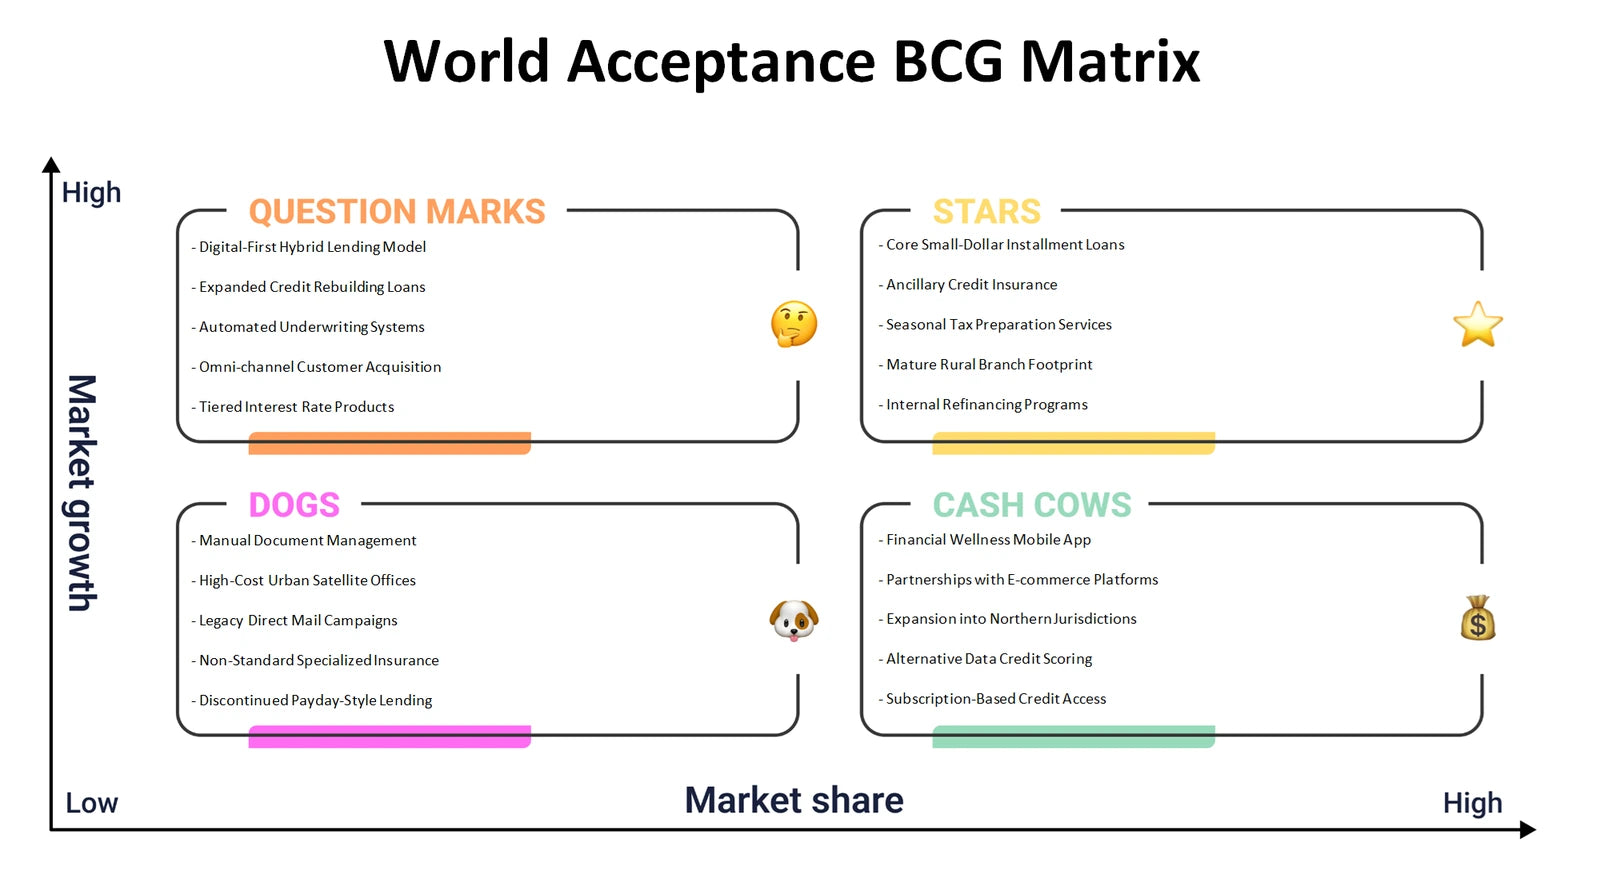
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer access, responsible lending service and loan economics connect in one operating model?
The World Acceptance Business Model Canvas examines the nine linked building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In this setting, it helps connect borrower needs with origination and servicing channels, returning-customer relationships and the economics of lending. It can also test how insurance-carrier arrangements, financial education materials and disclosure responsibilities may affect value delivery, non-interest revenue questions, operating work and customer trust without treating any one feature as a proven advantage.
- Value exchange. Trace how convenient access, understandable terms and borrower support may relate to customer retention and repayment quality.
- Economic links. Examine the relationship among loan revenue, possible commission income, funding and operating costs, underwriting and servicing activities.
- Model mapping. Populate the Excel canvas systematically, then use the Word analysis to assess tensions between growth, affordability, risk controls and cost structure.
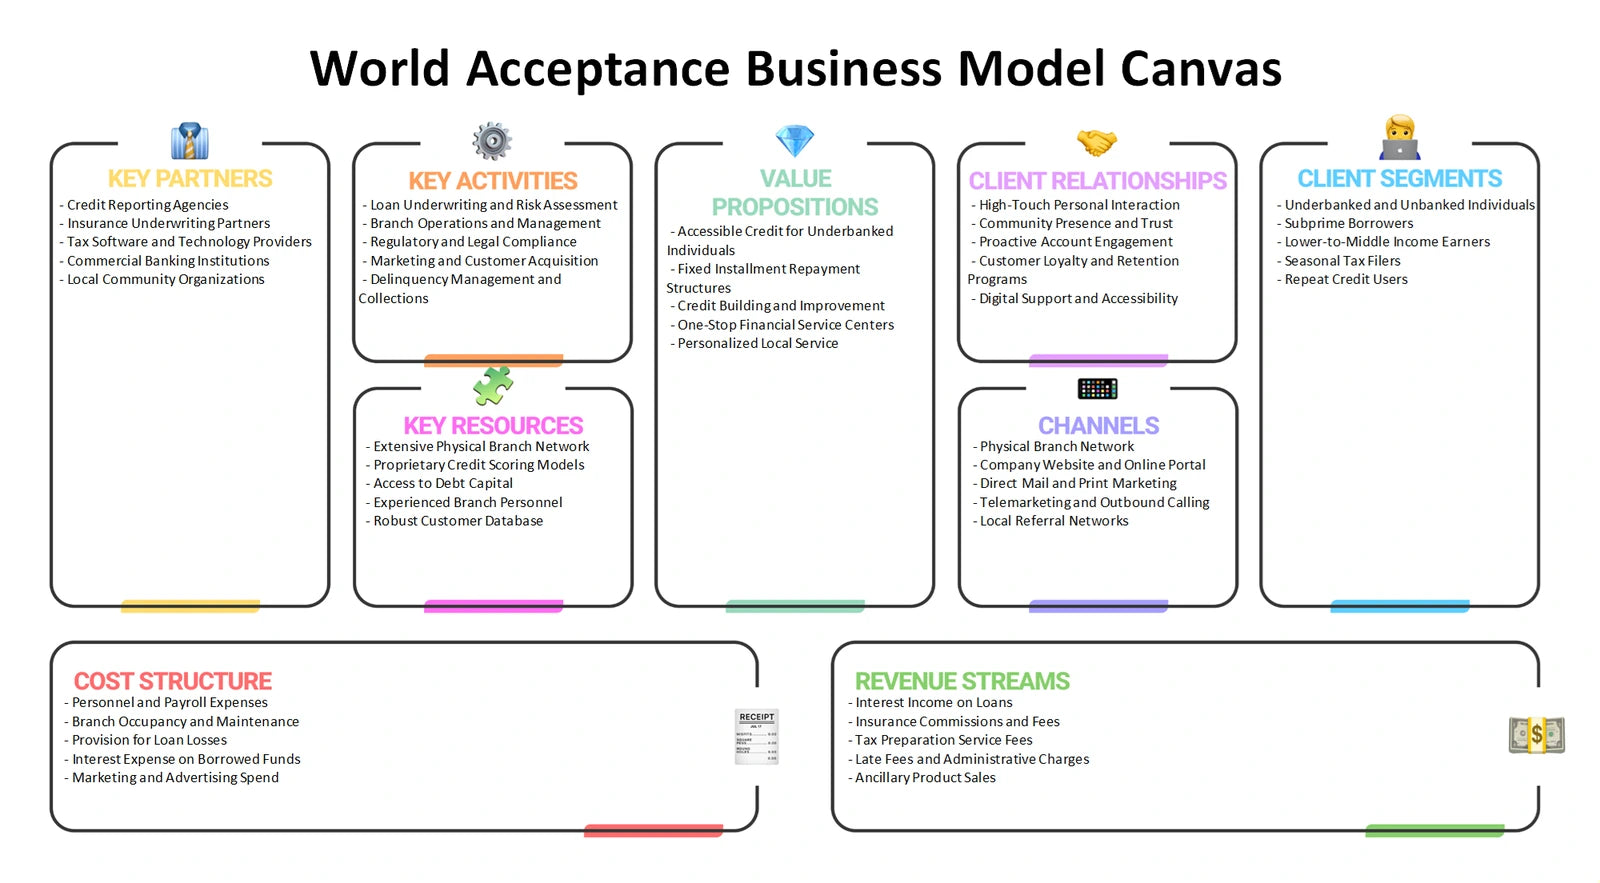
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape the attractiveness and resilience of consumer lending economics?
World Acceptance Porter's Five Forces focuses on the structure around a personal-credit institution rather than on a list of named competitors. Rivalry can influence borrower acquisition and renewal terms; supplier power can include the availability and cost of funding, technology and specialist services; and buyer power reflects customers' ability to compare credit choices. The framework also considers barriers facing new entrants and substitutes such as other regulated credit products, community-based alternatives or delayed purchasing. These forces matter because they can alter margins, borrower expectations and the cost of maintaining a compliant lending operation.
- Competitive pressure. Assess how lenders may compete for eligible borrowers while managing credit quality and responsible underwriting standards.
- Dependency exposure. Explore reliance on capital providers, data tools, insurance partners or other inputs that may influence operating flexibility.
- Evidence-led review. Use Excel to record force-specific observations and the Word analysis to connect those observations to strategic questions for management review.
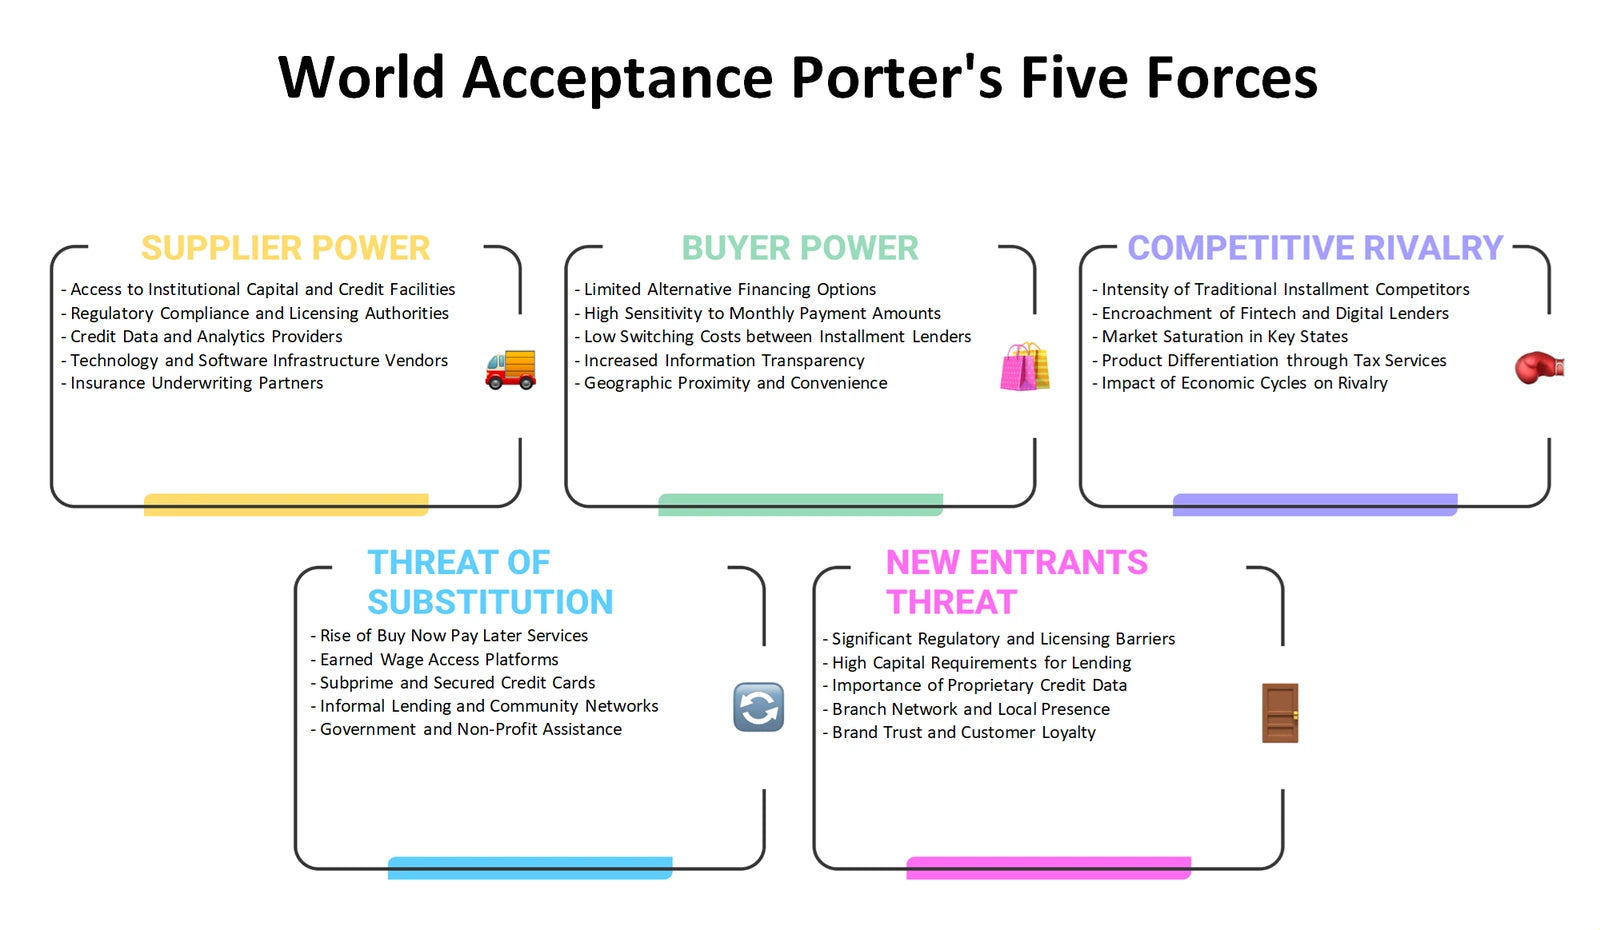
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a consumer lender align its offer, terms, access points and communications with borrower needs and regulatory expectations?
The World Acceptance Marketing Mix considers Product, Price, Place and Promotion in a regulated lending context. Product analysis can distinguish the loan experience, repayment support and relevant ancillary services from a generic consumer offer. Price examines the clarity and affordability implications of rates, fees and any optional add-ons rather than inventing a pricing level. Place addresses the role of branch interactions and digital materials in reaching and serving customers. Promotion considers how education, disclosures and acquisition messages should communicate value without encouraging unsuitable borrowing.
- Product clarity. Examine which service features help borrowers understand the loan, repayment obligations and available support.
- Channel discipline. Compare how physical and digital touchpoints may affect convenience, verification, disclosures and relationship continuity.
- Mix planning. Use the Excel framework to organize the four decisions, then consult the Word analysis when evaluating consistency across customer communications.
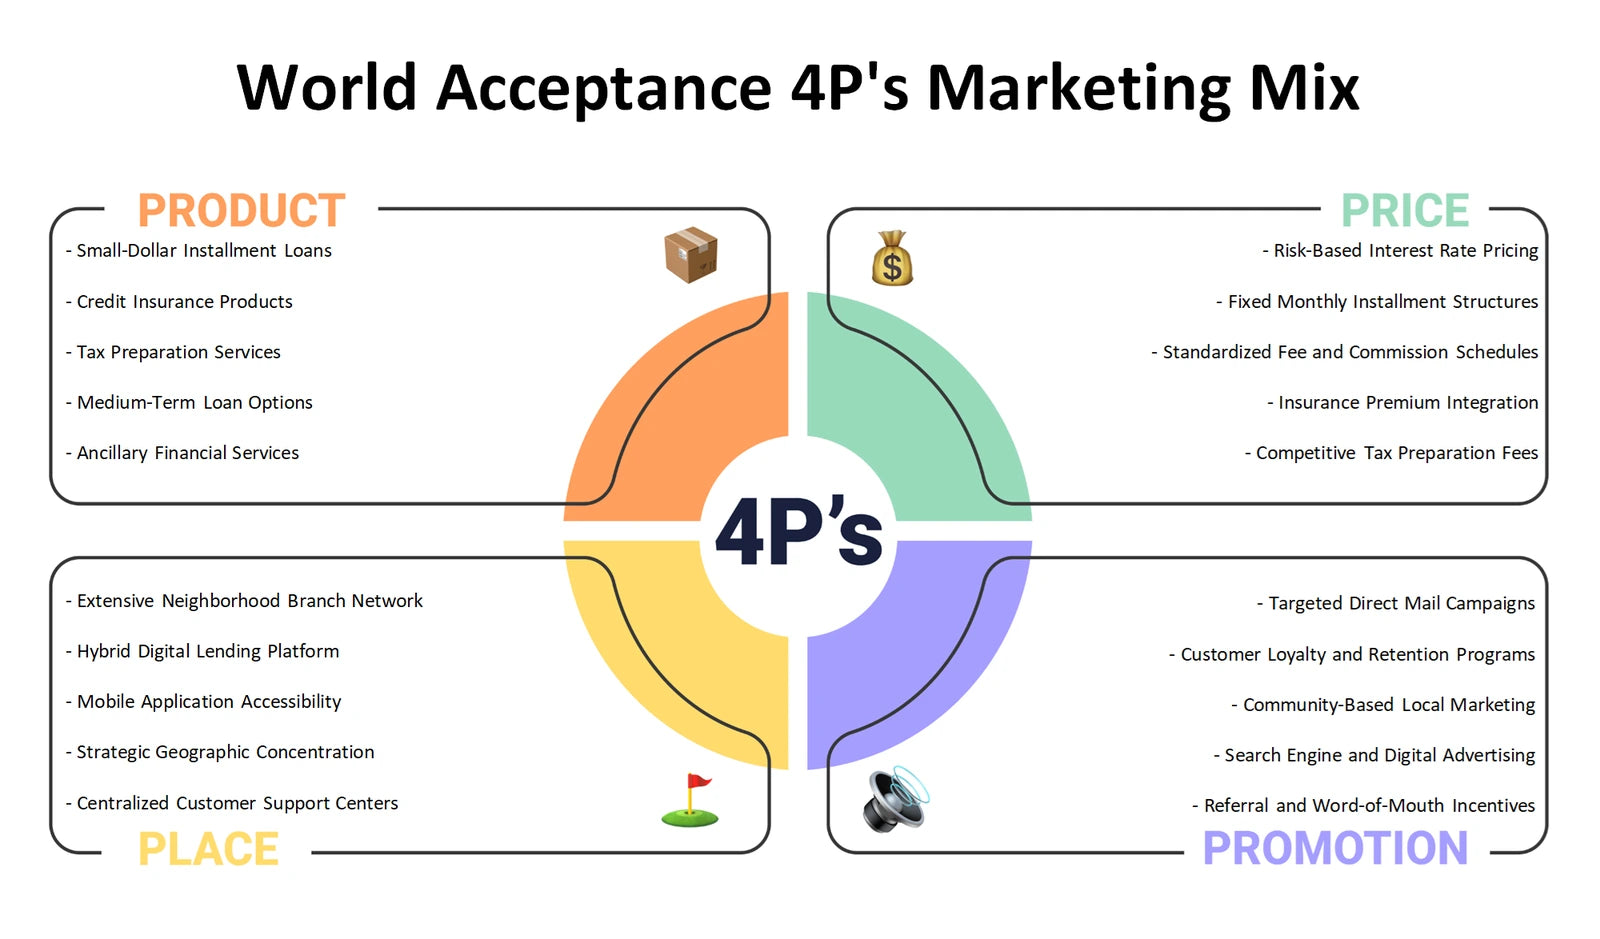
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should a personal-credit business monitor before they affect demand, cost, operations or compliance?
The World Acceptance PESTLE analysis, also commonly called PESTEL, organizes Political, Economic, Social, Technological, Legal and Environmental influences around consumer lending. Political and legal factors can include policy direction, consumer-protection expectations and disclosure requirements. Economic conditions may influence household cash flow, repayment capacity and funding questions. Social attitudes toward debt and financial education can affect trust, while technology changes can reshape application, verification and servicing processes. Environmental considerations may be indirect but still relevant where physical operations, customer resilience or paper-intensive processes face disruption.
- Regulatory horizon. Distinguish a policy or legal issue to monitor from an asserted new rule, keeping the analysis grounded in verified evidence.
- Customer conditions. Consider how broader household pressures and changing credit preferences may alter borrower needs and risk signals.
- External watchlist. Use Excel to categorize developments by PESTLE factor and the Word analysis to explore why each factor could matter operationally.
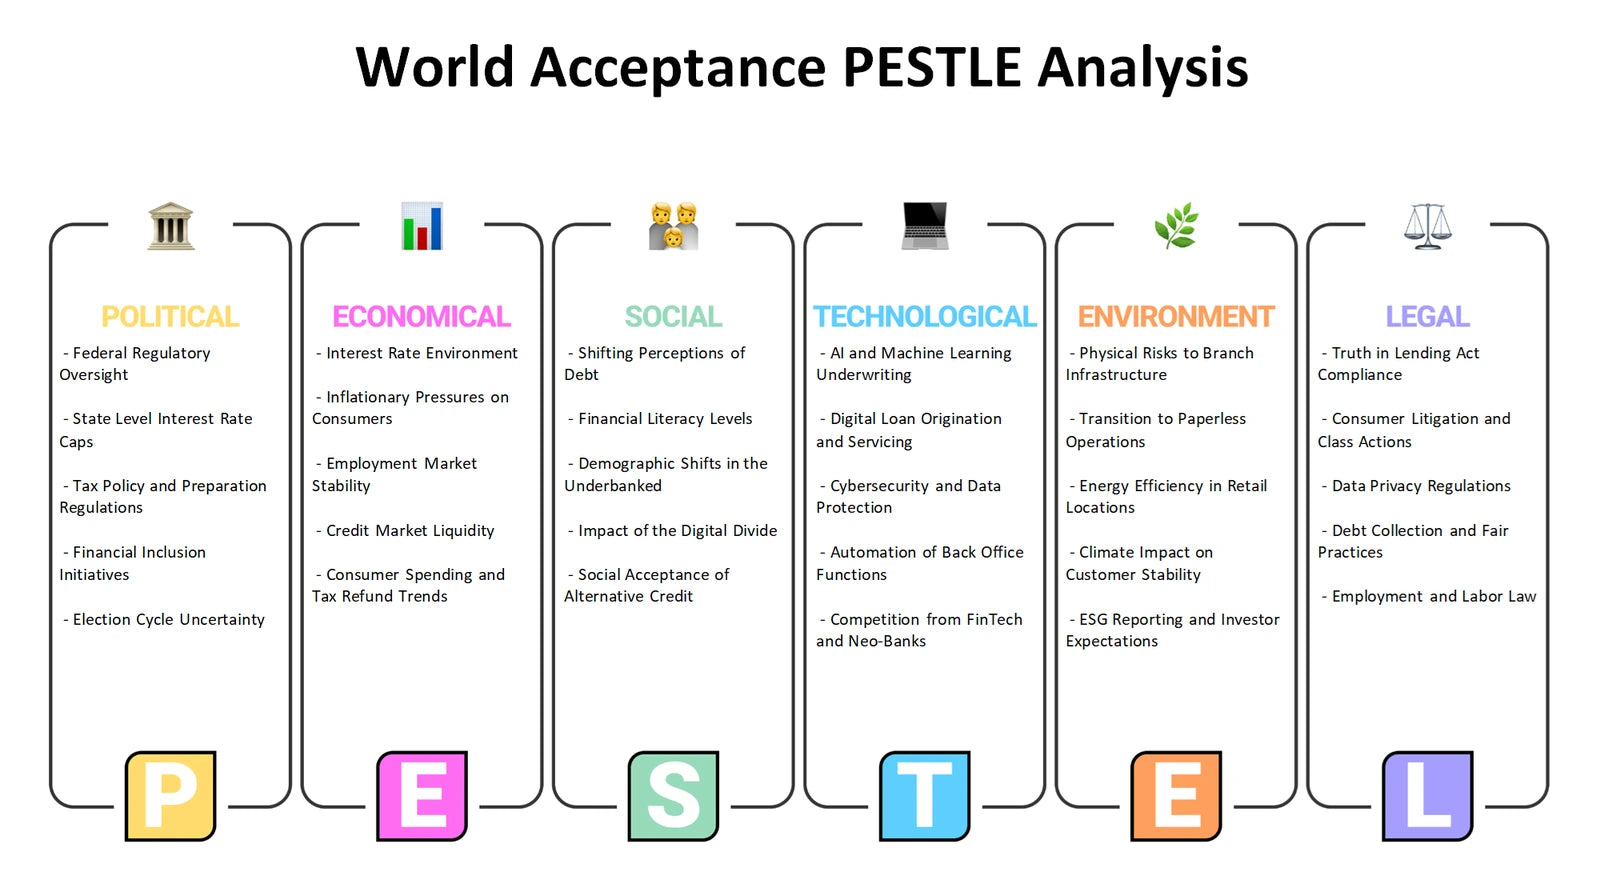
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside external opportunities and threats in consumer lending?
The World Acceptance SWOT analysis keeps internal Strengths and Weaknesses separate from external Opportunities and Threats. It can help examine potential internal themes such as repeat-borrower servicing knowledge, underwriting processes, customer communication practices, partner management and compliance capacity. It then sets those possible capabilities and limitations against external conditions such as changing borrower needs, credit alternatives, technology expectations and regulatory scrutiny. This distinction is valuable because a market opportunity is not automatically an internal strength, and a sector-wide threat may require a response that depends on evidence about the company's own resources.
- Internal reality. Test which operational capabilities, data practices and customer relationships are supported by evidence rather than assumed.
- External fit. Relate opportunities and threats to lending-market conditions without presenting plausible themes as established company results.
- Decision synthesis. Use the Excel matrix to separate categories and the Word analysis to develop informed links among risks, capabilities and priorities.
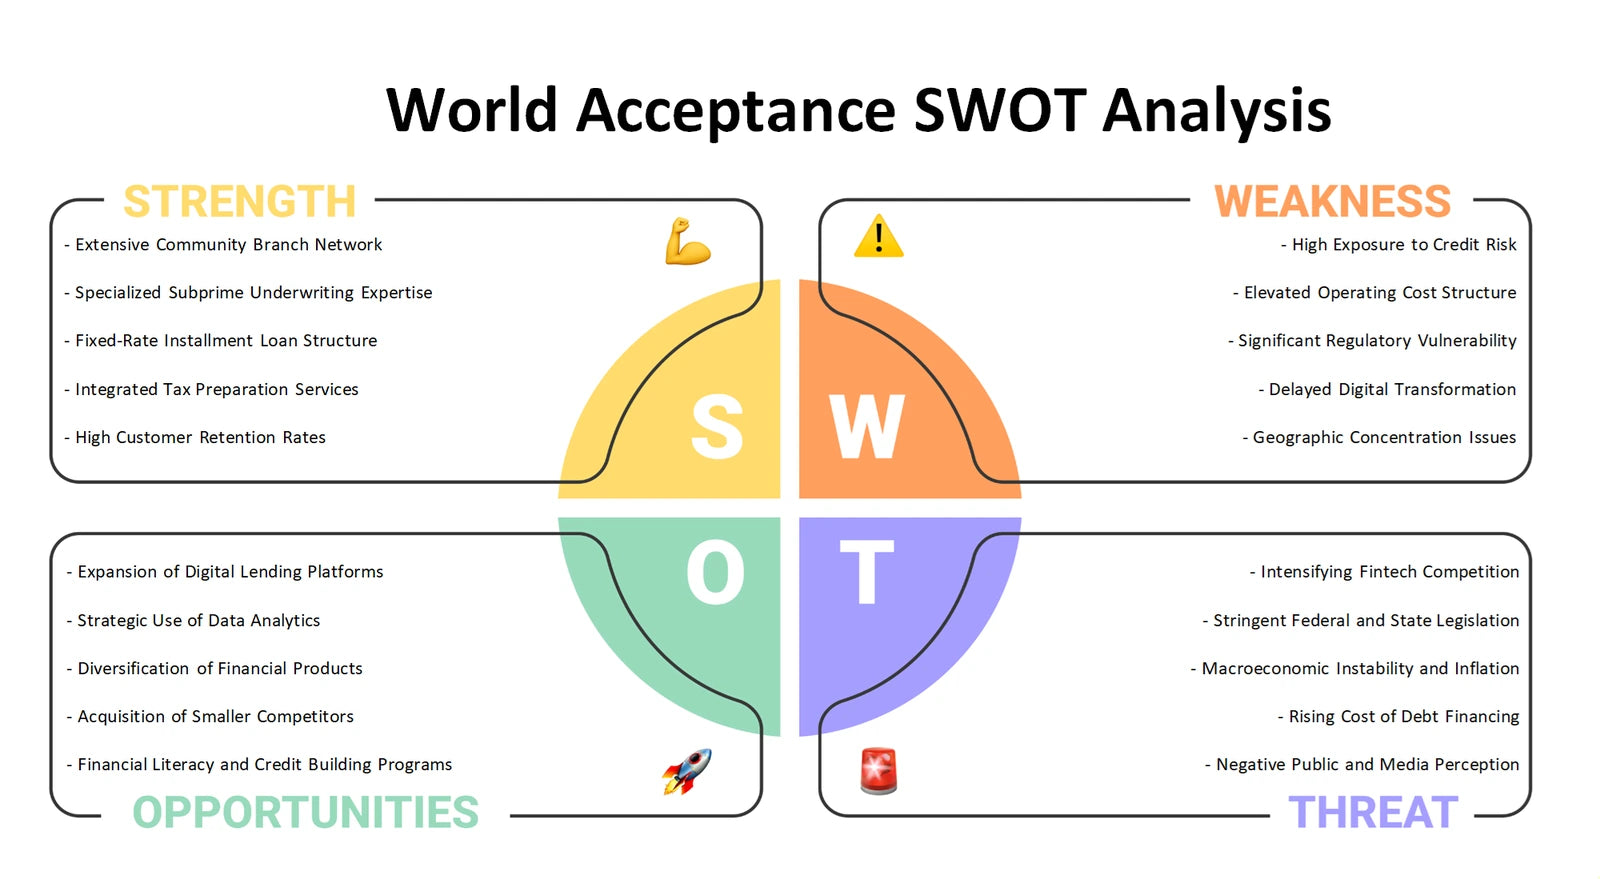
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with lending realities
Together, these six perspectives help turn a broad view of World Acceptance into connected strategic questions: what to prioritize, how the business model works, where industry pressure comes from, how customers are served, which external changes matter and how internal capabilities compare with market conditions. The Excel frameworks provide a structured way to organize the analysis, while the Word files provide detailed company-focused context for more informed discussion.
Company background: World Acceptance — SEC company submissions profile.