

loanDepot: Financial Services and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
loanDepot Strategy Analysis Bundle
loanDepot is the consumer-facing mortgage brand of LoanDepot, Inc., a United States mortgage holding company. The business serves homebuyers and homeowners seeking purchase mortgages or refinancing, with an online application journey and partner-led routes into the homebuying process. Its relevant strategic questions include how direct digital lending, homebuilder relationships and mortgage-servicing economics can work together across changing housing-market conditions.
In its Form 10-Q filed August 6, 2026, LoanDepot, Inc. reported a GAAP net loss of US$4.533 million for April 1 through June 30, 2026. In plain English, that quarterly loss makes capital discipline, channel productivity and the balance between origination volume and servicing-related value important topics to examine. The bundle provides structured lenses for exploring those questions without claiming that the downloadable files contain current financial forecasts.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending and servicing-related activities deserve resources when market growth and relative market share do not move together?
The loanDepot BCG Matrix helps organize possible portfolio priorities around two disciplined criteria: market growth and relative market share. Rather than assigning a quadrant without evidence, it provides a way to compare candidate activities such as purchase-lending pathways, refinancing demand, builder-linked origination channels and servicing-related economics. The familiar Stars, Cash Cows, Question Marks and Dogs categories are useful because a high-growth opportunity can still require funding, while a more established activity may be judged by cash contribution and resilience. For a mortgage business, this comparison matters when housing turnover, refinancing incentives and funding conditions can shift the usefulness of each channel.
- Portfolio boundaries. Separate customer routes and revenue-generating activities before comparing their market context and relative position.
- Resource tension. Consider where technology, marketing, relationship-management and capital capacity may face competing demands.
- Structured comparison. Use the Excel framework to map assumptions consistently, then use the detailed Word analysis to interpret the trade-offs behind each possible priority.
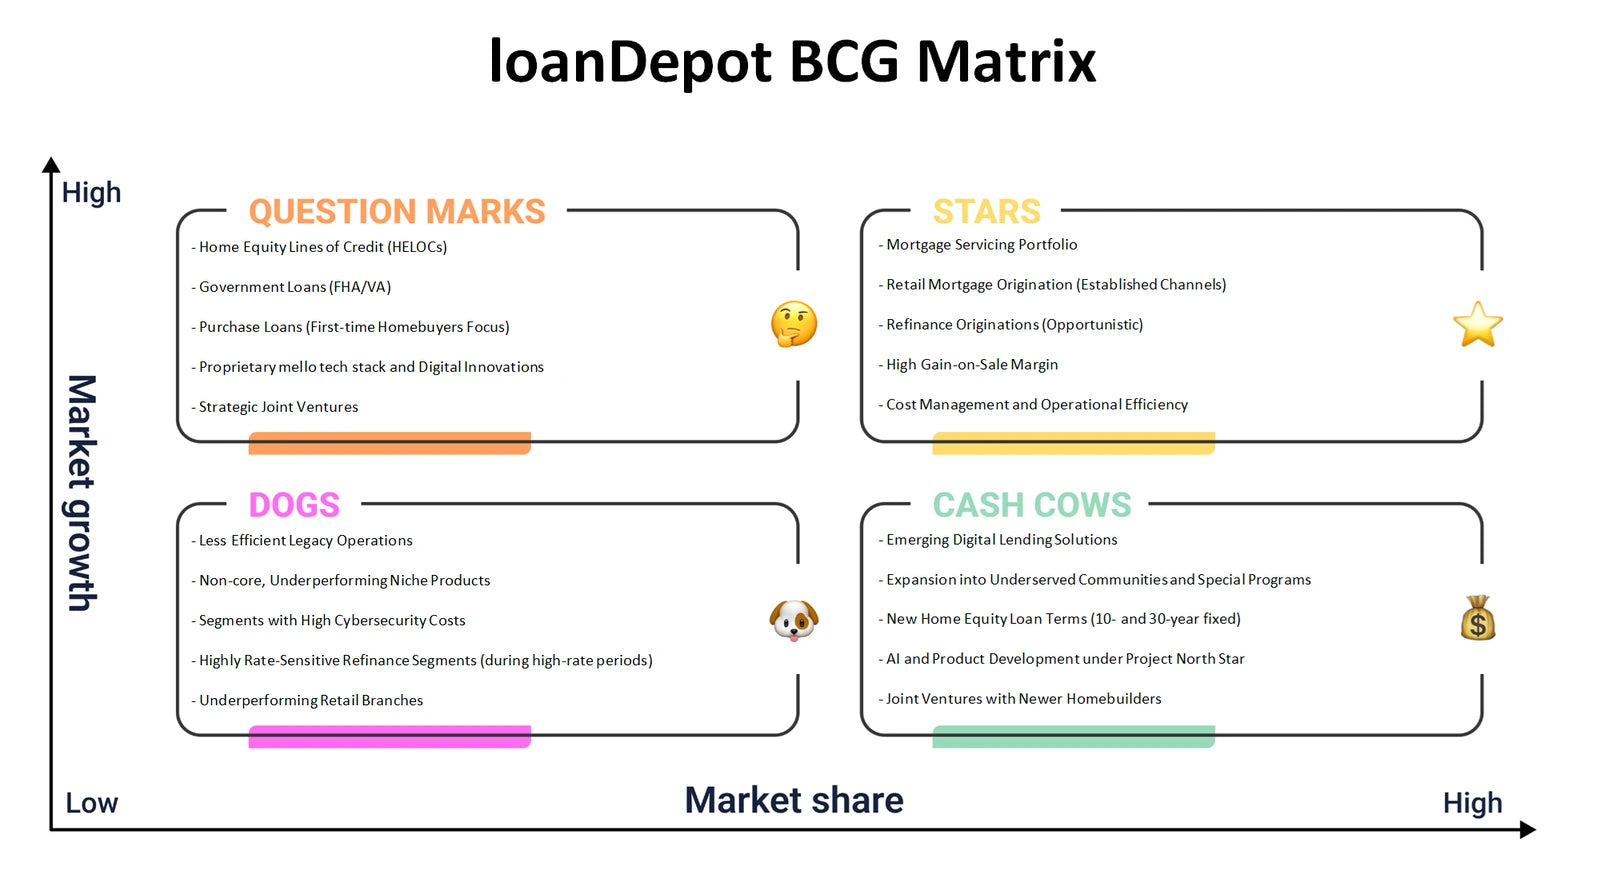
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do loanDepot's borrower experience, partner channels and mortgage economics connect into one workable operating model?
The loanDepot Business Model Canvas examines all nine building blocks together: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For this business, the useful connection is between borrowers seeking a simpler mortgage process, digital and partner-led access points, and the operational capabilities required to originate, fund and service loans. Homebuilder joint ventures can be assessed as partnerships and channels, while investors involved in mortgage servicing rights can be considered in relation to capital management and revenue logic. The Canvas does not presume that every relationship is equally valuable; it helps expose dependencies, handoffs and costs that must support the customer promise.
- Customer pathway. Trace how homebuyers and refinancing customers may move from discovery through application, closing and ongoing service.
- Economic links. Connect loan production, servicing-related activity, partner arrangements and the costs of compliance, technology and fulfillment.
- Model alignment. Populate the Excel blocks as a connected model and use the Word analysis to examine why changes in one block can affect several others.
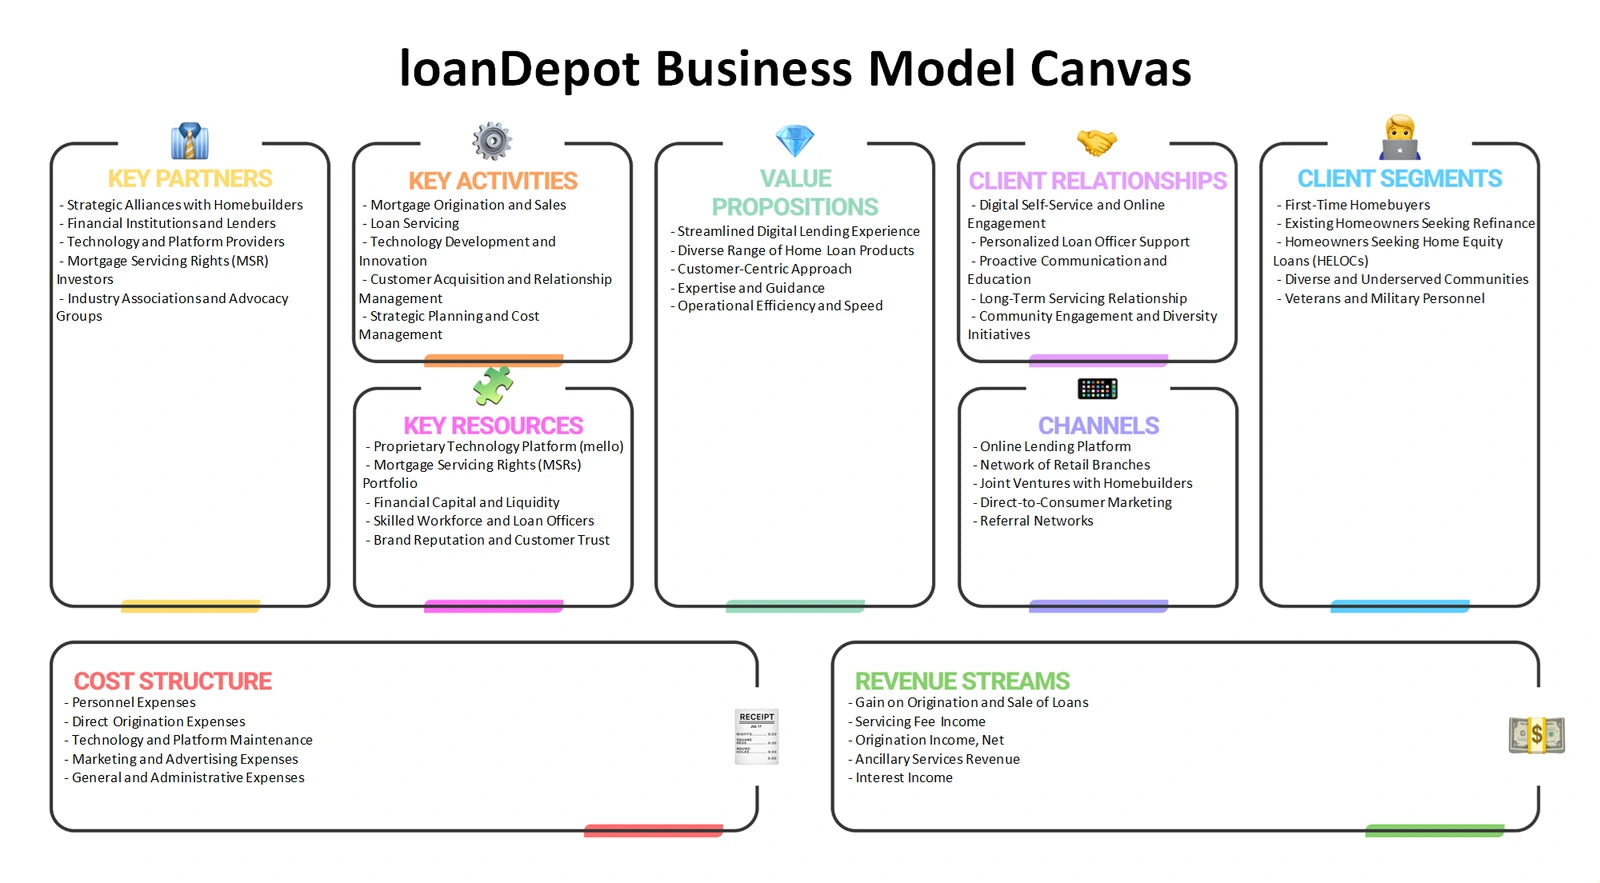
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape loanDepot's ability to attract borrowers, maintain margins and retain productive distribution channels?
loanDepot Porter's Five Forces frames the competitive environment around mortgage lending rather than treating demand as a standalone marketing issue. Rivalry can intensify when lenders compete for qualified borrowers and referral sources. Buyer power matters because customers can compare rates, fees, service expectations and application convenience. Supplier power includes the influence of funding providers, capital-market counterparties, technology suppliers and specialized labor. The threat of new entrants is constrained by licensing, compliance and capital needs, yet digital tools may lower some customer-acquisition barriers. Substitutes extend beyond direct lenders to alternatives such as using savings, delaying a transaction, changing the housing choice or seeking other financing arrangements.
- Margin pressure. Compare how rivalry and borrower price sensitivity may affect the economics of originating a mortgage.
- Dependency map. Identify where funding, capital-market access, referral relationships or external service providers can influence operating flexibility.
- Decision support. Use the Excel force-by-force structure to record evidence and questions, then consult the Word analysis for the implications of combined pressures.
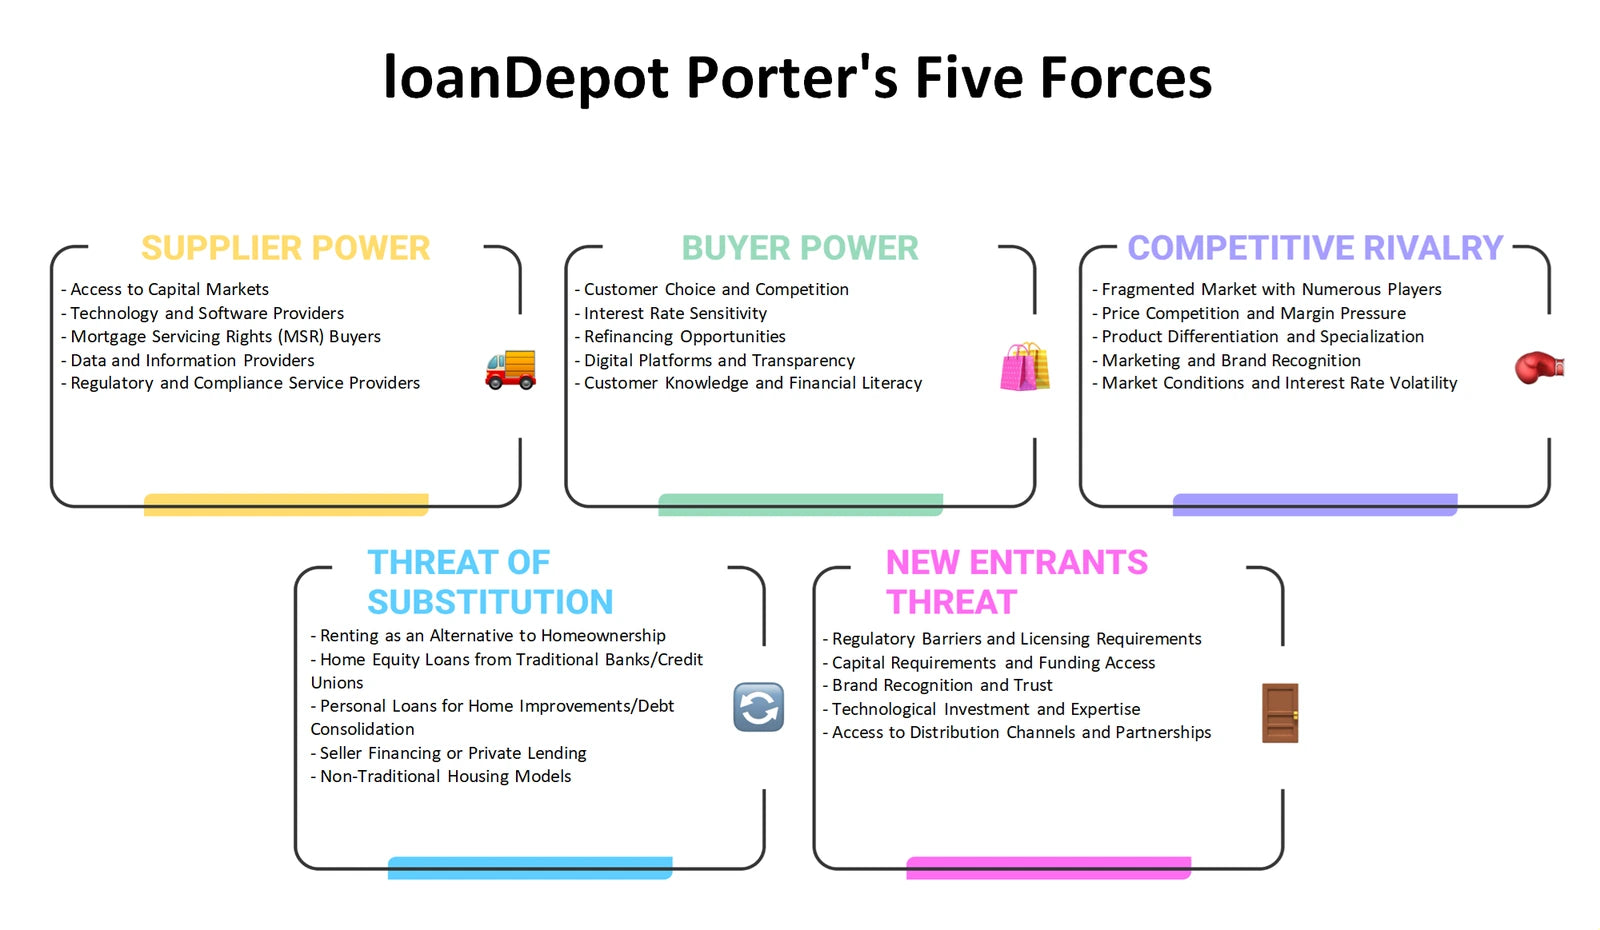
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can loanDepot present mortgage services clearly while coordinating product design, pricing logic, access and compliant communication?
The loanDepot Marketing Mix considers Product, Price, Place and Promotion in a regulated, high-consideration financial service. Product covers the mortgage and refinancing solutions, supporting process and service experience that borrowers evaluate as part of the offer. Price should be assessed through rate, fee and affordability communication, not as an assumed fixed price point. Place includes the online journey as well as homebuilder-linked or other relationship-based paths that can place lending closer to a housing transaction. Promotion is especially important because mortgage messages must build confidence while remaining clear about terms and eligibility. The framework helps connect the four Ps so that a customer promise is operationally and commercially credible.
- Offer clarity. Examine which customer needs the lending proposition addresses and what service elements make that proposition understandable.
- Channel fit. Compare direct digital discovery with partner-connected access points and the different expectations each route may create.
- Message review. Organize the Excel 4Ps prompts before using the Word analysis to consider consistent positioning, disclosures and customer communication.
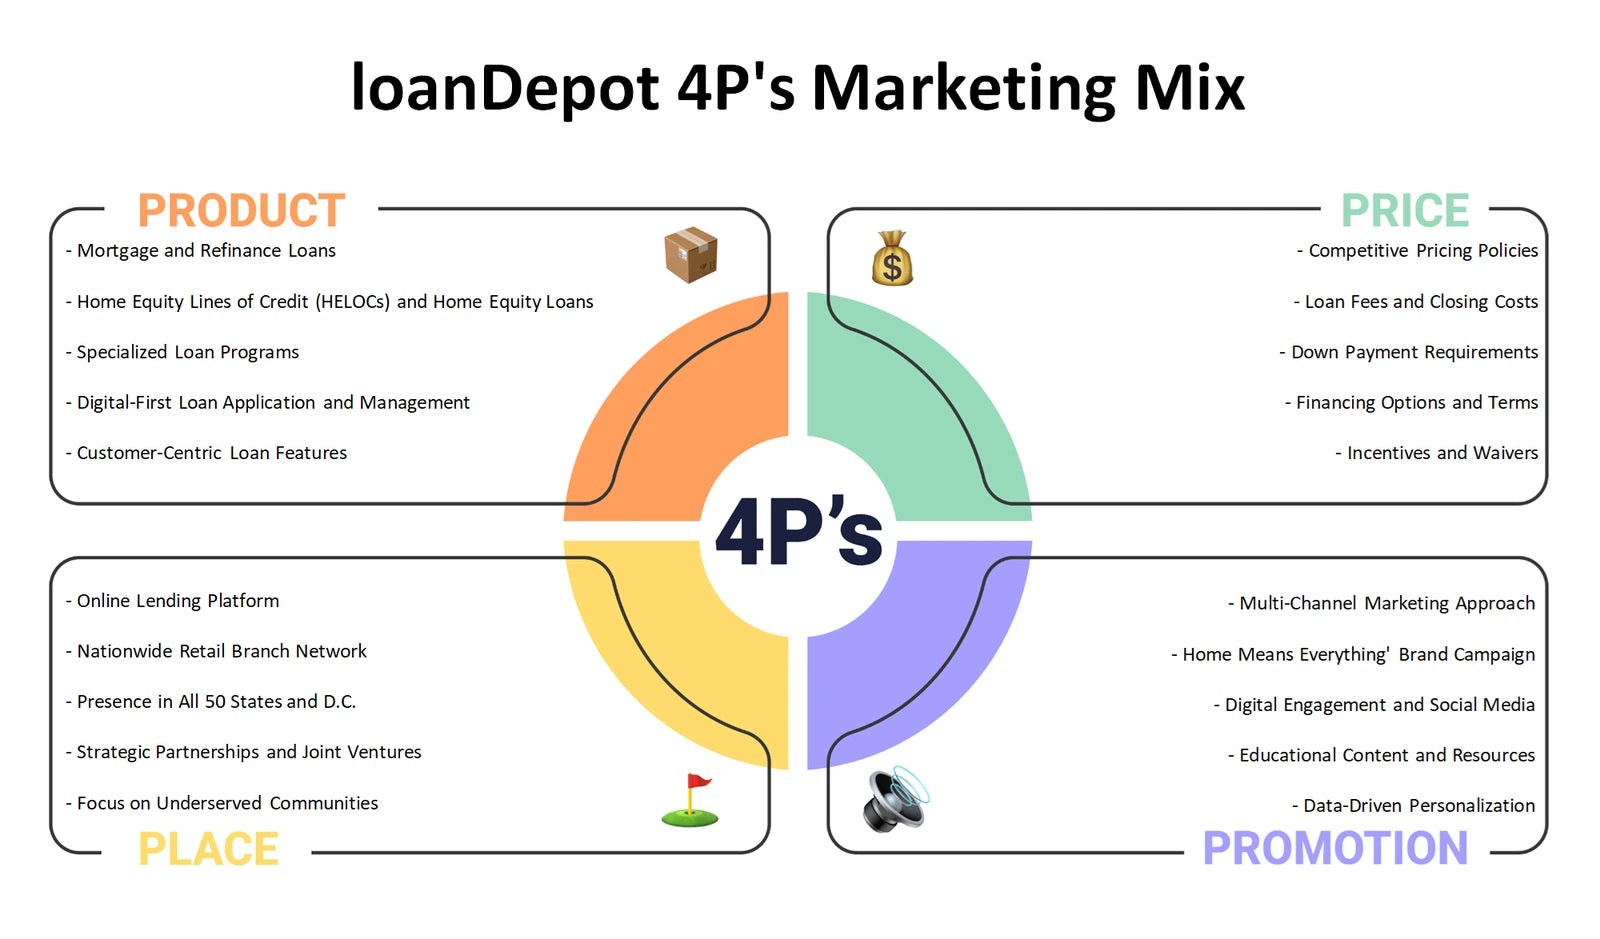
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should loanDepot monitor when mortgage demand, housing affordability and operating requirements can change quickly?
The loanDepot PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal factors include housing-finance policy, consumer-protection rules, licensing and disclosure obligations. Economic questions include interest-rate conditions, employment, home prices and affordability, without assuming a particular current rate environment. Social changes can affect household formation, mobility and preferences for digital service. Technology raises questions about application design, data security, automation and fraud prevention. Environmental exposure can enter through housing resilience, insurance availability and geographic risk. Used together, these categories help distinguish a documented external development from a planning scenario that should simply be monitored.
- Signal separation. Distinguish macroeconomic conditions from policy, regulatory, behavioral and technology developments that may require different responses.
- Housing exposure. Relate affordability, property-market conditions and environmental resilience to the demand context for mortgage lending.
- Monitoring agenda. Use the Excel framework to classify external signals and the Word analysis to develop informed discussion points for periodic review.
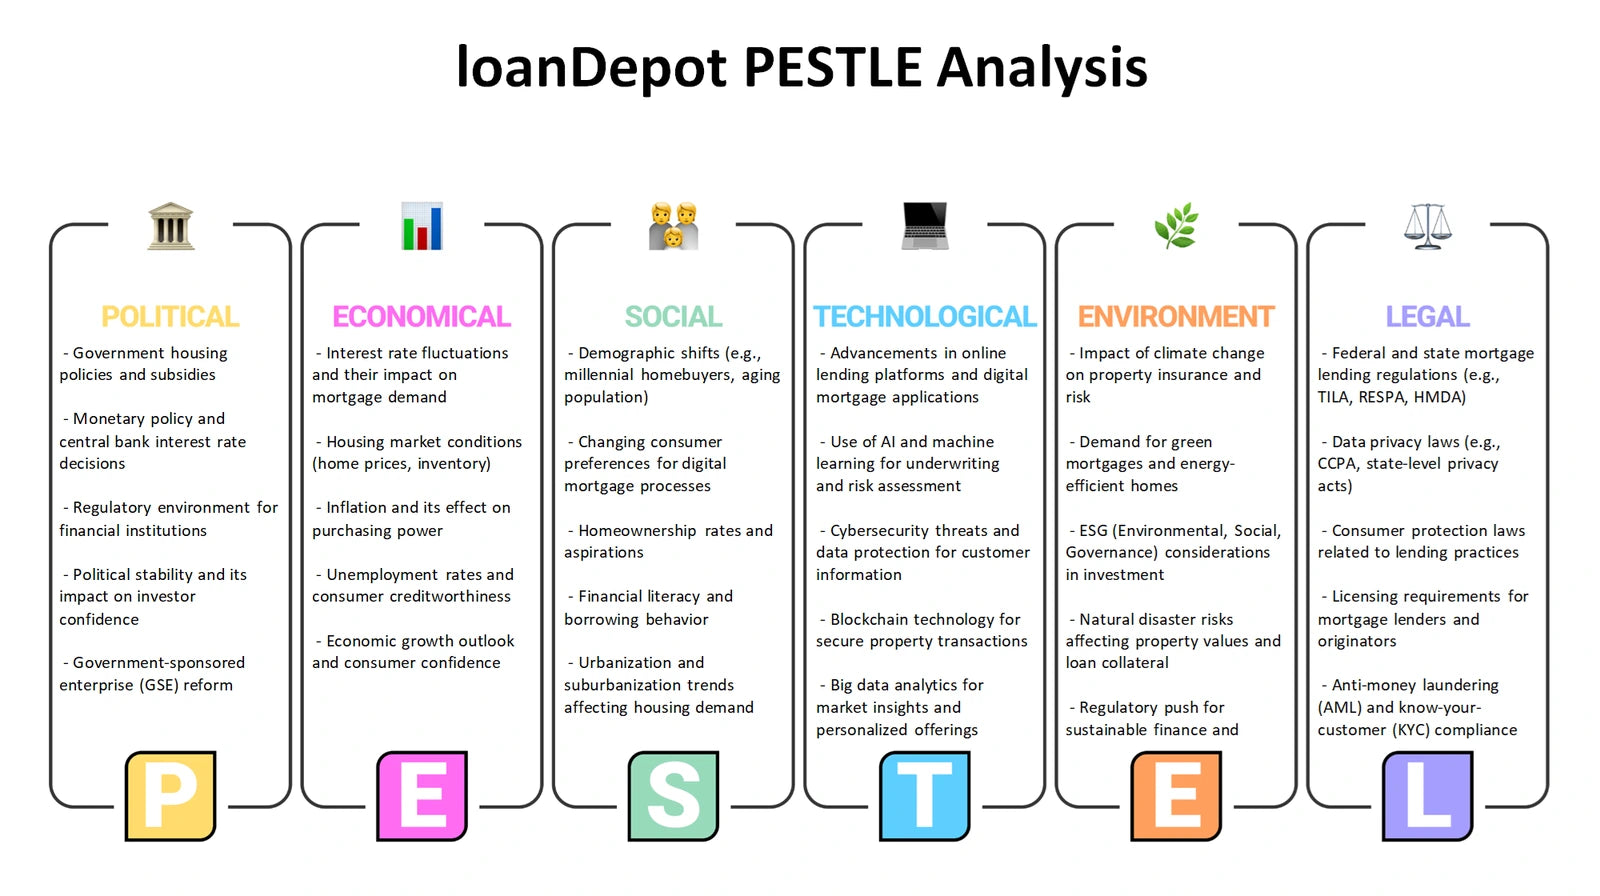
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can loanDepot separate its internal capabilities and constraints from the market opportunities and threats it cannot directly control?
The loanDepot SWOT analysis provides a disciplined final lens for connecting internal and external considerations. Strengths and weaknesses are internal: for example, the ability to coordinate a digital mortgage experience, partner channels, servicing capabilities, operating processes and capital-management choices can be examined as capabilities rather than assumed advantages. Opportunities and threats are external: housing demand, borrower preferences, partner-market development, competition, regulation and funding conditions belong outside the company boundary. This distinction is valuable because a favorable mortgage-market opening is not itself a strength, and an internal cost or execution constraint is not a market threat. The framework helps turn observations from the other five analyses into a balanced discussion of strategic fit.
- Classification discipline. Test whether each point is genuinely internal or external before treating it as a strategic priority.
- Cross-lens synthesis. Link possible capabilities and constraints to the portfolio, business-model, competitive and external factors reviewed elsewhere.
- Actionable record. Use the Excel grid to organize evidence by quadrant, then use the Word analysis to explore the relationships and tensions behind the entries.
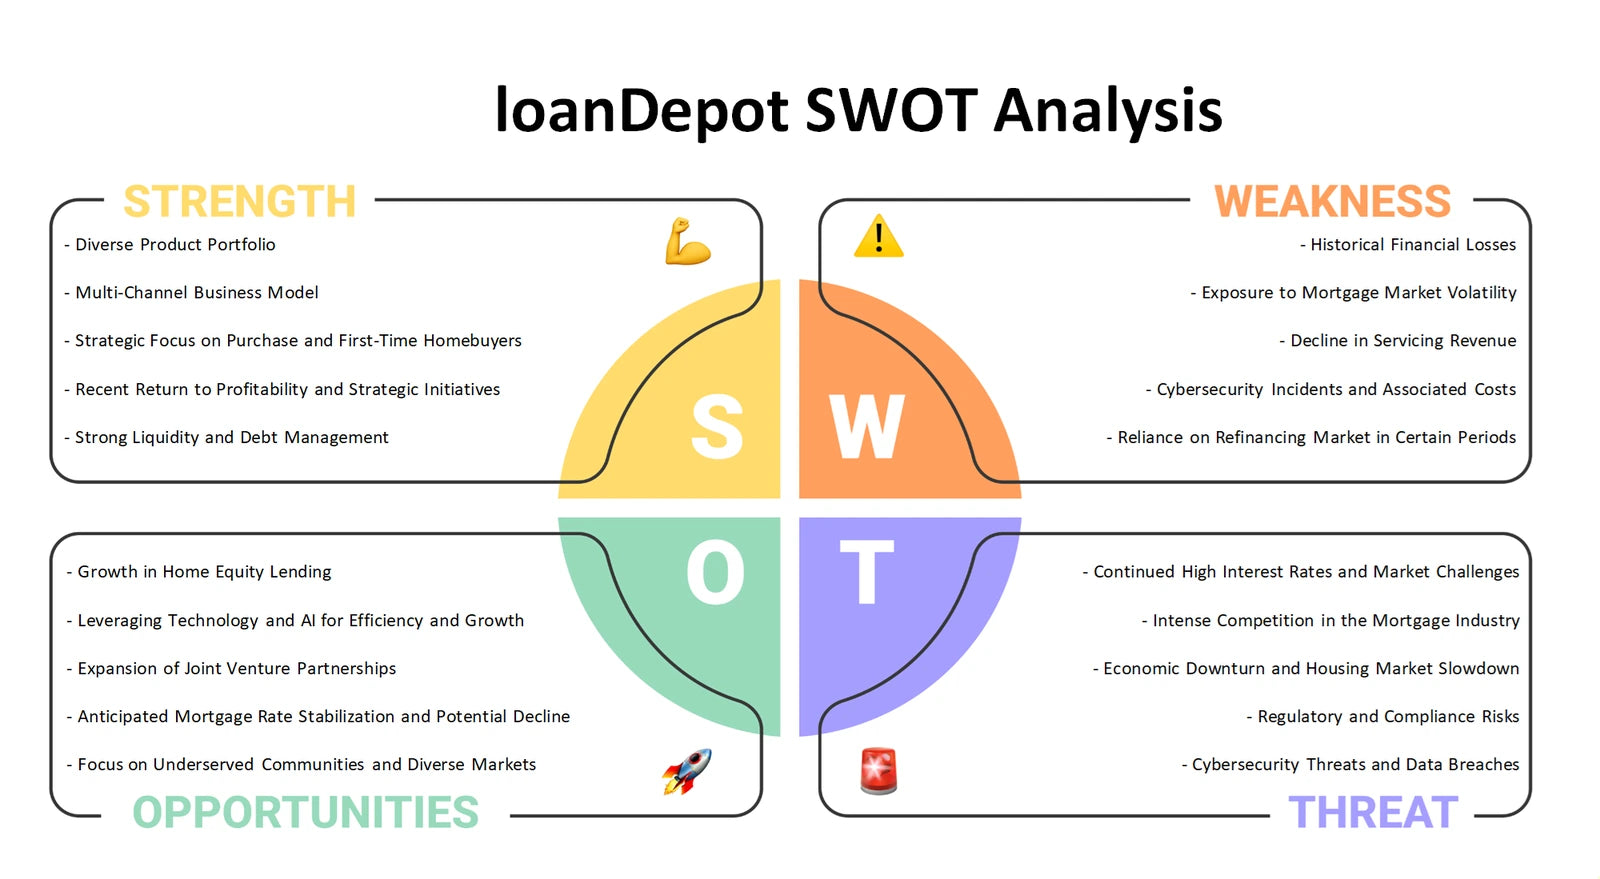
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect the mortgage-business questions
Together, the six perspectives move from portfolio choices and business-model connections to industry pressure, customer-facing decisions, external change and strategic fit. The Excel frameworks provide organized places to compare assumptions and evidence, while the detailed Word files support fuller company-focused interpretation. Used as complementary lenses, they can help customers develop a more coherent discussion of loanDepot's lending channels, servicing-related economics, capital considerations and market context.
Company background: loanDepot — official company website.