

Life Insurance Corp. of India: Distribution and Pricing – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Life Insurance Corp. of India Strategy Analysis Bundle
Life Insurance Corp. of India is treated in this bundle as the life-insurance business described in the supplied product context. Its relevant customer setting includes employers, public-sector undertakings and trade associations seeking group employee-benefit cover, including gratuity, superannuation and key-person protection. Policy administration, claims service and enduring institutional relationships are therefore important strategic considerations.
Rather than claiming a current financial result or market position, the materials organize practical questions around distribution, product mix, retention and service delivery. They help users compare how institutional requirements, life-insurance economics and external conditions may affect priorities. Excel provides structured frameworks for working through the issues, while the Word files provide detailed company analysis to read alongside them.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which policy propositions and customer routes merit different levels of management attention as growth and relative market share change?
The Life Insurance Corp. of India BCG Matrix helps separate portfolio questions from assumptions. It applies market growth and relative market share to policy lines, group propositions or distribution-led offers that the user wishes to compare. Stars, Cash Cows, Question Marks and Dogs are analytical categories rather than pre-assigned conclusions. For an insurer serving institutions, the exercise can clarify whether a proposition deserves expansion effort, disciplined cash generation, further validation or reduced resource commitment.
- Portfolio comparisons. Compare group employee-benefit propositions with other relevant policy or service categories without assuming that any one already occupies a BCG quadrant.
- Resource trade-offs. Consider where relationship-management capacity, underwriting attention, administration capability and retention effort may have the greatest strategic value.
- Working view. Use the Excel matrix to test candidate classifications, then use the Word analysis to document the evidence, caveats and priority questions behind each placement.
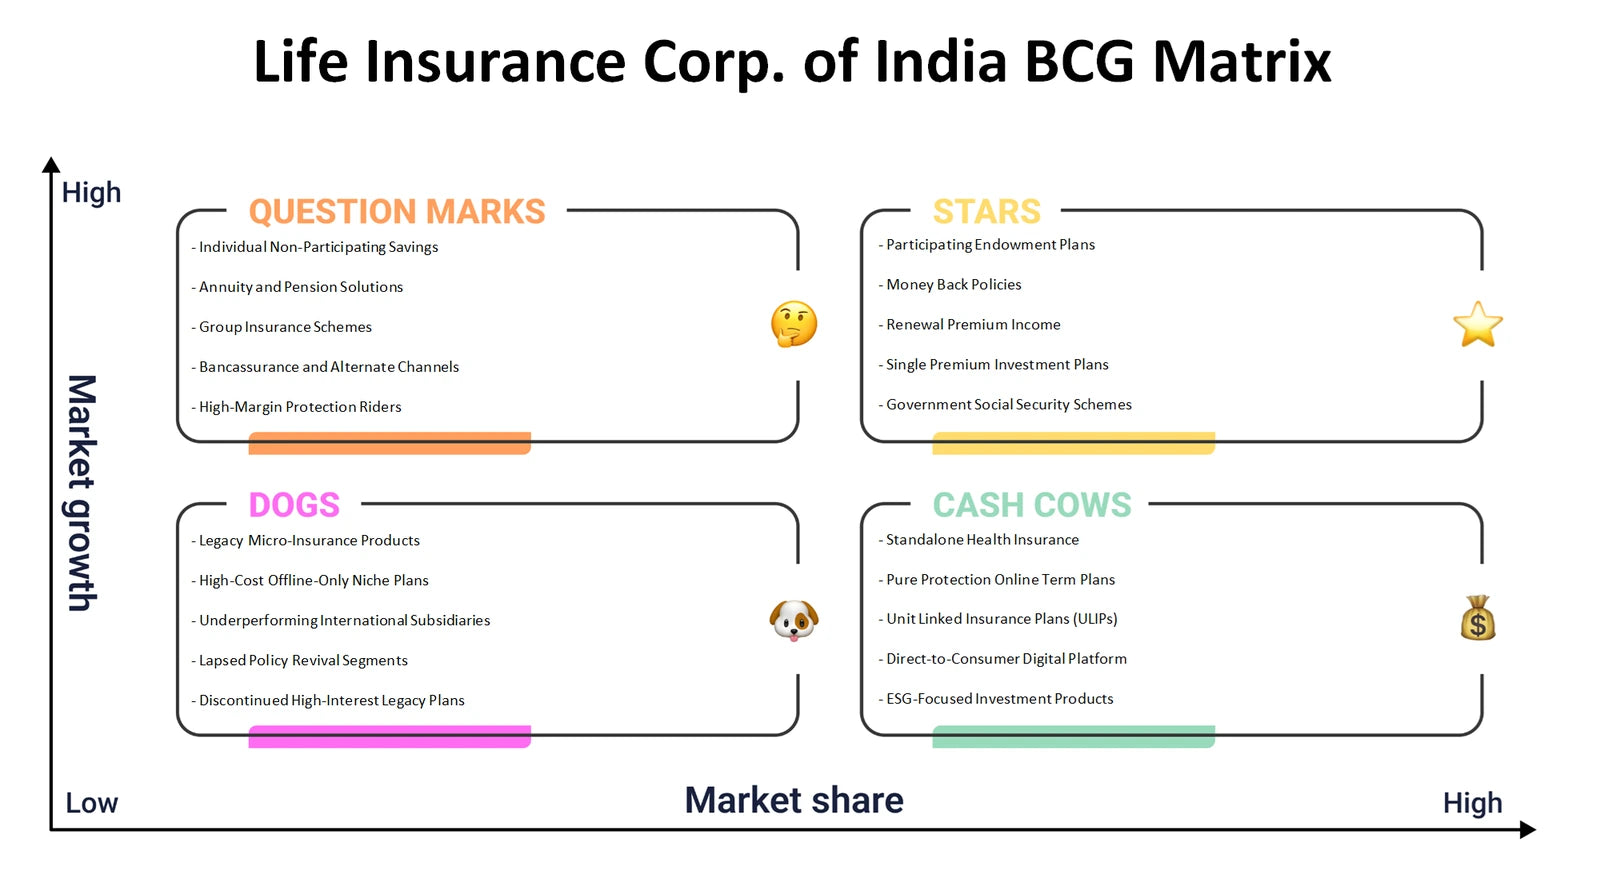
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do institutional customer needs, policy service delivery and premium economics connect in one operating model?
The Life Insurance Corp. of India Business Model Canvas organizes the nine linked building blocks behind value creation. It examines customer segments and value propositions alongside channels and customer relationships; revenue streams alongside key resources, key activities and key partnerships; and the cost structure required to sustain them. In the supplied context, group-policy purchasers may value tailored terms, reliable administration and claims turnaround. The canvas helps connect those expectations to the resources and operating choices needed to deliver them, rather than viewing sales, service and economics in isolation.
- Institutional value. Map how employers, PSUs and trade associations may evaluate employee-benefit cover, service levels and policy administration reliability.
- Economic connections. Examine how premium revenue logic, relationship-led acquisition, operating costs and partner dependencies could reinforce or constrain the proposition.
- Model alignment. Complete the Excel blocks as a connected map, then use the detailed Word discussion to challenge gaps between customer promise, delivery activities and cost structure.
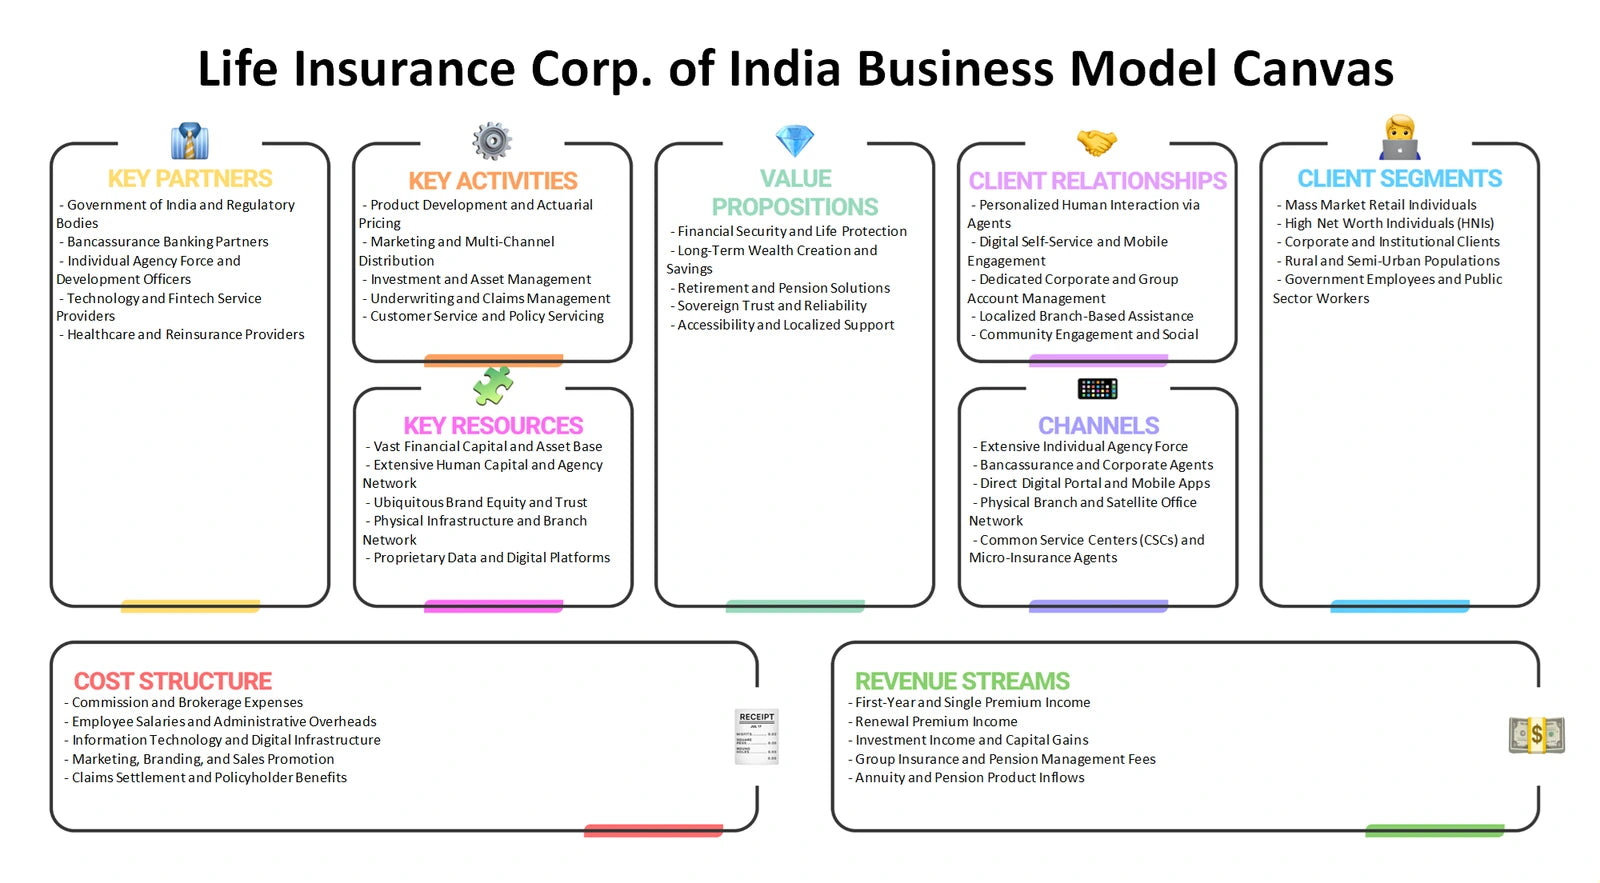
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness and bargaining dynamics of life-insurance and group-benefit business?
Life Insurance Corp. of India Porter's Five Forces frames competition beyond a simple list of insurers. It examines rivalry among providers; buyer power held by institutional purchasers; supplier power involving distribution, specialist talent, technology or risk-transfer capacity where relevant; the threat of new entrants; and substitutes for meeting protection, savings or employee-benefit needs. Institutional customers can compare offers, service standards and total cost per covered life, while alternatives may include self-funded benefits or non-insurance savings arrangements. The lens helps distinguish a pricing issue from a broader structural pressure.
- Buyer leverage. Assess how procurement requirements, service-level expectations and renewal alternatives may shape negotiations with large employee-benefit buyers.
- Alternative solutions. Consider substitutes as different ways of addressing protection, retirement or employee-security needs, not merely direct insurance competitors.
- Pressure map. Use the Excel framework to record evidence and assumptions for each force, with the Word analysis supporting fuller interpretation of the sector conditions.
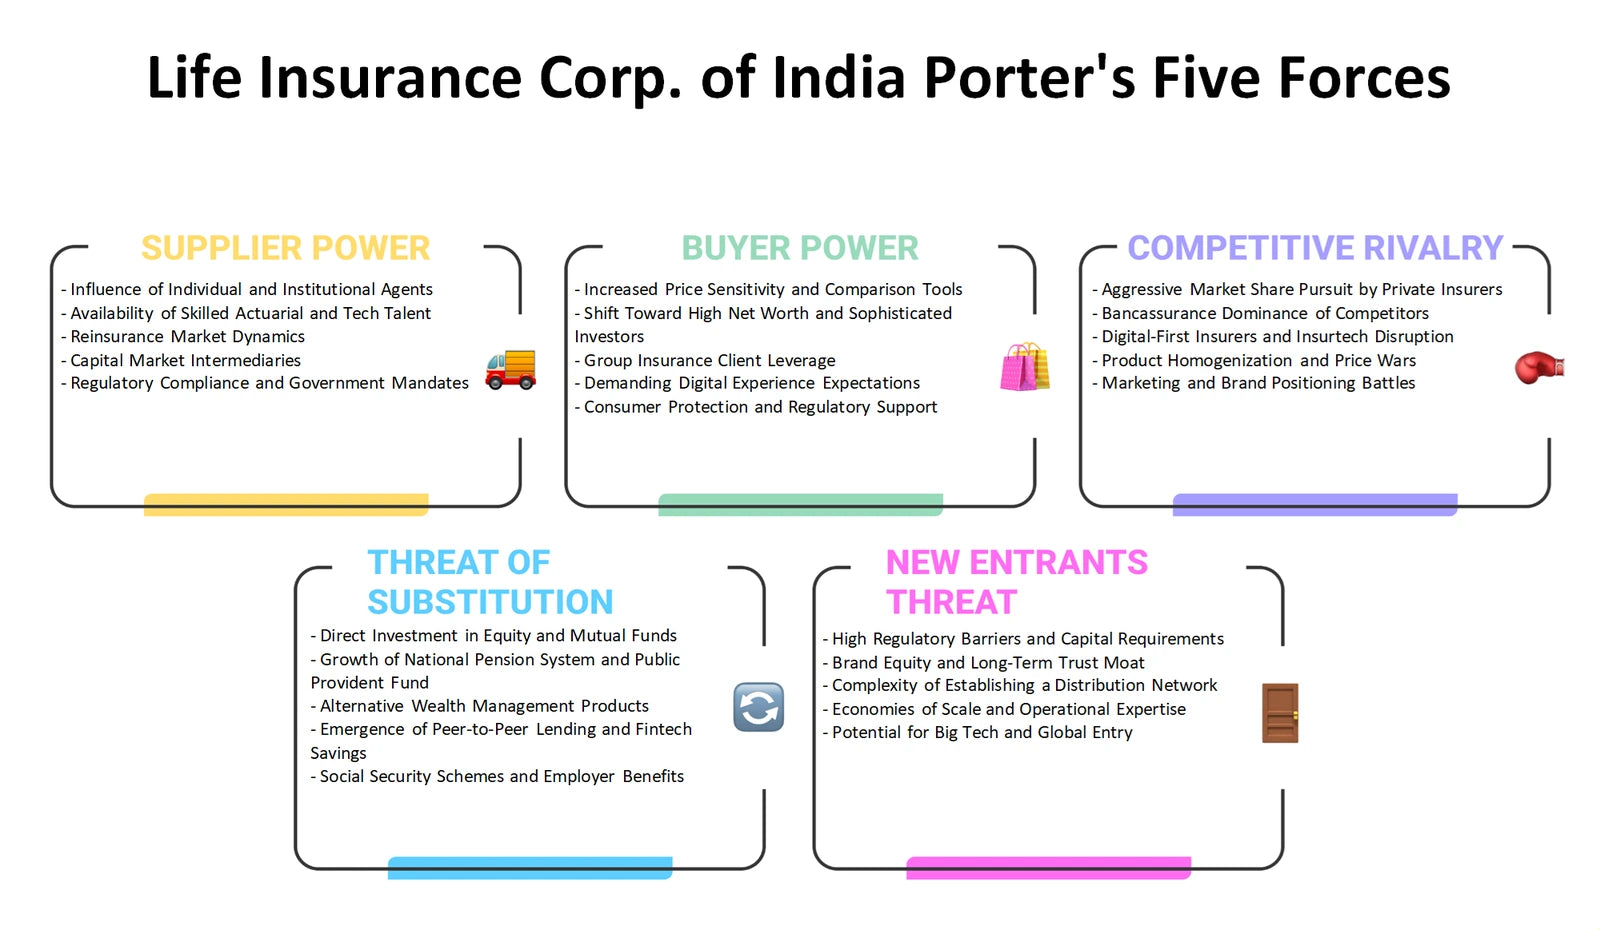
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, access routes and communication be examined for institutional life-insurance buyers?
The Life Insurance Corp. of India Marketing Mix considers Product, Price, Place and Promotion in a regulated, relationship-dependent service setting. Product analysis can distinguish employee-benefit protection and policy-administration needs from a generic insurance offer. Price can examine tailored cost-per-life logic and the trade-off between affordability, cover design and service expectations. Place focuses on the routes through which institutional buyers are supported, while Promotion considers credible communication for decision-makers rather than assumed campaigns or consumer advertising. Together, the 4Ps help keep service delivery connected to the promise made at acquisition and renewal.
- Product-service fit. Review how gratuity, superannuation and key-person cover may be assessed alongside claims handling and policy-administration requirements.
- Commercial coherence. Compare pricing principles, access points and communication needs without inventing actual rates, channel shares or promotional activity.
- Planning comparison. Use the Excel 4Ps framework to compare customer scenarios, then consult the Word analysis when developing discussion points for product, distribution or retention planning.
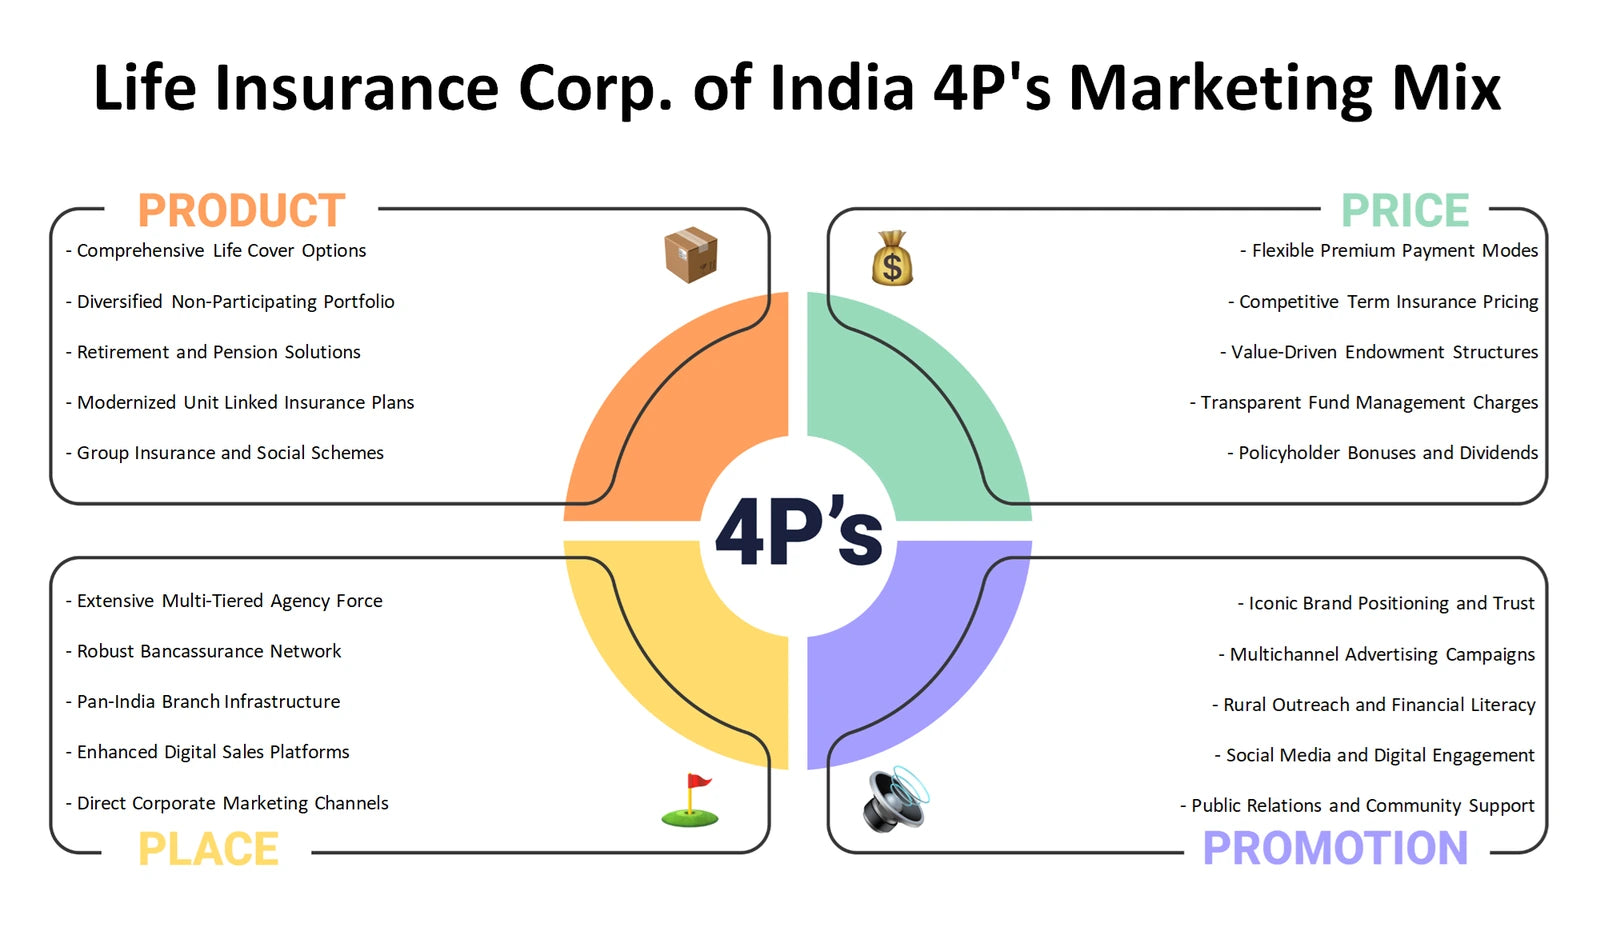
Marketing Mix (4Ps) summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored when assessing long-term life-insurance and employee-benefit priorities?
The Life Insurance Corp. of India PESTLE analysis, also commonly called PESTEL, separates the external environment into Political, Economic, Social, Technological, Legal and Environmental considerations. It can help users ask how public-policy direction, household or employer affordability, demographic needs, digital service expectations, insurance regulation and climate-related risk may affect the business context. These are questions for examination, not claims that a particular rule, interest-rate movement or policy change has occurred. For long-duration insurance relationships, separating controllable operating choices from external shifts is particularly useful.
- Policy and regulation. Track questions around oversight, employee-benefit arrangements and compliance obligations without treating possible developments as confirmed changes.
- Changing expectations. Explore how social protection needs, digital administration expectations and environmental risk awareness could alter customer or operating priorities.
- Monitoring agenda. Populate the Excel PESTLE grid with signals and implications, then use the Word analysis to add context, ownership questions and possible response themes.
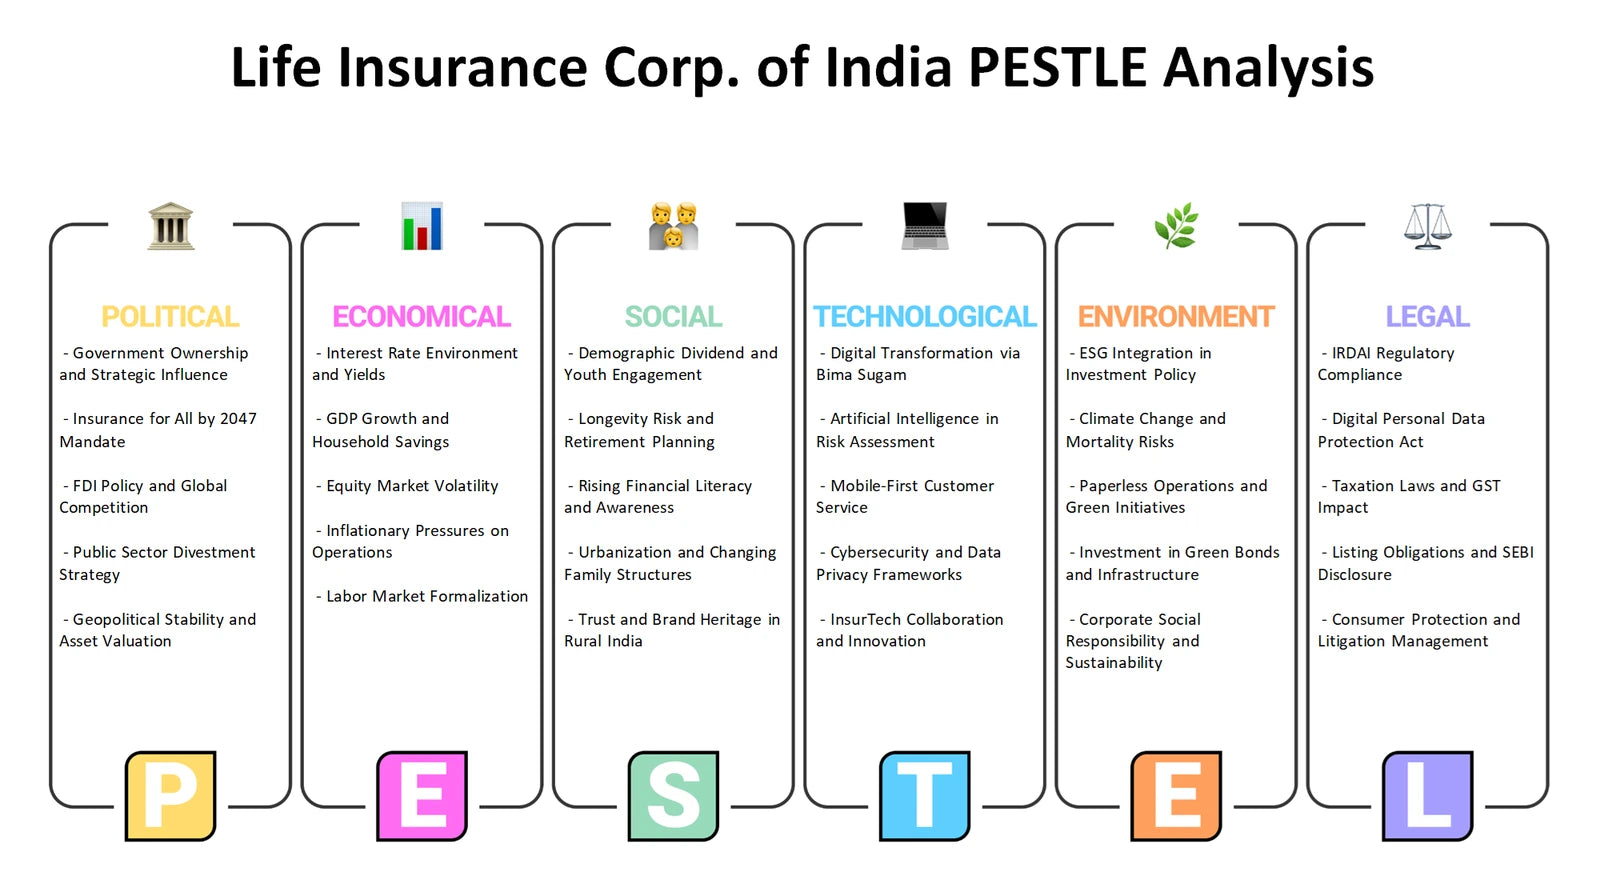
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside the external opportunities and threats facing the business?
The Life Insurance Corp. of India SWOT analysis brings the previous lenses into a clear internal-versus-external discussion. Strengths and weaknesses concern capabilities within the business, such as institutional relationships, policy administration, service processes or areas needing improvement. Opportunities and threats arise outside it, such as evolving employee-benefit demand, competitive alternatives, regulation or changing customer expectations. The supplied context makes long-term institutional relationships and dependable claims administration relevant themes to test, but the framework does not present them as independently verified conclusions. Its value lies in turning observations into explicitly classified strategic choices.
- Internal reality check. Test whether relationship continuity, service reliability, operational complexity or retention dependencies belong on the strengths or weaknesses side.
- External priorities. Separate possible demand openings from threats such as customer bargaining power, substitutes and regulatory change.
- Decision discipline. Use the Excel SWOT grid to rank evidence-backed issues, while the Word analysis helps explain why a theme is internal, external, actionable or uncertain.
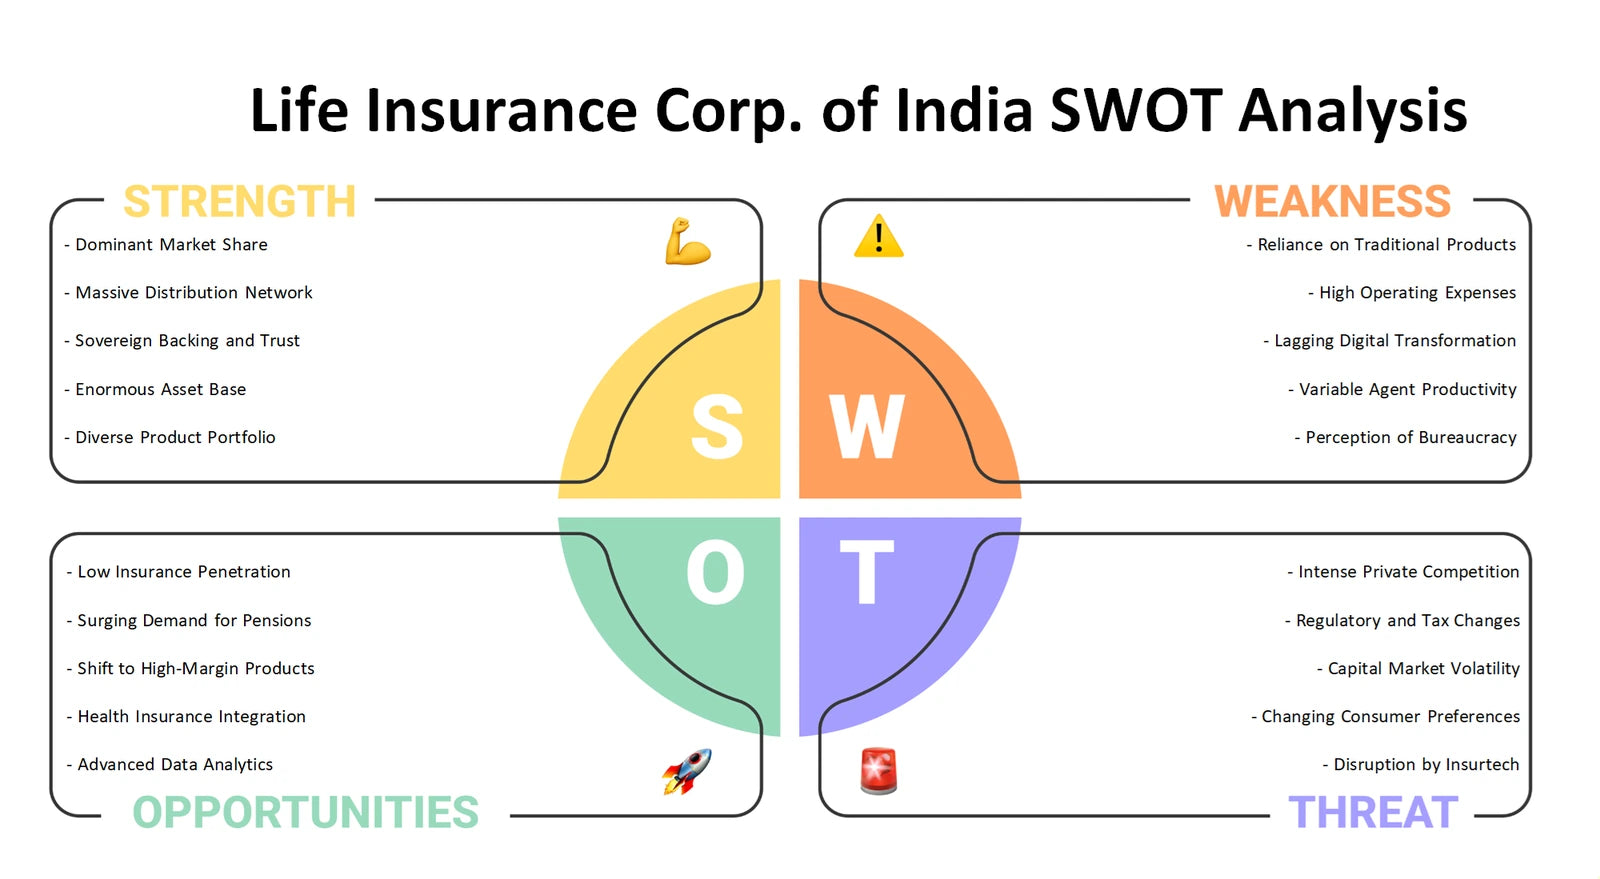
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices to the operating model
Used together, the six perspectives help relate portfolio priorities to customer value, industry pressure, marketing choices, external change and internal capability. For Life Insurance Corp. of India, the materials can support a more connected discussion of group-policy relationships, service delivery, retention and future strategic questions. The Excel frameworks provide a structured place to compare issues, while the Word files add detailed company-analysis context for interpretation and planning.
Company background: Life Insurance Corp. of India — product context page for the LICIndia Business Model Canvas.