

Lancashire: Six Analyses of Underwriting and Digital Investment

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Lancashire Strategy Analysis Bundle
For this bundle, Lancashire refers to the specialist (re)insurance business described in the supplied product context, rather than an unrelated same-name company. Its work centres on selecting, structuring and pricing complex property, casualty and energy risks, with technical underwriting and claims expertise supporting clients exposed to marine, energy and natural-catastrophe losses.
The available context highlights disciplined underwriting, catastrophe modelling, exposure analytics, specialist claims partners and carefully drafted policy terms. Those documented operating themes make portfolio allocation, risk economics, distribution, regulation and resilience useful questions to test through six connected strategic lenses rather than assumptions about an unrelated Lancashire business.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Lancashire underwriting activities merit capacity, specialist talent and management attention as market conditions change?
A Lancashire BCG Matrix helps organise a specialty underwriting portfolio around two analytical criteria: market growth and relative market share. It does not presume that any class of business belongs in a Star, Cash Cow, Question Mark or Dog quadrant. Instead, it helps compare areas such as property, casualty, energy, marine and catastrophe-related risk where demand, available capacity, loss experience and technical differentiation may move differently. This matters because insurance capacity is finite: a faster-growing opportunity may still need careful accumulation controls, while an established line may fund expertise without necessarily deserving additional exposure.
- Portfolio logic. Compare growth signals with relative competitive position while keeping underwriting profitability, aggregation risk and cycle conditions visible.
- Capacity trade-offs. Test whether specialist teams, modelling effort and line size should be prioritised, maintained, monitored or reconsidered across risk classes.
- Structured comparison. Use the Excel framework to map candidate activities and the Word analysis to record the evidence, definitions and cautions behind each placement discussion.
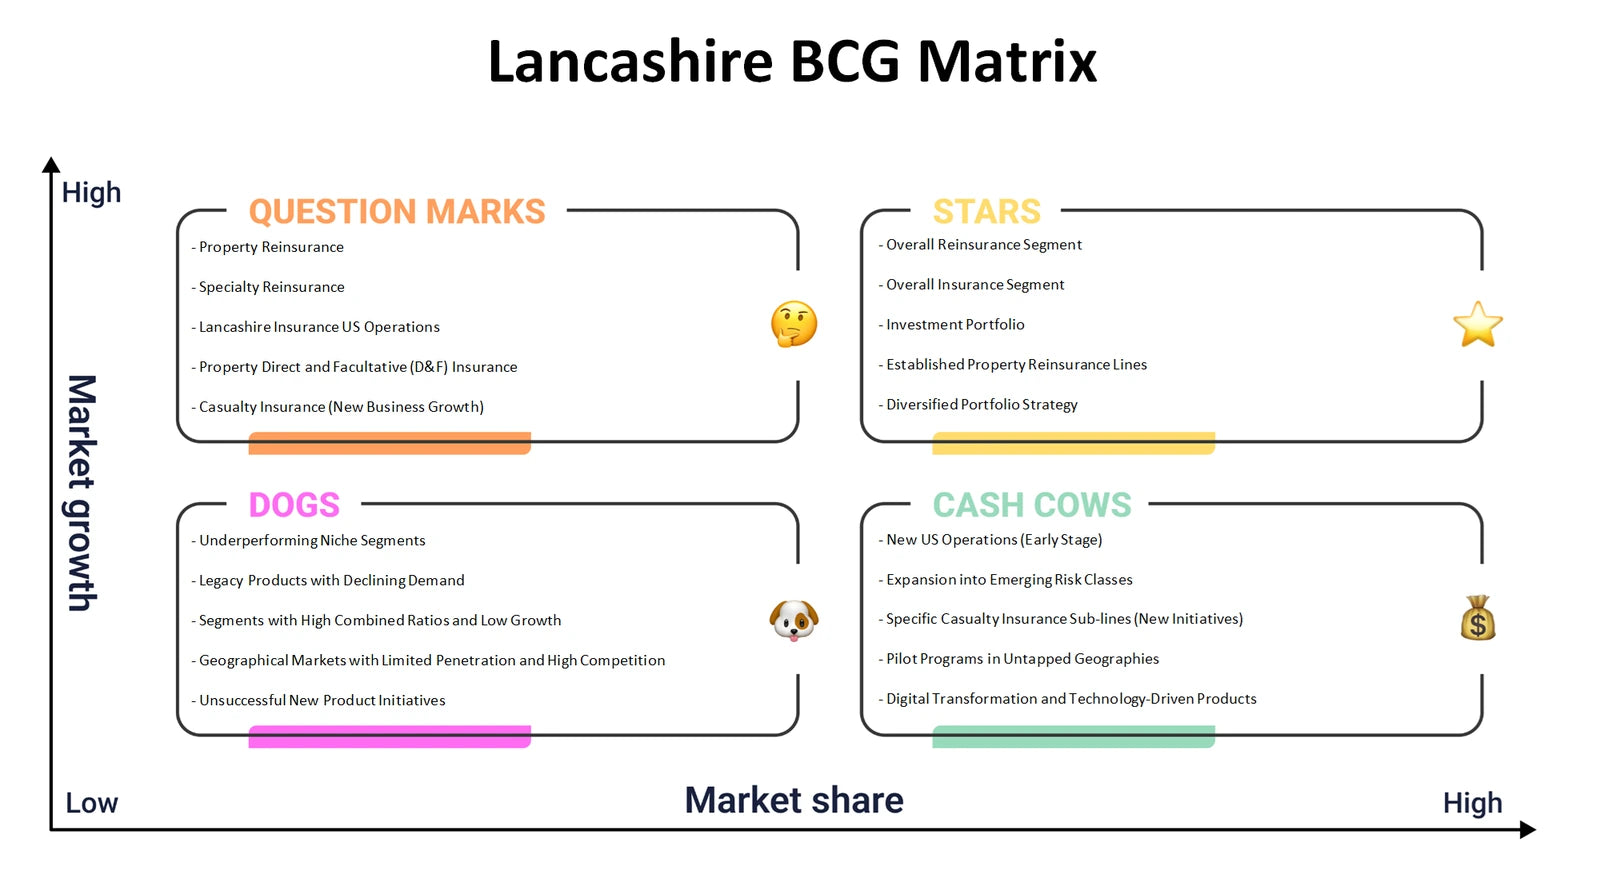
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do Lancashire's specialist underwriting and claims capabilities connect to client value and sustainable insurance economics?
The Lancashire Business Model Canvas examines the links between customer segments, value propositions, channels, customer relationships and revenue streams, alongside key resources, key activities, key partnerships, cost structure. In this context, the customer side can be explored through clients with complex exposures and the intermediaries involved in placing specialist cover. The value proposition can be tested through tailored wording, disciplined pricing, responsive claims handling and risk expertise. Resources such as underwriting judgement, exposure data and catastrophe models only create value when connected to sound risk selection, partner coordination and premium income that supports claims, reinsurance and operating costs.
- Value chain. Trace how risk information, technical terms and specialist claims support can improve the experience of clients facing complex losses.
- Economic links. Examine how premiums, policy limits, risk transfer, modelling costs and expert partners interact instead of treating each block in isolation.
- Connected evidence. Populate the Excel canvas with focused hypotheses, then use the Word analysis to explain assumptions and relationships across all nine building blocks.
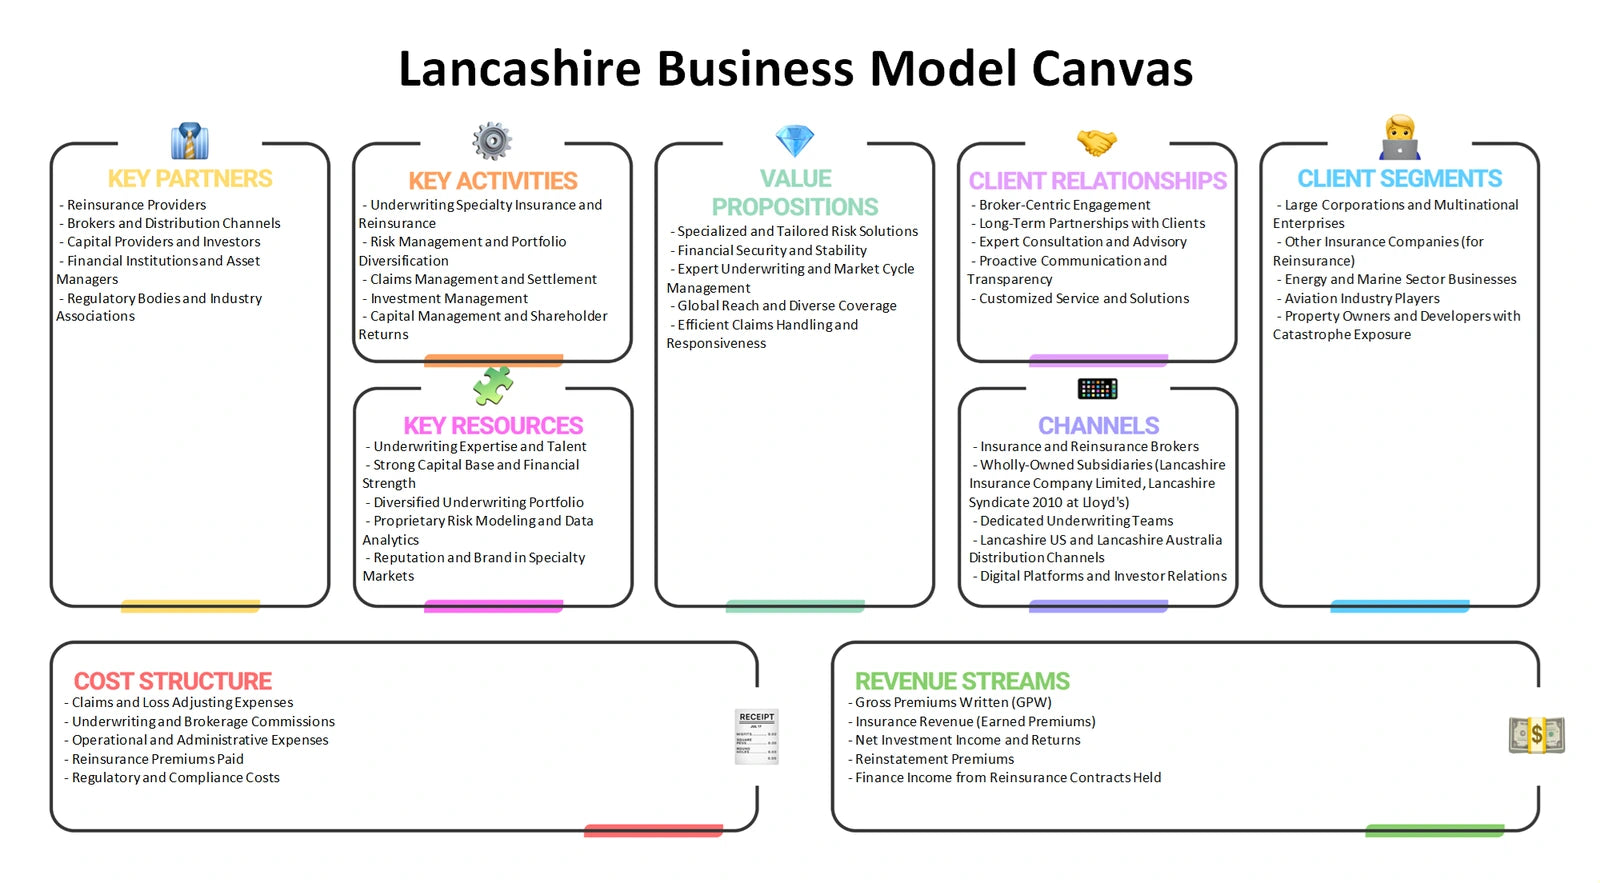
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape Lancashire's ability to price specialist risk with discipline?
Lancashire Porter's Five Forces frames the competitive setting around specialty (re)insurance rather than assigning an unsupported force score. Rivalry can intensify when carriers pursue similar classes or soften terms to deploy capital. Buyer power may arise through sophisticated insureds, brokers and large placements that compare coverage, wording and price. Supplier power is relevant to the providers of reinsurance capacity, catastrophe-model inputs, specialist talent, legal advice and claims services. New entrants may be enabled by fresh capital or platforms, while substitutes include self-insurance, captives, alternative risk transfer and different contractual ways of retaining risk. Each force matters because it can affect rates, terms, service expectations and underwriting selectivity.
- Rivalry and buyers. Consider how broker-led comparisons, renewals and capacity cycles can influence pricing discipline and differentiated policy terms.
- Inputs and alternatives. Explore dependence on external capacity, data and specialist services alongside clients' non-traditional risk-financing options.
- Pressure map. Use the Excel framework to separate the five forces, while the Word analysis helps document why a pressure matters for underwriting choices.
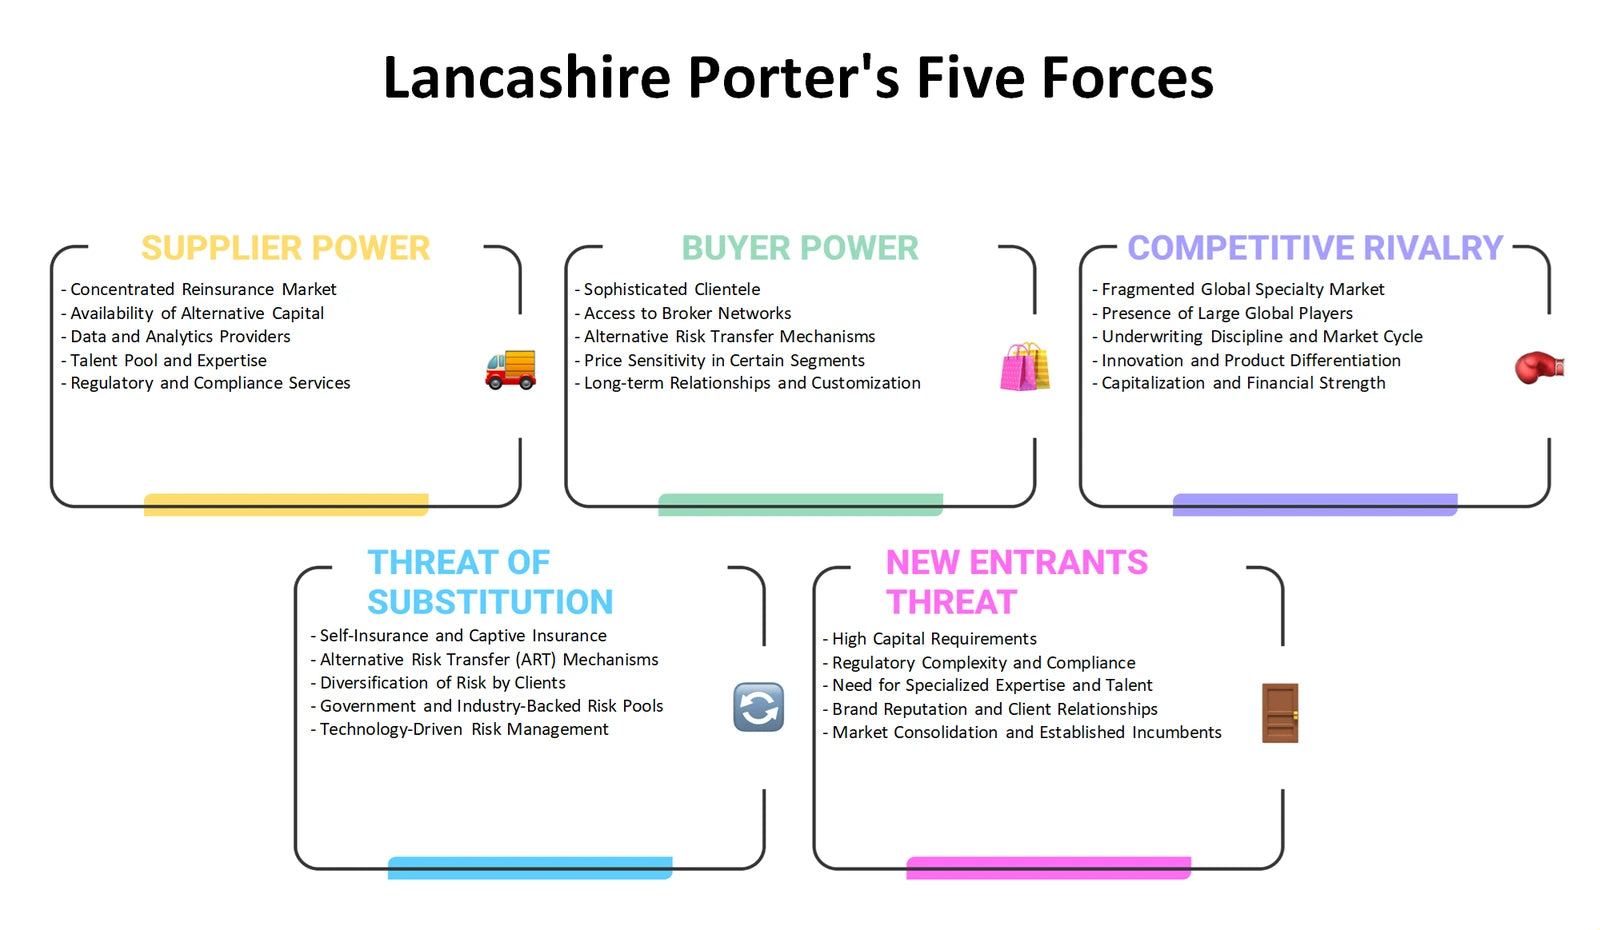
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Lancashire communicate specialist risk solutions without reducing a complex insurance purchase to a simple price comparison?
A Lancashire Marketing Mix examines Product, Price, Place and Promotion in a B2B, relationship-led risk market. Product can mean the combination of policy structure, limit, conditions, claims support and underwriting expertise offered for a defined exposure. Price is not merely a quoted premium: it can be considered alongside deductibles, attachment points, limits, exclusions and the uncertainty reflected in the risk. Place concerns routes through brokers, intermediaries and direct professional relationships where appropriate. Promotion is best assessed as evidence-led communication of appetite, expertise and service rather than mass-market advertising. The framework helps keep commercial positioning aligned with risk selection and policy wording.
- Offer design. Compare how tailored cover, technical wording and claims coordination may matter to clients managing energy, marine or catastrophe exposures.
- Pricing context. Examine the relationship between premium logic, risk information, coverage terms and the need to avoid underpricing complex exposures.
- Go-to-market review. Use Excel to organise the four Ps and use the Word analysis to add customer, intermediary and underwriting context to each choice.
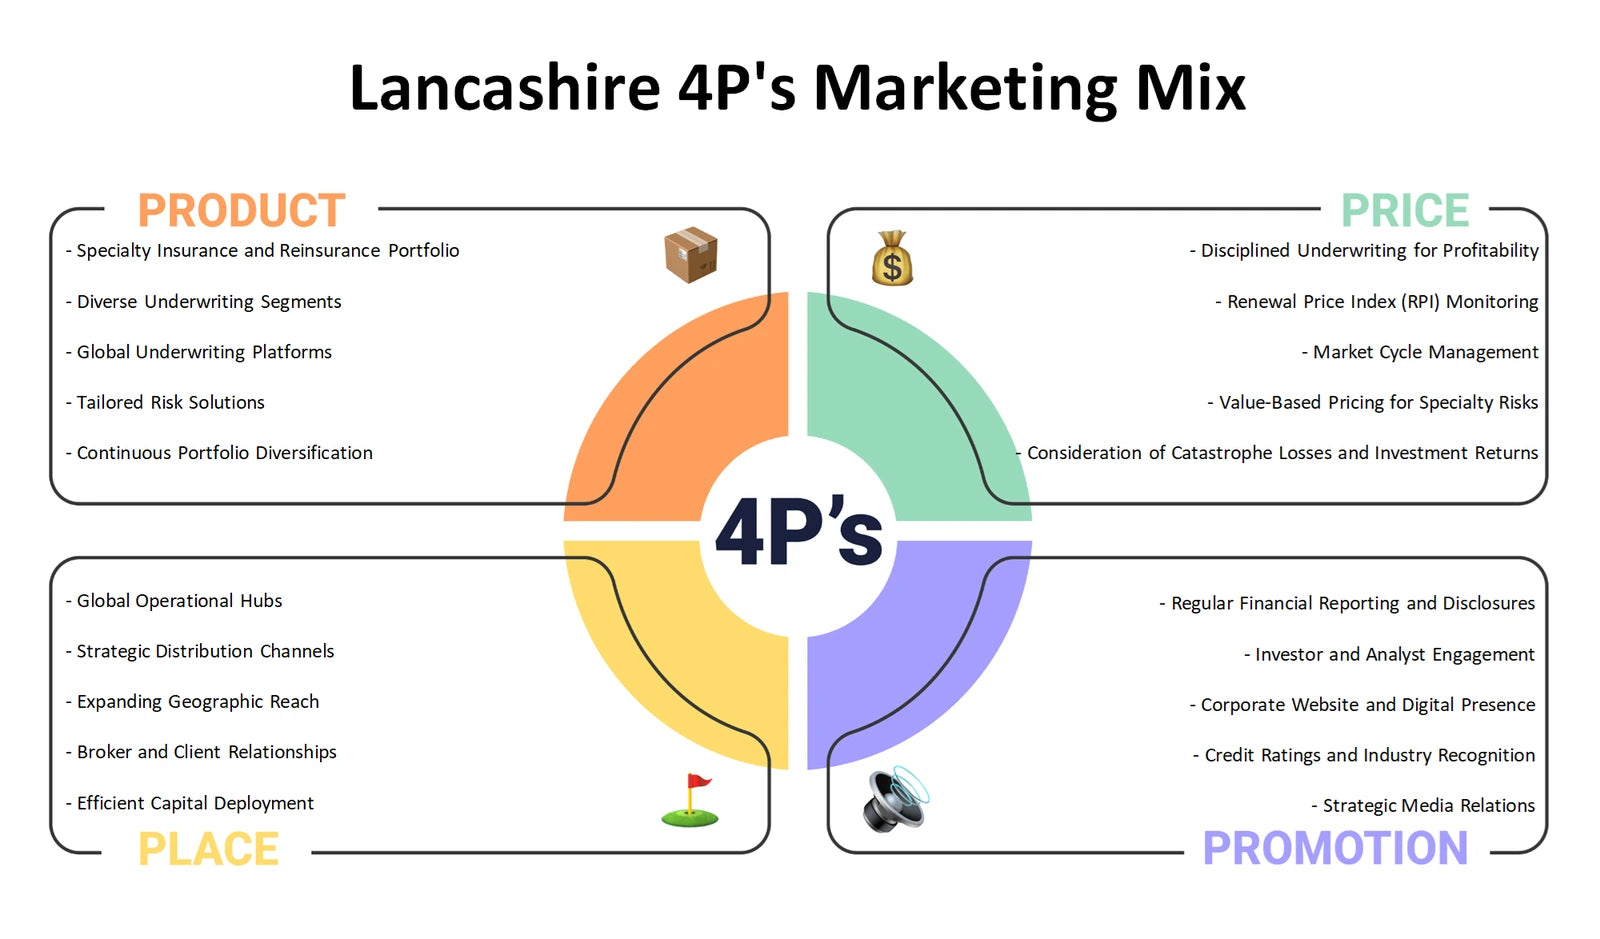
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter Lancashire's risk assumptions, operating requirements and client demand?
A Lancashire PESTLE analysis, also commonly called PESTEL, separates external influences from internal capabilities. Political conditions can affect cross-border risk, sanctions exposure and public-policy expectations. Economic changes may influence asset values, construction costs, claims inflation, insurance demand and the cost of capital. Social expectations can shape trust after a loss and the importance of clear claims communication. Technological factors include catastrophe models, geospatial analytics, secure cloud workflows and cyber resilience. Legal issues include insurance regulation, contract interpretation, data handling and claims obligations. Environmental factors are especially relevant where weather volatility and physical catastrophe exposure affect pricing, accumulations and scenario analysis. These are questions to investigate, not claims that a specific policy or rate has changed.
- External scan. Identify which political, economic and legal developments could affect specialist risk placement, claims handling or capital decisions.
- Risk signals. Relate climate, technology and social expectations to data quality, cyber security, catastrophe exposure and client confidence.
- Scenario discipline. Use the Excel framework to log external drivers and the Word analysis to develop reasoned implications without presenting scenarios as facts.
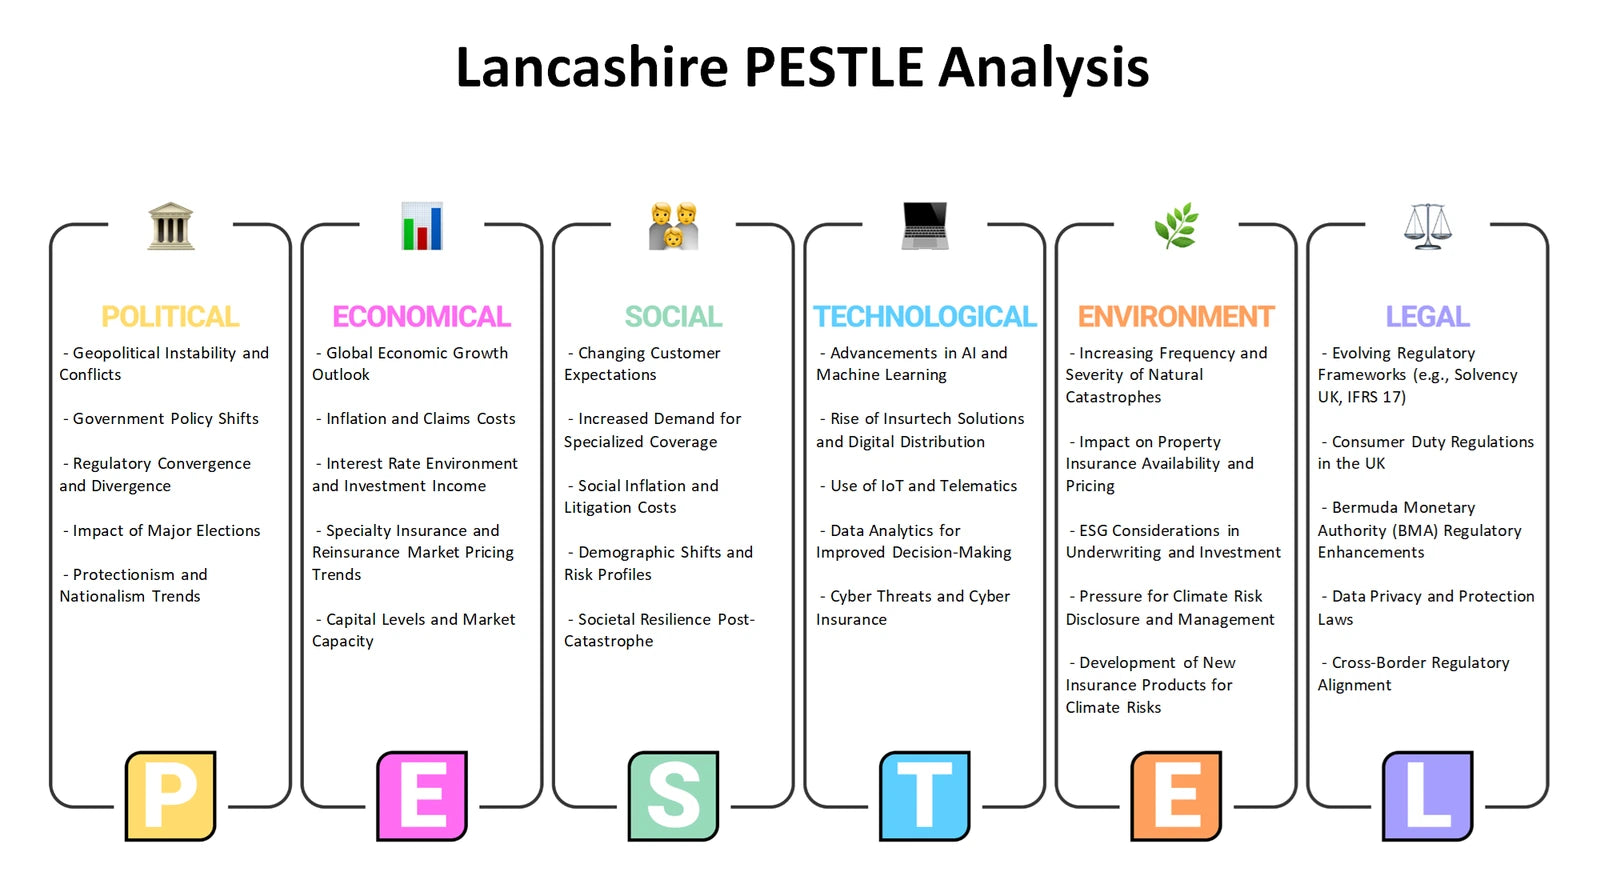
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Lancashire distinguish its internal underwriting capabilities from the external opportunities and threats facing specialty insurance?
A Lancashire SWOT analysis provides a disciplined bridge between the other five perspectives. Strengths and weaknesses are internal: potential topics include specialist underwriting judgement, exposure analytics, claims coordination, data security, concentration management and the limits of available capacity or information. Opportunities and threats are external: changing client exposures, demand for complex cover, competitive capacity, catastrophe volatility, regulatory developments and alternative risk-financing options can be assessed on that side of the framework. The analysis should not label these themes as established findings without supporting evidence. Its value is in making the classification explicit, then testing how a genuine capability may support a market opportunity or how a weakness may amplify an external threat.
- Internal versus external. Keep operational resources, technical expertise and potential constraints separate from market, regulatory and catastrophe conditions.
- Strategic fit. Explore whether a proposed response draws on a real strength, addresses a weakness or depends on an uncertain external development.
- Decision record. Use the Excel matrix to prioritise discussion points and the Word analysis to capture the rationale, evidence gaps and possible strategic connections.
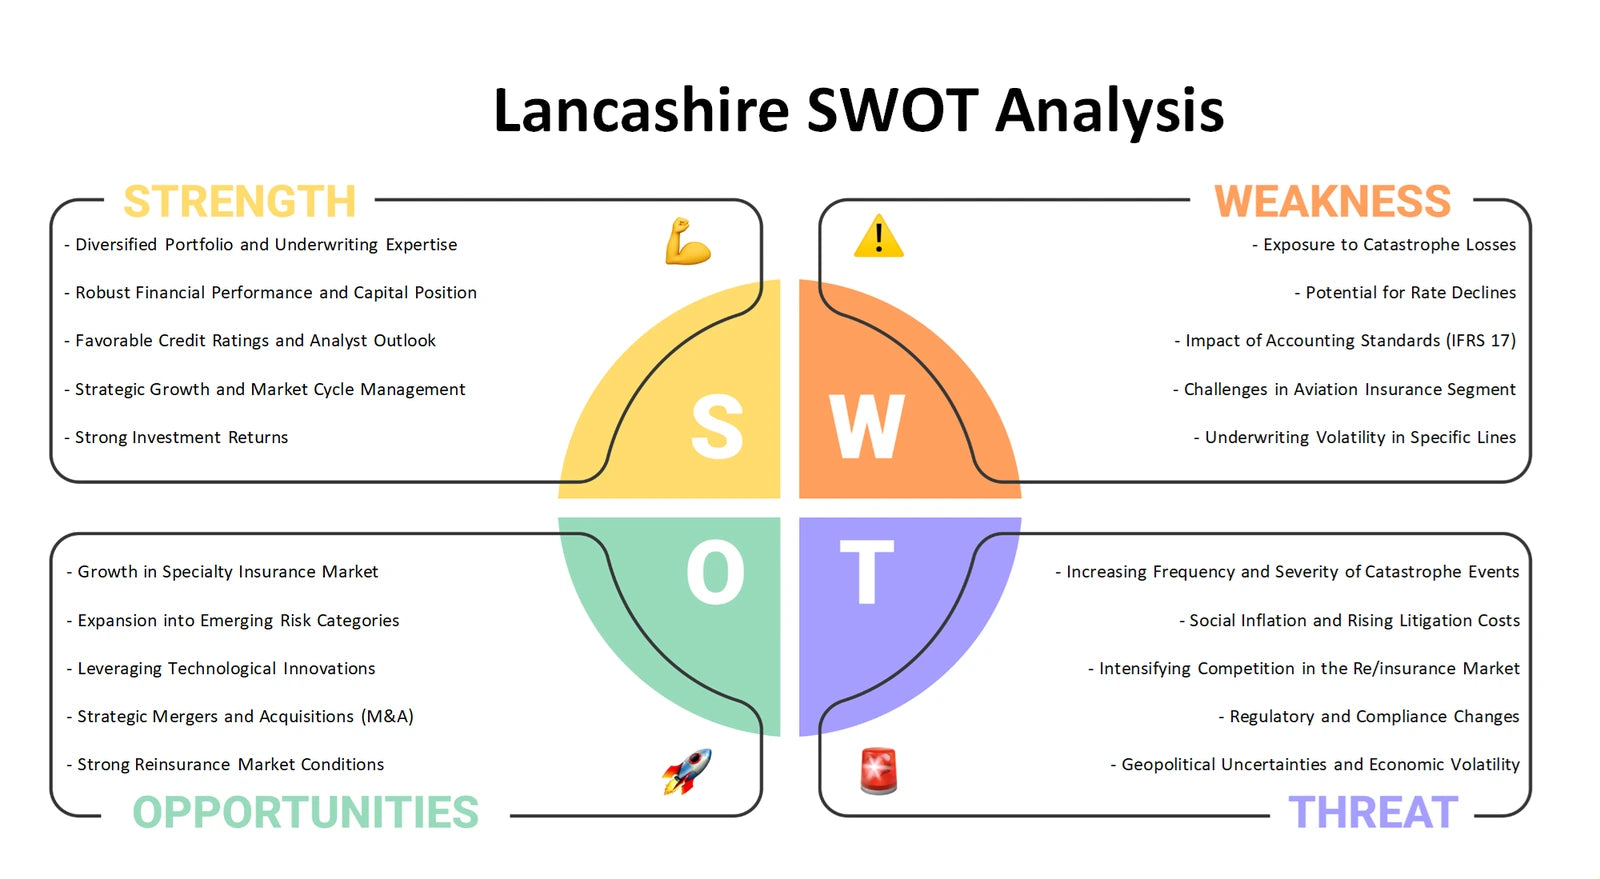
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the wider risk model
Used together, the six perspectives help customers examine Lancashire from complementary angles: portfolio priorities, value creation, industry pressure, client-facing choices, external change and strategic fit. The Excel frameworks provide a practical structure for comparison and discussion, while the detailed Word analysis supports deeper interpretation of the specialist (re)insurance context, underwriting trade-offs and evidence to investigate further.
Company background: Lancashire — supplied product-context background.