

Lakeland Bank: Banking Business and Pricing – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Lakeland Bank Strategy Analysis Bundle
For this product, Lakeland Bank refers to the relationship-led banking business described in the matching product context, with local teams serving commercial customers in New Jersey. Its relevant offerings include commercial lending, treasury support and real-estate financing for borrowers such as investors and developers pursuing multifamily, mixed-use and construction projects.
That operating model makes speed, credit judgement and local knowledge meaningful strategic questions. The six analyses help examine how relationship banking can be prioritised, how value is delivered and paid for, and how lending-market pressures, customer choices and external conditions may affect decisions without presenting unverified conclusions as established facts.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, deposit and specialist banking activities deserve the greatest management attention as Lakeland Bank balances relationship depth with disciplined resource use?
The Lakeland Bank BCG Matrix provides a portfolio lens for comparing activities by market growth and relative market share. For a relationship-focused bank, the useful comparison is not simply loan volume: it can consider whether commercial banking, real-estate financing, treasury services or other customer needs are operating in faster- or slower-growing markets and how competitively established each activity may be. The familiar Stars, Cash Cows, Question Marks and Dogs categories organise a discussion about investment, protection, selective development or review. They are analytical categories, not claims that Lakeland Bank has already been placed in any quadrant.
- Portfolio priorities. Compare activities that may require experienced lenders, underwriting capacity, branch support or specialist treasury expertise against their strategic role.
- Capital discipline. Explore how lending growth ambitions can be considered alongside credit quality, concentration awareness and the finite capacity of local relationship teams.
- Structured comparison. Use the Excel framework to map possible portfolio questions, then use the Word analysis to interpret what the criteria could mean for a relationship-banking model.
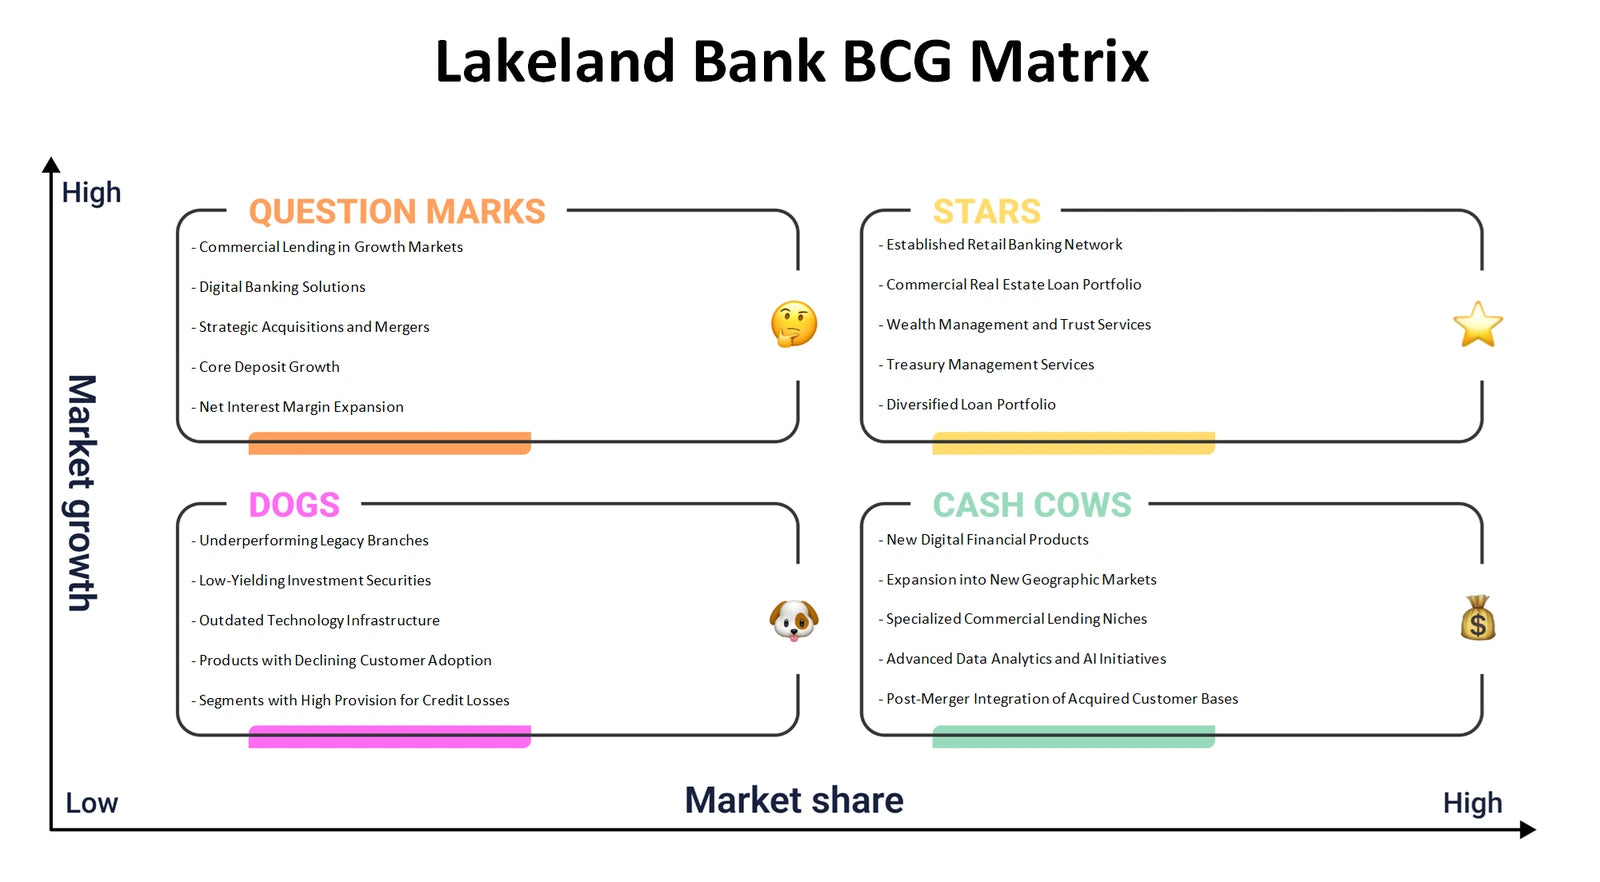
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do local relationships, credit decisions and banking services connect to the value Lakeland Bank offers commercial customers and to the economics of serving them?
The Lakeland Bank Business Model Canvas examines the connected logic behind a relationship-led banking proposition. Customer segments can include commercial borrowers and real-estate clients, while value propositions may centre on knowledgeable local service, financing support and responsive decisions. It then connects channels and customer relationships to revenue streams, such as the economic returns associated with banking relationships, without asserting specific financial outcomes. The nine building blocks also bring key resources, key activities, key partnerships and cost structure into view. This matters because relationship managers, underwriters, treasury specialists and local access may create value, but they also require disciplined operating capacity and risk management.
- Customer logic. Trace how businesses with time-sensitive property or operating needs may evaluate local expertise, responsiveness and ongoing banking support.
- Economic connections. Consider how relationship-building, lending, treasury services, risk processes and delivery costs fit together rather than treating each service in isolation.
- Model workshop. Use the Excel canvas to organise the nine building blocks and consult the Word analysis for company-relevant questions behind each connection.
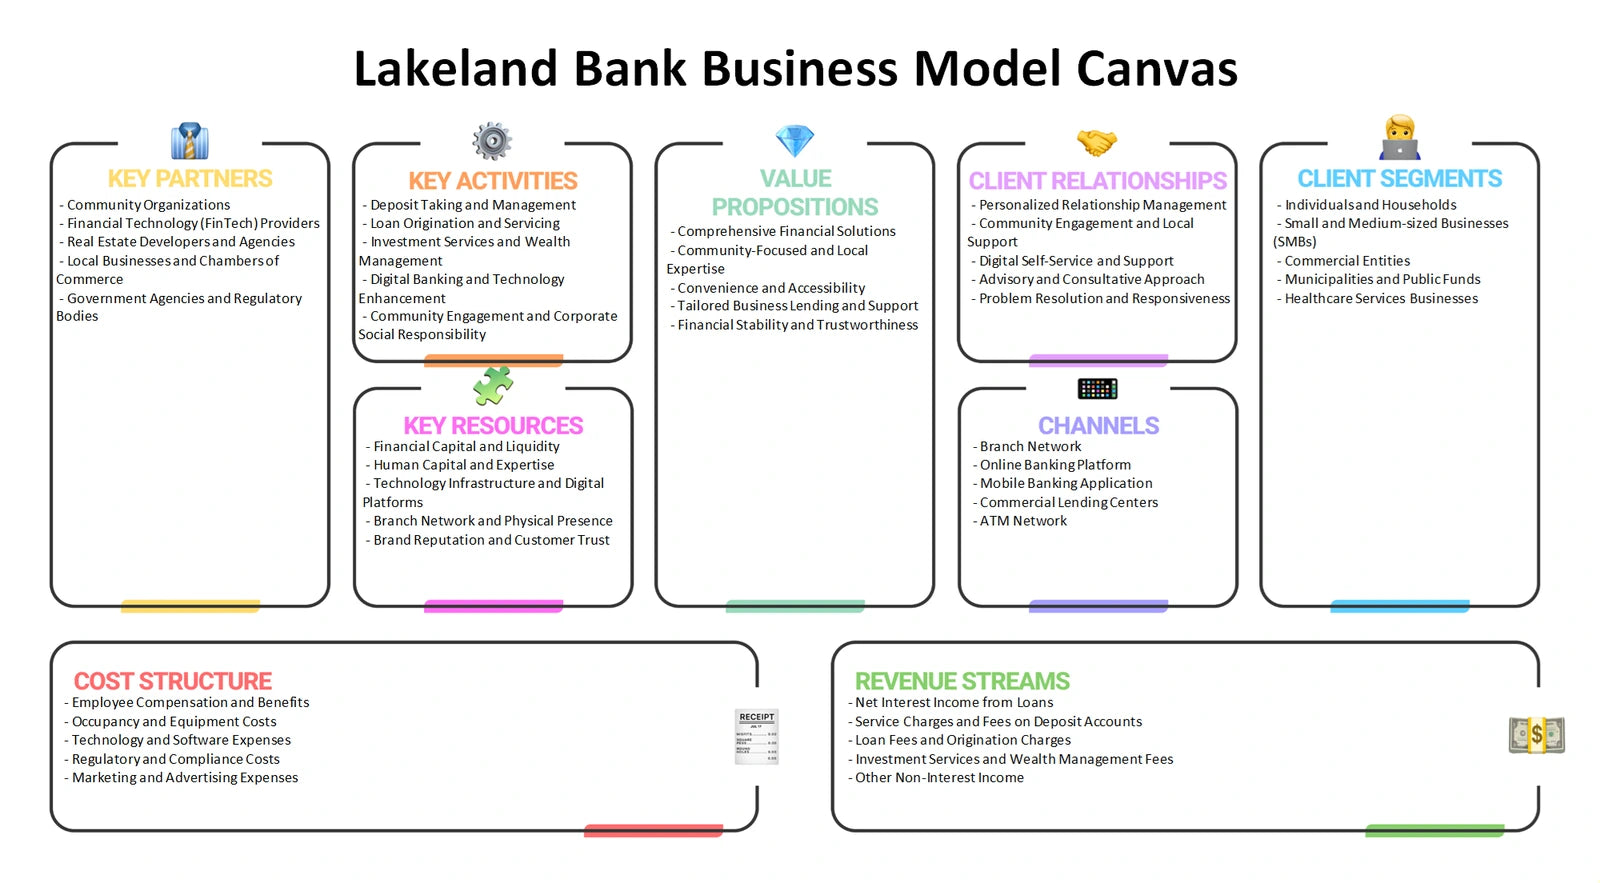
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape Lakeland Bank's ability to win and retain commercial banking relationships in its local markets?
Lakeland Bank Porter's Five Forces analysis considers the competitive environment around commercial banking and property-related financing rather than naming unverified competitors or assigning force scores. Rivalry can arise where banks seek the same local deposits, lending relationships and treasury business. Buyer power asks how readily commercial customers can compare credit terms, service responsiveness and banking alternatives. Supplier power is relevant to funding, specialist talent, technology and other inputs that support banking delivery. The framework also tests the threat of new entrants and the threat of substitutes, including non-bank lenders or alternative financing routes that meet a borrower need without being a traditional bank.
- Relationship competition. Examine whether local knowledge and faster coordination may differentiate service where customers can still evaluate multiple financing providers.
- Alternative finance. Distinguish direct banking rivals from substitutes such as private credit, specialist property lenders or other funding arrangements.
- Pressure map. Use the Excel structure to record evidence and assumptions by force, with the Word analysis supplying context for discussing implications and trade-offs.
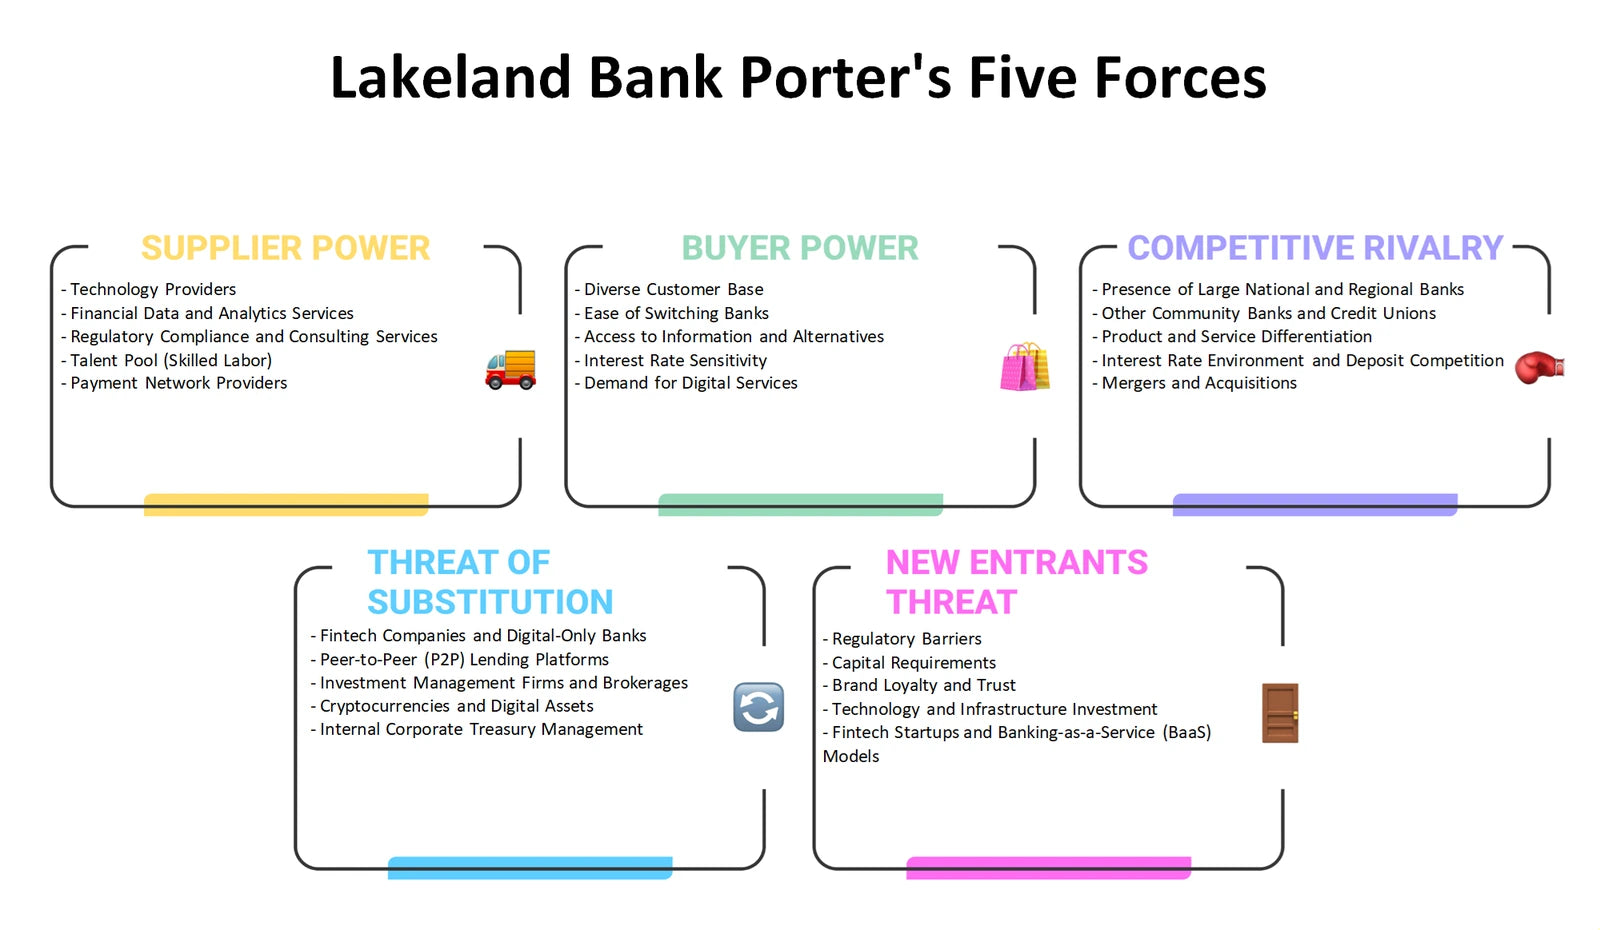
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Lakeland Bank's commercial proposition be assessed through Product, Price, Place and Promotion in a relationship-driven, regulated service market?
The Lakeland Bank Marketing Mix considers the 4Ps in a banking context where trust, suitability and long-term relationships matter as much as visibility. Product can cover the fit between commercial lending, real-estate finance, treasury support and the needs of business customers. Price concerns the logic behind rates, fees, risk and relationship economics, not invented price points. Place includes the role of local New Jersey teams, banker access and practical customer touchpoints. Promotion considers how a bank may communicate expertise and service benefits clearly while respecting the limits and responsibilities of financial-services communication. Together, the framework helps separate a useful customer proposition from unsupported marketing claims.
- Offering fit. Assess how financing and treasury needs may differ between operating businesses, developers and property investors.
- Route to customer. Explore how local relationship managers and service access can influence discovery, confidence, application progress and continuing support.
- Message planning. Use the Excel 4Ps grid to compare customer-facing choices, then use the Word analysis to develop a more considered discussion of the trade-offs.
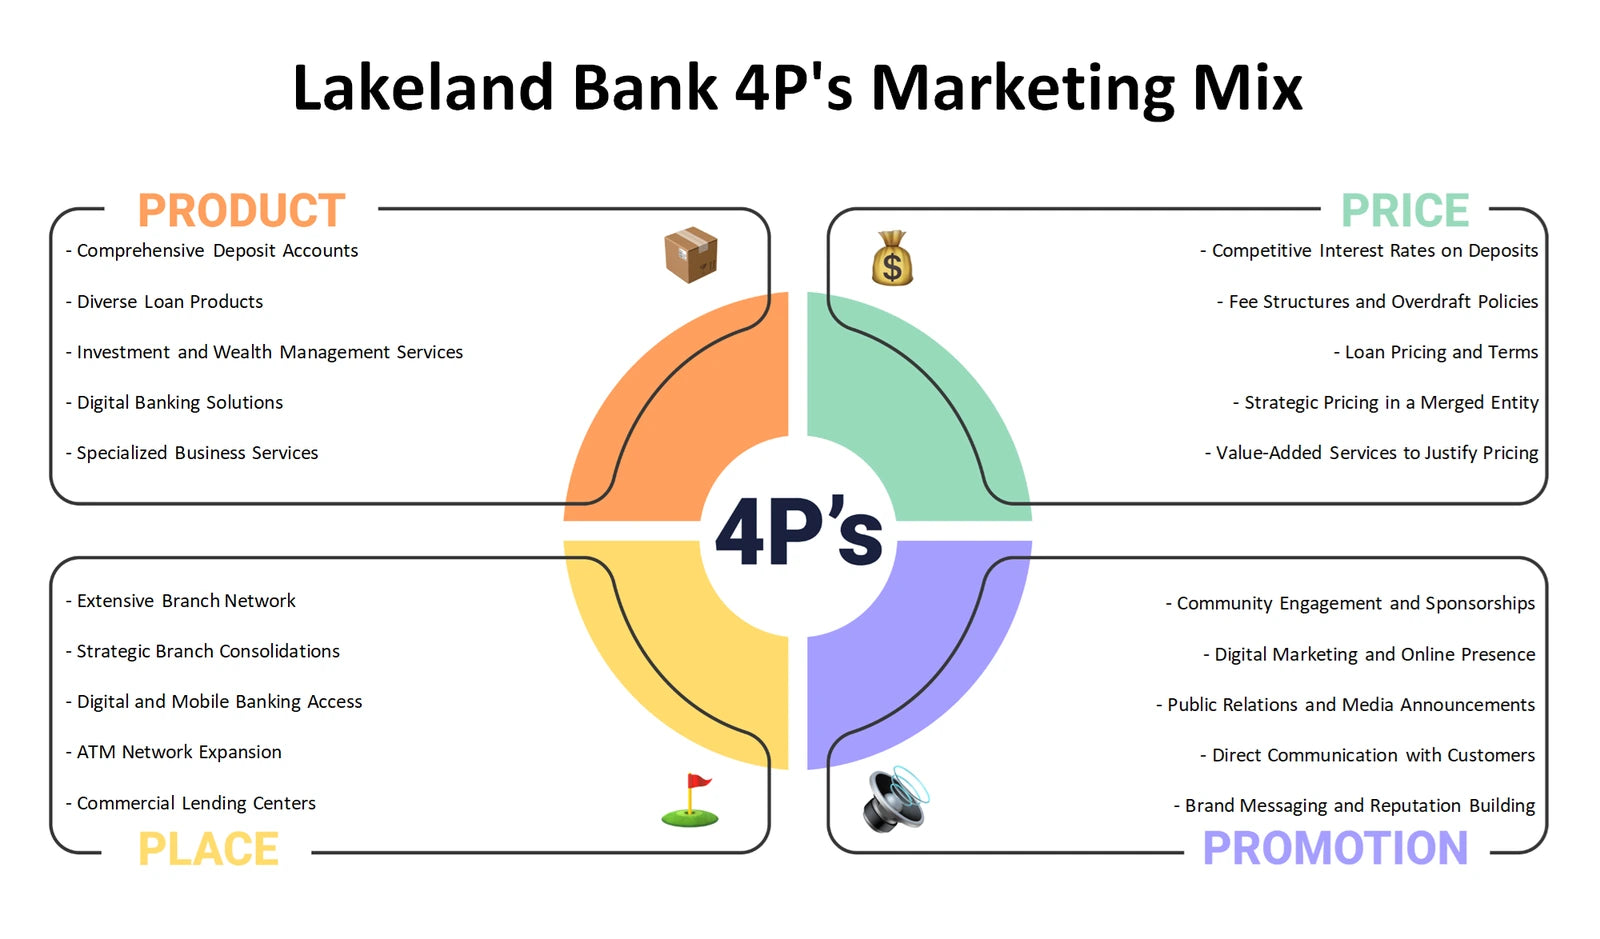
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should Lakeland Bank monitor when serving commercial borrowers and real-estate clients in a changing banking environment?
The Lakeland Bank PESTLE analysis, also commonly called PESTEL, separates external influences from internal capabilities. Political factors can include the policy environment affecting financial institutions and local development. Economic questions may cover borrowing demand, property-market conditions, inflation or interest-rate sensitivity without claiming a current rate change. Social factors include customer expectations for responsive, trusted service. Technological factors examine digital banking, data security and workflow expectations alongside the value of local advice. Legal conditions concern banking, lending, consumer-protection and compliance obligations, while environmental factors can affect property risk, construction activity and borrower resilience. The purpose is to identify questions worth monitoring, not to present every external factor as a documented change.
- Market sensitivity. Consider how commercial and real-estate borrowers may respond differently to economic uncertainty, financing conditions and project timing.
- Operating resilience. Examine the external implications of regulation, cybersecurity expectations, technology adoption and environmental exposure for a local banking model.
- Monitoring agenda. Use the Excel framework to group external signals by category and use the Word analysis to connect them to practical management questions.
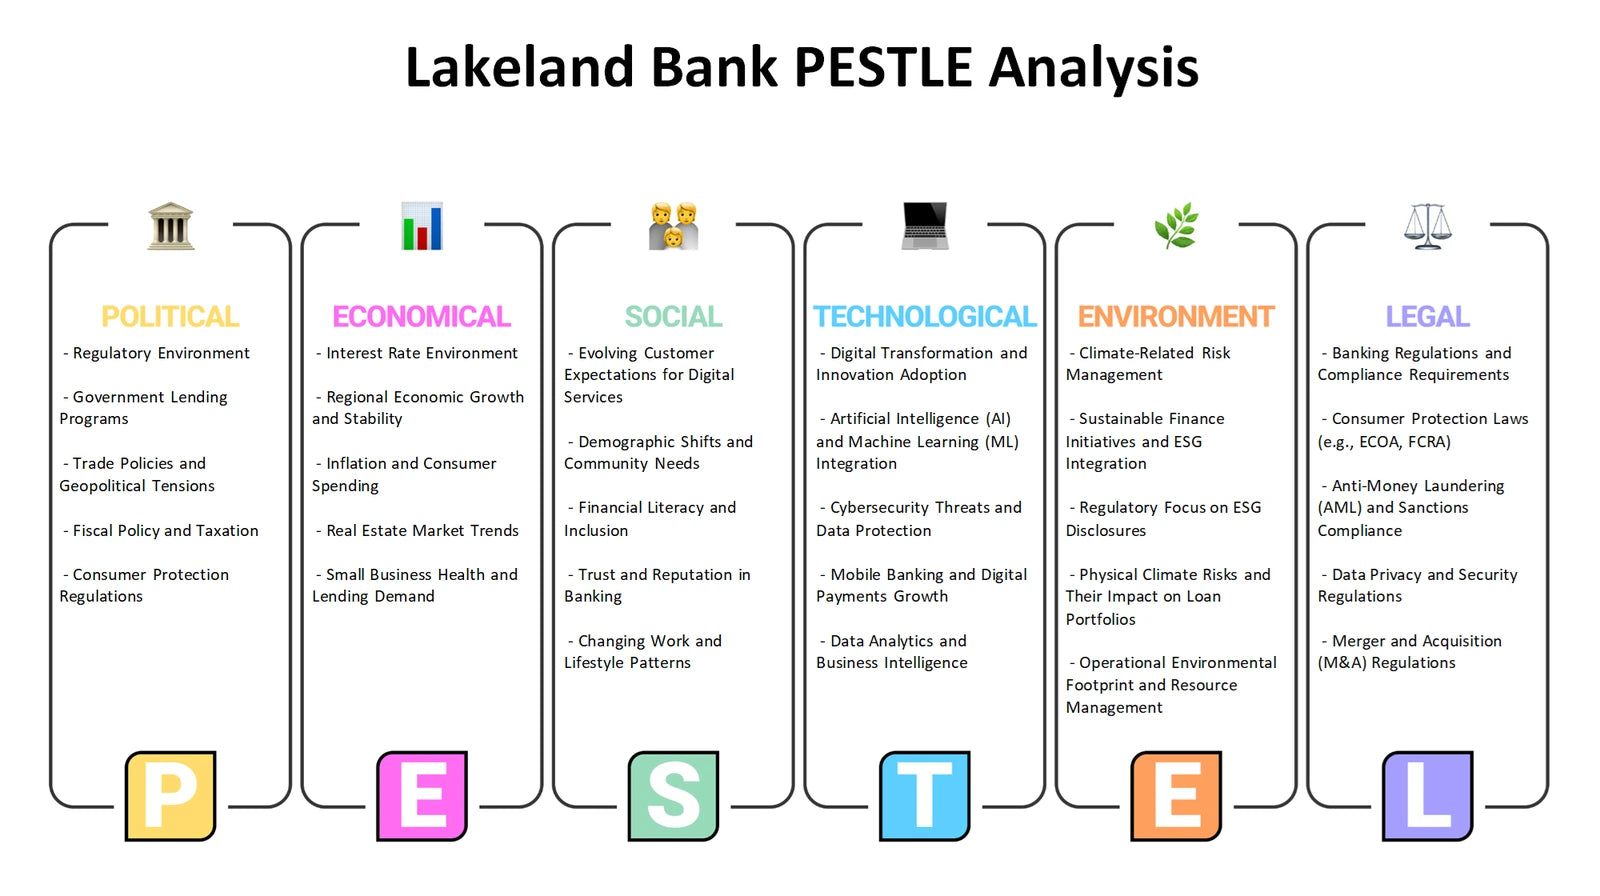
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Lakeland Bank distinguish its internal relationship-banking capabilities and constraints from the opportunities and threats created by its market environment?
The Lakeland Bank SWOT analysis keeps internal and external considerations properly separated. Possible strengths to examine include experienced relationship managers, underwriting knowledge, treasury expertise and familiarity with local commercial markets, as described in the product context. Potential weaknesses are internal limitations or dependencies that require evidence and should not be assumed as facts. Opportunities sit outside the organisation, such as changing customer needs or underserved financing requirements, while threats can include competitive pressure, credit-market volatility, substitute lenders or changing regulation. This distinction is especially useful for a bank because a capability is not automatically an opportunity, and an external market condition is not automatically a weakness. The framework supports a balanced discussion before priorities are chosen.
- Capability test. Evaluate how local insight, responsive coordination and specialist expertise may support commercial relationships while identifying areas that need careful validation.
- External fit. Compare potential market openings with risks from property cycles, funding conditions, compliance demands and alternative providers.
- Decision summary. Use the Excel matrix to separate internal from external observations, then draw on the Word analysis to formulate evidence-led strategic discussion points.
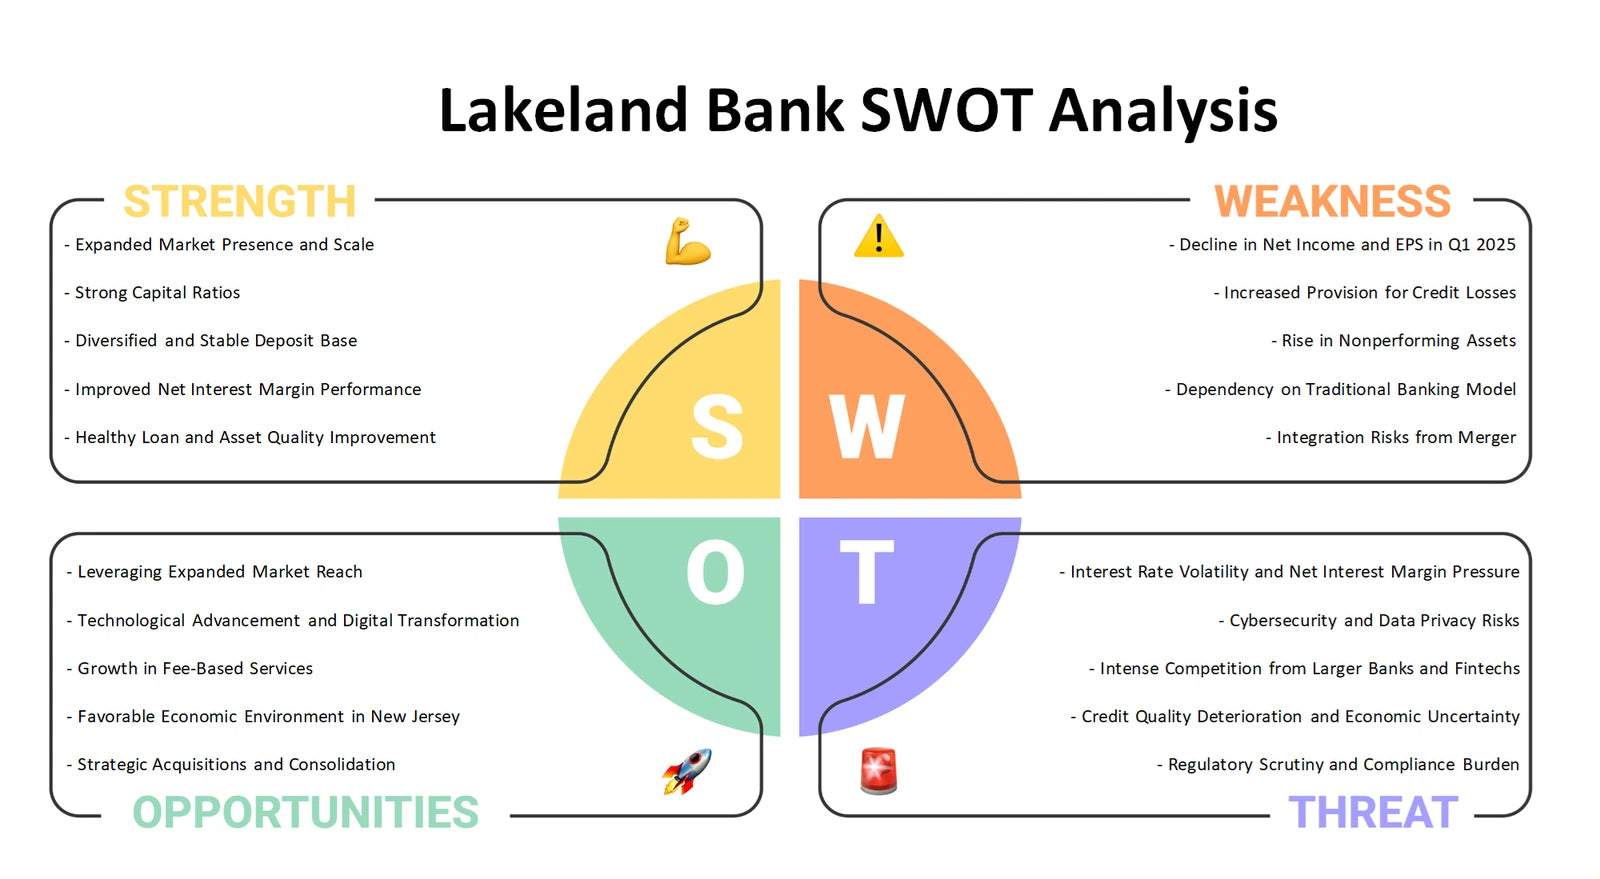
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect local banking insight with a broader strategic view
Together, the six perspectives let you examine Lakeland Bank from complementary angles: portfolio focus, value creation, industry pressure, customer-facing choices, external change and strategic fit. The Excel frameworks provide a structured way to organise comparisons and questions, while the Word files provide detailed company analysis to support more informed discussion of commercial banking, treasury relationships and real-estate financing priorities.
Company background: Lakeland Bank — matching product-context page.