

Kearny Bank: Banking Business and Product Innovation – Six-Framework Review

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Kearny Bank Strategy Analysis Bundle
Kearny Bank is a United States full-service community bank. Its official website says it provides banking services throughout New Jersey, Brooklyn, and Staten Island and serves individuals; the supplied product context also points to relationships with local businesses and community groups. Founded in 1884, the bank provides a specific community-banking setting for the six strategic frameworks.
The supplied bundle context describes FinTech collaboration to support digital banking and identifies ZSuite Technologies' ZEscrow product as an example of a specialised escrow service. These are analytical starting points rather than proof of current performance. The materials help examine product priorities, business-model economics, industry pressure, marketing choices, external conditions, and internal-versus-external strategic questions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking services deserve protection, testing, investment, or tighter resource discipline?
A Kearny Bank BCG Matrix separates portfolio choices using market growth and relative market share. It does not assign a verdict to an offering automatically; instead, it helps compare established local banking relationships with digitally enabled or specialist propositions. Stars, Cash Cows, Question Marks, and Dogs provide a common language for discussing where management attention, technology capacity, and customer-service effort may be most useful.
- Portfolio lens. Compare service categories by their relevant customer demand, competitive position, and strategic role rather than by headline visibility alone.
- Resource trade-offs. Consider whether a mature offer can support investment in a developing digital or escrow-related proposition.
- Structured review. Use the Excel matrix to organise comparison inputs, then use the Word analysis to interpret assumptions and decision questions.
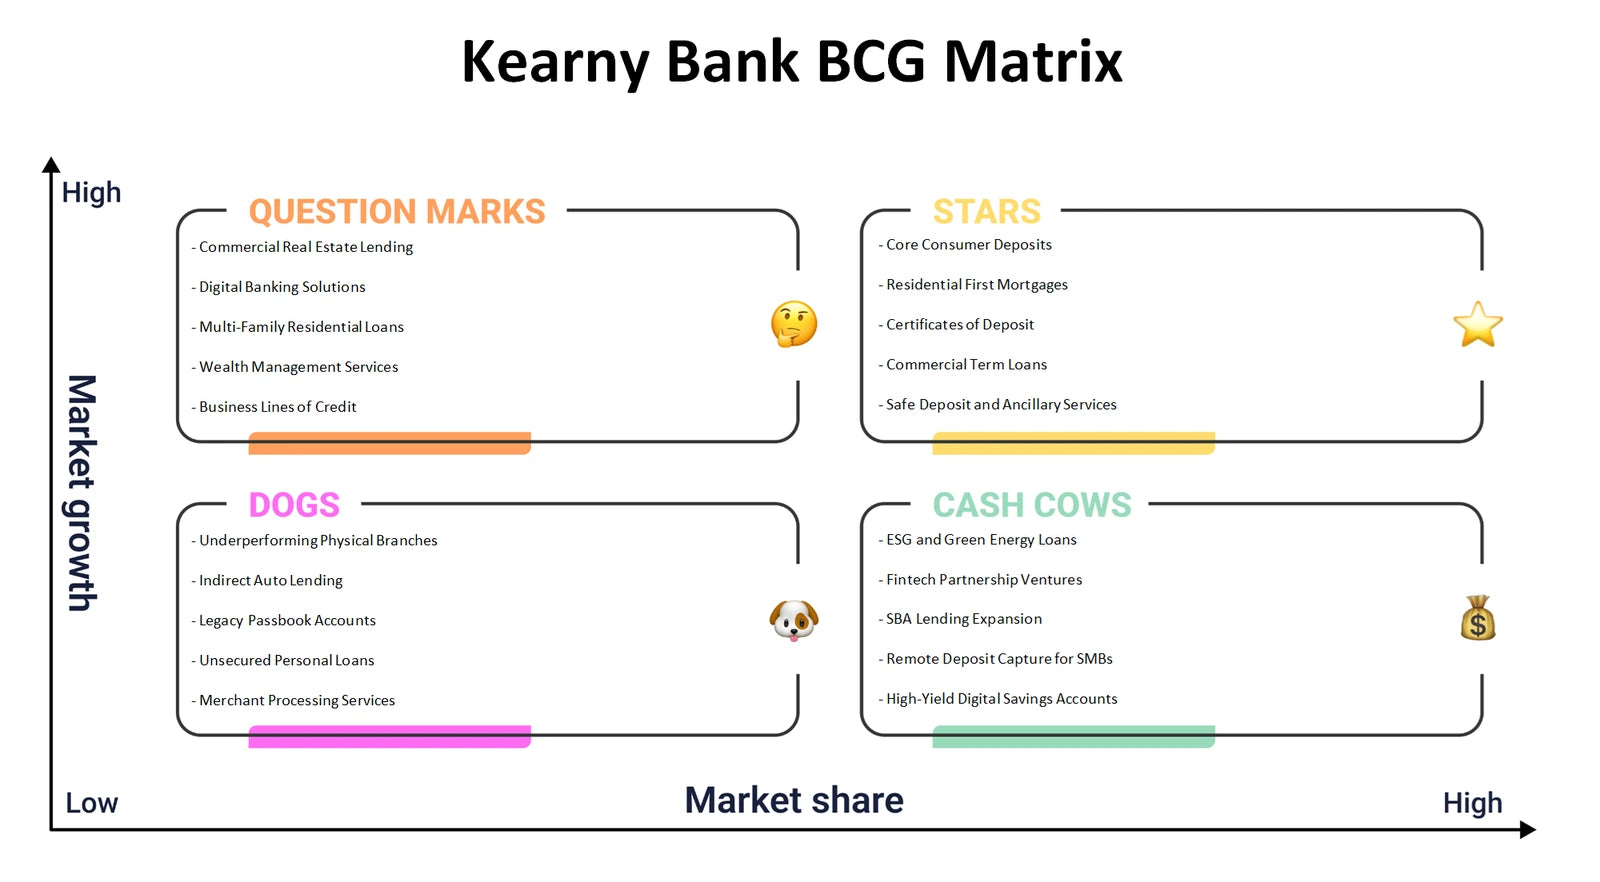
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, local delivery, digital capability, and banking economics fit into one operating model?
The Kearny Bank Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships, and cost structure. For a community bank, this lens helps relate customer trust and service access to the operational work behind secure transactions, compliance, technology, and relationship management. It also makes the supplied FinTech and community-partnership context useful as a question about how value is delivered, not as an unsupported claim about results.
- Value connections. Map how individual and local-business needs may connect with service, convenience, security, and specialised banking support.
- Economic logic. Examine how relationship channels, resources, partnerships, and operating costs may influence sustainable revenue streams.
- Model mapping. Complete the Excel canvas block by block while using the Word analysis to explain the links and trade-offs between blocks.
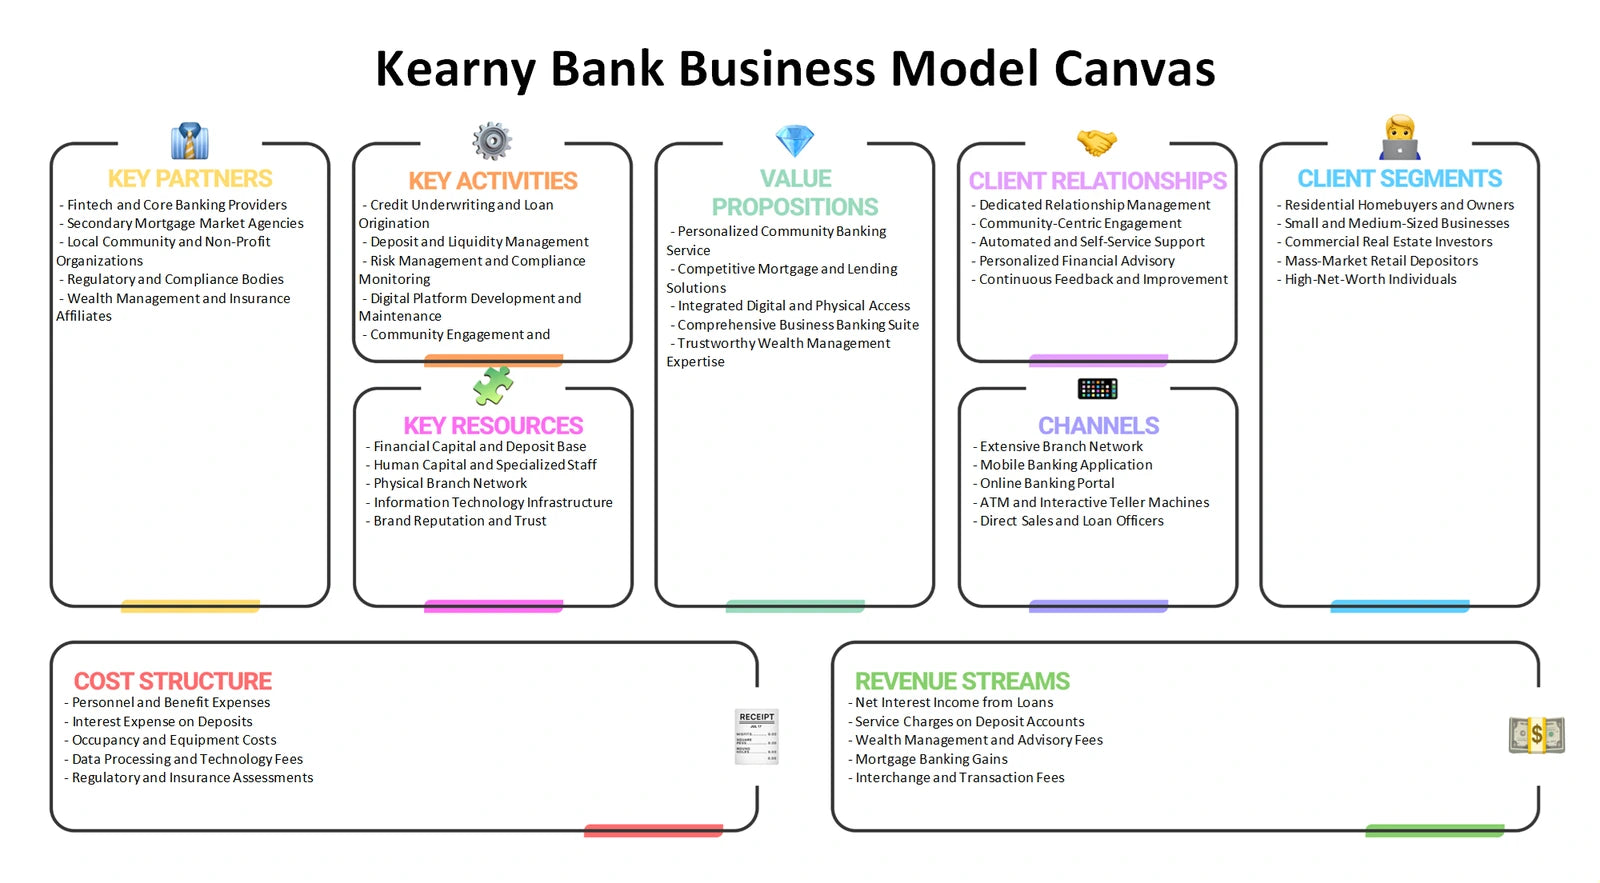
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures can shape Kearny Bank's ability to attract deposits, serve borrowers, and maintain valued relationships?
Kearny Bank Porter's Five Forces frames community banking as an industry shaped by rivalry, supplier power, buyer power, the threat of new entrants, and the threat of substitutes. Rivalry can involve banks competing for trust and customer relationships; buyer power concerns the choices available to depositors and business clients. Supplier power can arise around technology, payment infrastructure, specialised providers, and skilled capabilities. New digital financial providers and substitutes such as alternative payment, lending, or investment options can meet parts of the same customer need without being direct bank competitors.
- Competitive boundaries. Distinguish direct banking competition from substitutes that reduce reliance on traditional banking services.
- Dependency check. Explore where external technology or specialist partners may affect cost, flexibility, security, or service differentiation.
- Pressure comparison. Use the Excel framework to record force-specific evidence and the Word file to develop balanced implications rather than force scores.
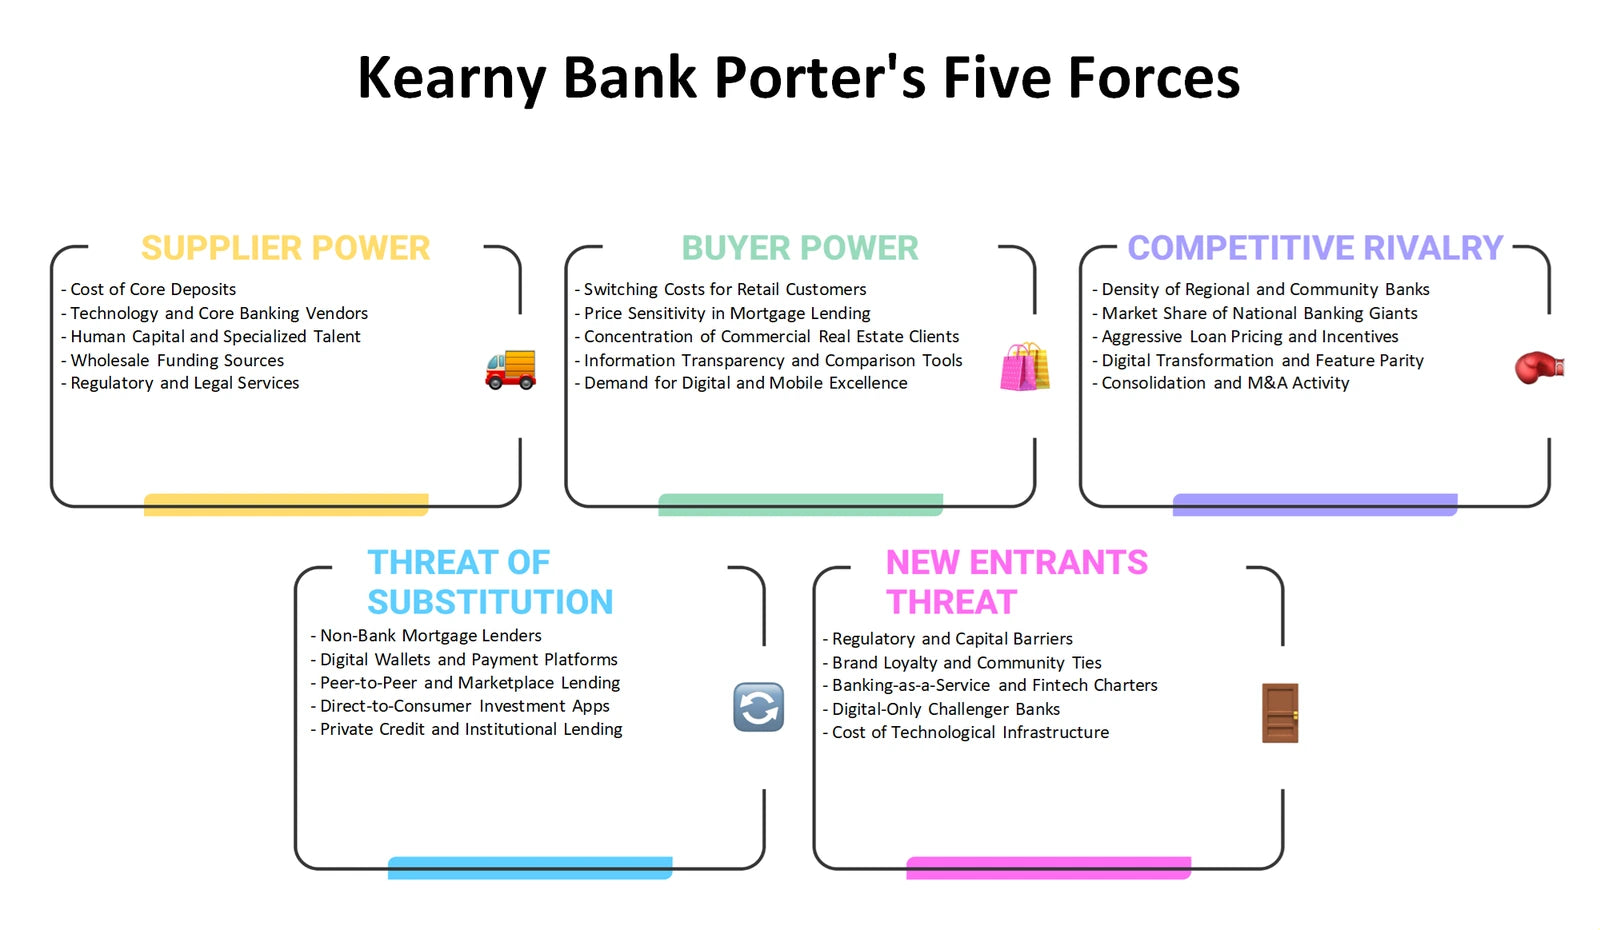
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking propositions be aligned with customer value, pricing logic, service access, and trusted communication?
The Kearny Bank Marketing Mix applies Product, Price, Place, and Promotion to a regulated service business. Product analysis can compare banking needs with digital, payment, and escrow-related propositions. Price focuses on the logic of rates, fees, terms, and perceived value rather than inventing actual prices. Place considers service availability across the bank's stated New Jersey, Brooklyn, and Staten Island footprint alongside digital access. Promotion examines how community relevance, security, clarity, and relationship trust may be communicated responsibly to individuals and local businesses.
- Offer design. Test whether each product proposition addresses a recognisable customer need and is understandable at the point of choice.
- Channel fit. Compare the role of local presence, online banking, and specialist service journeys without assuming channel shares.
- Marketing worksheet. Use the Excel 4Ps structure to organise choices, then consult the Word analysis for the strategic rationale behind each element.
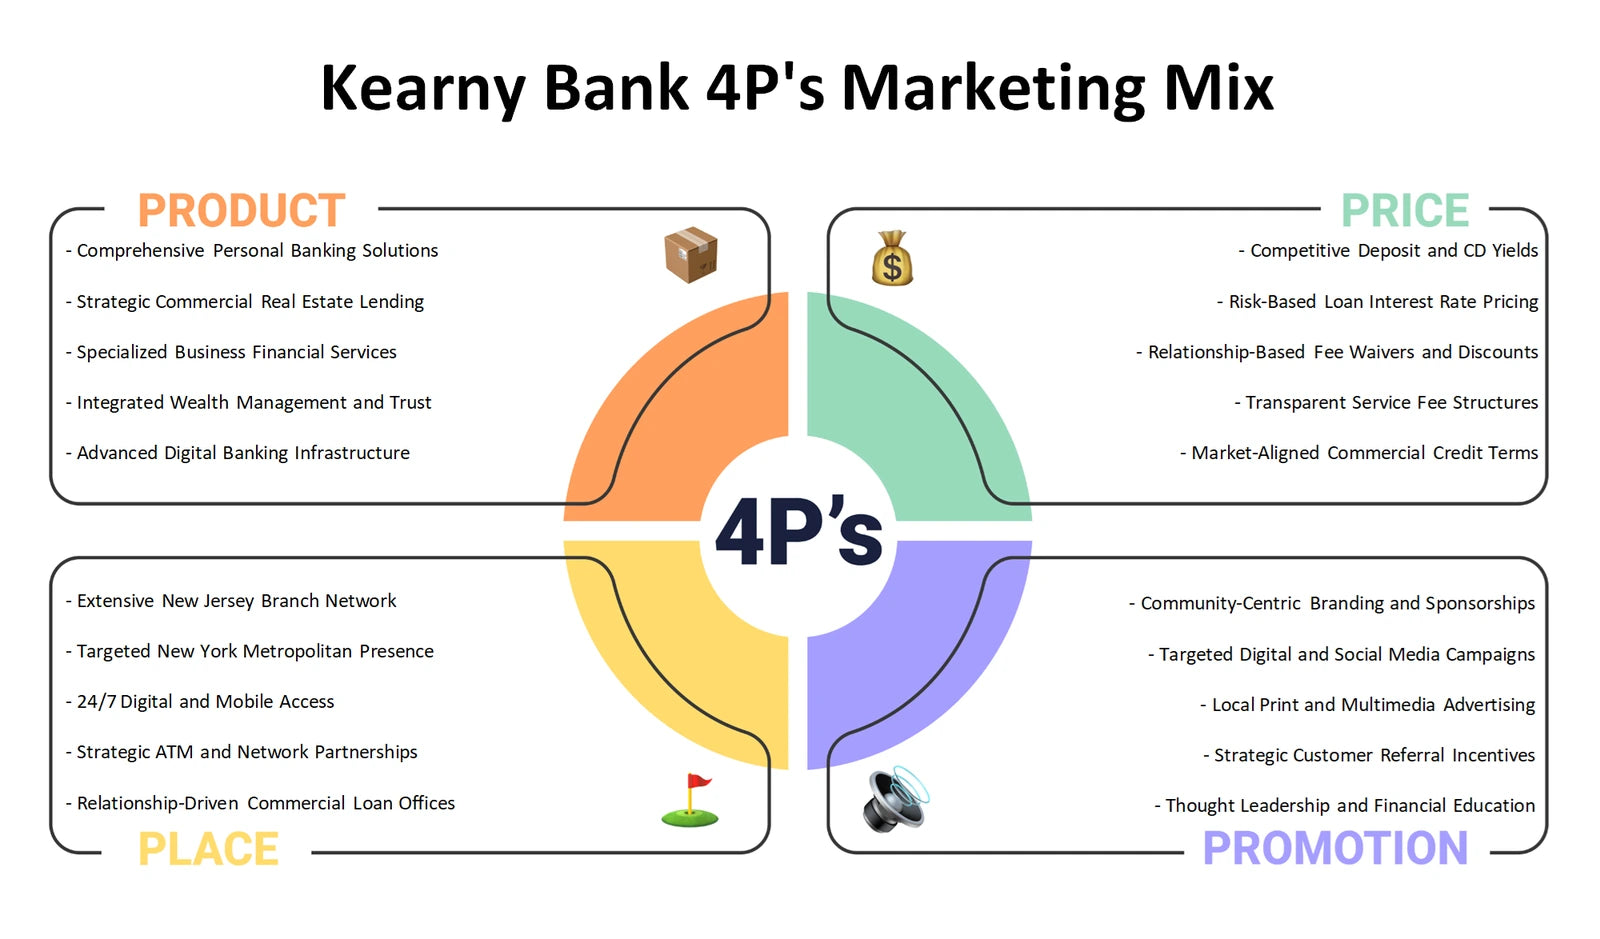
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter the conditions under which a community bank serves its customers and communities?
A Kearny Bank PESTLE analysis examines Political, Economic, Social, Technological, Legal, and Environmental influences around United States community banking. Political and legal questions can include supervisory policy, consumer protection, and privacy expectations. Economic analysis can consider rate-sensitive customer behaviour, funding conditions, and credit demand without asserting a current rate change. Social factors include local demographics and changing expectations for convenience. Technology covers secure digital services and cyber resilience; environmental considerations can include operational continuity and physical disruption exposure. PESTEL is a commonly used alternative spelling for the same framework.
- External scanning. Separate confirmed external developments from issues that should be monitored, tested, or researched further.
- Local relevance. Relate broad banking trends to the communities Kearny Bank says it serves in New Jersey, Brooklyn, and Staten Island.
- Scenario workspace. Use the Excel categories to capture signals and uncertainties, with the Word analysis supporting interpretation of possible implications.
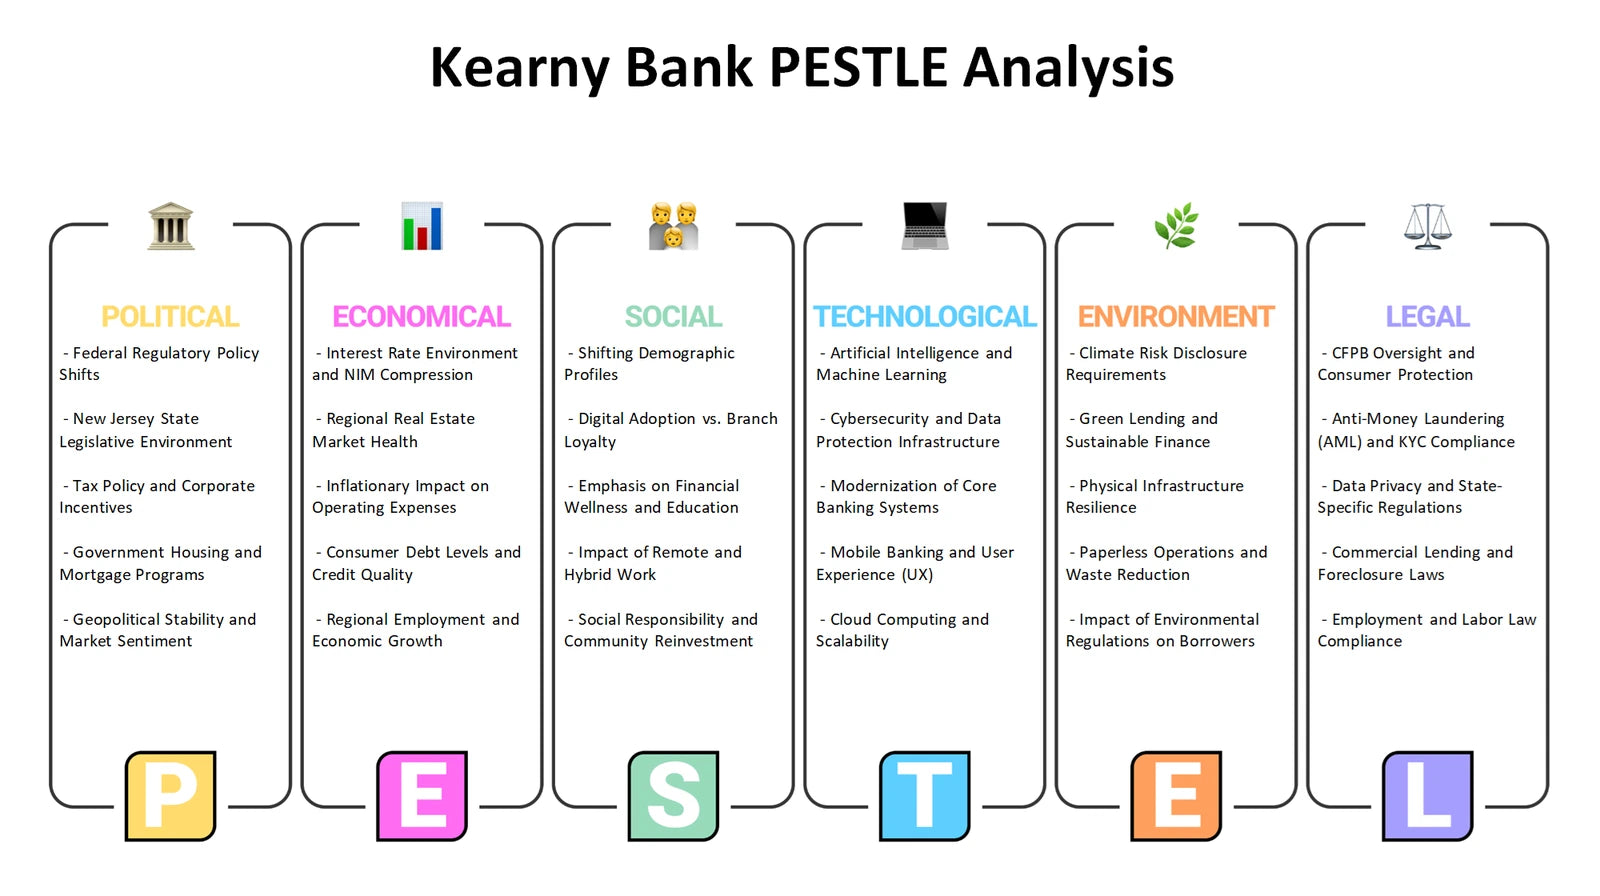
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside the opportunities and threats facing Kearny Bank?
A Kearny Bank SWOT analysis keeps internal and external issues distinct. Strengths and weaknesses concern capabilities within the organisation, such as relationship knowledge, service delivery, technology readiness, operating complexity, or resource constraints that require validation. Opportunities and threats arise outside the bank, including changing customer expectations, digital alternatives, sector competition, and the regulatory environment. The bank's long history, stated service geography, and supplied digital-partnership context can guide questions, but they should not be converted into automatic strengths or weaknesses without evidence.
- Classification discipline. Prevent external market pressures from being labelled as weaknesses, or internal operating matters from being labelled as threats.
- Strategic matching. Explore how a validated capability might address an external opportunity, or where a limitation could increase exposure.
- Action-oriented synthesis. Use the Excel SWOT grid to organise observations and the Word analysis to turn them into focused discussion priorities.
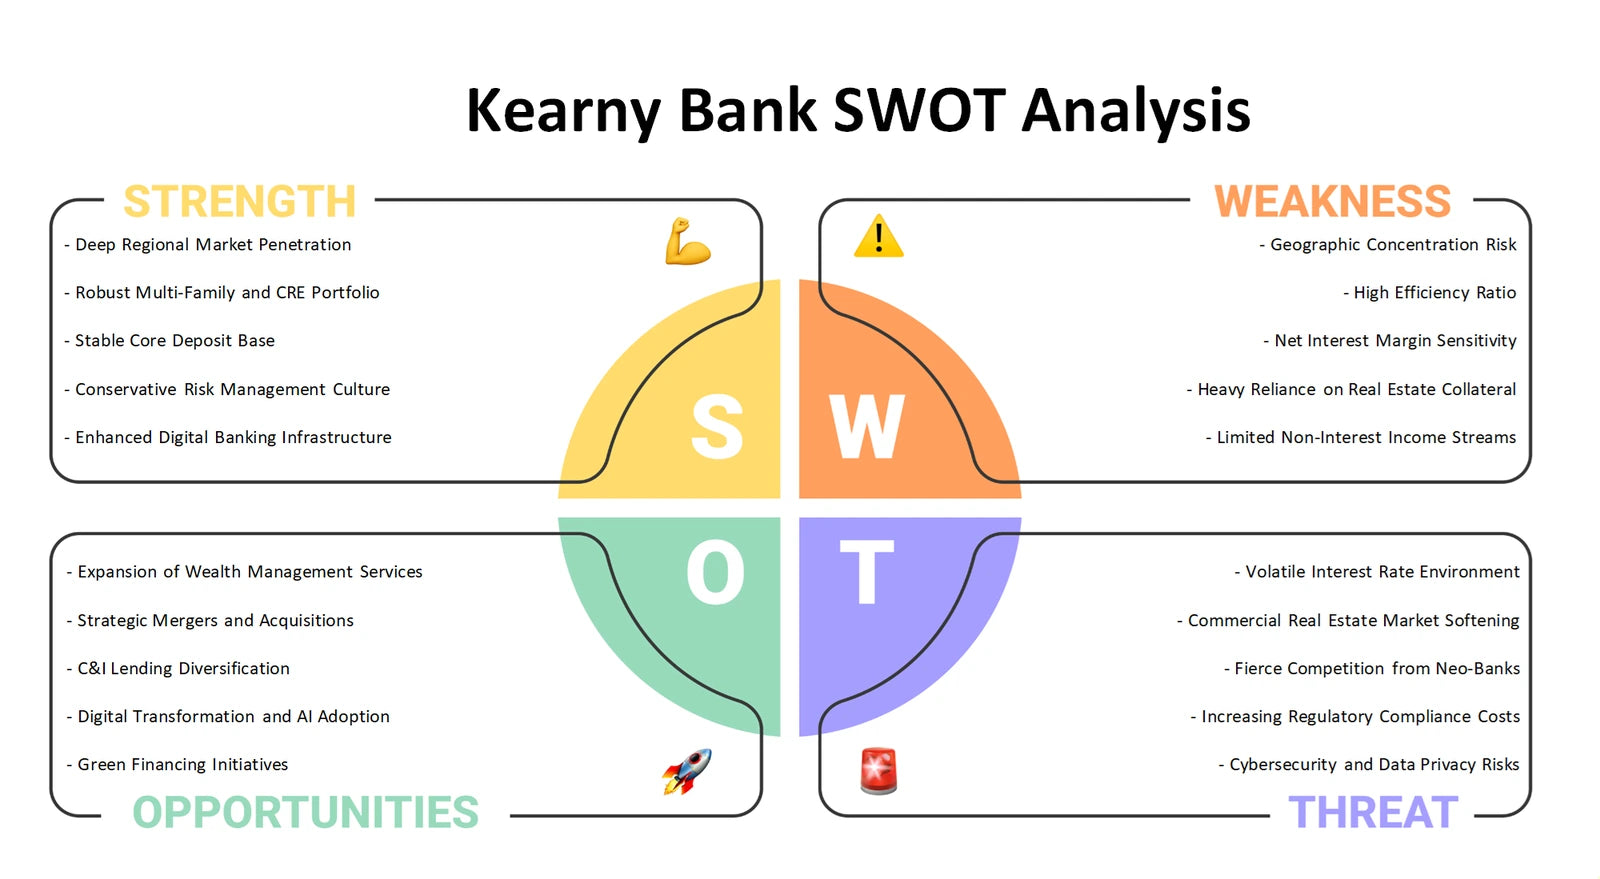
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected strategic view of Kearny Bank
Used together, the six perspectives move from portfolio priorities and business-model logic to competitive conditions, customer choices, external forces, and strategic fit. The Excel frameworks provide structured places to compare inputs, while the Word files provide detailed company analysis to support clearer discussion, research preparation, and decision-oriented review.
Company background: Kearny Bank — official website.