

Intact Financial: Insurance Business and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Intact Financial Strategy Analysis Bundle
Intact Financial is a Canadian insurance company whose customer-facing context includes auto, home and business insurance. Its route to market includes independent insurance brokers and BrokerLink, its wholly owned brokerage subsidiary, making distribution relationships important alongside underwriting, claims service and risk selection.
The company context behind this bundle also highlights technology and AI partnerships supporting platform modernization, pricing, claims handling and customer experience. That makes portfolio priorities, broker-channel economics and the balance between digital capability, regulation and insurance risk especially useful questions to examine. The six connected analyses help turn those questions into a structured view rather than presenting unverified conclusions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance lines or distribution-focused activities deserve resources when growth potential and relative market share point in different directions?
An Intact Financial BCG Matrix helps assess a portfolio through the two original BCG dimensions: market growth and relative market share. For an insurer, the comparison can explore personal and business insurance categories, distribution opportunities or capability investments without assuming that any one activity already occupies a particular quadrant. Stars, Cash Cows, Question Marks and Dogs are analytical categories for comparing possible resource priorities, not labels that should be assigned without supporting market and performance evidence. This is useful where capital, underwriting attention, broker support and technology spending may compete for management focus.
- Portfolio logic. Compare how growth conditions and relative share could alter the role of auto, home or business insurance opportunities within a broader portfolio discussion.
- Capital discipline. Consider whether a mature activity may support cash generation while a less established opportunity needs evidence before attracting additional investment.
- Structured review. Use the Excel framework to organize comparison inputs, then use the detailed Word analysis to interpret the assumptions and questions behind each potential quadrant.
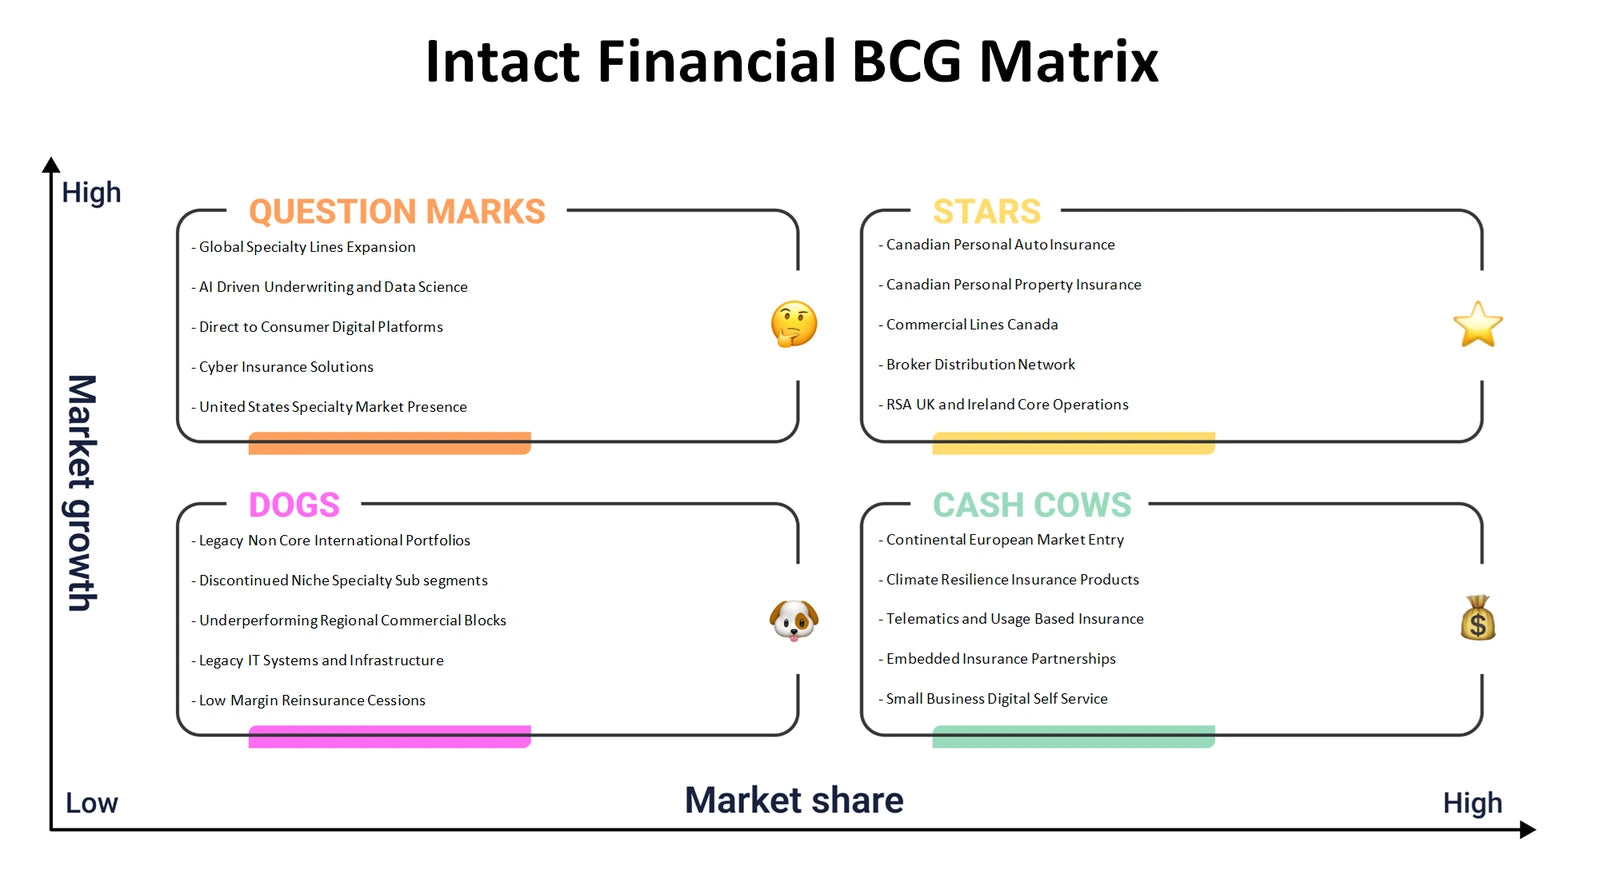
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do broker relationships, insurance expertise and digital modernization fit together to create value and generate sustainable economics?
The Intact Financial Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It helps examine how households and businesses may access insurance through broker-led channels; how coverage, claims support and service experience create value; and how underwriting, pricing, claims operations and technology capabilities support that promise. Independent brokers, BrokerLink and technology providers are relevant partnership questions because they affect customer access, data flows, operating coordination and the cost of service delivery. The canvas does not presume a single revenue mix or cost position; it provides a disciplined way to test the links between them.
- Value delivery. Map the relationship between insurance customers, broker channels, service expectations and the practical moments when coverage or claims support matters most.
- Economic connections. Examine how premium-based revenue logic, underwriting activities, claims costs, technology resources and partnership dependencies may influence one another.
- Connected evidence. Use the Excel framework to trace the nine blocks in one view, alongside the Word analysis for fuller explanation of the business-model relationships.
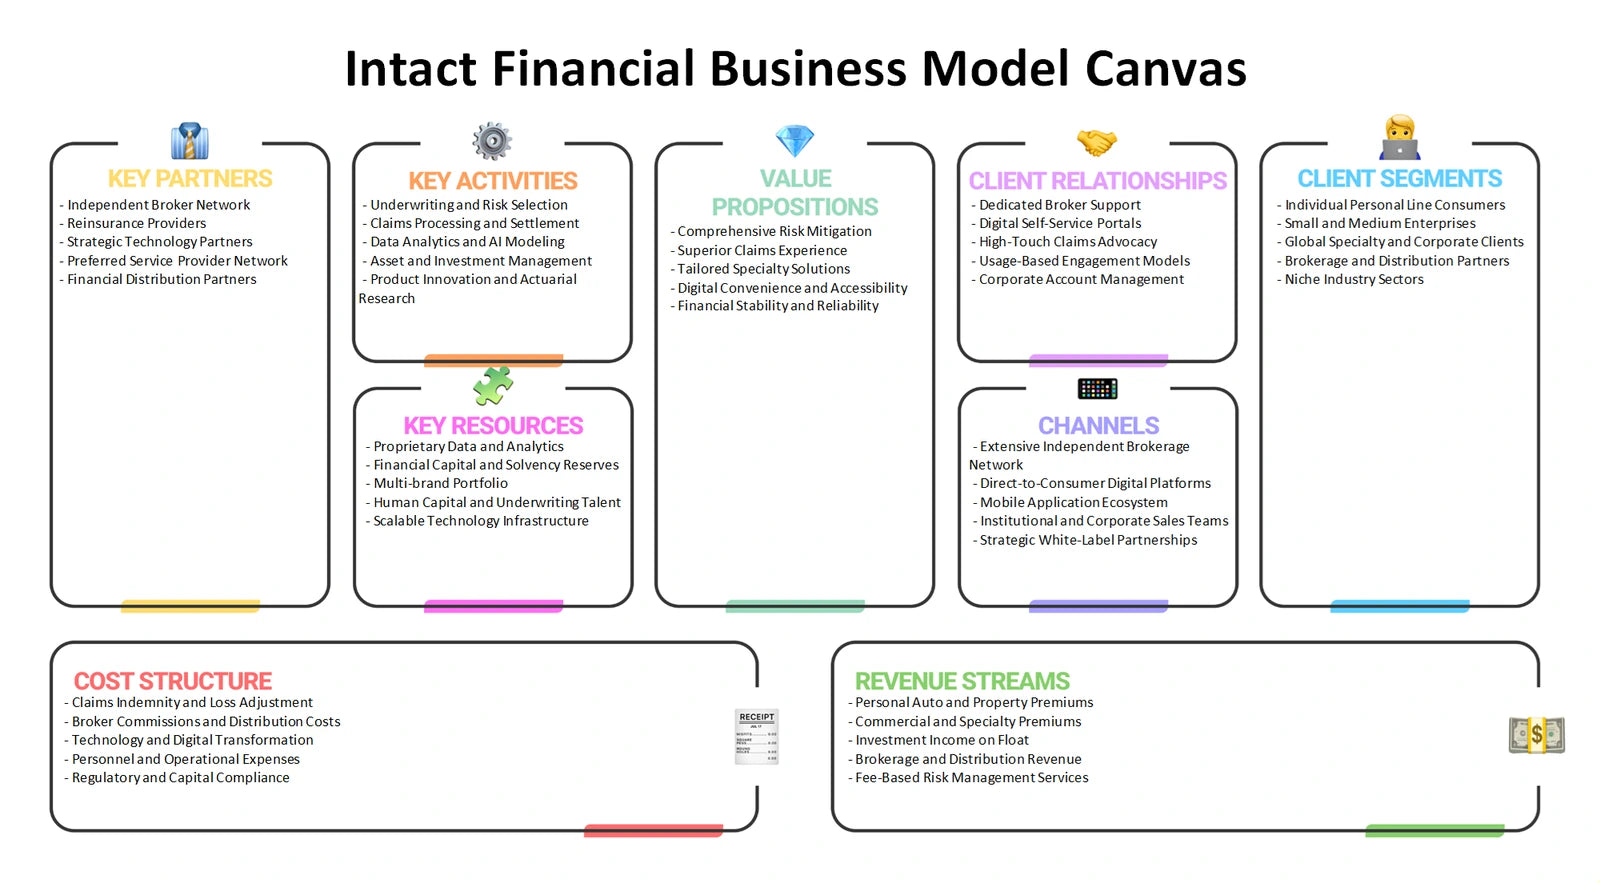
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures shape the attractiveness of Canadian insurance markets beyond direct competition for policies?
Intact Financial Porter's Five Forces analysis frames industry pressure through rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes. Rivalry can be considered across insurers competing for policies, broker relationships and service reputation. Supplier power may involve reinsurance capacity, repair and claims-service networks, specialist technology providers or access to relevant talent. Buyer power is shaped by customer choice, broker influence, renewal decisions and the ability to compare coverage. New entrants may include digital specialists, while substitutes are alternative ways customers meet a risk-management need, such as retaining more risk or using non-insurance arrangements. The framework helps distinguish these forces instead of treating every challenge as simple price competition.
- Competitive pressure. Assess how underwriting discipline, claims experience and broker support may matter when insurance offerings appear similar to customers.
- Dependency exposure. Consider where external providers, reinsurance markets or channel partners could affect costs, capacity, service levels or negotiating leverage.
- Force comparison. Use the Excel framework to compare the five forces consistently, then refer to the Word analysis for the reasoning and sector context behind each pressure.
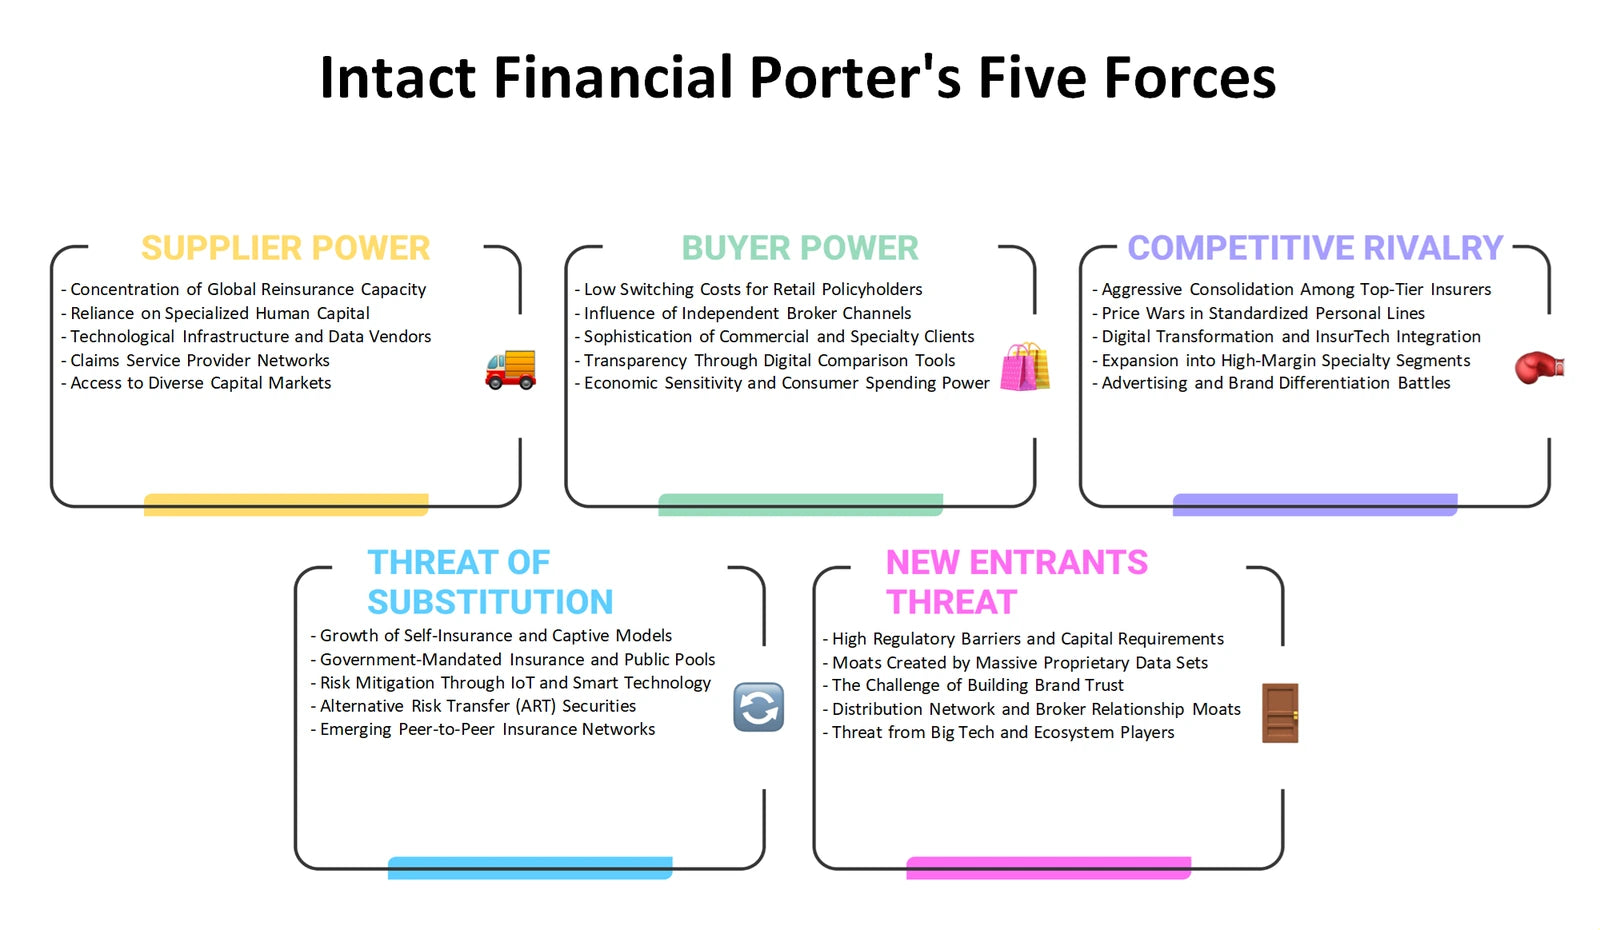
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can insurance offerings, pricing logic, broker access and customer communication be considered as one coordinated market approach?
An Intact Financial Marketing Mix examines Product, Price, Place and Promotion in the practical setting of insurance. Product concerns the coverage, service and claims experience customers seek across auto, home and business needs. Price is not merely a list amount: analysis can consider underwriting, risk characteristics, coverage terms, customer value and the regulated context in which insurance is sold. Place is particularly relevant because broker relationships and BrokerLink provide routes through which customers can compare, understand and purchase coverage. Promotion can assess how clear communication, broker enablement and trust-building messages support informed decisions without assuming any specific campaign or channel share. Together, the 4Ps help test whether customer-facing choices reinforce the operational model.
- Offer design. Compare how coverage needs, claims expectations and service features may differ between household and business insurance customers.
- Channel fit. Examine how broker-led distribution can influence advice, customer relationships, communication needs and the presentation of insurance value.
- Four-part planning. Use the Excel framework to review Product, Price, Place and Promotion side by side, supported by the Word analysis for company-relevant context.
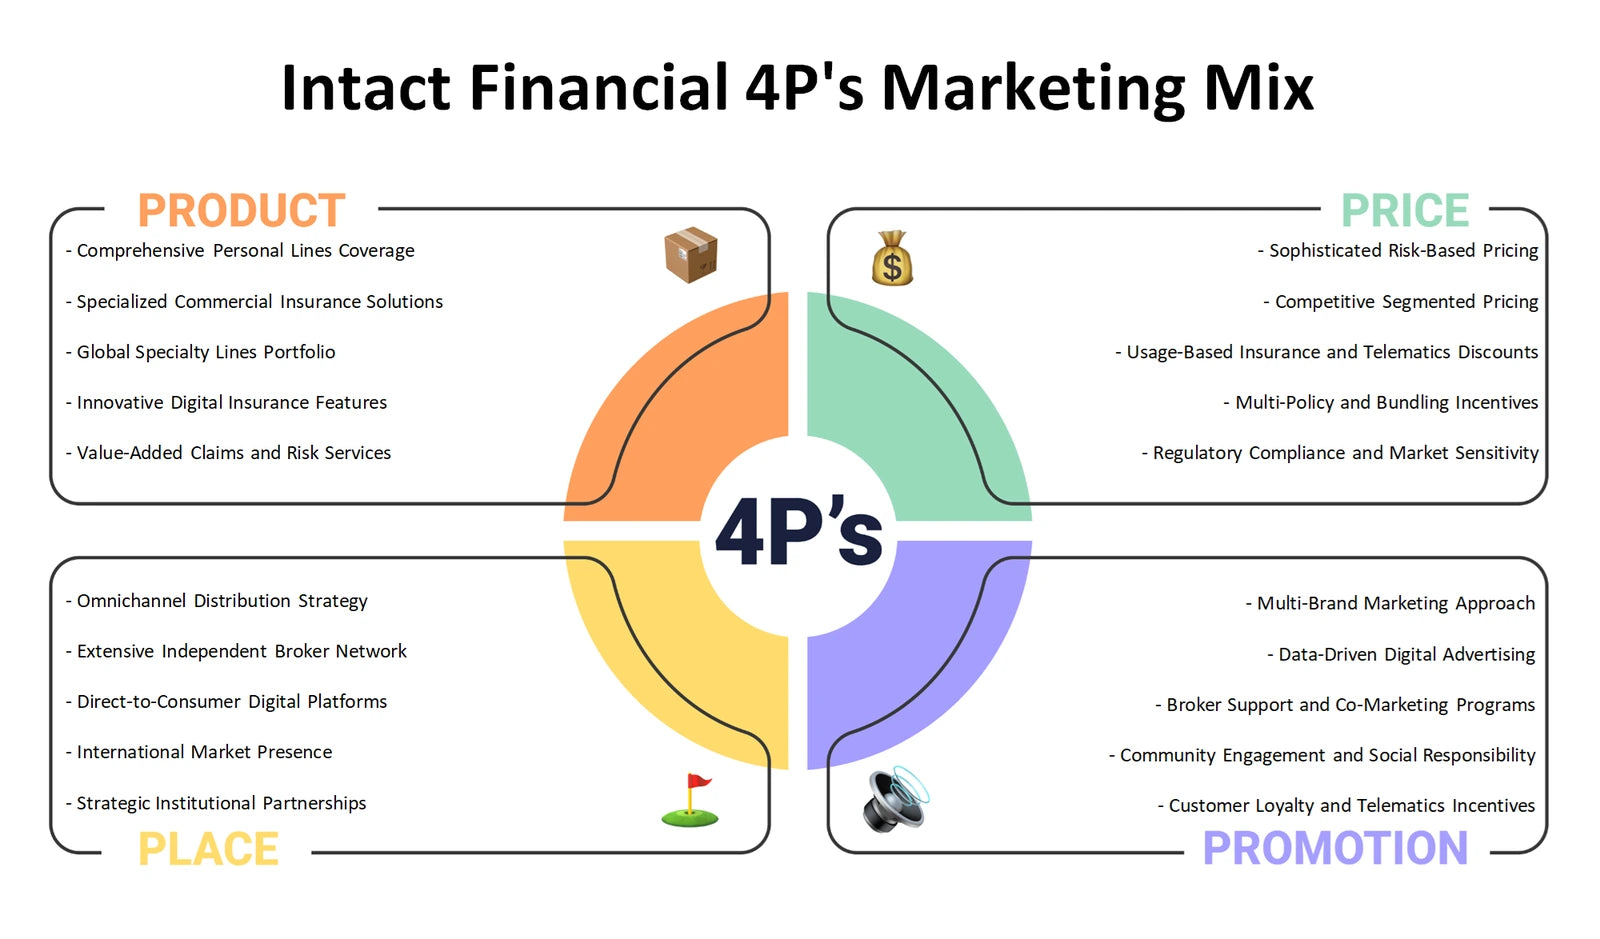
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter insurance demand, underwriting assumptions, claims costs or customer expectations in Canada?
An Intact Financial PESTLE analysis, also commonly called PESTEL, organizes external influences into Political, Economic, Social, Technological, Legal and Environmental categories. Political and legal questions can include provincial insurance policy, consumer protection, privacy and the governance of data-driven decisions. Economic analysis can test how repair costs, construction costs, household budgets or interest-rate conditions might affect claims and insurance purchasing, without presenting a current rate or policy change as fact. Social factors include changing service expectations and risk awareness. Technology covers AI, cybersecurity and modernization choices, while environmental factors can consider weather-related loss exposure and resilience. These are external conditions to monitor, not established conclusions about the company.
- Regulatory horizon. Separate policy and legal questions from documented changes, helping users identify where compliance, transparency or fairness may deserve closer review.
- Risk environment. Consider how inflation-sensitive claims inputs, cyber exposure and environmental loss patterns could affect the context for insurance decisions.
- External scan. Use the Excel framework to log and compare PESTLE factors, then use the Word analysis to add business relevance and avoid confusing signals with proven impacts.
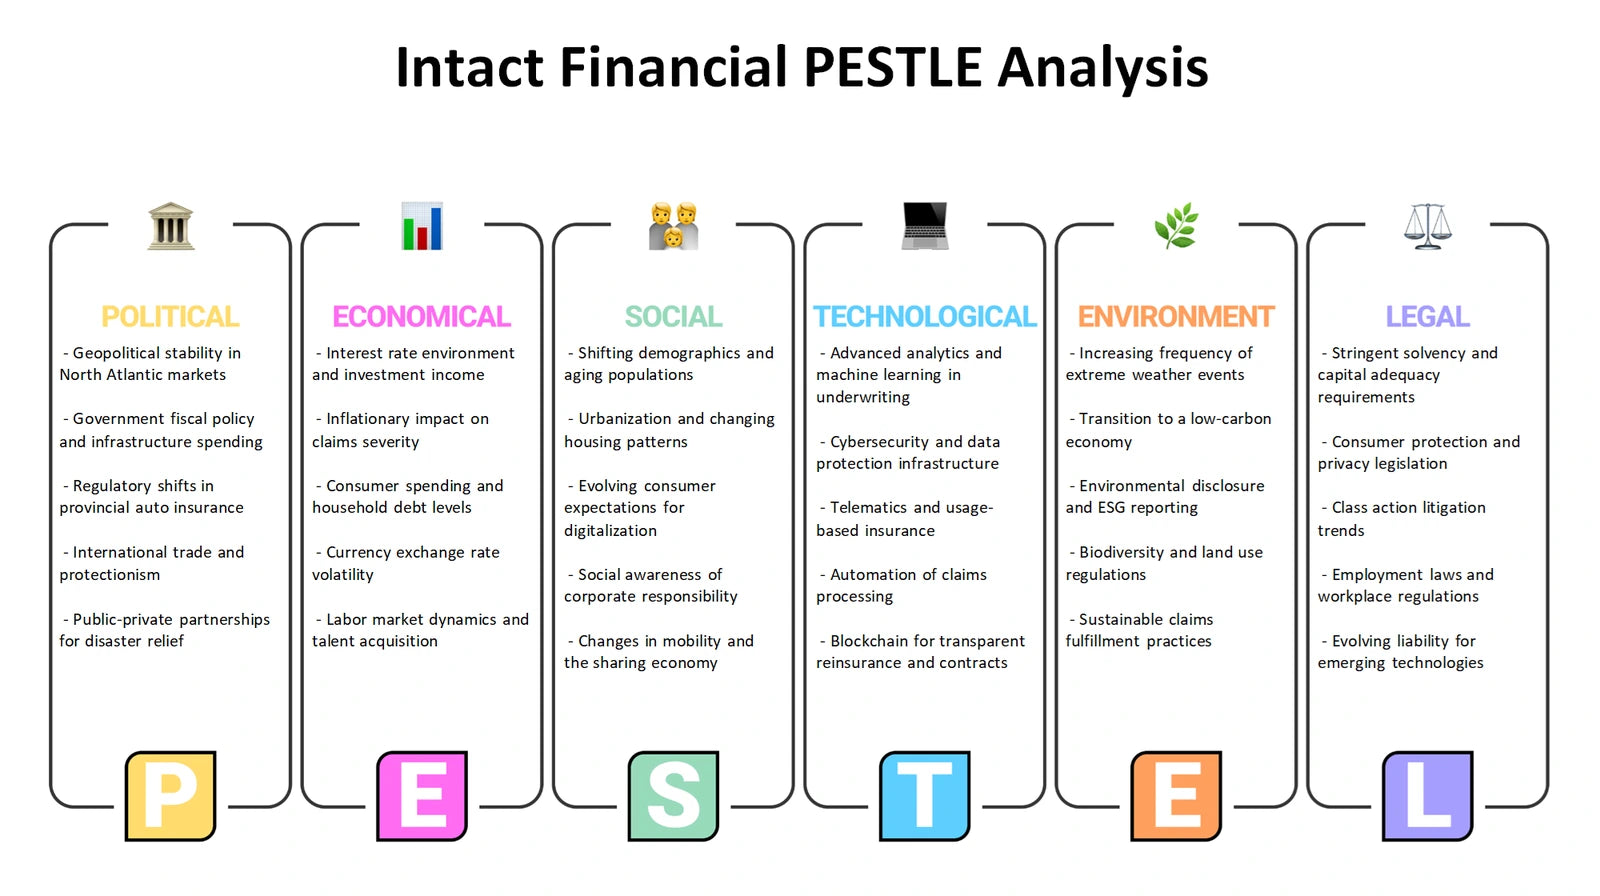
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal insurance capabilities and constraints be distinguished from the external opportunities and threats facing the business?
An Intact Financial SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. The broker network, BrokerLink relationship, insurance operating knowledge and stated technology modernization context can be explored as potential internal capability themes, rather than automatically treated as proven advantages. Internal constraints may include the coordination demands of distribution, claims operations, data governance and large-scale technology change. Opportunities and threats belong outside the organization: evolving customer needs, new digital channels, regulatory expectations, claims-cost pressure, cyber risk and environmental volatility are examples to assess according to available evidence. This distinction matters because a useful SWOT should not mix a controllable operating capability with an external market condition.
- Internal clarity. Test which resources, processes, channel relationships or modernization efforts may be strengths and which may create execution constraints.
- External priorities. Contrast possible market opportunities with threats arising from regulation, changing risk conditions, customer choice or industry economics.
- Decision framing. Use the Excel framework to keep internal and external factors separate, while the Word analysis provides detailed prompts for interpreting their strategic implications.
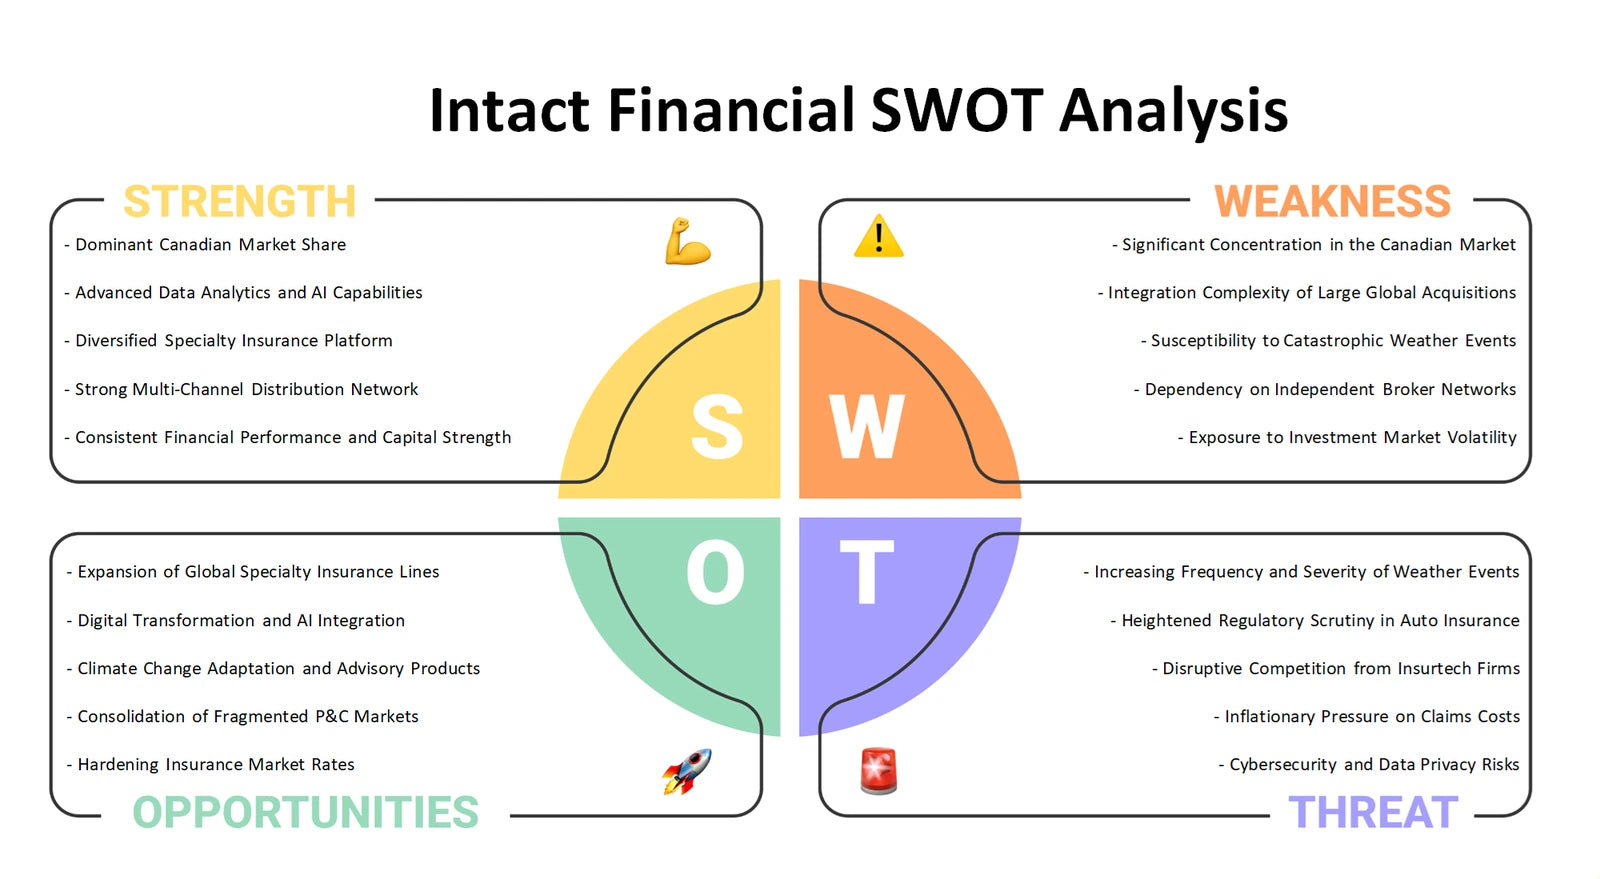
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Intact Financial
Used together, the six perspectives link portfolio choices to the business model, competitive pressures, customer-facing decisions, external conditions and organizational capabilities. The Excel frameworks provide structured ways to compare strategic questions, while the detailed Word files provide company-specific analytical context. This combination can help customers develop a more coherent discussion of Intact Financial's insurance, broker-distribution and technology-modernization considerations without mistaking framework prompts for verified investment conclusions.
Company background: Intact Financial — Wikipedia company article.