

IIFL Finance: Lending Economics and Brand Positioning – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
IIFL Finance Strategy Analysis Bundle
Available matching product context identifies IIFL Finance as a lending business serving borrowers seeking credit, with gold and small-business loans specifically referenced. It highlights digital KYC, limited documentation and predictable turnaround times as important operating themes, alongside community-based credit awareness intended to support financial inclusion and borrower relationships.
Those characteristics make portfolio priorities, lending economics, customer access and risk management closely connected. This bundle helps examine questions such as which lending propositions deserve resources, how quick approval processes create value, and which external pressures could affect credit demand or operating discipline. It presents analytical frameworks rather than claiming current financial results or predetermined strategic conclusions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending propositions should receive attention when growth potential must be balanced against relative market share and credit-risk discipline?
The IIFL Finance BCG Matrix provides a structured way to compare lending propositions by market growth and relative market share. For a lender associated in the supplied context with gold and small-business credit, the useful question is not simply whether a product is growing; it is whether its competitive position, operational capacity and risk-adjusted economics justify further resources. The familiar Stars, Cash Cows, Question Marks and Dogs categories are analytical outcomes to test, not labels assigned here. This lens can help separate mature cash-generating activity from areas that may need investment, repositioning, closer monitoring or a clearer rationale for continued support.
- Portfolio logic. Compare gold lending, small-business lending and other relevant propositions against both market momentum and relative competitive standing.
- Resource tension. Examine how branch capacity, digital processing, underwriting attention and collections capability might be allocated across differing priorities.
- Decision worksheet. Use the Excel matrix to record comparison assumptions, then use the detailed Word analysis to document why a proposed portfolio priority fits the wider lending model.
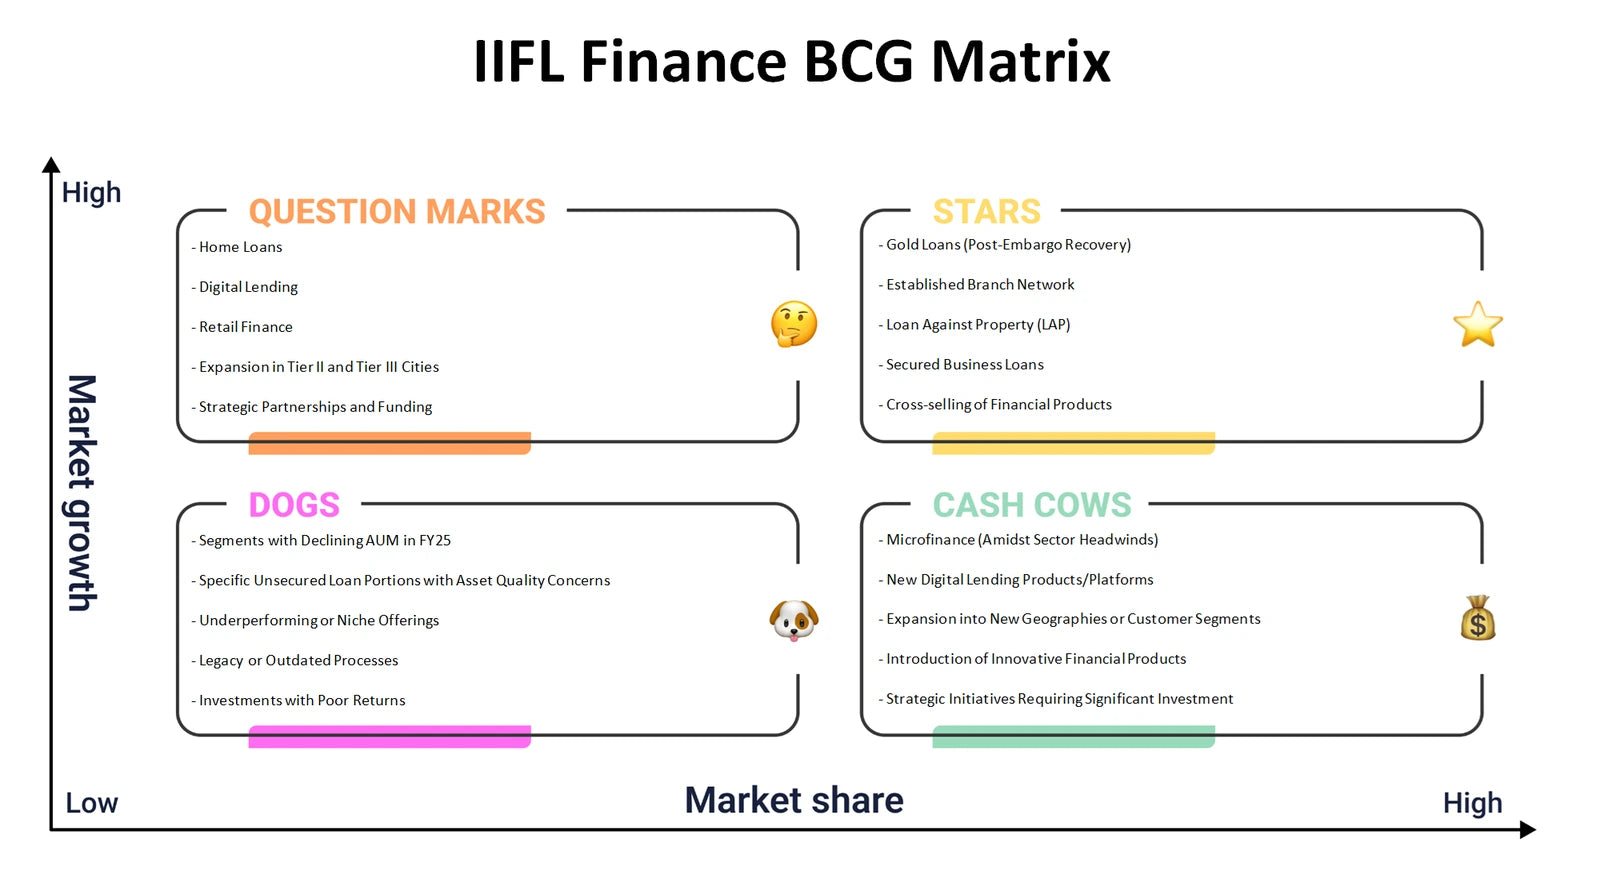
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do rapid lending processes, borrower trust and credit-risk controls fit together to create value and generate sustainable lending income?
The IIFL Finance Business Model Canvas connects customer segments and value propositions with channels, customer relationships and revenue streams. It also brings together the enabling side of the model: key resources, key activities, key partnerships and cost structure. The supplied context makes speed, digital KYC, minimal documentation and community presence useful themes to examine, because a quick borrower experience still depends on dependable verification, underwriting, servicing and recovery processes. The canvas helps trace how access to credit is delivered to borrowers and how interest-related income, fees where applicable, operating costs and credit losses should be considered as connected economic questions rather than isolated boxes.
- Borrower journey. Map how different customers discover, apply for, receive and manage credit through physical, digital or assisted channels relevant to the business.
- Operating backbone. Relate loan processing, risk assessment, technology, funding relationships and frontline support to the value promised to borrowers.
- Connected model. Populate the Excel canvas with working hypotheses and use the Word analysis to explain dependencies between value delivery, revenue logic and cost or risk exposure.
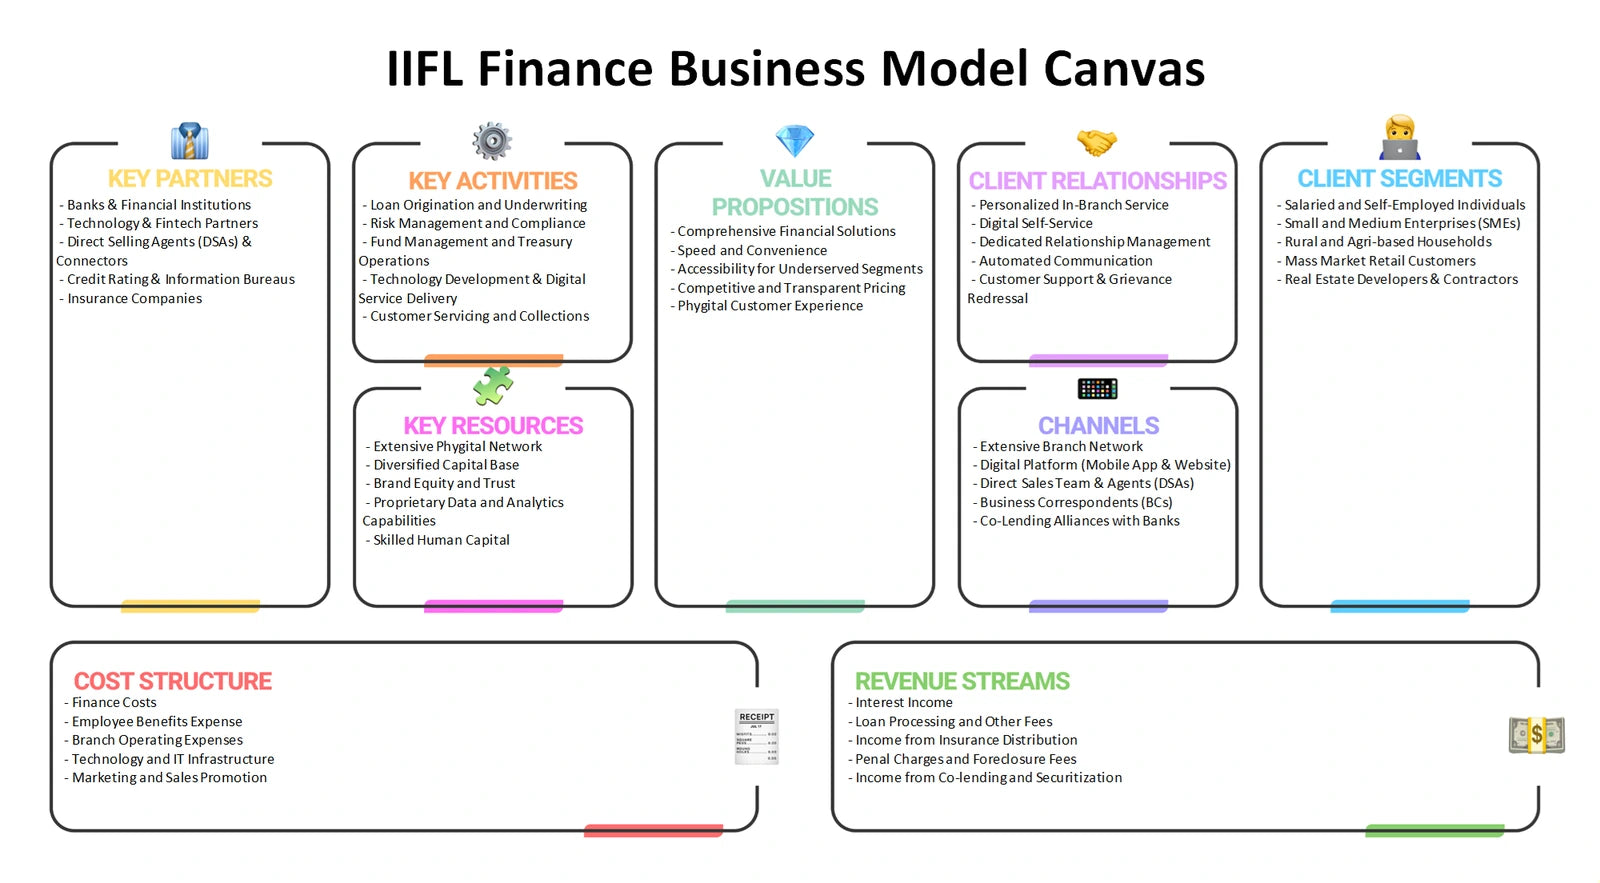
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence pricing power, borrower retention and the cost of delivering credit efficiently?
IIFL Finance Porter's Five Forces examines the lending environment around the business rather than judging a single internal process. Rivalry considers pressure from other providers of borrower finance. Buyer power asks how readily borrowers can compare terms, switch providers or delay borrowing. Supplier power is relevant to providers of funding, specialist technology, distribution support and other resources that affect a lender's cost base. The threat of new entrants considers firms that can build credible lending access and risk capabilities, while substitutes include alternative ways borrowers may meet a financing need, such as savings, informal credit or other forms of finance. Each force can change the trade-off between speed, price, risk and service quality.
- Competitive pressure. Distinguish direct lending rivalry from the broader alternatives that may reduce demand for a particular credit proposition.
- Funding sensitivity. Explore how bargaining positions across funding and operating inputs can affect margins, capacity and customer terms.
- Evidence trail. Score discussion points in the Excel framework and use the Word analysis to keep the assumptions, industry observations and implications behind each force visible.
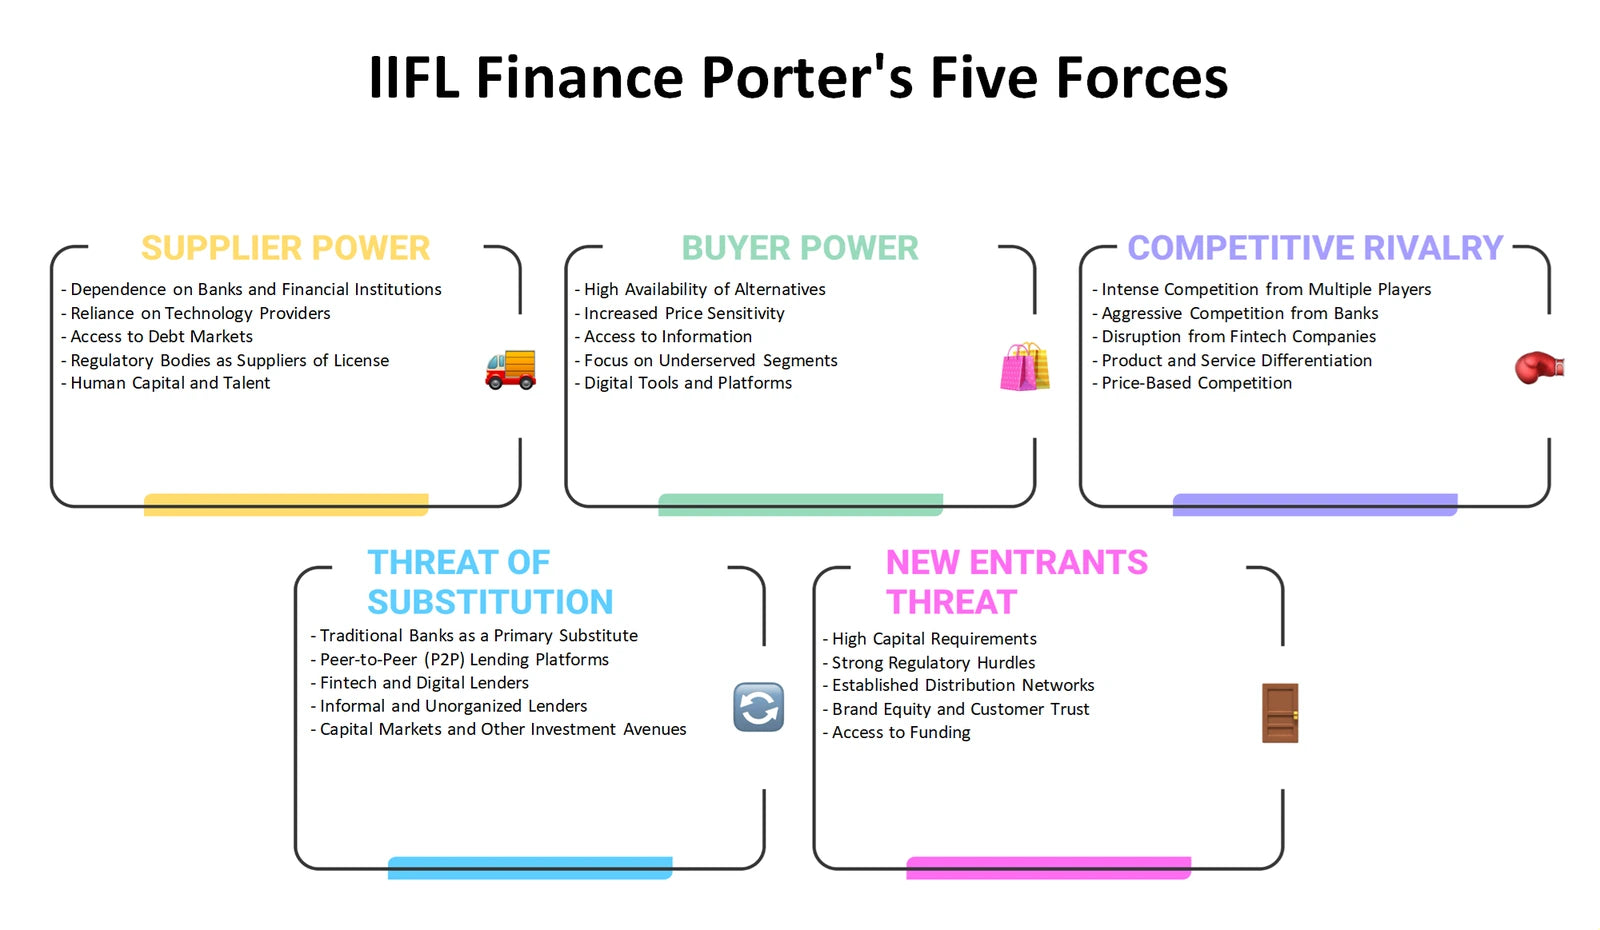
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should a lender communicate convenience and accessibility while setting realistic customer expectations about eligibility, pricing and repayment?
The IIFL Finance Marketing Mix applies Product, Price, Place and Promotion to a regulated, trust-dependent lending service. Product analysis can examine the borrower need addressed by credit propositions and the role of application speed, documentation requirements and service support. Price considers interest, fees and repayment terms as customer decision factors without assuming specific prices. Place looks at the routes through which borrowers may access assistance or apply, including relevant digital and local touchpoints. Promotion considers how credit awareness, product communication and responsible disclosure shape trust. The supplied context on community engagement is particularly useful for assessing how awareness-building could complement, rather than replace, clear and compliant customer communication.
- Offer design. Test whether product features and service expectations match the practical needs of gold-loan and small-business borrowers.
- Access and trust. Compare the role of digital journeys, local presence and educational communication in reducing uncertainty before application.
- Message planning. Use the Excel 4Ps structure to organise customer-facing choices, then use the Word analysis to articulate consistent positioning and disclosure considerations.
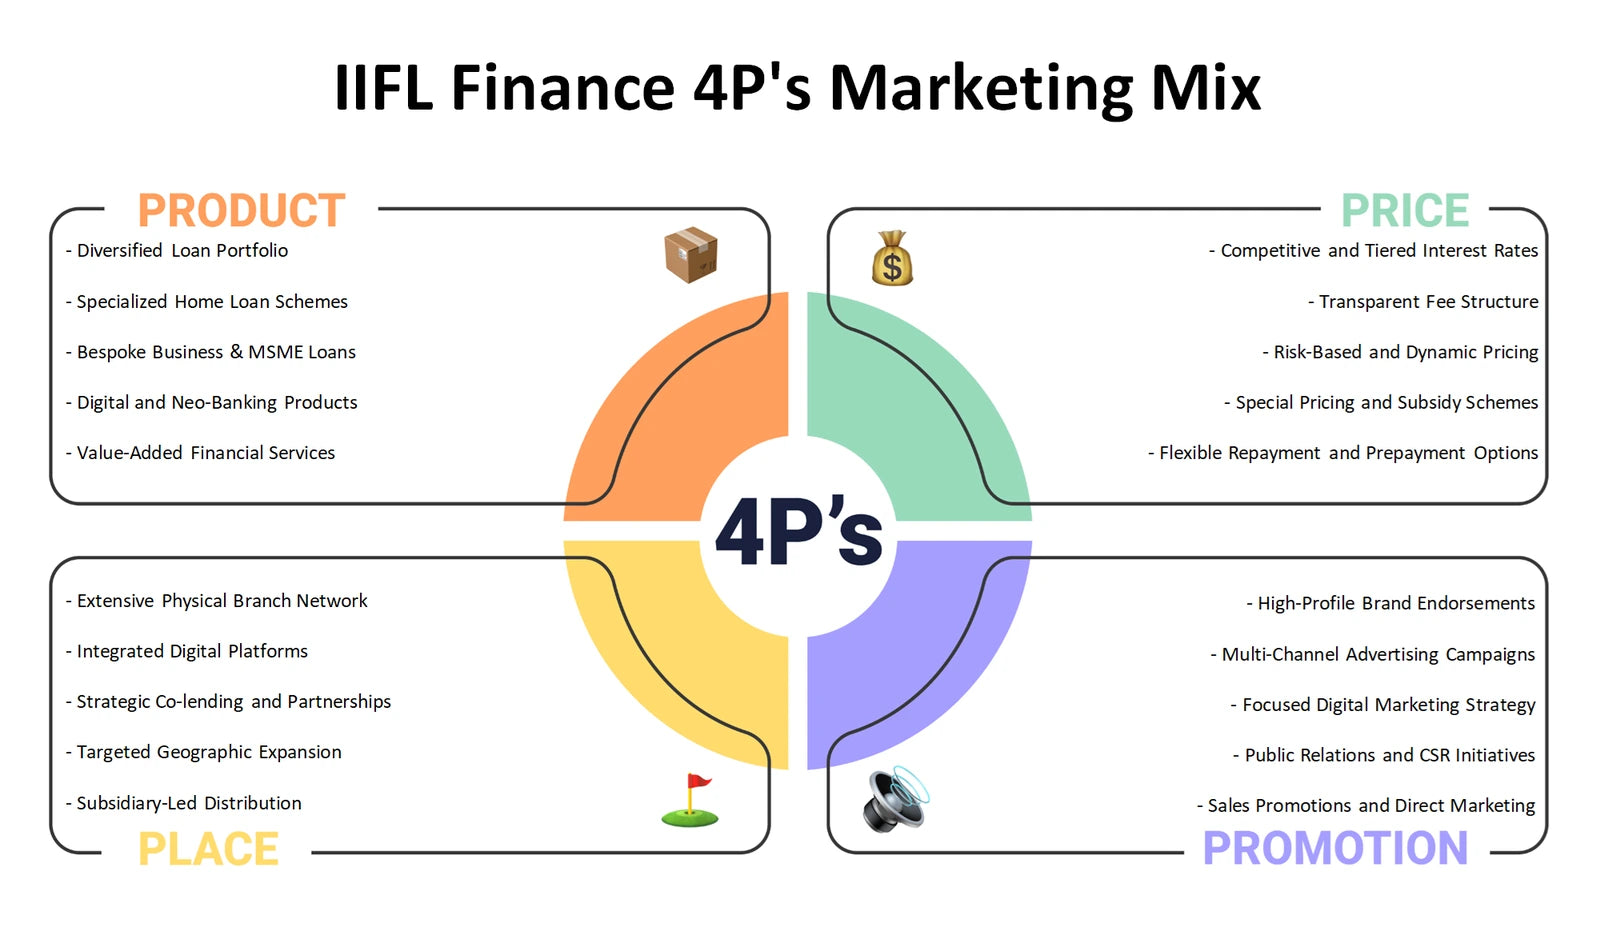
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter borrower demand, funding conditions, digital lending expectations or the compliance burden around credit delivery?
The IIFL Finance PESTLE analysis, also commonly called PESTEL, separates external influences that a lender cannot control but must monitor. Political factors can include public-policy direction affecting financial inclusion or credit access. Economic conditions may shape borrower repayment capacity, business activity and funding costs. Social themes include trust in formal credit and demand for convenient documentation. Technological change raises questions about digital identity, application journeys, fraud prevention and data security. Legal factors cover lending, customer protection, privacy and disclosure obligations in relevant jurisdictions, while environmental conditions can affect borrower livelihoods, collateral-related activity or operational continuity. These are monitoring questions, not claims that a particular policy, rate or law has recently changed.
- External watchlist. Identify which macro, social and regulatory signals could matter most for borrower segments and lending operations.
- Risk pathways. Link a possible external development to its potential effects on demand, underwriting, servicing, costs or customer communication.
- Scenario record. Use the Excel framework to rank issues by relevance and use the Word analysis to develop concise scenarios, assumptions and management questions.
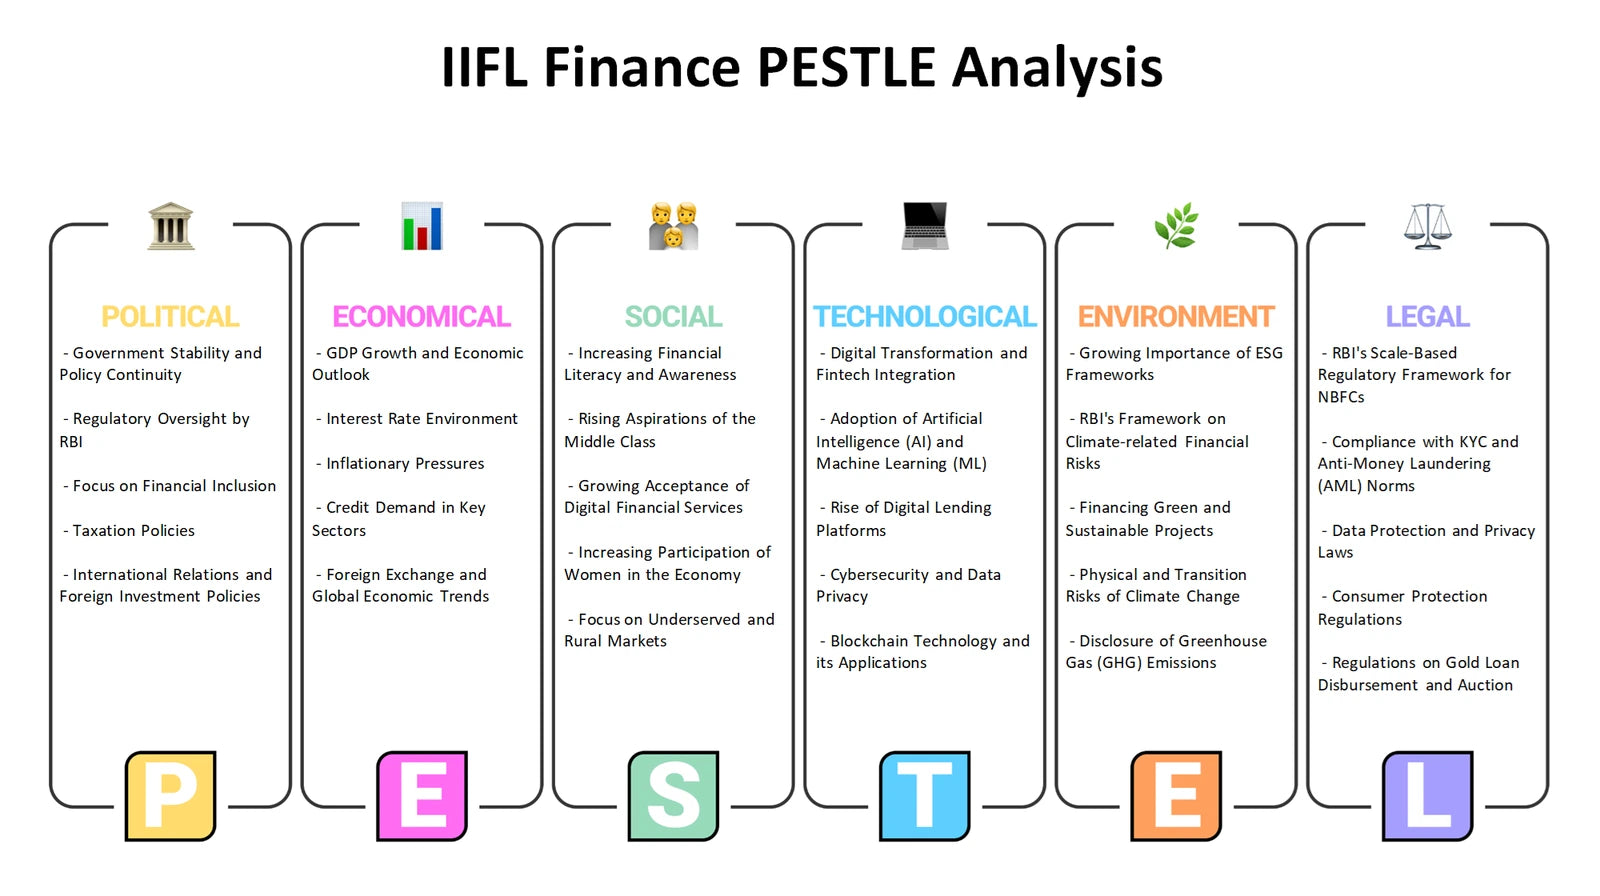
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal lending capabilities and constraints be considered alongside external opportunities and threats without confusing the two?
The IIFL Finance SWOT analysis separates internal strengths and weaknesses from external opportunities and threats. The supplied context points to possible internal themes worth validating, including streamlined processing, digital KYC, quick approvals and community-facing credit awareness. These should be assessed alongside the controls, people, systems and funding discipline needed to support responsible lending at scale. Opportunities might arise from underserved borrower needs or more convenient access to formal credit, while threats may include stronger competitive pressure, changing borrower conditions, fraud risks or regulatory expectations. The value of SWOT is not a generic list: it is the comparison of what the business can reliably do with the market conditions it may encounter.
- Internal reality. Test whether speed, customer access, risk processes and relationship-building are durable capabilities or areas needing further evidence and investment.
- External fit. Relate potential borrower opportunities to threats that could affect repayment, trust, compliance or operating resilience.
- Action map. Capture internal and external factors in the Excel grid, then use the Word analysis to turn priority combinations into focused questions for management review.
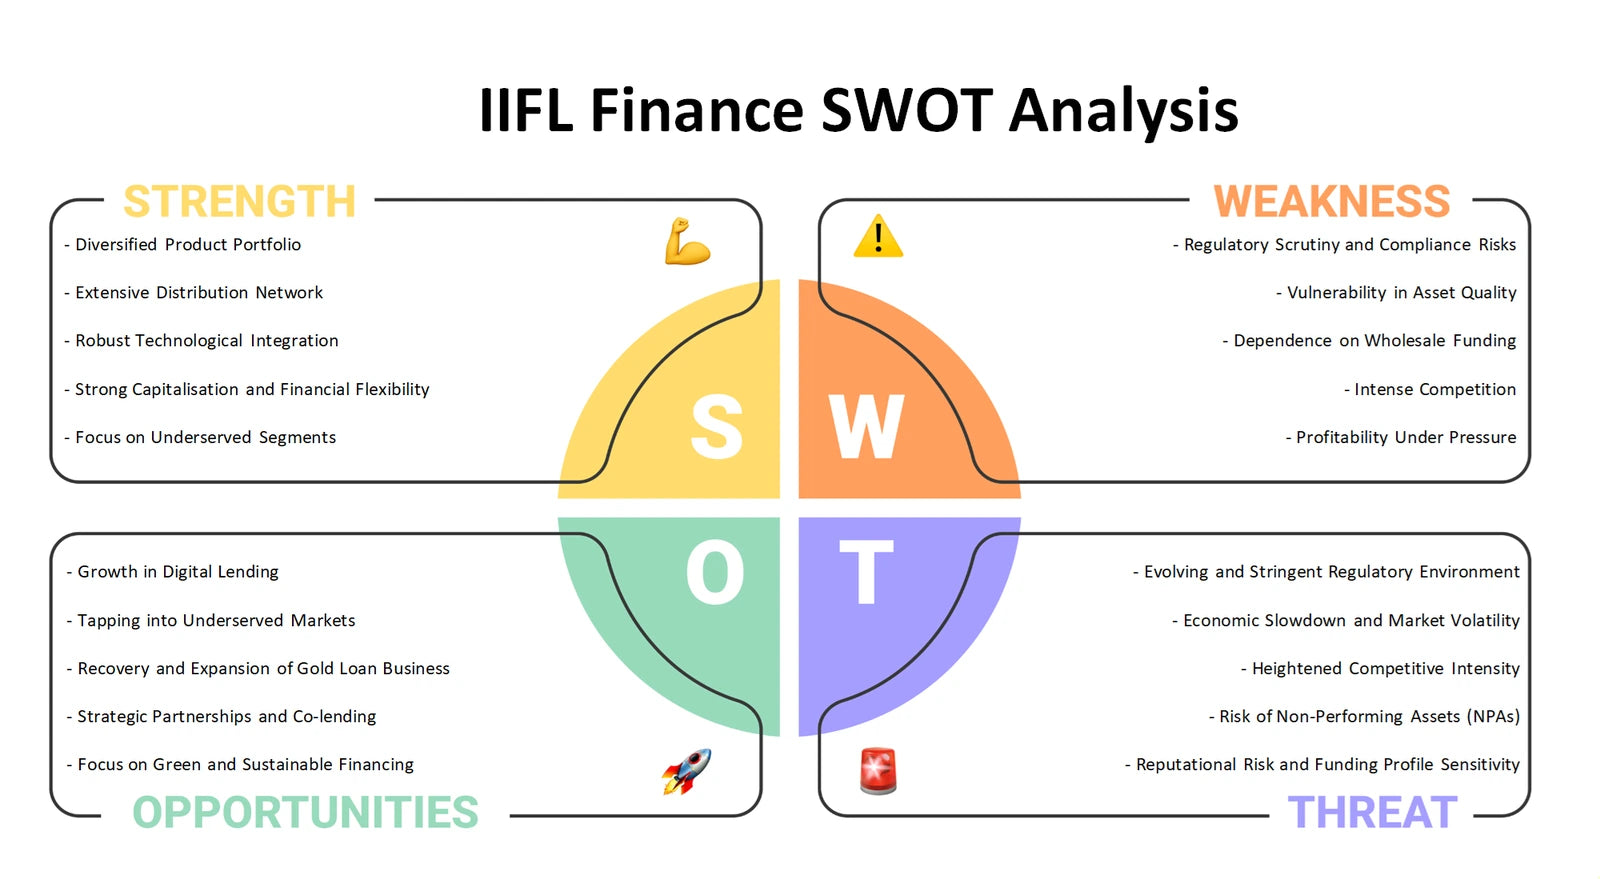
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of lending strategy
Together, the six perspectives help connect portfolio choices with the way IIFL Finance serves borrowers, earns lending income, manages operational dependencies, communicates value and responds to external conditions. The Excel frameworks provide structured places to compare assumptions and priorities, while the detailed Word files support fuller interpretation of the business questions behind those choices.
Company background: IIFL Finance — matching business-model context (product page).