

IDFC First Bank: Banking Business and Deposit Funding – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
IDFC First Bank Strategy Analysis Bundle
IDFC First Bank is an Indian banking company. Its public website presents personal banking services that include accounts, loans and investments, placing customer trust, convenient access and responsible financial service delivery at the centre of the business. The bundle is designed around this banking context rather than a generic consumer-products model.
For IDFC First Bank, strategic questions can include how deposit and lending services fit together, how physical and digital service access should be assessed, and how technology, risk and compliance costs affect value creation. The Excel frameworks and detailed Word analyses help organise those questions across six connected business lenses without presenting assumptions as established findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking offerings deserve priority when their market growth prospects and relative market share may differ?
An IDFC First Bank BCG Matrix provides a disciplined way to compare a portfolio of banking activities using the two proper BCG dimensions: market growth and relative market share. It can help separate the evidence needed to consider deposit relationships, lending categories, investment services and transaction-access propositions. Stars, Cash Cows, Question Marks and Dogs are analytical portfolio labels, not conclusions about any particular IDFC First Bank offering. That distinction matters where customer acquisition, funding needs, credit risk and service capacity can make a seemingly attractive category resource-intensive.
- Portfolio boundaries. Define comparable product or customer propositions before judging relative position, rather than mixing broad banking activity with a narrow service feature.
- Resource trade-offs. Examine where growth investment, relationship support, technology capacity or rationalisation questions may arise across the portfolio.
- Structured comparison. Use the Excel matrix to record assumptions and comparison criteria, then use the Word analysis to interpret what each possible quadrant would mean for management priorities.
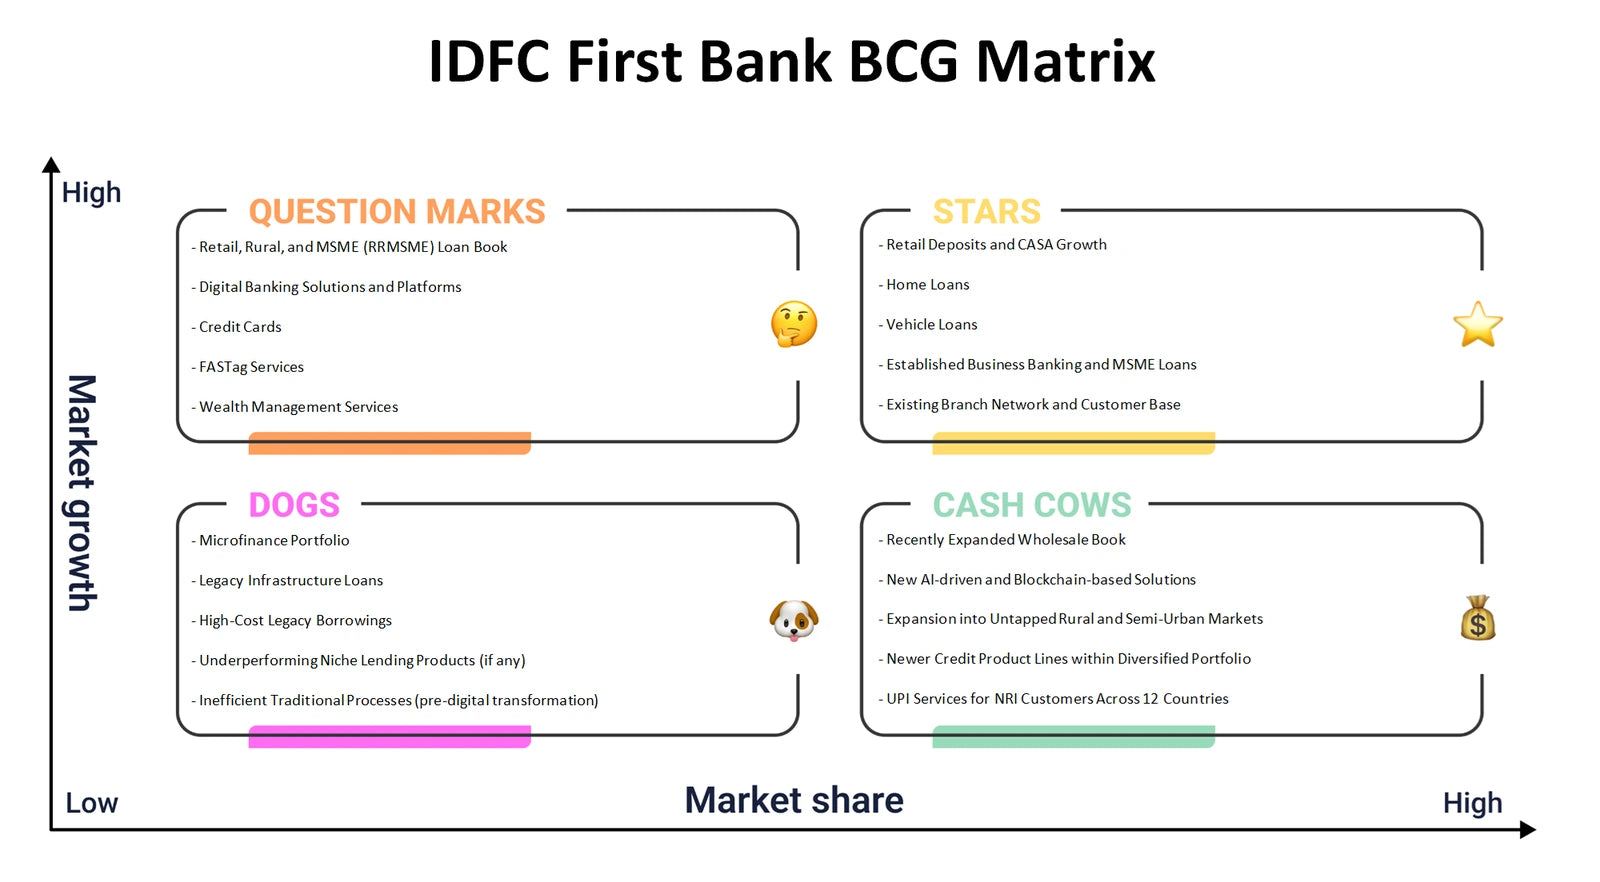
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, banking delivery channels and operating costs connect to IDFC First Bank's economic model?
The IDFC First Bank Business Model Canvas examines all nine building blocks as one system: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a bank serving personal-banking needs, the useful question is not simply which products are offered, but how account, credit, investment and service journeys create value while requiring secure operations and controlled risk. The framework supports a connected view of convenience, trust, revenue logic and the continuing cost of infrastructure, technology and regulatory capability.
- Customer journey links. Map how different customer segments may encounter value propositions through assisted, physical and digital channels, and where relationships require reassurance or service support.
- Operating economics. Connect revenue-stream questions with key resources, activities, partnerships and cost structure instead of treating banking income and operating spend as unrelated cells.
- Model workshop. Populate the Excel canvas with evidence and open questions, then use the detailed Word analysis to discuss dependencies between delivery choices, risk controls and economics.
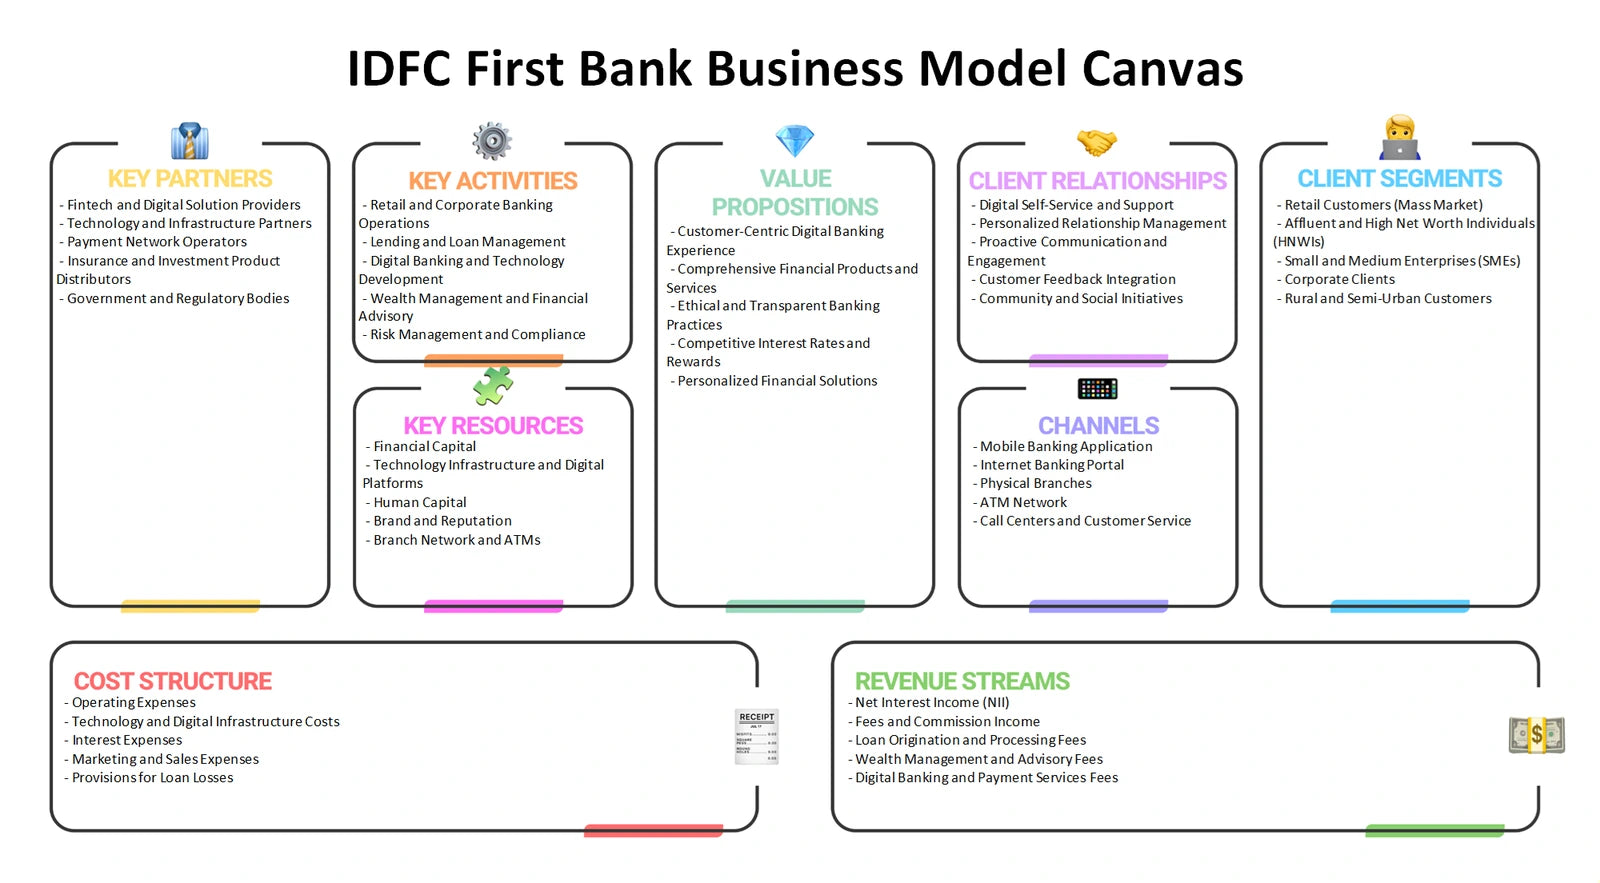
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape the attractiveness and defensibility of personal banking in India?
IDFC First Bank Porter's Five Forces analysis frames the competitive environment around banking services rather than assuming that every pressure comes from direct bank-to-bank rivalry. It considers rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes. Depositors, borrowers and investors can compare service quality, convenience and trust; meanwhile, alternatives may include non-bank ways to make payments, save, borrow or invest. The analysis helps identify where switching, funding, technology providers, distribution access and regulatory expectations may alter bargaining conditions.
- Competitive pressure. Consider how rivalry and potential entrants can influence customer acquisition, product differentiation and the cost of maintaining a credible service proposition.
- Choice and dependency. Assess buyer power alongside supplier power, including questions around customer switching and reliance on technology, infrastructure or specialist service inputs.
- Evidence-led assessment. Use the Excel framework to document each force and its rationale, while the Word analysis provides context for interpreting alternative banking and financial-service substitutes.
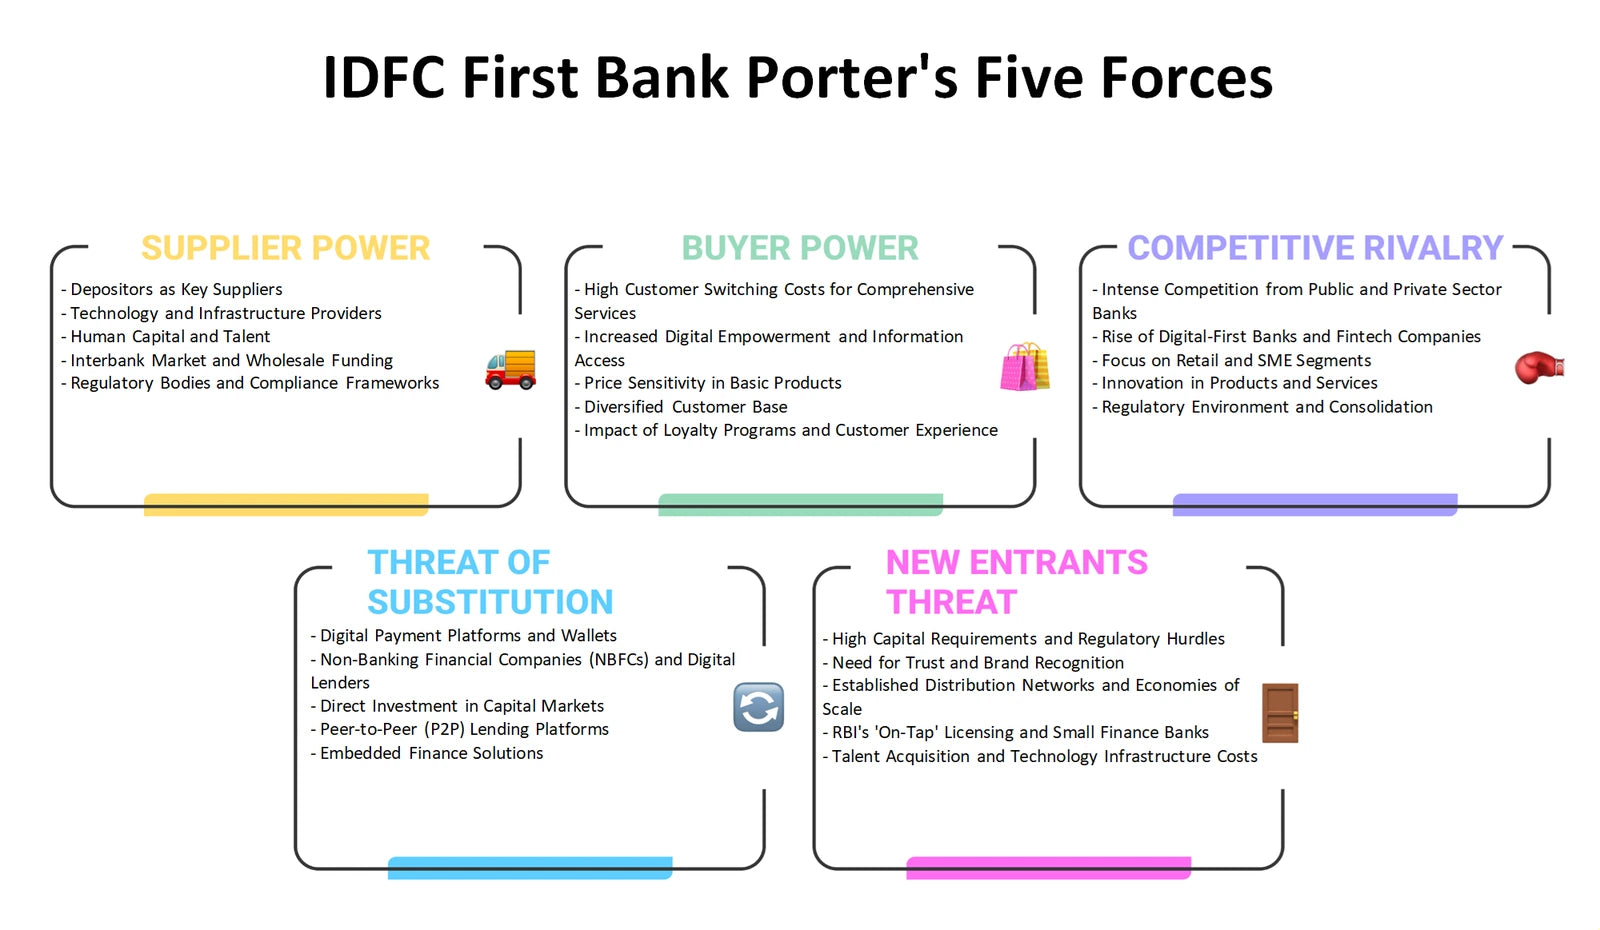
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Product, Price, Place and Promotion be evaluated for a trust-based personal banking proposition?
An IDFC First Bank Marketing Mix considers the 4Ps in a regulated service setting. Product can cover the design and clarity of accounts, loans, investments and supporting service experiences. Price concerns the logic and transparency of rates, fees or other customer charges, not an invented price list. Place asks how customers can access and use services through appropriate physical, assisted and digital routes. Promotion examines how communications can explain value, build confidence and support informed financial choices without overstating what a product can deliver.
- Service proposition. Compare product features with the practical needs of customers who may value everyday access, borrowing support, savings options and investment guidance.
- Channel coherence. Test whether Place and Promotion reinforce each other across branch, ATM, cash-deposit and digital touchpoints instead of creating fragmented expectations.
- Planning view. Use the Excel 4Ps structure to organise alternatives and customer implications, then use the Word analysis to explore the trade-offs between reach, communication, pricing logic and trust.
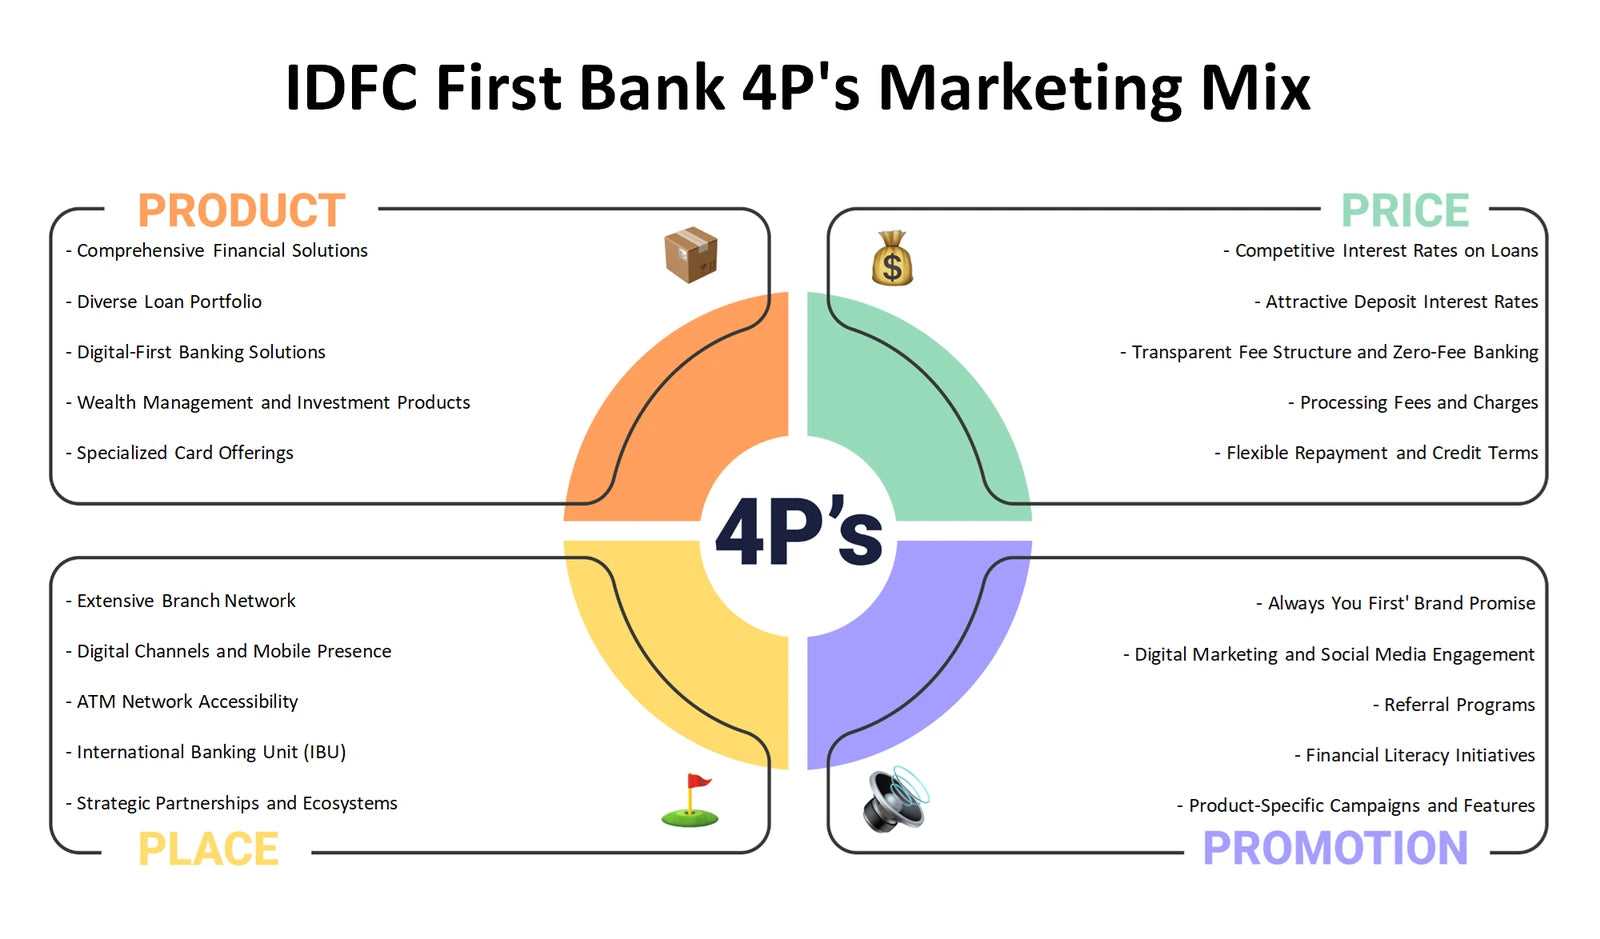
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could reshape banking demand, operating requirements and risk for IDFC First Bank?
IDFC First Bank PESTLE analysis, also commonly called PESTEL, separates external influences from internal capabilities. Political conditions can affect the policy environment for financial services; economic conditions can influence borrowing, saving, repayment capacity and funding questions. Social factors include changing expectations for convenience and trust. Technological change raises questions around digital delivery, resilience and cyber security. Legal requirements shape conduct, data, compliance and consumer-protection obligations, while environmental factors can affect lending considerations, operational continuity and stakeholder expectations.
- External scanning. Distinguish an observable external driver from a claimed company result, and identify which conditions require monitoring rather than prediction.
- Banking relevance. Connect each PESTLE factor to possible effects on customer behaviour, credit assessment, service reliability, compliance workload or investment priorities.
- Scenario record. Use the Excel framework to classify and rank external questions, then use the Word analysis to develop reasoned scenarios and management discussion points.
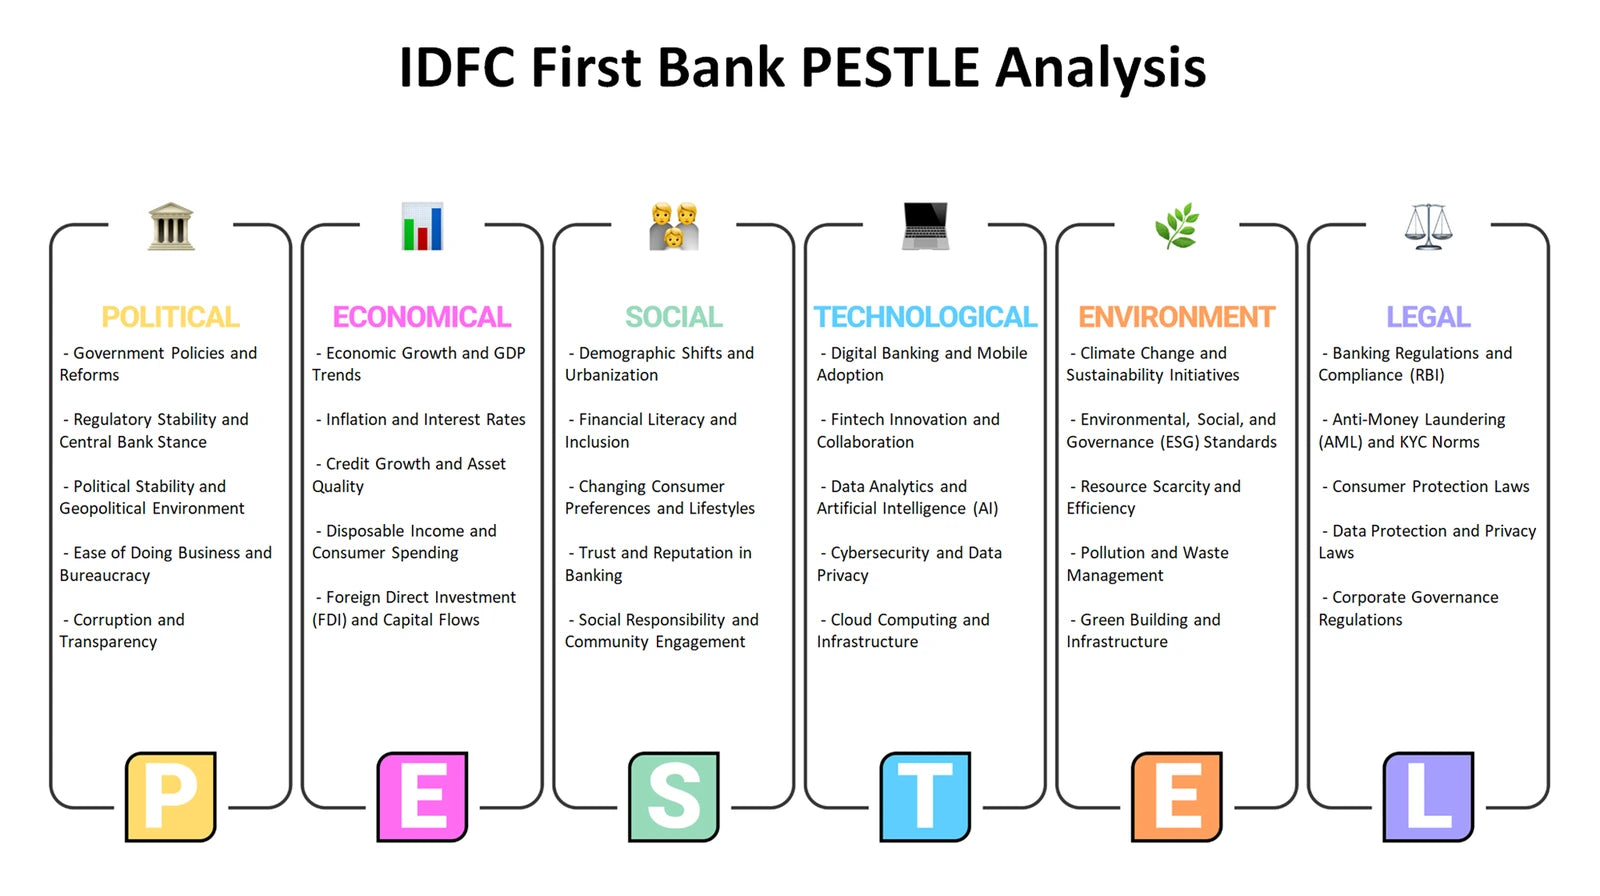
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities be separated from external opportunities and threats before setting priorities?
An IDFC First Bank SWOT analysis helps keep classification clear. Strengths and weaknesses are internal: they may concern customer-service capability, technology, operating processes, risk management, distribution capacity or cost discipline, subject to evidence. Opportunities and threats are external: they can arise from customer needs, market developments, alternative financial solutions, economic conditions or regulatory change. This distinction is valuable because a capability is not automatically an opportunity, and a market risk is not automatically an internal weakness. The framework turns a broad strategic discussion into issues that can be validated and connected to action.
- Internal diagnosis. Identify capabilities and constraints that should be tested with company evidence, especially where service reliability, security and credit-risk control affect customer confidence.
- External fit. Relate opportunities and threats to the Five Forces and PESTLE questions without presenting plausible themes as proven company outcomes.
- Priority translation. Use the Excel SWOT grid to capture and compare items, then use the Word analysis to examine how internal factors may respond to external conditions.
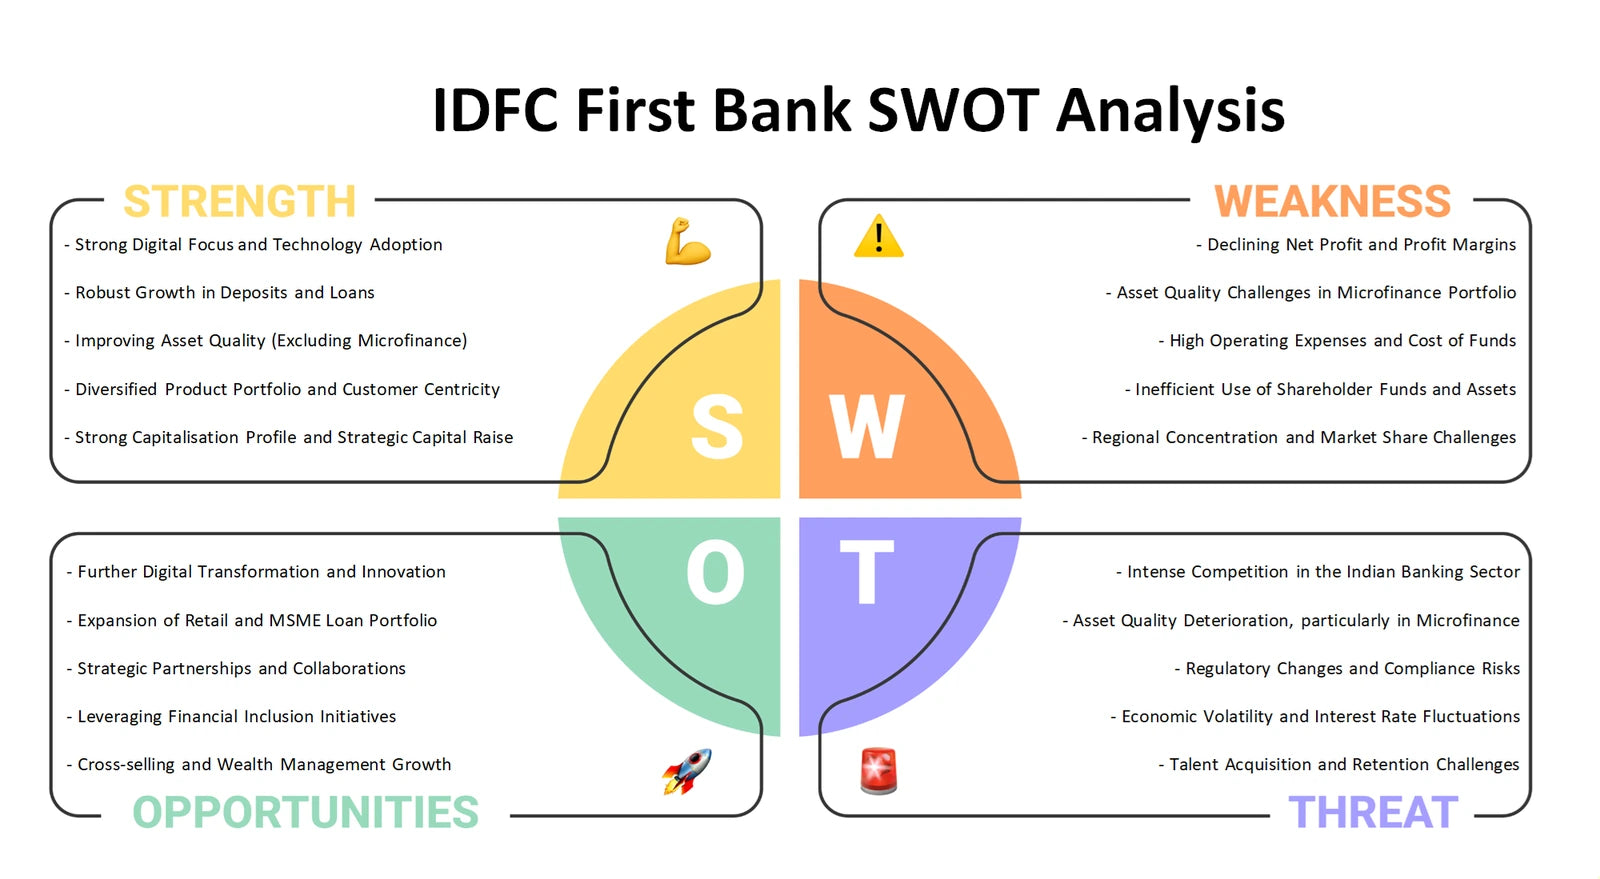
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring the six perspectives into one strategic conversation
Used together, the BCG Matrix, Business Model Canvas, Five Forces, Marketing Mix, PESTLE and SWOT analyses let you move from portfolio questions to business-model connections, market pressure, customer delivery, external change and organisational fit. The Excel frameworks provide a practical structure for comparison and discussion, while the Word files provide detailed company analysis to support a more considered view of IDFC First Bank.
Company background: IDFC First Bank — official website.