

ICICI Lombard General Insurance: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
ICICI Lombard General Insurance Strategy Analysis Bundle
ICICI Lombard General Insurance is an India-based general insurance provider serving individuals, businesses and institutional customers across protection needs such as health, motor, travel, property and commercial risk. Its model depends on underwriting risk, collecting premiums, distributing policies through direct and intermediary routes, and delivering a credible claims and service experience when customers need support.
The available company context highlights broker and corporate-agent distribution, alongside customer support through call centres, chat and email with escalation processes. That makes questions about portfolio priorities, complex-risk placement, customer access, claims friction, pricing clarity and digital service especially relevant. The bundle helps turn those questions into structured strategic analysis rather than presenting unsupported conclusions about the company.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance product areas may warrant greater resource attention when growth prospects are compared with relative market share?
An ICICI Lombard General Insurance BCG Matrix helps organise a broad insurance portfolio around two analytical criteria: market growth and relative market share. Rather than assigning a product to a quadrant without evidence, it provides a disciplined way to test whether motor, health, travel, property or commercial cover behaves more like a Star, Cash Cow, Question Mark or Dog. This matters because underwriting talent, claims capability, distribution support and marketing budgets cannot be expanded everywhere equally. Portfolio choices should also consider capital use, claims volatility and whether a line strengthens relationships with retail or corporate customers.
- Portfolio comparison. Examine product categories against growth conditions and relative competitive position without treating premium volume alone as a priority signal.
- Resource trade-offs. Compare potential investment, maintenance, selective improvement or rationalisation choices while considering underwriting discipline and service capacity.
- Structured review. Use the Excel matrix to map assumptions and compare scenarios, then use the Word analysis to document the reasoning behind each portfolio question.
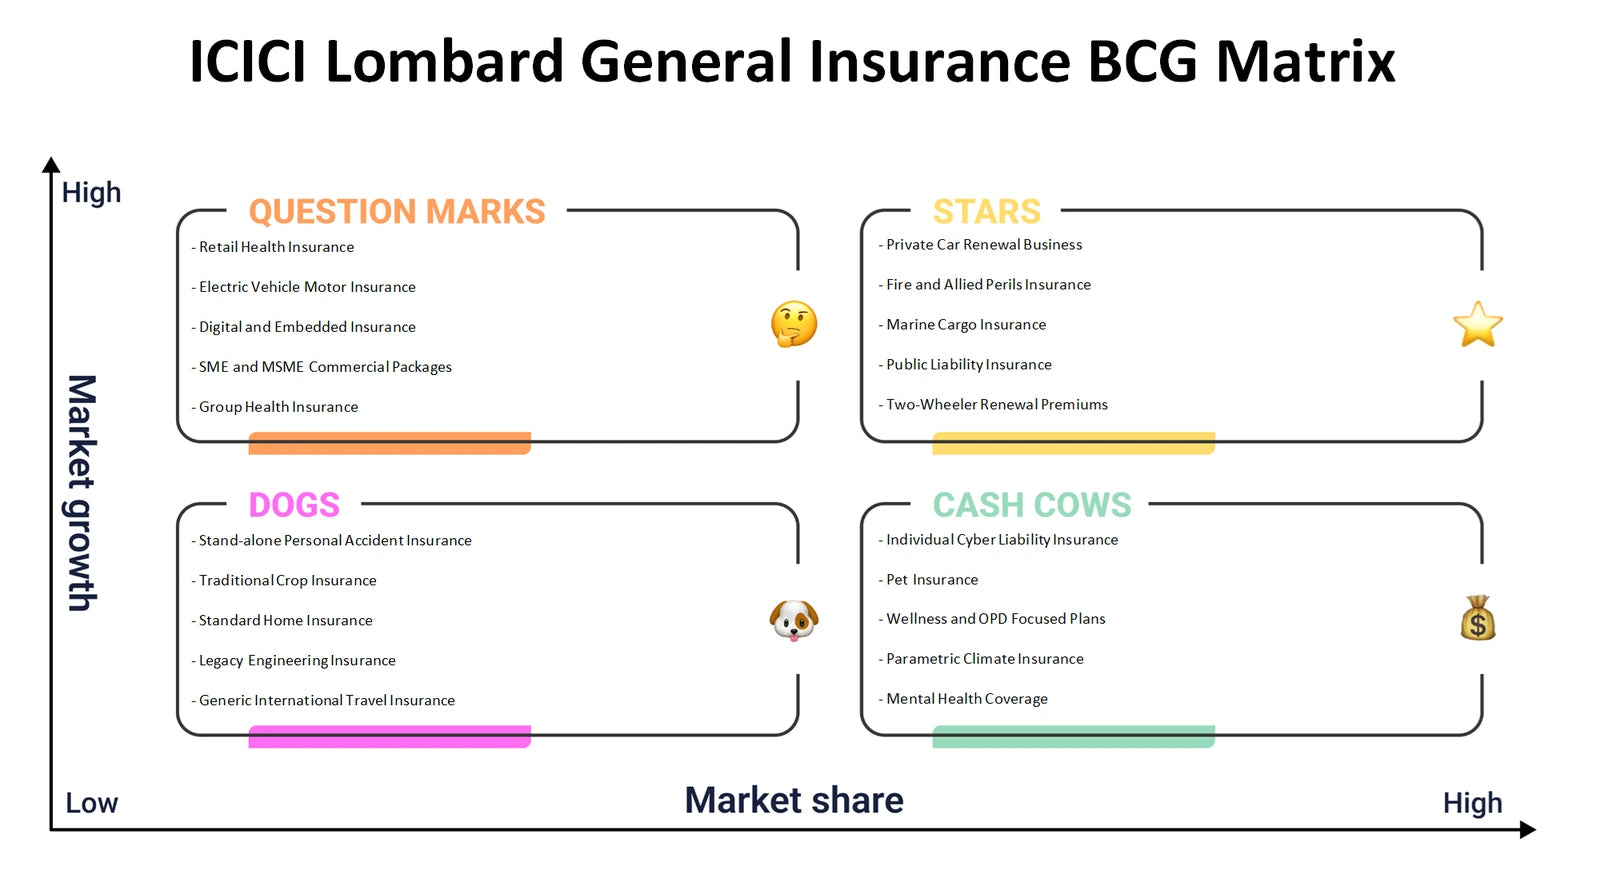
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do underwriting, distribution, claims and customer service connect to value creation and insurance economics?
The ICICI Lombard General Insurance Business Model Canvas examines all nine building blocks as one connected operating system: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For this insurer, the useful question is how protection products and responsive service reach retail, SME and corporate needs through direct contact and intermediaries, while premiums must cover claims, acquisition, servicing and risk-management costs. Brokers and corporate agents are particularly relevant analytical partners where complex risks and institutional pools require technical placement and ongoing servicing.
- Customer-value fit. Assess how coverage relevance, smoother onboarding, clearer policy terms and claims support may reduce customer uncertainty at different service moments.
- Economic linkages. Trace how premium revenue, underwriting quality, distribution costs, claims handling and partner relationships interact rather than viewing each lever in isolation.
- Connected model. Complete the Excel canvas block by block and use the Word analysis to explore dependencies, assumptions and possible operating tensions.
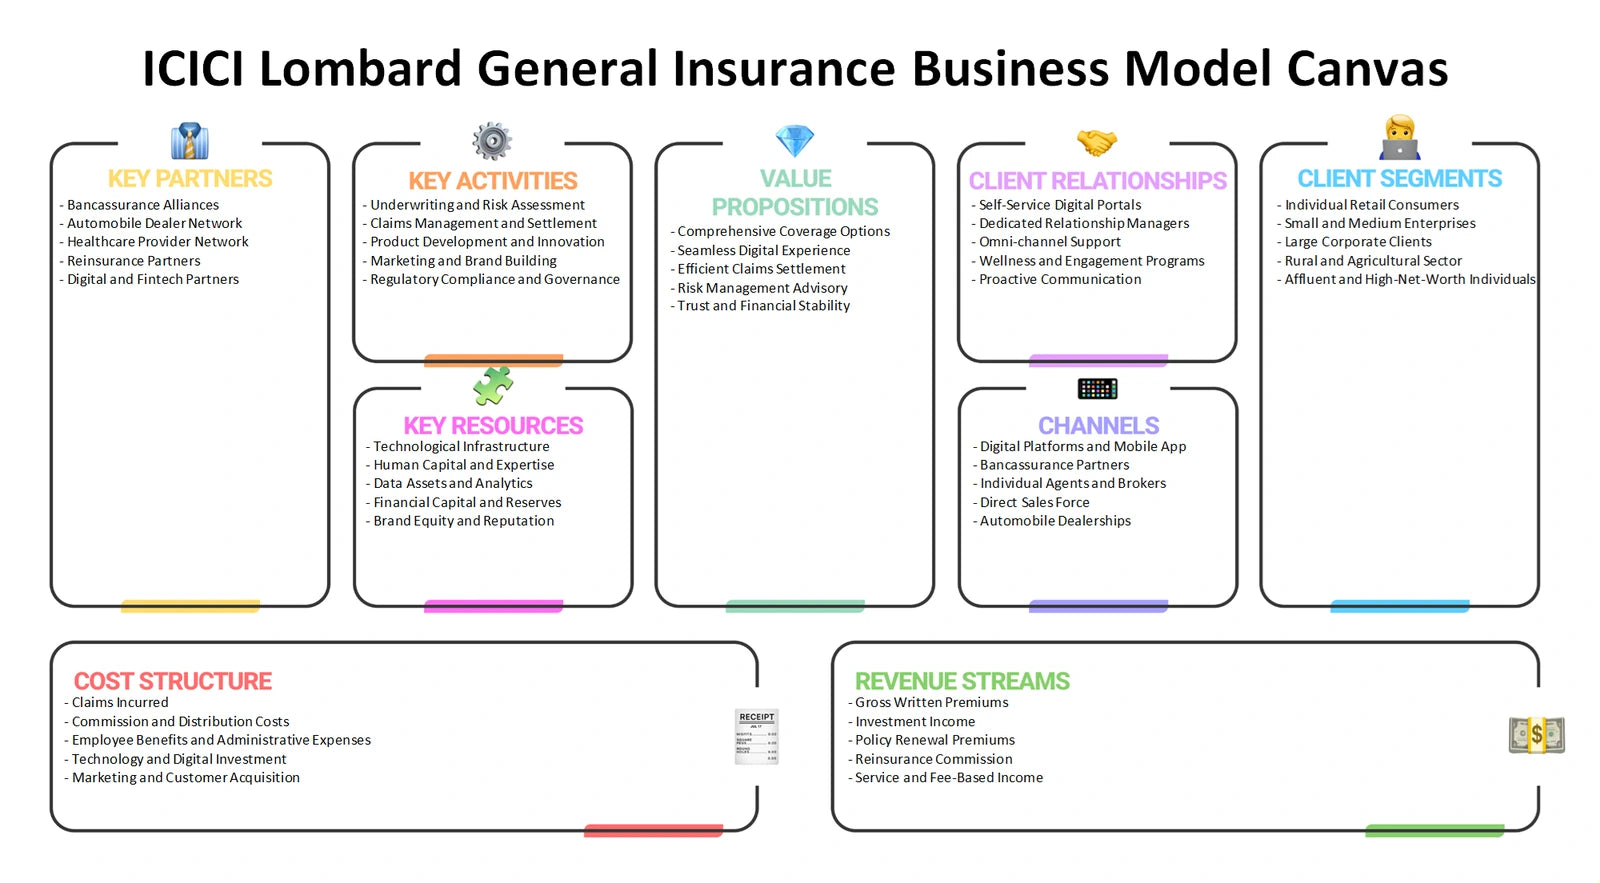
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence underwriting margins, distribution leverage and customer retention in Indian general insurance?
ICICI Lombard General Insurance Porter's Five Forces frames competitive conditions beyond a simple list of insurers. Rivalry can shape product comparison and service expectations; buyer power can be stronger where corporate clients, brokers or informed consumers can assess alternatives; and supplier power can arise around specialist services, technology, repair networks or other operating inputs. The framework also considers the threat of new entrants and the threat of substitutes, such as self-insurance, risk-prevention investments or alternative ways customers manage particular financial exposures. Each force should be assessed with supporting evidence rather than assigned a generic high or low score.
- Competitive pressure. Explore how comparable coverage, claims experience and distribution access may affect the ability to differentiate without weakening risk selection.
- Counterparty leverage. Consider how intermediaries, corporate purchasers and essential service providers may influence terms, service expectations and operating costs.
- Evidence-led assessment. Use the Excel framework to record force-by-force observations and use the Word analysis to interpret their implications for strategic choices.
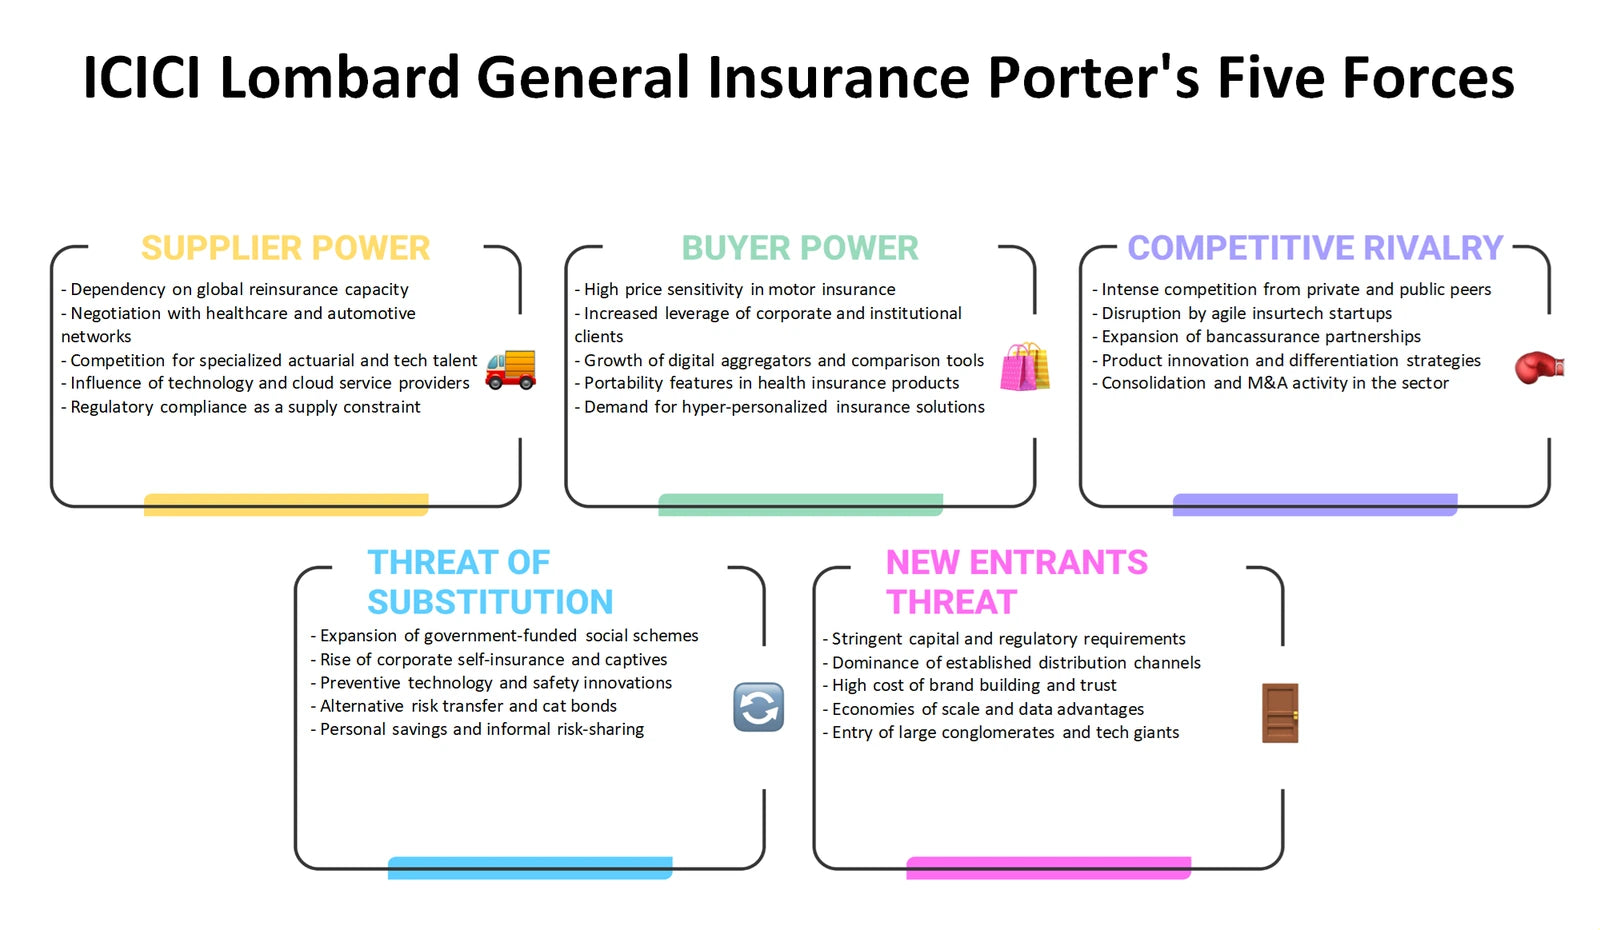
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, access routes and communications be assessed across retail and business insurance journeys?
The ICICI Lombard General Insurance Marketing Mix applies Product, Price, Place and Promotion to a regulated service where customers are buying protection and confidence, not a physical good. Product analysis can compare the relevance and clarity of coverage, exclusions, add-ons and claims support. Price should be examined as a risk-based and value-sensitive decision, not merely a discounting tool. Place includes direct digital and assisted touchpoints as well as brokers and corporate agents that can broaden access to complex or institutional risks. Promotion can then be tested for whether it explains coverage and service expectations responsibly.
- Product clarity. Examine whether policy design and service promises address coverage gaps, claim anxiety and the different needs of individual and commercial customers.
- Route-to-market choices. Compare the roles that direct channels, support teams and intermediaries may play in acquisition, advice and after-sale service.
- Mix planning. Use the Excel framework to align the four Ps by segment, with the Word analysis providing context for evaluating trade-offs and messaging questions.
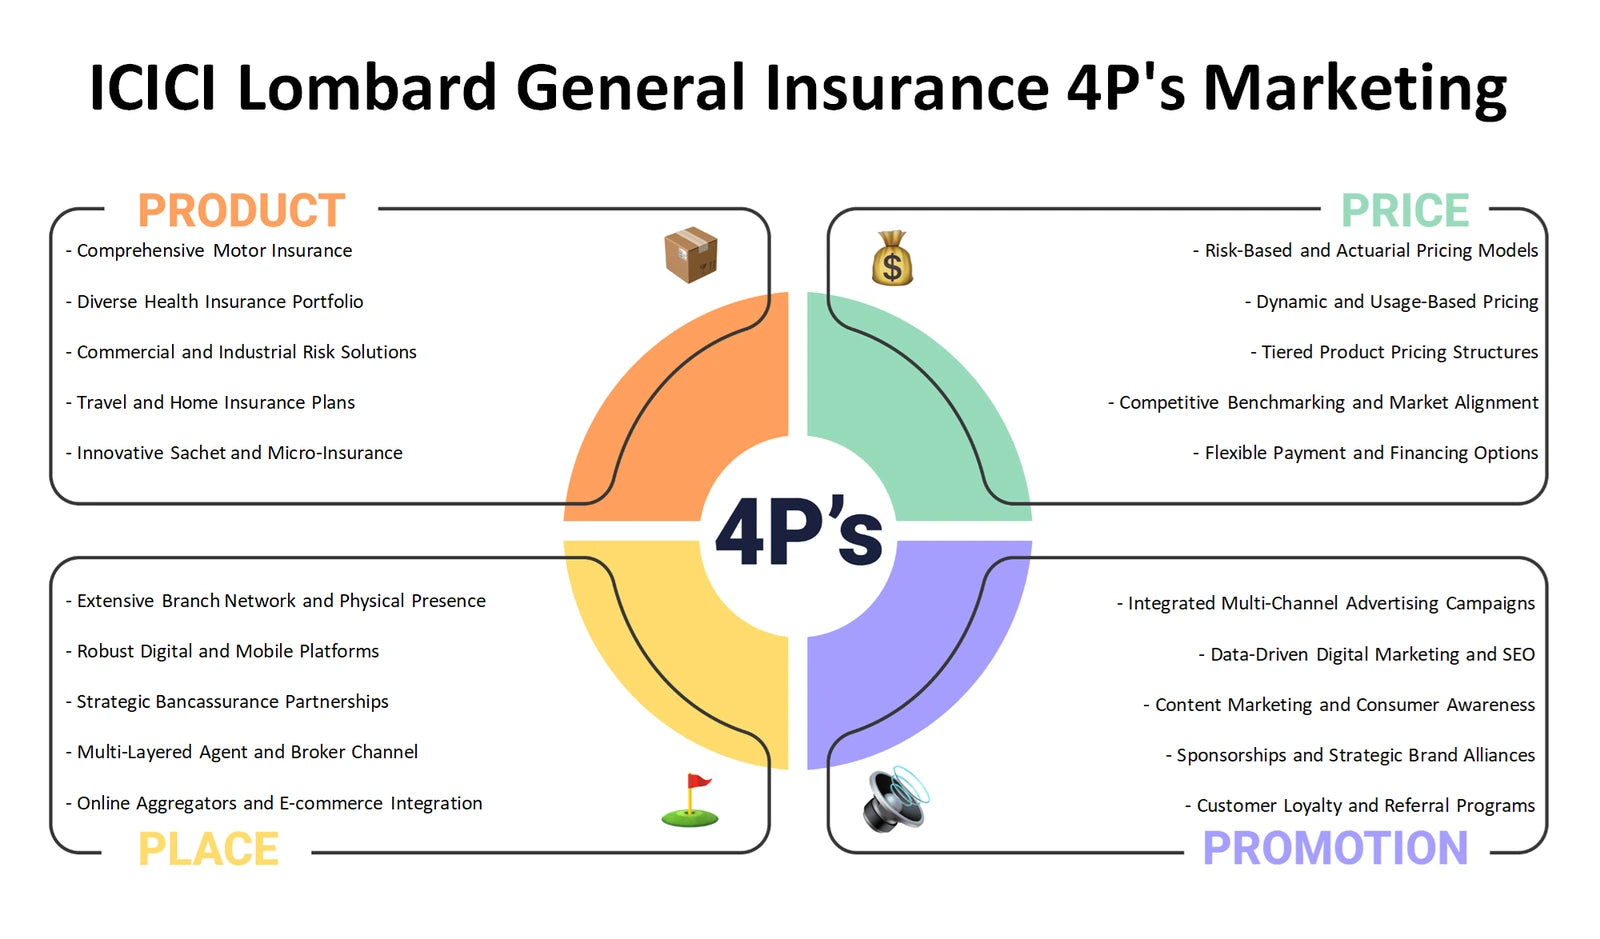
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could reshape insurance demand, risk exposure, regulation and operating priorities in India?
An ICICI Lombard General Insurance PESTLE analysis, also commonly called PESTEL, separates the Political, Economic, Social, Technological, Legal and Environmental forces that sit outside day-to-day management control. It can help distinguish a policy or regulatory question from a documented change, and an economic scenario from a known result. Relevant topics may include household and business risk awareness, affordability pressures, digital adoption, data and service expectations, legal obligations, climate-related loss exposure and public-policy conditions that affect insurance markets. The value of the framework is not predicting one outcome; it is making external assumptions visible and comparable.
- Demand environment. Explore how social awareness, economic conditions and changing customer expectations may alter the appeal or affordability of insurance protection.
- Operating exposure. Consider technology, legal requirements and environmental risk as external influences on claims, data practices, distribution and resilience.
- Scenario discipline. Use the Excel categories to separate drivers from implications, then use the Word analysis to build a more reasoned discussion of priorities.
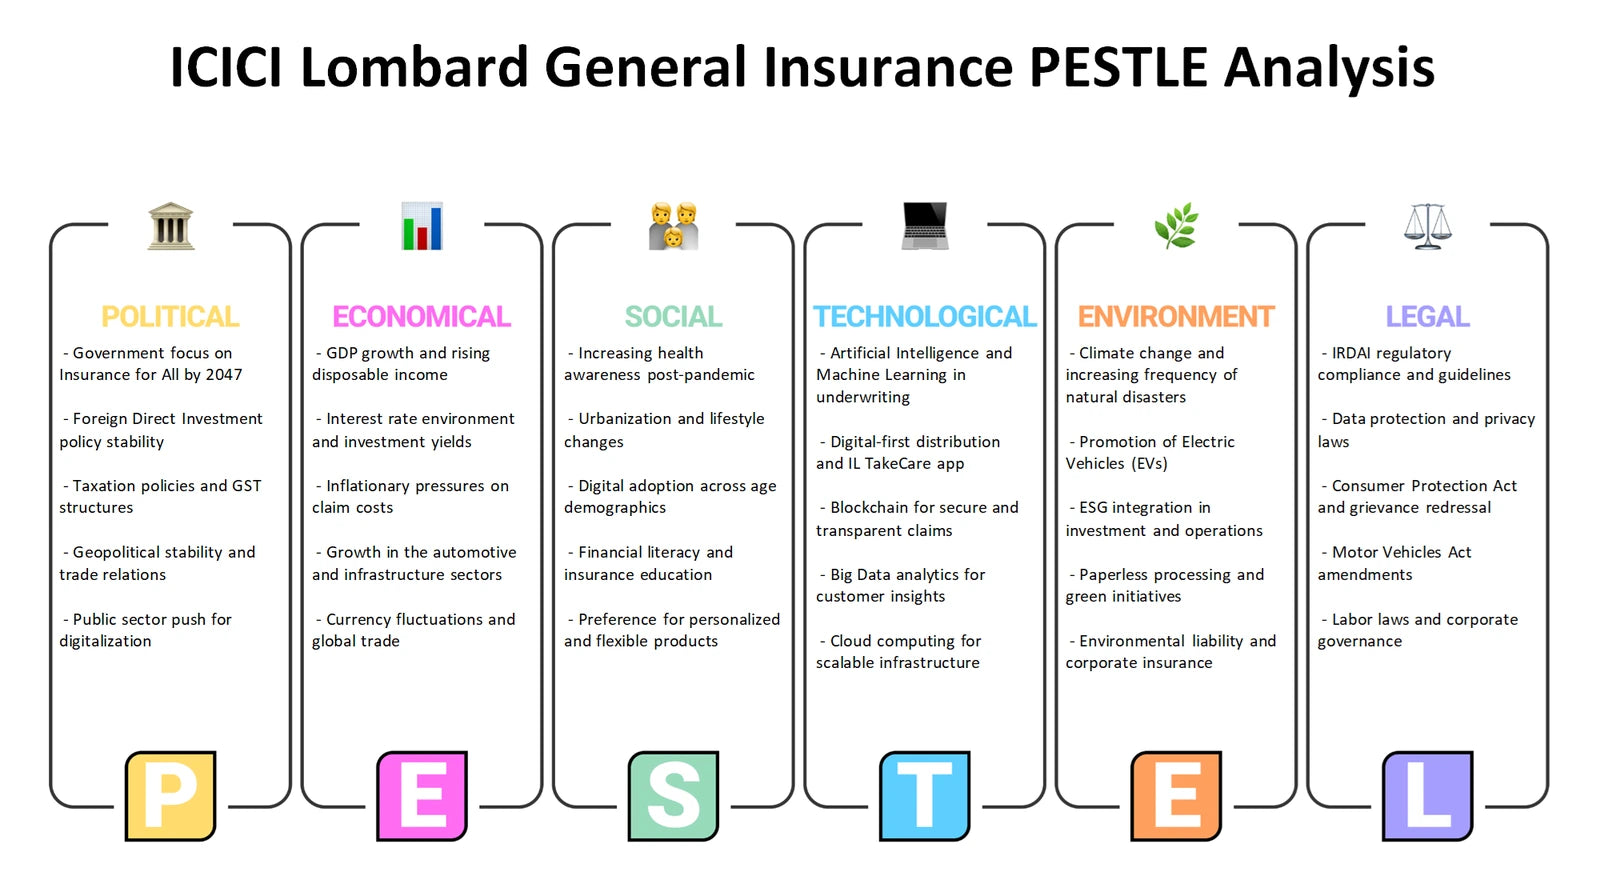
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities and constraints be considered alongside external opportunities and threats facing the insurer?
An ICICI Lombard General Insurance SWOT analysis keeps internal and external issues correctly separated. Strengths and weaknesses concern capabilities the business may control or develop, such as underwriting processes, claims operations, service design, partner management, digital journeys and specialist expertise. Opportunities and threats arise from outside conditions, including changing customer needs, market demand, technology shifts, regulation, economic uncertainty and evolving risk patterns. The framework should not present plausible themes as established findings. Instead, it helps users test which strengths are supported, where weaknesses may limit execution, and whether an external opportunity or threat matters enough to change priorities.
- Internal diagnosis. Review capabilities linked to risk assessment, distribution support, customer communication and claims handling as potential strengths or development needs.
- External fit. Compare possible opportunities and threats with the insurer's ability to respond, rather than treating every market change as equally material.
- Actionable synthesis. Use the Excel SWOT grid to organise evidence and use the Word analysis to connect the resulting themes to strategic questions from the other frameworks.
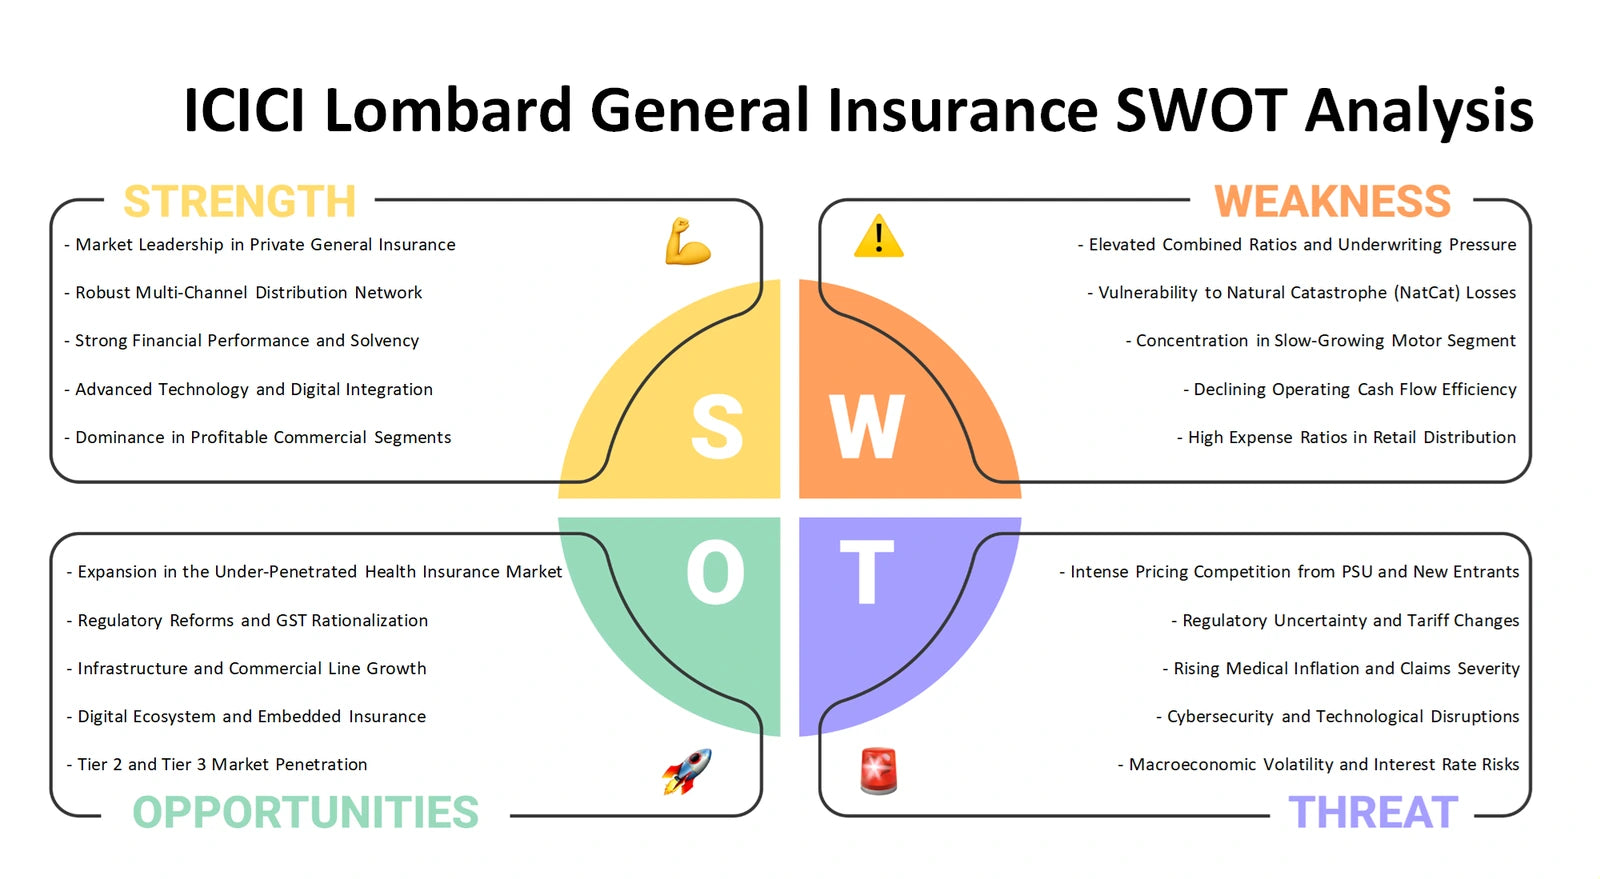
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring the six perspectives into one strategic conversation
Together, the six analyses help connect ICICI Lombard General Insurance's portfolio questions, business-model logic, competitive pressures, customer-facing choices, external environment and internal-versus-external position. The Excel frameworks provide a structured way to compare inputs and organise discussion, while the detailed Word files help develop company-specific reasoning without treating the preview images as the complete analysis.
Company background: ICICI Lombard — Wikidata company profile.