

HomeTrust Bank: Banking Business and Regulation – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
HomeTrust Bank Strategy Analysis Bundle
In the supplied business-model context, HomeTrust Bank is presented as a relationship-based banking business serving community organizations and local businesses. Its model combines direct customer relationships with correspondent arrangements involving larger financial institutions, helping broaden access to payment networks and services such as international wire transfers that may not be delivered independently.
That context raises practical questions about which services deserve resources, how partner-enabled capabilities create value, and how regulation and changing payment expectations affect the model. The six analyses help organize those questions without assuming unverified market shares, financial results, product rankings, or investment conclusions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which HomeTrust Bank service areas may justify greater attention when market growth is considered alongside relative market share?
The HomeTrust Bank BCG Matrix provides a disciplined way to compare a portfolio of banking and partner-enabled service lines. It uses market growth and relative market share to frame possible Stars, Cash Cows, Question Marks, and Dogs; these are analytical categories, not claimed placements for any HomeTrust Bank offering. For a relationship-focused bank, the useful issue is how limited management, technology, compliance, and partnership capacity should be balanced between established customer services and capabilities intended to meet changing business-payment needs.
- Portfolio comparison. Examine relationship banking, payment access, and wire-related services as distinct areas rather than treating the business as one undifferentiated offering.
- Resource trade-offs. Consider whether higher-growth opportunities require investment, whether mature services can fund them, and what low-return complexity should be reviewed.
- Structured prioritization. Use the Excel matrix to organize assumptions and comparisons, then use the Word analysis to interpret why market growth and relative position matter.
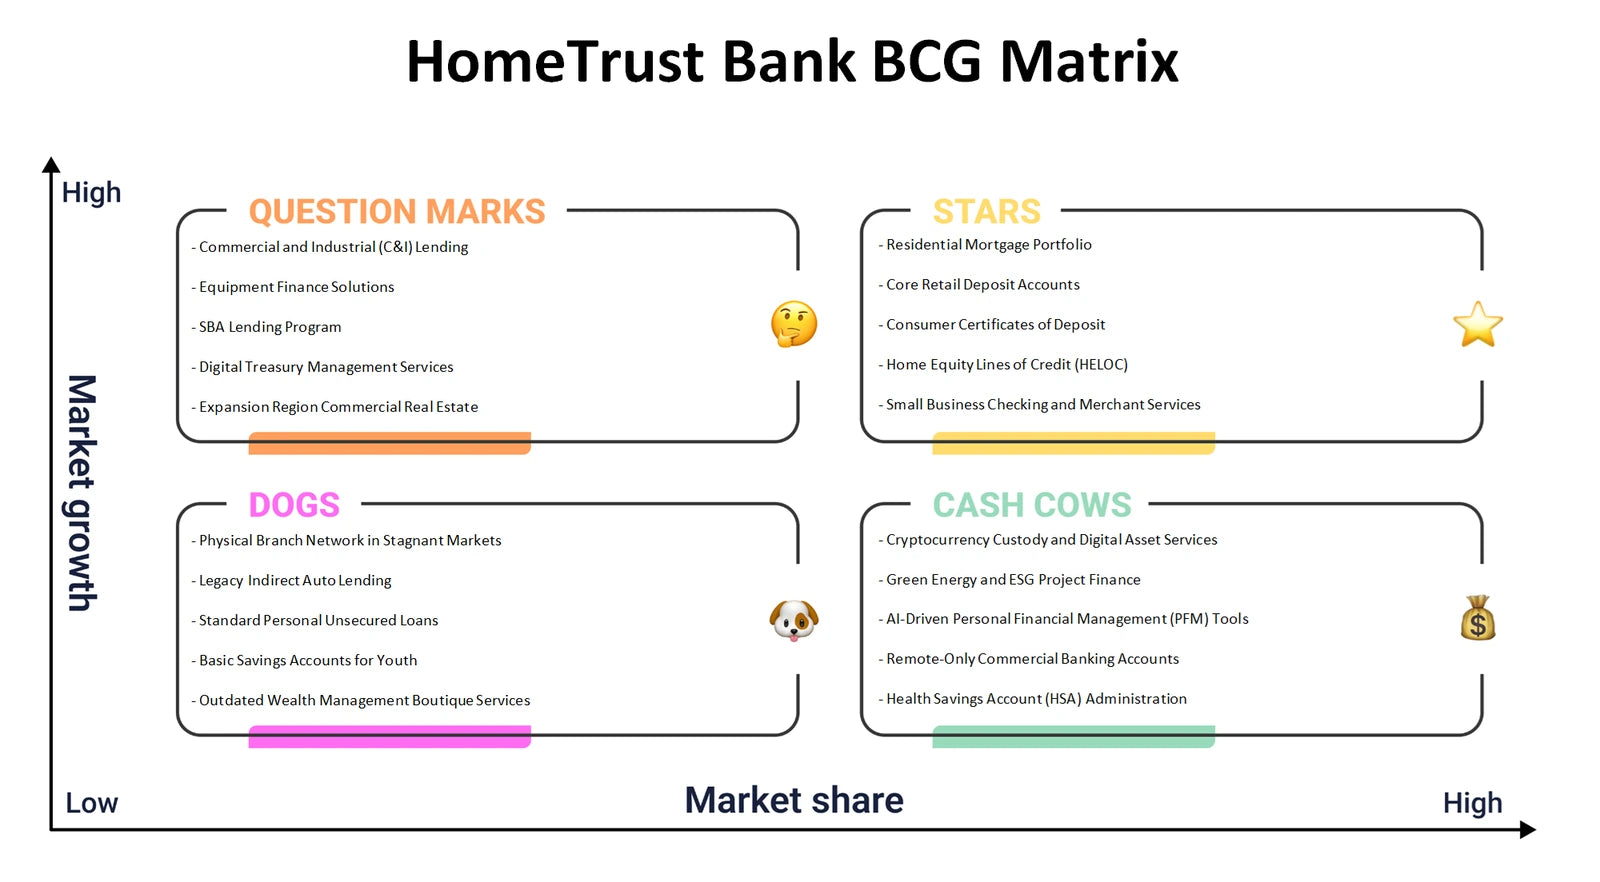
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How can HomeTrust Bank connect relationship-led customer service with partner-supported banking capabilities and sustainable economics?
The HomeTrust Bank Business Model Canvas brings the full operating logic into one view. It considers customer segments, value propositions, channels, customer relationships, and revenue streams alongside key resources, key activities, key partnerships, and cost structure. In the supplied context, correspondent banking relationships are especially relevant because they may extend payment-network and international-wire capability while also creating dependency, coordination, and control requirements. The canvas helps assess whether the value promised to local businesses and community organizations is matched by practical delivery channels and a viable economic structure.
- Value connection. Link relationship-based service to the customer needs that payment access, transfers, and banking support are intended to address.
- Partner economics. Explore how correspondent relationships affect activities, resources, costs, customer experience, and possible revenue-stream questions without assuming fee levels.
- Model mapping. Populate the Excel framework block by block and use the Word analysis to examine the dependencies and trade-offs between the nine building blocks.
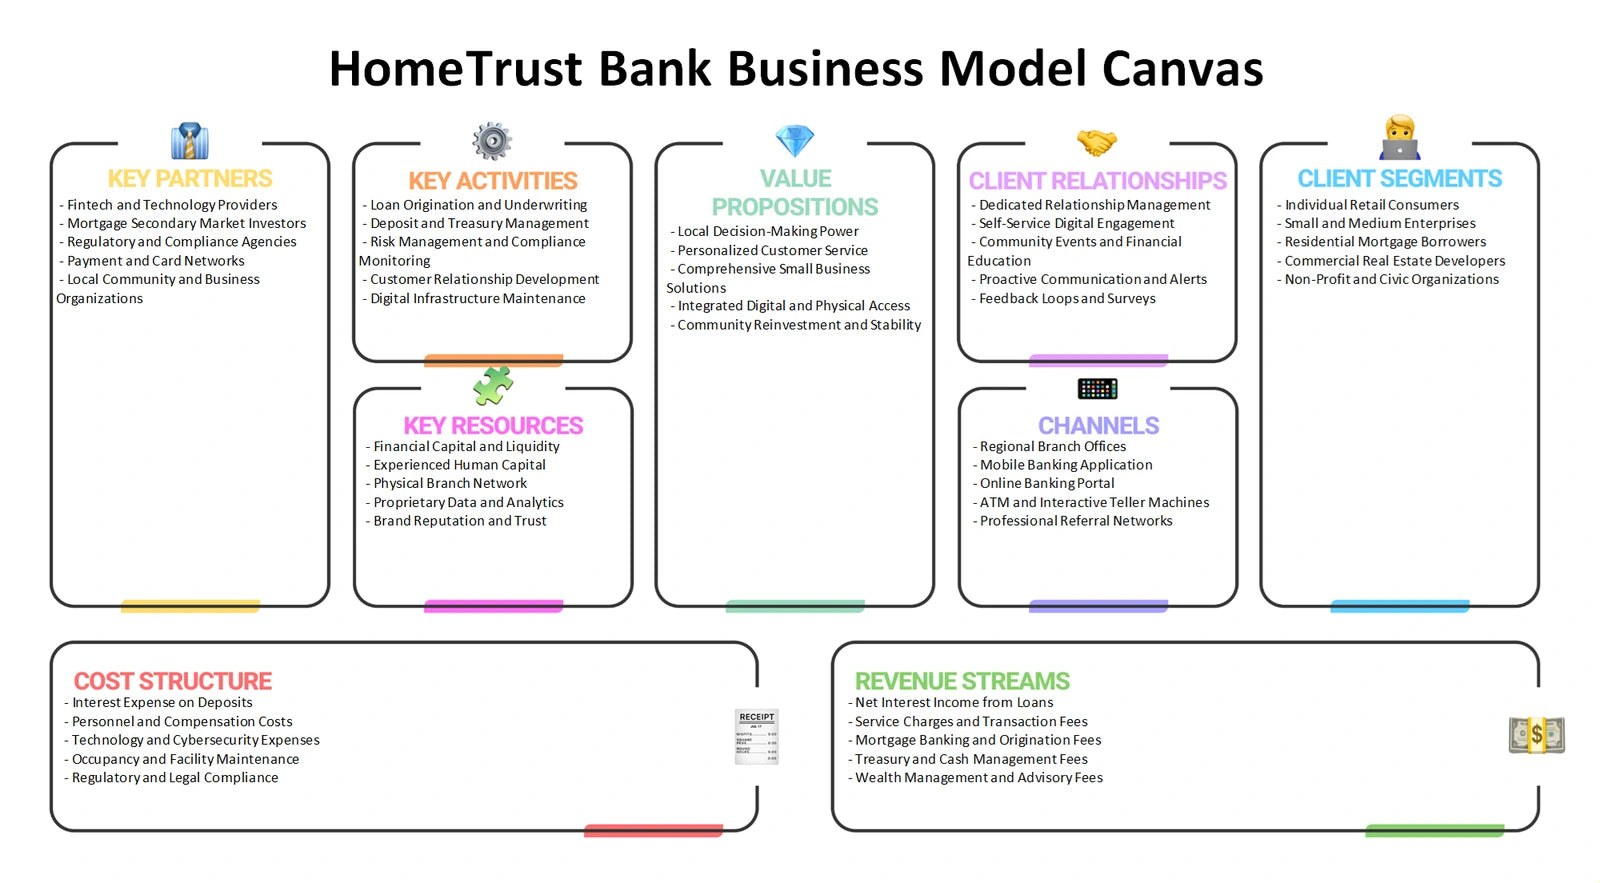
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What competitive pressures could shape the attractiveness of relationship banking and partner-enabled payment services?
HomeTrust Bank Porter's Five Forces examines the industry conditions surrounding its described banking model rather than assigning an unsupported competitive score. Rivalry can include banks and specialist providers seeking similar business relationships. Buyer power concerns customers' ability to compare banking, payment, and transfer options. Supplier power can arise through correspondent institutions, payment infrastructure, technology providers, and other essential counterparties. The framework also considers new entrants, including digitally led financial services, and substitutes such as non-bank payment tools or alternative sources of business finance.
- Rivalry and choice. Assess where local relationship service may differentiate an offer and where customers can switch based on convenience, cost, or digital capability.
- Dependency exposure. Compare the benefits of partner access with the negotiating power and operating constraints that important external providers can create.
- Pressure testing. Use the Excel framework to record each force and supporting observations, then consult the Word analysis to connect pressures to strategic responses worth evaluating.
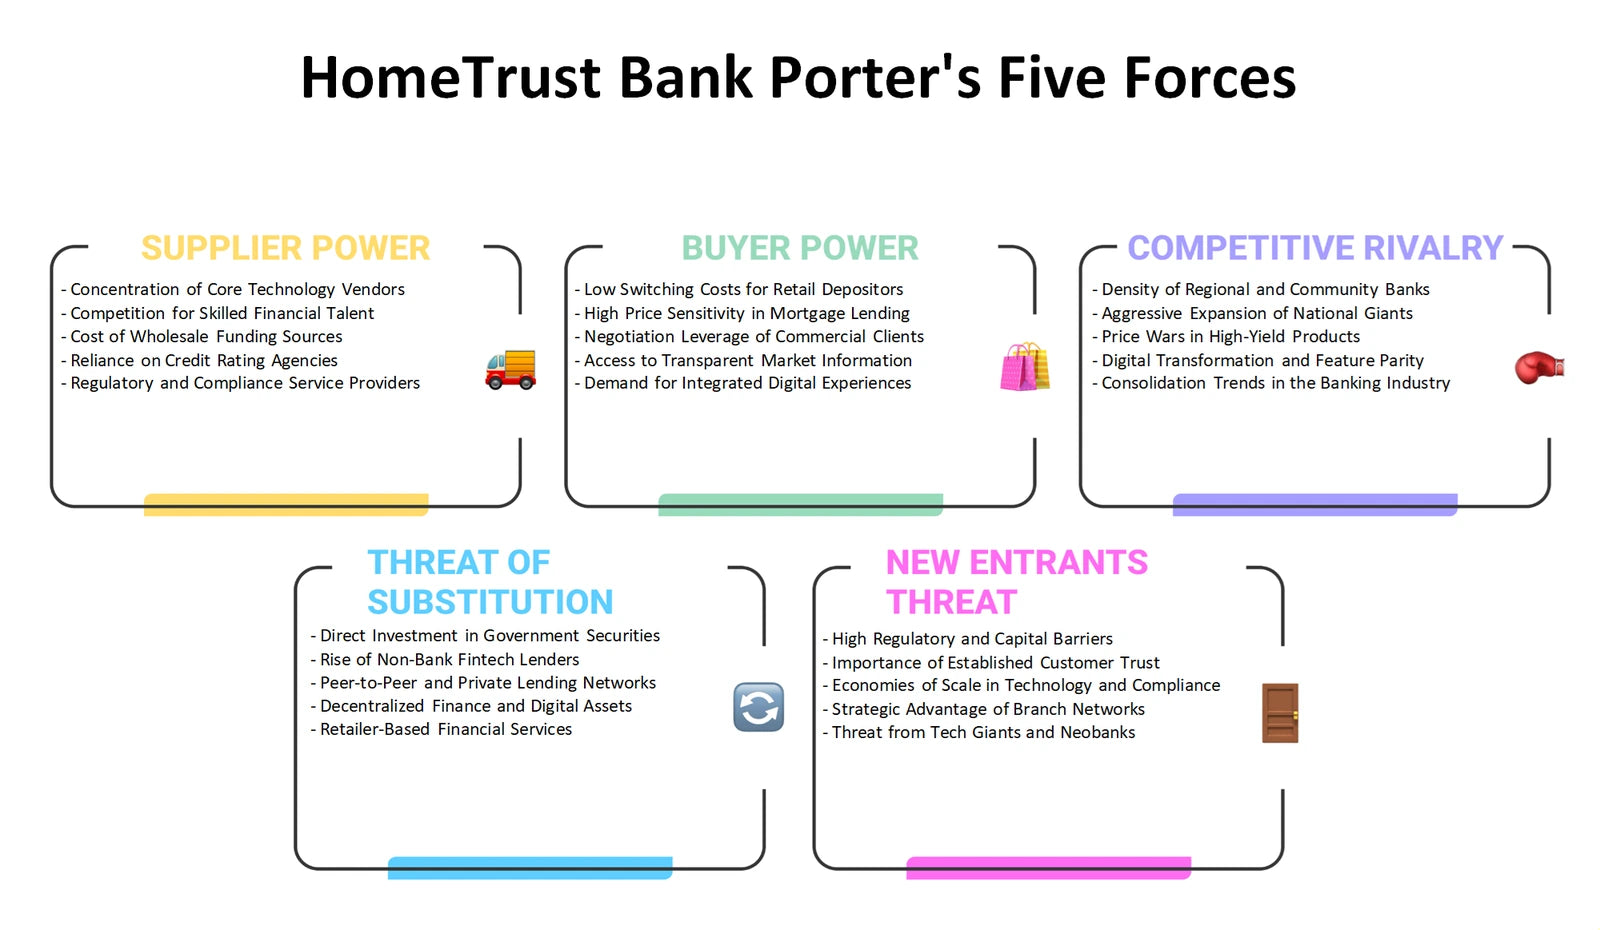
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should HomeTrust Bank align its service proposition, pricing logic, customer access, and communications in a trust-sensitive banking market?
The HomeTrust Bank Marketing Mix applies Product, Price, Place, and Promotion to a regulated service business. Product analysis can distinguish core relationship banking from partner-supported payment and international-transfer access. Price is not simply a list of charges; it helps examine the clarity and perceived fairness of account, service, or transaction economics where relevant. Place considers direct relationship channels and the role of external networks in service delivery. Promotion considers how useful, accurate communications can build understanding among local businesses and community organizations without making unsupported promises.
- Service design. Compare the customer value of personal banking relationships with the convenience expectations attached to payment and transfer services.
- Channel fit. Evaluate how direct contact, partner infrastructure, and customer communication routes may support access while preserving confidence and clarity.
- 4P alignment. Use the Excel framework to test consistency across Product, Price, Place, and Promotion, with the Word analysis adding context for each decision area.
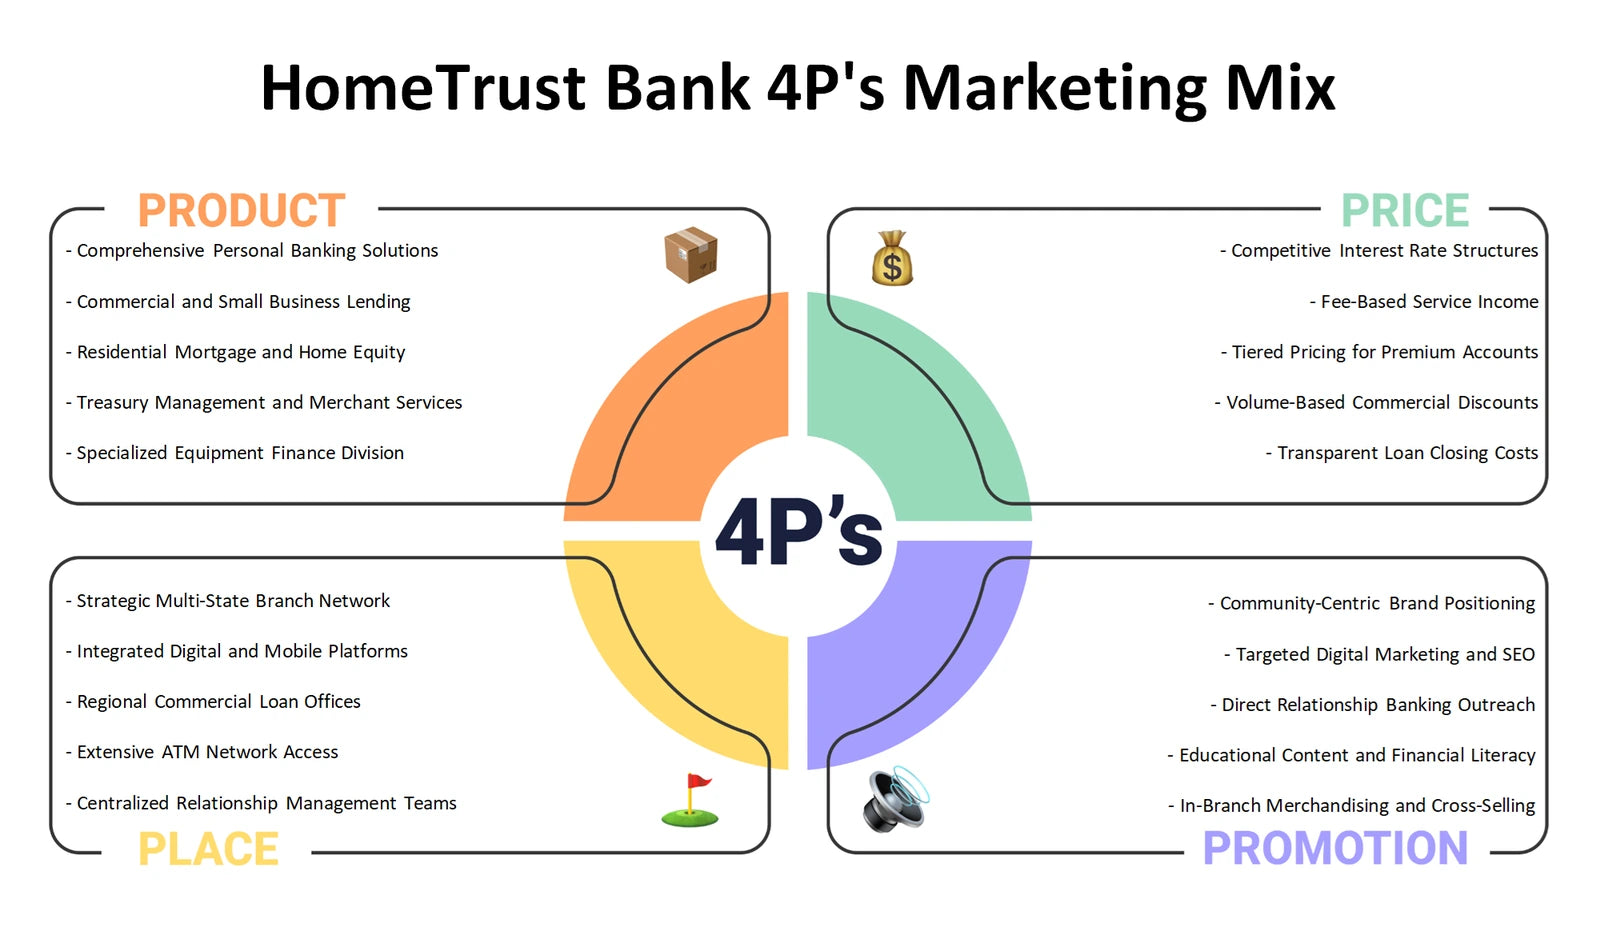
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should HomeTrust Bank monitor when planning relationship banking and correspondent-supported services?
The HomeTrust Bank PESTLE analysis, often written PESTEL, separates external influences from internal operating choices. Political factors can include public-policy direction affecting financial services. Economic conditions may shape customer demand, funding conditions, and the affordability of finance. Social expectations can affect trust, inclusion, and preferences for personal versus digital service. Technological change raises questions about payment rails, cybersecurity, and integration. Legal factors include compliance, privacy, anti-financial-crime, and consumer-protection obligations, while environmental considerations may affect local economies, operational resilience, and risk assessment.
- External signals. Distinguish documented sector developments from questions to monitor, rather than treating a possible policy, rate movement, or law as an established current fact.
- Connected exposure. Consider how technology, regulation, and economic conditions can interact with correspondent dependencies and customer expectations.
- Monitoring agenda. Use the Excel structure to sort developments by category and the Word analysis to translate them into relevant planning and review questions.
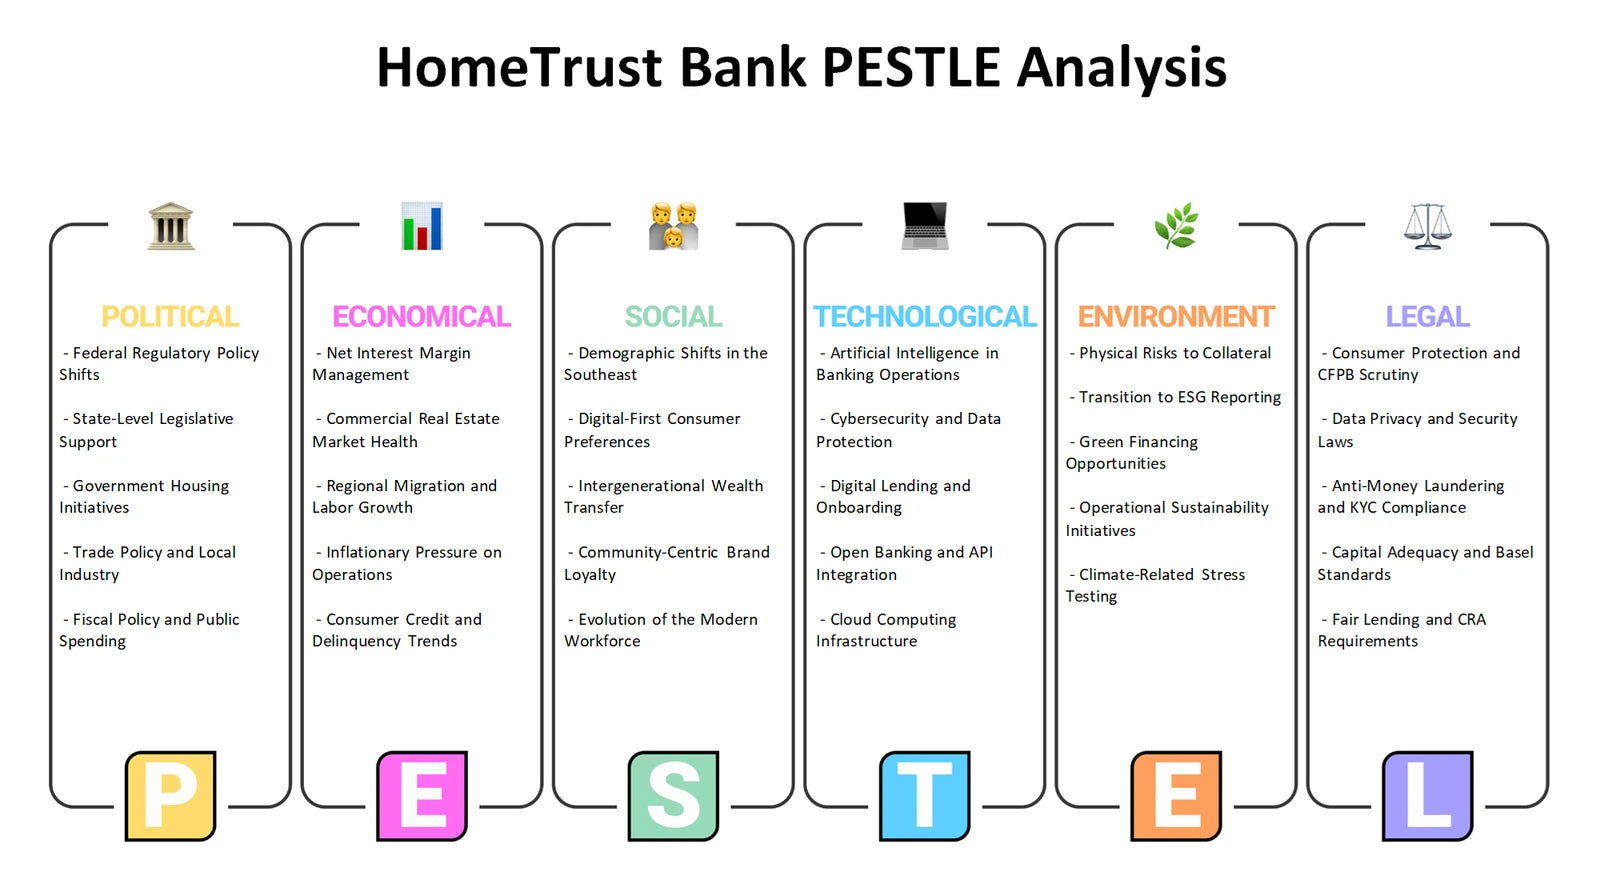
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can HomeTrust Bank distinguish its controllable capabilities and limitations from the outside opportunities and threats it faces?
The HomeTrust Bank SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. The supplied context suggests themes worth testing, including relationship-based customer engagement, community connections, correspondent access, compliance demands, and reliance on external infrastructure. These are not pre-set SWOT findings. The value of the framework is in asking which capabilities are genuinely distinctive, where systems or counterparties could limit execution, and which external shifts in payments, customer behavior, or regulation may create opportunities or threats. This distinction prevents a market trend from being mislabeled as an internal strength.
- Internal reality. Examine capabilities, resources, processes, and constraints that management can influence, including the operational implications of partner relationships.
- External fit. Compare those internal factors with outside changes that may expand customer needs or increase competitive and regulatory pressure.
- Actionable synthesis. Use the Excel SWOT grid to separate evidence by category, then use the Word analysis to develop focused questions and possible strategic priorities.
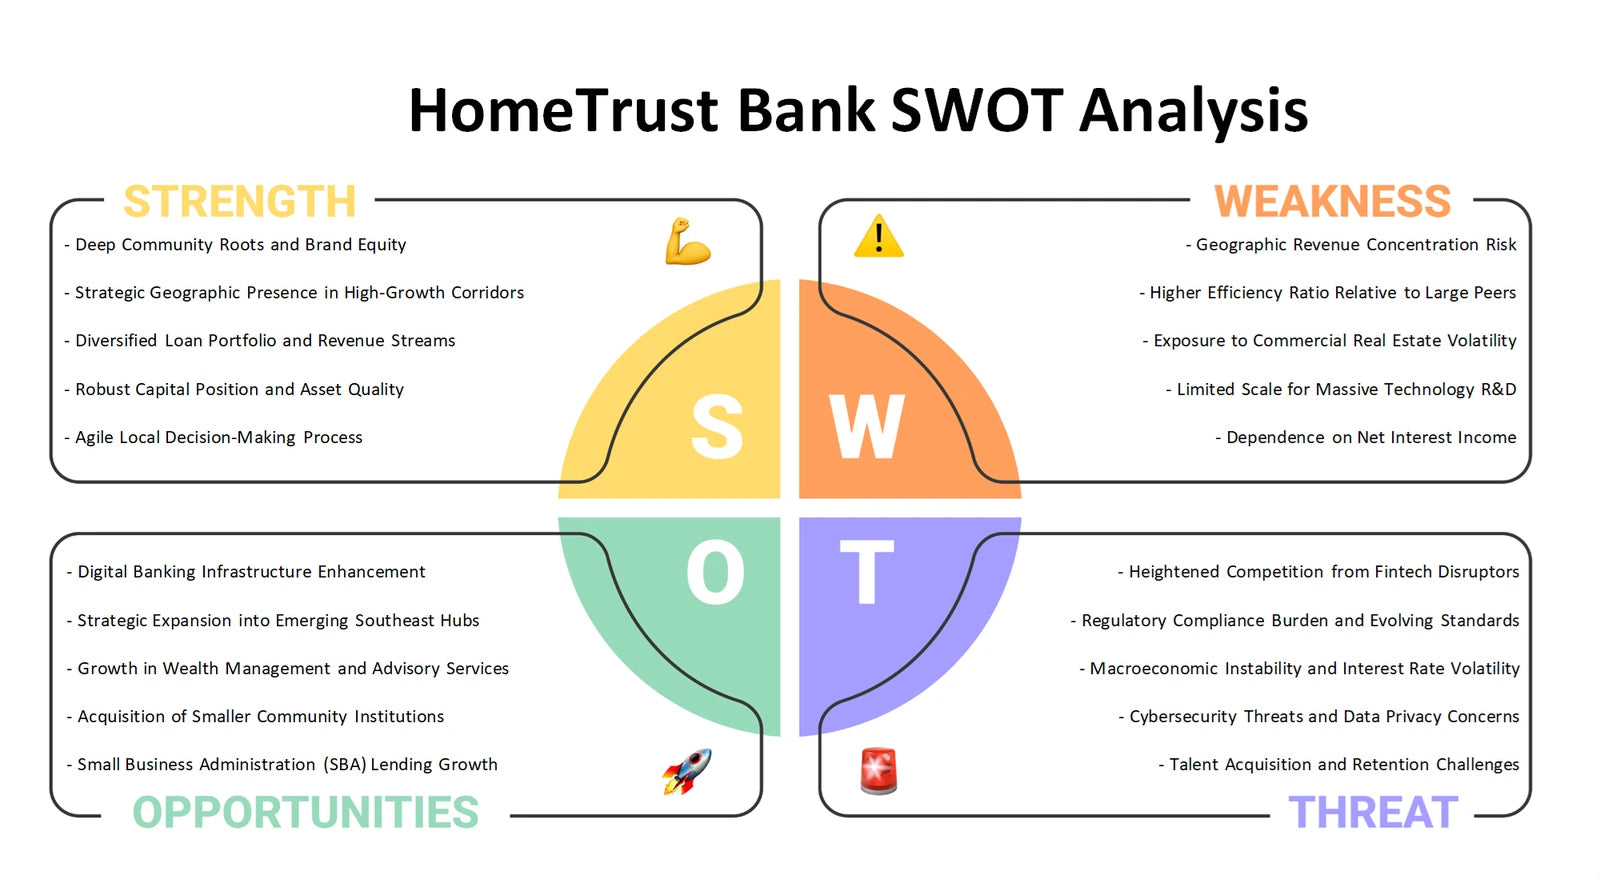
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of HomeTrust Bank
Used together, the six perspectives move from portfolio choices and business-model logic to market pressure, customer-facing decisions, external change, and strategic fit. The Excel frameworks provide a structured way to compare questions and organize inputs, while the Word files support deeper interpretation of the relationship-banking and partner-enabled service context described for HomeTrust Bank.
Company background: HomeTrust Bank — supplied business-model context.