

HomeStreet: Banking Business – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
HomeStreet Strategy Analysis Bundle
HomeStreet refers here to HomeStreet Bank, an American bank identified in public directory records within financial services. The supplied product context centres on relationship-based banking for consumers and small businesses, including deposit, lending, advisory and engagement questions relevant to a regional banking footprint described across Washington, Oregon, California and Hawaii.
The analytical value is not in treating a high-level company snapshot as a verdict. It is in examining how relationship benefits, digital access, financial education and cross-service needs could affect customer retention, funding, operating priorities and growth choices. The six connected frameworks help turn those questions into a structured strategic discussion.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking offer categories deserve scarce growth investment when market growth and relative market share are considered together?
The HomeStreet BCG Matrix provides a disciplined way to compare a bank's possible portfolio areas, such as consumer relationships, small-business services, lending propositions, deposit products or digital service initiatives. It applies the two BCG criteria of market growth and relative market share rather than relying on headline size alone. The familiar Stars, Cash Cows, Question Marks and Dogs are analytical categories, not pre-assigned labels for HomeStreet offerings. That distinction matters when leadership must weigh growth spending, service investment, balance-sheet capacity and the support required for mature customer relationships.
- Portfolio comparison. Examine which service areas may combine stronger demand conditions with a defensible relative position, and which need evidence before receiving additional resources.
- Capital discipline. Consider how cash-generating relationship activity could support selective investment without assuming that every growth opportunity warrants the same priority.
- Planning workspace. Use the Excel framework to organise candidate services and assumptions, then use the Word analysis to record the reasoning, evidence gaps and management questions behind each placement.
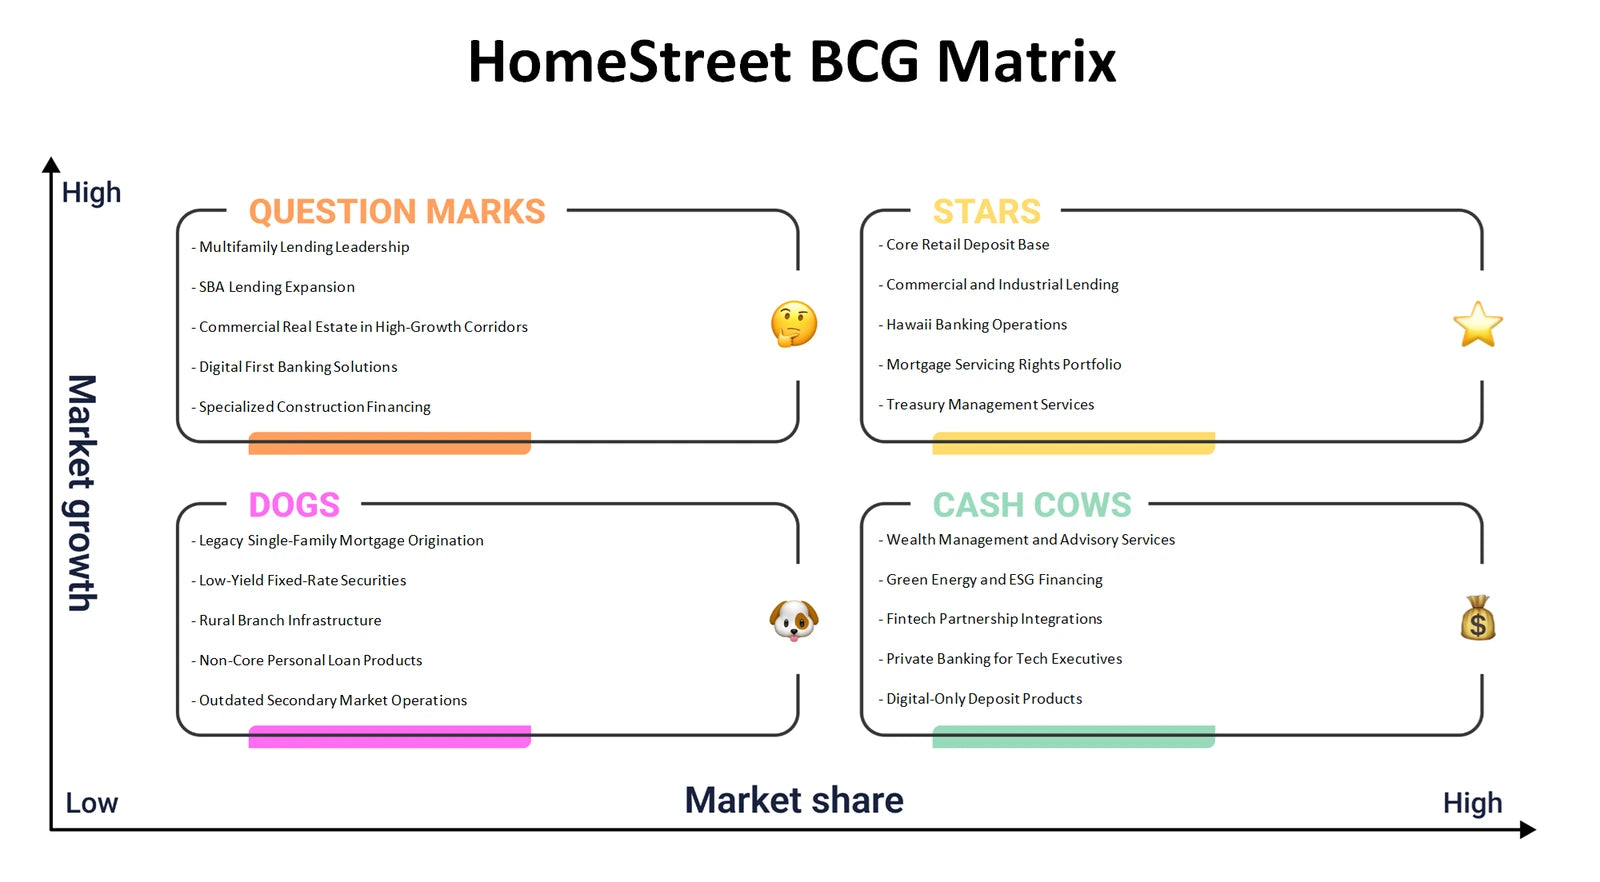
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, banking services and operating resources fit together to create sustainable value?
The HomeStreet Business Model Canvas helps connect all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a relationship-led bank, the useful question is how consumer and small-business needs move through advice, account access, credit, service interactions and retention efforts into revenue and operating requirements. The canvas does not assume that a particular product, partner or income stream is more important; it makes the dependencies visible so that teams can test whether the stated customer promise is supported by the needed capabilities and economics.
- Customer-value fit. Map distinct customer needs against value propositions, relationship expectations and channels such as branch, adviser, telephone or digital access where relevant.
- Economic links. Trace how revenue streams may depend on key resources, activities, partnerships and the cost structure needed to serve regulated financial relationships well.
- Connected documentation. Populate the Excel canvas as a one-page operating map, then use the Word analysis to add context on assumptions, interdependencies and questions requiring validation.
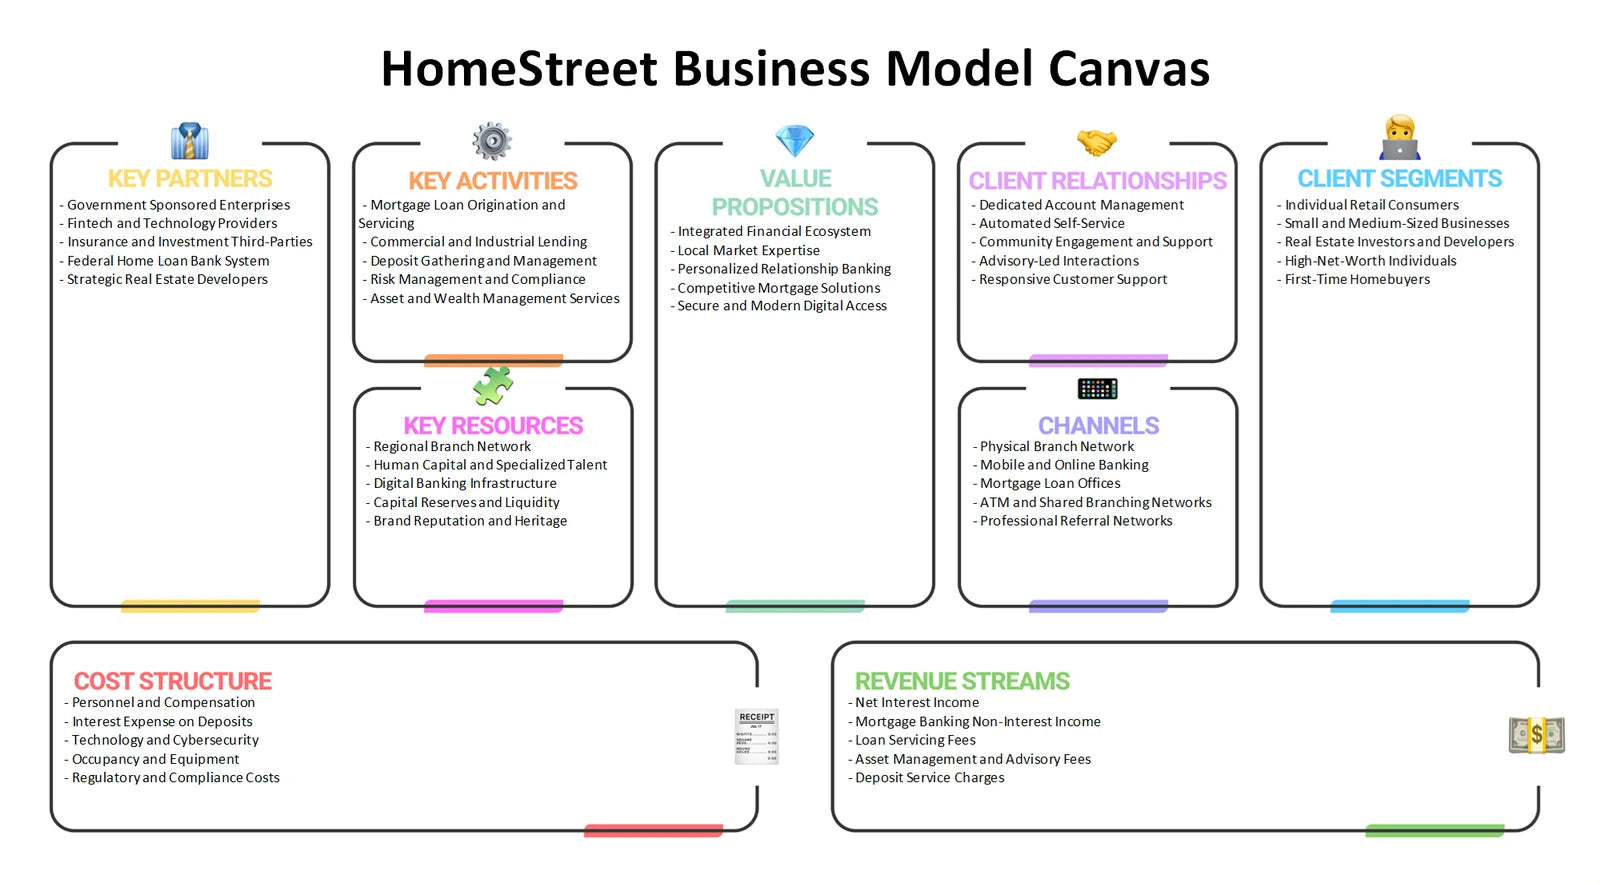
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness and resilience of HomeStreet's banking relationships?
HomeStreet Porter's Five Forces examines the banking environment through rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes. Rivalry can shape how banks compete for deposits, lending relationships and service quality. Supplier power may arise around funding, technology, payments infrastructure or specialist talent, while buyers can compare rates, fees, convenience and advice. New entrants include digitally enabled financial providers and other institutions able to serve specific needs. Substitutes are broader alternatives to bank products, such as non-bank payment, savings, credit or investment routes, rather than simply another direct bank competitor.
- Competitive pressure. Compare where customer switching, rate sensitivity and differentiated service may increase rivalry across consumer and small-business relationships.
- Dependency exposure. Consider the bargaining position of important funding, technology and service inputs alongside the options available to customers.
- Evidence-led review. Use the Excel framework to rate discussion topics consistently, then use the Word analysis to explain why each force matters and what evidence would strengthen the assessment.
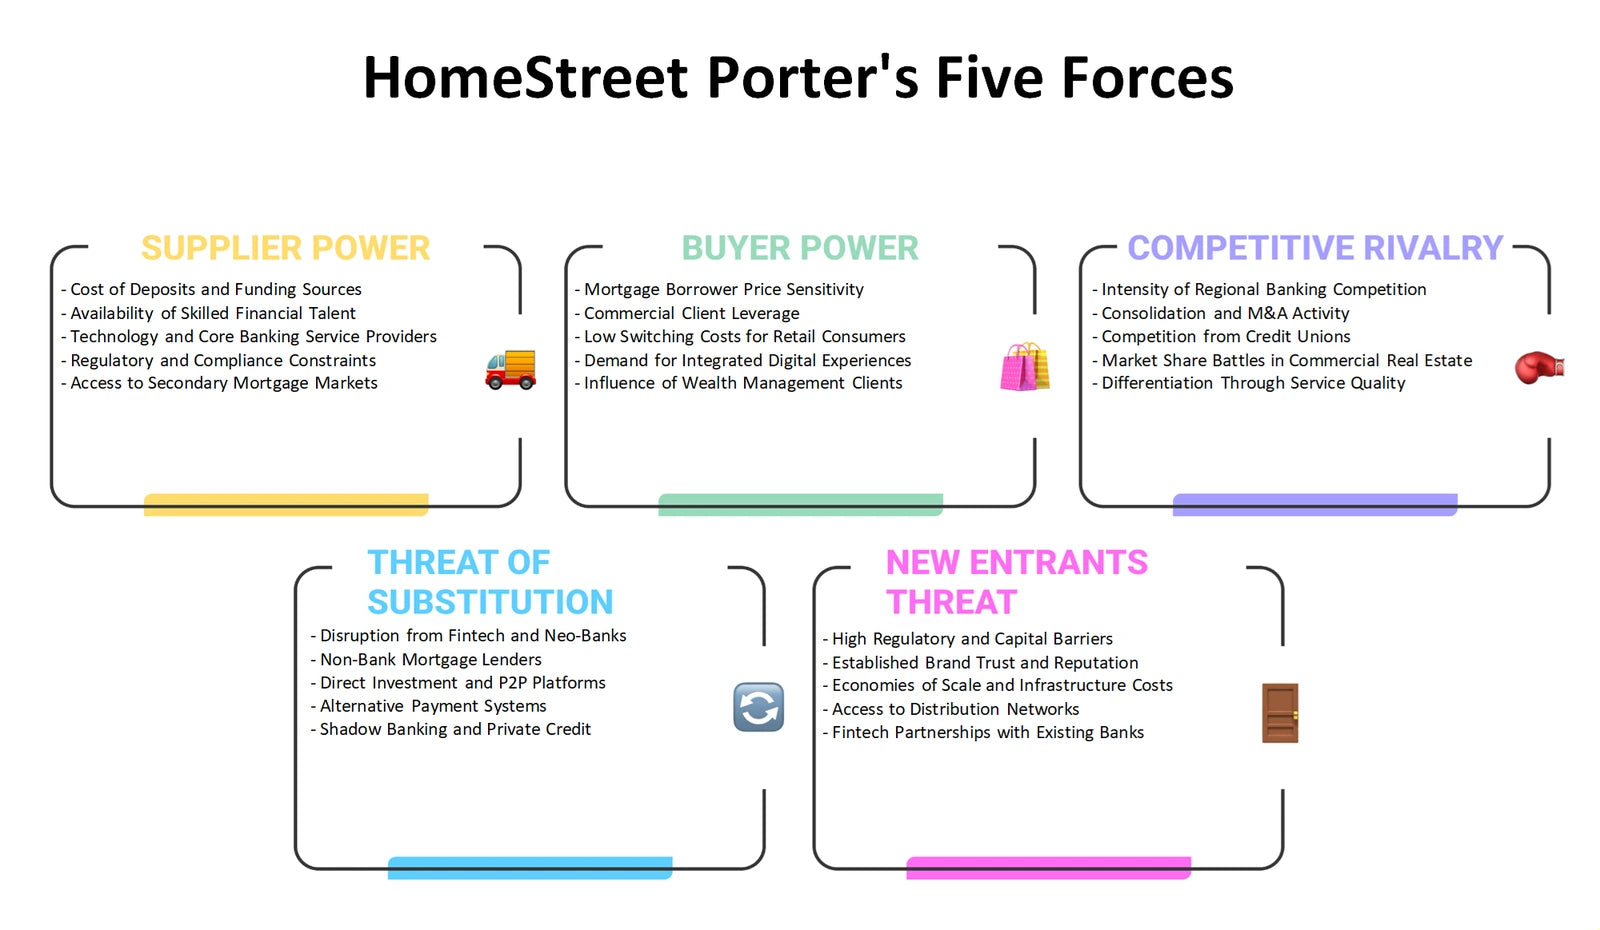
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, access routes and communications reinforce a trusted banking relationship?
The HomeStreet Marketing Mix applies Product, Price, Place and Promotion to a regulated financial-service setting. Product analysis can compare the role of accounts, lending, relationship support and associated financial-service needs. Price is broader than a posted fee: it can include interest, account charges, waivers, terms and the value customers attach to service. Place considers how regional presence and digital access work together, while Promotion assesses how clear, compliant communication, education and personalised outreach might help customers understand relevant choices. The framework supports alignment rather than assuming a campaign, price point or channel share.
- Offer design. Test whether services address distinct consumer and small-business needs while remaining understandable across the customer journey.
- Access and trust. Examine the trade-off between convenient digital service, human relationship support and communications suited to financial decisions.
- Action map. Use the Excel structure to compare the four Ps by audience or offer, and use the Word analysis to capture positioning questions, constraints and possible follow-up research.
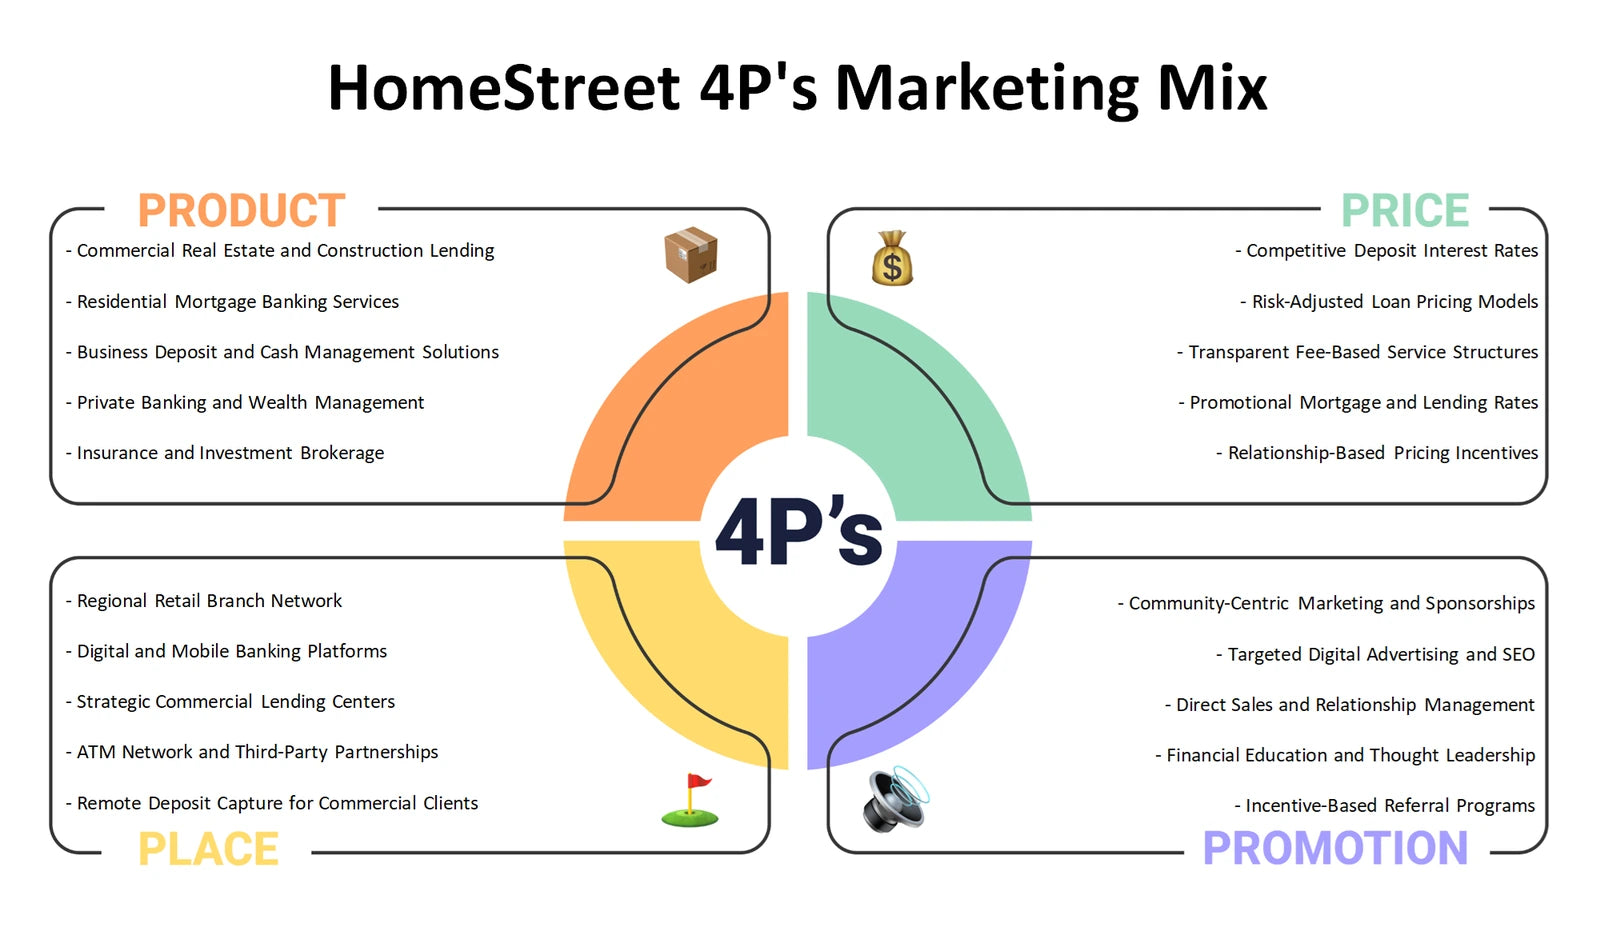
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external forces should be monitored when planning banking growth, service design and risk management?
The HomeStreet PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal factors can affect banking supervision, consumer protection and operating expectations; economic conditions can influence borrowing demand, deposit behaviour, credit quality and funding choices. Social shifts may change preferences for advice, financial education or digital convenience. Technology raises questions about cyber resilience, payments and service delivery, while environmental factors can affect physical operations, customer risks and lending-related exposure. These are external conditions to assess, not claims that a particular law, rate or event has already changed HomeStreet's position.
- External scan. Separate macroeconomic, policy, customer-behaviour and technology questions so that risks are not confused with internal operating weaknesses.
- Regional relevance. Consider how the product context's Pacific-region footprint could make local economic, weather, infrastructure and regulatory conditions strategically relevant.
- Monitoring tool. Use the Excel framework to log external signals by category and priority, then use the Word analysis to develop implications, owners and review questions for discussion.
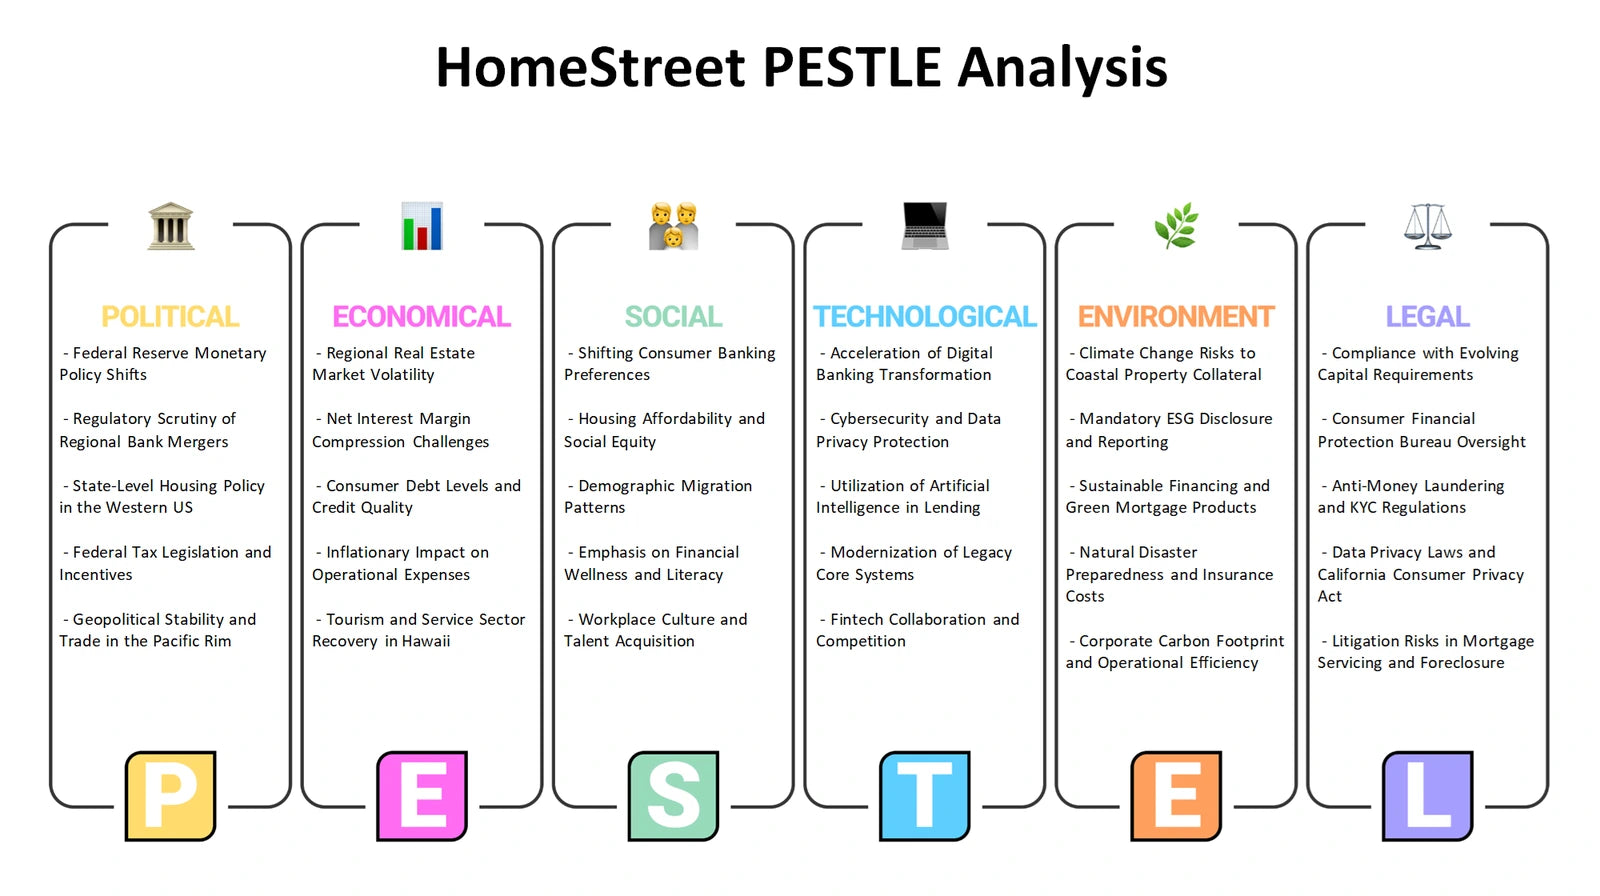
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and constraints be considered alongside external opportunities and threats?
The HomeStreet SWOT analysis keeps internal and external factors distinct. Strengths and weaknesses concern capabilities under greater organisational influence, such as relationship-management capacity, customer experience, operating processes, digital delivery or resource constraints. Opportunities and threats arise from market conditions, customer needs, regulatory expectations, technology shifts and competitive alternatives. The supplied context points to themes such as relationship benefits, financial education and cross-service engagement, but the framework treats these as areas to investigate rather than established competitive advantages. This separation is valuable because an attractive market opportunity is not automatically an internal strength, and an internal weakness is not the same as an external threat.
- Balanced diagnosis. Distinguish possible capabilities to build on from limitations that may require investment, redesign, control or clearer evidence.
- Strategic pairing. Explore how potential strengths could support opportunities, where weaknesses may amplify threats and which trade-offs deserve management attention.
- Decision record. Use the Excel matrix to sort observations by source and ownership, then use the Word analysis to explain priorities, uncertainties and strategic implications in fuller language.
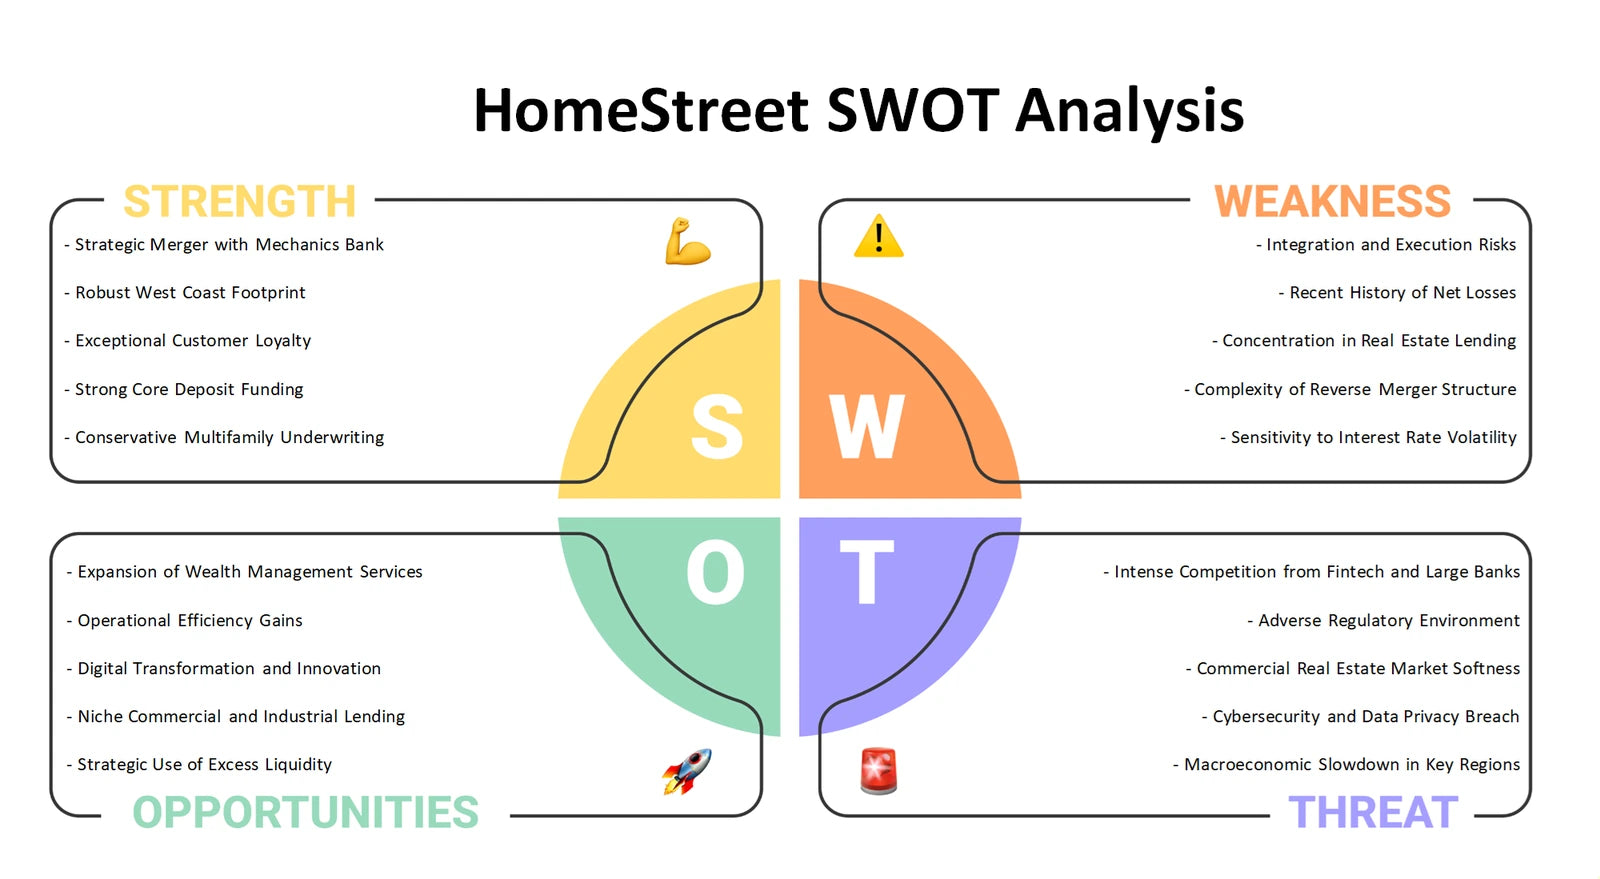
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected strategic view of HomeStreet
Used together, the BCG Matrix clarifies portfolio questions, the Canvas links value creation to economics, Five Forces and PESTLE examine outside pressure, the Marketing Mix tests customer-facing choices, and SWOT brings internal and external considerations together. The Excel frameworks support structured comparison, while the detailed Word analysis helps turn that structure into company-specific discussion, evidence questions and strategic priorities.
Company background: HomeStreet Bank — public directory profile.