

Hippo Insurance Services: Underwriting and Pricing – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Hippo Insurance Services Strategy Analysis Bundle
The supplied product context for Hippo Insurance Services describes a U.S.-focused property-insurance business built around digital underwriting, smart-home integrations and broker relationships. Its model considers property attributes, weather and peril information when assessing residential risk, while carrier-capacity and reinsurance relationships support the insurance offering. Homeowners, distribution partners and insurance-capacity providers therefore sit within the same operating system, even though they have different needs and incentives.
That context makes portfolio choices, underwriting discipline, distribution economics and catastrophe exposure especially useful questions to examine. The six connected frameworks help organise those questions without assuming a particular market share, financial result or strategic recommendation. Together, the Excel frameworks and detailed Word analysis provide practical ways to map priorities, compare trade-offs and discuss how a technology-enabled property-insurance model may evolve.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which offerings, customer routes or risk pools deserve resources when growth potential must be balanced against relative market share?
A Hippo Insurance Services BCG Matrix helps distinguish the portfolio logic behind growth from the quality of that growth. The framework uses market growth and relative market share to consider Stars, Cash Cows, Question Marks and Dogs; it does not presume that any Hippo activity belongs in one of those quadrants. For a digitally enabled property-insurance model, the useful comparison may include insurance propositions, partner-led distribution paths or geographic risk exposures. Each can require different capital, data, service and risk-capacity commitments. The analysis supports a more disciplined discussion of where management attention could be concentrated, maintained, tested or reduced.
- Portfolio boundaries. Compare business activities at a sensible level, separating customer acquisition routes from insurance-risk concentrations where needed.
- Capital trade-offs. Examine how expansion into higher-growth opportunities could affect underwriting capacity, catastrophe exposure and operating focus.
- Decision workspace. Use the Excel matrix to record comparable assumptions, then use the Word analysis to explain why each placement should be challenged or revisited.
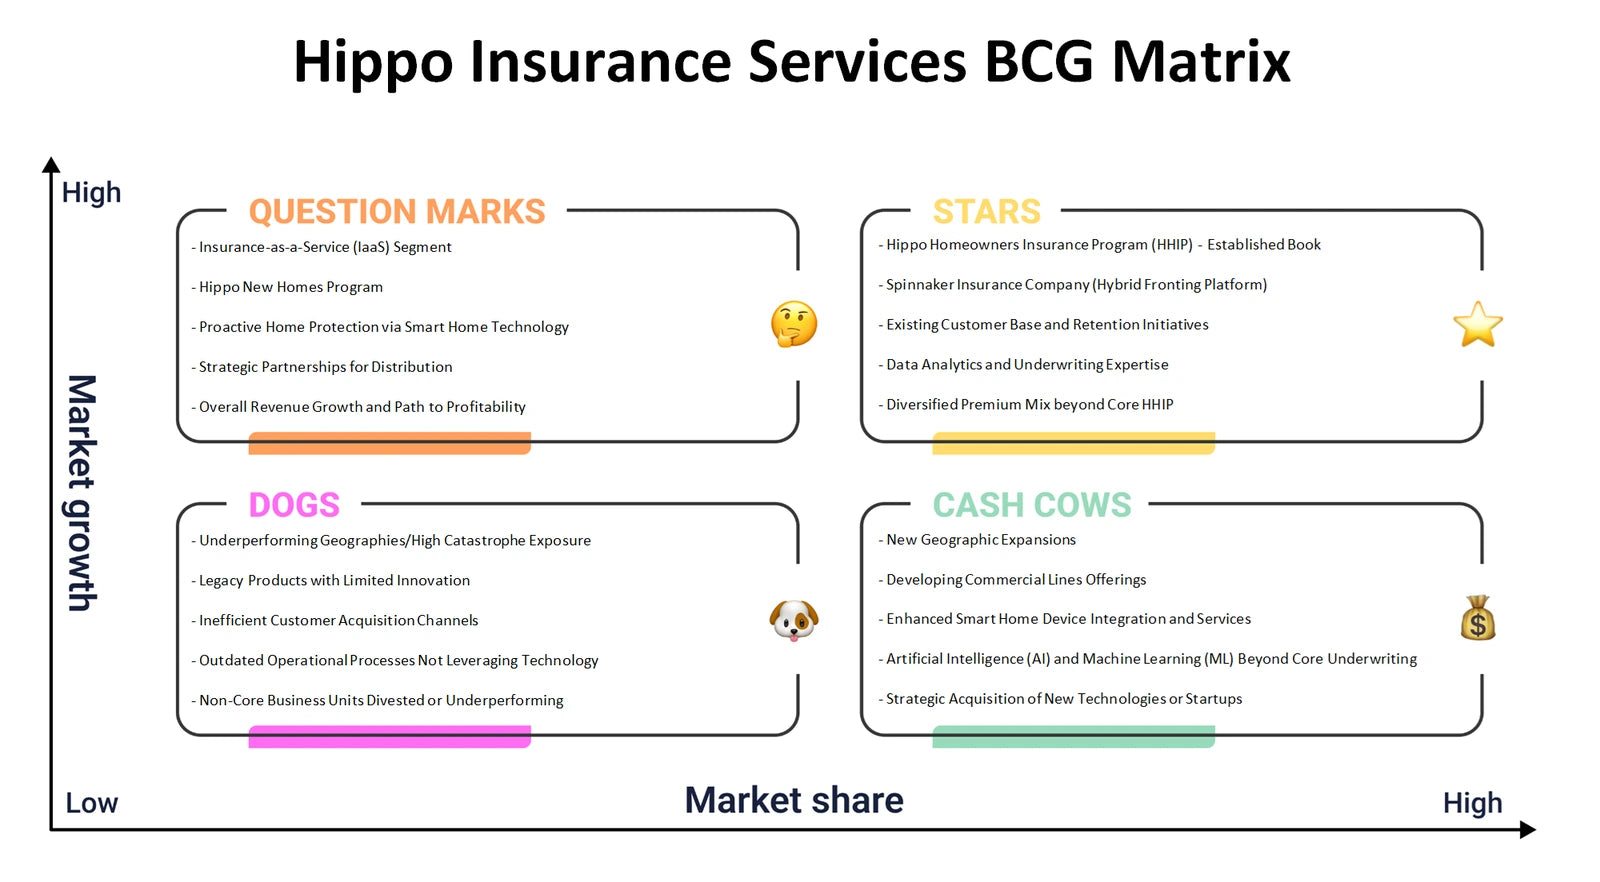
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do data-enabled underwriting, partner distribution and insurance capacity connect to customer value and economic viability?
The Hippo Insurance Services Business Model Canvas brings the nine building blocks into one connected view: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. The supplied context points to homeowners, brokers, smart-home connections, property intelligence and risk-capacity relationships as relevant topics to assess. Rather than treating technology as a standalone feature, the canvas helps examine whether it improves selection, reduces friction, supports service or changes acquisition economics. It also makes the dependencies visible: a customer promise can rely on data quality, underwriting operations, distribution partners and the availability of carrier or reinsurance capacity.
- Value delivery. Trace how a homeowner-facing experience may be linked to property data, digital processes and support through the insurance journey.
- Economic links. Consider how channels, relationships, partnership costs and operating activities influence the path from policy acquisition to sustainable revenue.
- Model alignment. Populate the Excel canvas with working hypotheses and use the Word analysis to connect each block to the operational questions behind it.
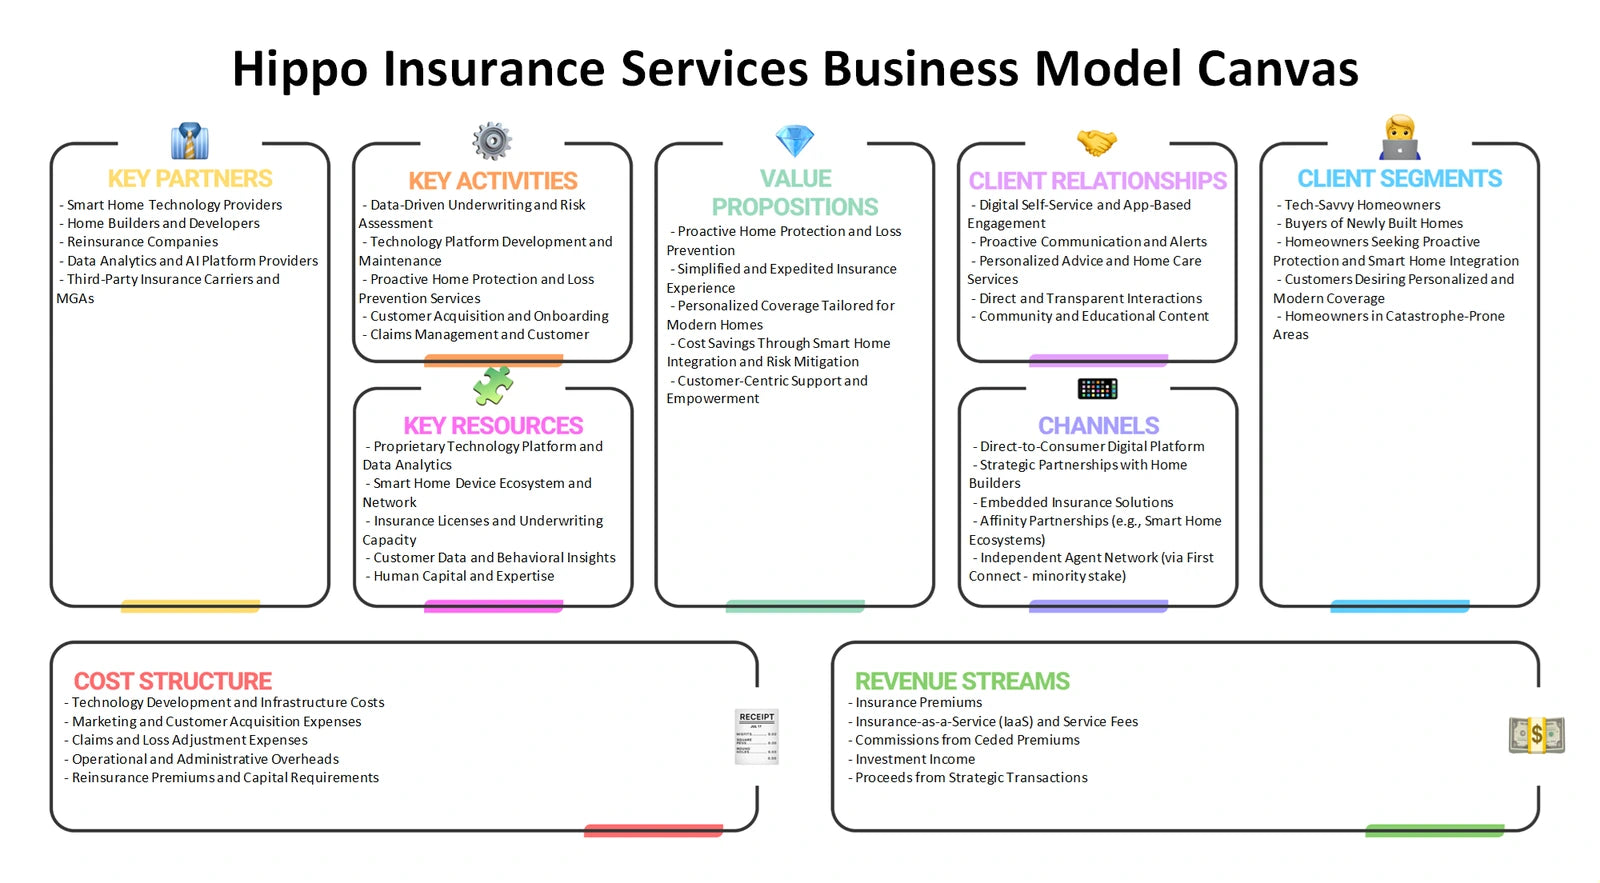
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape the ability of a technology-enabled property-insurance business to compete and retain economic flexibility?
Hippo Insurance Services Porter's Five Forces analysis examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes in the relevant property-insurance environment. Rivalry can extend beyond other insurers to firms competing for homeowner attention, broker support and trusted service. Supplier power is particularly important to explore because insurance capacity, reinsurance, data inputs and technology services can each influence economics and operating choices. Buyers may compare policy value, service and coverage terms, while substitutes can include alternative ways homeowners manage risk or obtain protection. New entrants may bring digital experiences, but regulated underwriting capability and risk capacity can remain meaningful barriers.
- Capacity dependence. Assess how carrier and reinsurance relationships may affect scale, pricing flexibility and exposure management.
- Customer switching. Consider the role of trust, coverage clarity, broker advice and claims experience in homeowner choice and retention.
- Pressure test. Use the Excel framework to rank evidence and uncertainties by force, with the Word analysis providing context for the resulting discussion.
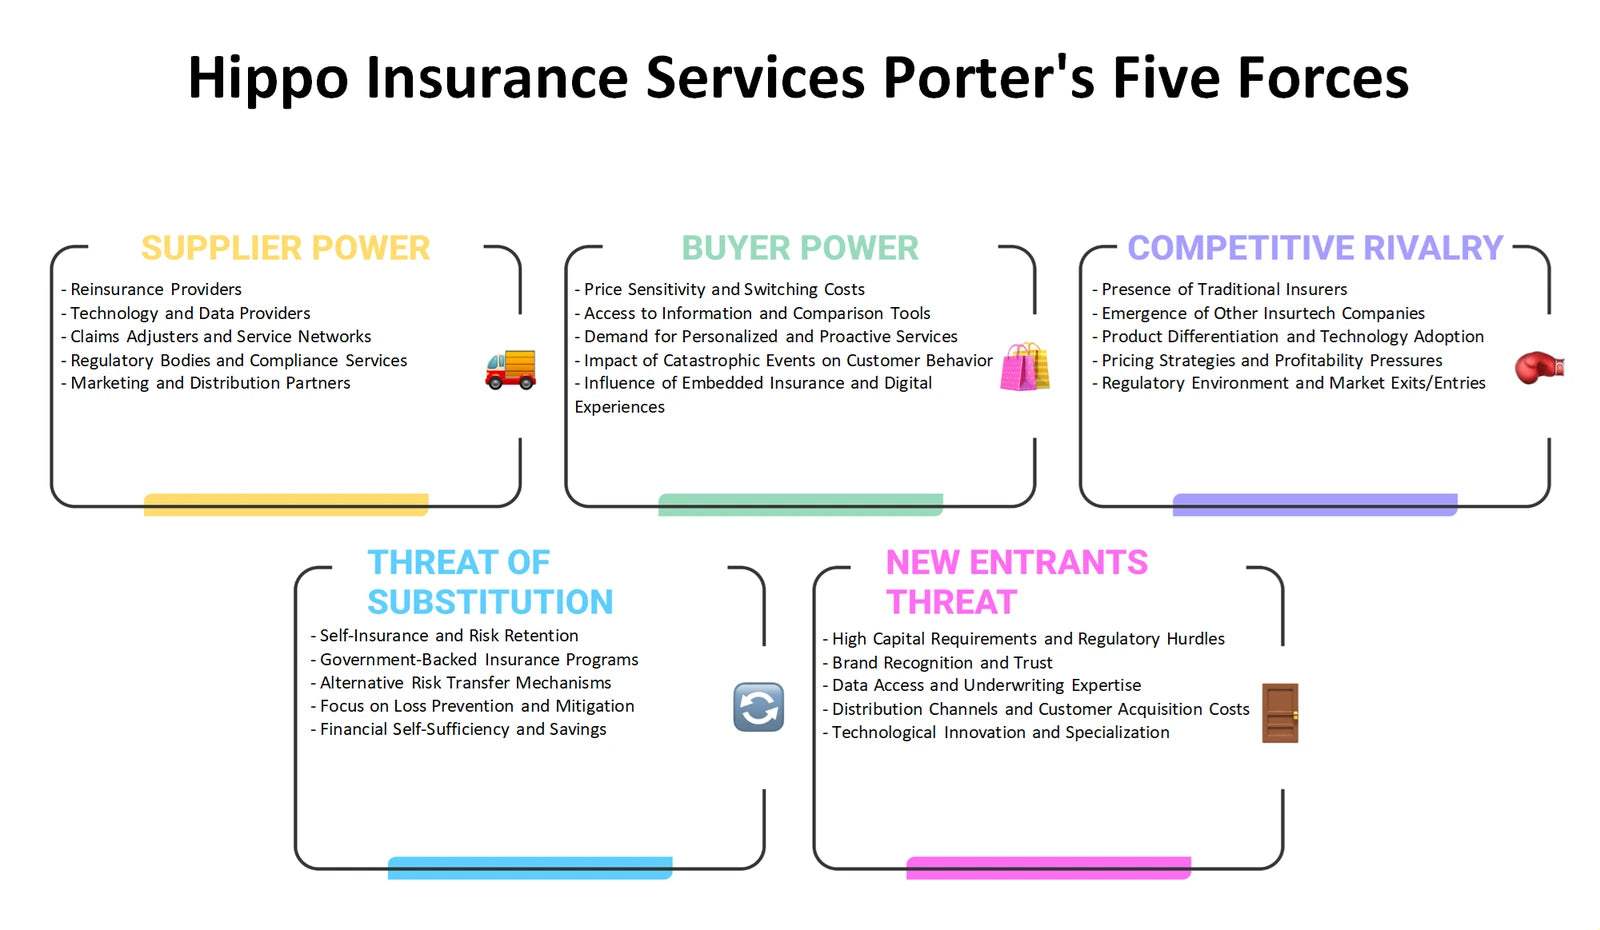
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should Product, Price, Place and Promotion work together when insurance purchase decisions involve risk, regulation and trust?
The Hippo Insurance Services Marketing Mix considers the 4Ps in a regulated service setting. Product analysis can examine the insurance proposition alongside digital underwriting and smart-home-related experiences described in the supplied context. Price is not simply a marketing message: it can be evaluated as a reflection of risk selection, coverage design, capacity costs and customer affordability, without inventing policy prices. Place focuses on the routes through which customers may encounter and obtain the offering, including broker partnerships and digital journeys. Promotion can then be assessed for how it communicates protection, convenience and confidence without overstating what an insurance policy provides.
- Product clarity. Test whether the customer proposition translates complex property-risk protection into understandable benefits and service expectations.
- Channel fit. Compare direct digital touchpoints with broker-supported routes, considering where advice, trust and efficient acquisition matter most.
- Message planning. Structure the Excel 4Ps view around customer decisions, then use the Word analysis to develop reasoned discussion points for each element.
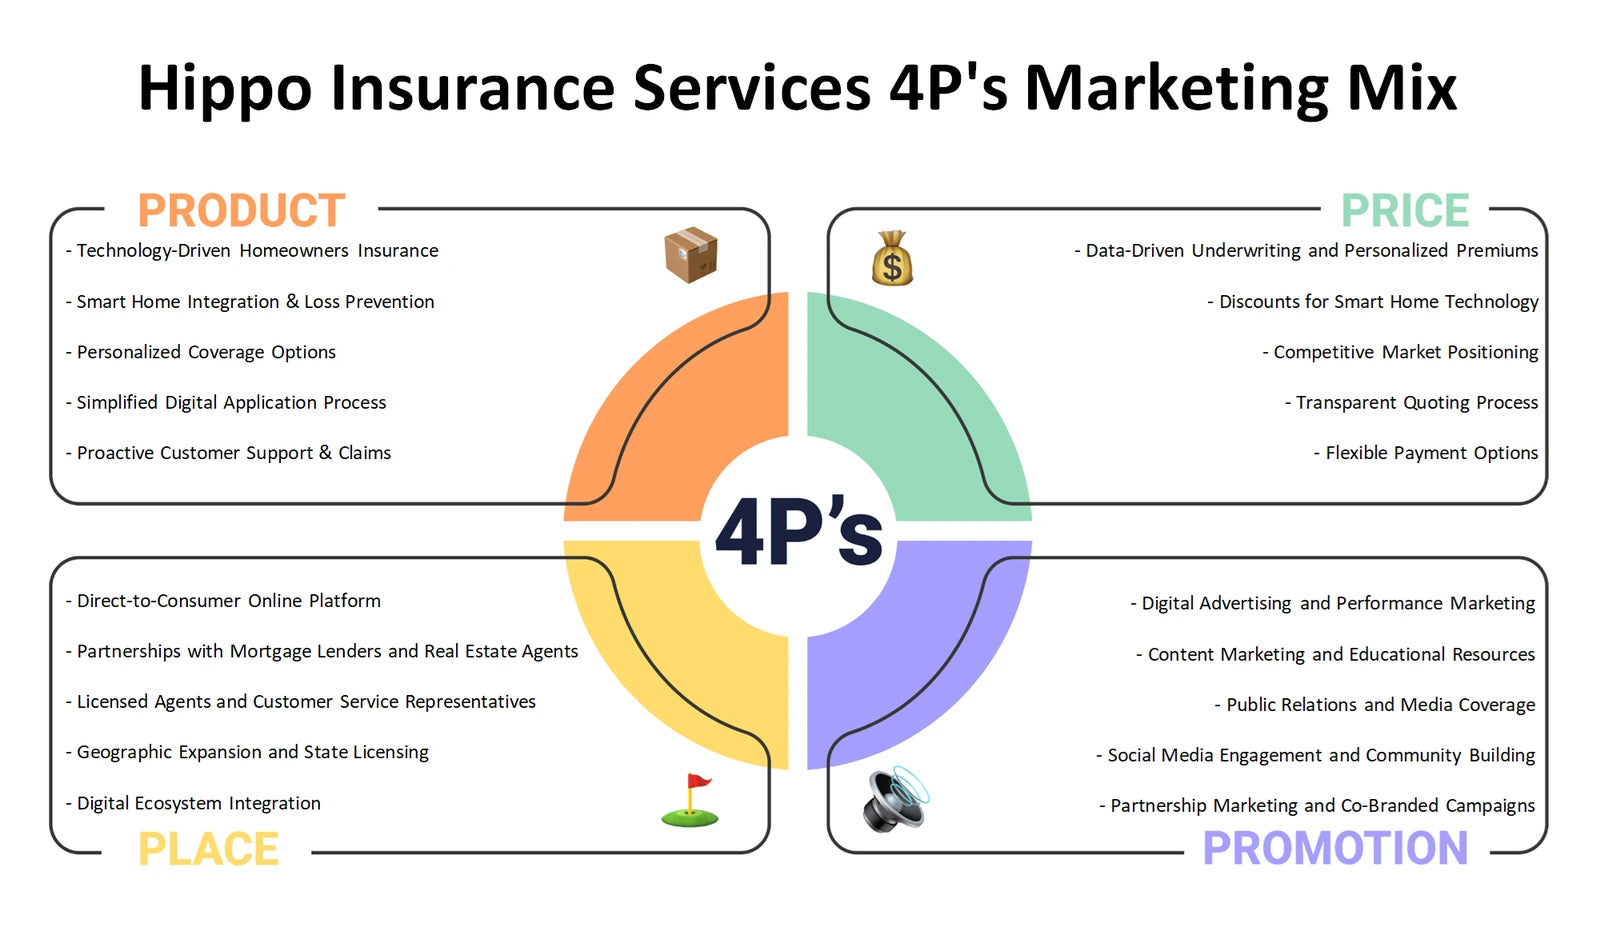
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape property-risk assumptions, insurance demand, distribution conditions and operating requirements?
A Hippo Insurance Services PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. This matters in property insurance because external conditions can change both customer needs and the cost or feasibility of serving them. Political and legal questions may concern insurance oversight, consumer protection or state-level operating requirements; they should be investigated rather than treated as documented changes. Economic factors can affect household budgets and rebuilding costs. Social expectations may elevate ease, transparency and responsive claims support. Technology can improve property insight while raising data-governance questions, and environmental conditions can affect weather-related loss exposure and portfolio concentration.
- External signals. Separate broad trends from company-specific facts so that scenario discussions do not become unsupported claims about current regulation or rates.
- Risk interdependence. Explore how climate-related property exposure, repair-cost conditions and insurance availability can interact rather than occur in isolation.
- Scenario record. Use the Excel framework to log drivers and potential implications, while the Word analysis helps frame questions for monitoring and review.
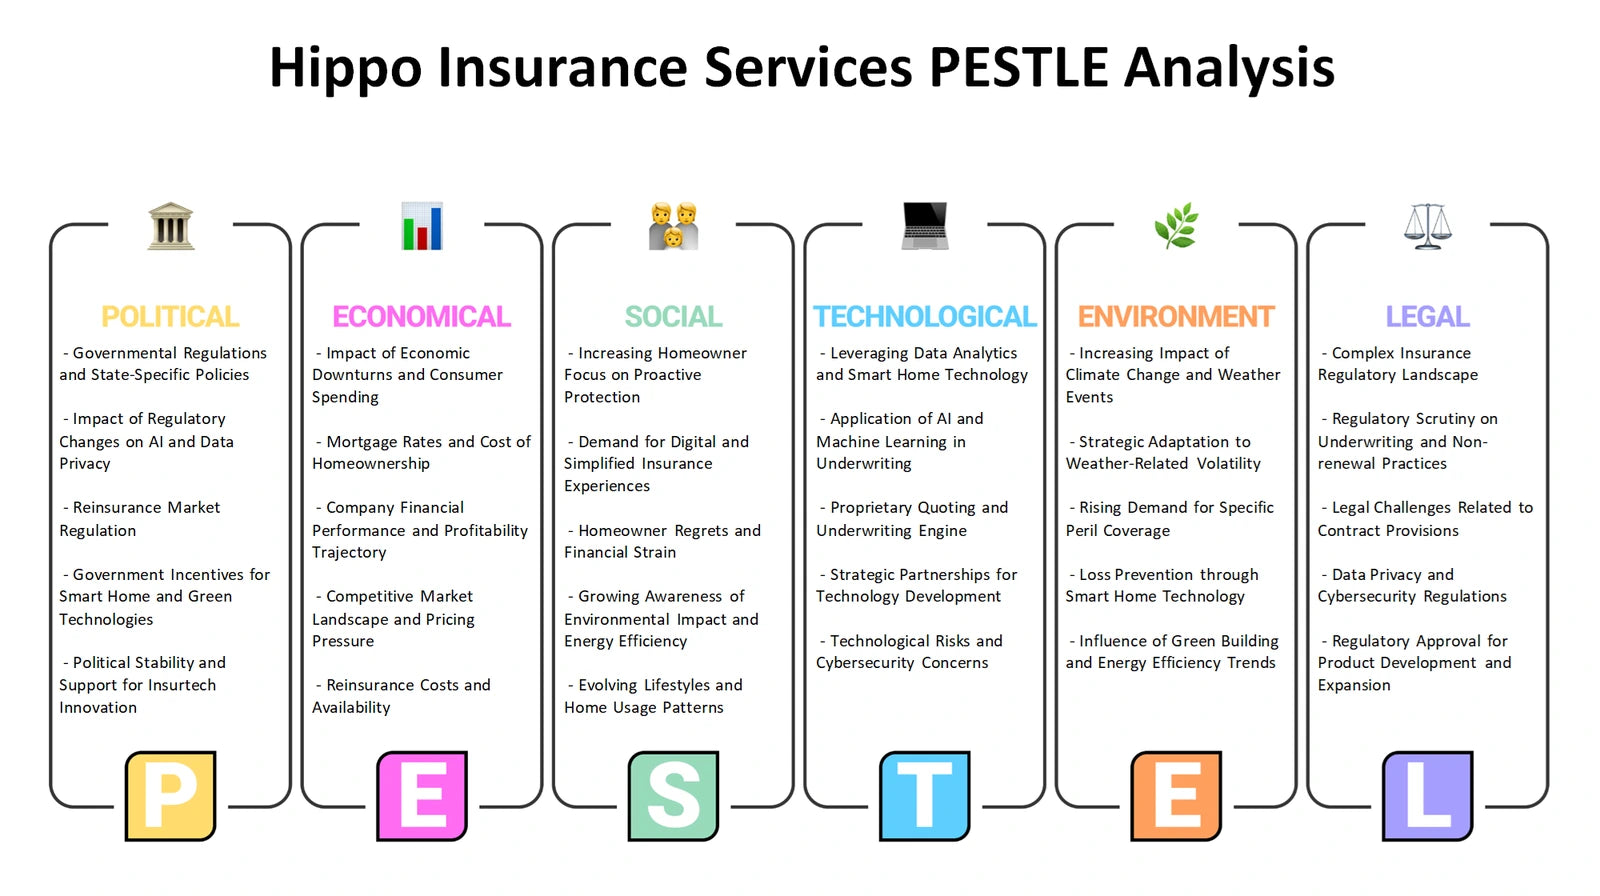
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities and constraints be considered alongside external openings and threats in a changing property-insurance market?
The Hippo Insurance Services SWOT analysis keeps internal and external factors distinct. Strengths and weaknesses concern capabilities or limitations within the business model, such as the possible usefulness of digital underwriting processes, property-data integration, partner coordination or operational complexity. Opportunities and threats arise outside the organisation, including shifts in customer expectations, risk-capacity conditions, environmental exposure and competitive pressure. The supplied context suggests relevant themes for examination, but it does not establish that any theme is a proven strength, weakness, opportunity or threat. This distinction makes SWOT useful as a synthesis tool after the portfolio, model, market, marketing and macro-environment lenses have been considered.
- Internal reality. Assess whether data, underwriting workflows, partner relationships and service design create repeatable advantages or execution dependencies.
- External fit. Compare those internal considerations with changing homeowner needs, catastrophe conditions and industry constraints.
- Priority synthesis. Use the Excel grid to separate evidence from assumptions, then use the Word analysis to turn the most important intersections into discussion priorities.
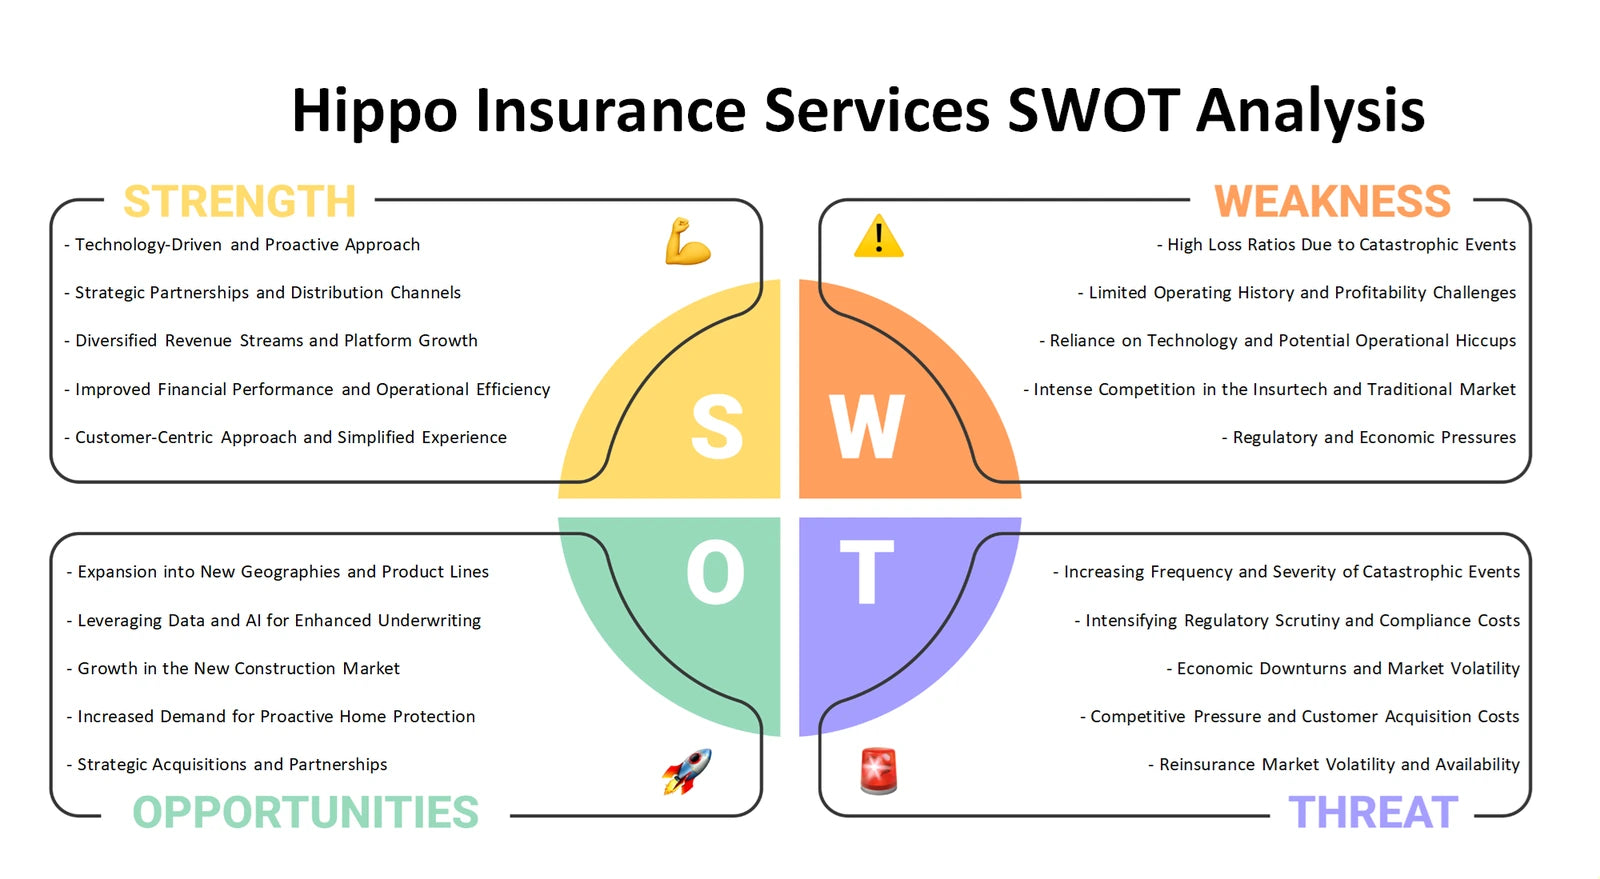
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the operating model
Viewed together, the six perspectives move from portfolio allocation and value creation to industry pressure, customer-facing choices, external change and strategic synthesis. The materials can help customers build a more structured discussion around Hippo Insurance Services: what to compare, which dependencies to test and where assumptions about underwriting, partnerships, customer experience and property risk need stronger evidence. The Excel frameworks provide organised working spaces, while the Word files provide detailed company-analysis context for interpreting the questions behind each framework.
Company background: Hippo Insurance Services — supplied product-context page.