

Heritage Insurance Holdings: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Heritage Insurance Holdings Strategy Analysis Bundle
Heritage Insurance Holdings is addressed here as Heritage Insurance Holdings, Inc., the SEC registrant classified in fire, marine and casualty insurance. The supplied business context places its underwriting in Florida and other coastal, hurricane-exposed markets, where property-insurance customers need coverage that can remain viable through severe-weather volatility. This makes risk selection, distribution, capital and risk transfer more consequential than in a generic insurance-business analysis.
In its 10-Q filed August 7, 2026, Heritage Insurance Holdings, Inc. reported revenue of USD 214.195 million and GAAP net income of USD 61.710 million for April 1 through June 30, 2026. Those quarterly figures raise practical questions about market priorities, reinsurance economics and customer access. They provide dated company context only; they do not indicate that the downloadable analysis files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which product-market priorities merit capital, management attention and catastrophe capacity?
A Heritage Insurance Holdings BCG Matrix helps separate portfolio questions from headline financial performance. It uses market growth and relative market share to examine possible product, state or distribution priorities through the familiar Stars, Cash Cows, Question Marks and Dogs categories. For a coastal insurer, the useful discussion is not a presumed quadrant assignment; it is whether growth opportunities can be supported by underwriting discipline, reinsurance availability and capital resilience.
- Portfolio lens. Compare possible markets or offerings by growth conditions and relative competitive position without inventing market-share conclusions.
- Capacity discipline. Relate expansion choices to catastrophe exposure, premium quality and the practical cost of risk transfer.
- Planning workflow. Use the Excel framework to test category assumptions, then use the Word analysis to document the evidence and priority rationale.
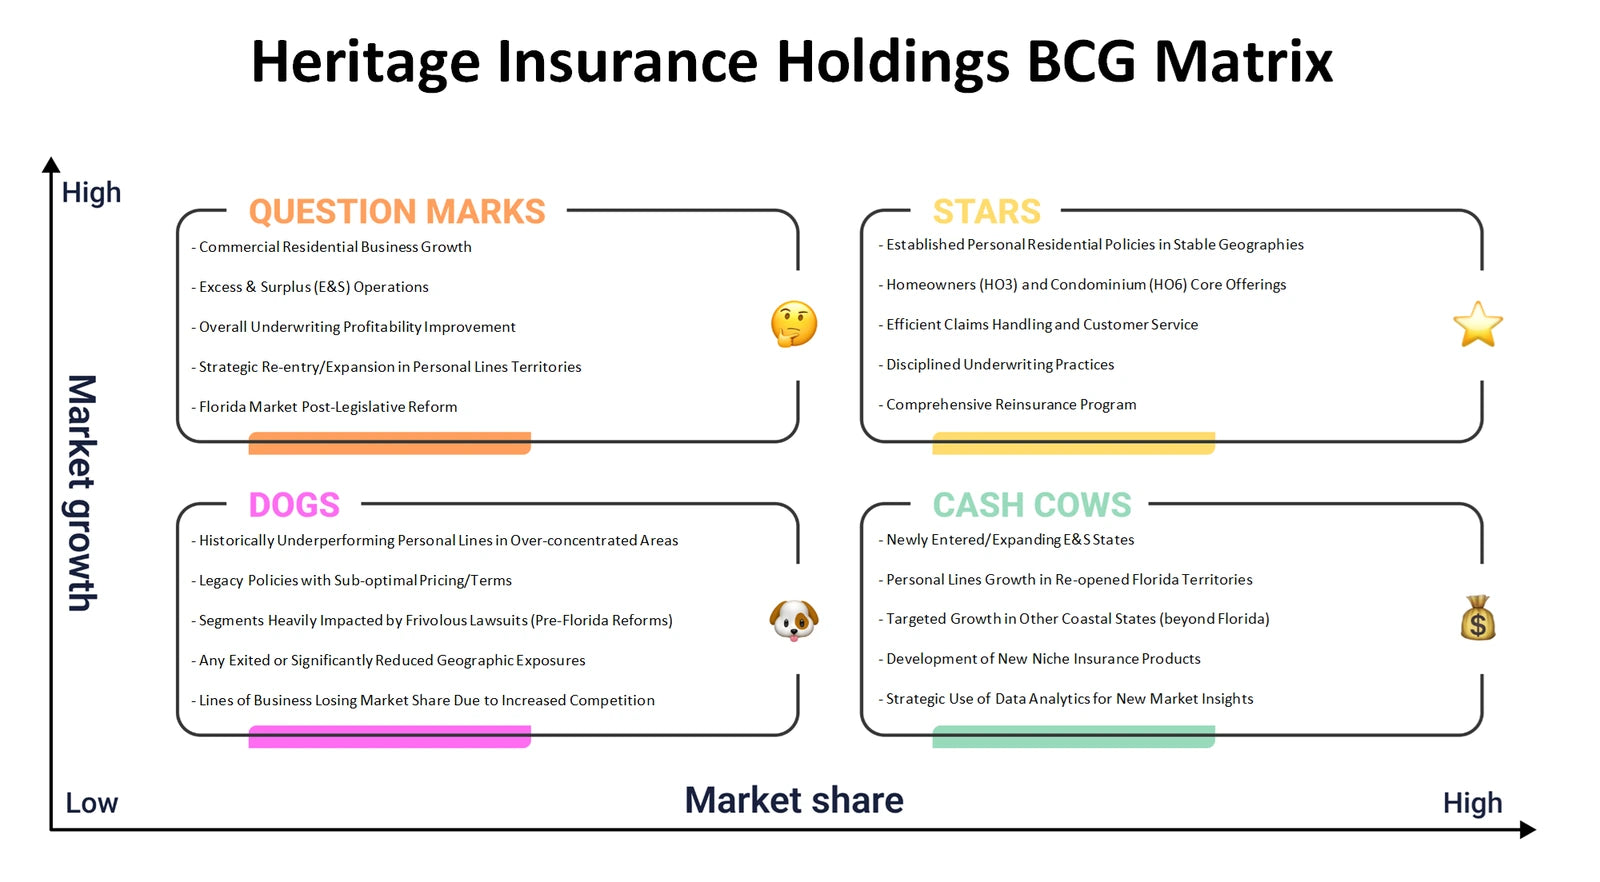
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer access, underwriting delivery and risk-transfer economics connect in one operating model?
The Heritage Insurance Holdings Business Model Canvas brings together customer segments, value propositions, channels, customer relationships and revenue streams with the operating side of the business. It also connects key resources, key activities, key partnerships and cost structure. For a property insurer exposed to major storms, this is useful for examining how policyholders are served, how premiums are earned, and how underwriting, claims handling, licensing, reinsurance and operating costs need to work together.
- Customer-value fit. Examine which customer needs, coverage propositions and relationship expectations should be considered across coastal insurance markets.
- Economic connections. Trace how premium revenue, claims obligations, partnership dependencies and expense pressures affect the model as a whole.
- Model alignment. Populate the Excel canvas as a shared map and use the Word analysis to explore links, tensions and assumptions behind each block.
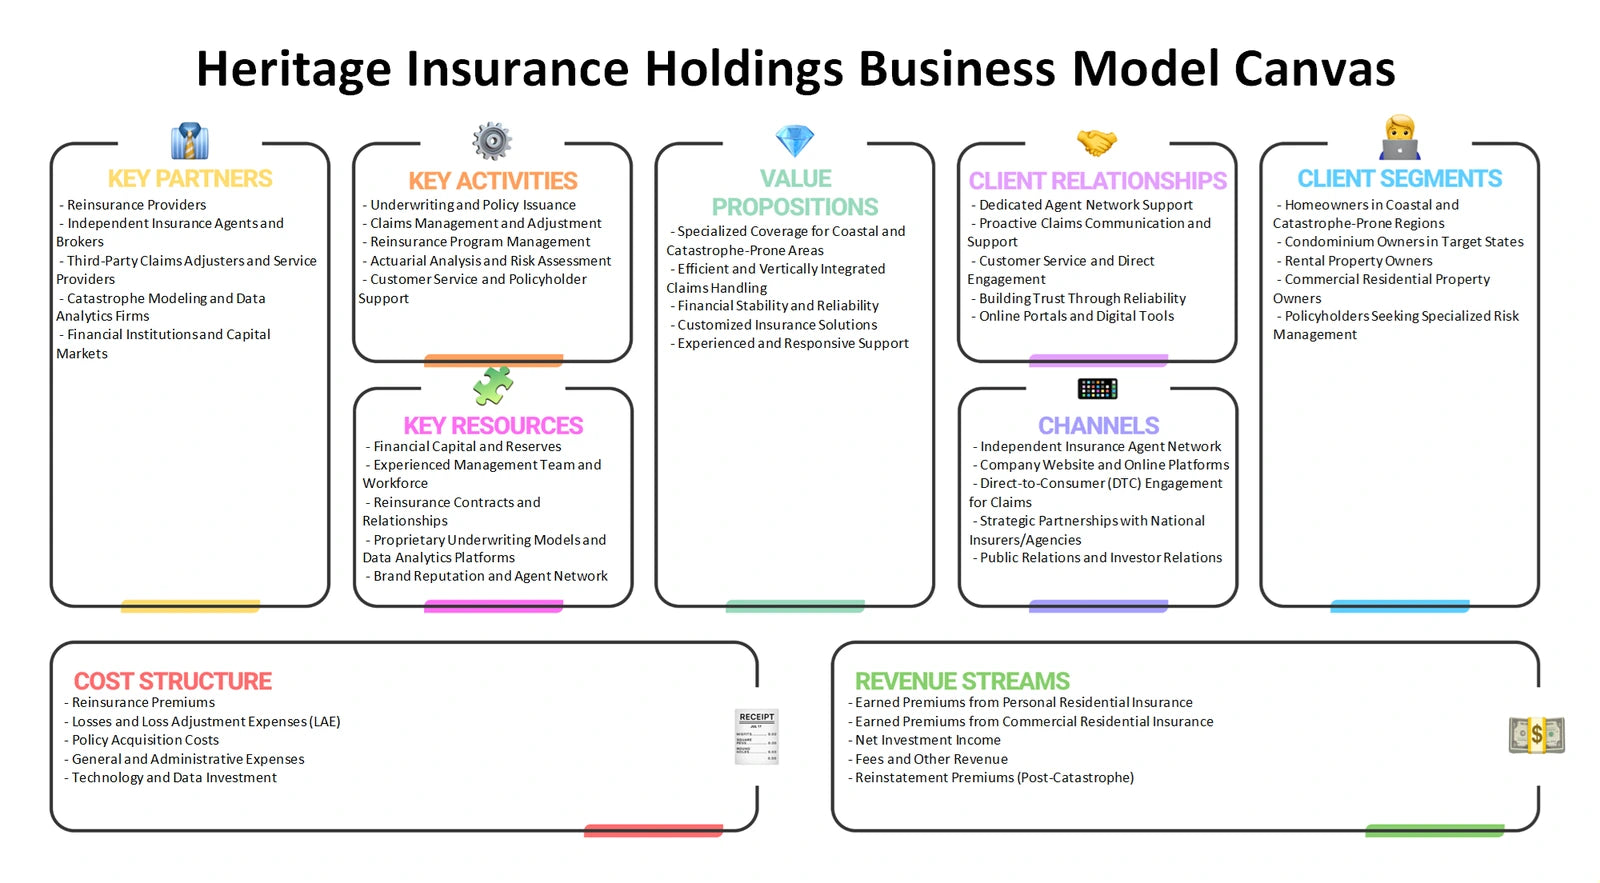
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape underwriting margins and strategic room to manoeuvre?
Heritage Insurance Holdings Porter's Five Forces analysis frames the property-insurance environment around rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes. Supplier power is especially relevant where reinsurers, catastrophe-capital providers, claims services and data capabilities influence capacity or cost. Buyer power can reflect policyholder choice and intermediary influence, while entry barriers may include regulation, capital and catastrophe expertise. Substitutes can include retaining more risk or using alternative ways to manage property-loss exposure.
- Rivalry context. Consider how competition for acceptable risks can affect pricing discipline and service expectations without assigning force scores.
- Reinsurance dependence. Assess how counterparties and renewal conditions may influence underwriting appetite after severe loss events.
- Evidence trail. Use Excel to organize the five pressures and the Word analysis to record the business implications behind each assessment.
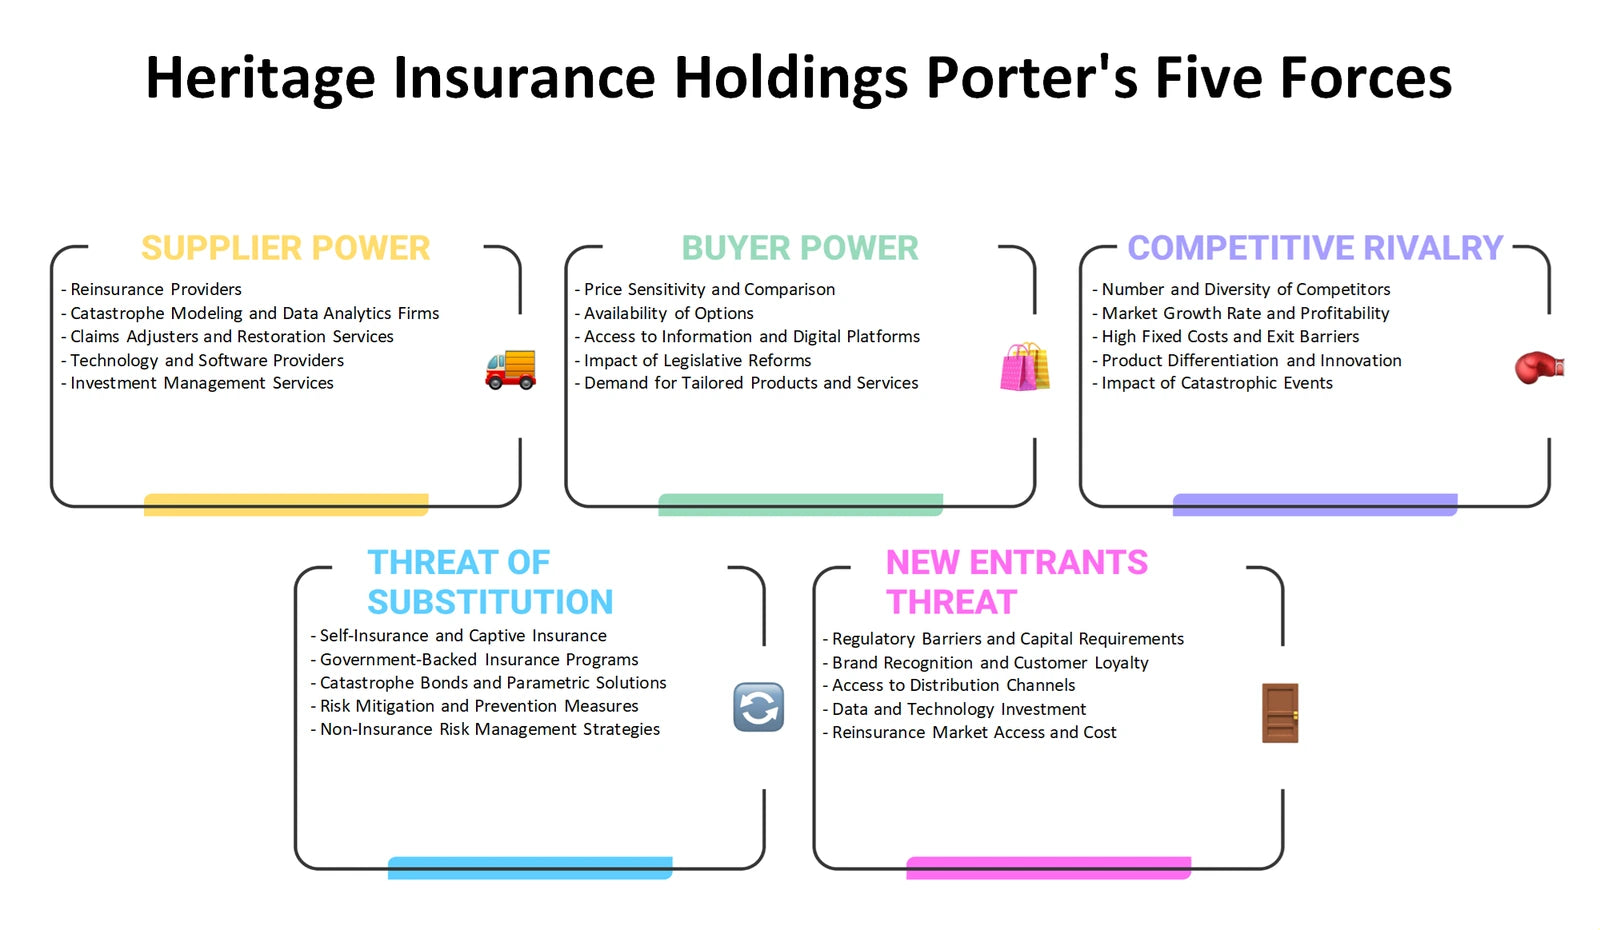
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should coverage design, premium logic, route to market and communications reinforce one another?
A Heritage Insurance Holdings Marketing Mix considers Product, Price, Place and Promotion in a regulated insurance setting. Product analysis can examine coverage, policy service and claims-related expectations. Price focuses on premium logic relative to expected losses, expenses, reinsurance and permitted rating practices rather than on invented price points. Place considers agency, digital or other compliant customer routes, while Promotion tests whether communications explain value, limitations and preparedness clearly to households facing property-risk decisions.
- Offering clarity. Review how insurance propositions can be assessed against customer needs, protection expectations and underwriting boundaries.
- Channel choices. Compare the role that distribution routes and intermediary relationships may play in access, service and acquisition cost.
- Decision support. Organize 4Ps observations in Excel, then use the Word analysis to turn the comparisons into a focused marketing discussion.
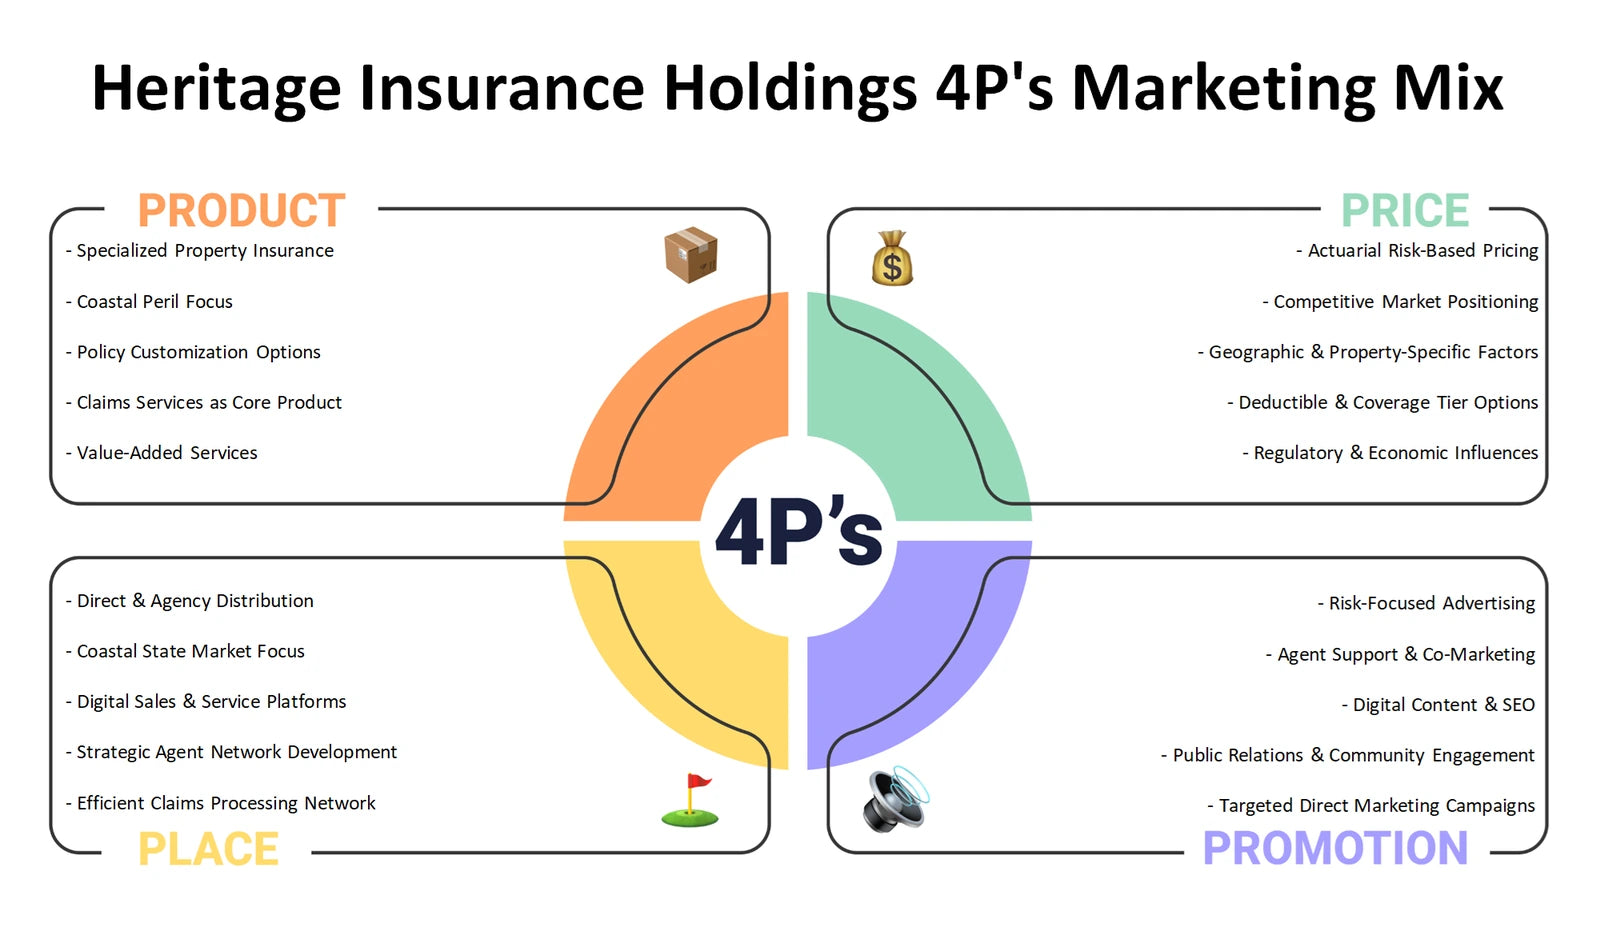
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external shifts could alter the conditions for writing and servicing catastrophe-exposed insurance?
A Heritage Insurance Holdings PESTLE analysis, also commonly called PESTEL, organizes the external conditions surrounding its business. Political considerations can include state insurance-policy priorities; Economic factors may affect repair costs, household affordability and capital conditions. Social patterns can influence migration and protection expectations. Technological change matters for underwriting data and claims processes, while Legal factors include regulation, forms and market conduct. Environmental exposure is central because weather-related losses can reshape capacity and risk concentration.
- External scan. Separate documented conditions from questions to monitor, rather than treating possible policy or economic changes as established facts.
- Catastrophe relevance. Connect environmental risk to the wider legal, economic and social pressures that influence insurance availability.
- Monitoring map. Use the Excel framework to categorize signals and the Word analysis to explain why selected external factors matter strategically.
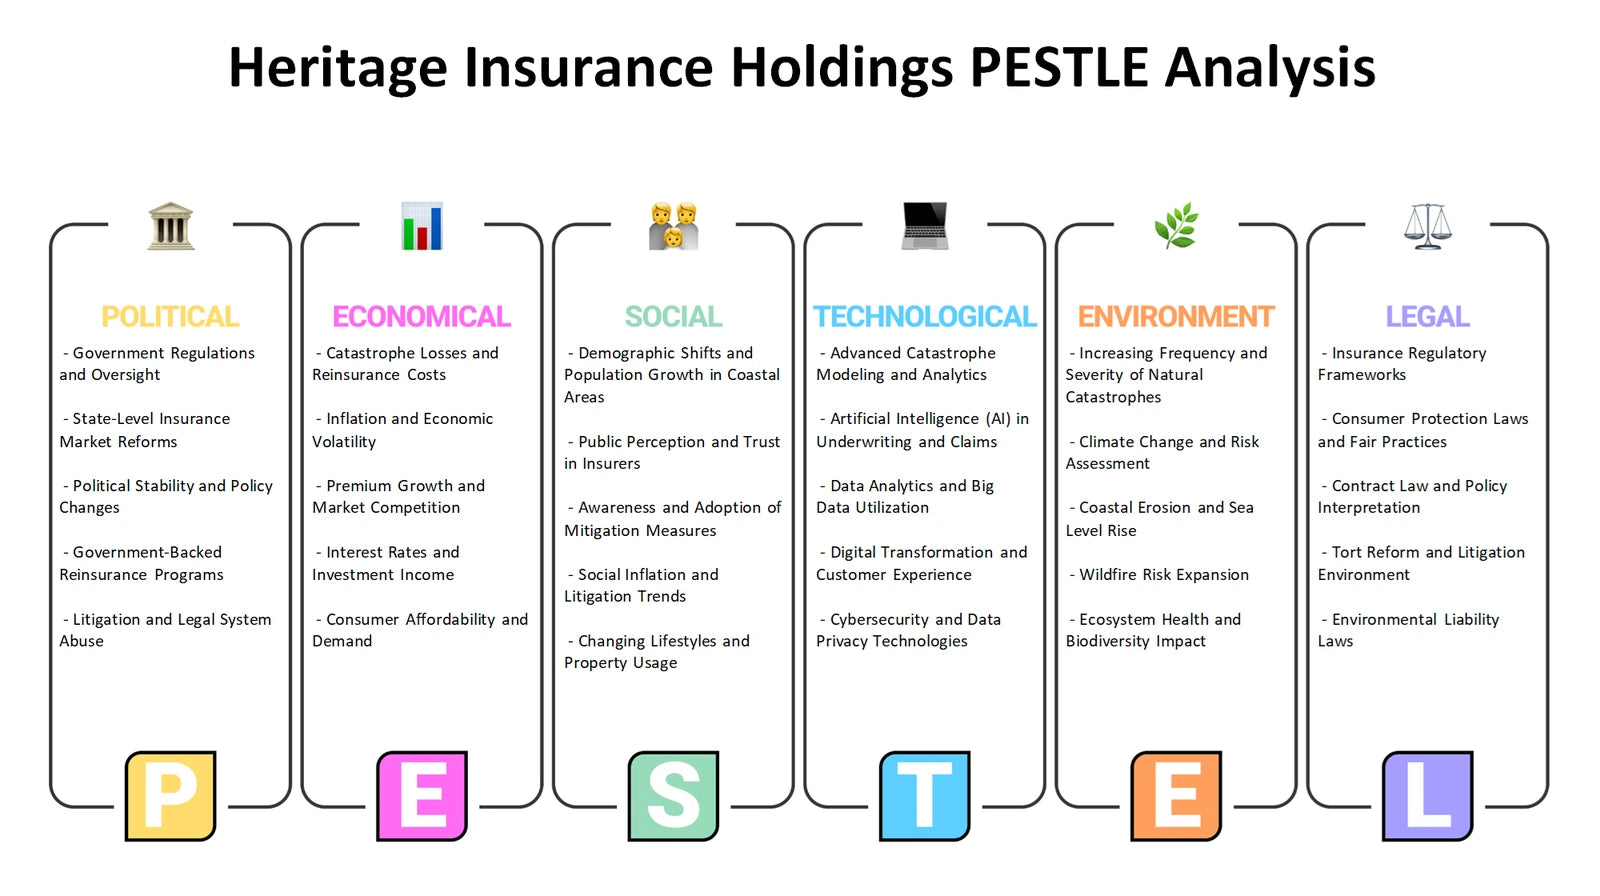
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities and constraints be considered alongside coastal-market opportunities and threats?
The Heritage Insurance Holdings SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. It can help assess capabilities such as underwriting discipline, market access, capital management, operational processes and reinsurance relationships without presenting them as pre-established conclusions. It then places those internal considerations beside external opportunities in suitable markets and threats such as catastrophe losses, capacity tightening, regulation and changing customer affordability. The value is in keeping controllable issues separate from market conditions.
- Internal reality check. Identify evidence to examine when considering operational capabilities, dependencies and areas that may require reinforcement.
- External trade-offs. Compare potential market opportunities with threats that could affect resilience, profitability or customer retention.
- Action framing. Use Excel to sort observations into the four categories and the Word analysis to develop balanced strategic questions from them.
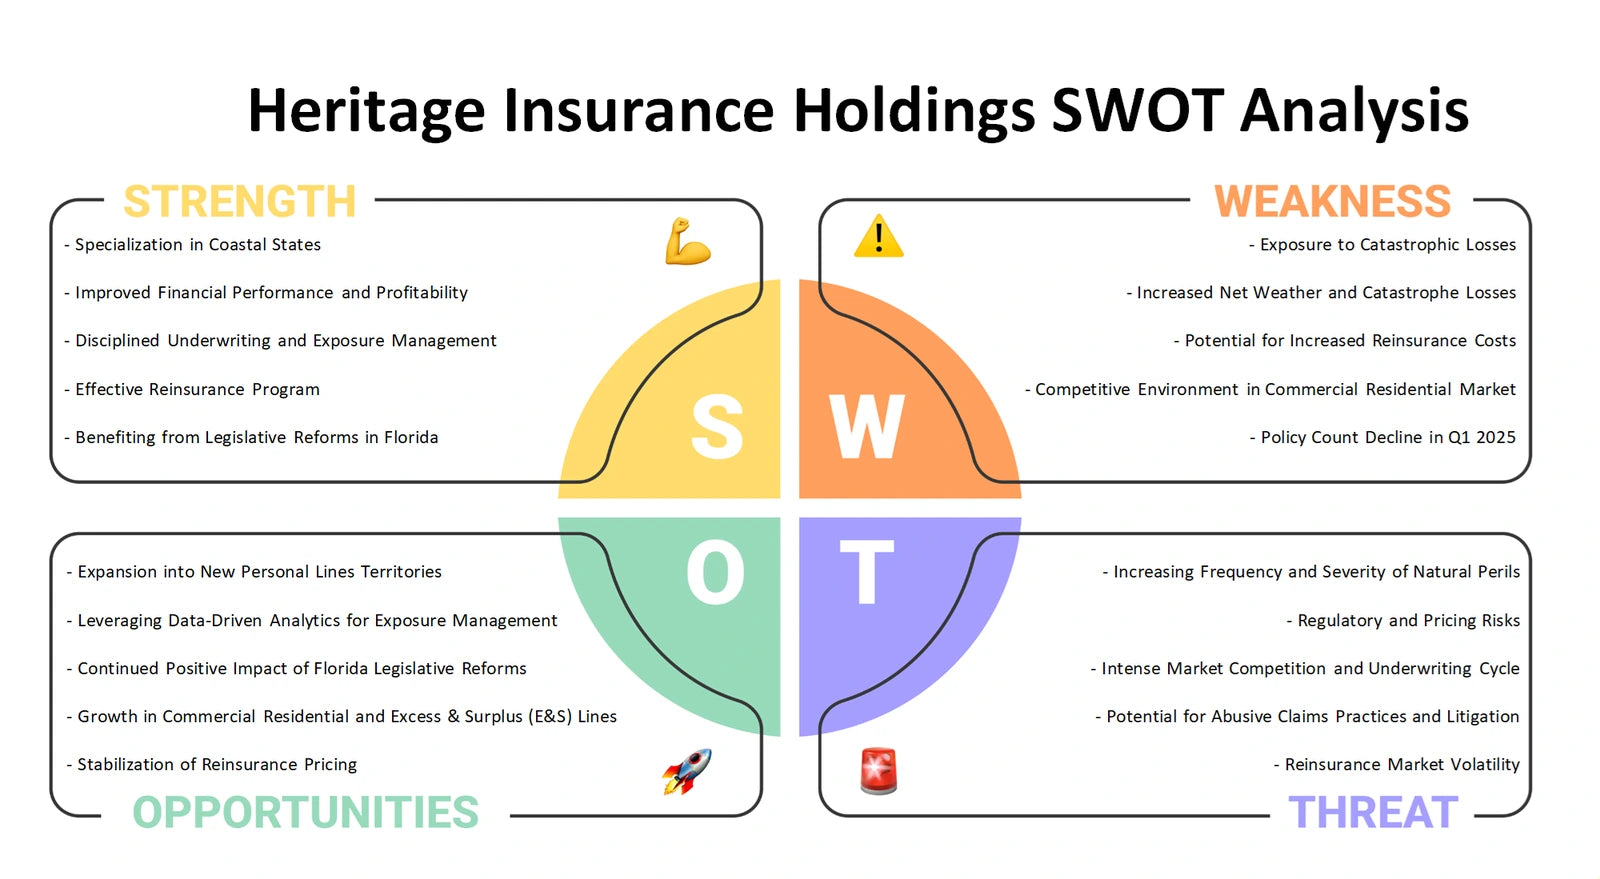
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with insurance economics
Together, the six perspectives help relate Heritage Insurance Holdings' portfolio choices to its operating model, industry pressures, customer routes, external conditions and internal readiness. The Excel frameworks provide structured places to compare assumptions, while the detailed Word analyses support fuller discussion of the strategic trade-offs relevant to catastrophe-exposed property insurance.
Company background: Heritage Insurance Holdings, Inc. — SEC company submissions profile.