

Helia Group: Underwriting and Pricing – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Helia Group Strategy Analysis Bundle
This bundle examines Helia Group in the supplied business context of an Australian lender mortgage-insurance business. Its work is centred on helping lender partners manage mortgage-credit risk through underwriting, policy assessment, claims handling, recoveries and portfolio insight. Reinsurance capacity, specialist actuarial judgement and lender relationships are therefore relevant commercial considerations, rather than generic insurance-industry talking points.
The analysis materials help turn that operating model into structured strategic questions: where should resources be concentrated across lender-facing propositions, how do underwriting and claims activities create economic value, and which external changes could affect demand, pricing and capital requirements? The six perspectives distinguish matters to investigate from conclusions that would require company-specific evidence.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lender-policy propositions merit priority when market growth and relative market share point in different directions?
A Helia Group BCG Matrix helps examine the portfolio choices behind a lender mortgage-insurance model. Rather than assuming that every lender relationship, loan cohort or adjacent service has the same strategic value, the framework compares market growth with relative market share. It then provides a disciplined language for considering Stars, Cash Cows, Question Marks and Dogs. For Helia Group, useful questions may include whether resources should favour established, cash-generative relationships, growing areas requiring underwriting capacity, or propositions whose economics deserve closer review. The matrix does not assign a quadrant without evidence; it helps make the criteria behind portfolio priorities visible.
- Portfolio boundaries. Separate lender-facing insurance propositions, distribution relationships or service lines so that unlike activities are not treated as one undifferentiated business.
- Capital attention. Compare growth opportunity with relative position while considering the capital, reinsurance and specialist capability each area may require.
- Working view. Use the Excel matrix to map assumptions and options, then use the Word analysis to record the commercial rationale and evidence needed before a priority decision.
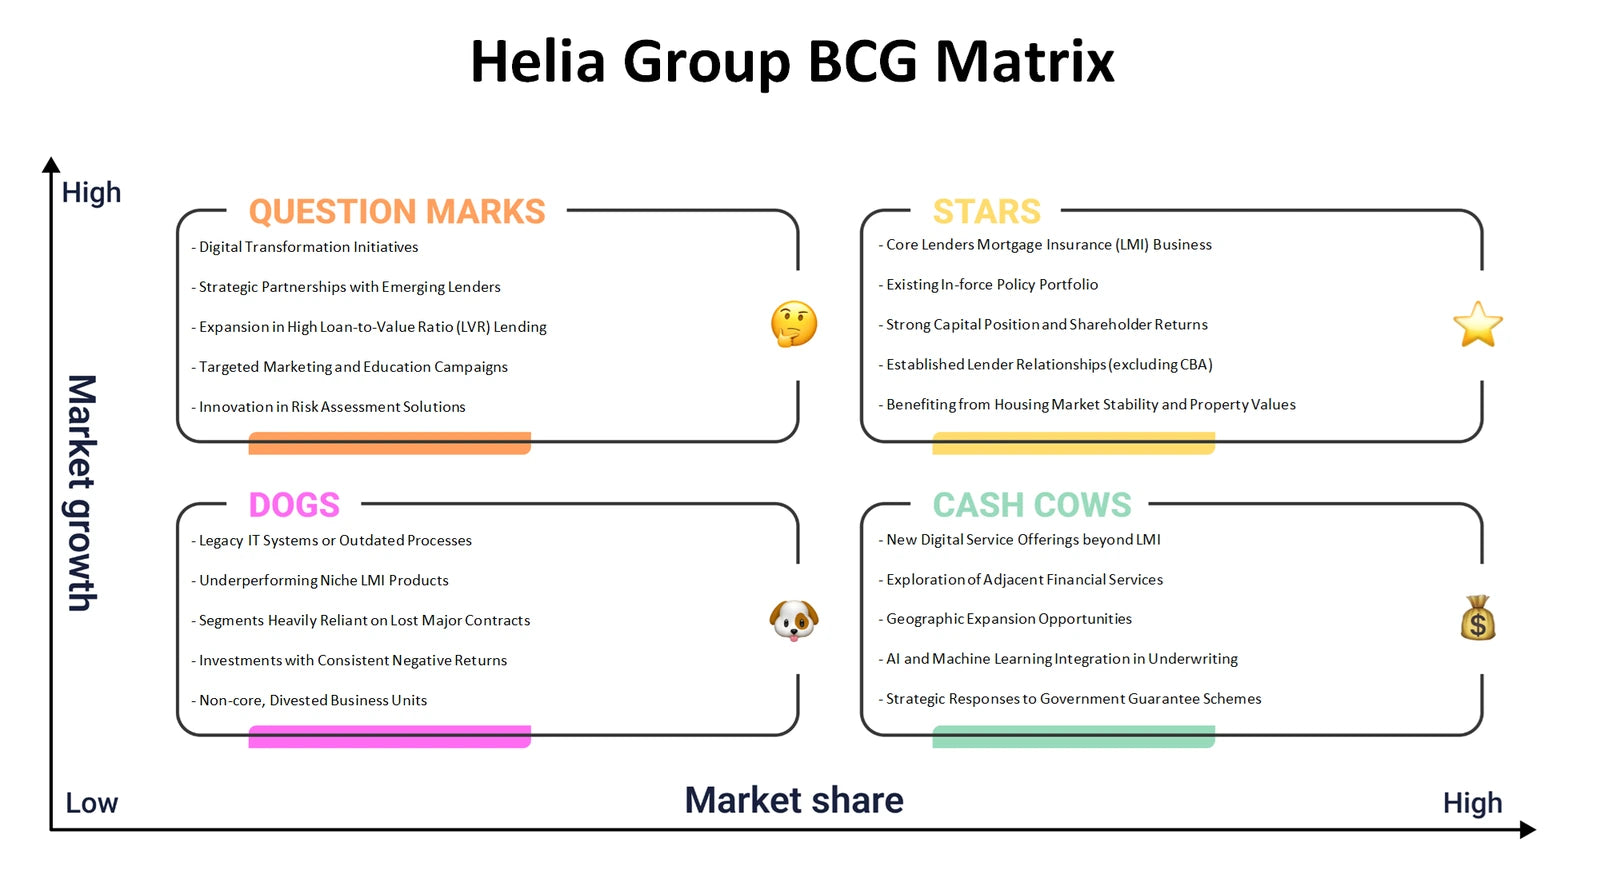
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do lender relationships, risk expertise and reinsurance support connect to a durable Helia Group value-and-revenue model?
The Helia Group Business Model Canvas connects nine building blocks that can otherwise be considered in isolation: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In this setting, lenders are the central customer segment to examine, while underwriting expertise, claims capability, actuarial judgement and recovery processes may be assessed as resources and activities that support the proposition. Reinsurers can be considered within key partnerships, and lender-network coverage within channels and relationship management. The Canvas is especially useful because risk pricing, servicing effort, capital support and claims outcomes must work together for the model to create value.
- Value exchange. Trace how support for mortgage-credit decisions and loss management may create value for lenders while requiring disciplined risk selection and policy administration.
- Economic links. Test how revenue logic relates to pricing, claims costs, operating capability, reinsurance arrangements and the wider cost structure.
- Connected evidence. Populate the Excel Canvas as a one-page operating map and use the Word analysis to add explanations, dependencies and questions for each block.
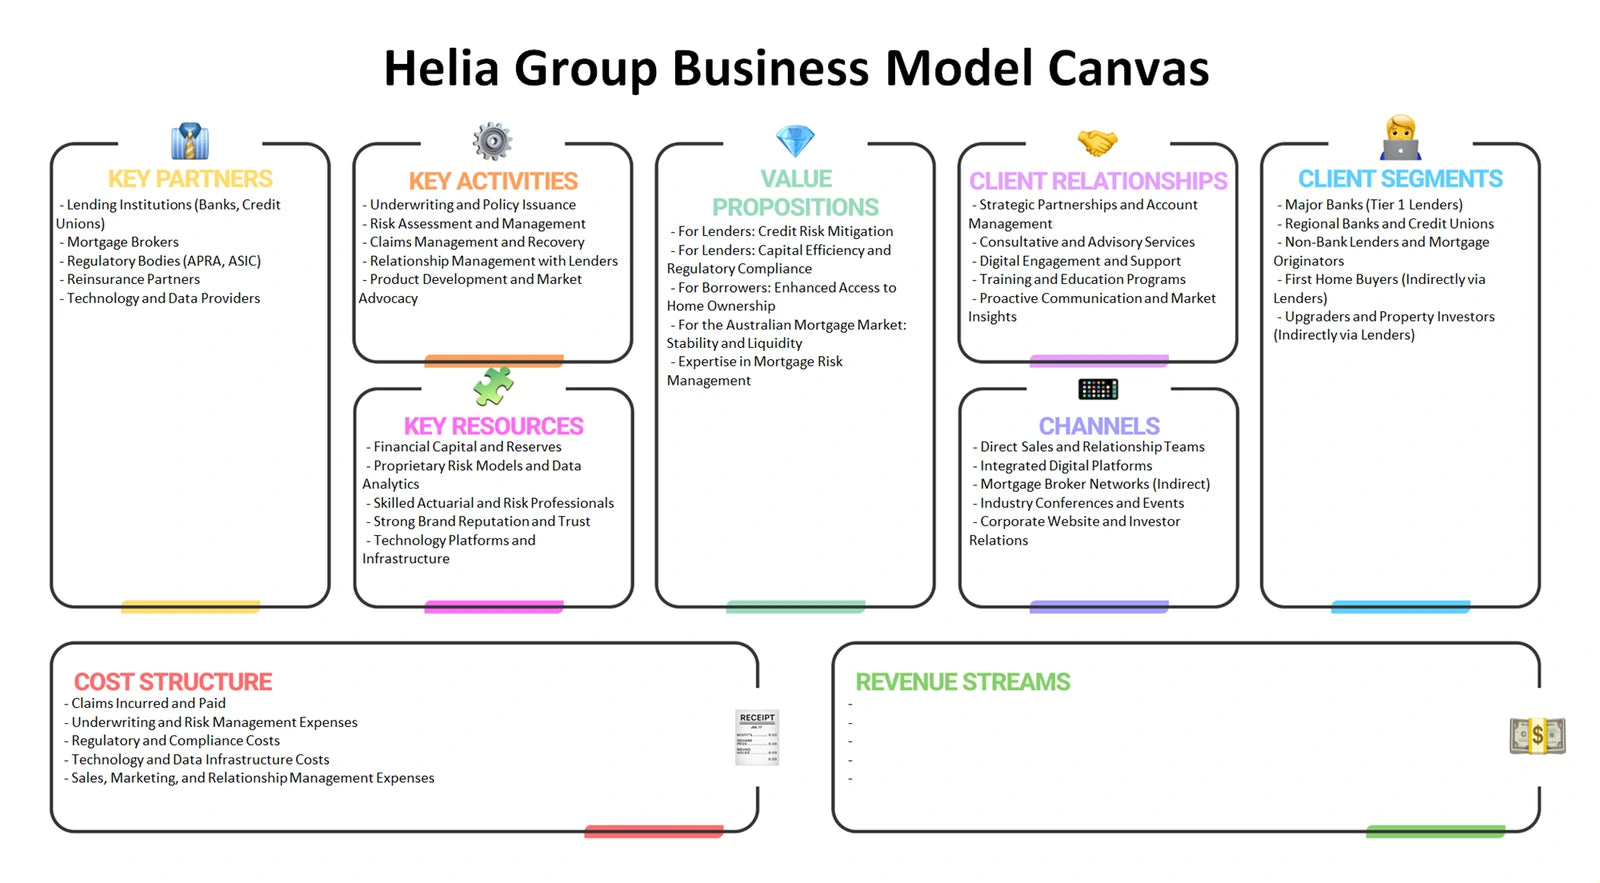
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What could shape the bargaining position and long-term attractiveness of Australia’s lender mortgage-insurance environment?
Helia Group Porter's Five Forces analysis frames industry pressure around the economics of lender mortgage insurance. Rivalry concerns competition for lender mandates and the ability to differentiate service, risk appetite and pricing discipline. Buyer power is relevant because lender customers may have meaningful scale and procurement influence. Supplier power can include the role of reinsurance capacity and specialist external support. New entrants may face actuarial, capital, regulatory and relationship barriers, while substitutes extend beyond direct insurers to other ways lenders or borrowers may manage credit risk, such as changed lending structures or alternative risk-transfer approaches. The framework helps investigate these forces without assigning unsupported force scores.
- Lender leverage. Examine how concentration, tender processes, service expectations and switching considerations may affect negotiation and retention.
- Risk-transfer access. Consider how the availability and terms of reinsurance could influence capacity, volatility management and underwriting economics.
- Scenario discipline. Use the Excel framework to compare each force and its evidence, with the Word analysis providing context for the assumptions behind potential industry pressure.
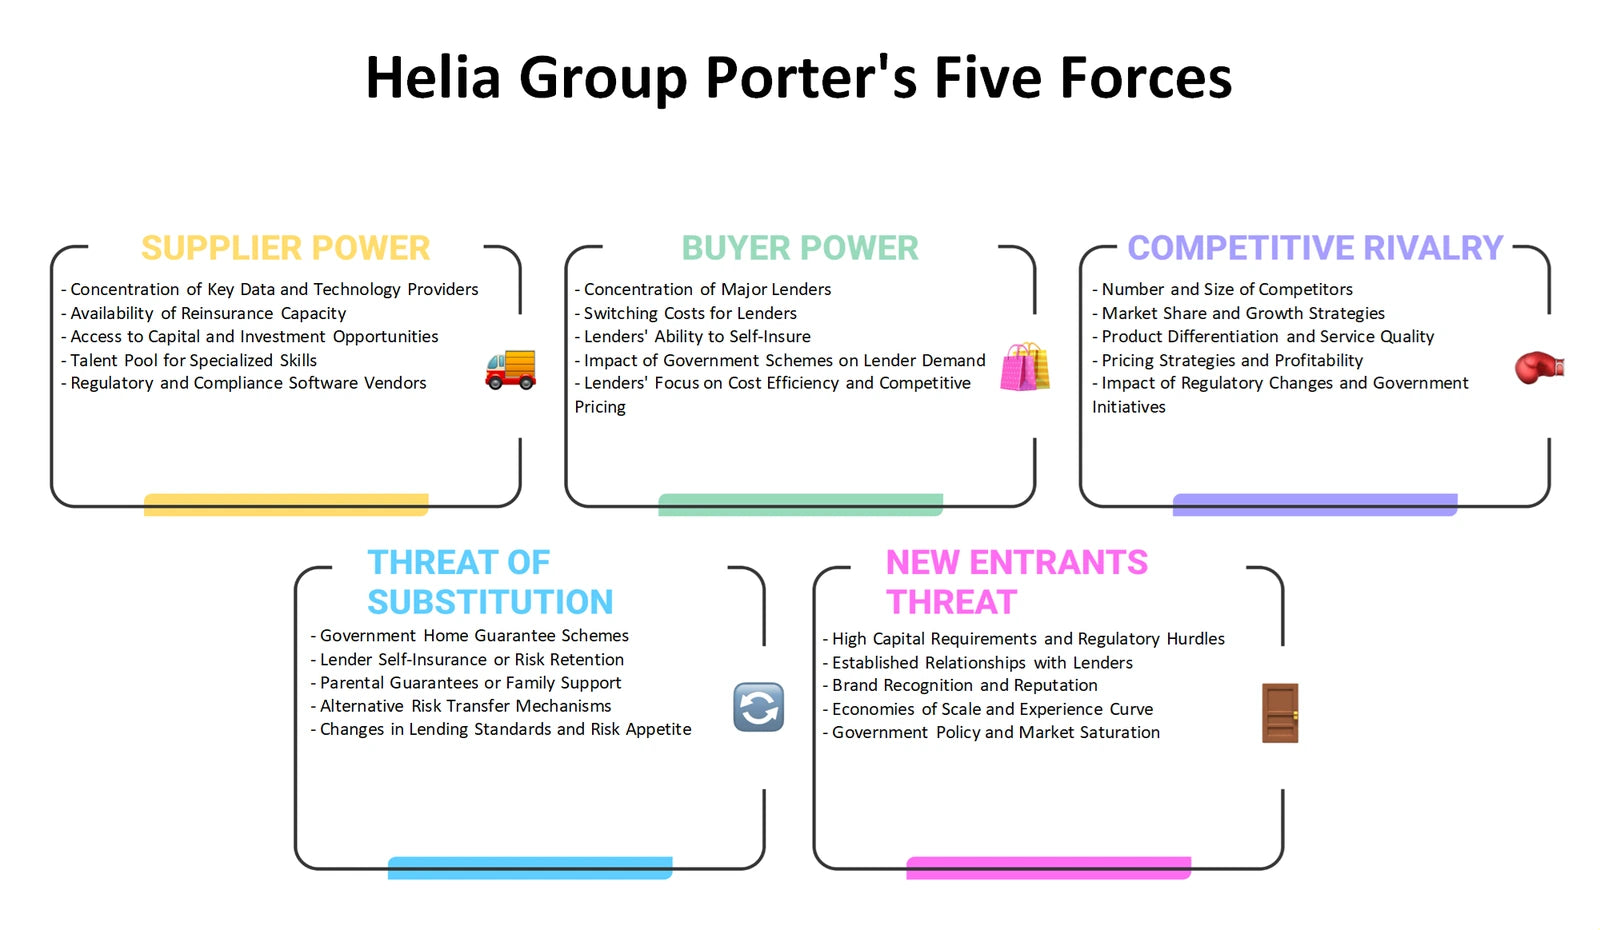
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a lender-facing mortgage-insurance proposition align its offer, pricing logic, routes to market and communication?
A Helia Group Marketing Mix applies the 4Ps to a relationship-led, regulated B2B context rather than to mass-market consumer promotion. Product can cover the insurance proposition and associated underwriting, claims and portfolio-support services that lenders evaluate. Price concerns risk-based terms and the trade-off between competitive positioning, expected losses, capital and reinsurance costs. Place focuses on how the offer reaches lender partners through account relationships, operational integration and distribution coverage. Promotion is best assessed as clear, credible communication of risk expertise, service standards and policy value to relevant decision-makers. The framework helps connect commercial messaging to the operational reality that must support it.
- Offer design. Assess which policy features, decision support and claims-service attributes matter most to lender customers and their borrower outcomes.
- Route and message. Compare relationship management, lender-network access and evidence-led communication rather than assuming a consumer advertising model.
- Go-to-market review. Use the Excel 4Ps structure to identify alignment gaps, then use the Word analysis to capture audience, proposition and pricing questions for discussion.
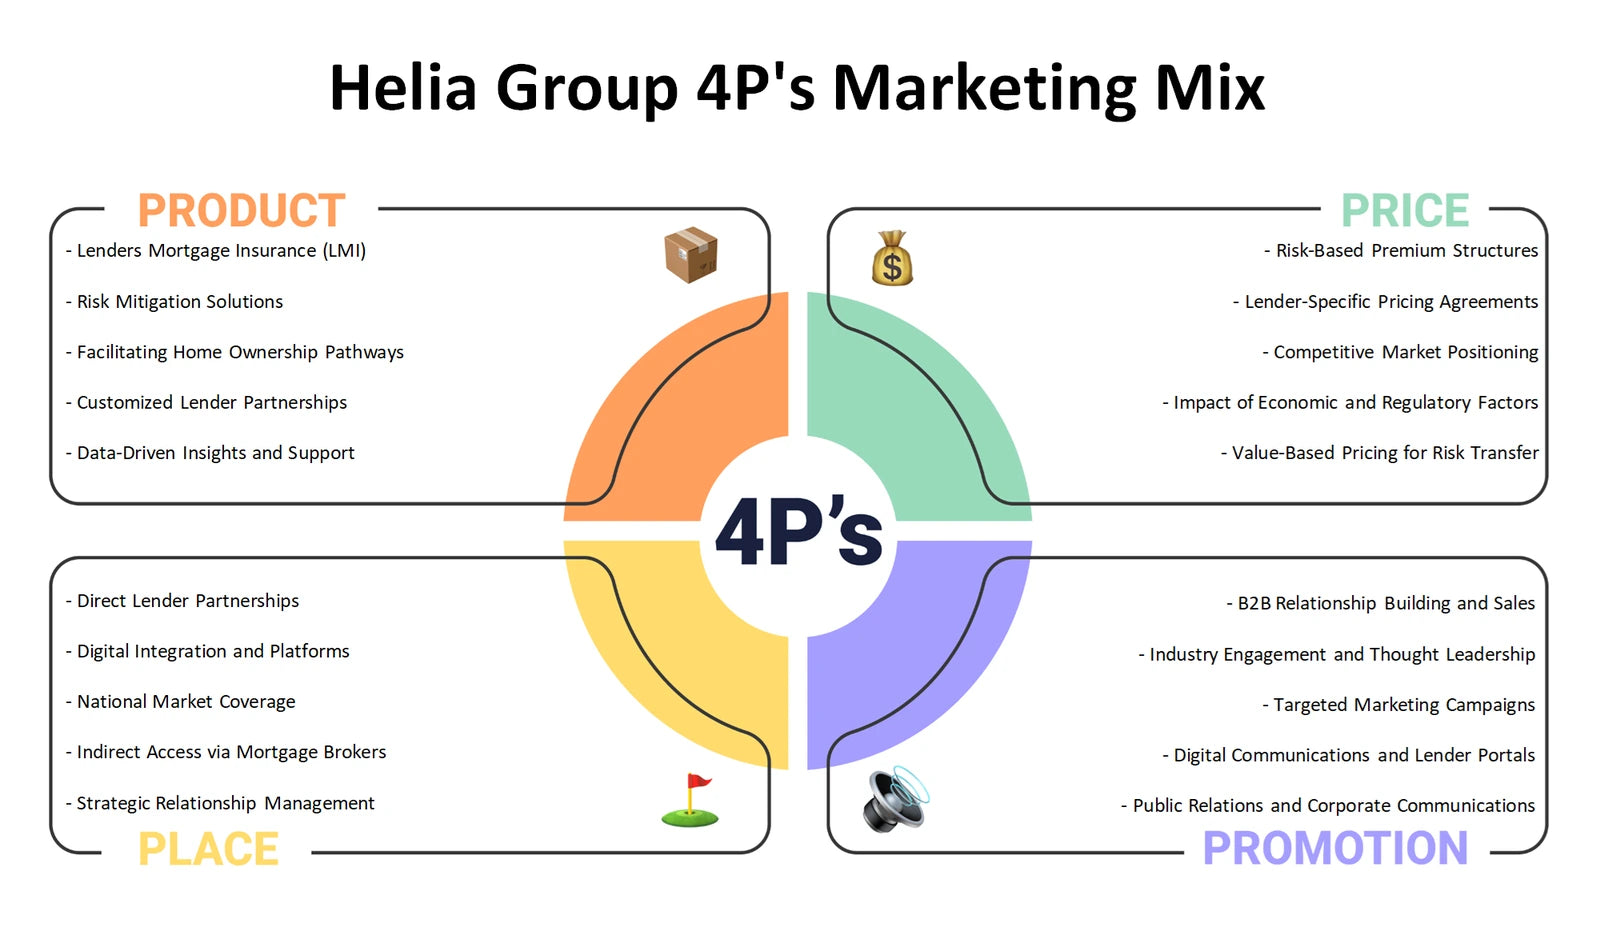
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter mortgage-credit demand, claims experience, compliance obligations or reinsurance conditions?
Helia Group PESTLE analysis, also commonly called PESTEL, separates external influences that should not be mistaken for internal operating choices. Political factors may include housing and financial-system policy settings; economic conditions can affect borrower stress, property markets, lending volumes and credit performance. Social factors include household expectations and confidence around home ownership. Technological change can reshape lender data, underwriting processes and claims operations. Legal considerations include insurance, consumer, privacy and lending-related obligations, while environmental conditions may influence property exposure and risk assessment. The framework does not claim that a particular law, rate or event has changed; it helps organise the questions that management and customers should monitor.
- Housing-cycle exposure. Explore how changing lending conditions or borrower resilience could affect demand patterns and loss assumptions.
- Regulatory horizon. Distinguish documented requirements from policy questions that may warrant scenario planning across insurance and lending activity.
- External watchlist. Use the Excel framework to sort signals by PESTLE category and the Word analysis to explain why each potential development could matter to the business model.
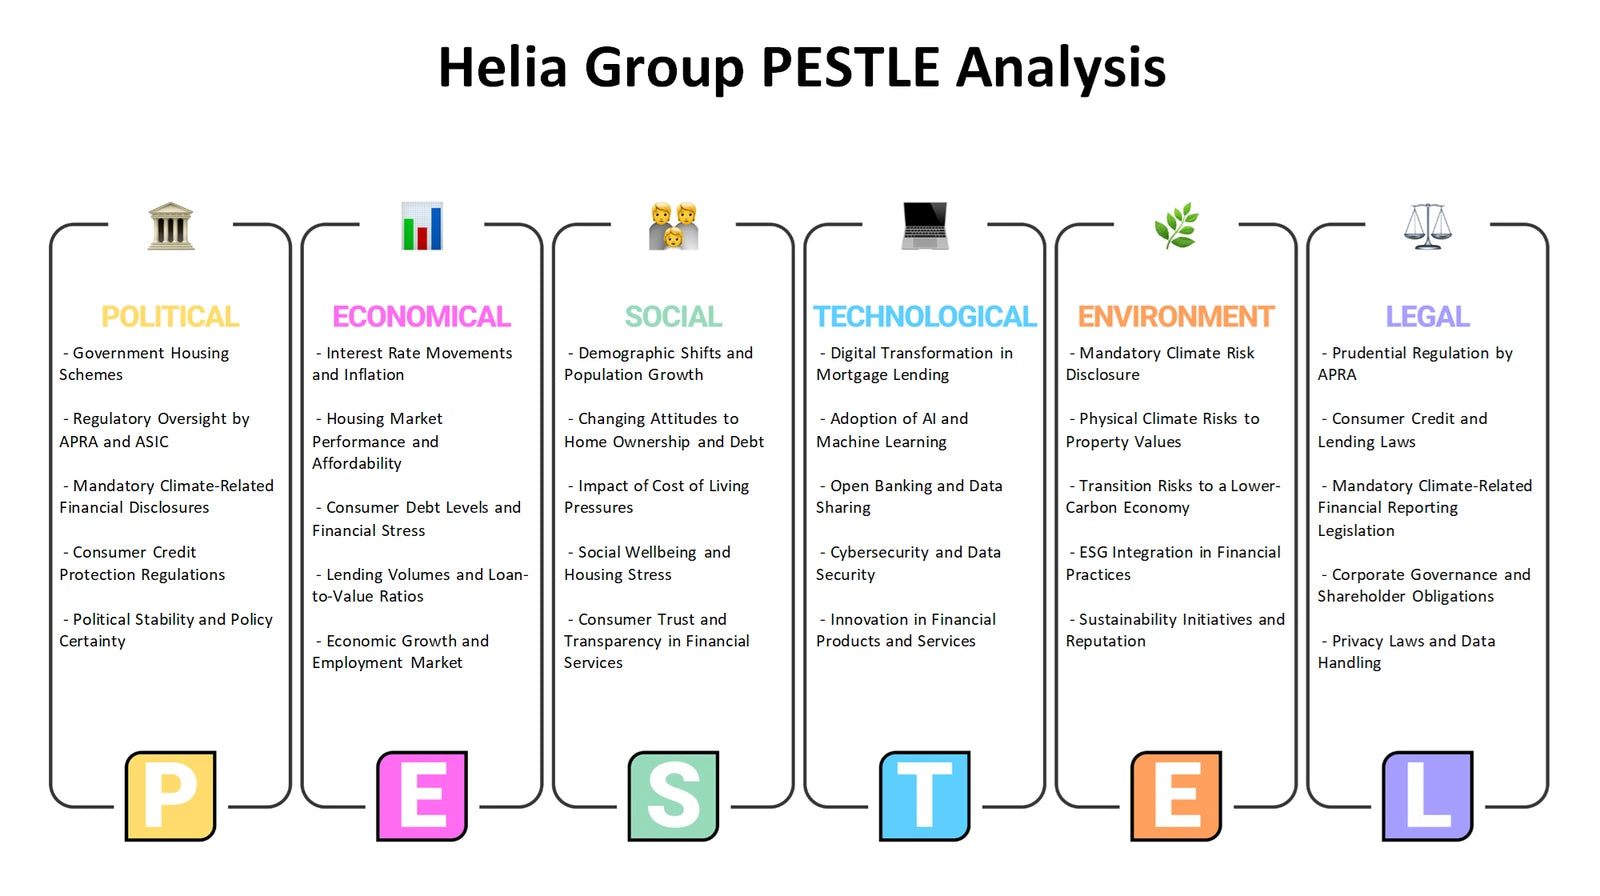
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Helia Group distinguish its internal capabilities and constraints from opportunities and threats in its external environment?
A Helia Group SWOT analysis brings the earlier lenses together while keeping classifications accurate. Strengths and weaknesses are internal: the supplied context points to areas worth examining such as lender-policy knowledge, underwriting capability, claims expertise, recovery processes, actuarial insight and relationship management. These should be tested as capabilities rather than automatically treated as proven advantages. Opportunities and threats are external: changes in lender needs, credit conditions, technology, regulation, reinsurance markets and property-risk patterns may create possibilities or pressures. The value of SWOT lies in pairing evidence-based internal assessment with external scenarios, then identifying where a capability may matter most or where a constraint needs mitigation.
- Capability test. Assess whether specialist underwriting, claims handling and portfolio learning are sufficiently distinctive, scalable and resilient for the strategic task.
- Boundary clarity. Keep possible dependence on partners, concentration exposure or operational complexity as internal questions, while treating market and policy developments as external conditions.
- Action bridge. Use the Excel SWOT grid to prioritise relationships between factors and the Word analysis to develop balanced discussion points, evidence needs and response options.
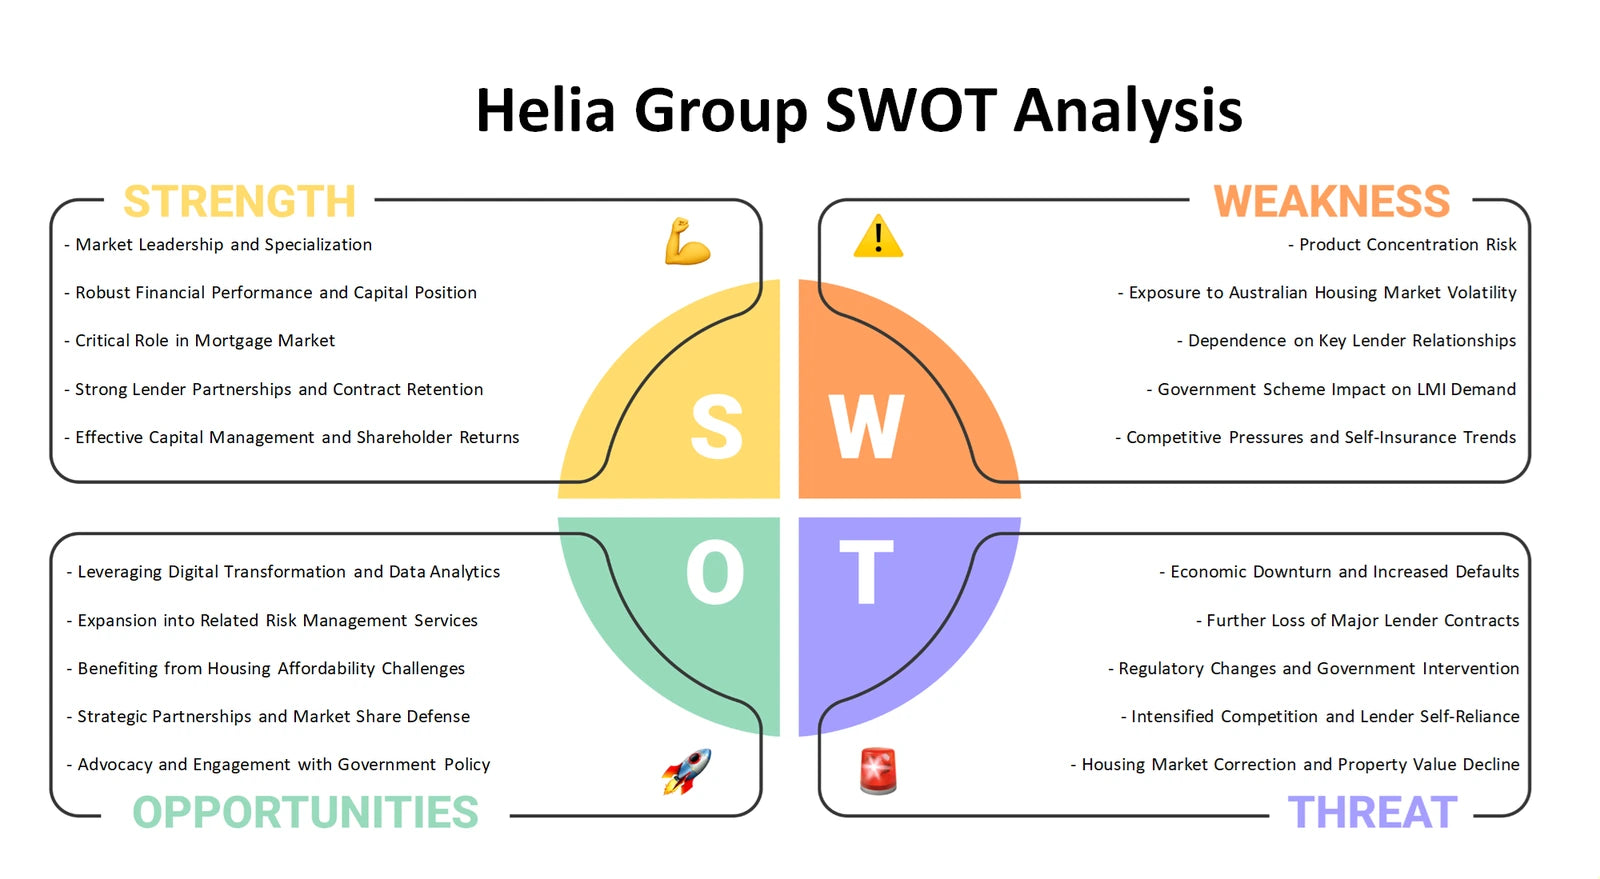
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Helia Group
The six analyses work best as a sequence: the Canvas explains how value and economics connect; Five Forces and PESTLE examine industry and external conditions; BCG supports portfolio-priority discussion; the 4Ps tests the lender-facing proposition; and SWOT brings internal and external considerations together. Using the structured Excel frameworks alongside the detailed Word analysis, customers can develop a more organised basis for strategic conversations about risk, relationships, operating capability and future choices.
Company background: Helia Group — business-model context page.