

Hanover Insurance Group: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Hanover Insurance Group Strategy Analysis Bundle
Hanover Insurance Group refers here to HANOVER INSURANCE GROUP, INC., the SEC filing issuer classified as Fire, Marine & Casualty Insurance (SIC 6331). The business context used for this bundle is a property-and-casualty insurer serving individuals, families and businesses through independent agents and brokers, while using reinsurance relationships to help manage significant underwriting exposures.
For the three months from April 1 to June 30, 2026, the company reported revenue of USD 1.7262 billion and GAAP net income of USD 191.6 million in its 10-Q filed July 29, 2026. These quarterly figures provide company context, not proof that the downloadable files were refreshed in 2026. They help frame questions about portfolio priorities, agent-led value delivery and exposure to changing insurance-market conditions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance portfolios deserve capacity, distribution attention and management focus when growth potential and relative market share differ?
A Hanover Insurance Group BCG Matrix helps organise potential portfolio priorities using the two core BCG criteria: market growth and relative market share. Rather than assigning unverified insurance lines to Stars, Cash Cows, Question Marks or Dogs, the analysis provides a disciplined way to compare product, customer or distribution portfolios. This matters in property-and-casualty insurance because underwriting capacity, claims expertise, agent support and reinsurance protection all require careful allocation.
- Portfolio comparison. Examine where growth conditions and relative competitive position may justify different resource priorities.
- Capacity trade-offs. Consider how underwriting appetite, catastrophe exposure and service requirements may affect portfolio decisions.
- Working view. Use the Excel framework to map candidate portfolios, then use the Word analysis to interpret assumptions and strategic implications.
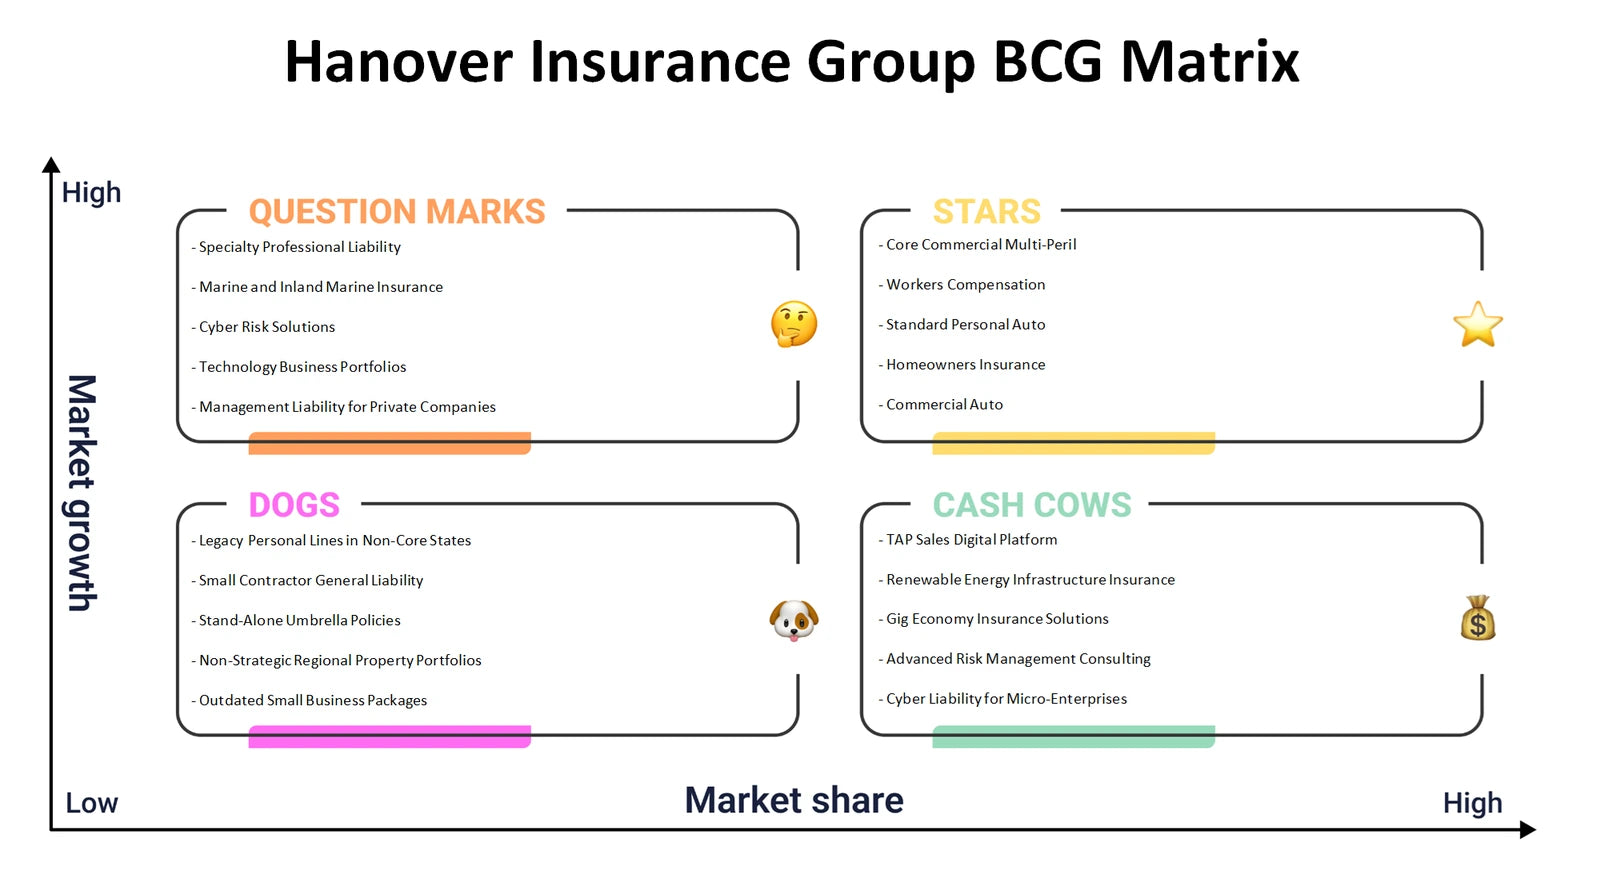
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do agent relationships, underwriting capabilities and risk-transfer partnerships connect to the way the business creates and captures value?
The Hanover Insurance Group Business Model Canvas examines the links among customer segments, value propositions, channels and customer relationships. It also connects revenue streams to key resources, key activities, key partnerships and cost structure. For this insurer, independent agents and brokers are particularly relevant channels and relationship intermediaries, while reinsurance can be assessed as a partnership supporting risk management. Analytics and claims-process capabilities can be considered as resources or activities that may influence service, selection and operating economics.
- Value delivery. Trace how policyholders and business customers may receive advice, coverage access and ongoing service through agent networks.
- Economic logic. Relate underwriting, claims handling, distribution support and reinsurance choices to the model's revenue and cost questions.
- Connected evidence. Populate the Excel canvas by block and use the Word analysis to examine dependencies between operating choices.
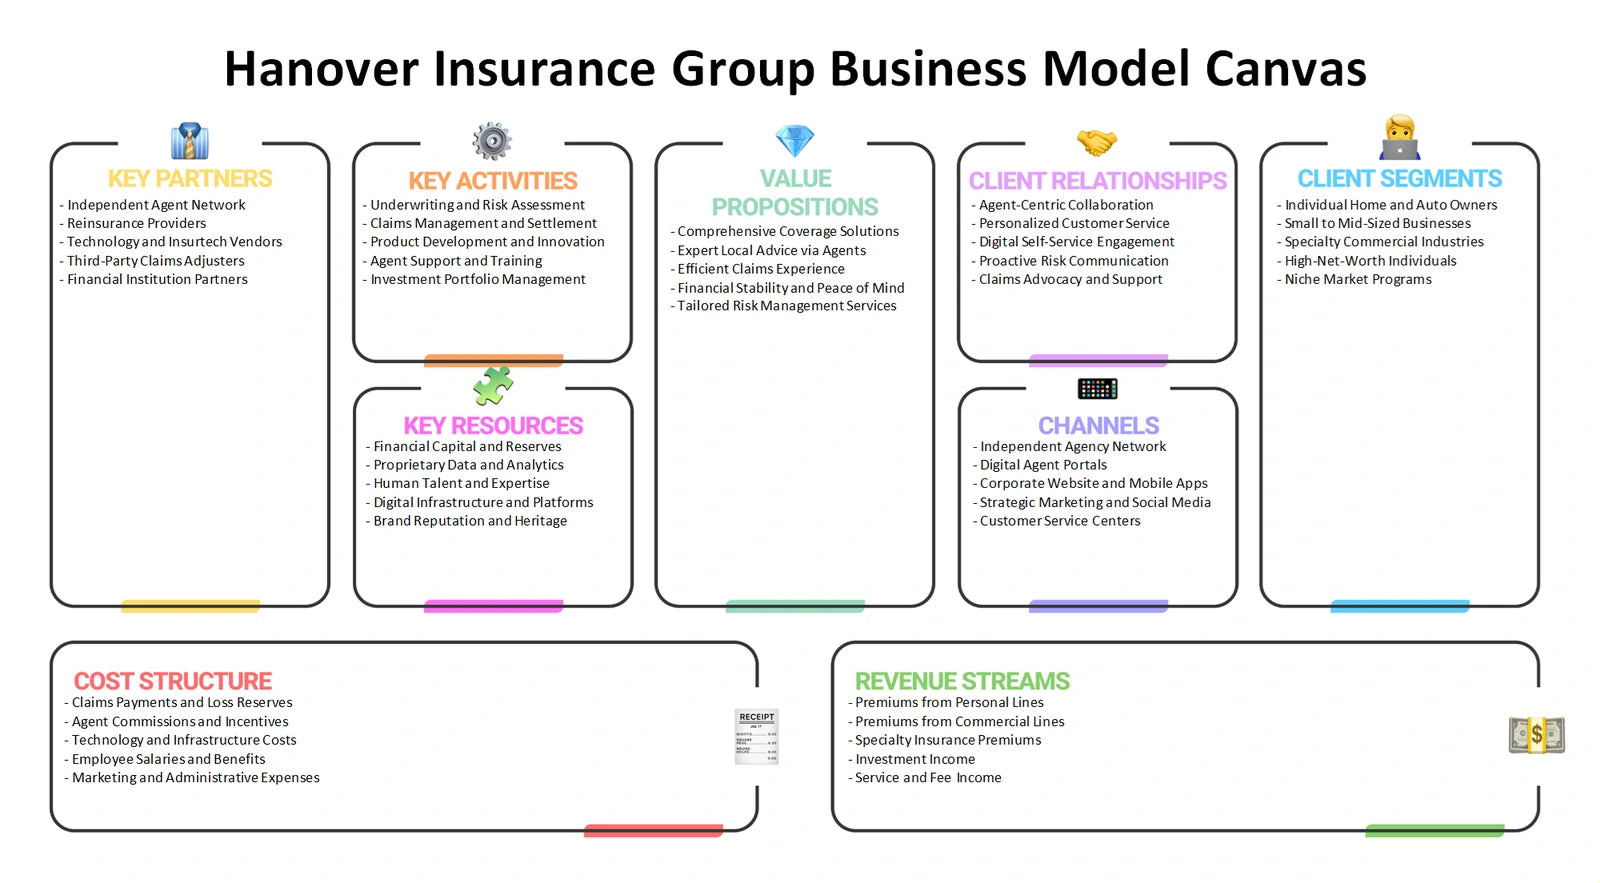
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence underwriting discipline, distribution economics and customer retention in property-and-casualty insurance?
The Hanover Insurance Group Porter's Five Forces analysis assesses rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes without assigning unsupported force scores. Rivalry can be considered alongside policy pricing and service expectations. Reinsurers, technology providers and specialist service suppliers may inform supplier-power questions, while policyholders and influential distribution intermediaries can affect buyer dynamics. New entrants face capital, regulatory and risk-management barriers, while substitutes may include self-insurance, captives or other risk-financing approaches.
- Competitive pressure. Assess how insurance-market rivalry may affect differentiation beyond premium pricing alone.
- Risk-financing alternatives. Compare direct insurance with customer alternatives that address risk retention or transfer differently.
- Force-by-force review. Use the Excel framework to record evidence and assumptions, supported by the Word analysis for industry interpretation.
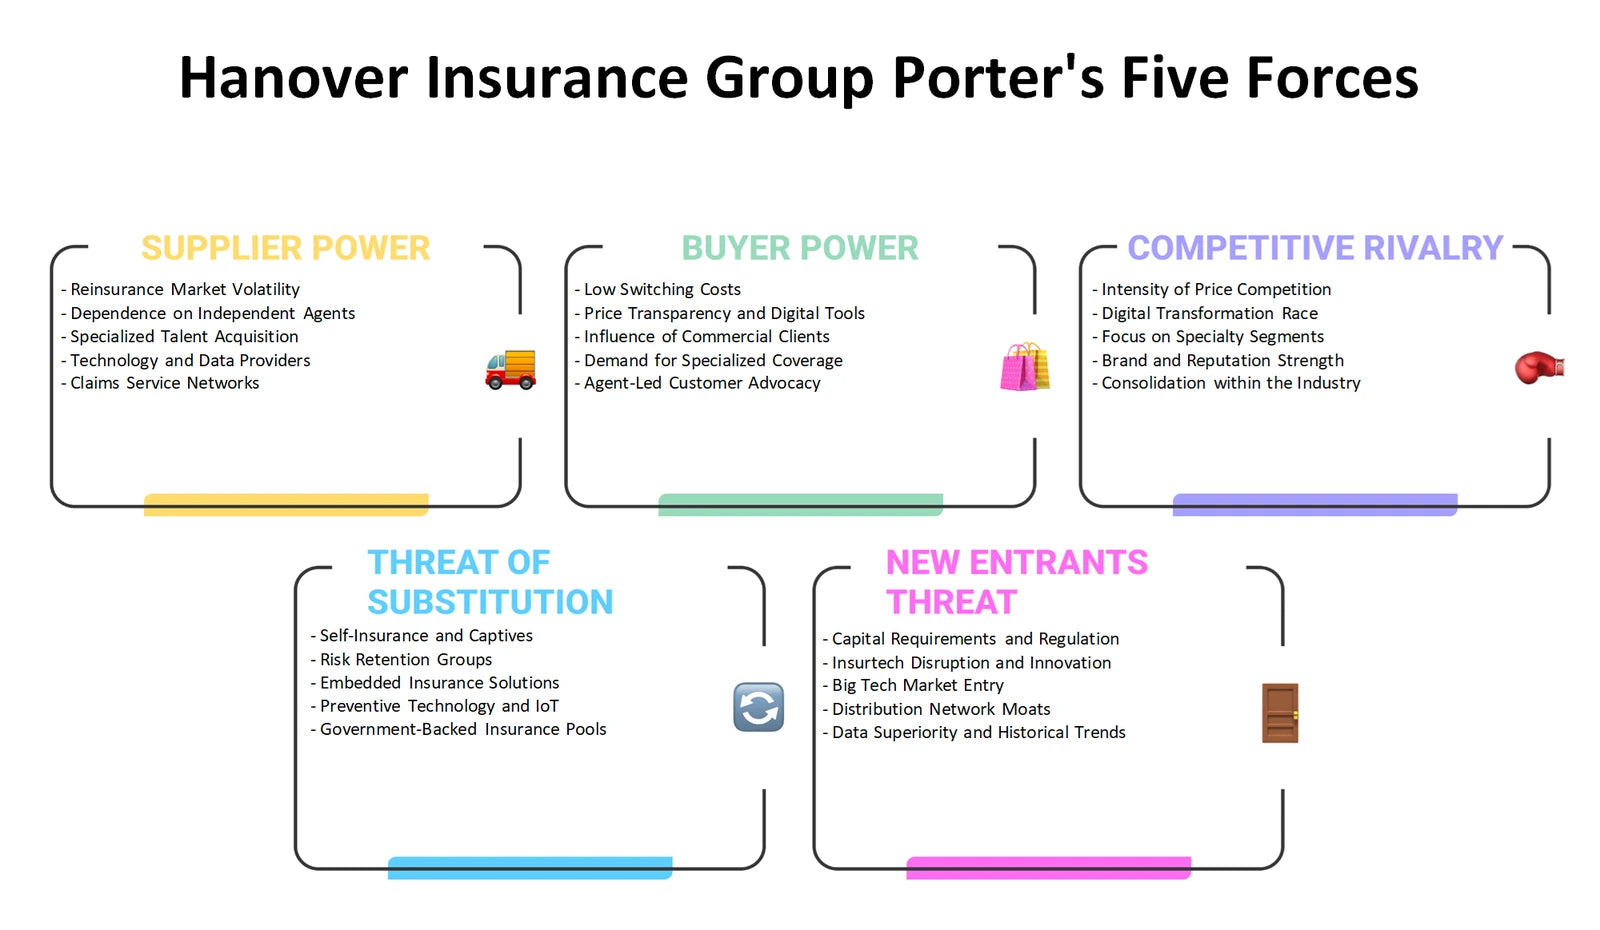
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can insurance offerings, premium logic, agent distribution and communications be considered as one coordinated customer proposition?
The Hanover Insurance Group Marketing Mix examines Product, Price, Place and Promotion in a regulated insurance context. Product analysis can distinguish the protection, service and claims-related experience customers evaluate. Price focuses on insurance premium and underwriting considerations rather than assumed price points. Place is especially important because independent agents and brokers connect the insurer with individuals, families and businesses. Promotion can assess how clear product information, agent enablement and trust-building communications support informed insurance decisions without inventing campaigns or channel shares.
- Product fit. Review how coverage needs, service expectations and risk characteristics may vary by customer context.
- Channel coherence. Examine how agent and broker relationships can influence reach, advice and the consistency of communications.
- Mix alignment. Use the Excel structure to compare the four Ps, then consult the Word analysis to connect marketing choices to insurance economics.
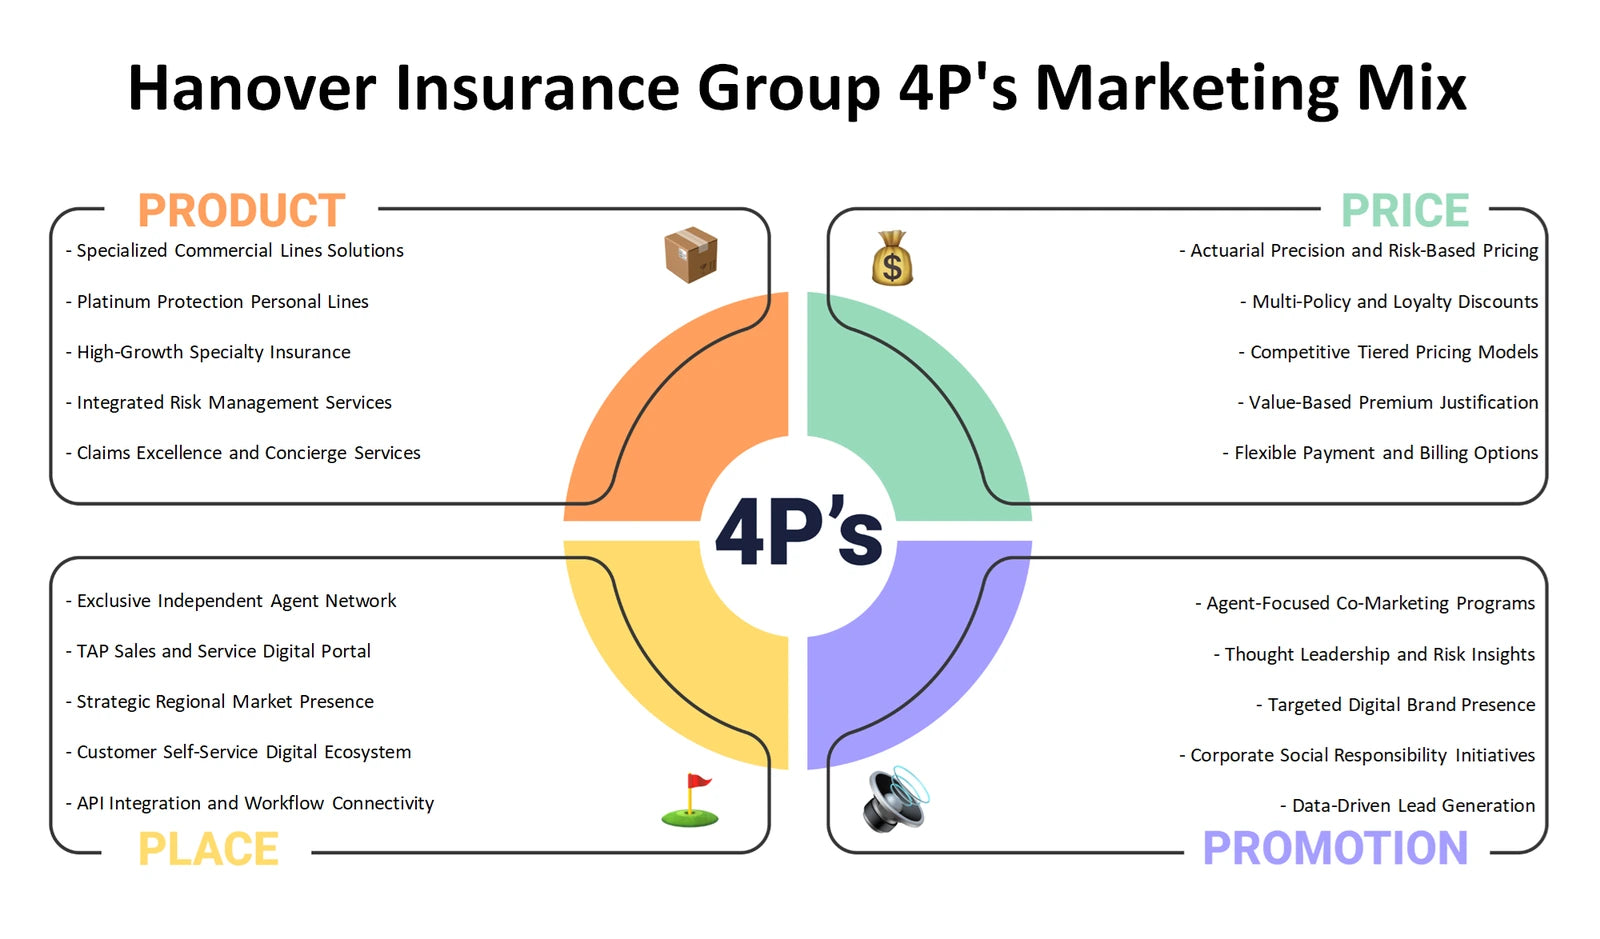
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored because they may affect insurance demand, claims severity, capital decisions or operating requirements?
The Hanover Insurance Group PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental factors. Political and legal questions include insurance oversight, policy rules and claims obligations. Economic conditions can affect affordability, repair costs, loss trends and investment-related considerations. Social expectations may shape service and protection needs, while technology raises questions around data, automation and cyber risk. Environmental conditions are relevant to catastrophe exposure and resilience, but the framework distinguishes scenarios to examine from documented company outcomes.
- External scan. Organise policy, economic, customer, technology, legal and environmental signals in one decision-ready view.
- Scenario discipline. Separate a possible regulatory, catastrophe or cost-pressure scenario from evidence that it has already occurred.
- Monitoring tool. Use the Excel framework to prioritise external factors and the Word analysis to develop their potential strategic relevance.
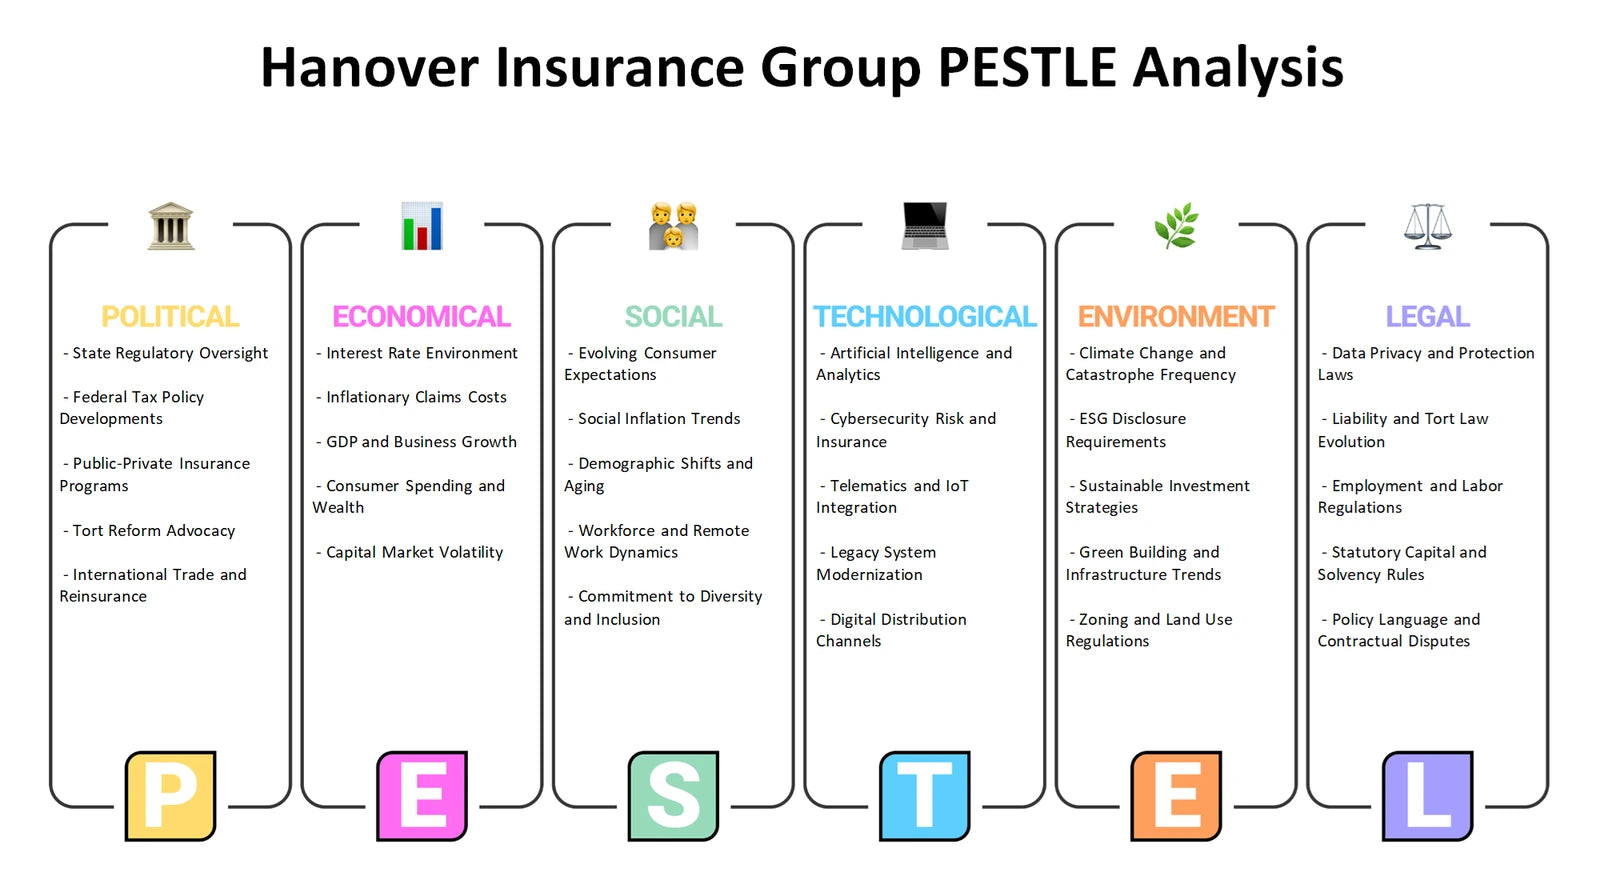
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal operating capabilities be assessed against external opportunities and threats without confusing potential themes with proven findings?
The Hanover Insurance Group SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. Agent and broker relationships, reinsurance arrangements, advanced analytics and claims technology are useful company-context topics to test as possible capabilities or constraints; they should not automatically be labelled proven strengths. External opportunities may arise from changing customer needs or distribution practices, while threats can include catastrophe volatility, insurance-market competition, cyber exposure and cost pressures. Keeping these categories separate helps prevent a broad industry list from becoming an unsupported company conclusion.
- Internal diagnosis. Assess resources, processes, distribution relationships and operating limitations that may influence execution.
- External fit. Compare those internal factors with market openings and risks identified through the wider environment.
- Decision register. Use the Excel matrix to classify evidence and questions, with the Word analysis providing context for balanced interpretation.
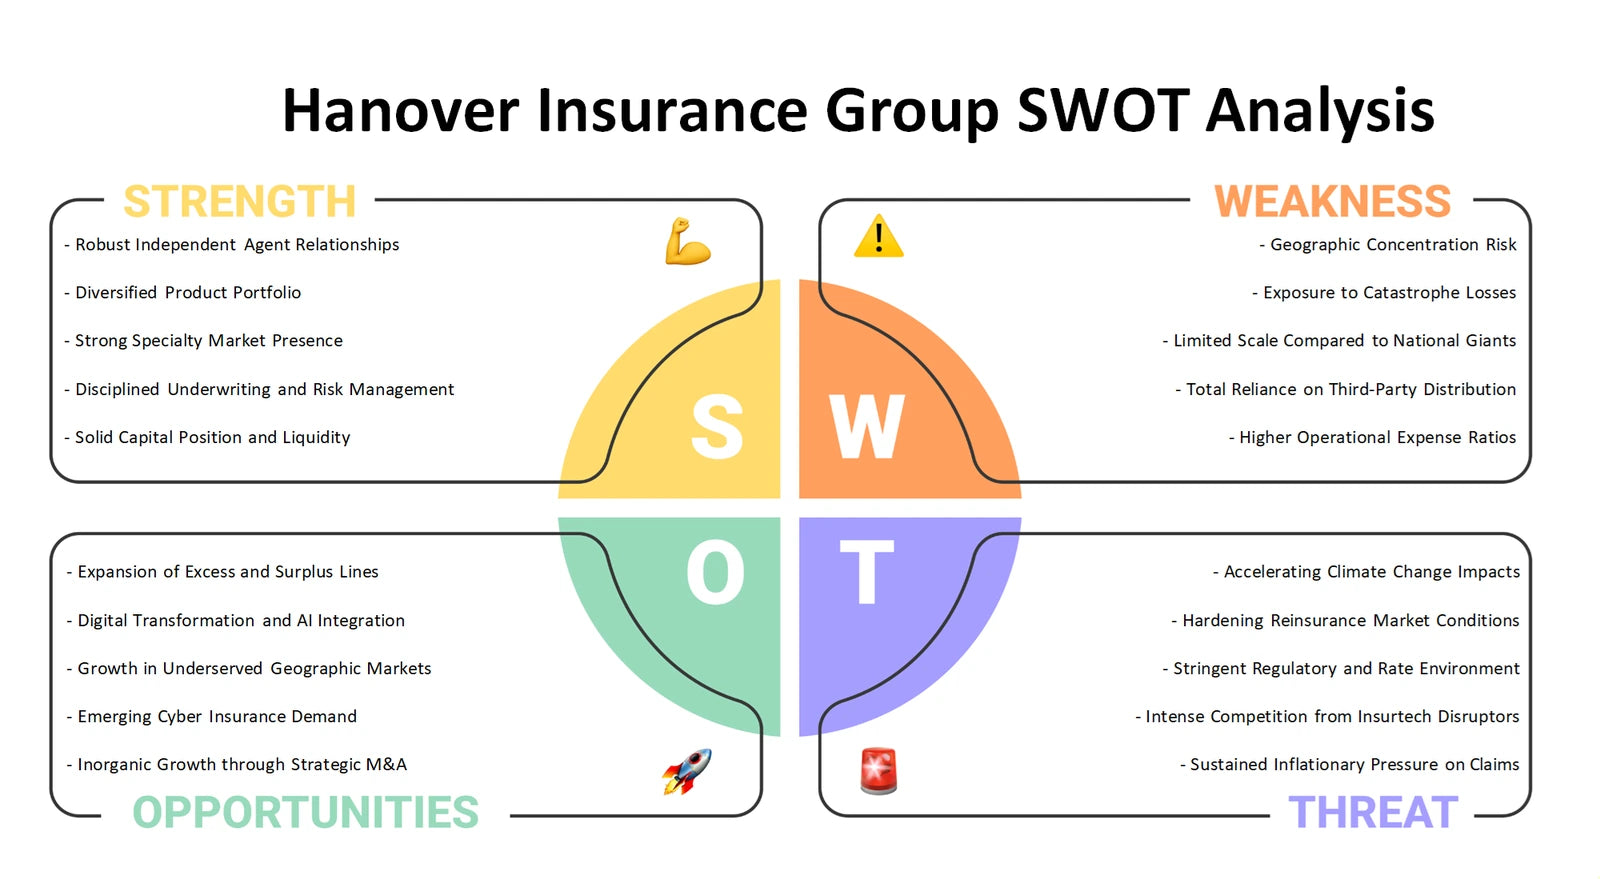
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Hanover Insurance Group
Together, the six perspectives connect portfolio choices, business-model economics, insurance-industry pressures, customer and channel decisions, external change and internal-versus-external strategic assessment. The Excel frameworks help organise comparisons and working assumptions, while the Word files provide detailed company analysis that can support more focused planning conversations.
Company background: Hanover Insurance Group — SEC issuer submissions profile.