

Guangzhou Rural Commercial Bank: Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Guangzhou Rural Commercial Bank Strategy Analysis Bundle
Guangzhou Rural Commercial Bank is a Chinese banking business associated with Guangzhou and identified on its corporate homepage as 广州农村商业银行股份有限公司. The company context used for this bundle centres on retail customers, small and medium-sized enterprises, agricultural borrowers and corporate clients in Guangzhou’s local economy. Relevant banking topics include working-capital lending, mortgages, equipment finance, project loans, payments and foreign-exchange service needs.
That mix creates connected questions about which banking activities deserve resources, how value is delivered through branches and digital channels, and how lending, settlement and customer trust interact with risk control. The six analyses help organise those questions without assuming unverified market shares, financial results, portfolio rankings or investment conclusions for Guangzhou Rural Commercial Bank.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, payment and customer-service activities should receive the greatest attention as Guangzhou’s banking needs evolve?
The Guangzhou Rural Commercial Bank BCG Matrix helps frame portfolio priorities through market growth and relative market share rather than treating every banking activity as equally strategic. It can compare potential areas such as retail lending, SME finance, agricultural credit, corporate lending and payment-related services against the growth of the relevant need and the bank’s relative competitive position. Stars, Cash Cows, Question Marks and Dogs are analytical categories, not claimed placements for the bank’s products. The value is in making the evidence required for resource decisions visible.
- Portfolio lens. Compare mature income-generating activities with newer areas that may require investment, specialist capacity or closer risk monitoring.
- Capital discipline. Consider how loan growth ambitions, credit quality, liquidity needs and operational capacity affect the resources available to each activity.
- Structured prioritisation. Use the Excel framework to map possible business areas, then use the Word analysis to document assumptions, evidence gaps and discussion points.
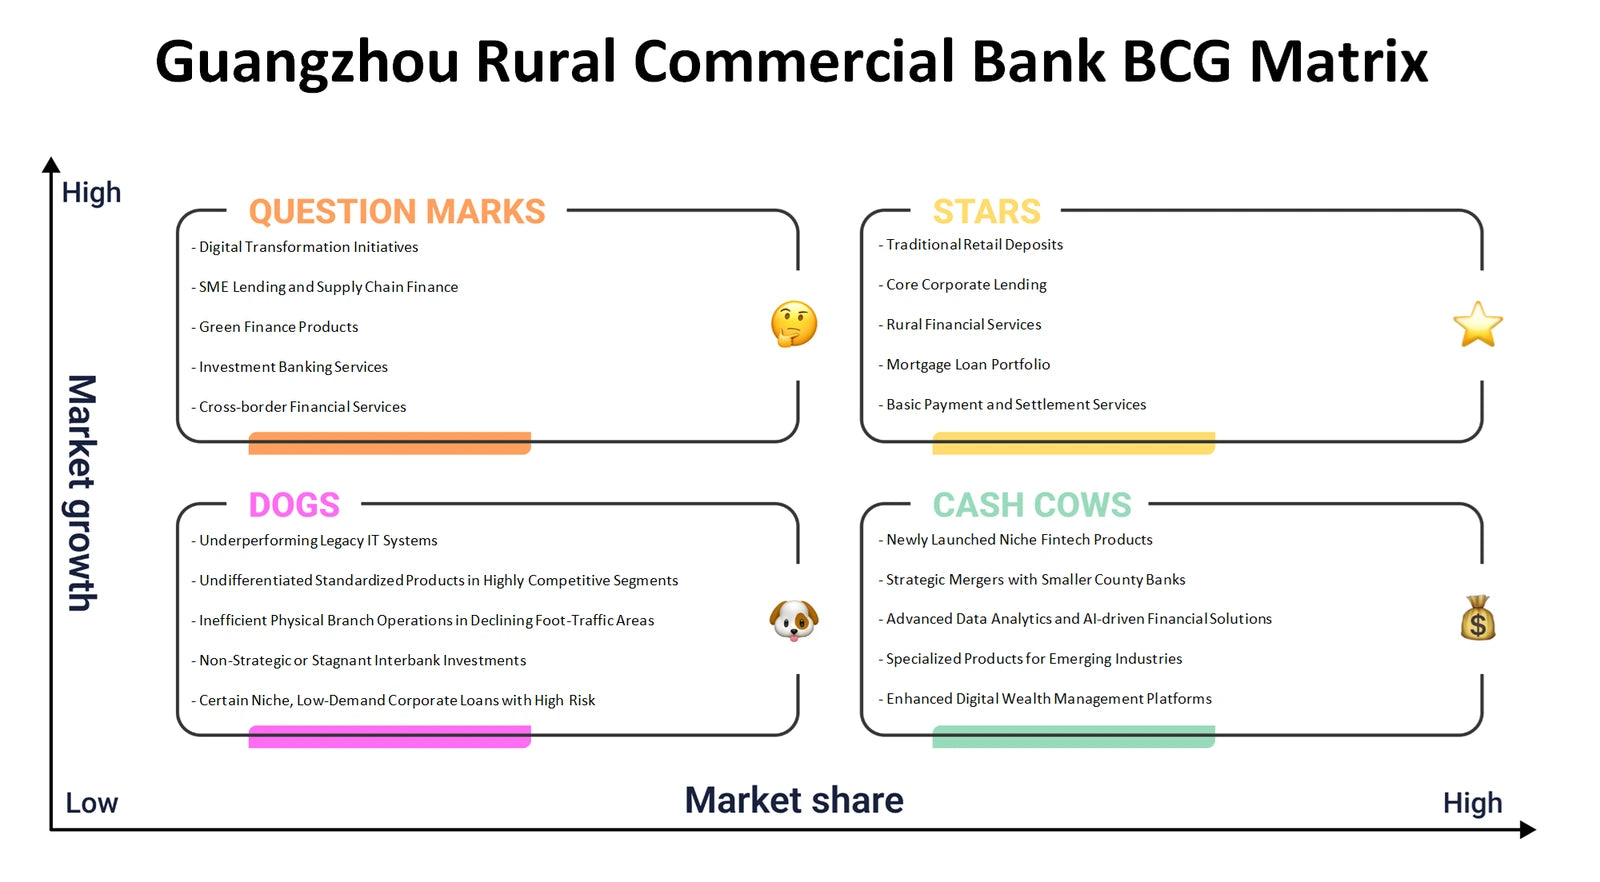
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, banking channels, risk capabilities and revenue logic fit together in one operating model?
The Guangzhou Rural Commercial Bank Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a bank serving households, SMEs, agricultural borrowers and corporate customers, the framework helps examine how lending and settlement needs are reached through relationship-led, branch-based or digital channels; how trust and service are maintained; and how interest, fee and transaction economics must support the operating model. It also highlights the importance of underwriting, collateral processes, payment infrastructure and external network relationships.
- Customer-value fit. Examine whether financing, payments and service support address the differing cash-flow, property, equipment and trade requirements of each customer group.
- Operating links. Trace how people, systems, licences, risk controls and partnerships enable the activities that create value and generate revenue.
- Model alignment. Populate the Excel canvas as a one-page working view and use the Word analysis to explore the connections and trade-offs behind each block.
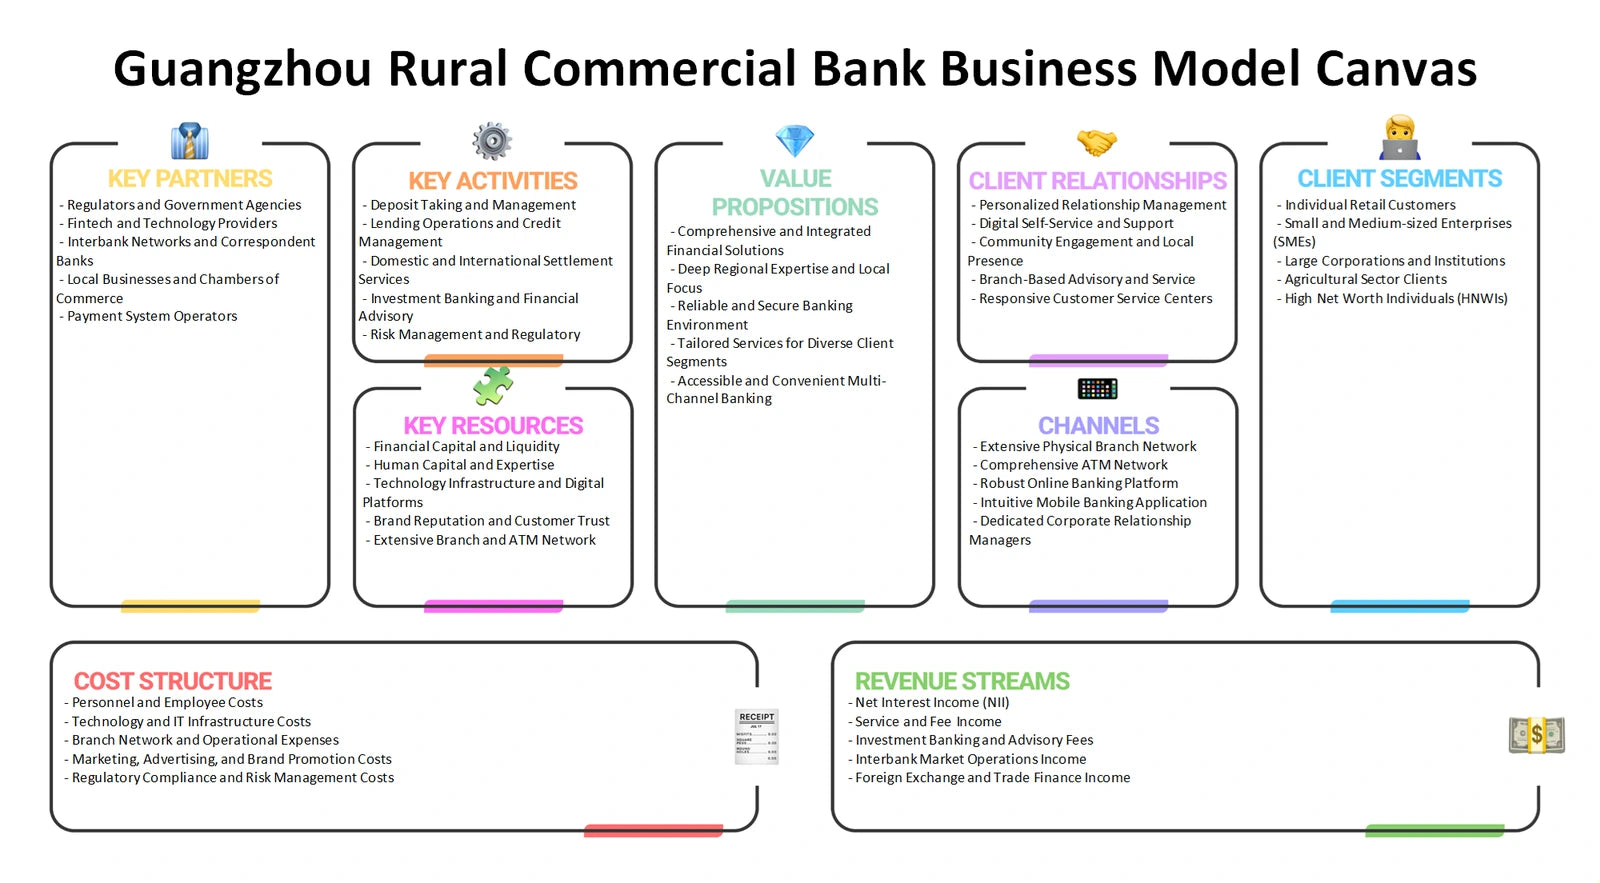
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness and margins of the banking services relevant to Guangzhou Rural Commercial Bank?
Guangzhou Rural Commercial Bank Porter’s Five Forces analysis examines competition across banking and adjacent financial-service choices without inventing force scores or naming unverified rivals. Rivalry concerns the contest for deposits, borrowers and transaction relationships. Supplier power can include the cost and availability of funding, technology, specialist talent and service partners. Buyer power reflects customers’ ability to compare financing and payment options. The framework also considers barriers facing new entrants and substitutes such as non-bank financing, digital payment methods or other ways customers meet credit and cash-management needs.
- Competitive pressure. Assess where similar lending and payment offerings may compress pricing flexibility or increase customer-acquisition effort.
- Alternative solutions. Distinguish direct banking competition from substitutes that solve a borrower’s funding or a merchant’s settlement need differently.
- Evidence-led review. Use the Excel force structure to record pressure points and the Word analysis to explain why each force matters for decisions and monitoring.
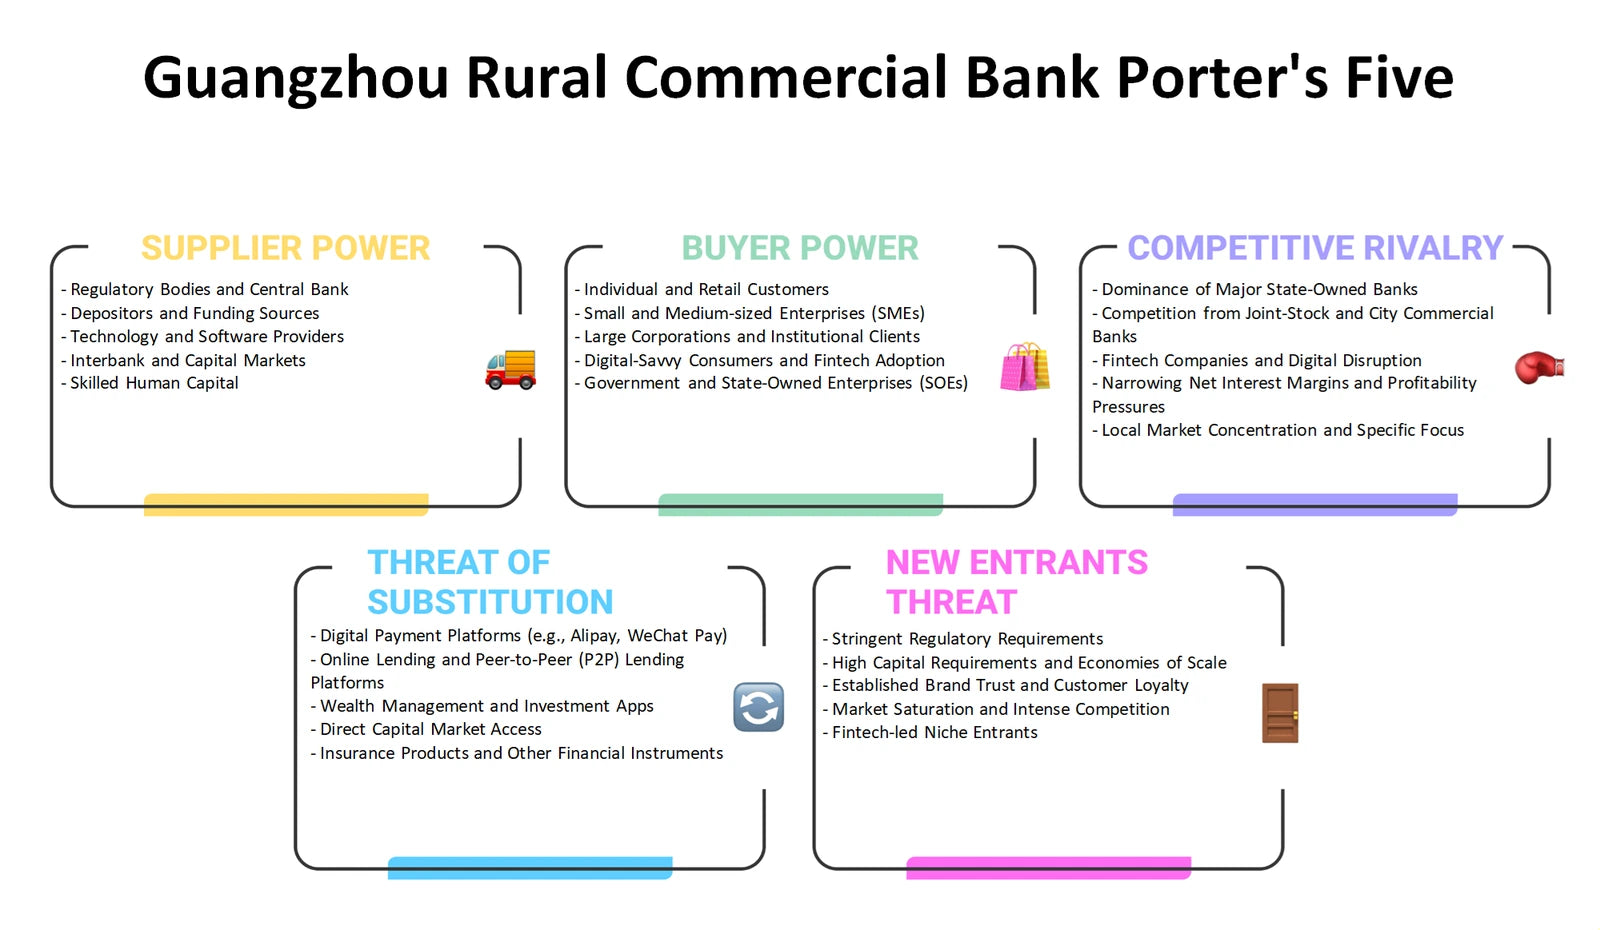
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated bank present relevant services to local customers while keeping product, pricing, access and communication coherent?
The Guangzhou Rural Commercial Bank Marketing Mix considers Product, Price, Place and Promotion through the realities of banking. Product analysis can distinguish loan, deposit, payment, card, settlement and foreign-exchange needs across individuals and business customers. Price is not simply a headline rate: it can include lending terms, fees, risk-based pricing and the value customers receive from service and convenience. Place considers branches, relationship managers, digital journeys and payment access. Promotion examines clear, compliant communication that helps customers understand suitable services rather than assuming a particular campaign or channel share.
- Service design. Compare how mortgage, working-capital, equipment and project-finance needs may require different product features and service support.
- Channel coherence. Examine where local presence, relationship management and digital access may complement each other across customer journeys.
- Practical planning. Use the Excel framework to organise the four Ps and the Word analysis to add banking-specific rationale, customer questions and implementation considerations.
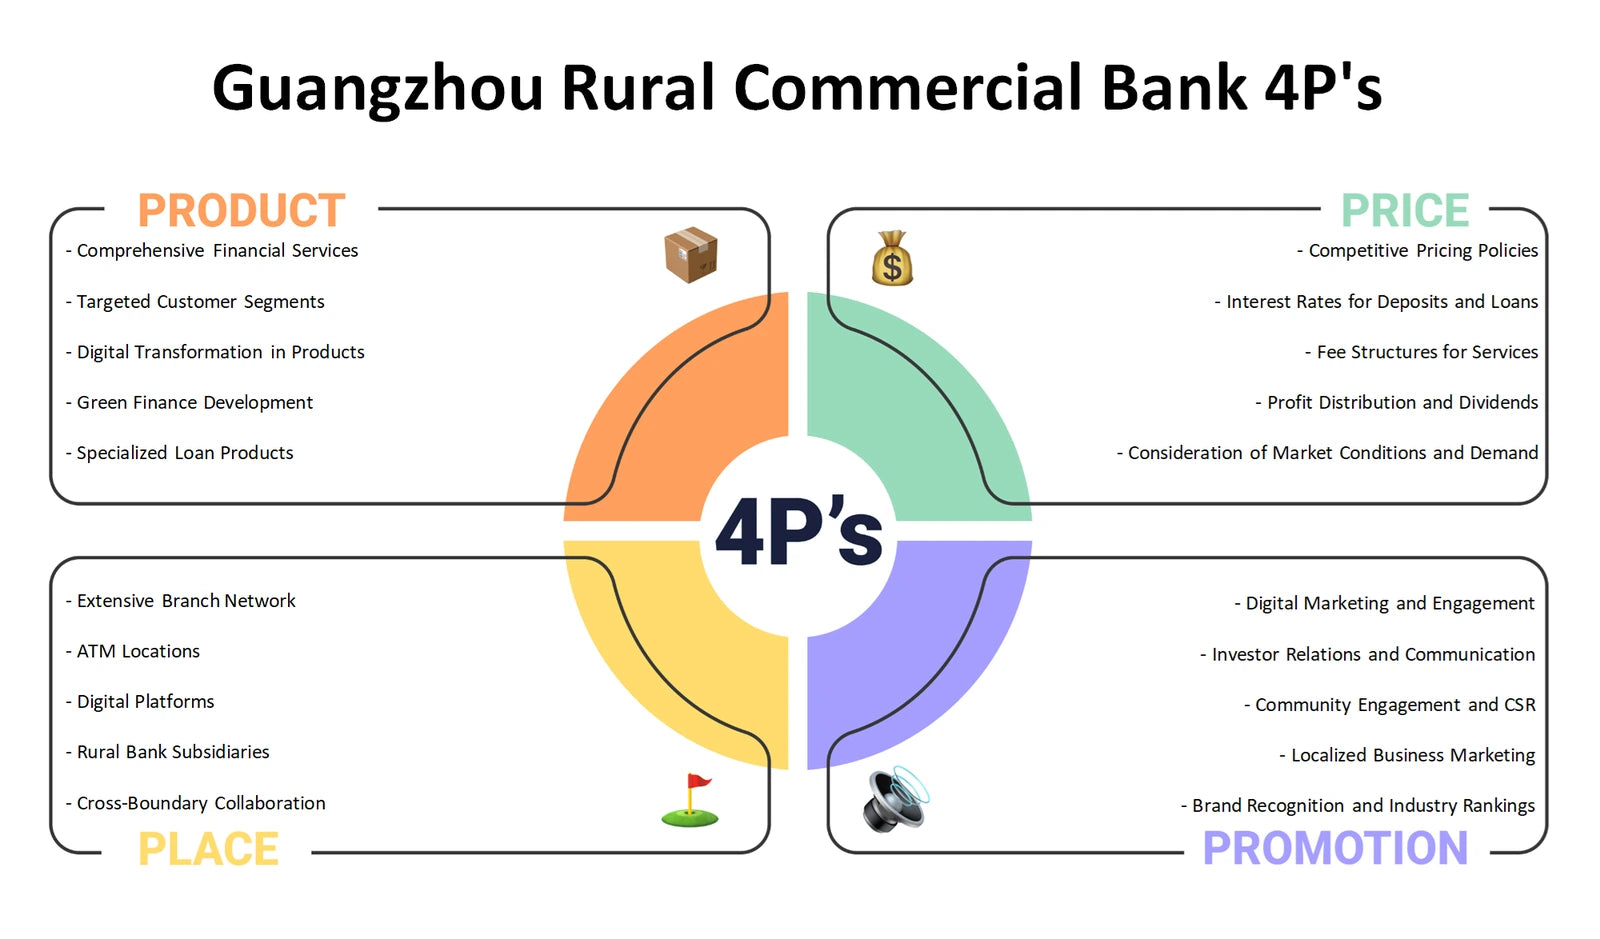
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored when assessing banking demand, operating requirements and risk in Guangzhou?
The Guangzhou Rural Commercial Bank PESTLE analysis, also commonly called PESTEL, separates six external influences that can affect a Chinese bank. Political questions may concern policy direction and the role of financial institutions in local economic development. Economic conditions can affect borrower cash flow, credit demand and funding conditions. Social change may alter expectations for convenient and trusted service. Technological developments can reshape digital banking, payment security and data use. Legal issues cover regulated banking conduct, foreign-exchange compliance and customer protection. Environmental factors can influence financed assets, project risks and sustainability expectations. These are areas for assessment, not claims that a particular change has occurred.
- External scan. Identify the macro and regulatory questions most relevant to lending, payments, cross-border service and customer confidence.
- Risk connections. Link changes outside the bank to potential effects on demand, asset quality, operating processes and compliance requirements.
- Monitoring record. Use the Excel categories to maintain a structured external checklist and the Word analysis to develop context for management discussion.
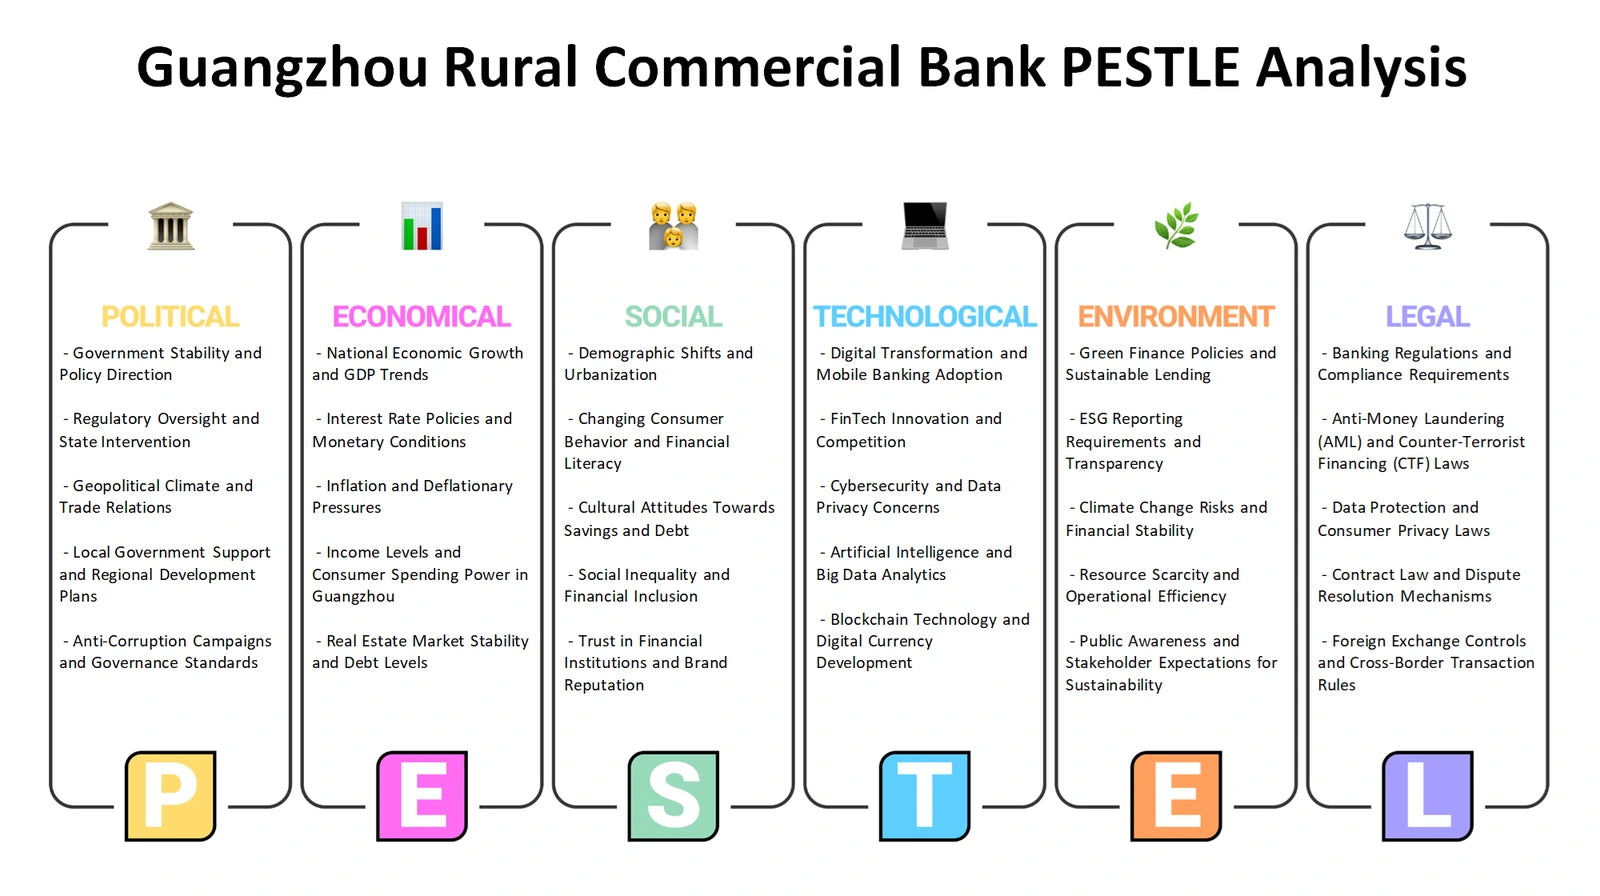
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and constraints be considered alongside opportunities and threats in Guangzhou’s changing financial-services environment?
The Guangzhou Rural Commercial Bank SWOT analysis provides a disciplined distinction between internal and external factors. Strengths and weaknesses concern capabilities that may be shaped within the organisation, such as local customer understanding, lending processes, service capacity, risk systems, technology or operational complexity. Opportunities and threats arise outside the bank, including evolving customer demand, digital adoption, economic conditions, regulation and alternative financial solutions. The framework should not present plausible themes as proven findings; instead, it helps test which evidence supports each classification and where management should avoid confusing a market trend with an internal capability.
- Internal diagnosis. Explore how customer relationships, underwriting discipline, payment capabilities and operating constraints may influence strategic options.
- External choices. Compare possible opportunities and threats against the bank’s ability to respond, rather than listing trends without a decision context.
- Actionable synthesis. Use the Excel SWOT grid to sort evidence and the Word analysis to connect validated themes to questions for planning, risk review or further research.
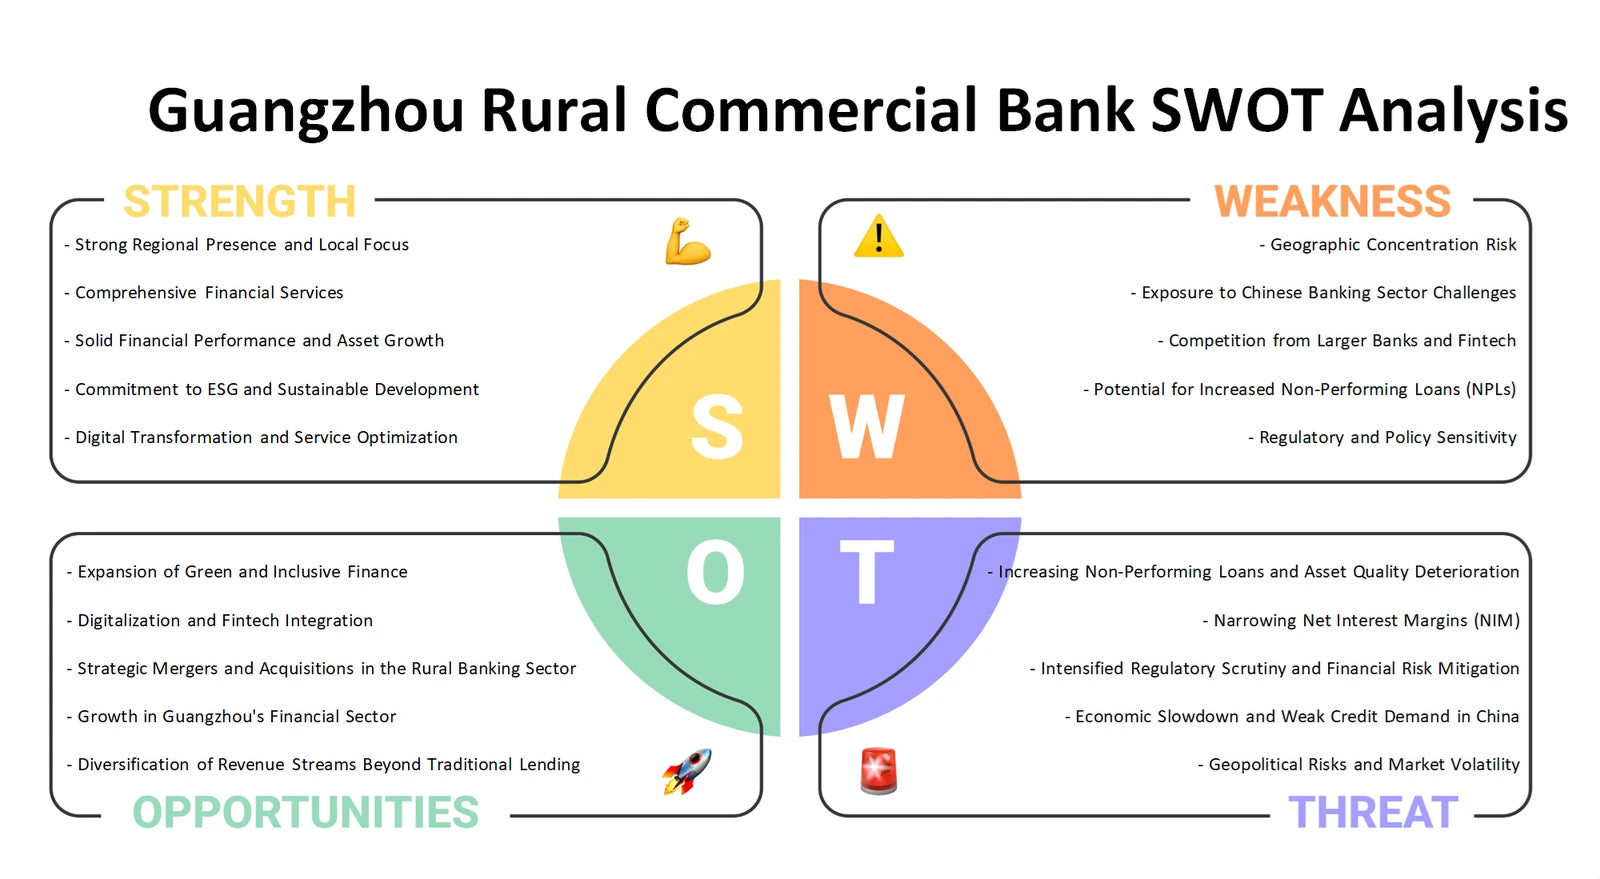
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected banking strategy view
Together, the six perspectives move from portfolio choices and business-model logic to competitive pressures, customer-facing decisions, external conditions and strategic fit. The Excel frameworks provide structured ways to compare and organise the issues, while the detailed Word analysis supports fuller interpretation of Guangzhou Rural Commercial Bank’s lending, payment, customer and risk-management context.
Company background: Guangzhou Rural Commercial Bank — corporate homepage.