

Guild Mortgage: Lending Economics and Agricultural Demand – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Guild Mortgage Strategy Analysis Bundle
Guild Mortgage is the display name used here for Guild Mortgage Company, an American mortgage lending company serving homebuyers in the United States. Its residential lending model can be examined through the needs of borrowers seeking conventional and government-backed mortgage options, including pathways associated with FHA, VA and USDA programs described in the supplied company context.
The supplied Guild Mortgage business-model context also describes selling originated mortgages into the secondary market to replenish lending capacity, alongside relationships with government housing agencies. These are useful business-model inputs rather than conclusions from the downloadable files. The bundle helps customers assess portfolio priorities, lending economics, competitive pressure and external conditions through six connected strategic lenses.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending products, customer segments or local-market priorities deserve resources when growth and relative market share differ?
A Guild Mortgage BCG Matrix helps organize a mortgage lender's portfolio choices rather than presume that every loan category should receive equal attention. The framework compares market growth with relative market share and uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to structure resource-priority discussions. For this business, useful comparison areas may include government-backed versus conventional lending pathways, borrower needs, geographic opportunity and the operational capacity required to originate and sell loans. It does not assign Guild Mortgage offerings to a quadrant or claim market-share results; it provides a disciplined way to test what evidence would justify investment, maintenance, selective development or exit.
- Portfolio lens. Compare mortgage-product and market opportunities using growth and relative-share criteria instead of treating volume alone as a strategic priority.
- Capital discipline. Consider how loan-origination capacity, secondary-market liquidity and compliance effort affect the resources available for different portfolio areas.
- Structured comparison. Use the Excel framework to map possible categories and assumptions, then use the detailed Word analysis to interpret the strategic questions behind each position.
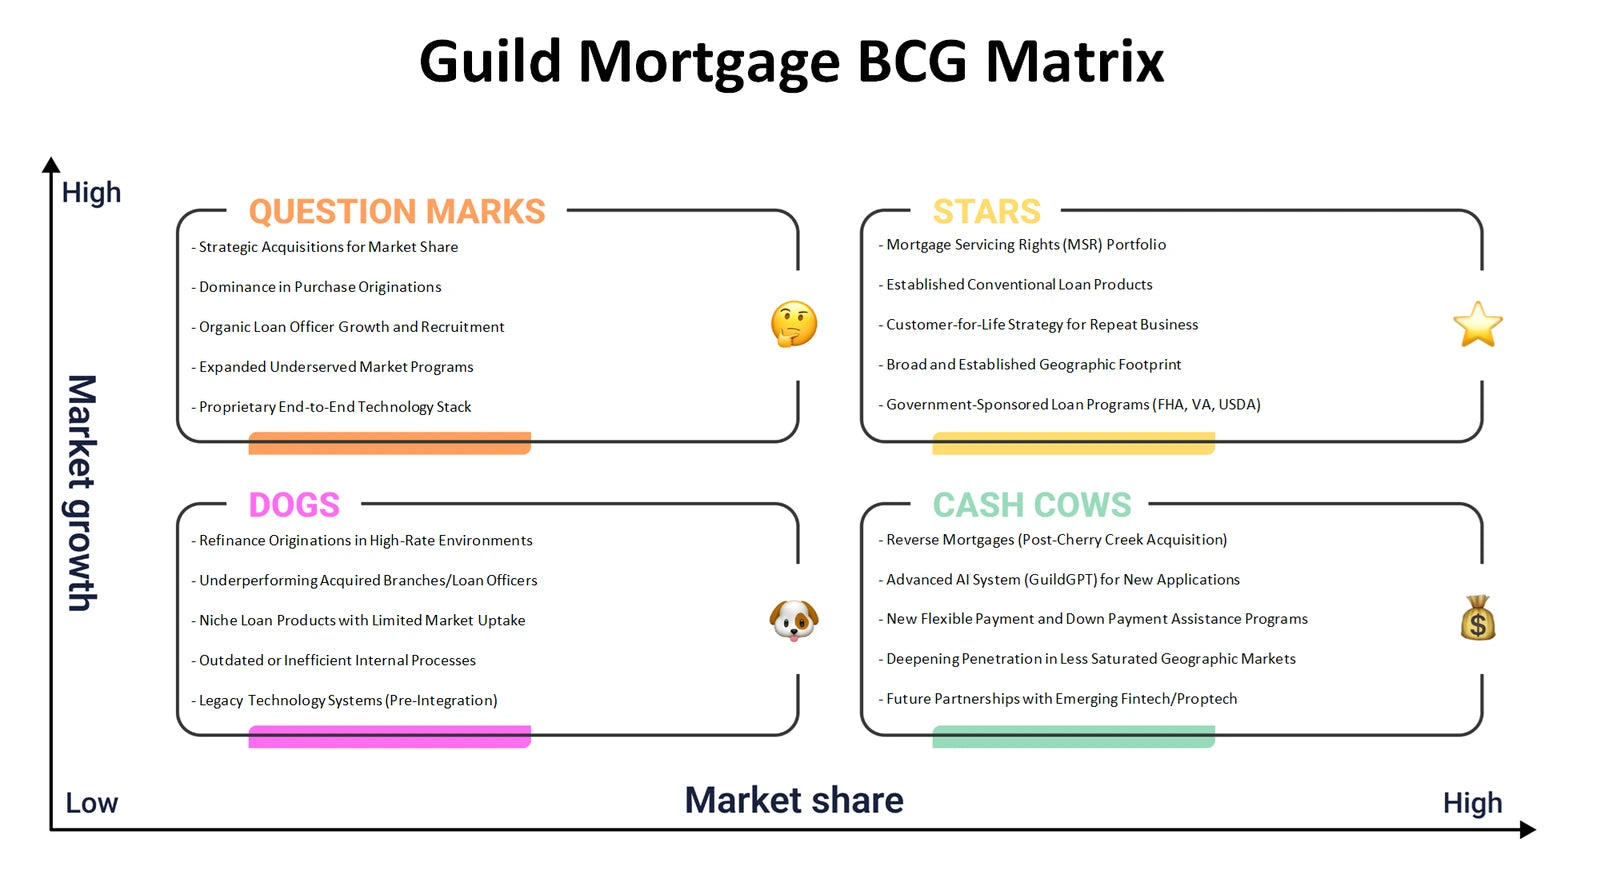
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do borrower needs, loan delivery, funding relationships and operating costs fit together in Guild Mortgage's value-creation logic?
The Guild Mortgage Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a residential lender, the connections matter. Homebuyers need financing options and guidance; channels and relationships shape how applications are acquired and supported; underwriting, origination, servicing and secondary-market execution may shape activities and economics. The supplied context makes government-agency relationships and investor liquidity especially relevant topics to examine as partnerships and funding-related dependencies. The Canvas helps users trace these links without presenting unverified revenue, cost or operational results as established facts.
- Borrower-to-value fit. Examine how first-time buyers, veterans, rural borrowers and other potential customer segments may connect to distinct financing needs and value propositions.
- Economic connections. Assess how channels, relationships, key activities and key resources could influence revenue streams, cost structure and lending capacity.
- Model mapping. Populate the Excel Canvas systematically, using the Word analysis to add context and test whether each building block supports the others.
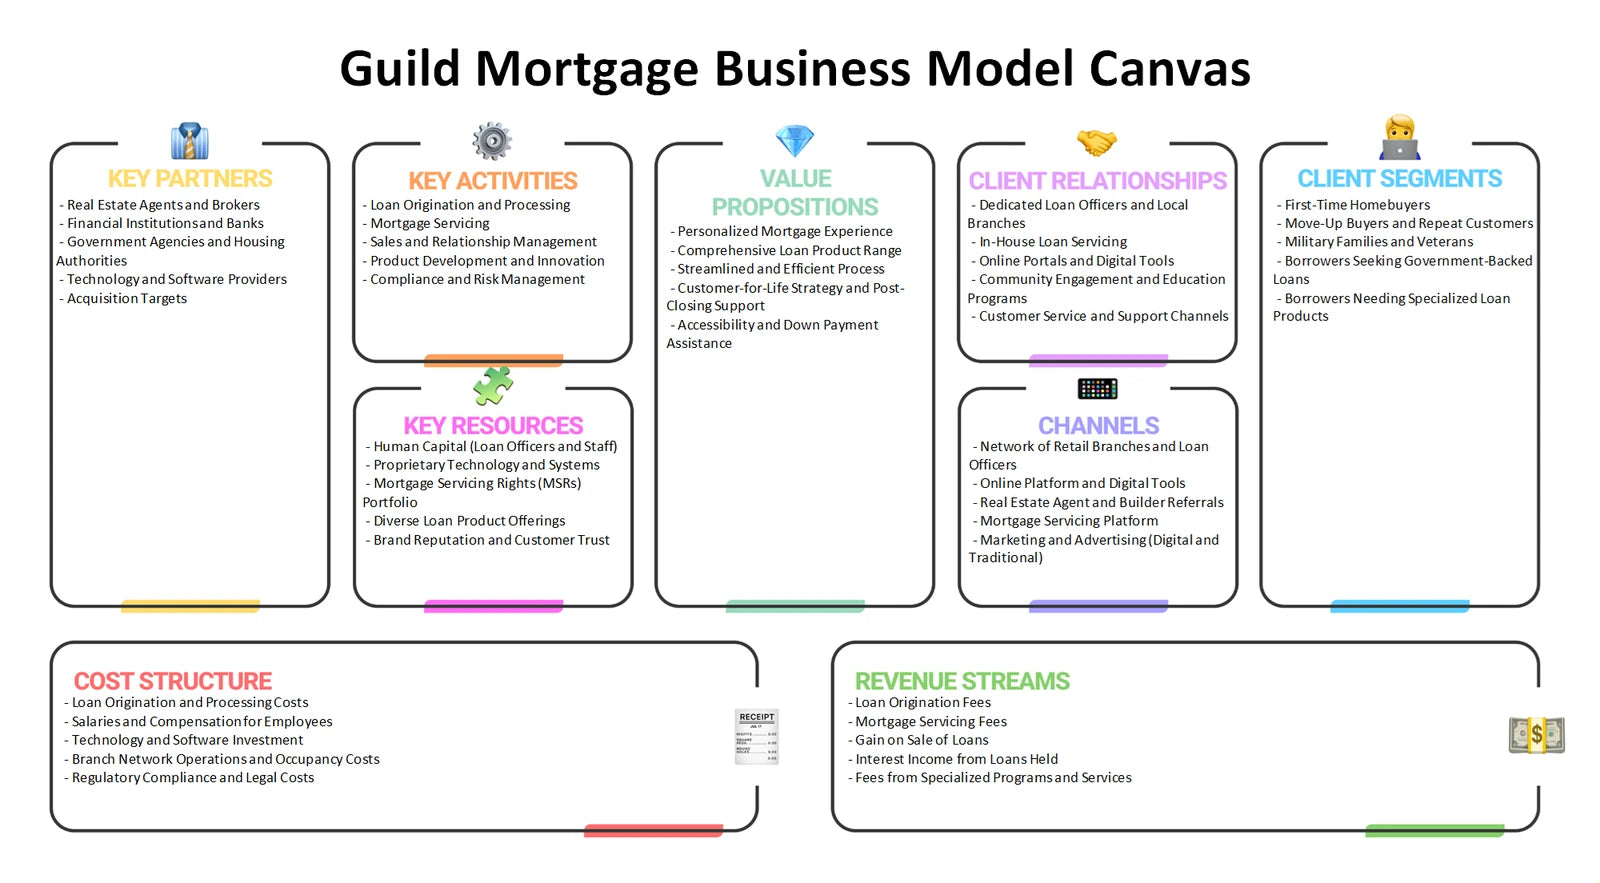
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect Guild Mortgage's ability to attract borrowers, fund loans and protect attractive economics?
Guild Mortgage Porter's Five Forces examines the competitive setting around U.S. residential mortgage lending. Rivalry concerns the intensity of competition for borrowers, referral relationships and lending volume. Buyer power considers how borrowers can compare loan options, rates, service and approval experiences. Supplier power is relevant to access to capital, investors, technology and specialized talent. The threat of new entrants asks how regulatory, funding and operational requirements shape entry, while substitutes extend beyond direct lenders to other ways households may delay, finance or solve housing needs. The analysis offers a framework for assessing pressure points; it does not assign force scores or name competitors without supporting evidence.
- Funding dependence. Explore how capital-market access and mortgage investors may influence supplier power and operational resilience.
- Borrower choice. Assess why transparent terms, speed, service and product eligibility can matter when buyers have multiple financing alternatives.
- Pressure testing. Use the Excel force-by-force structure to record evidence and hypotheses, while the Word analysis explains the strategic significance of each pressure.
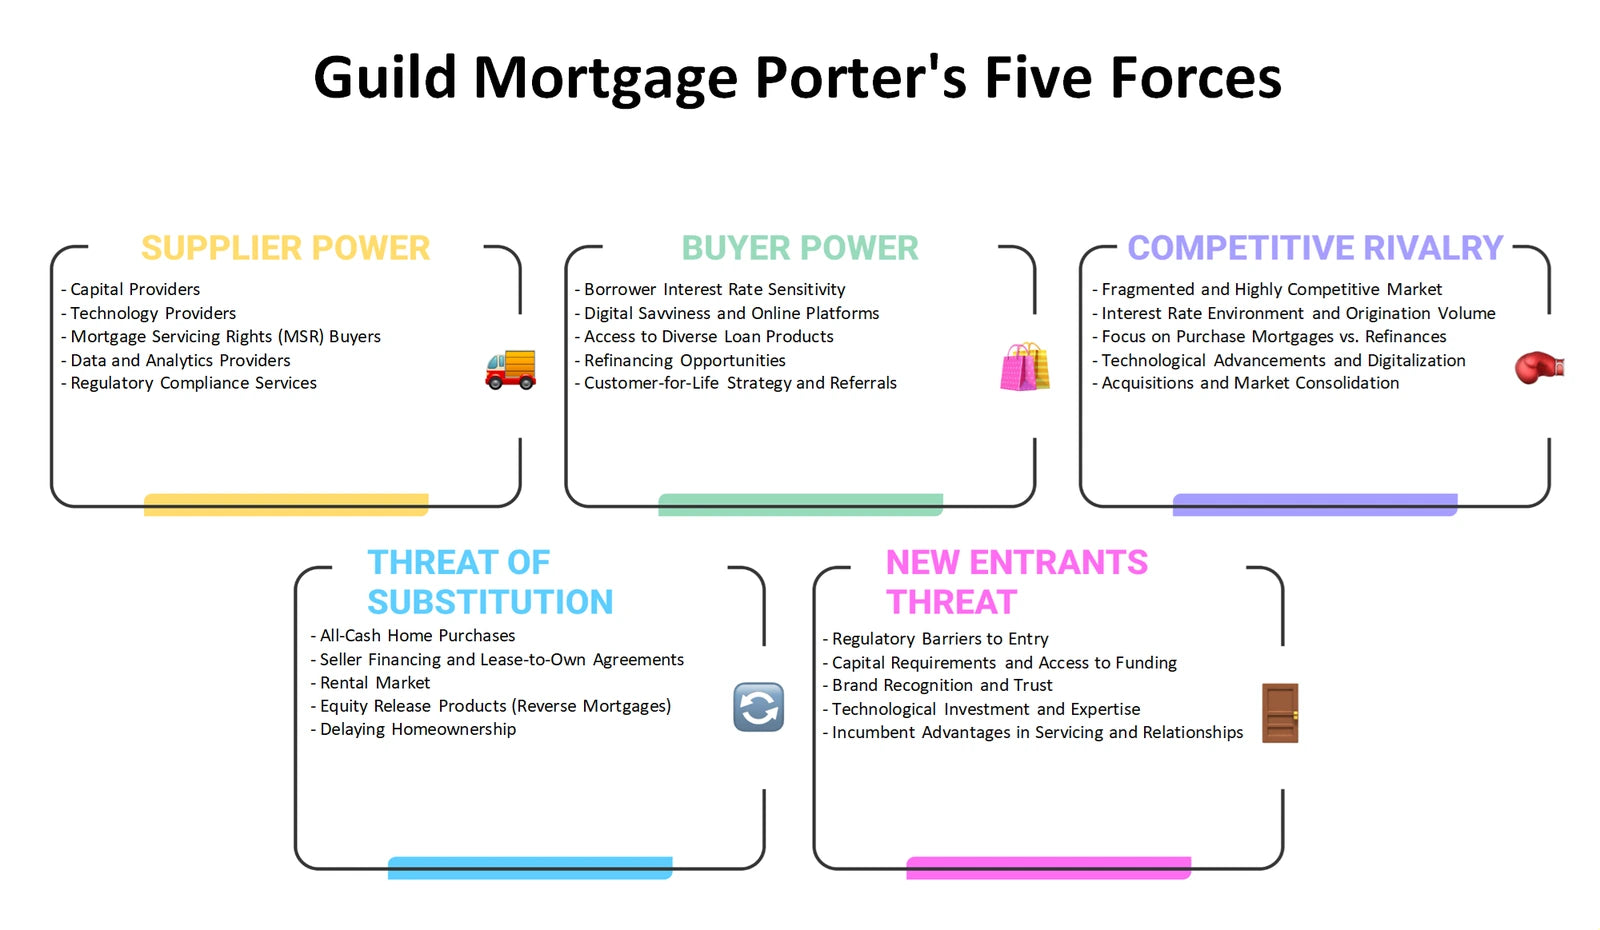
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Guild Mortgage align mortgage offerings, borrower costs, distribution routes and communications in a regulated service category?
A Guild Mortgage Marketing Mix considers Product, Price, Place and Promotion as linked customer choices rather than a generic consumer-goods checklist. Product can include the range and suitability of residential loan options, including government-backed pathways identified in the supplied context. Price is not simply a sticker price: borrowers may evaluate interest rates, fees, eligibility conditions and the overall affordability of financing. Place examines how prospective borrowers reach the lender through relevant origination and service channels. Promotion addresses how information is communicated clearly and responsibly when decisions are high-value and regulated. The framework helps distinguish what should be examined from claims about Guild Mortgage's actual pricing, campaigns or channel share.
- Offering clarity. Compare how loan features and eligibility considerations may address different homebuyer circumstances without assuming a one-size-fits-all proposition.
- Trust journey. Examine how place and promotion can support informed borrower decisions before and during a complex application process.
- 4P alignment. Organize Product, Price, Place and Promotion observations in Excel, then use the Word analysis to connect them to customer expectations and compliance-aware messaging.
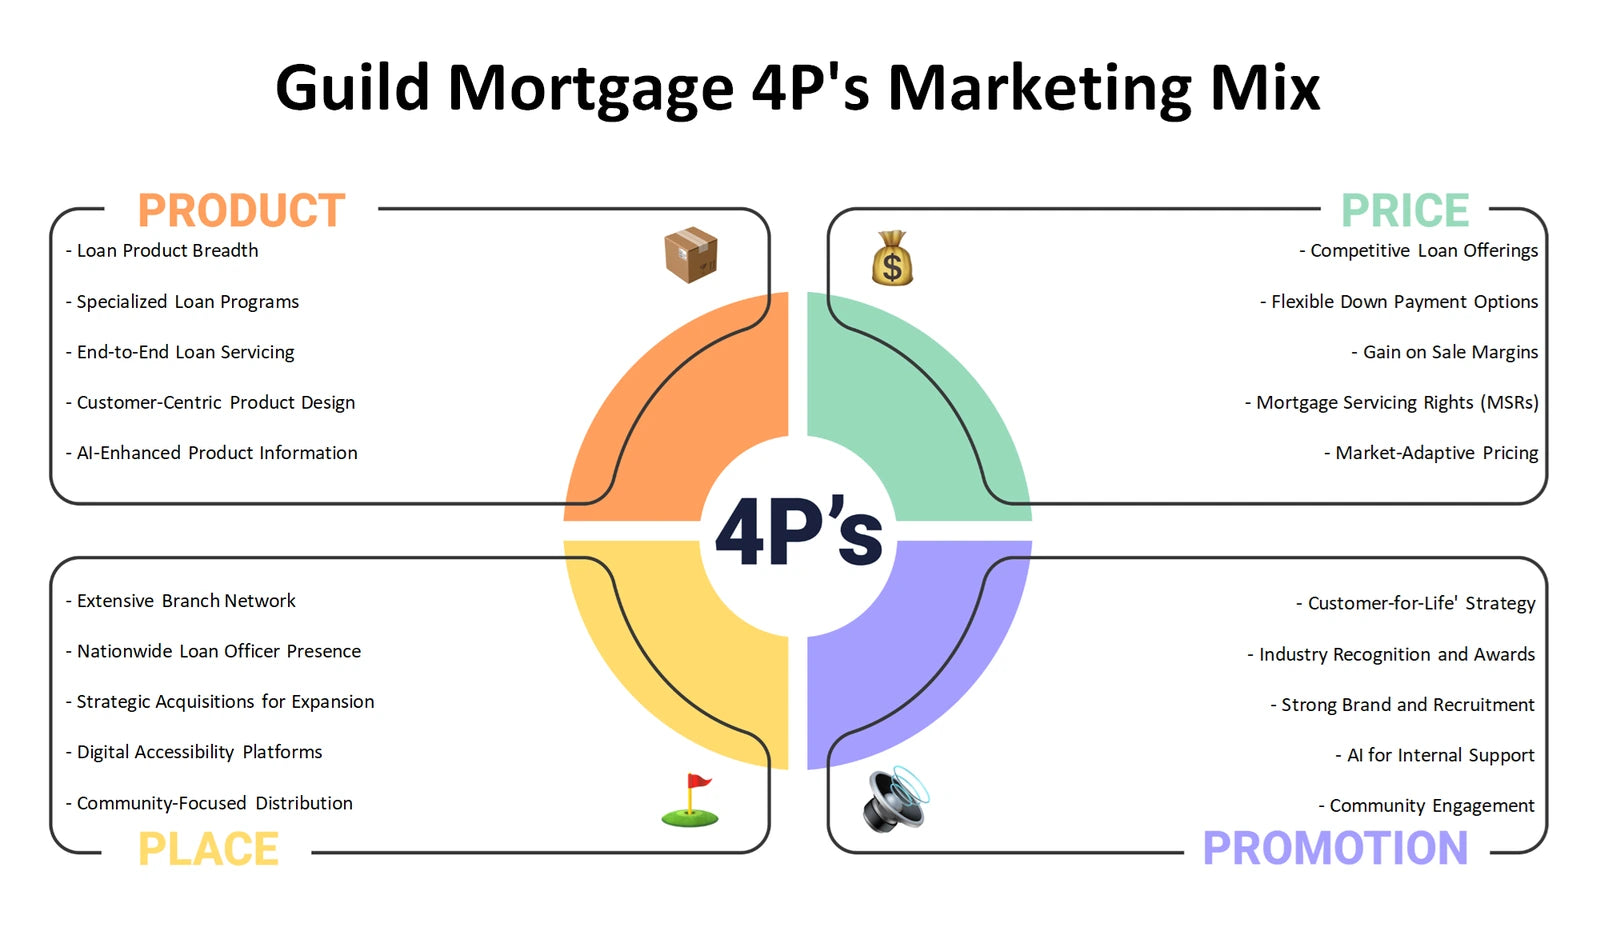
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external U.S. housing, policy and technology conditions should be monitored when evaluating Guild Mortgage's operating environment?
Guild Mortgage PESTLE analysis, also commonly written as PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal questions can include the continuing importance of government housing programs, consumer-protection expectations and lending compliance. Economic conditions may affect housing demand, affordability, funding costs and borrower confidence, but the framework should not be mistaken for a statement about current interest rates. Social factors include household formation, mobility and changing borrower preferences. Technology raises questions around digital application journeys, data security and process efficiency, while environmental considerations can intersect with property risk, resilience and community lending needs. These are analytical categories, not assertions that a particular policy or event has occurred.
- External scan. Separate policy, macroeconomic, social and property-related signals so that different drivers are not collapsed into one broad market assumption.
- Compliance horizon. Consider how legal and technological change may create both operational obligations and opportunities to improve borrower experience.
- Monitoring record. Use the Excel framework to log external factors and their possible relevance, with the Word analysis providing a reasoned starting context for review.
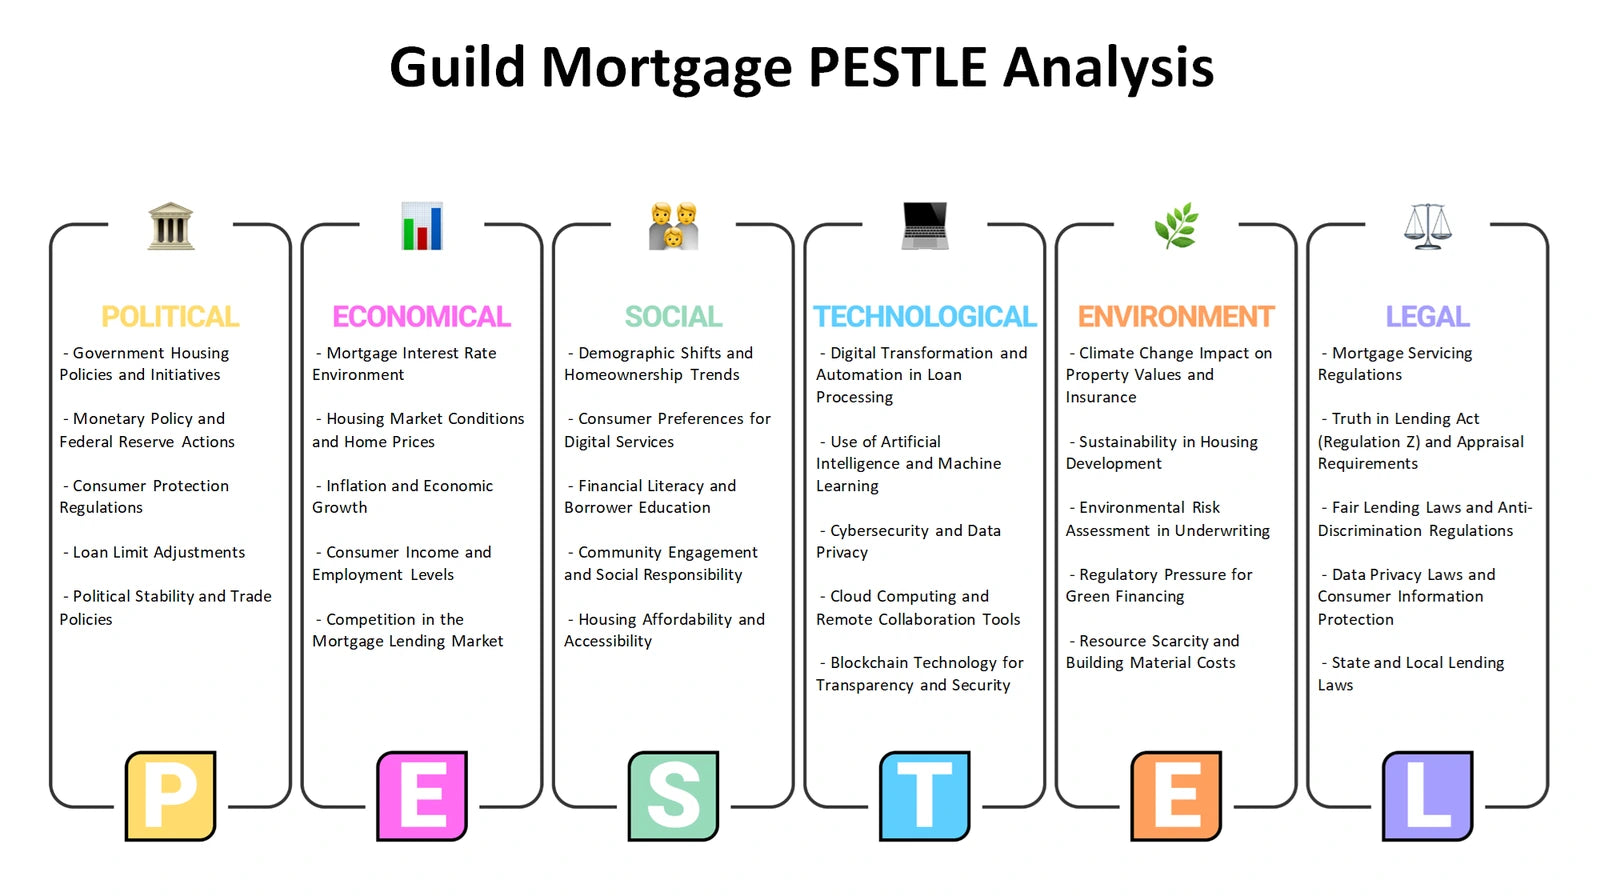
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside external mortgage-market opportunities and threats?
A Guild Mortgage SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. This distinction is especially useful for a lender whose potential capabilities may involve product knowledge, borrower support, partner relationships, lending operations and access to secondary-market liquidity, while internal constraints may include process complexity, capital requirements or execution capacity. Opportunities and threats belong outside the company: housing demand patterns, policy conditions, technological shifts, competitive pressure and economic uncertainty are examples to investigate. The framework does not declare these themes to be proven Guild Mortgage strengths, weaknesses, opportunities or threats. Instead, it helps users evaluate evidence and avoid treating an external market development as an internal capability.
- Classification discipline. Distinguish controllable operational capabilities from external housing, regulatory and capital-market conditions before drawing strategic implications.
- Trade-off view. Explore how potential government-program expertise and investor relationships could be weighed against dependency, complexity or changing market conditions.
- Actionable synthesis. Use Excel to sort evidence into the four SWOT areas, then consult the Word analysis to develop balanced discussion points rather than unsupported conclusions.
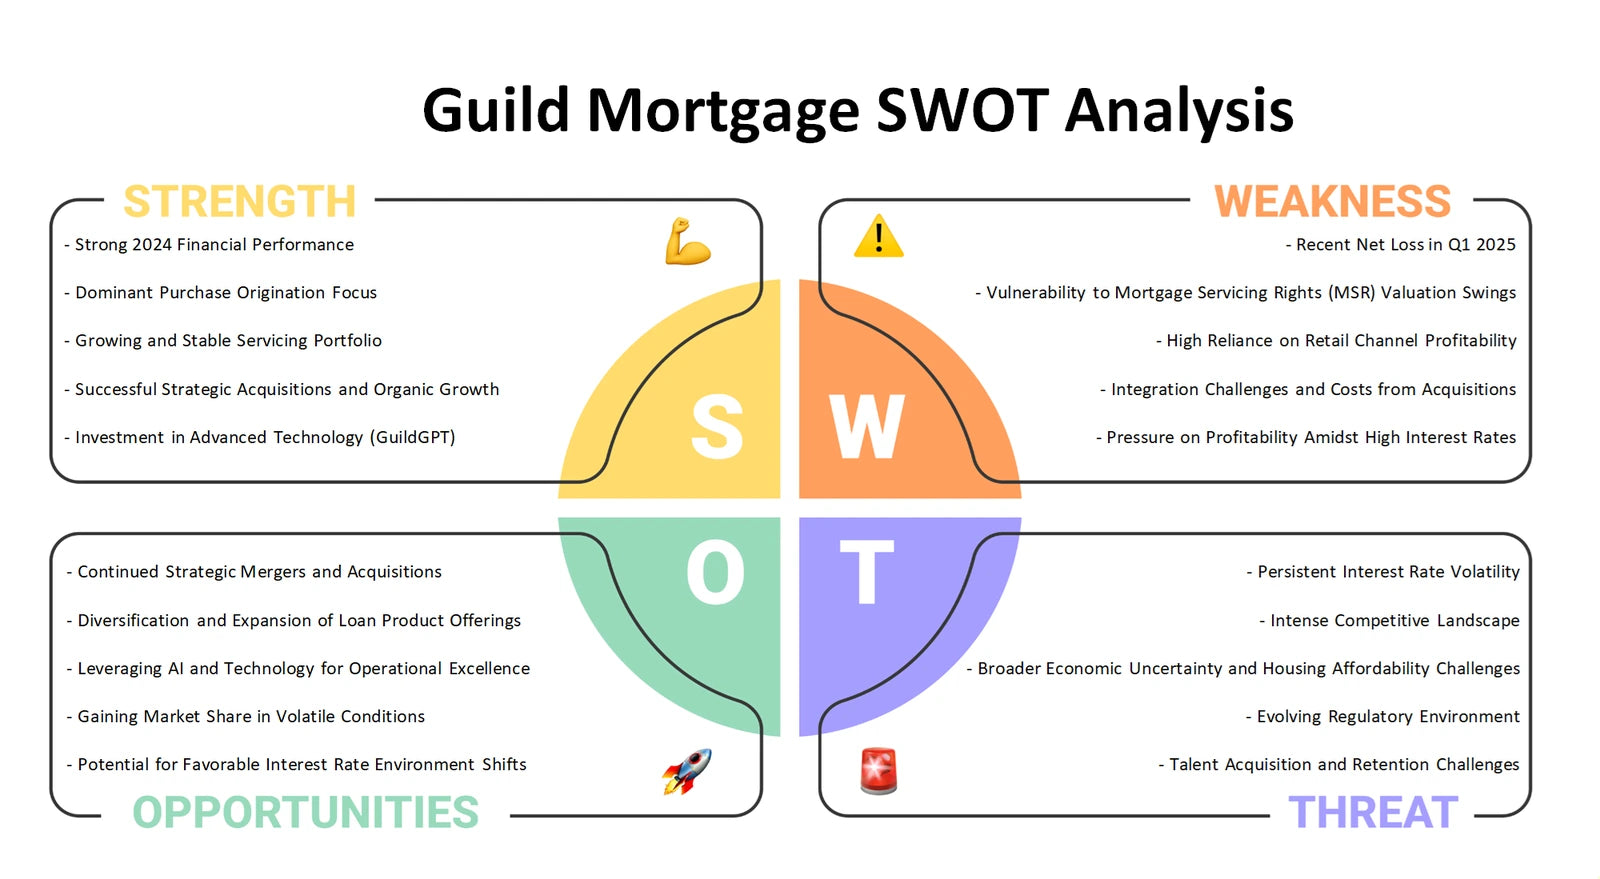
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring the six perspectives into one lending strategy discussion
Used together, the BCG Matrix, Business Model Canvas, Five Forces, Marketing Mix, PESTLE and SWOT lenses move from portfolio questions to operating logic, customer choices, industry pressure, external change and strategic fit. The Excel frameworks provide a structured way to organize comparisons, while the detailed Word files support deeper company-specific interpretation for Guild Mortgage.
Company background: Guild Mortgage — business-model context source.