

goeasy: Financial Services and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
goeasy Strategy Analysis Bundle
goeasy is a Canadian alternative financial company with lending activities serving consumers who may seek credit options outside conventional bank lending. Its business model depends on originating and servicing loans while maintaining access to capital to fund customer demand, making affordability, underwriting discipline and funding capacity important strategic questions.
The supplied company context describes relationships with financial institutions as important sources of lending capital and highlights regulatory compliance as central to trust and operational integrity. This bundle helps examine how those conditions shape portfolio priorities, customer value, competitive pressure and risk without presenting analytical assumptions as established company findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending activities or customer propositions merit capital, management attention and measured restraint?
A goeasy BCG Matrix provides a disciplined way to compare parts of a lending portfolio using market growth and relative market share. Rather than assuming that any product belongs in a quadrant, it tests whether a lending offer, customer route or servicing capability might function as a Star, Cash Cow, Question Mark or Dog. For an alternative lender, this matters because growth can consume funding, collections capacity and risk-management attention before it produces durable economics. The framework encourages a comparison between expansion potential and the resources required to support responsible lending.
- Portfolio logic. Compare possible product or customer-area priorities by their relative share position and the growth conditions around them, without treating loan volume alone as strategic strength.
- Capital trade-off. Consider where funding availability, credit performance monitoring and servicing effort could affect the attractiveness of maintaining, scaling or reviewing an activity.
- Working view. Use the Excel matrix to organise candidate activities and the Word analysis to record the evidence, assumptions and implications behind each potential quadrant discussion.
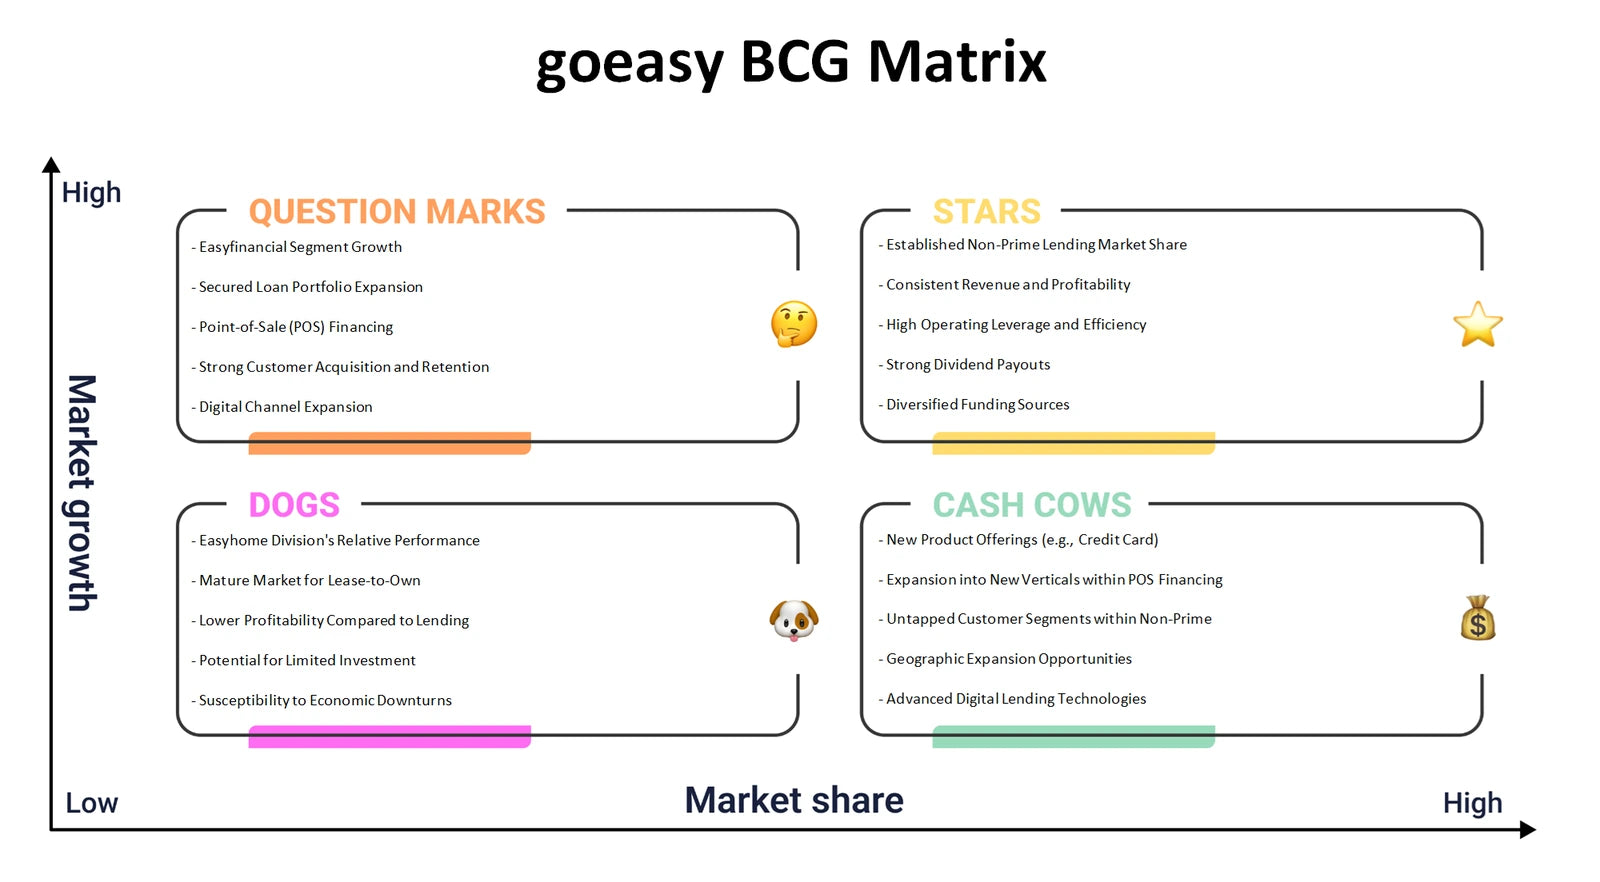
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, loan funding, service delivery and compliance connect to create value at goeasy?
The goeasy Business Model Canvas brings the operating logic of an alternative financial company into one connected view. It examines customer segments seeking credit alternatives, value propositions built around access to lending, channels through which customers engage, and customer relationships needed across the loan life cycle. It also connects revenue streams to key resources, key activities and key partnerships, including the relevance of financial-institution funding relationships. Finally, the cost structure can be considered alongside credit administration, technology, customer service and regulatory obligations. The point is not to presume the economics of any one offering, but to show how a change in one block can affect the others.
- Value connection. Trace how accessibility, lending decisions and customer support may shape the proposition for distinct customer segments while affecting revenue and relationship requirements.
- Funding dependence. Assess why dependable capital partnerships can influence the ability to originate loans, manage growth and balance cost structure with service delivery.
- Model mapping. Complete the Excel canvas block by block, then use the Word analysis to add narrative links, open questions and evidence for the nine building blocks.
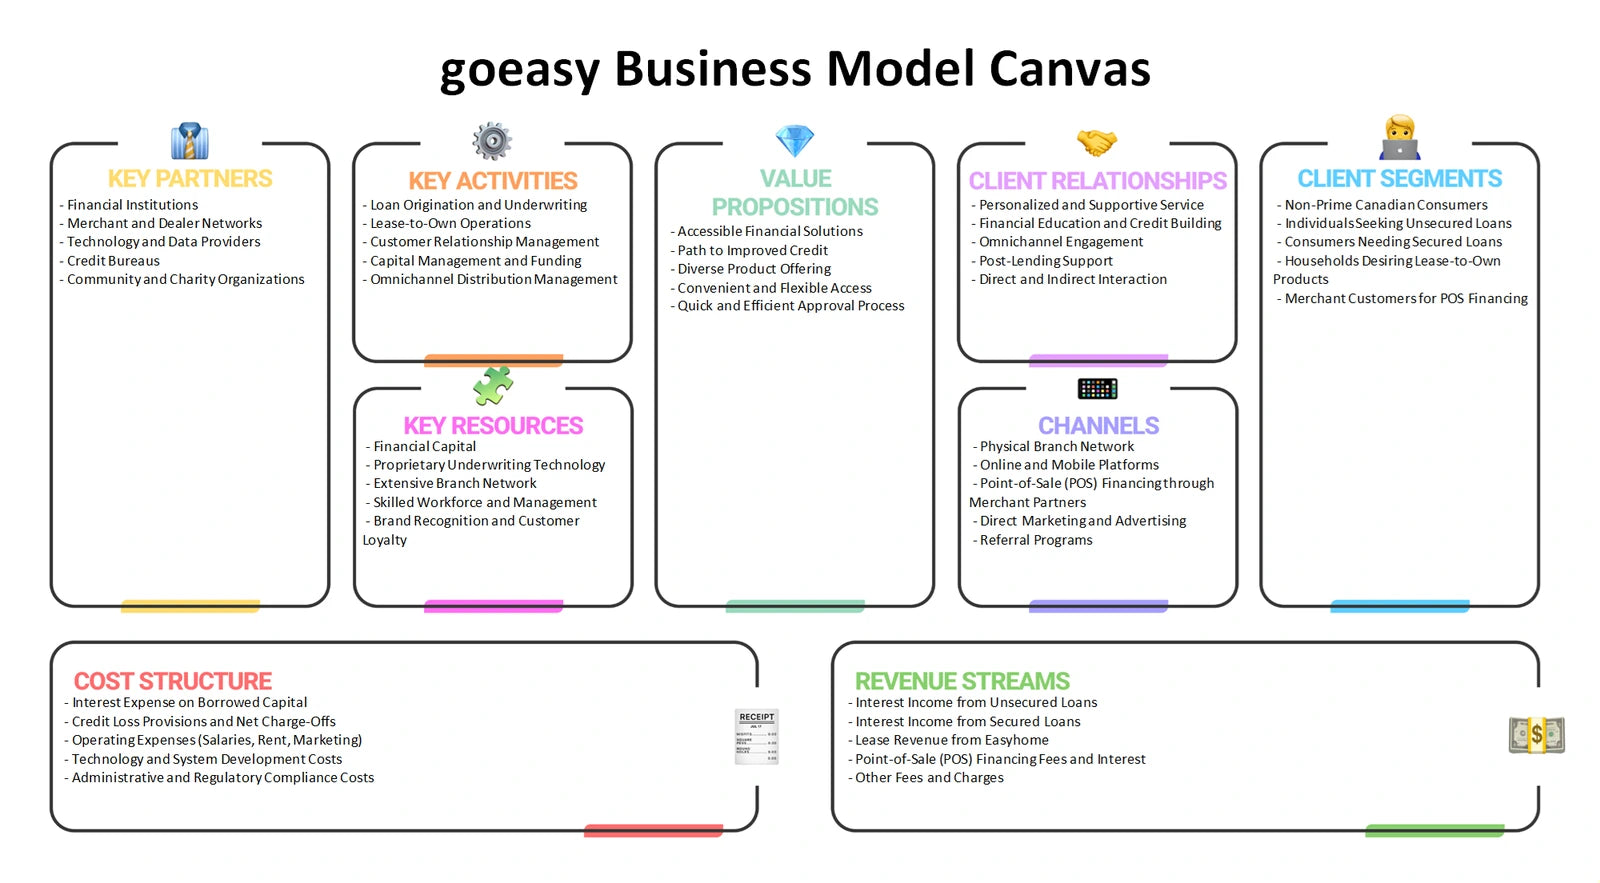
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can influence goeasy's ability to serve borrowers sustainably and earn acceptable returns?
goeasy Porter's Five Forces focuses on the structure around alternative consumer lending rather than on unsupported claims about named competitors. Rivalry concerns the intensity of choice among lending providers. Supplier power is especially relevant where access to capital from financial institutions and other funding sources affects lending capacity or cost. Buyer power considers how borrowers compare approval terms, repayment conditions and available alternatives. The threat of new entrants asks how technology, compliance requirements, capital access and trust barriers shape entry. Substitutes include other ways consumers may meet a short-term or longer-term credit need, not only direct lending rivals.
- Funding leverage. Explore how the terms, availability and diversity of capital sources could influence supplier power and the flexibility to support lending growth.
- Customer alternatives. Compare the practical appeal of alternative credit routes, conventional borrowing and non-lending options when assessing buyer power and substitutes.
- Pressure register. Use the Excel framework to organise evidence for each force and the Word analysis to explain how the forces may interact rather than assigning unsupported force scores.
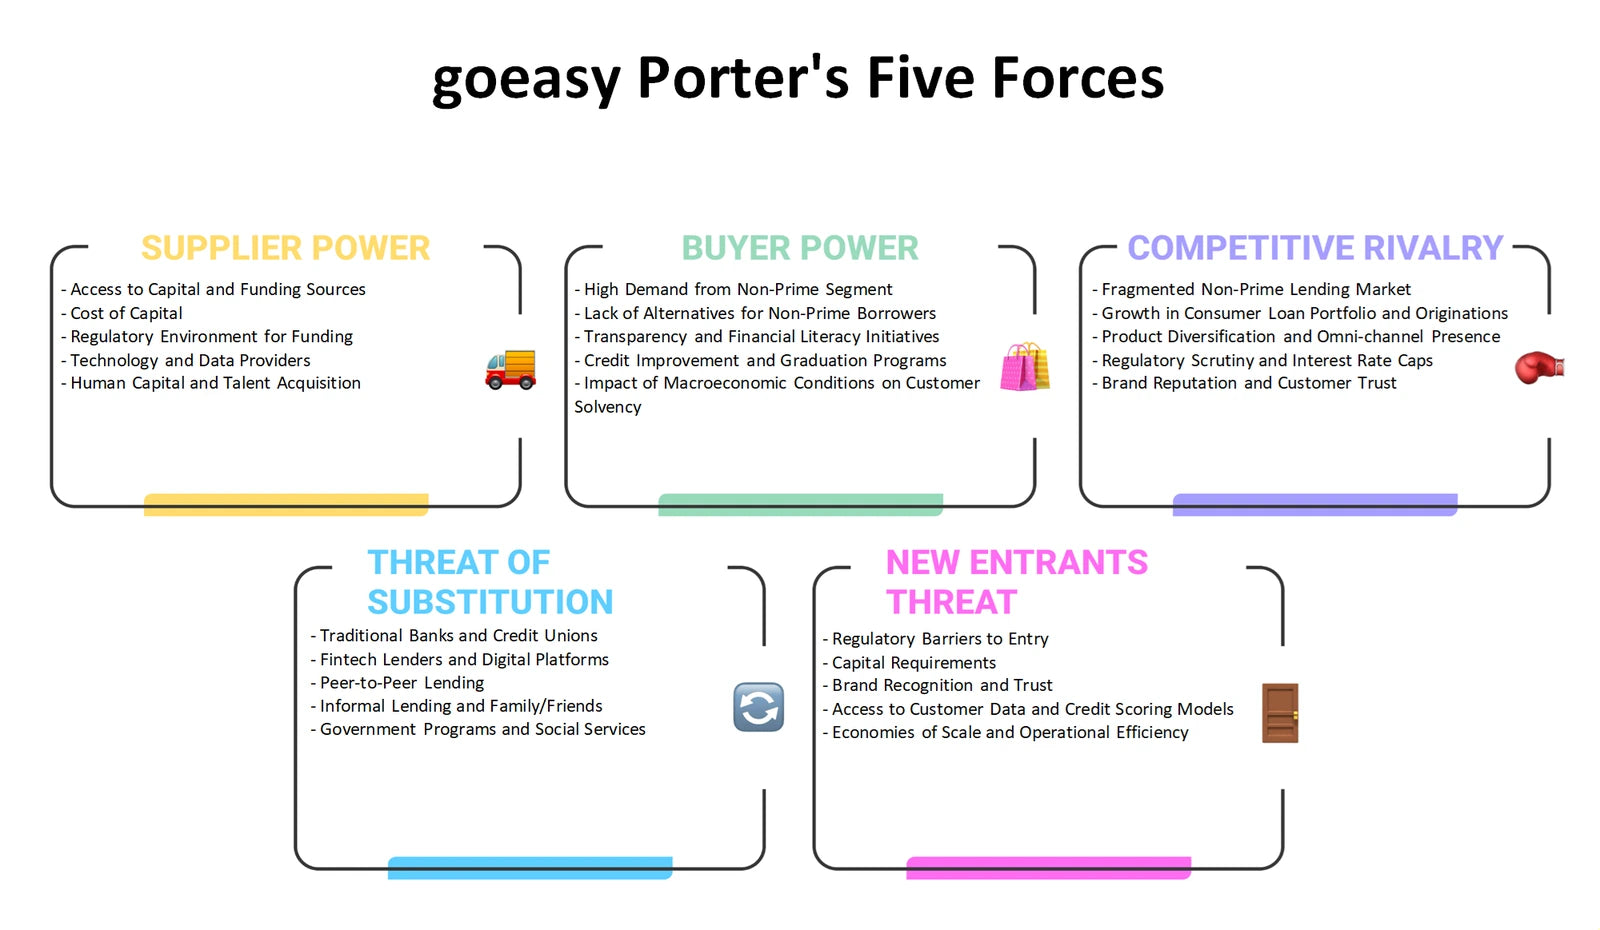
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can goeasy assess the fit between lending offers, customer communication and responsible access to credit?
The goeasy Marketing Mix examines Product, Price, Place and Promotion in a regulated consumer-finance setting. Product analysis considers how lending offers and service support address identified borrower needs. Price is broader than a headline rate: it can prompt examination of repayment terms, fees, affordability communication and the relationship between pricing logic and risk. Place considers the routes through which customers can learn about, apply for and manage lending products. Promotion addresses how messages can communicate access, obligations and customer value clearly without making unsupported promises. Together, the 4Ps help connect commercial choices to customer understanding and operational delivery.
- Offer clarity. Review how product features, application expectations and servicing touchpoints could be expressed for customers comparing different credit options.
- Responsible pricing. Examine whether pricing and repayment communications are understandable, comparable and aligned with the practical realities of a regulated lending relationship.
- Channel review. Use the Excel 4Ps layout to compare customer-facing choices, then consult the Word analysis to develop a written rationale for potential positioning and communication priorities.
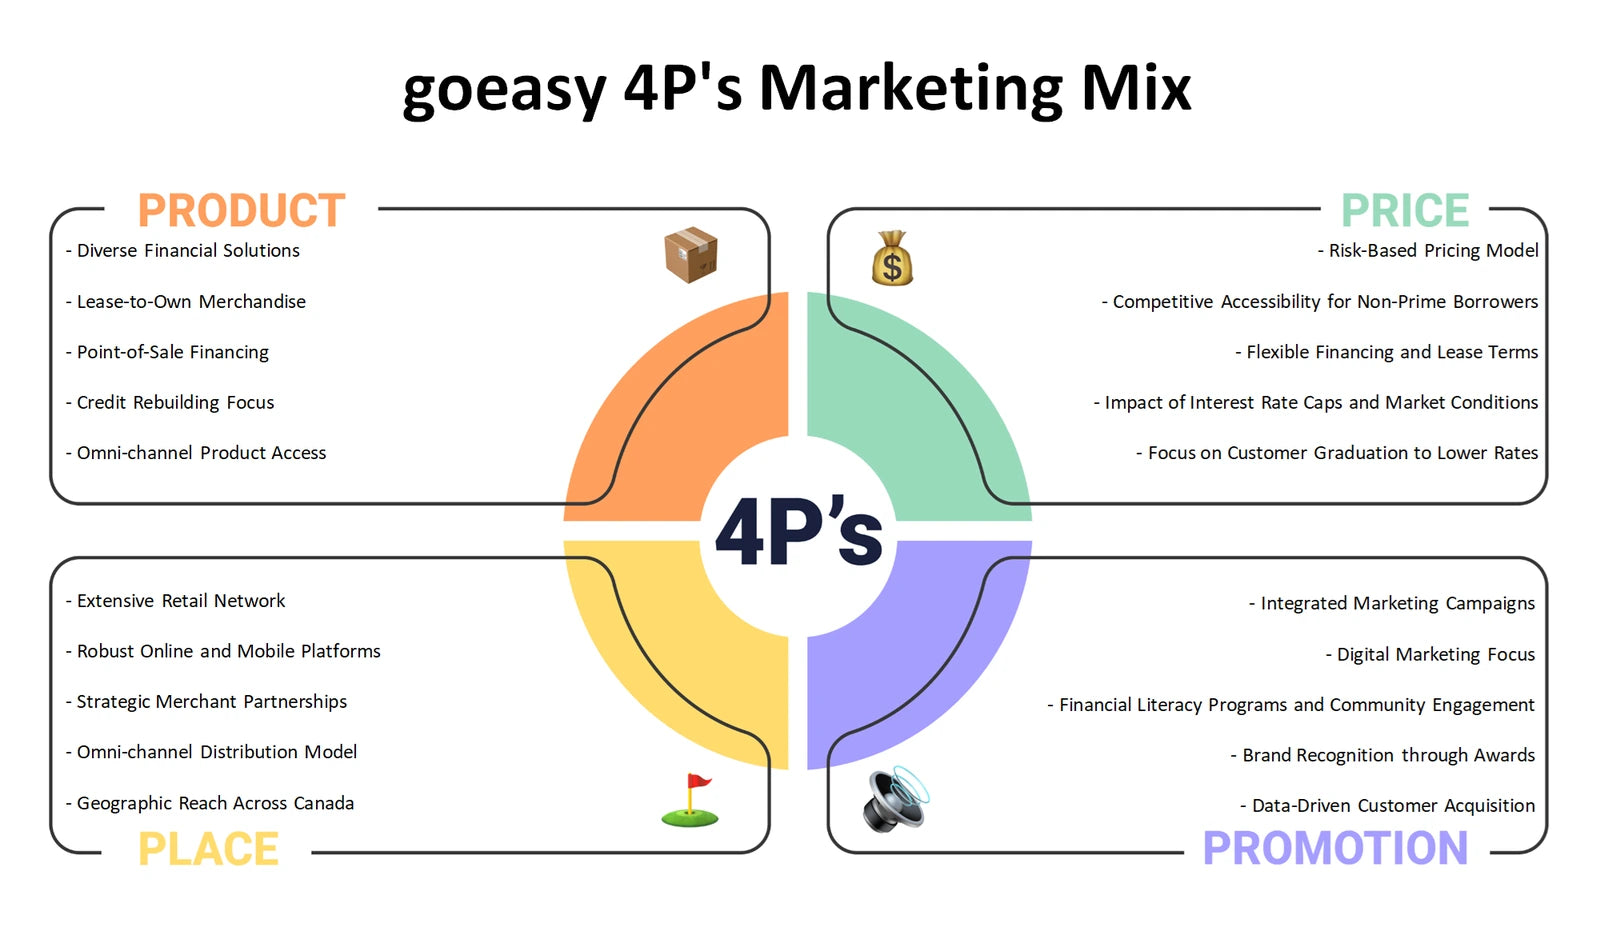
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter customer demand, funding conditions and compliance expectations for goeasy in Canada?
A goeasy PESTLE analysis, also commonly called PESTEL, separates external change from internal capability. Political factors can include public-policy priorities affecting financial services. Economic conditions may influence household budgets, borrowing demand, credit outcomes and the cost or availability of funding. Social factors help examine consumer trust, financial inclusion and attitudes toward non-bank credit. Technological change raises questions about digital service, data protection and operational resilience. Legal factors cover lending rules, consumer protection and compliance expectations, while environmental considerations can include disruption risks and expectations around resource use. These are analytical categories, not claims that a particular policy or market change has occurred.
- Canadian context. Consider how external conditions relevant to Canadian consumer finance could affect borrowers, capital providers and the operating environment at different times.
- Change signals. Distinguish a possible interest-rate, policy or technology question from a documented development before drawing strategic implications.
- Scenario discipline. Use the Excel framework to sort external signals by category and the Word analysis to build concise scenarios, assumptions and monitoring questions.
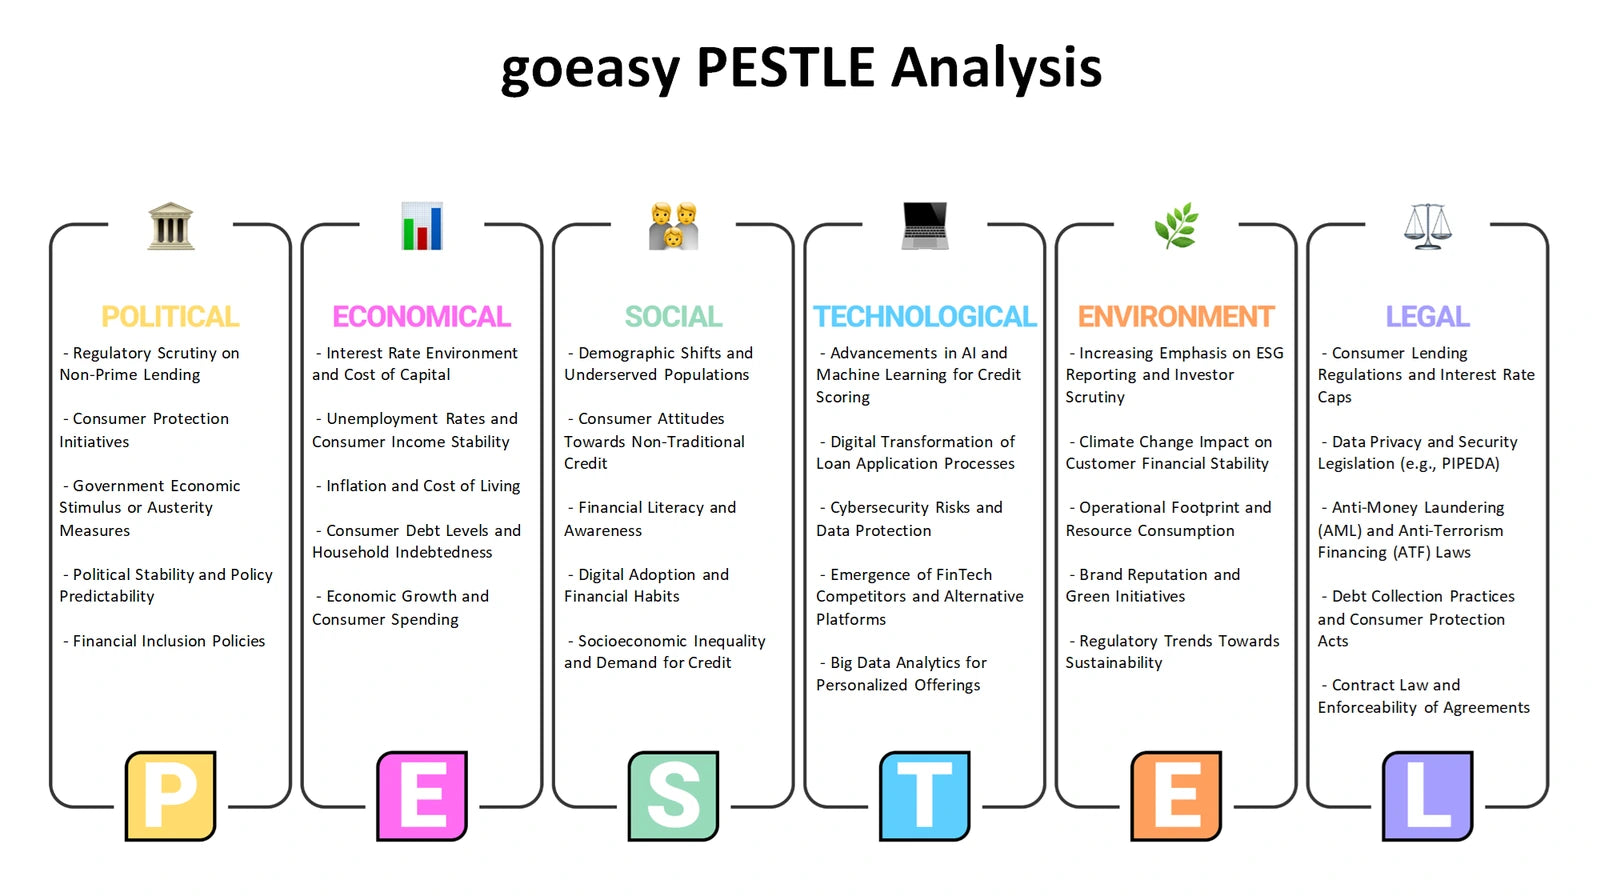
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can goeasy distinguish its potential internal advantages and constraints from external opportunities and threats?
A goeasy SWOT analysis helps keep internal and external issues in their proper categories. Strengths and weaknesses concern capabilities, resources, processes and constraints within the business. The supplied context makes funding relationships and regulatory discipline useful themes to test as possible internal capabilities, while reliance on capital access or complex credit operations may warrant examination as potential constraints. Opportunities and threats arise outside the company, such as changing customer needs, technology, competitive conditions or regulation. The framework does not declare these themes proven findings; it helps users document which evidence supports them and where uncertainty remains.
- Internal evidence. Separate potential strengths in customer service, funding access or compliance execution from weaknesses that could involve concentration, cost or operating complexity.
- External exposure. Relate opportunities and threats to conditions identified through PESTLE and Five Forces instead of misclassifying market changes as internal attributes.
- Decision synthesis. Populate the Excel SWOT grid with concise evidence points, then use the Word analysis to connect the most material combinations to practical strategic questions.
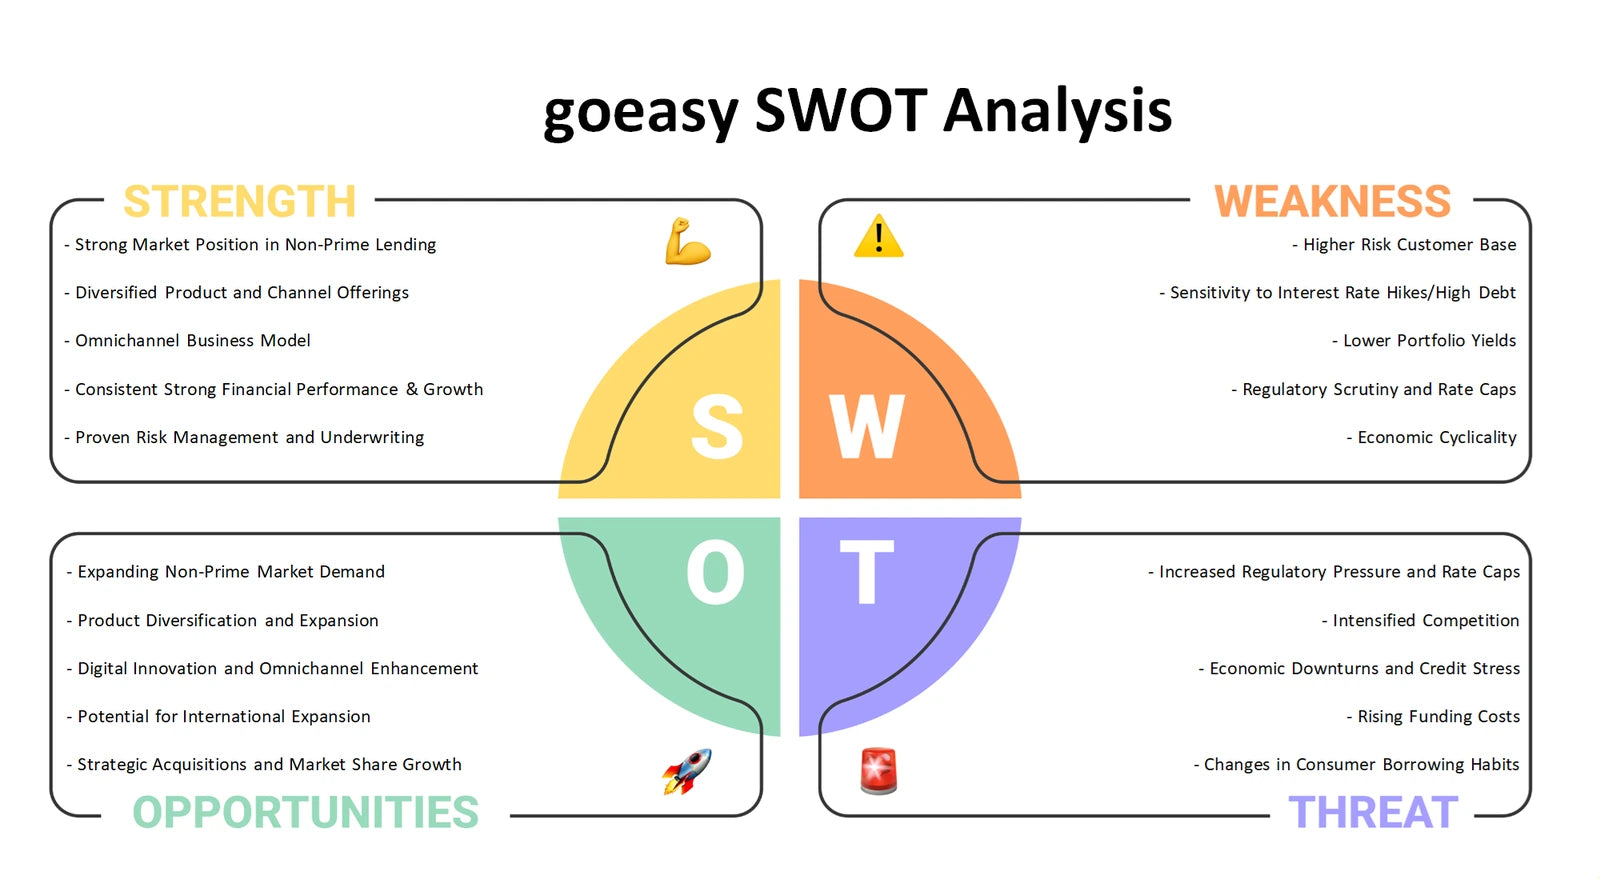
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of goeasy's strategic choices
Used together, the six perspectives move from portfolio priorities and business-model connections to market pressure, customer-facing choices, external conditions and strategic trade-offs. The Excel frameworks provide a practical structure for organising comparisons, while the detailed Word analysis supports more considered interpretation of goeasy's lending model, funding context and regulated Canadian environment.
Company background: goeasy — Wikidata entity profile.