

Global Indemnity (GBLI): Underwriting and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Global Indemnity (GBLI) Strategy Analysis Bundle
This bundle uses the supplied Global Indemnity (GBLI) business context: a specialty-insurance operation built around experienced underwriters, class-specific knowledge, underwriting authority frameworks and broker relationships. That context points to an insurance model in which selecting, pricing and servicing appropriate risks matters as much as building a disciplined portfolio.
The available context also highlights policy administration, claims systems, data infrastructure and external model or integration costs. The six analyses help examine how underwriting classes should be prioritised, how broker-led distribution supports value creation, and how capital, technology and market pressures may affect strategic choices without assuming unverified financial results or portfolio outcomes.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which specialty classes, distribution niches or service propositions deserve capital and management attention as growth and competitive position change?
A Global Indemnity (GBLI) BCG Matrix helps organise a specialty-insurance portfolio around two distinct questions: market growth and relative market share. Rather than assuming that any underwriting class belongs in a quadrant, it provides a disciplined way to compare classes, broker-served niches or related offerings against the conditions needed for Stars, Cash Cows, Question Marks and Dogs. For an insurer, the practical issue is not simply premium volume; it is whether growth can be pursued without weakening risk selection, pricing integrity or available underwriting capacity.
- Portfolio logic. Compare growth opportunities with relative competitive position before treating expanding classes as automatic priorities.
- Capital discipline. Consider where specialist underwriting attention, systems support and capacity may be maintained, tested, reduced or redeployed.
- Working view. Use the Excel framework to place and compare candidate portfolio areas, then use the Word analysis to document the assumptions behind each position.
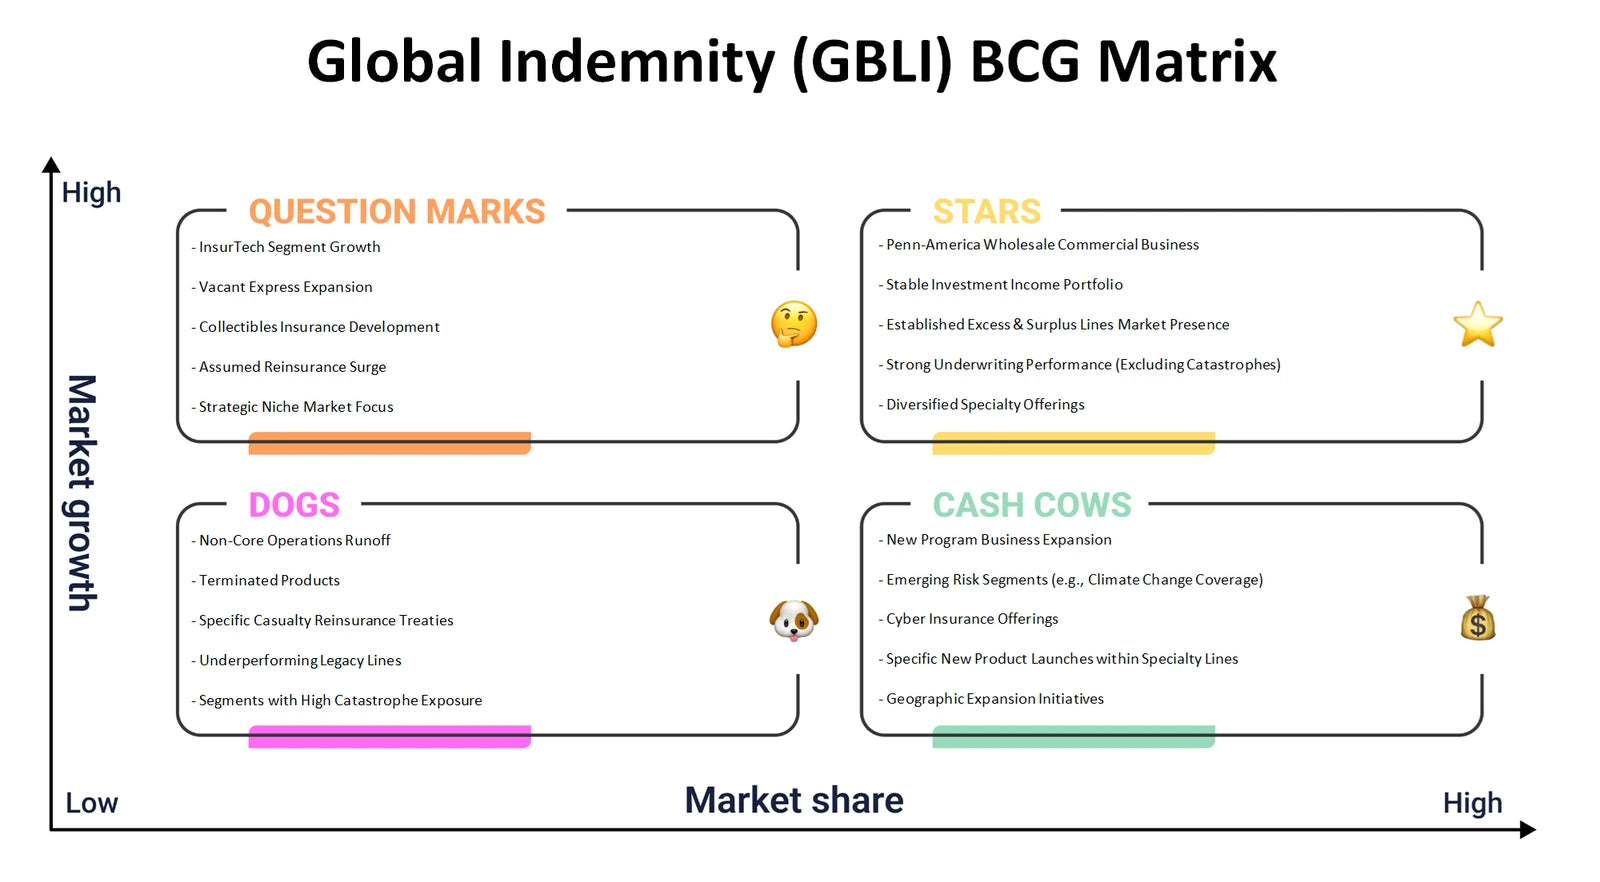
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do underwriting expertise, broker access, operational systems and capital commitments fit together to create value for insured customers?
The Global Indemnity (GBLI) Business Model Canvas connects the business model rather than viewing underwriting, distribution and operating costs separately. It helps map customer segments and value propositions alongside channels and customer relationships, including the role broker relationships may play in bringing suitable risks to the business. Revenue streams can be considered with key resources such as underwriting expertise and data capabilities; key activities such as risk selection, policy administration and claims handling; key partnerships; and the cost structure created by systems, vendor models and integrations. Seeing all nine building blocks together makes dependencies and trade-offs easier to discuss.
- Value chain. Trace how specialist class knowledge and formal decision frameworks may support a consistent proposition from submission through policy and claims activity.
- Economic links. Examine how premium-related revenue logic must support the people, technology, partnerships and recurring operating costs required to deliver service.
- Model workshop. Populate the Excel blocks with working hypotheses and use the Word analysis to explain relationships, dependencies and questions requiring validation.
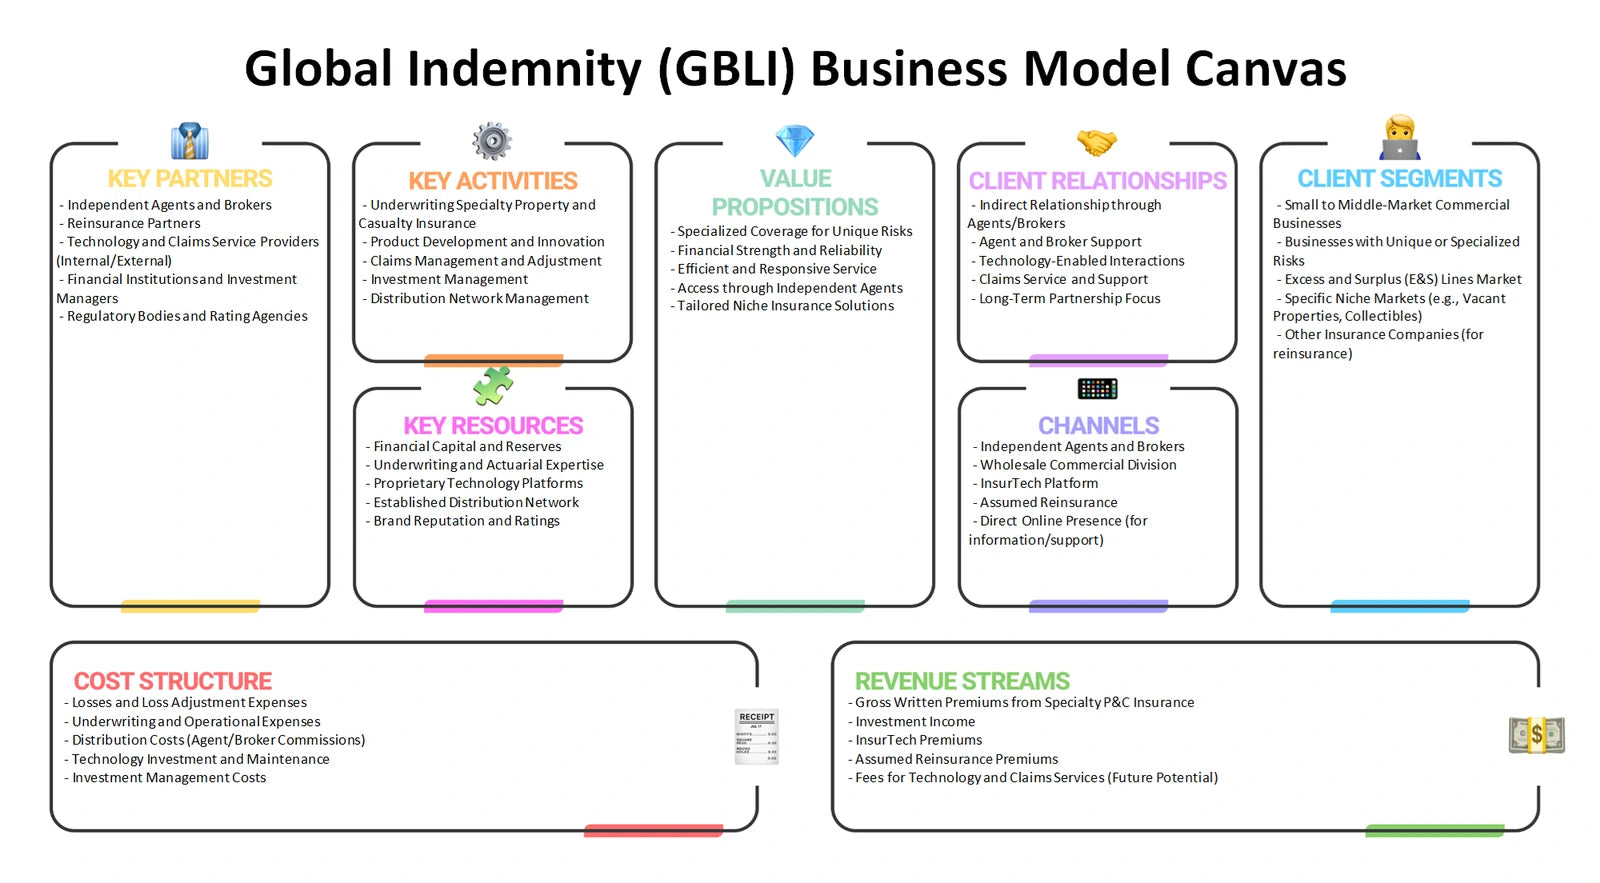
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can affect specialty-insurance pricing, access to distribution, underwriting capacity and the attractiveness of selected risk classes?
Global Indemnity (GBLI) Porter's Five Forces focuses on the competitive environment around specialty insurance rather than claiming a force score or naming unverified competitors. Rivalry can shape pricing and service expectations. Buyer power may arise through sophisticated insureds, intermediaries or concentrated placement relationships. Supplier power may need to be considered where reinsurance capacity, specialist data, technology providers or external service partners are important. Threats from new entrants can be tested against regulatory, capital and expertise barriers, while substitutes include self-insurance, captives, risk retention and alternative methods of financing exposure rather than only direct insurance rivals.
- Pricing pressure. Assess where competitive intensity could challenge underwriting discipline or make differentiated specialist knowledge more valuable.
- Dependency exposure. Compare potential leverage held by distribution, capacity, technology and data counterparties that support the operating model.
- Scenario comparison. Use Excel to rate and contrast force-related considerations by market or class, with the Word analysis providing the strategic rationale for discussion.
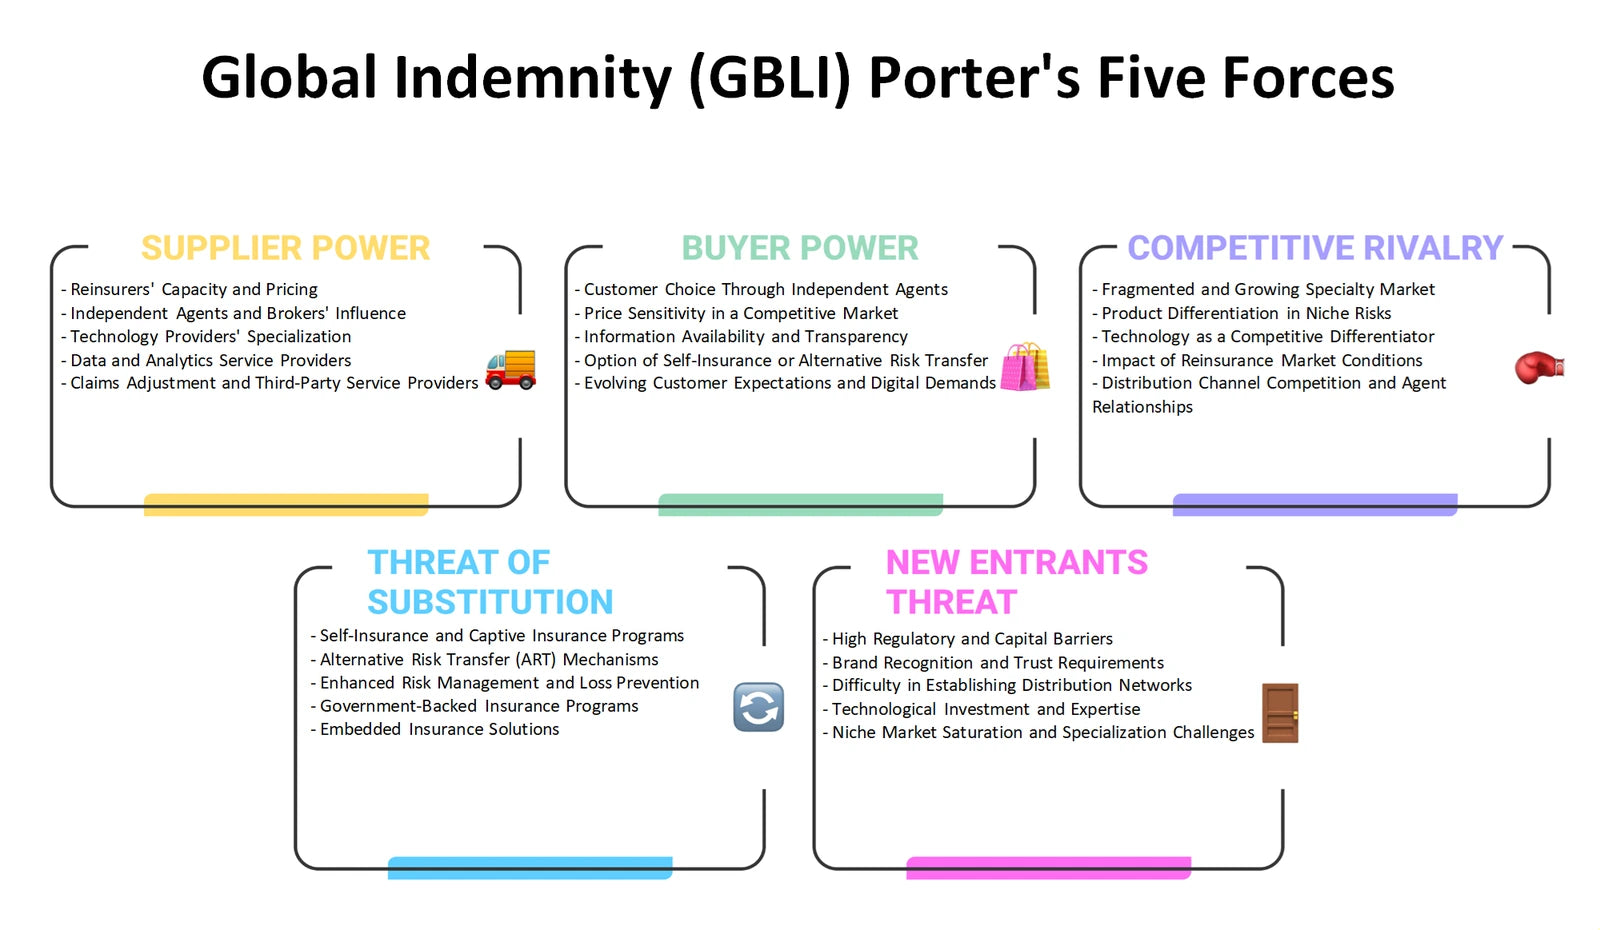
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a broker-oriented specialty-insurance proposition align its product design, pricing approach, routes to market and communications?
The Global Indemnity (GBLI) Marketing Mix examines Product, Price, Place and Promotion in a context where the offering is an insurance promise supported by underwriting judgment and service delivery. Product analysis can consider risk classes, coverage design, policy service and claims experience without inventing specific products. Price can examine premium adequacy, risk selection and the trade-off between growth and pricing integrity. Place looks at broker relationships, submission flows and operating channels, while Promotion considers how underwriting expertise, authority discipline and a clear appetite may be communicated to appropriate intermediaries and customers.
- Product fit. Test whether the risk appetite and service proposition are clear enough for the customer needs and broker submissions being targeted.
- Commercial consistency. Compare pricing logic with the distribution route, underwriting authority and level of service required to sustain the proposition.
- Go-to-market plan. Use the Excel structure to organise 4Ps decisions and the Word analysis to record the reasoning, trade-offs and evidence to investigate.
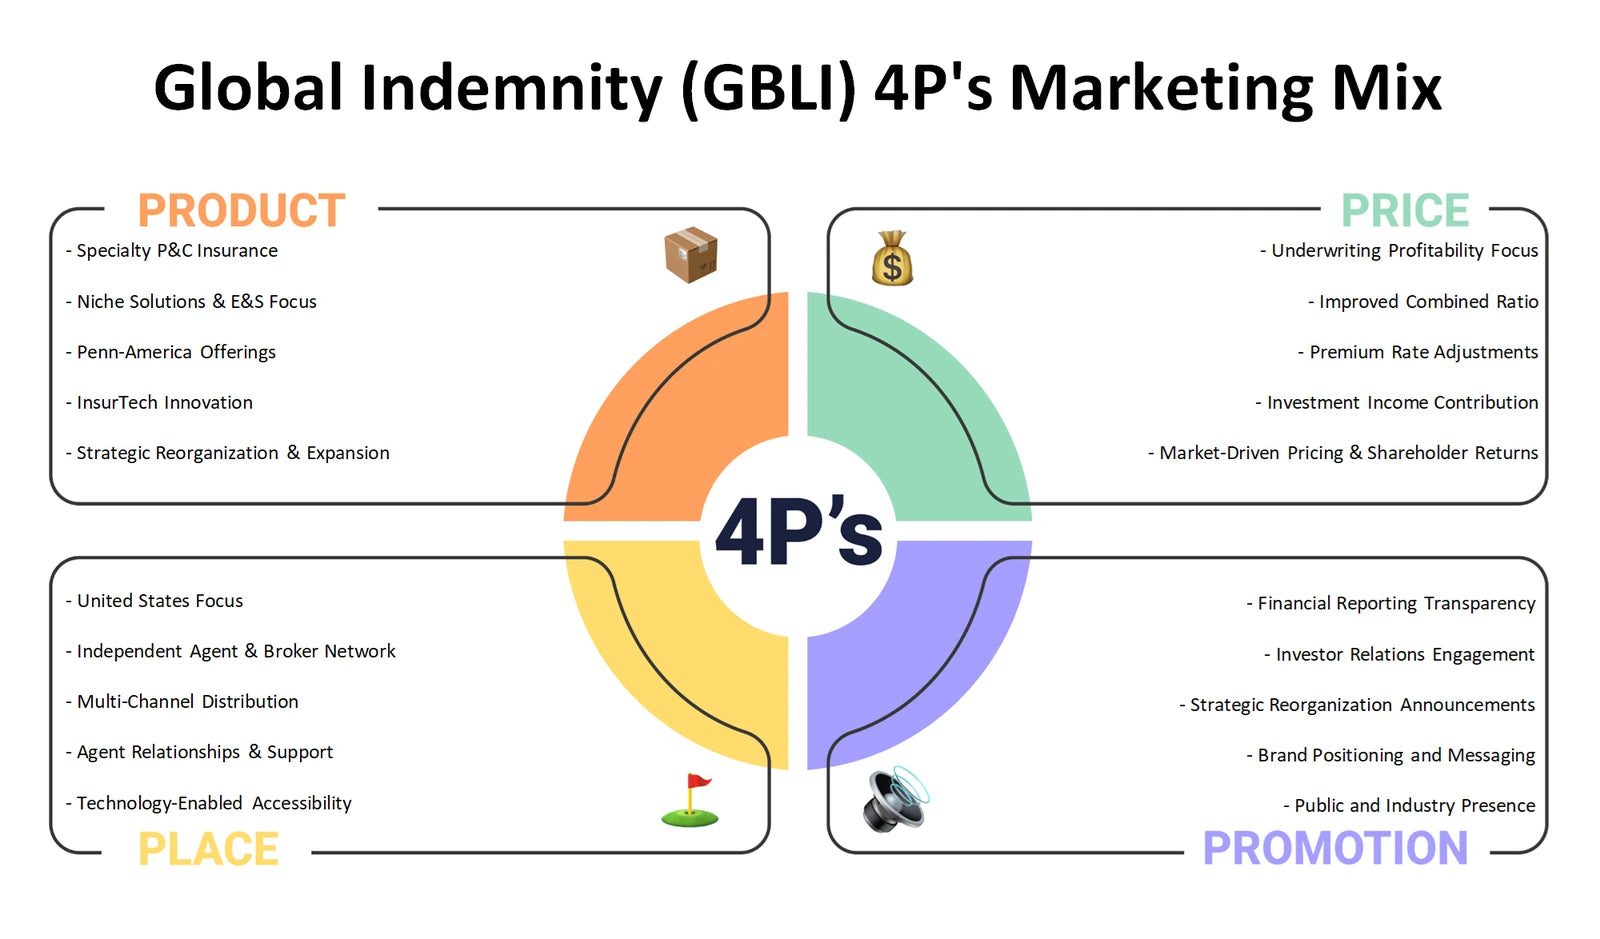
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored because they may alter specialty-risk demand, underwriting conditions, operating costs or compliance expectations?
A Global Indemnity (GBLI) PESTLE analysis, also commonly called PESTEL, separates external drivers from internal performance assumptions. Political factors can include public-policy and supervisory direction in applicable jurisdictions. Economic questions may cover inflation, insurance affordability, investment conditions and the cost of capacity. Social developments can change risk awareness and customer expectations, while technological change can affect data quality, policy administration, claims processes and model-vendor reliance. Legal analysis addresses evolving obligations and dispute exposure; environmental factors help frame physical, transition and catastrophe-related risk considerations where relevant to the portfolio. These are questions to assess, not claims that a particular change has occurred.
- External watchlist. Distinguish macroeconomic, regulatory, technological and environmental signals that could affect different underwriting classes in different ways.
- Operating implications. Connect external shifts to possible consequences for data infrastructure, claims capability, pricing assumptions and governance requirements.
- Monitoring tool. Use Excel to log drivers, relevance and review priorities, then use the Word analysis to develop context for management discussion.
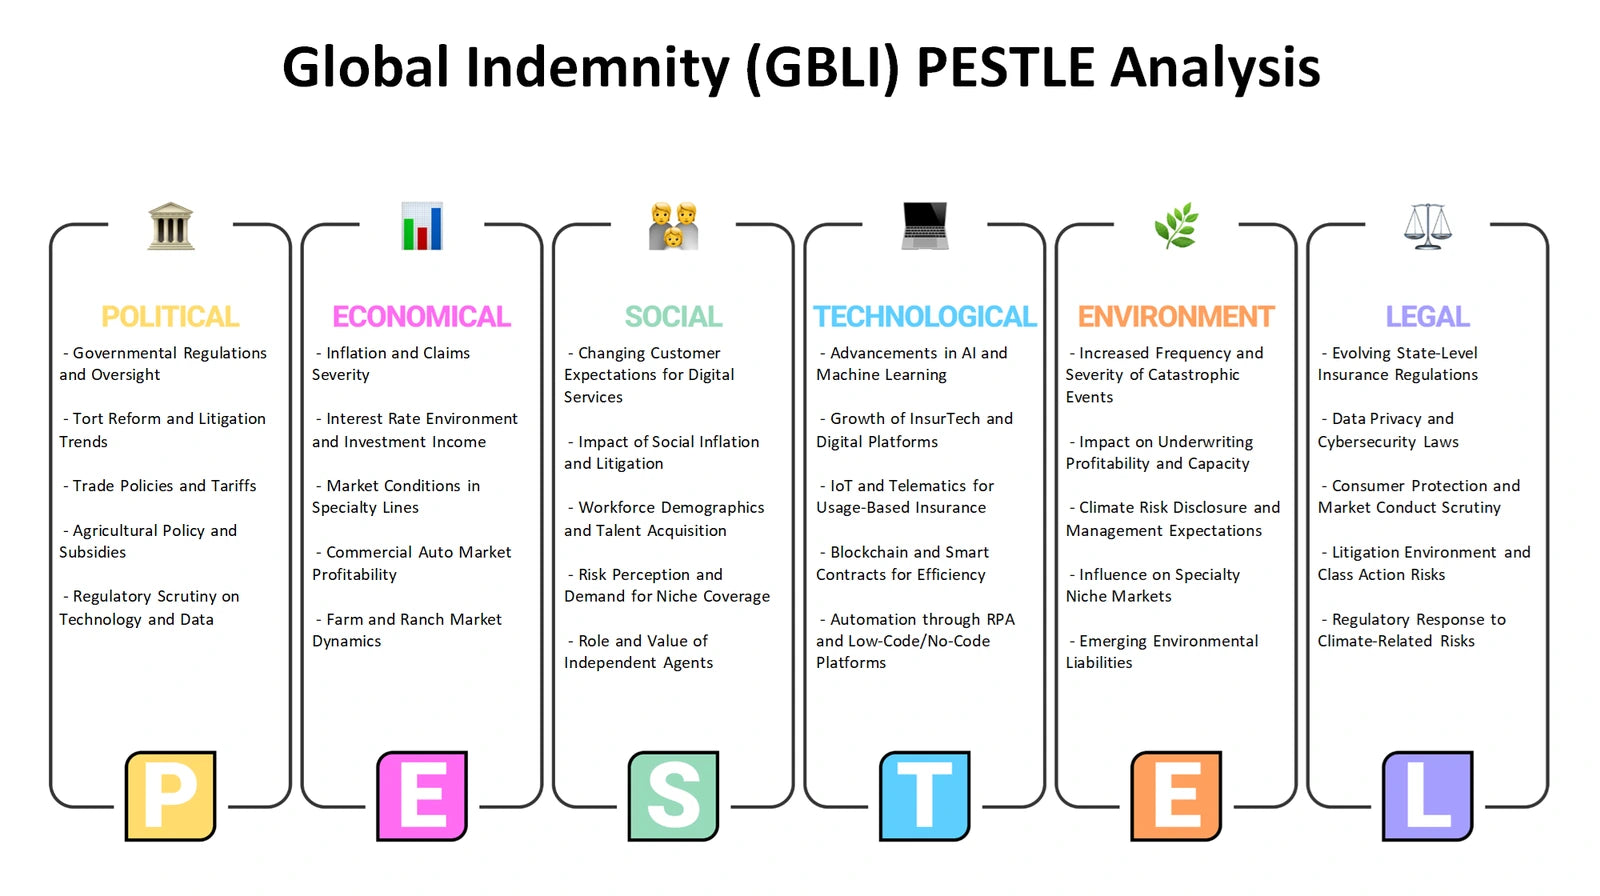
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Global Indemnity (GBLI) distinguish internal underwriting and operating capabilities from external opportunities and threats?
The Global Indemnity (GBLI) SWOT analysis provides a disciplined boundary between internal factors and external conditions. The supplied business context highlights experienced specialty underwriters, formal authority frameworks, broker relationships and ongoing exposure training as capabilities worth evaluating as potential strengths. Systems dependence, recurring technology and vendor costs, capacity constraints or execution complexity may be areas to investigate as possible weaknesses rather than established conclusions. Opportunities belong outside the business, such as attractive unmet risk needs or improved operating tools; threats include competitive pricing, changing exposure patterns, regulatory demands and market volatility. Keeping categories accurate prevents opportunities from being mistaken for current strengths.
- Capability test. Examine whether specialist knowledge, governance and broker connectivity are durable advantages or capabilities requiring continued investment.
- Risk separation. Keep internal process limitations distinct from external market, regulatory and risk-environment pressures when setting priorities.
- Action mapping. Use the Excel matrix to capture evidence and ownership questions, while the Word analysis helps turn linked themes into a coherent strategic narrative.
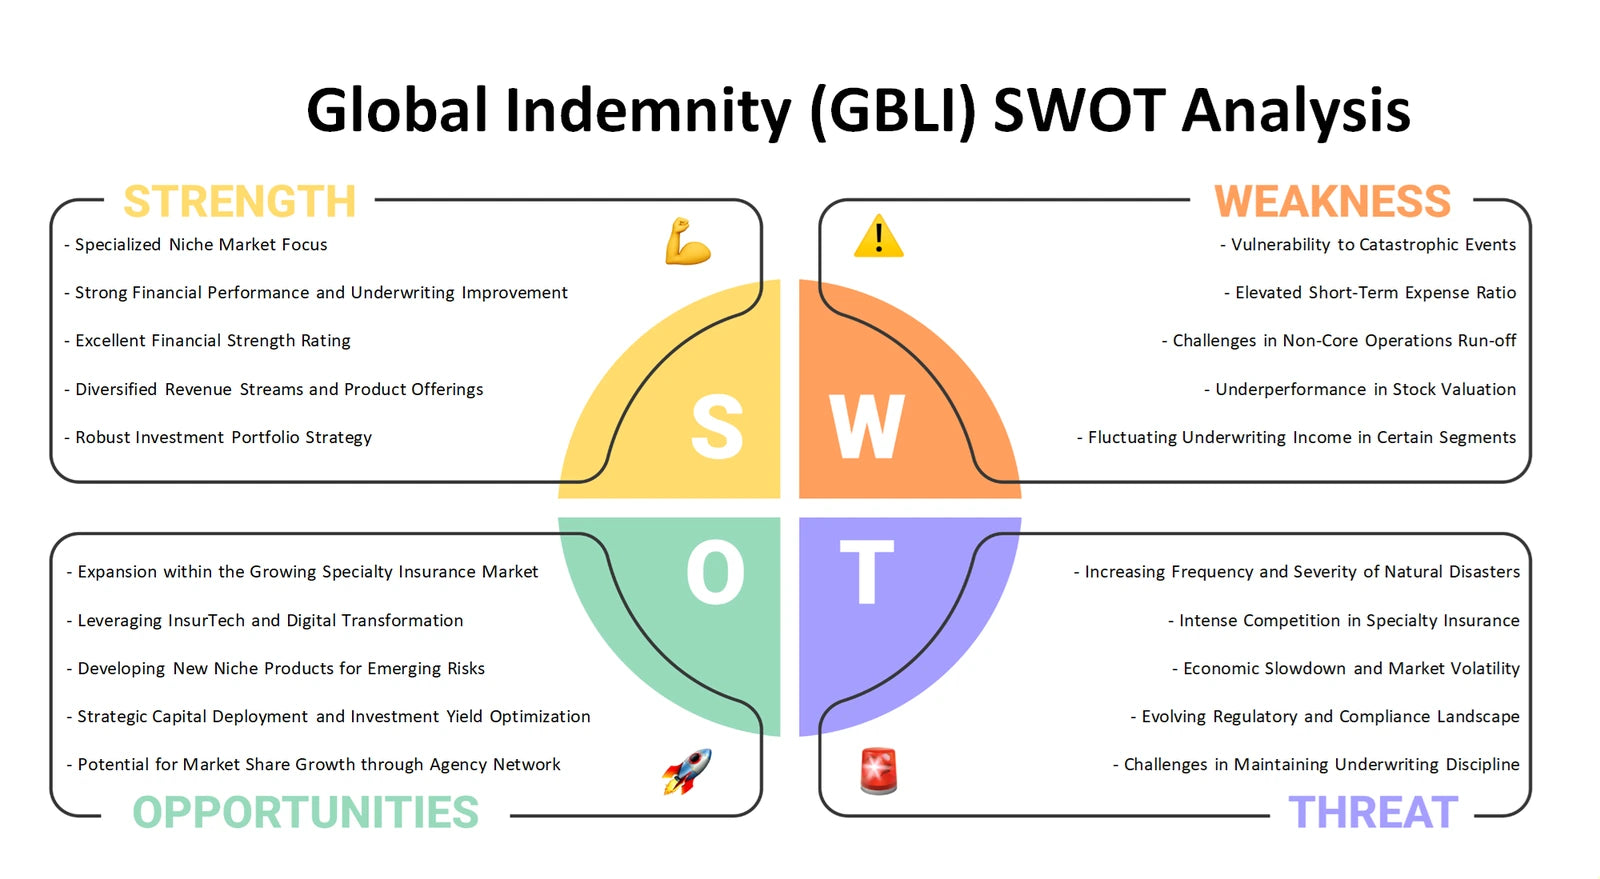
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect underwriting discipline with the wider strategic picture
Together, the six perspectives allow Global Indemnity (GBLI) to be examined from portfolio, business-model, competitive, commercial, external-environment and capability angles. The Excel frameworks provide structured places to compare assumptions and organise discussions, while the detailed Word analyses help explain why the questions matter for specialty underwriting, broker relationships, operational infrastructure and capital-aware decision-making.
Company background: Global Indemnity (GBLI) — product context page.