

Fusion Microfinance: Lending Economics and Agricultural Demand – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Fusion Microfinance Strategy Analysis Bundle
Fusion Microfinance is presented in the supplied product context as a microfinance business centred on lending, client outreach and risk controls. That context describes serving borrowers whose income may be informal, while reporting repayments to credit bureaus can help build a formal repayment record. It also highlights household-income diversity and crop or livestock insurance as risk topics relevant to portfolio resilience.
The supplied context does not independently establish a legal issuer, geography or current financial reporting period, so this bundle focuses on supported operating themes rather than unverified company results. It helps users examine how lending propositions, client trust, credit access, funding discipline and external conditions can be connected in practical strategic decisions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending propositions or client-focused initiatives deserve priority when resources must be allocated carefully?
A Fusion Microfinance BCG Matrix helps separate the language of portfolio priority from assumptions about performance. It tests possible business units, such as lending propositions, client segments, service models or outreach initiatives, against market growth and relative market share. The familiar Stars, Cash Cows, Question Marks and Dogs are analytical categories, not claims about Fusion Microfinance’s current position. For a lender working with customers who may be building formal credit histories, the useful question is whether resources should support expansion, protect dependable activity, investigate uncertain opportunities or reduce effort where strategic fit is weak. The framework encourages comparable evidence before drawing that conclusion.
- Portfolio boundaries. Define comparable units carefully so that a customer segment, product approach or delivery initiative is not mistaken for a whole company result.
- Growth versus position. Compare the attractiveness of a lending opportunity with its relative competitive standing, while keeping unverified market-share assumptions visible.
- Structured prioritisation. Use the Excel framework to map candidate priorities, then use the Word analysis to record the evidence, caveats and resource questions behind each placement.
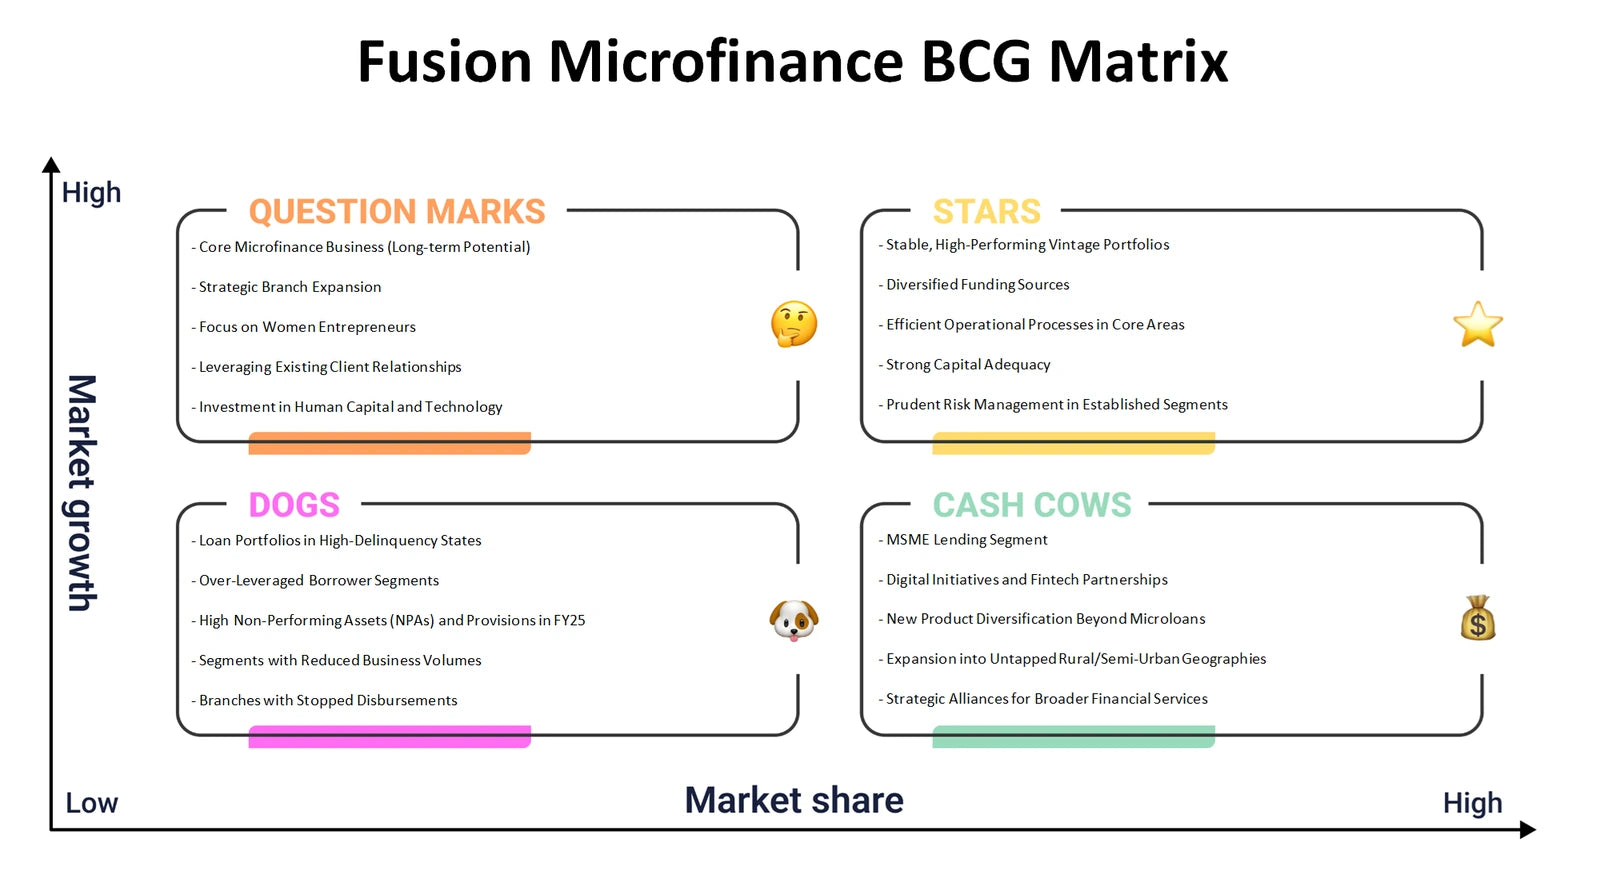
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How can lending, trust-building and credit-history creation work together as one coherent client and revenue model?
The Fusion Microfinance Business Model Canvas connects all nine building blocks rather than treating lending as a standalone product. It examines customer segments and value propositions alongside channels and customer relationships: for example, how outreach and repayment support may help clients engage with formal credit. It also considers revenue streams, key resources, key activities, key partnerships and cost structure. Repayment reporting to bureaus is particularly relevant because it links a client benefit beyond immediate funding to the operating capabilities, data processes and relationship management that may be needed to deliver it. The canvas does not assume any particular partnership, pricing model or channel mix; it gives those choices a single place for comparison.
- Client-value logic. Relate access to credit, repayment history and borrower support to the needs of distinct customer groups rather than using one generic client profile.
- Economic connections. Examine how funding, operations, servicing, risk control and collection costs interact with lending-related revenue streams.
- Model alignment. Complete the Excel canvas as a one-page working map, using the Word analysis to explore dependencies, evidence gaps and strategic trade-offs in greater depth.
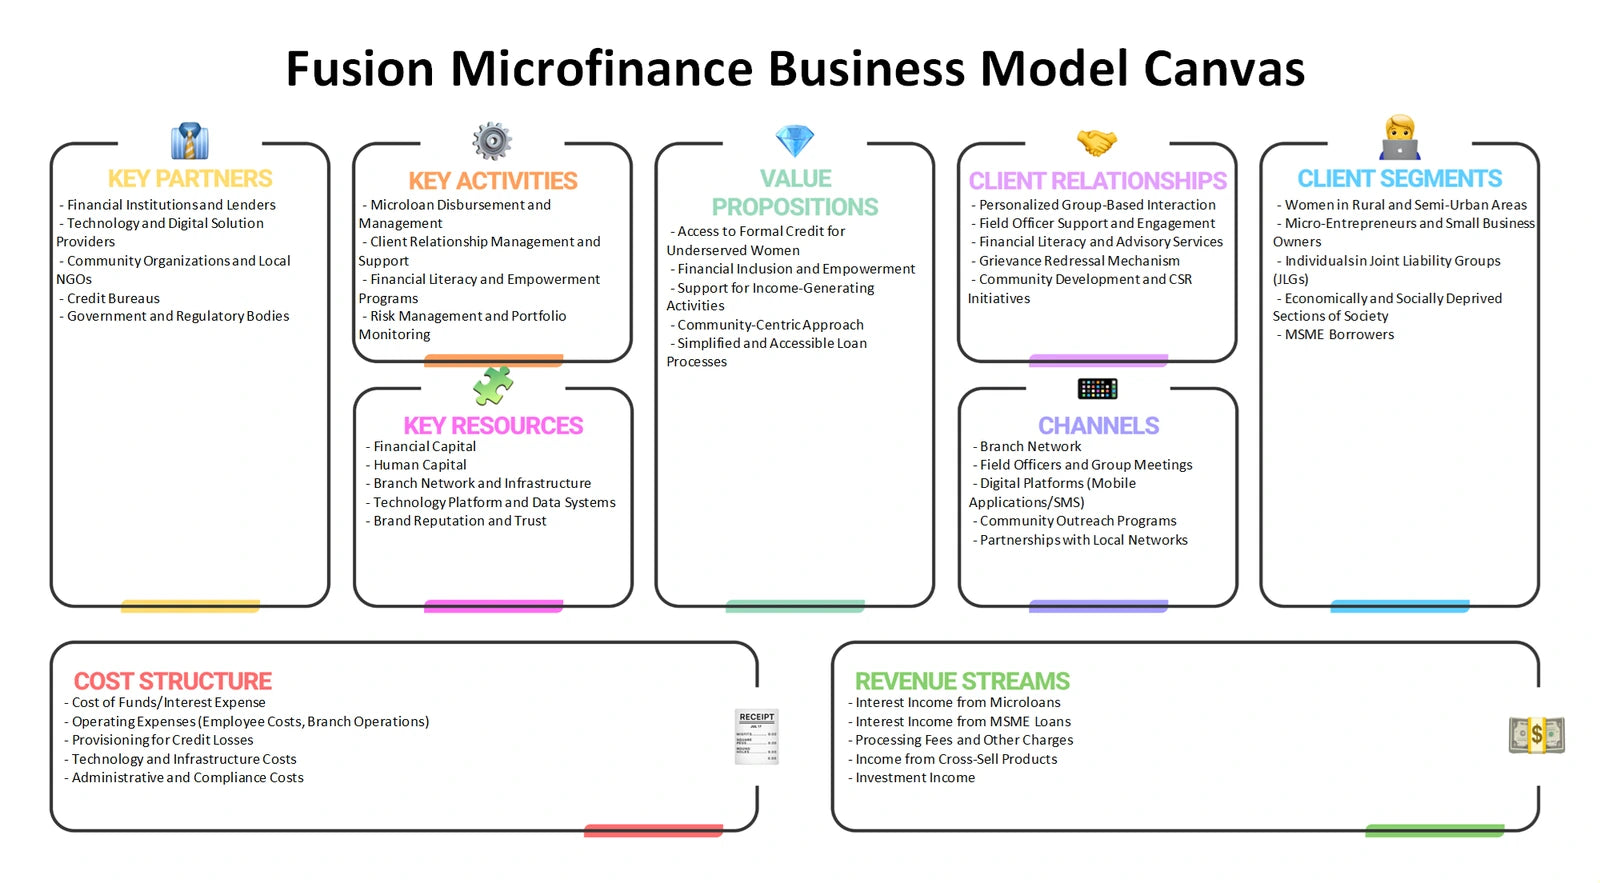
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness and resilience of a microfinance lending model?
Fusion Microfinance Porter's Five Forces examines the industry environment around client lending rather than rating the company or naming unsupported competitors. Rivalry can be considered through the contest for suitable borrowers, trusted relationships and responsible repayment performance. Supplier power matters because providers of funding, technology, insurance-related services or essential operating inputs may influence cost and capacity. Buyer power reflects borrowers’ alternatives, sensitivity to borrowing terms and ability to switch. New entrants may face barriers involving capital, compliance, credit processes and local trust, while substitutes include informal borrowing, bank credit, digital credit and other ways households meet short-term finance needs. The framework makes these pressures comparable without assigning force scores unsupported by evidence.
- Funding dependence. Explore how access to capital and operational inputs may affect margins, product flexibility and the ability to serve borrowers consistently.
- Alternative finance. Distinguish direct lending rivals from substitutes that meet a similar household cash-flow or emergency-finance need.
- Pressure map. Use the Excel framework to compare each force and its drivers, then use the Word analysis to capture implications, assumptions and questions for further research.
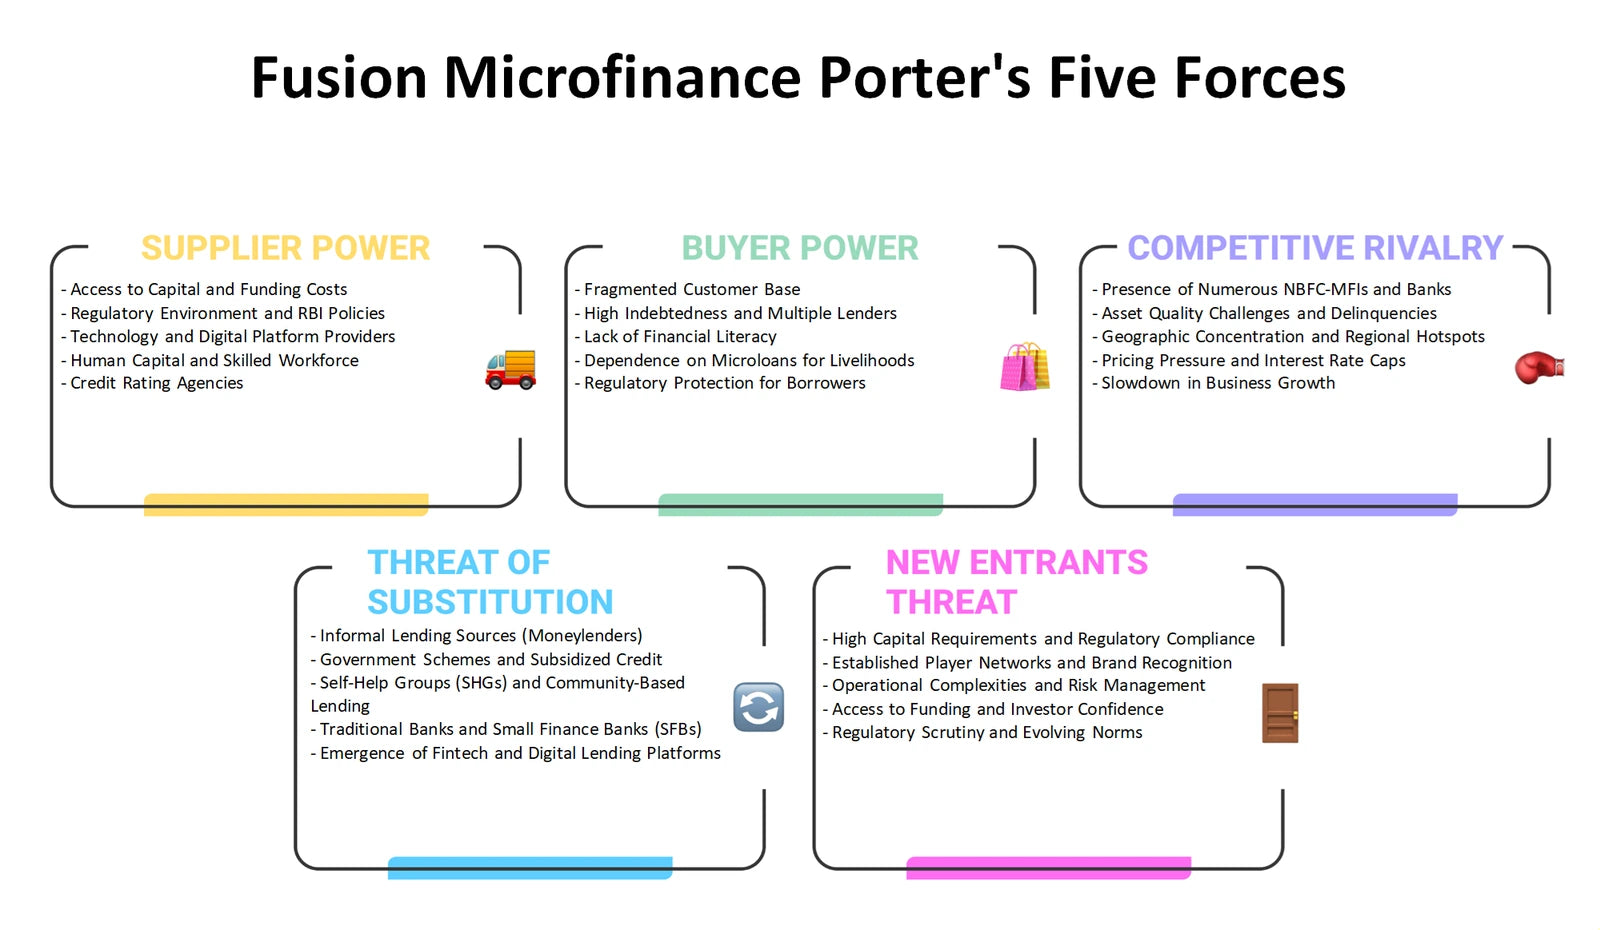
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should a client-centred lending offer be framed, priced, delivered and communicated responsibly?
The Fusion Microfinance Marketing Mix applies Product, Price, Place and Promotion to a trust-sensitive financial service. Product analysis can examine lending support alongside the potential value of a formal repayment history. Price should consider the full borrower decision, including affordability, clarity of terms and the trade-off between sustainable operations and accessible finance; it does not presume actual rates or fees. Place addresses how clients are reached and served, including the role that outreach, assisted access or other appropriate touchpoints may play. Promotion considers how clear, responsible communication can explain obligations, repayment discipline and the possible long-term value of credit records. Together, the 4Ps help avoid treating distribution or communication as separate from borrower outcomes.
- Offer design. Compare the practical borrower need being addressed with the service features, repayment expectations and support needed to make the offer understandable.
- Responsible access. Assess potential routes to clients and communication priorities without inventing campaign activity, channel shares or published prices.
- Decision-ready mix. Use the Excel structure to align the four Ps in one view, while the Word analysis supports fuller discussion of customer fit, conduct and trade-offs.
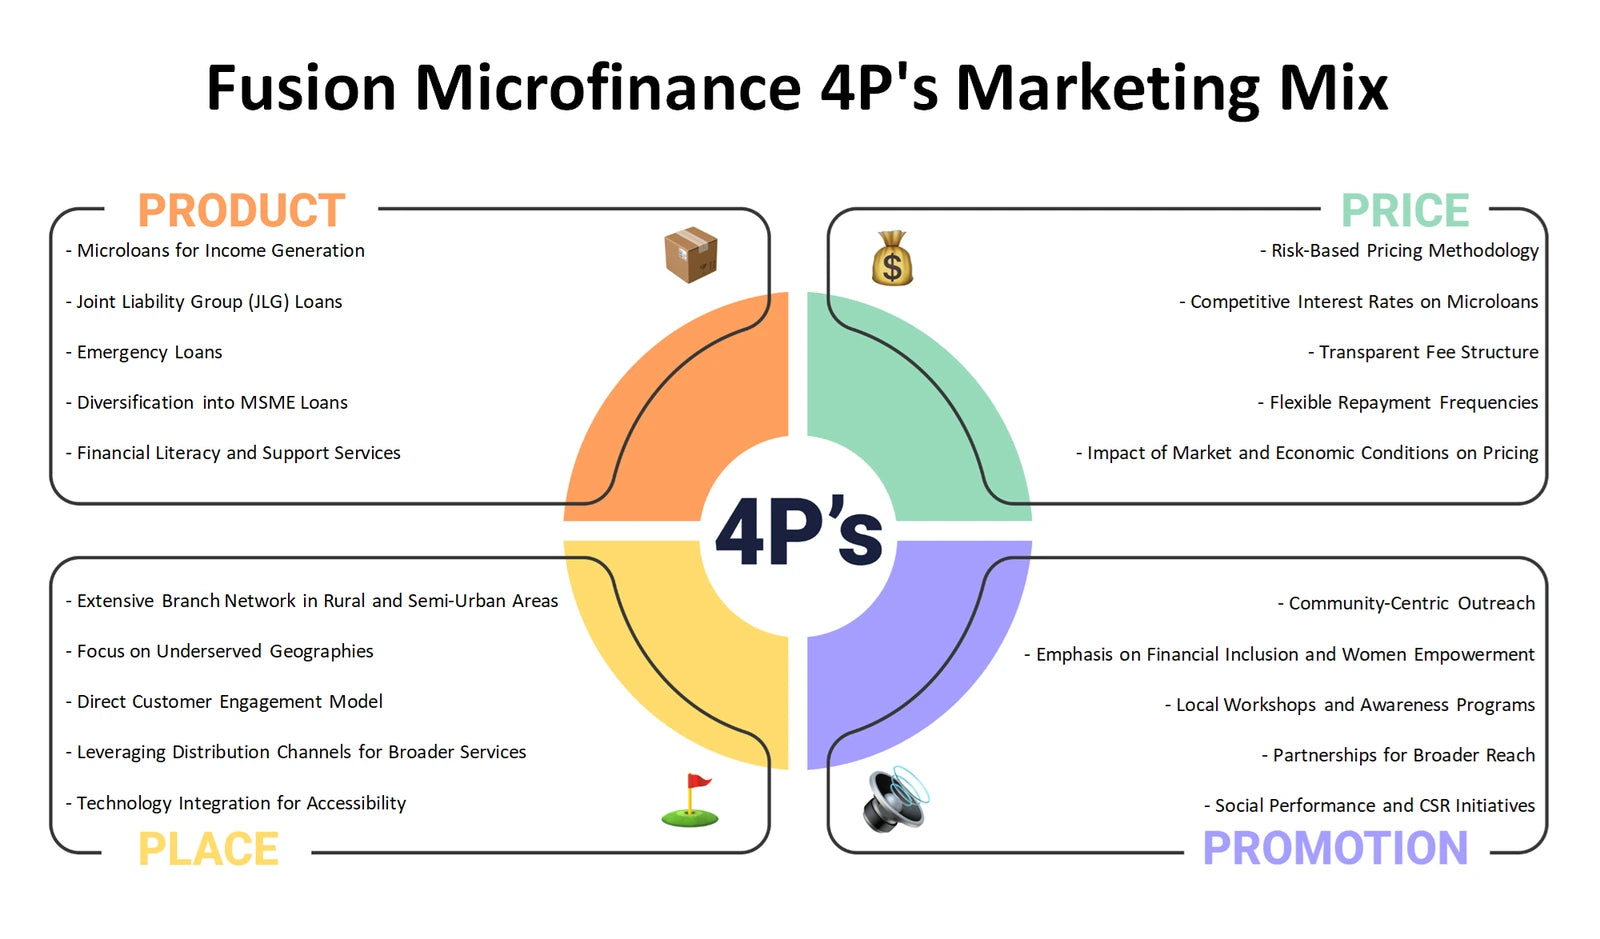
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter borrower needs, lending risk and the operating environment for microfinance?
A Fusion Microfinance PESTLE analysis, also commonly called PESTEL, separates external influences from internal operating choices. Political factors can include public-policy priorities and the stability of the financial-services environment. Economic conditions affect household income, repayment capacity, funding costs and demand for credit. Social factors may shape trust, financial inclusion and willingness to build formal credit histories. Technological issues include credit-data processes, service access and information security. Legal considerations include lending conduct, consumer protection, data obligations and applicable supervisory requirements. Environmental conditions are relevant where client livelihoods can be affected by weather, crops or livestock, making insurance uptake and income diversity useful topics to examine. These are analytical questions, not claims about a particular new law, interest rate or country event.
- External signal scan. Identify which developments may affect borrower resilience, funding conditions, data practices and portfolio risk before they become urgent decisions.
- Livelihood exposure. Consider how environmental disruption could interact with household cash flows and insurance-related risk mitigation themes in the supplied context.
- Scenario record. Use the Excel framework to organise external factors by category and the Word analysis to document possible implications, evidence sources and monitoring priorities.
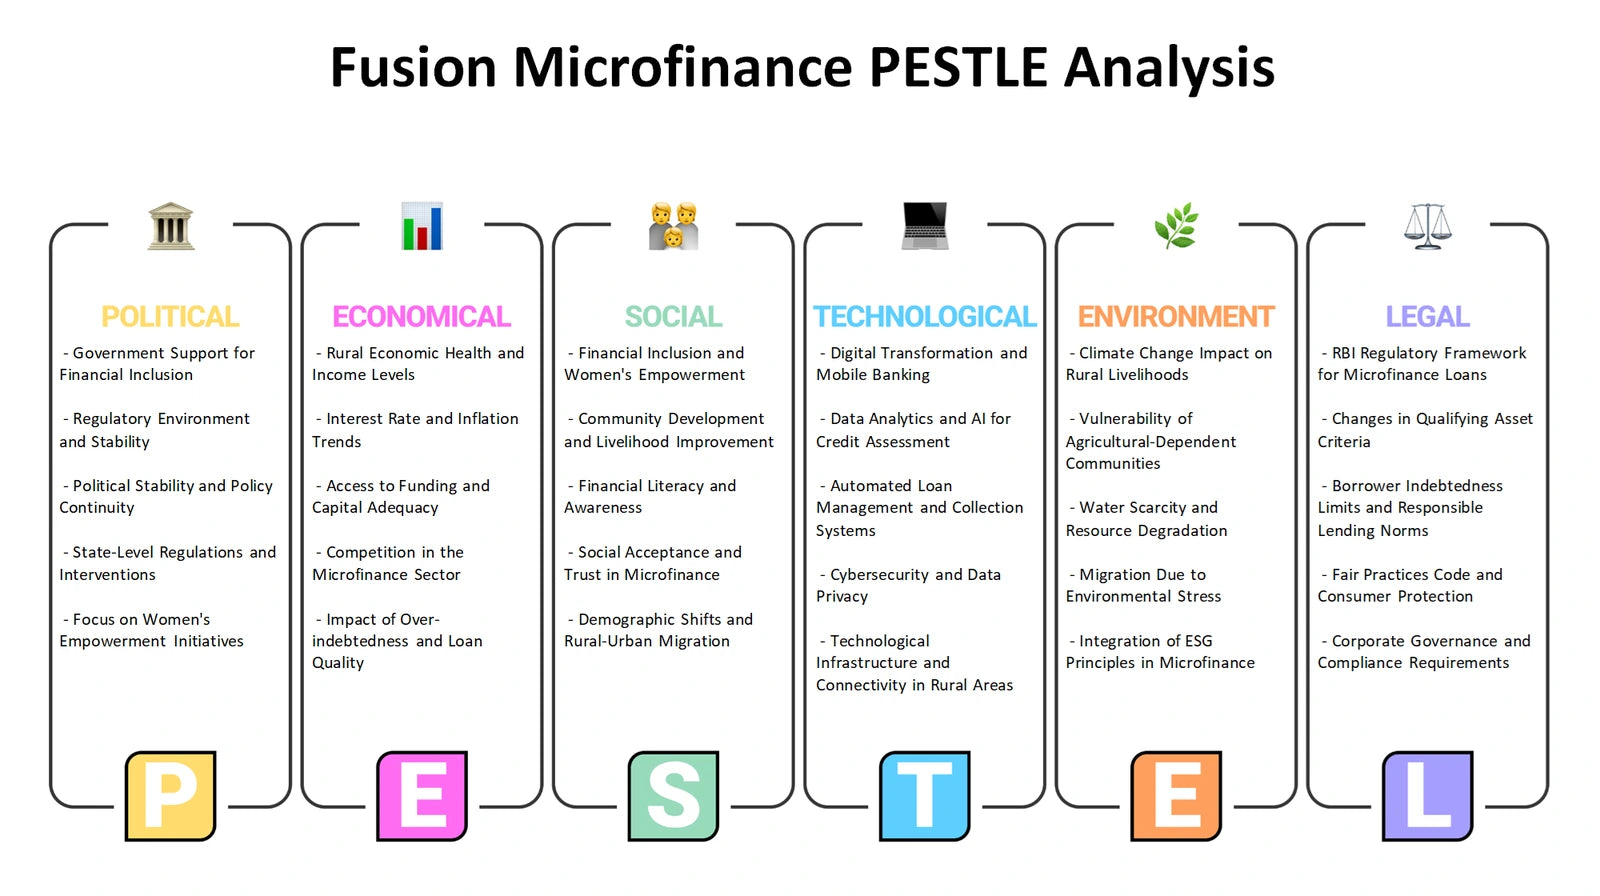
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal lending capabilities and constraints be assessed alongside external openings and risks?
The Fusion Microfinance SWOT analysis distinguishes what is internal from what is external before turning observations into strategy. Strengths and weaknesses concern capabilities, resources, processes and limitations within the business. Opportunities and threats arise from market, customer, technology, funding, regulatory or environmental conditions outside it. The supplied context offers starting themes to test, including outreach, repayment reporting, household-income diversity and insurance-related risk mitigation, but it does not prove that these are established strengths or outcomes. That distinction is important: a capability only becomes a strength when supported by evidence, while an external trend should not be labelled a weakness. SWOT helps bring those boundaries into one decision-focused view.
- Internal evidence. Evaluate potential capabilities such as client engagement, credit-information processes and risk controls alongside genuine operational constraints.
- External fit. Relate possible opportunities and threats to changing borrower needs, alternative finance, regulation and livelihood volatility without confusing them with internal facts.
- Action comparison. Use the Excel matrix to organise evidence by category, then use the Word analysis to develop balanced strategic questions and possible responses for review.
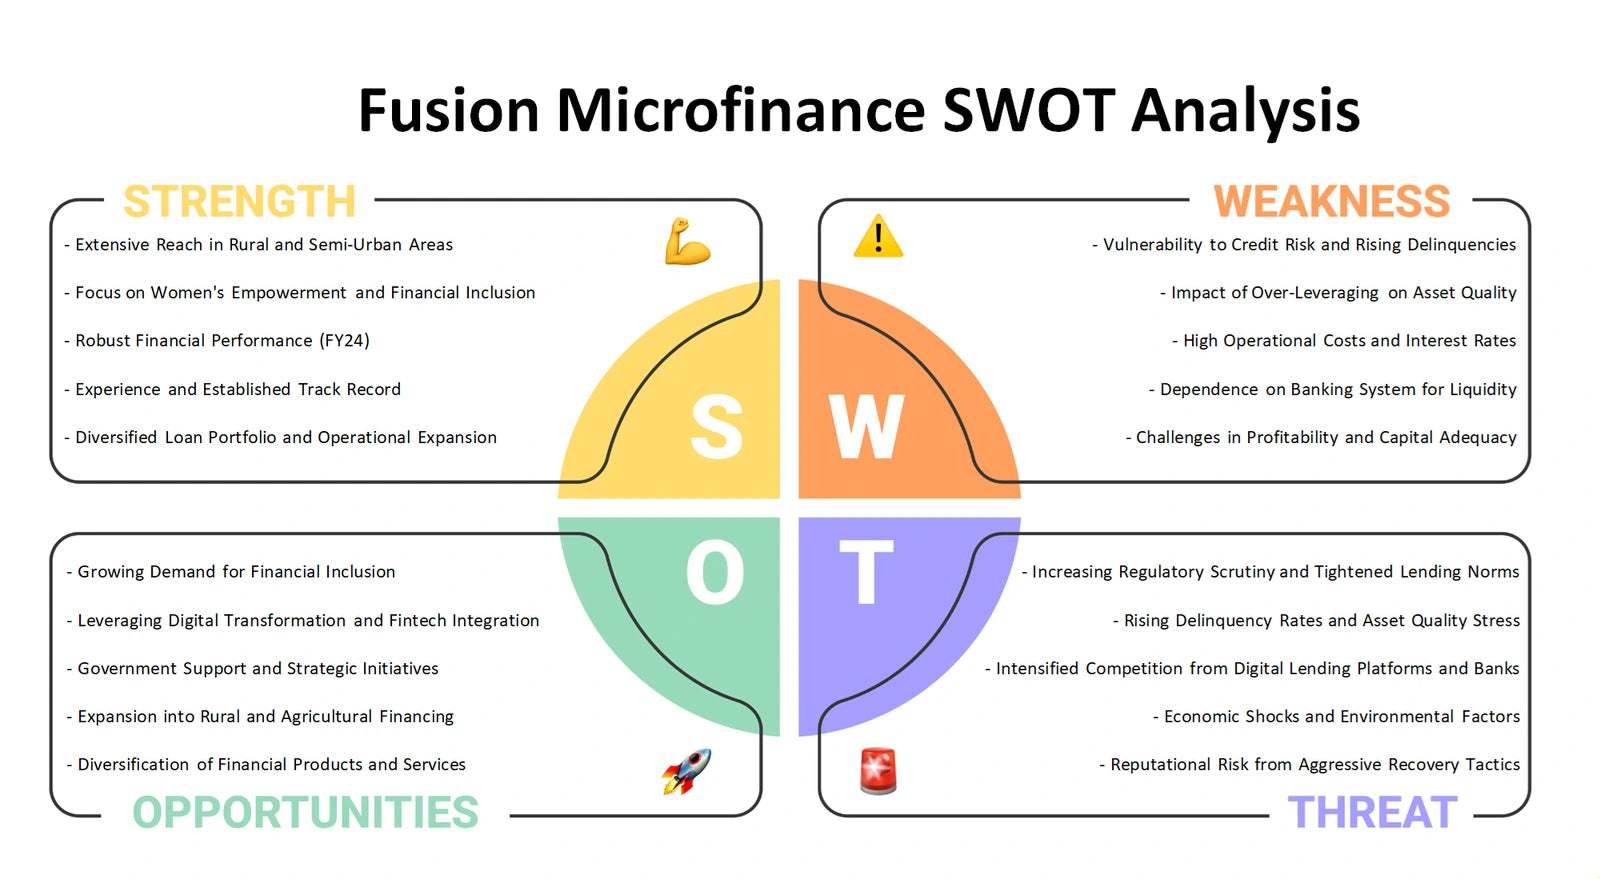
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Turn six perspectives into a connected strategic discussion
Used together, the six analyses move from portfolio priorities and business-model logic to industry pressure, client-facing choices, external change and strategic fit. The Excel frameworks give users practical structures for comparing issues consistently, while the detailed Word analysis supports fuller interpretation of lending, outreach, credit-history and risk-management questions relevant to Fusion Microfinance.
Company background: Fusion Microfinance — product-context analysis page.