

Cullen/Frost Bank: Banking Business and Market Access – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Cullen/Frost Bank Strategy Analysis Bundle
The supplied product context presents Cullen/Frost Bank as a full-service banking business serving commercial and consumer needs, alongside wealth, trust, advisory and insurance-related services. It describes banking permissions and continuing compliance as important enablers of this service mix, while fraud, credit and cash-flow alerts provide a useful lens on relationship-led client support and risk monitoring.
These materials do not treat that business description as a verdict on performance. Instead, they help examine how banking and advisory activities may compete for resources, how customer relationships and regulated delivery affect economics, and how external conditions can change priorities. The Excel frameworks provide a structured way to compare issues, while the Word files support deeper company-specific discussion.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking, wealth and protection-oriented activities deserve priority when growth potential and relative market share may differ?
A Cullen/Frost Bank BCG Matrix helps separate portfolio logic from headline impressions. The framework compares market growth with relative market share, then uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to organize discussion. For a banking business with commercial and consumer relationships, advisory capabilities and insurance distribution, the useful question is not whether one service is simply “good” or “bad,” but whether its market position, growth outlook, capital needs and management attention fit together. It can help frame trade-offs between expanding a developing offer, defending a mature relationship base, improving a constrained activity or reducing complexity.
- Portfolio boundaries. Compare service lines or customer-facing activities consistently without assuming that any has a proven quadrant placement.
- Capital discipline. Consider how credit capacity, technology spending, specialist talent and compliance effort could affect portfolio priorities.
- Decision mapping. Use the Excel matrix to test possible classifications and use the Word analysis to record assumptions, evidence needs and implications for resource allocation.
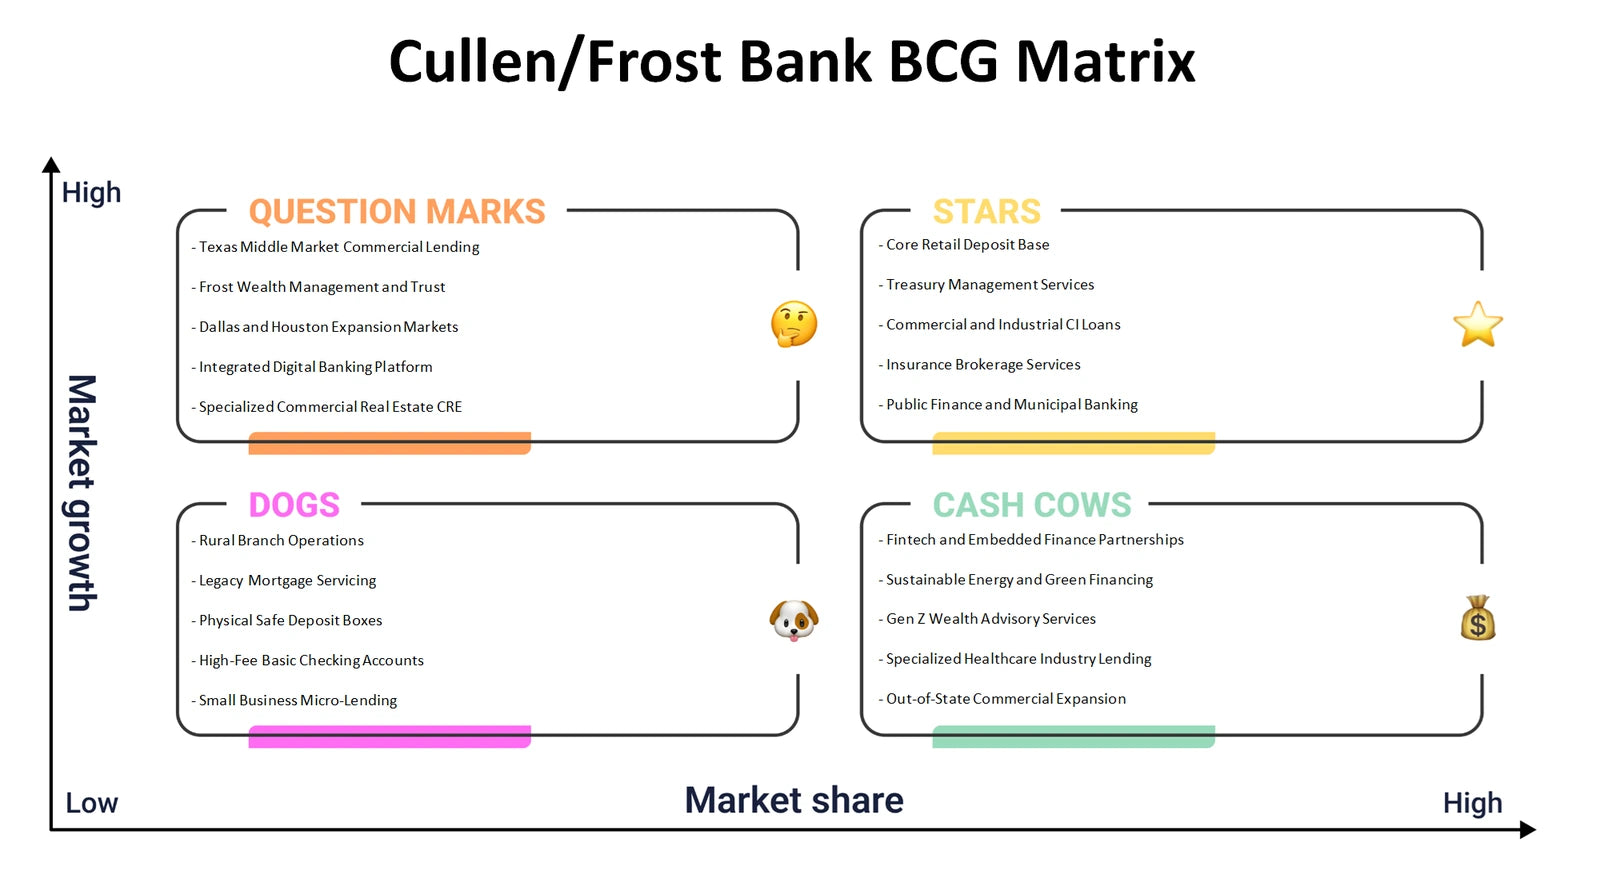
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, regulated banking delivery and specialist services connect to Cullen/Frost Bank’s economics?
The Cullen/Frost Bank Business Model Canvas organizes the full operating model rather than looking only at individual products. It links customer segments and value propositions to channels and customer relationships, then connects revenue streams to key resources, key activities, key partnerships and cost structure. Commercial clients may value credit, deposit and cash-management support, while consumer and wealth clients may value convenient banking, advice, trust services or protection products. These different needs can require different relationship models and delivery routes. The canvas helps examine how licensed capabilities, risk controls, technology, frontline expertise and external service partners support value creation while also creating operating and compliance costs.
- Customer architecture. Distinguish the needs of commercial, consumer, wealth and advisory-oriented customer segments before evaluating channels or propositions.
- Economic connections. Trace how deposits, lending, fees or advisory-related income may relate to servicing costs, risk management and relationship depth.
- Model alignment. Populate and compare the nine Excel building blocks, then use the Word analysis to explain dependencies and tensions across the model.
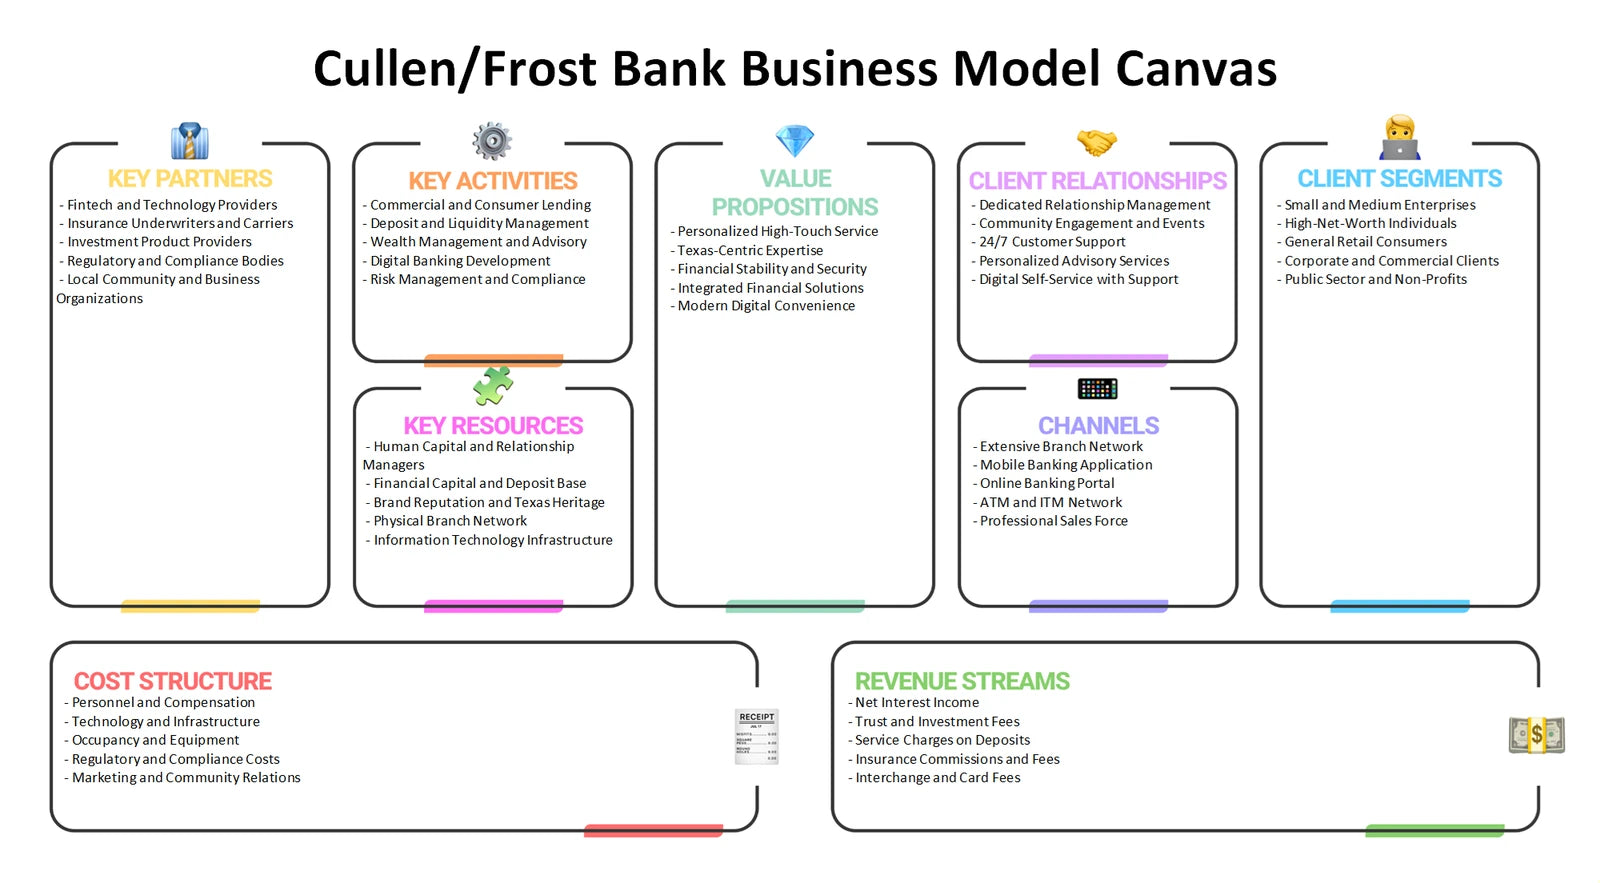
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the ability to attract deposits, extend credit and retain relationship-based customers?
Cullen/Frost Bank Porter’s Five Forces examines the competitive environment around banking, advisory and related financial services. Rivalry can arise from institutions competing for deposits, loans, affluent-client relationships and business accounts. Buyer power may increase when customers can compare rates, fees, digital experiences or advisory options more easily. Supplier power is relevant to specialist technology, data, payment infrastructure, professional talent and third-party providers. The threat of new entrants includes digitally enabled financial providers as well as smaller specialist firms, while substitutes include non-bank funding, payment solutions, investment platforms and alternative ways to meet cash-management or advice needs. The framework does not assign force scores; it gives a disciplined structure for testing which pressures matter most.
- Competitive pressure. Assess where relationship quality, local knowledge, pricing transparency or digital convenience may intensify rivalry.
- Substitute pathways. Compare banking needs with alternative payment, credit, investment and cash-management solutions rather than limiting the view to direct banks.
- Evidence trail. Use the Excel framework to rank questions and the Word analysis to document rationale, supporting observations and unanswered competitive issues.
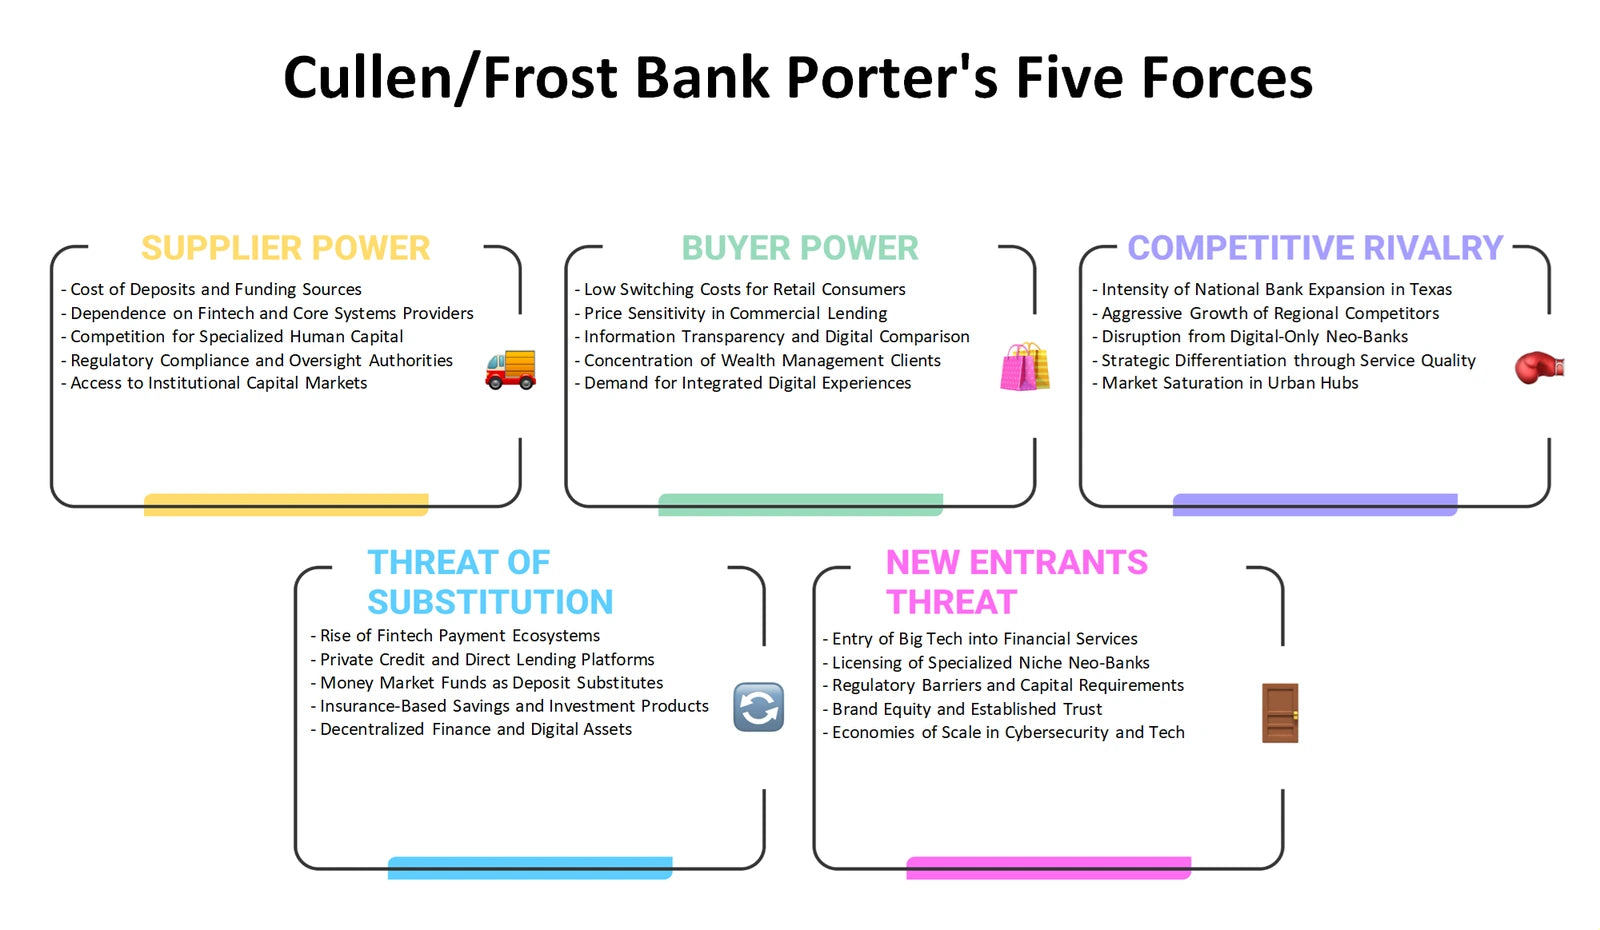
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, distribution and communication be assessed across a regulated financial-services relationship?
A Cullen/Frost Bank Marketing Mix considers Product, Price, Place and Promotion in a setting where trust, suitability, risk and compliance influence the customer experience. Product can include banking services, lending, deposit relationships, wealth and trust support, advisory activity and insurance-related distribution. Price is broader than a posted fee: it can involve interest-rate terms, account pricing, service charges, advisory compensation and the value customers attach to responsive support. Place can include relationship managers, branches, digital access and specialist channels, while promotion must communicate useful value without overstating outcomes or overlooking disclosures. The 4Ps lens helps determine whether a chosen message, delivery route and pricing approach fit the needs of each customer group.
- Offer coherence. Examine whether the stated benefits of banking, wealth and protection services match the practical needs of different clients.
- Channel fit. Compare when a customer may need digital self-service, direct relationship support or specialist advisory engagement.
- Campaign planning. Structure Product, Price, Place and Promotion choices in Excel, then use the Word analysis to develop a compliant, customer-focused rationale.
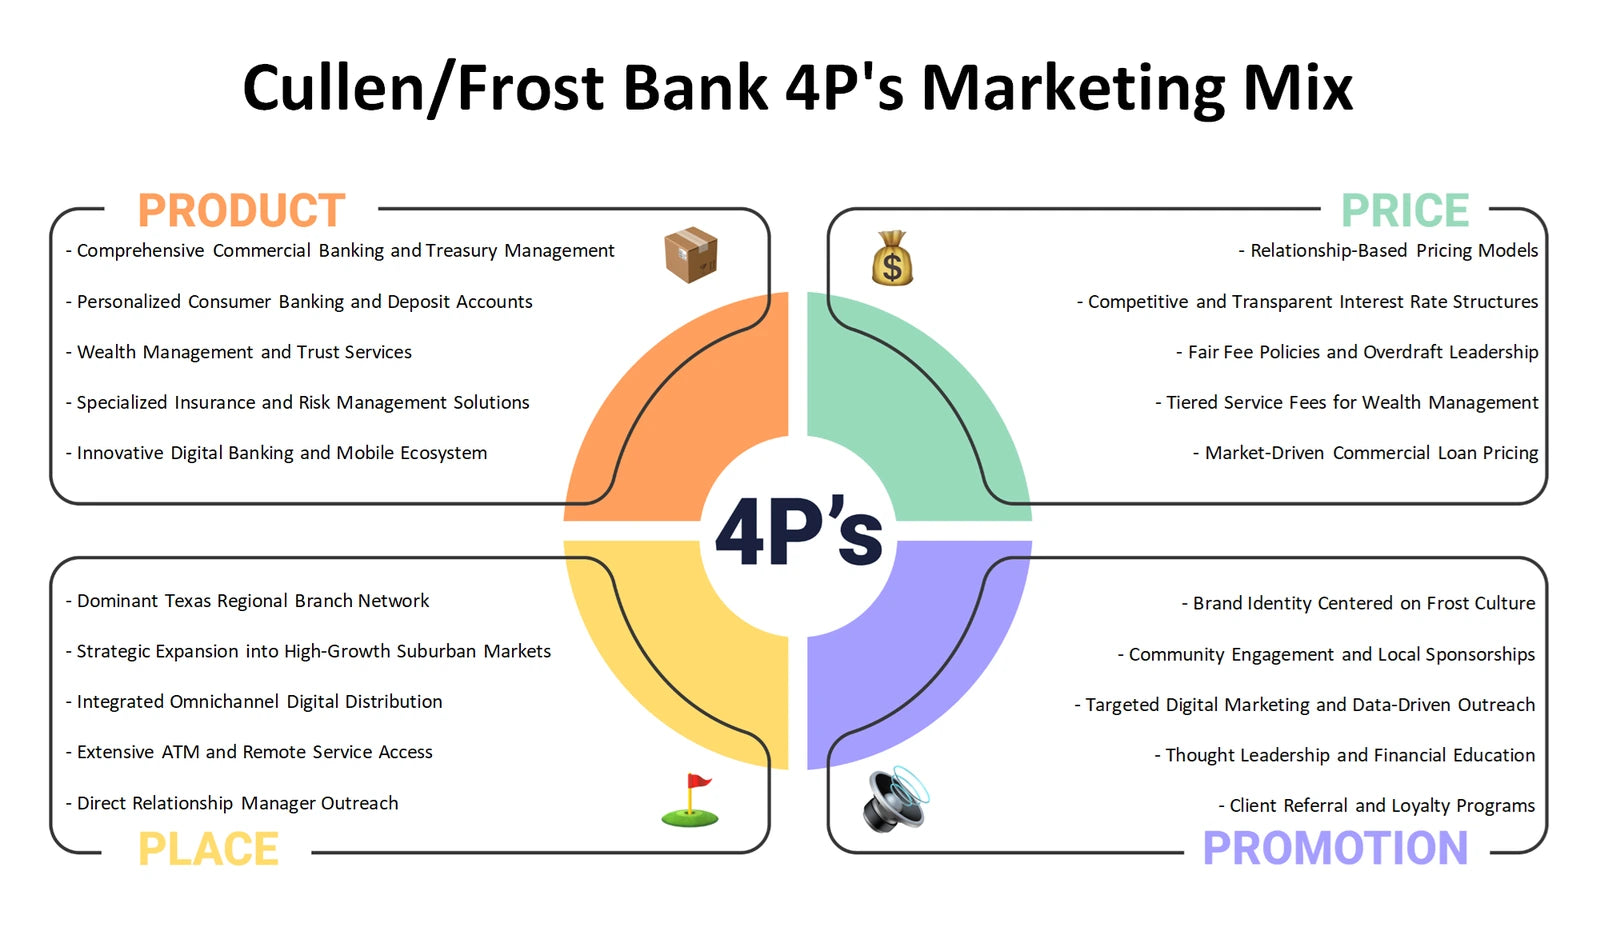
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should be monitored because they can alter banking demand, operating costs, risk appetite or client expectations?
Cullen/Frost Bank PESTLE analysis, also commonly called PESTEL, separates the external environment into Political, Economic, Social, Technological, Legal and Environmental influences. Political and Legal questions include supervision, charter-related requirements, consumer protection and changing expectations for financial institutions. Economic factors can include interest-rate conditions, credit demand, deposit behavior and local business confidence. Social trends may reshape expectations for convenience, advice and financial security. Technological change brings both digital-service opportunities and fraud, cyber and third-party dependency questions. Environmental factors can affect physical operations, borrower exposure, insurance considerations and risk assessments. This framework distinguishes documented business conditions from scenarios that management may need to monitor.
- Regulatory horizon. Track questions about permissions, compliance obligations, data governance and consumer safeguards without assuming a particular policy outcome.
- Risk transmission. Consider how economic, technological or environmental changes may move through clients, credit quality, operations and service demand.
- Monitoring agenda. Use the Excel categories to prioritize external signals and the Word analysis to explain why each signal could matter to the business model.
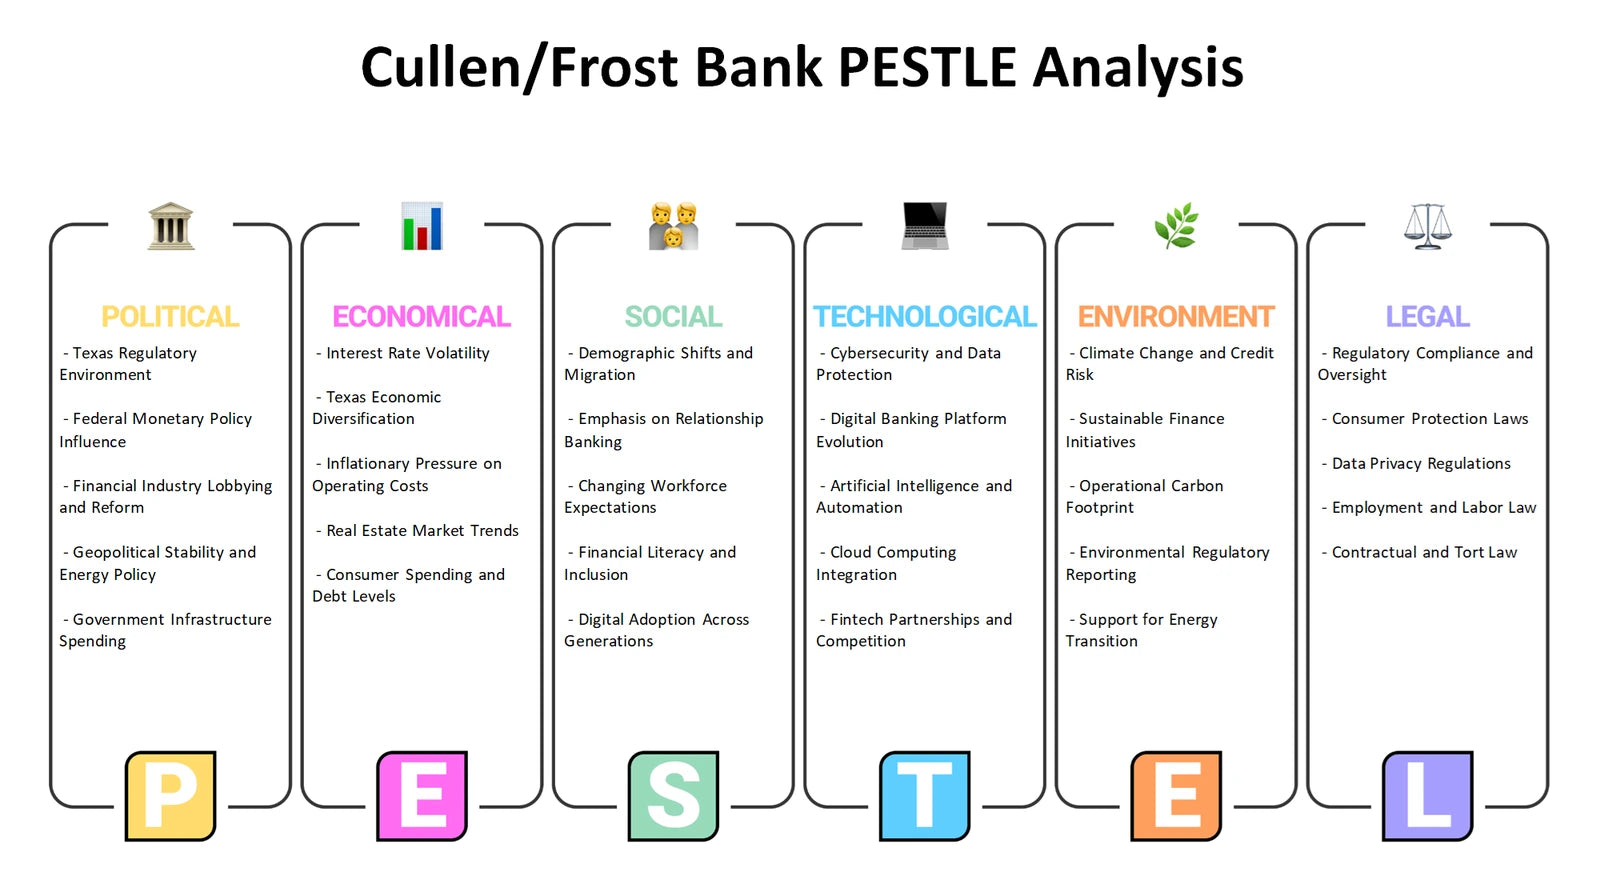
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities and constraints be distinguished from external opportunities and threats in a changing financial-services market?
A Cullen/Frost Bank SWOT analysis keeps internal and external issues separate before connecting them in strategy discussion. Potential internal strengths to test may include relationship-based service, regulated capabilities, specialist expertise or data-supported client alerts; these should be examined as evidence-based possibilities rather than assumed advantages. Internal weaknesses may involve complexity, cost, legacy processes, capability gaps or concentration risks. Opportunities and threats belong outside the organization: changing customer behavior, technology shifts, economic conditions, regulation and substitute services can all reshape the market. By placing each issue in the correct category, SWOT prevents external pressure from being mistaken for an internal failing and prevents a capability from being mistaken for a market opportunity.
- Internal realism. Test whether operational capabilities, customer insight, compliance capacity and delivery consistency are supported by evidence.
- External choices. Relate market openings and threats to customer needs, competitive pressure and the broader banking environment.
- Action linkage. Build the four-part view in Excel and use the detailed Word analysis to connect priority combinations to questions for leadership review.
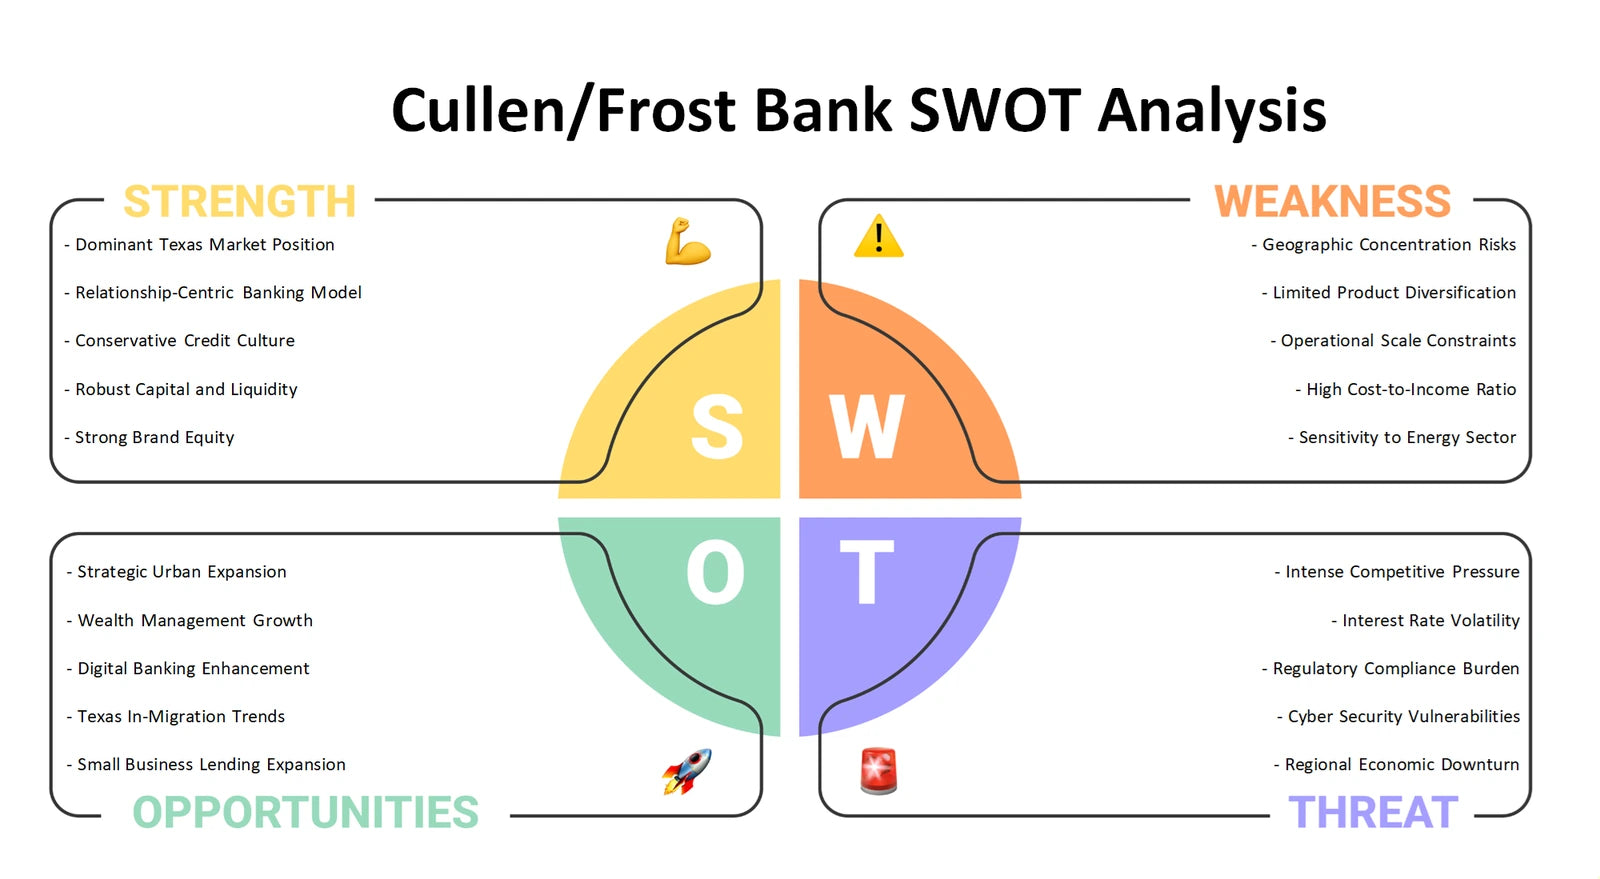
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected strategic view
Together, the six perspectives move from portfolio priorities and business-model economics to industry pressure, customer-facing choices, external change and internal-versus-external positioning. The Excel frameworks help organize comparisons and working assumptions, while the Word files provide detailed company analysis that can support more structured discussion of Cullen/Frost Bank’s banking, advisory and relationship-led service model.
Company background: Cullen/Frost Bank — product-context business model page.