

First Foundation: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
First Foundation Strategy Analysis Bundle
First Foundation refers here to First Foundation Inc., the regulated banking issuer classified by the SEC as a state commercial bank. Its supported business context includes deposit-funded lending, loan-sale and servicing relationships, and branch or advisory-office interactions for clients with more complex lending, wealth and estate-planning needs. This bundle examines how those connected activities can be assessed as one financial-services model rather than as isolated products.
In its 2025 Form 10-K filed March 16, 2026, First Foundation Inc. reported revenue of USD 34.373 million for the year ended December 31, 2025, and a GAAP net loss of USD 8.040 million for the quarter ended December 31, 2025. These reported figures make capital allocation, funding economics and relationship-led growth important questions to examine through the six frameworks.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which activities merit scarce capital and management attention as First Foundation balances lending, deposits and advisory relationships?
A First Foundation BCG Matrix helps organize possible business activities around market growth and relative market share. It does not presume that a lending product, deposit relationship or advisory service belongs in any quadrant. Instead, it provides a disciplined way to compare candidates for Stars, Cash Cows, Question Marks and Dogs, while recognizing that banking capacity is shaped by funding, credit exposure, capital and client retention rather than sales volume alone.
- Portfolio logic. Compare mature relationship activities that may support recurring economics with newer or expanding opportunities that could require investment before they contribute meaningfully.
- Balance-sheet trade-offs. Consider whether growth in lending, deposits or advisory reach consumes capital, liquidity capacity and specialist attention in ways that alter portfolio priority.
- Structured review. Use the Excel framework to map alternatives consistently, then use the Word analysis to interpret the assumptions and questions behind each potential priority.
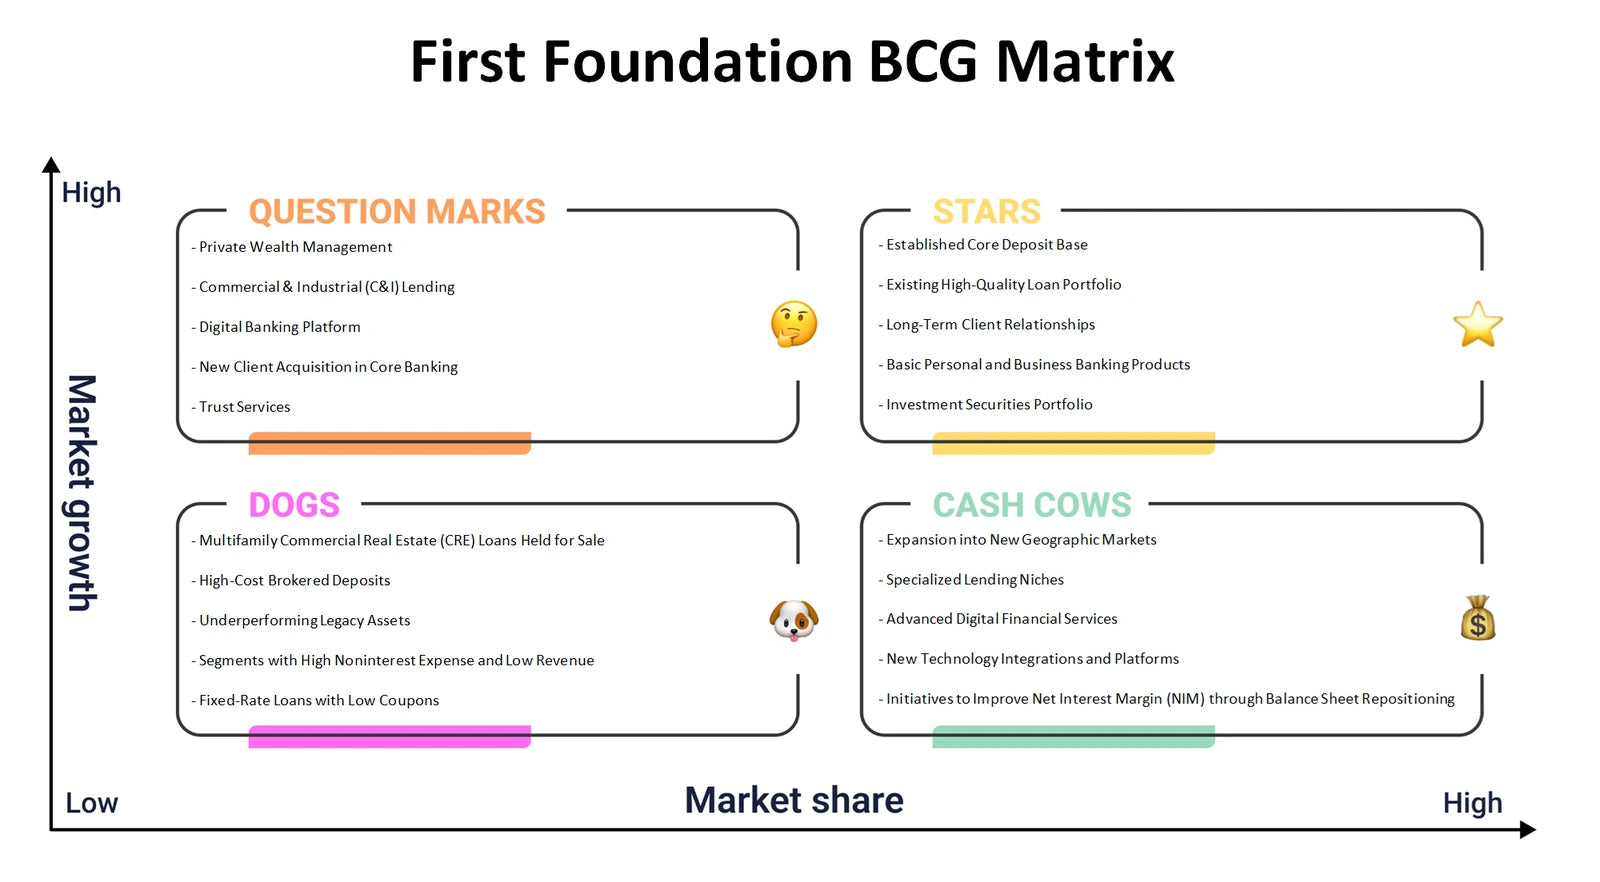
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do deposits, lending, advisory contact and external loan outlets fit together to create value and earn an acceptable return?
The First Foundation Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For this business, the useful issue is the link between relationship-based service and balance-sheet economics. Deposits can support lending capacity; branches and advisory offices can support trust in complex decisions; and whole-loan buyers or servicing partners can affect liquidity, risk transfer and the continuity of client relationships.
- Client architecture. Examine how households or other relationship clients may experience lending, deposits and advisory contact through physical offices and ongoing service channels.
- Economic connections. Trace how funding costs, credit risk, loan sales, servicing arrangements and operating infrastructure may influence revenue streams and the cost structure.
- Model alignment. Populate the Excel canvas to test connections between blocks, then consult the Word analysis for detailed prompts on dependencies and trade-offs.
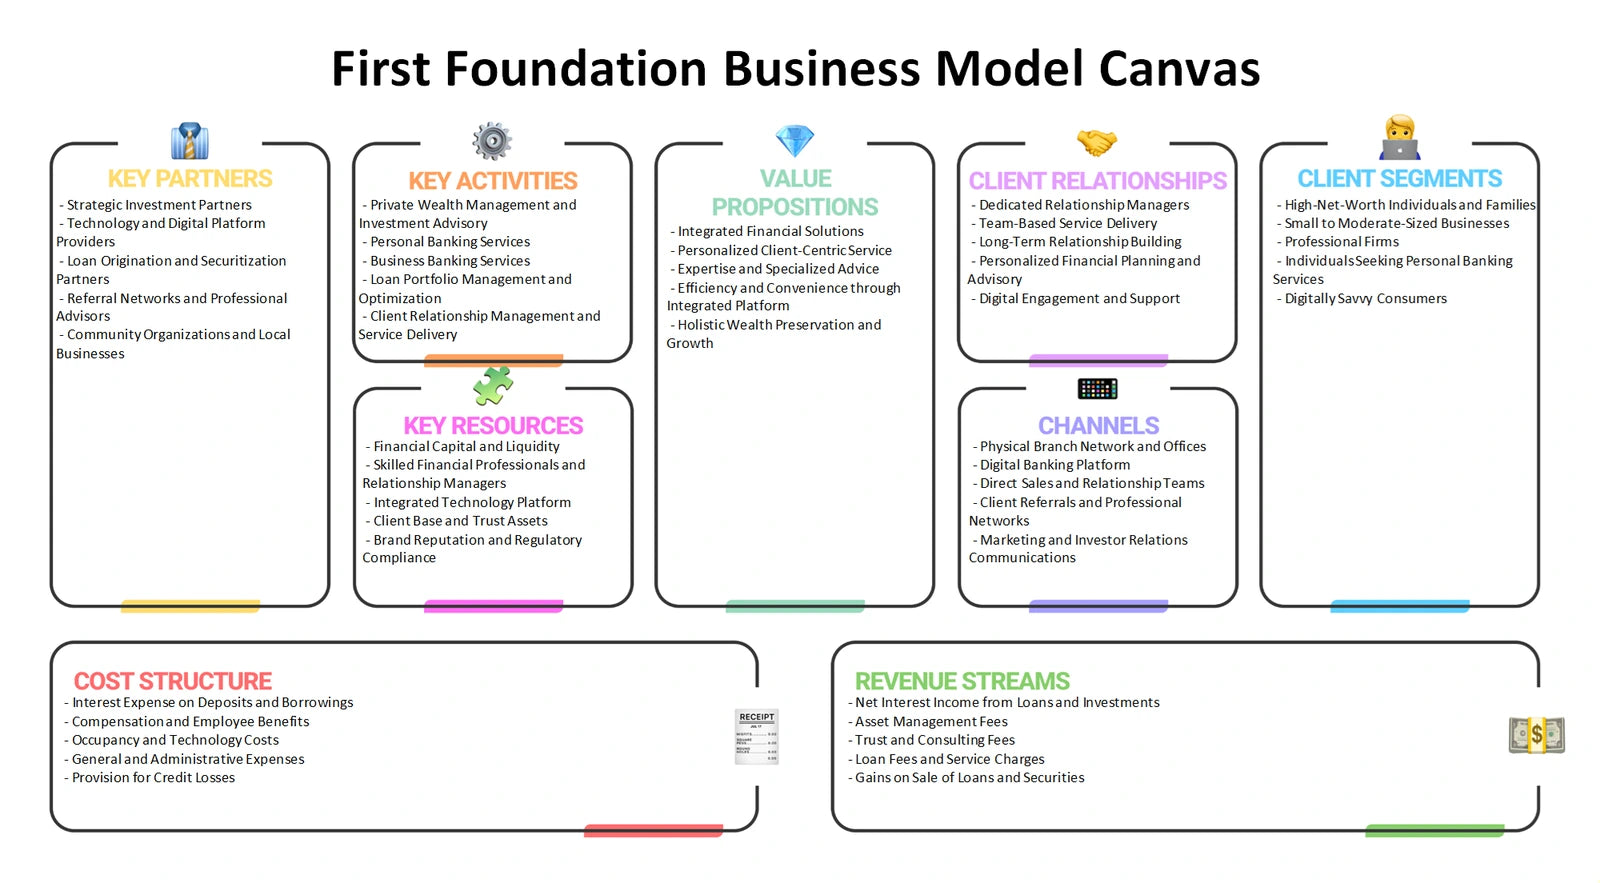
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness of relationship banking, lending and advisory-oriented service?
First Foundation Porter's Five Forces frames the competitive environment around five distinct pressures: rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes. In banking, competition is not limited to another bank. Depositors can compare places to hold funds, borrowers can seek different funding sources, and clients can choose alternative providers for planning or investment-related needs. The framework helps separate these demand-side choices from the cost and availability of funding, specialist talent, technology and other inputs.
- Rivalry and choice. Assess how comparable financial institutions and alternative providers may compete for deposits, loans and trusted advisory relationships without assuming a named competitor is dominant.
- Entry barriers. Consider how regulation, capital requirements, brand trust, local relationships and operating scale can shape the threat of entrants in relevant service areas.
- Evidence trail. Use the Excel framework to compare force-specific observations, while the Word analysis helps explain why each pressure matters to margins, retention or growth options.
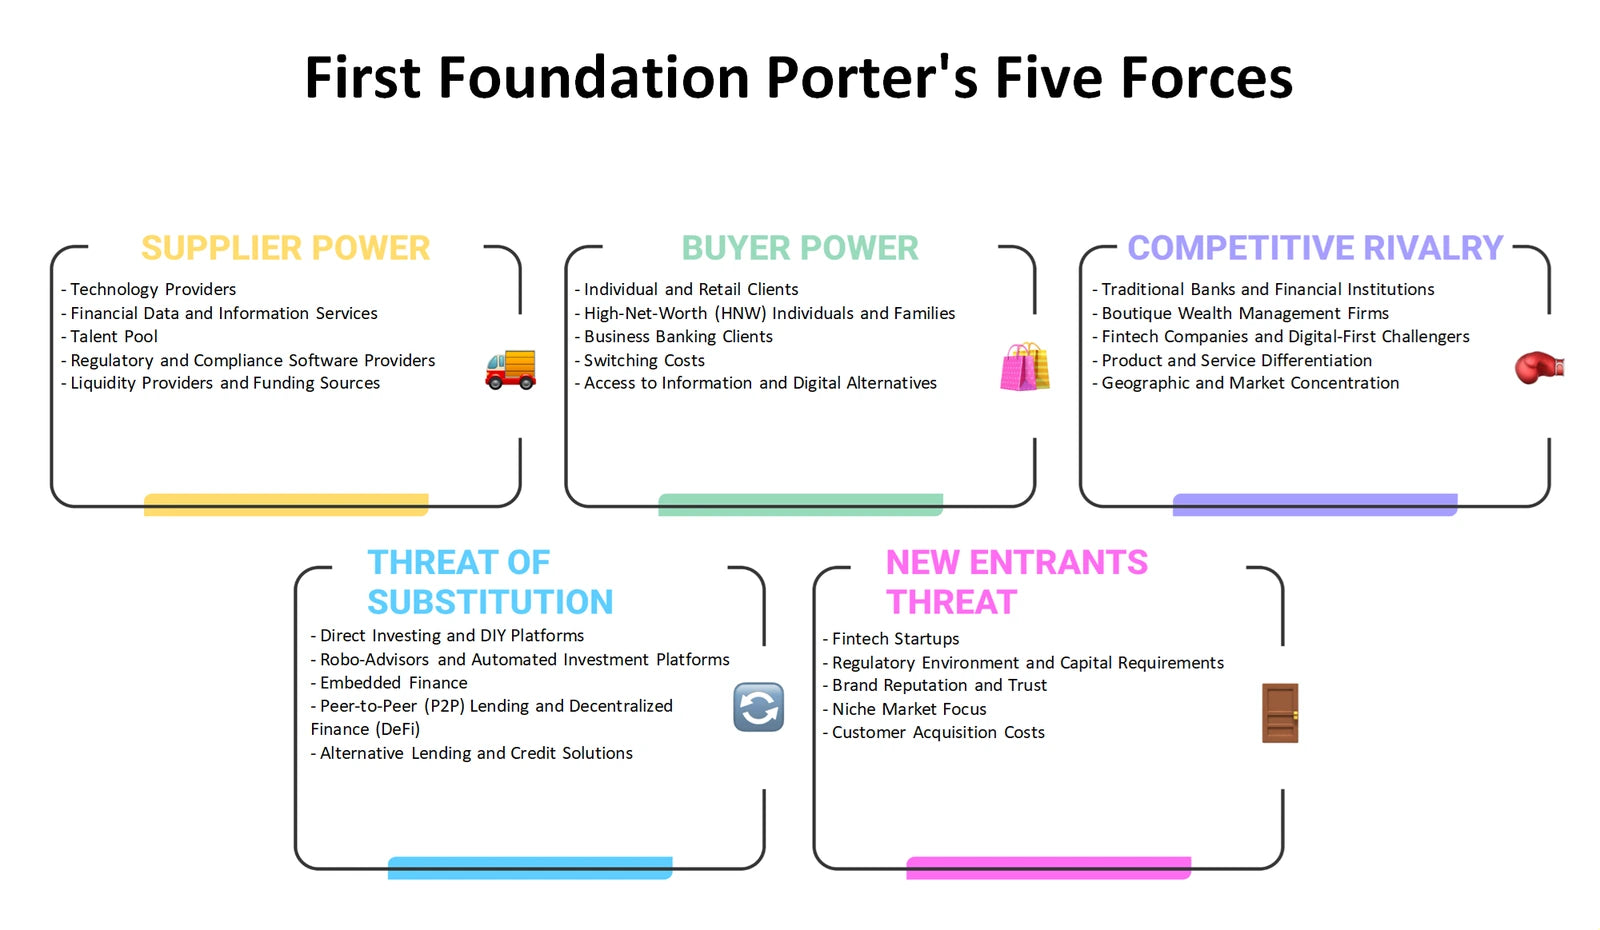
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can First Foundation present a coherent client proposition when trust, pricing discipline and service access all influence financial decisions?
The First Foundation Marketing Mix applies Product, Price, Place and Promotion to a regulated, relationship-led service business. Product can include the way deposit, lending and advisory needs are assembled around a client relationship. Price is broader than a published fee: it can involve deposit rates, loan terms, service charges and the value clients attach to advice. Place includes branches, advisory offices and other approved access routes, while promotion must communicate capabilities carefully and credibly.
- Offering design. Explore how complex lending, wealth-related discussions and estate-planning interactions may require clear product boundaries and coordinated service delivery.
- Access and communication. Compare the role of face-to-face trust-building, referral networks and other channels without assuming any particular campaign or channel share.
- Decision worksheet. Use the Excel framework to align the four Ps by client need, then use the Word analysis to add sector context and questions for review.
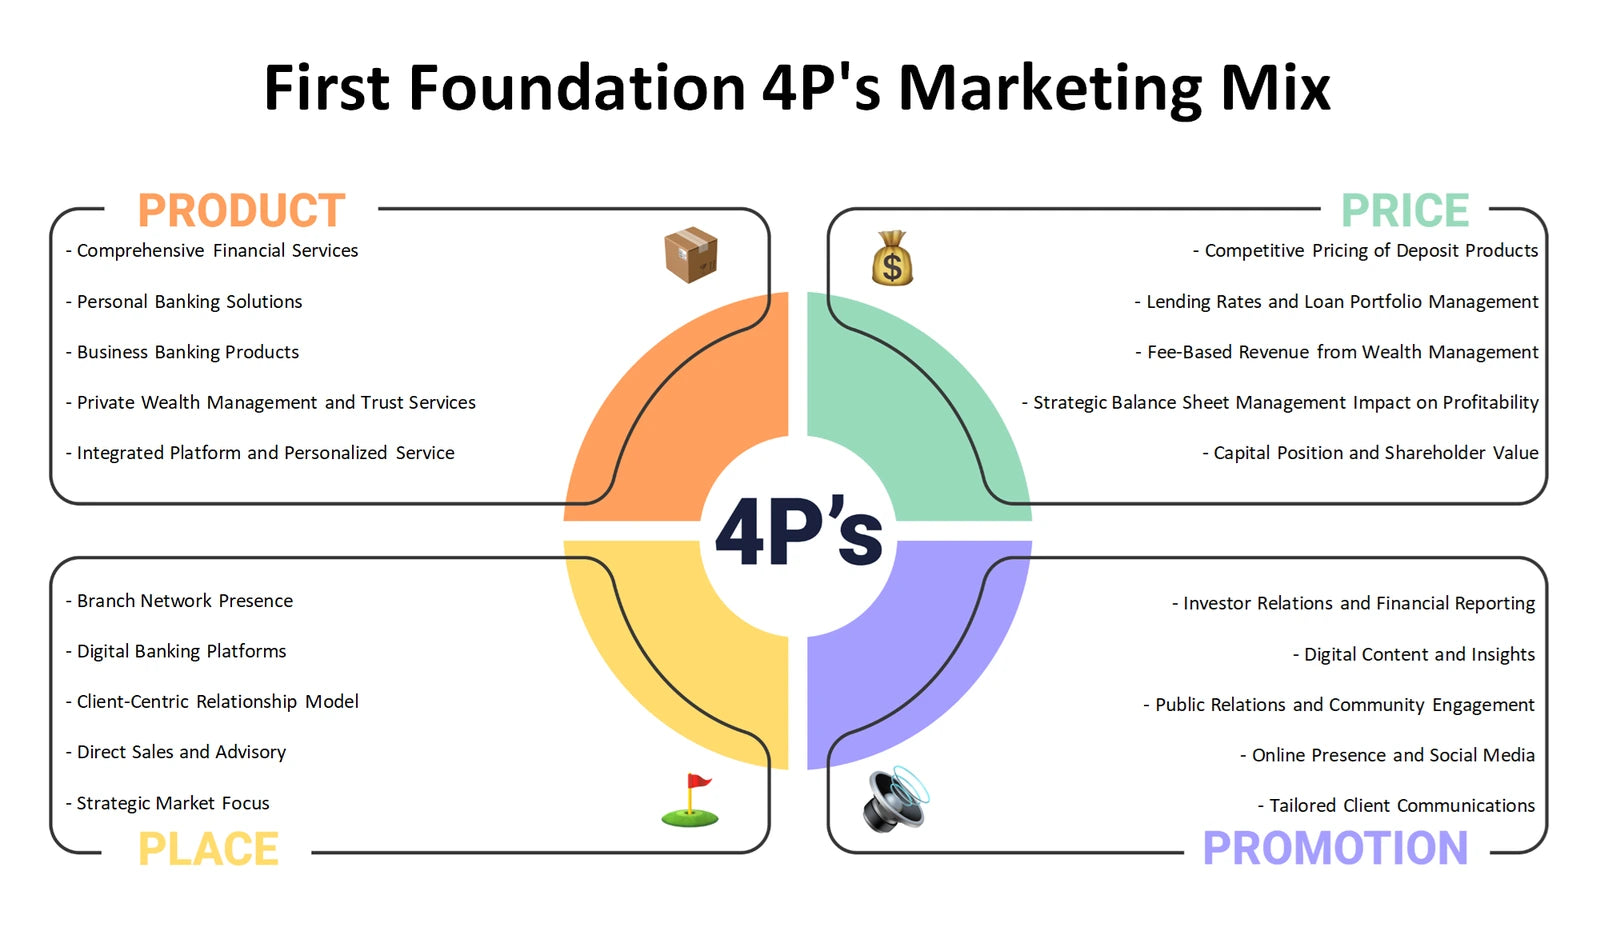
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should be monitored because they could alter funding conditions, client needs or the cost of operating a bank?
A First Foundation PESTLE analysis, also called PESTEL, examines Political, Economic, Social, Technological, Legal and Environmental influences outside the company’s direct control. For a commercial-bank context, policy and supervisory expectations may affect operating choices, while economic conditions can shape borrower demand, deposit behavior and credit performance. Social preferences may influence the value placed on human advice or local presence. Technology, legal compliance and environmental exposure can each affect service design, risk management and operating investment.
- External watchlist. Separate a possible rate, policy or regulatory question from a documented change so planning does not treat uncertainty as an established fact.
- Client implications. Consider how changing expectations for convenient service, data protection and informed financial guidance may affect relationship models and channel choices.
- Scenario preparation. Use the Excel framework to record external drivers and potential effects, with the Word analysis providing structured context for discussion and prioritization.
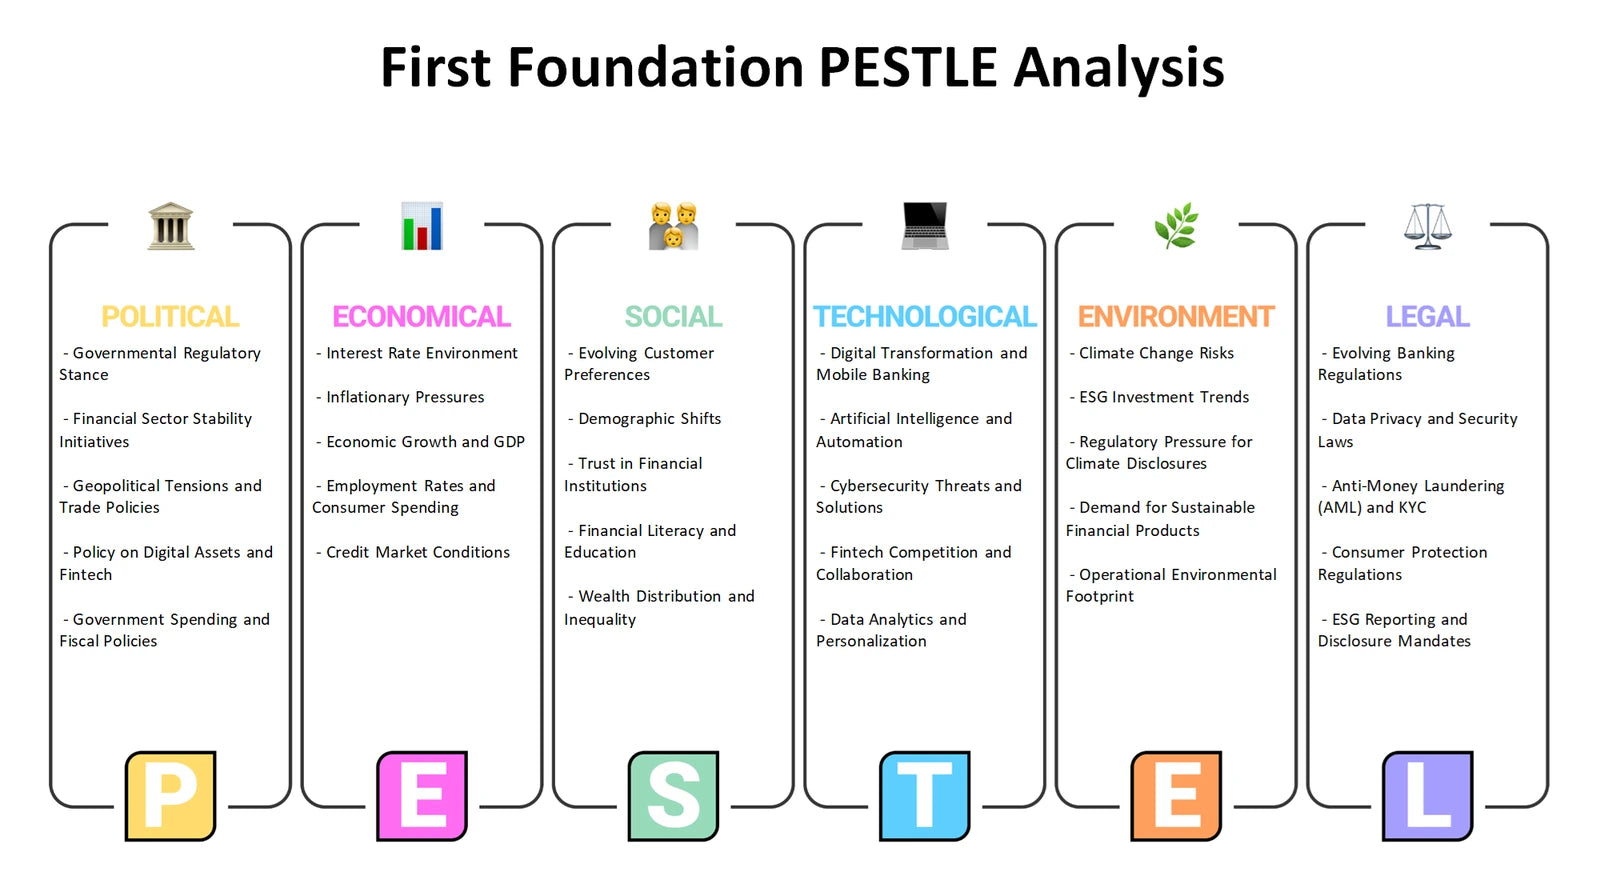
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities and constraints be considered alongside the external opportunities and threats facing First Foundation?
The First Foundation SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. Potential internal topics for examination include the quality of deposit relationships, lending expertise, capital capacity, advisory-office presence, operating costs and risk-management demands. External topics may include shifts in client preferences, competitive intensity, economic conditions, technology expectations and regulation. The value of the framework is not to declare these themes proven strengths or weaknesses; it is to classify evidence and identify where internal realities meet outside conditions.
- Internal diagnosis. Assess resources, relationship capabilities, service infrastructure and balance-sheet constraints as company-specific factors management can influence.
- Strategic fit. Compare external openings and risks with the capabilities needed to respond, including the trade-off between measured expansion and resilience.
- Action framing. Use the Excel matrix to group observations by category, then use the Word analysis to develop reasoned links between issues, questions and possible priorities.
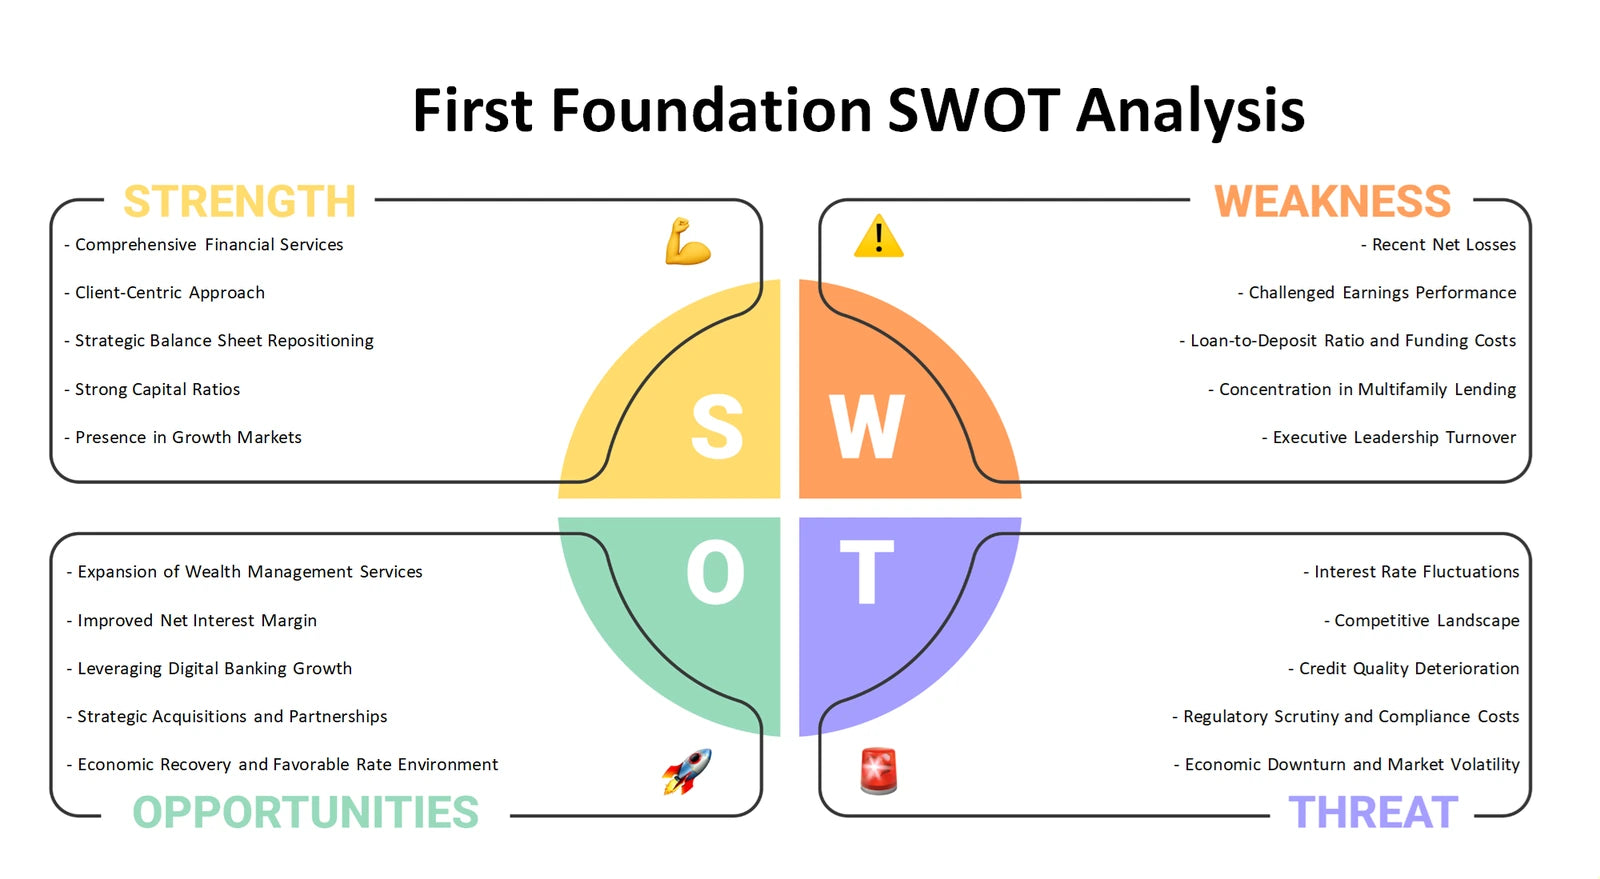
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the operating model behind them
Together, the six perspectives help turn a broad view of First Foundation into connected strategic questions. The BCG Matrix considers portfolio priorities; the Canvas traces value creation and economics; Five Forces and PESTLE examine outside pressure; the Marketing Mix considers client-facing choices; and SWOT brings internal and external considerations together. The Excel frameworks provide a structured way to organize comparisons, while the detailed Word files support deeper company-focused interpretation.
Company background: First Foundation — SEC 2025 Form 10-K filing.