

First Citizens Bank (NC): Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
First Citizens Bank (NC) Strategy Analysis Bundle
This bundle focuses on First Citizens Bank (NC), the banking business described in the supplied product context through consumer, mortgage, small-business and commercial lending. Its customers may range from households seeking everyday banking or home finance to business owners and commercial borrowers requiring credit, relationship support and risk-aware financial services.
Lending quality, collateral discipline, portfolio monitoring and diversification are especially relevant themes for this business. The six connected frameworks help examine how lending and customer propositions fit together, where resources may be concentrated, and how changing economic, competitive and regulatory conditions could shape strategic choices without assuming unverified results or recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, customer or service priorities merit resources when both market growth and relative market share are considered?
The First Citizens Bank (NC) BCG Matrix provides a disciplined way to compare possible banking portfolios rather than treating every product line as equally attractive. It can frame consumer lending, mortgage activity, small-business banking and commercial credit as distinct areas to assess against market growth and relative market share. The familiar Stars, Cash Cows, Question Marks and Dogs categories are analytical positions, not claims about this bank’s actual business units. For a lender, the useful discussion extends beyond volume: growth may require funding, specialist expertise, distribution capacity, underwriting attention and continuing credit surveillance.
- Portfolio comparison. Compare established banking activities with developing customer needs while keeping growth potential separate from relative competitive position.
- Capital discipline. Consider how a growing lending area could affect risk capacity, collateral controls and management attention before prioritising expansion.
- Working view. Use the Excel matrix to organise candidate activities, then use the Word analysis to record the assumptions and strategic questions behind each placement.
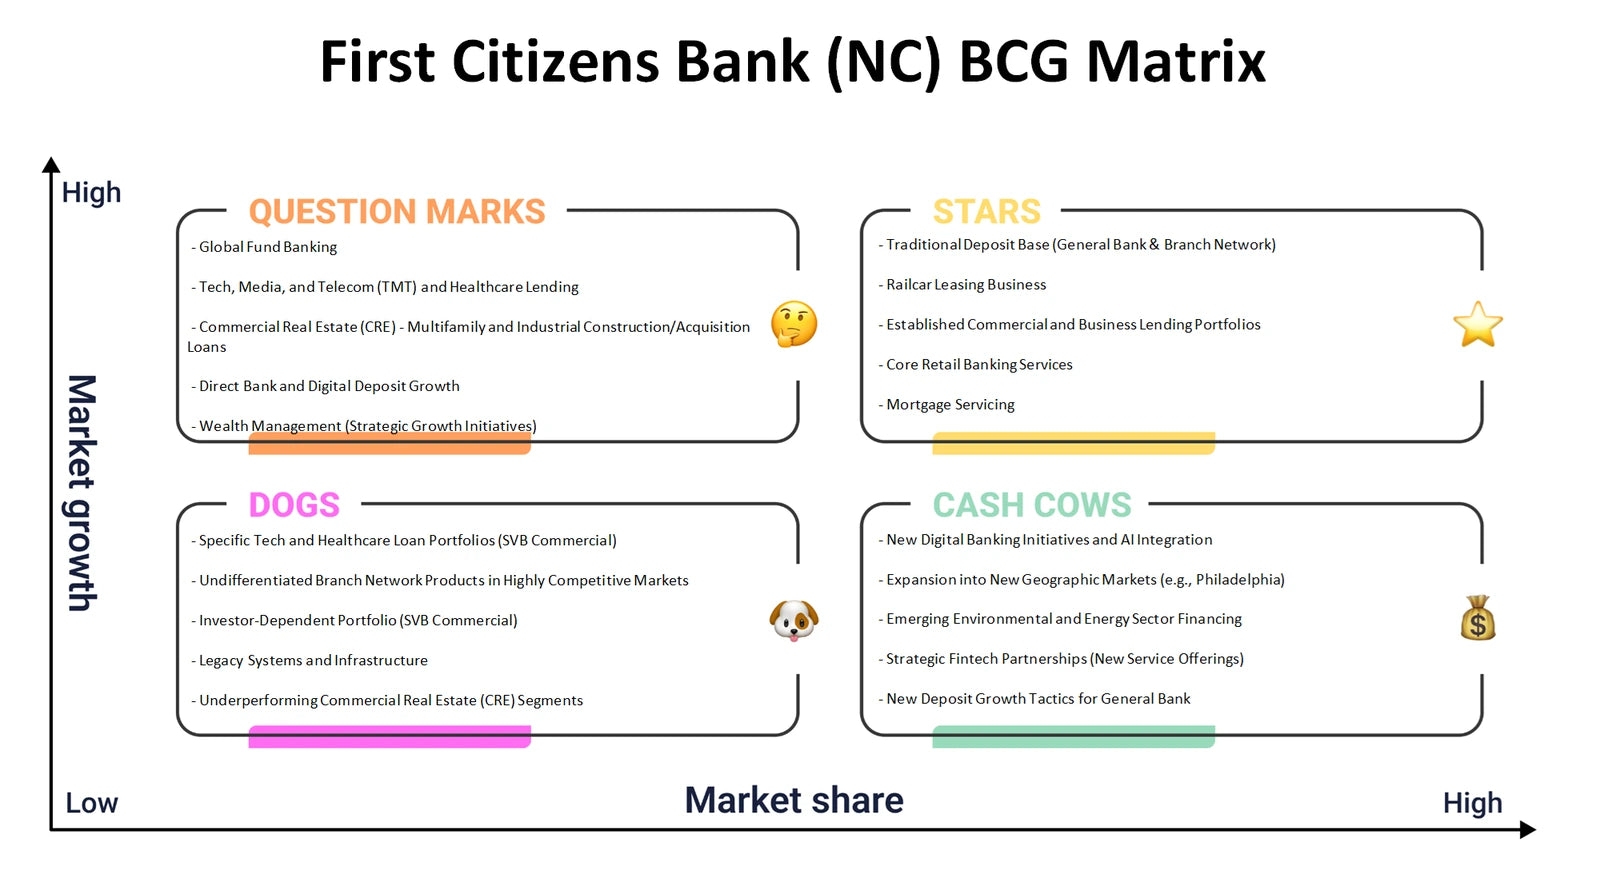
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, lending relationships, operating capabilities and economics connect in the bank’s business model?
The First Citizens Bank (NC) Business Model Canvas brings the bank’s value creation and revenue logic into one connected view. It considers customer segments, value propositions, channels and customer relationships alongside revenue streams, key resources, key activities, key partnerships and cost structure. Consumer, mortgage, small-business and commercial customers may require different propositions and relationship models, yet each depends on sound credit processes and dependable servicing. The canvas helps trace the links between delivering financing, managing collateral and monitoring exposures, while also asking where specialist partners, legal advice, compliance support or technology capabilities may be important to the operating model.
- Customer fit. Examine how household and business borrower needs may differ in service expectations, credit requirements and relationship depth.
- Economic links. Connect lending-related revenue streams to the resources, underwriting activities, partnerships and cost commitments required to serve them responsibly.
- Model mapping. Complete the Excel canvas block by block and use the Word analysis to interpret dependencies, trade-offs and unanswered business-model questions.
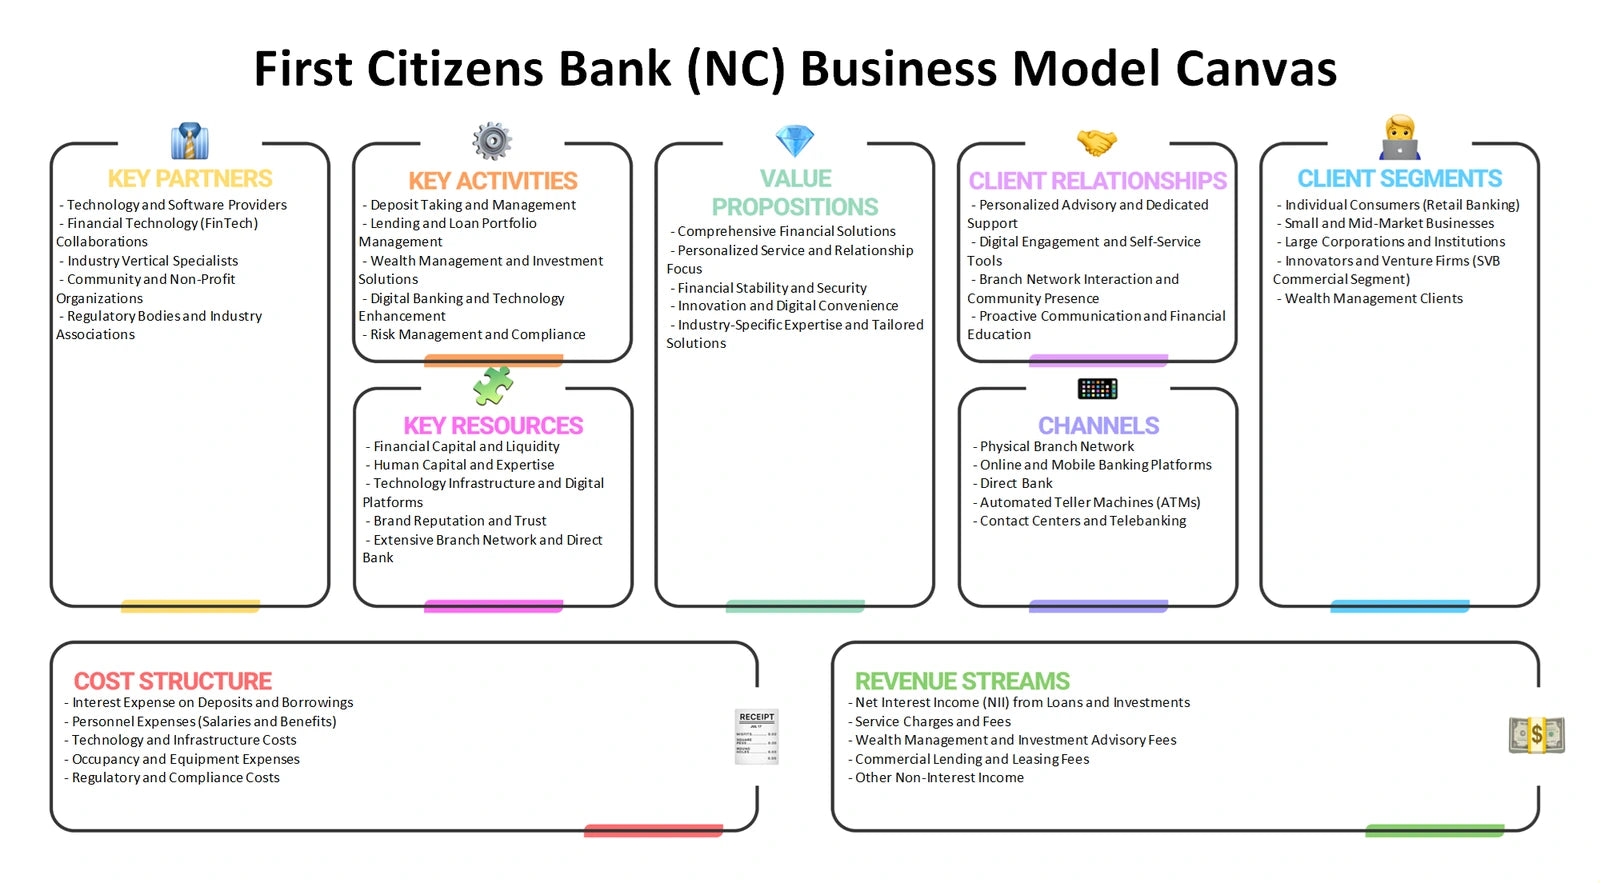
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence the attractiveness and resilience of the markets served by First Citizens Bank (NC)?
First Citizens Bank (NC) Porter's Five Forces analysis examines the competitive setting around banking, lending and financial relationships without assigning unsupported force scores. Rivalry can arise from institutions competing for deposits, loans and business relationships. Buyer power may increase when consumers or commercial borrowers can compare rates, service terms or financing alternatives. Supplier power can include the cost and availability of funding, specialist technology, data and professional services. New entrants may use digital delivery or focused propositions, while substitutes include non-bank financing, capital-market funding, fintech tools and other ways customers can meet payment, savings or credit needs.
- Competitive pressure. Identify where relationship banking, product breadth, credit expertise or service quality may matter more than headline pricing alone.
- Alternatives to credit. Separate direct banking rivals from substitute ways households and businesses may obtain finance or manage cash flow.
- Evidence trail. Use the Excel framework to compare the five forces and the Word analysis to capture the banking-specific rationale behind each pressure.
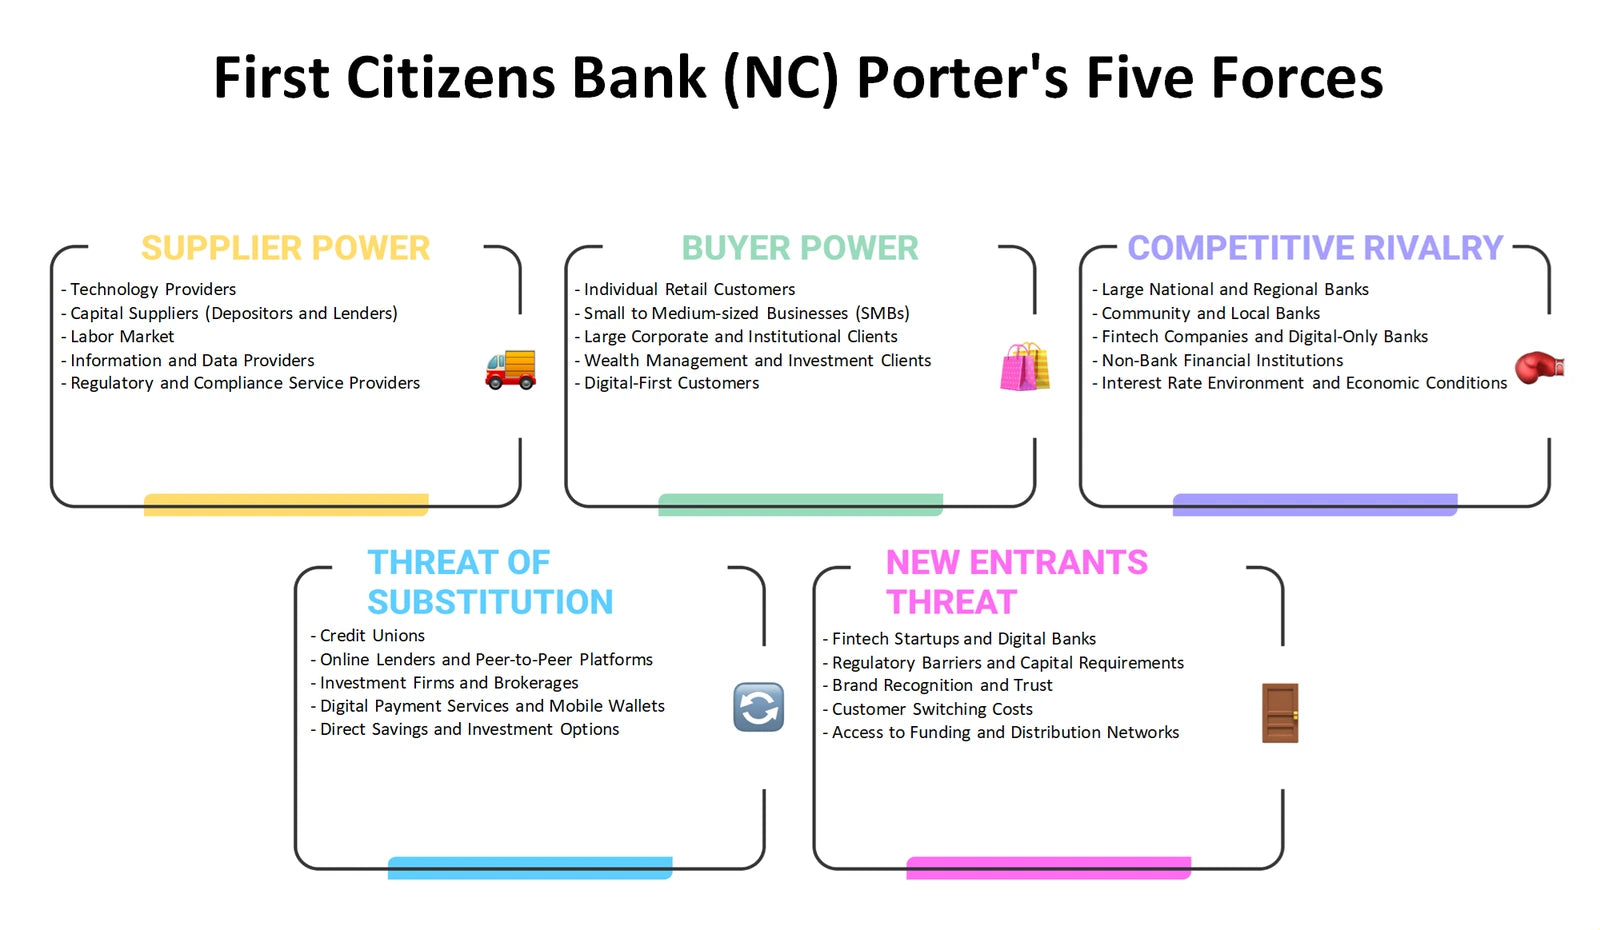
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking offers, pricing logic, access routes and communications be assessed for different customer groups?
The First Citizens Bank (NC) Marketing Mix considers Product, Price, Place and Promotion in a regulated, trust-dependent service environment. Product can include the way banking, mortgage, consumer, small-business and commercial lending solutions are organised around customer needs. Price is broader than a quoted rate: it can involve fees, credit terms, relationship value and risk-based economics. Place covers the routes through which customers research, apply, transact and receive support, while Promotion examines how messages communicate suitability, confidence and responsible financial decision-making. This lens helps avoid treating acquisition activity separately from servicing capacity and credit-quality considerations.
- Offer design. Compare how lending and banking propositions may need to differ for households, entrepreneurs and commercial customers.
- Trust and access. Explore the balance between convenient customer access, clear communications and the reassurance expected from financial services.
- Planning support. Use the Excel 4Ps structure to test messaging and channel questions, then consult the Word analysis for context on the related customer and operating trade-offs.
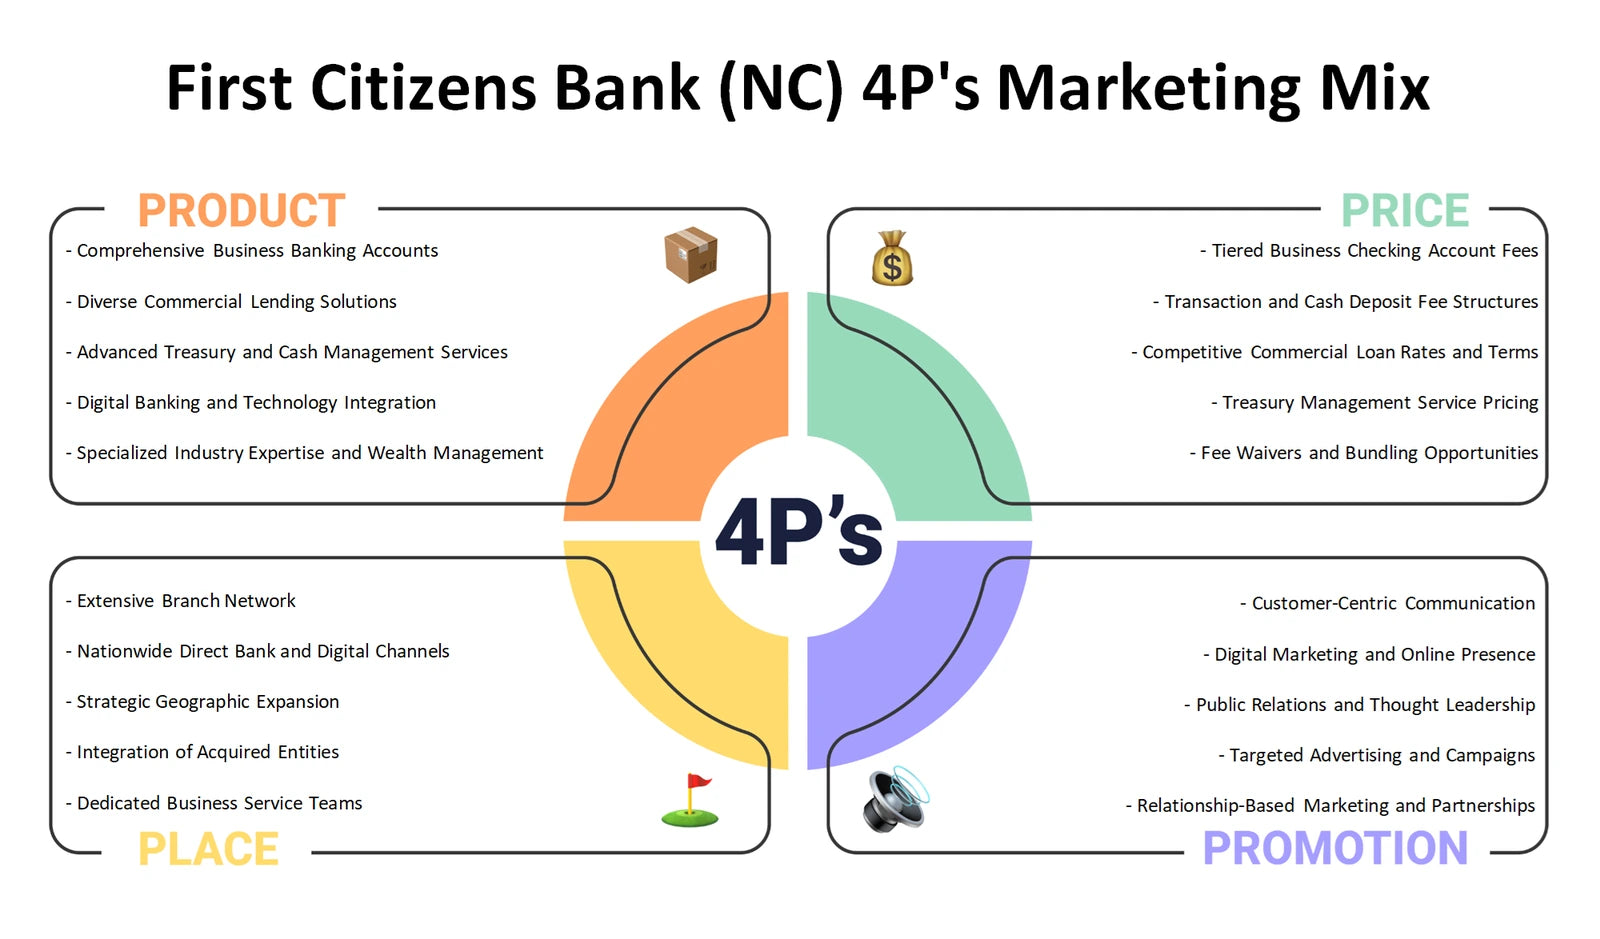
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter lending demand, operating requirements or risk management priorities for the bank?
The First Citizens Bank (NC) PESTLE analysis, also commonly called PESTEL, organises the external conditions that can influence a banking business. Political factors may affect public policy priorities and supervisory expectations; economic conditions can shape borrower demand, credit performance, funding costs and property-related activity. Social shifts may change how customers expect to access and understand financial services. Technological developments raise questions about digital delivery, security and third-party dependence. Legal factors include compliance, consumer protection and lending obligations, while environmental considerations may affect collateral, borrower resilience and long-term risk assessment. These are areas to examine, not assertions that a particular change has occurred.
- External signals. Separate macroeconomic and policy questions from operational technology, customer-behaviour and credit-risk implications.
- Risk connections. Consider how an external factor might flow through to underwriting standards, monitoring routines, customer demand or compliance workload.
- Scenario use. Use the Excel PESTLE categories to log developments and use the Word analysis to develop reasoned scenarios for strategic review.
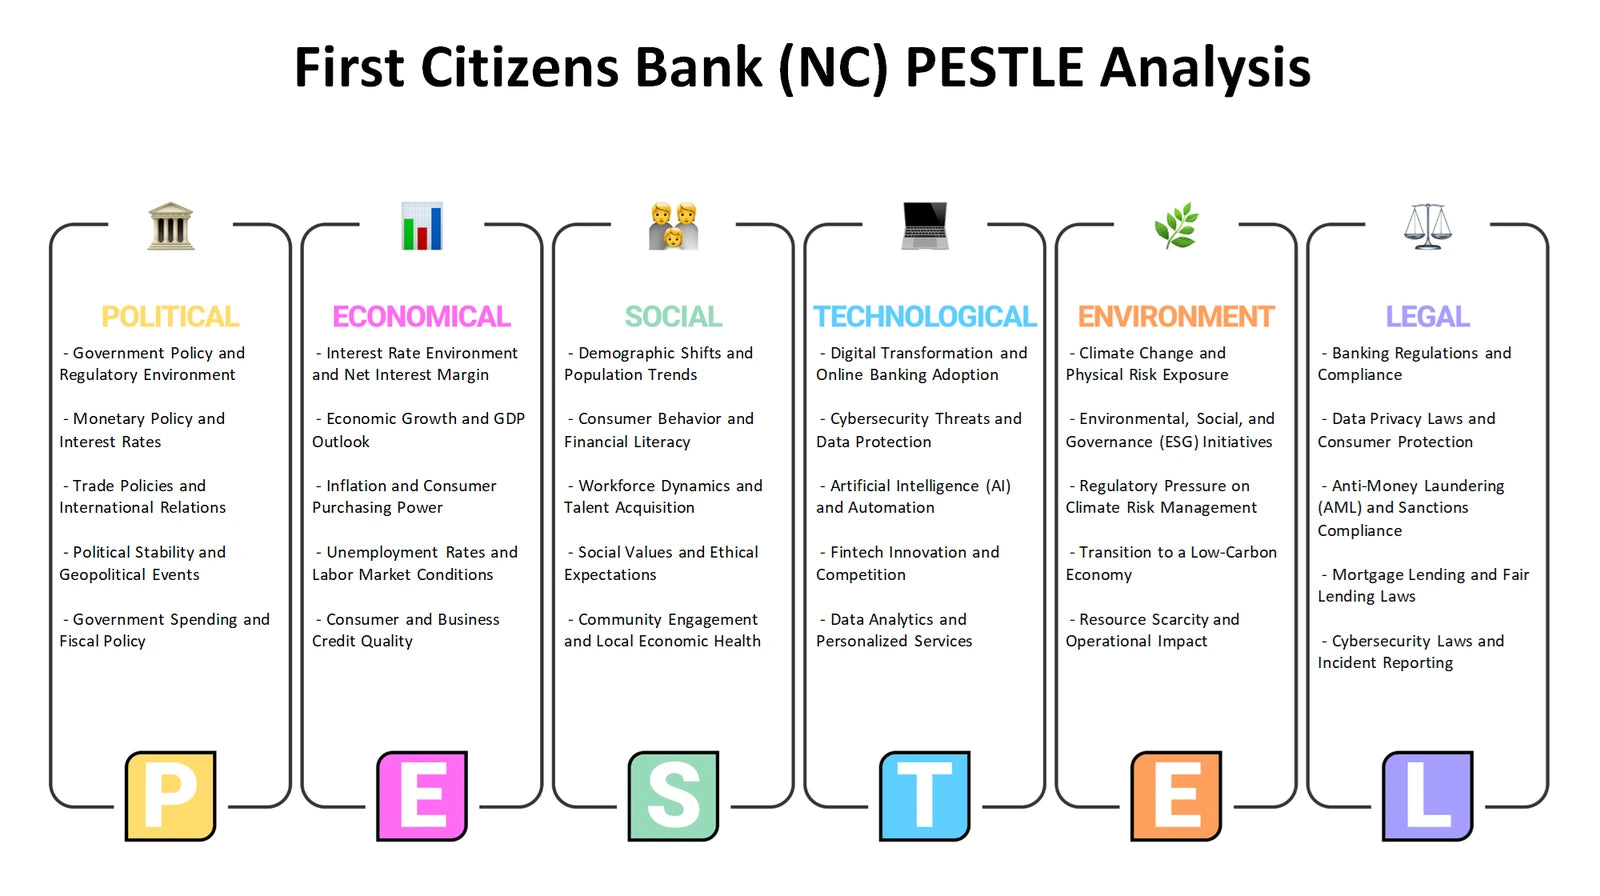
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities and limitations be considered alongside external opportunities and threats in lending-led banking?
The First Citizens Bank (NC) SWOT analysis distinguishes internal strengths and weaknesses from external opportunities and threats. Potential internal discussion areas include underwriting processes, collateral management, portfolio monitoring, relationship capabilities and the ability to serve varied borrower groups; the framework does not present these as proven advantages or deficiencies. External opportunities may emerge from changing customer needs or market gaps, while threats can include economic stress, competitive alternatives, cyber exposure, shifting regulation or concentrated risks. The value of SWOT is in testing whether a possible opportunity fits the bank’s actual capabilities and whether an identified threat exposes a manageable operating weakness or a broader market condition.
- Correct classification. Keep controllable resources, processes and constraints on the internal side, while placing market, regulatory and economic conditions outside the organisation.
- Strategic fit. Link a possible growth opportunity to the credit discipline, people, systems and governance needed to pursue it responsibly.
- Action review. Use the Excel SWOT grid to prioritise observations and the Word analysis to add context, ownership questions and strategic implications.
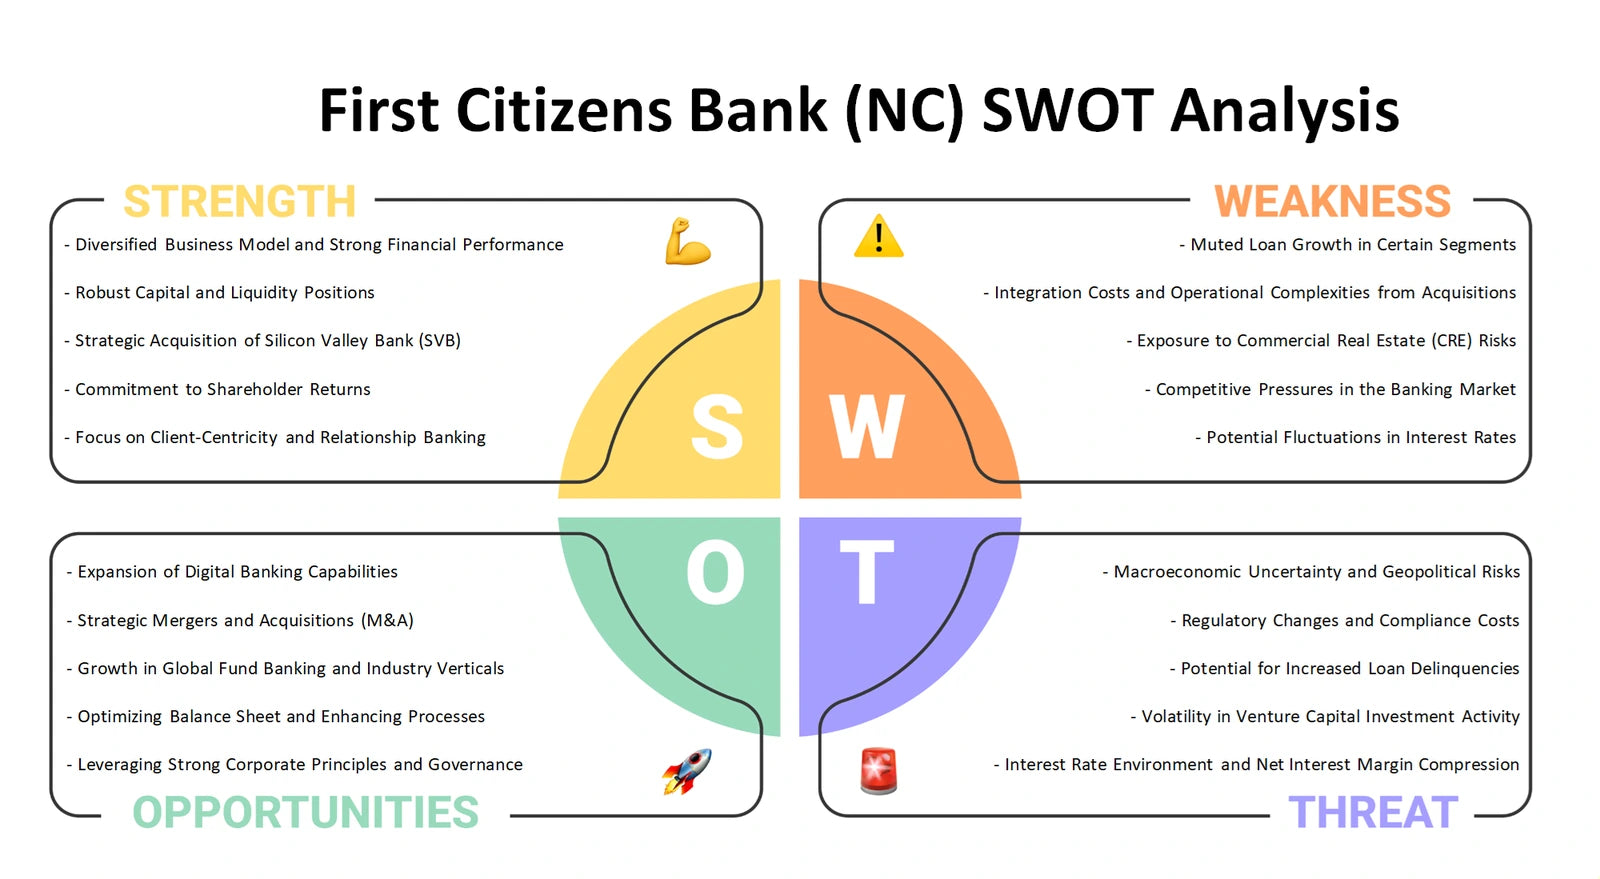
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the operating model
Together, the six perspectives let customers examine First Citizens Bank (NC) from linked but distinct angles: portfolio priorities, value creation, industry pressure, customer-market choices, external change and strategic fit. The Excel frameworks provide structured places to compare issues and develop working assumptions, while the detailed Word analysis supports a fuller discussion of banking, lending, credit-risk and operating considerations. Used together, they can help turn broad strategic questions into a more organised company-specific review.
Company background: First Citizens Bank (NC) — supplied product-context page.