

First Interstate Bank: Banking Business and Fulfillment – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
First Interstate Bank Strategy Analysis Bundle
First Interstate Bank is a United States regional financial-services business operating within First Interstate BancSystem, Inc. Its banking and lending activities serve consumer and business customers, making decisions about deposits, credit, service delivery, risk and customer access closely connected rather than separate product choices.
Its parent company, First Interstate BancSystem, Inc., reported GAAP net income of US$83.9 million for April 1 through June 30, 2026, filed on August 3, 2026. That single-quarter result raises practical questions about portfolio priorities, funding and lending economics, and which customer channels merit continued investment. It does not indicate when the downloadable analysis files were prepared.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking and lending activities deserve capital, management attention and measured experimentation?
The First Interstate Bank BCG Matrix uses market growth and relative market share rather than a simple revenue ranking to examine portfolio priorities. It helps compare mature deposit, lending, mortgage or service propositions against faster-changing opportunities after defining the relevant customer market for each one. The familiar Stars, Cash Cows, Question Marks and Dogs categories are analytical lenses, not pre-assigned conclusions. For a regional bank, the value is in making resource trade-offs visible where capital, funding capacity, technology investment and risk oversight compete for attention.
- Comparable markets. Test whether products should be compared by customer type, lending purpose, geography or service channel before considering relative share.
- Capital discipline. Explore how growth potential may differ from cash generation, operating complexity and risk-adjusted resource needs.
- Portfolio working session. Use the Excel framework to organize candidate activities and assumptions, then use the Word analysis to discuss the implications behind each possible category.
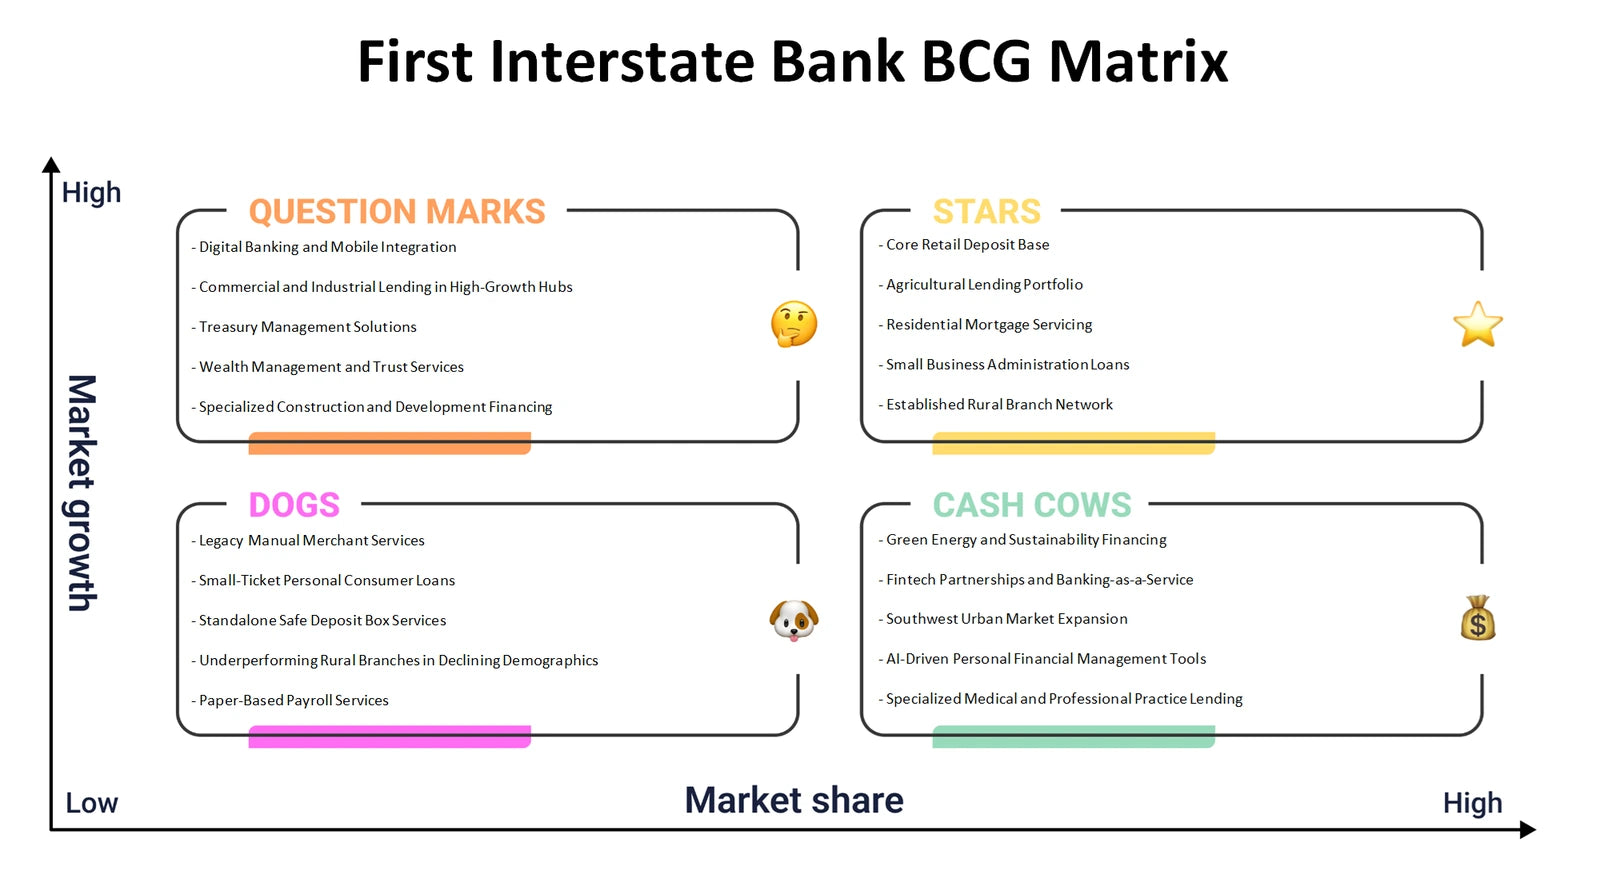
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer service, lending fulfillment, funding and operating costs connect into one economic model?
The First Interstate Bank Business Model Canvas maps customer segments, value propositions, channels and customer relationships alongside revenue streams. It then connects those customer-facing choices to key resources, key activities, key partnerships and cost structure. This is particularly useful for examining how banking and mortgage workflows create value while managing liquidity and execution. For example, secondary-market relationships, servicing support and pipeline-management practices can be considered as possible links between loan fulfillment, rate commitments, balance-sheet flexibility and the cost to serve.
- Value chain connections. Trace how deposits, lending and support interactions may affect both customer experience and the economics of delivery.
- Partnership logic. Examine where investors, servicing providers, technology suppliers or other partners may add scale while introducing dependency or control questions.
- Model alignment. Populate the Excel canvas with working assumptions, then use the detailed Word analysis to review whether the nine building blocks reinforce one another.
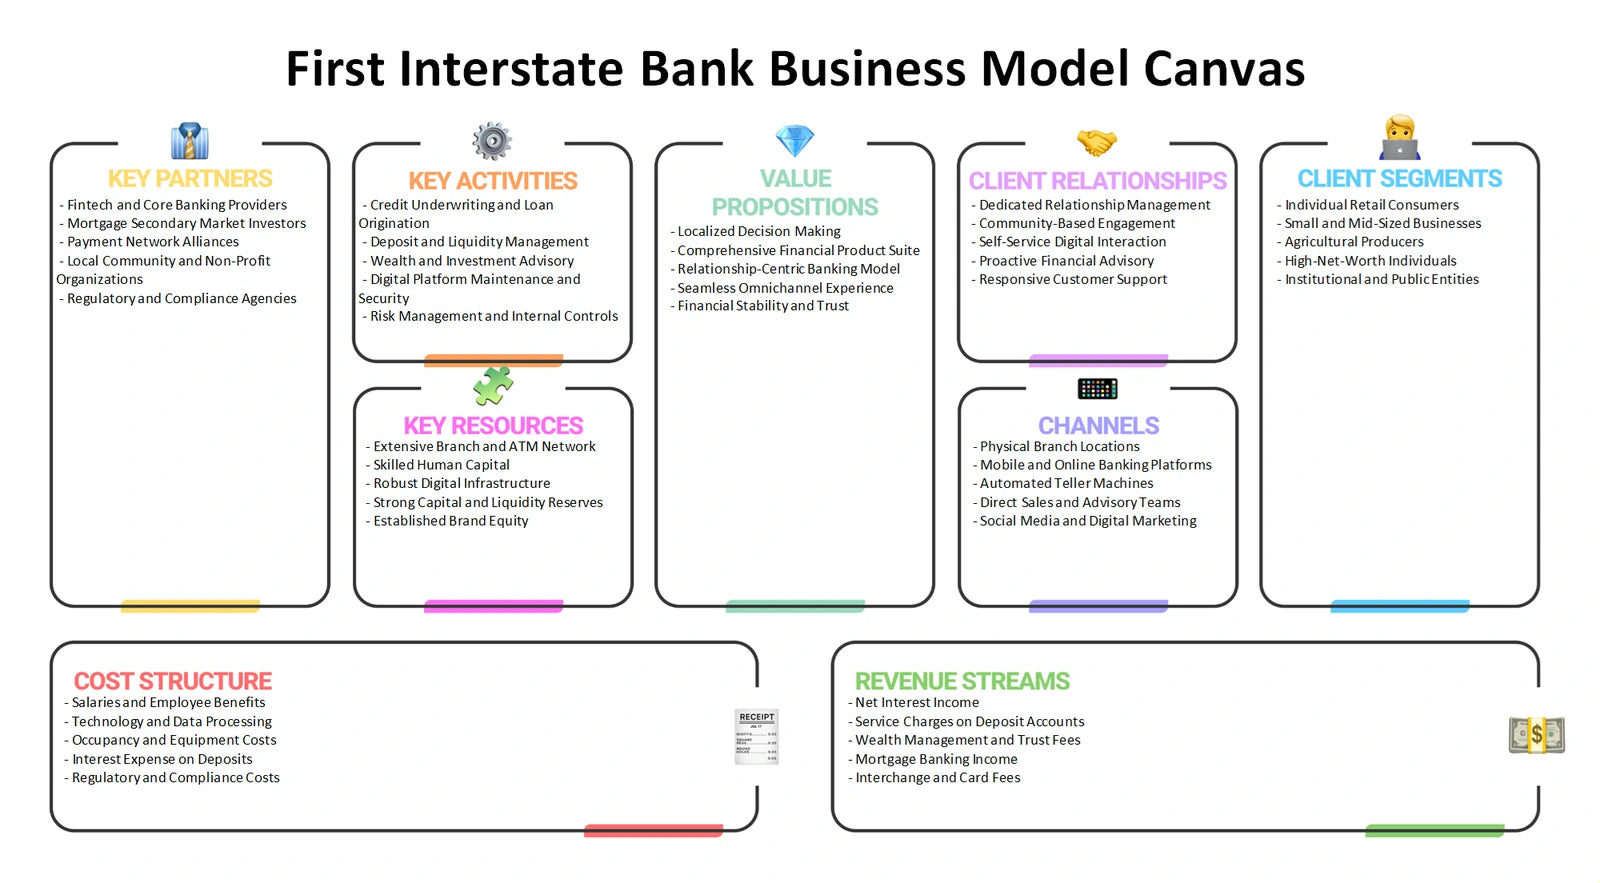
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape margins, customer retention and the cost of competing in regional banking?
The First Interstate Bank Porter's Five Forces analysis looks beyond named competitors to assess rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes. Banking customers can compare rates, fees and service convenience, while funding sources, technology providers, payment infrastructure and mortgage-market counterparties can influence operating economics. Entrants may include digitally focused financial providers, and substitutes can include nonbank credit, payment tools or other ways customers meet borrowing, saving and transaction needs. The framework helps distinguish a broad competitive concern from the specific pressure it could place on profitability or customer relationships.
- Customer switching. Consider how rate sensitivity, digital expectations and relationship-based service can affect buyer power across different banking needs.
- Funding and vendor exposure. Compare the influence of deposit competition, capital-market connections and essential operational suppliers on flexibility.
- Pressure map. Use Excel to record evidence and questions for each force, with the Word analysis providing a fuller narrative for discussing strategic responses.
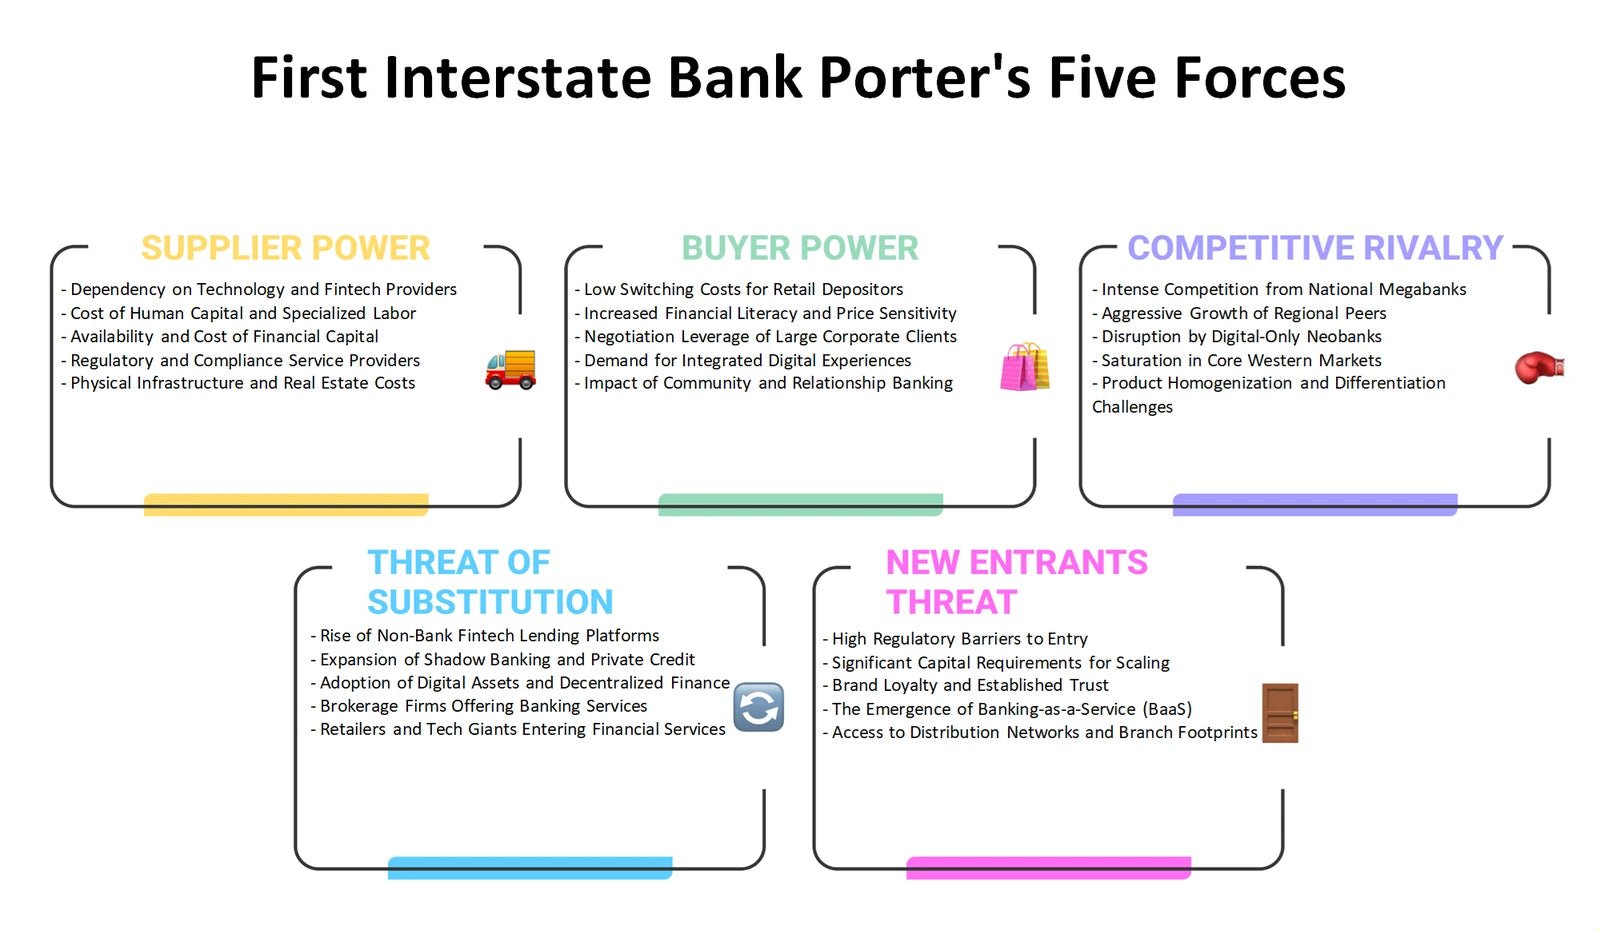
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking offers, pricing communication and service access be assessed together for target customers?
The First Interstate Bank Marketing Mix considers Product, Price, Place and Promotion in a regulated financial-services setting. Product covers the usefulness and clarity of deposit, credit and support offerings. Price examines rates, fees and margin trade-offs without assuming any particular pricing level. Place extends beyond a physical location to assisted, phone and digital routes through which customers open accounts, seek help or progress a lending need. Promotion tests whether communications explain value and terms clearly while supporting trust. The framework is useful because a strong offer can still underperform if access, pricing explanation or customer communication is mismatched.
- Offer design. Compare whether customer needs are best served by product breadth, simpler journeys, specialist assistance or more relevant service bundles.
- Channel consistency. Assess how phone support, self-service and relationship-led interactions can be evaluated for accessibility and resolution quality.
- Go-to-market review. Organize the four Ps in Excel for cross-functional comparison, then use the Word analysis to explore the service and compliance context behind the choices.
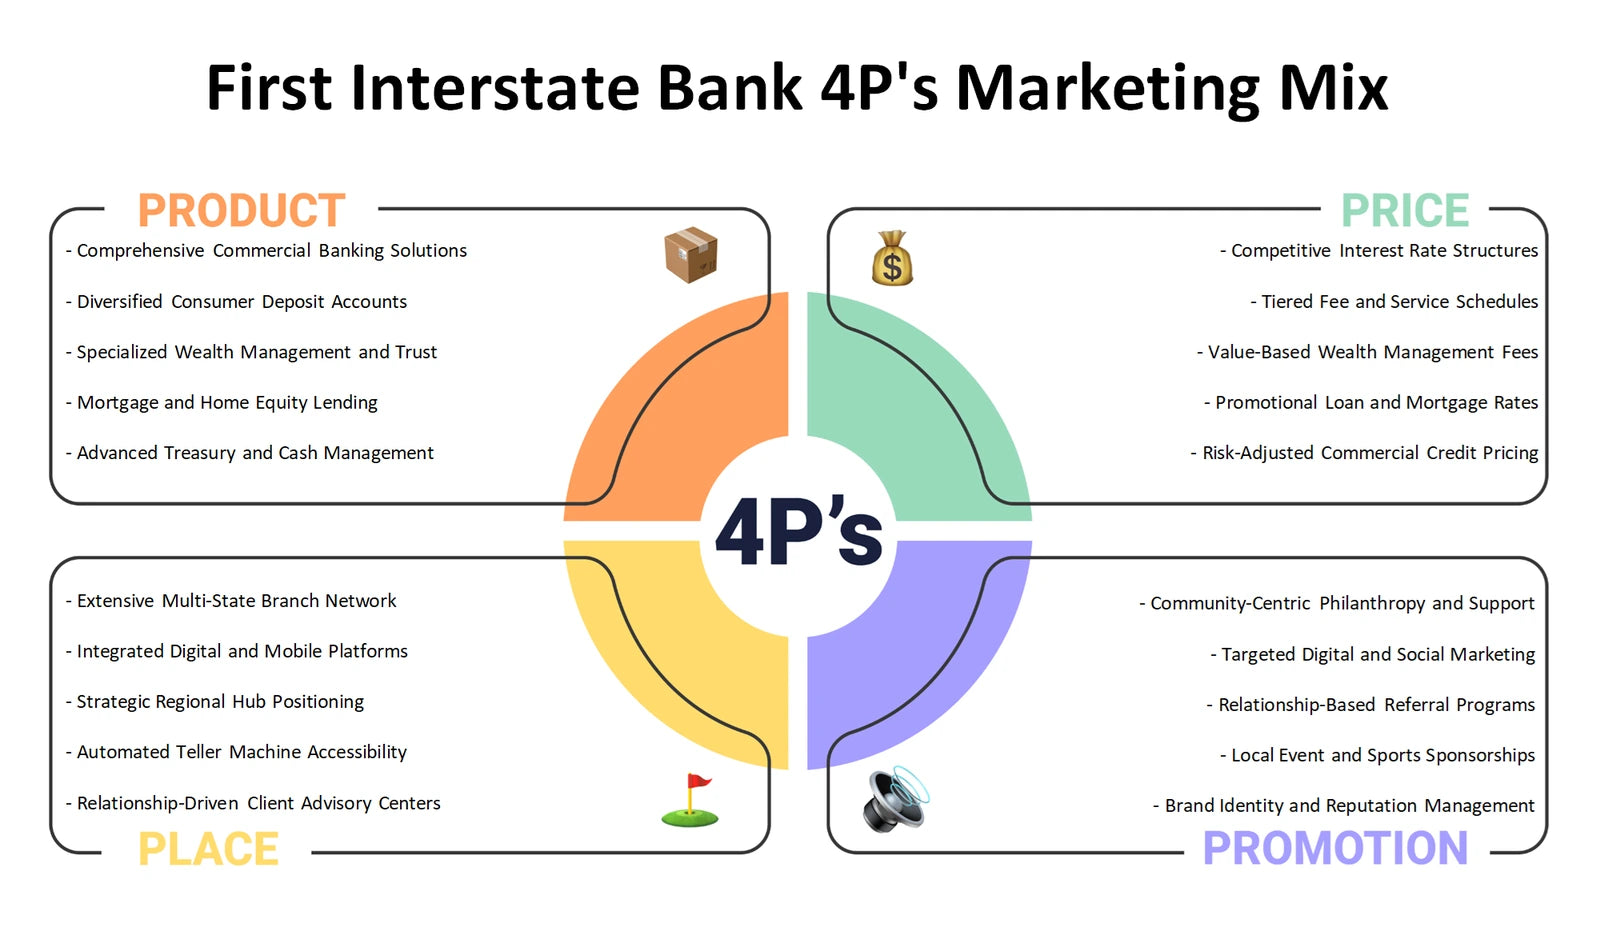
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter customer demand, lending risk, operating costs or regulatory expectations?
The First Interstate Bank PESTLE analysis, often called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences so external issues are not treated as one undifferentiated risk list. Political and legal questions can include financial-services policy, supervision, consumer protection, privacy and anti-money-laundering requirements. Economic factors may affect borrowing demand, credit conditions, funding costs and interest-rate sensitivity. Social expectations around convenience and trust interact with technology choices such as security, fraud prevention and digital service. Environmental conditions can also be considered where severe weather or climate-related exposure affects customers, collateral or continuity planning.
- External signals. Separate a possible policy or rate scenario from an established change, helping teams avoid treating assumptions as facts.
- Linked exposures. Explore how technology, customer behavior and legal obligations may combine to affect service delivery and control requirements.
- Scenario register. Use the Excel framework to sort external developments by category and relevance, while the Word analysis supports a more detailed discussion of possible implications.
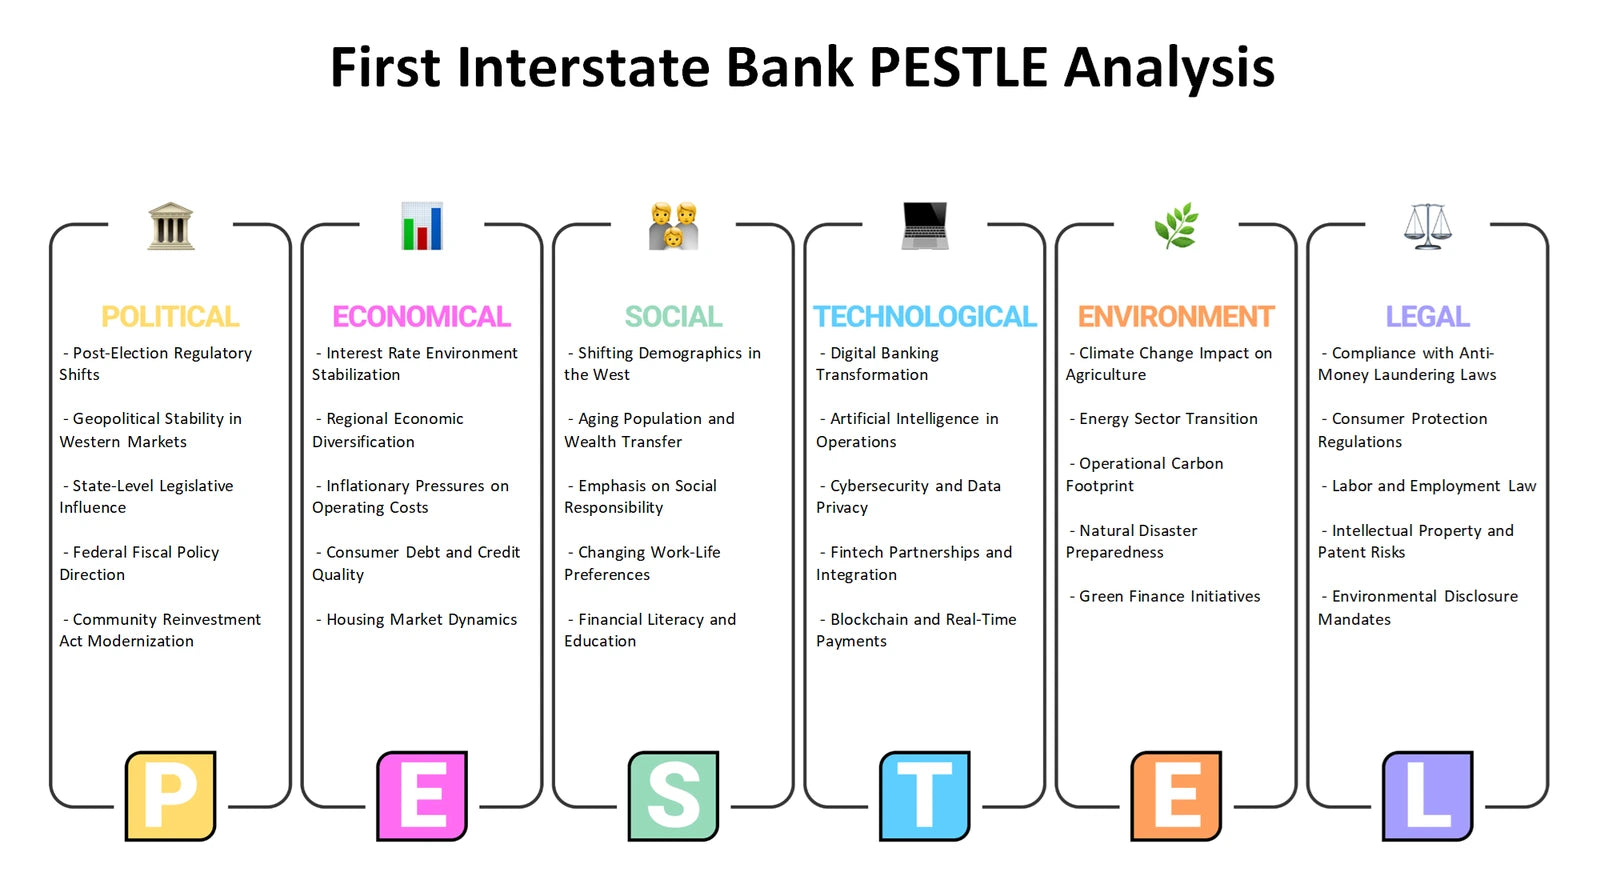
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities and constraints be considered alongside changing financial-services conditions?
The First Interstate Bank SWOT analysis keeps internal Strengths and Weaknesses distinct from external Opportunities and Threats. It provides a practical way to examine possible internal capabilities such as customer-service expertise, lending knowledge, risk processes, technology resources or partnership management without automatically treating them as proven advantages. It also separates external opportunities, such as evolving customer needs, from threats including competitive pressure, credit deterioration, cyber risk or regulatory change. This distinction matters because an issue should be managed differently depending on whether the bank can directly improve it or must adapt to a market condition.
- Internal reality check. Review whether resources, processes and service capabilities are supported by evidence and where operational limitations need attention.
- External fit. Compare market opportunities and threats with the capabilities required to respond, rather than listing broad industry trends in isolation.
- Priority conversion. Use Excel to capture and group SWOT observations, then use the detailed Word analysis to turn the most relevant combinations into focused discussion topics.
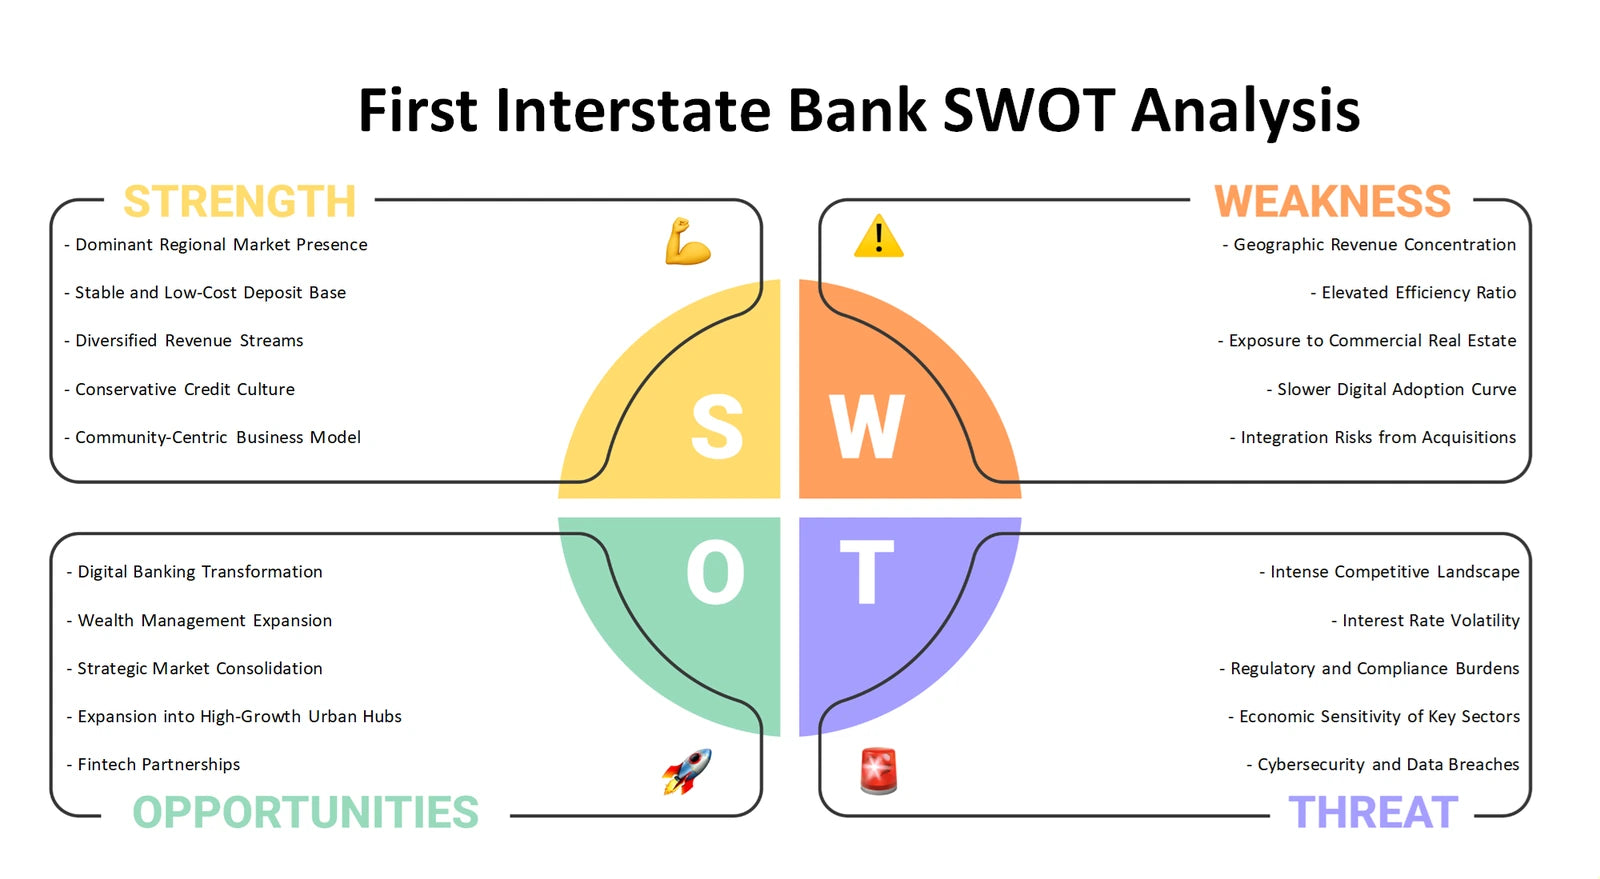
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more connected strategic view
Together, the six perspectives let you examine First Interstate Bank from portfolio, business-model, industry, customer-market, external-environment and capability angles. The Excel frameworks provide a structured way to organize questions and comparisons, while the Word files provide detailed company analysis to support more informed internal discussion.
Company background: First Interstate Bank — corporate overview from First Interstate BancSystem, Inc..