

Fedbank Financial Services: Underwriting and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Fedbank Financial Services Strategy Analysis Bundle
This bundle examines Fedbank Financial Services through the branch-led lending model described in the supplied business context. That context centres on local branches serving urban, semi-urban and rural catchments, with relationship managers and certified appraisers supporting sourcing, underwriting, collections and gold-loan cycles. It also describes digital lending tools such as LOS/LMS, eKYC, eNACH, e-sign, bureau connections and field mobility support.
These operating features make resource allocation, borrower experience, credit control and distribution economics practical strategic questions. The six analyses do not claim pre-set conclusions about performance; instead, they help users examine how local service, secured lending processes, technology-enabled origination and external lending conditions may fit together in a structured decision-making view.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending activities deserve additional branch, technology and risk-management capacity when growth and relative market share are considered together?
A Fedbank Financial Services BCG Matrix helps separate portfolio-priority questions from assumptions about any one lending product. The framework compares market growth with relative market share, then uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to organise discussion. For a branch-supported secured-lending operation, the useful issue is not simply whether loan demand is attractive: it is whether a product or customer route can justify appraiser capacity, working capital, local collection effort and digital-process investment. It can also highlight where mature activity may fund newer growth opportunities, where market expansion warrants testing, and where complexity may consume more managerial attention than it returns.
- Portfolio logic. Compare gold-loan activity, branch catchments and other relevant lending lines only after defining their market boundaries and relative-share evidence.
- Capacity trade-offs. Examine how sourcing teams, appraisal expertise, turnaround expectations and collections requirements vary between potentially different portfolio priorities.
- Structured comparison. Use the Excel framework to map candidate activities against growth and relative share, then use the Word analysis to record assumptions, evidence gaps and implications.
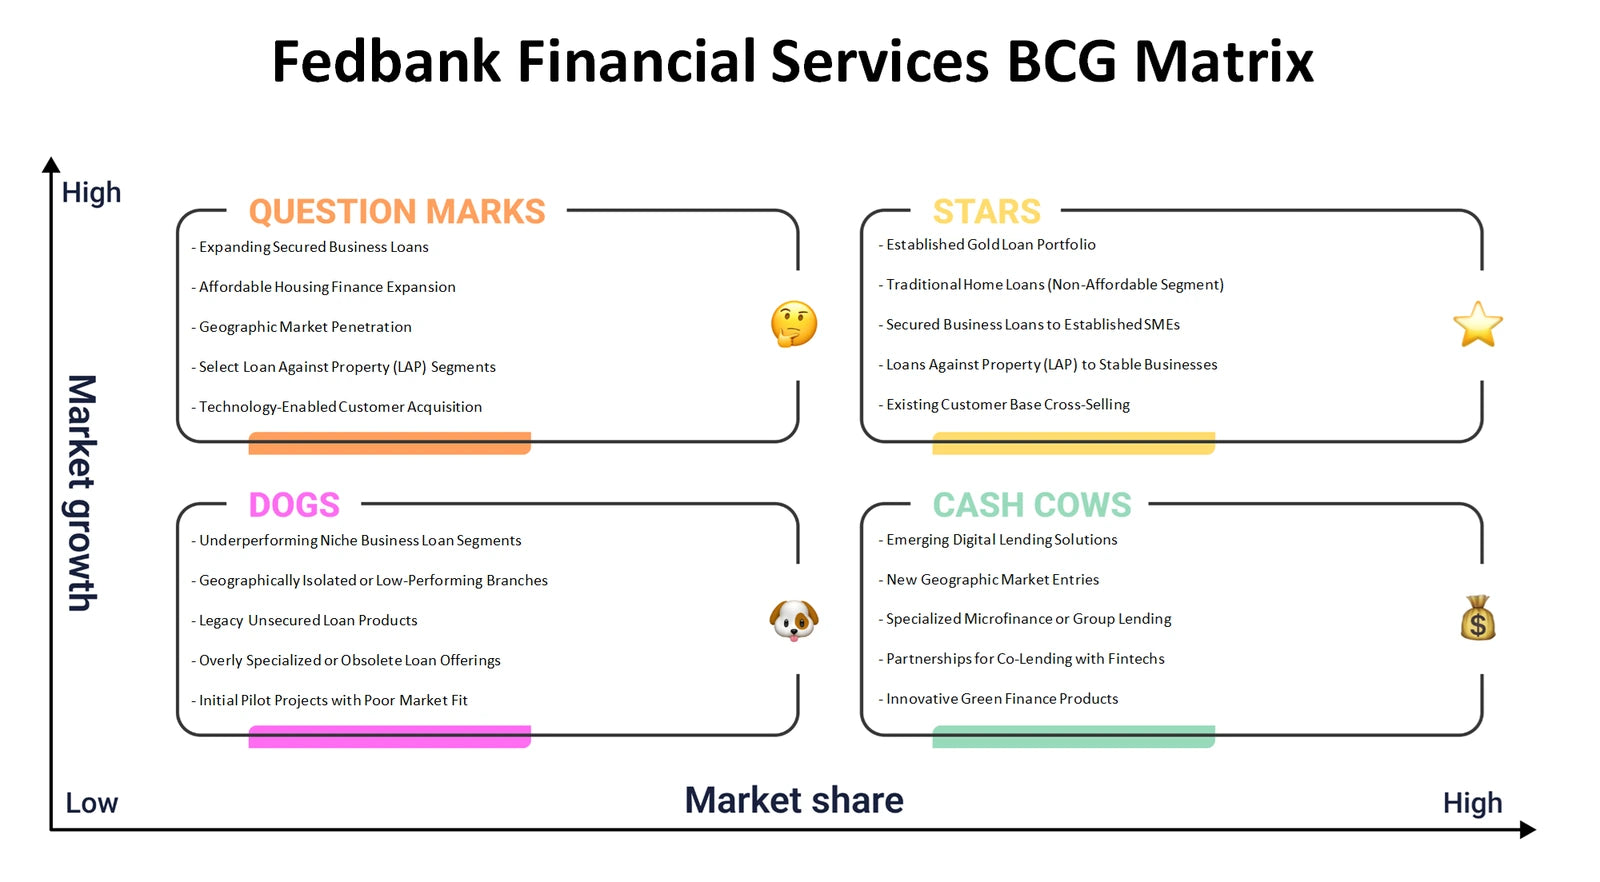
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do local branch service, digital lending processes and credit controls combine to create value for borrowers and sustainable lending economics?
The Fedbank Financial Services Business Model Canvas connects the nine building blocks behind the operating model. It helps examine customer segments such as borrowers seeking accessible secured credit; value propositions such as convenient local assistance and faster processing; channels including branches, field teams and digital touchpoints; and customer relationships shaped by responsive service and repayment contact. It also brings revenue streams, key resources, key activities, key partnerships and cost structure into one coherent view. For this business context, trained people, appraisal capability, loan-processing systems, bureau links, e-signing, collection routines and partner interfaces can be considered together rather than as isolated operational features. The result is a more disciplined view of what must work simultaneously for a lending proposition to deliver value and earn returns.
- Value-chain links. Trace how branch reach and field service can support borrower access while technology reduces manual hand-offs in origination and disbursal.
- Economic dependencies. Consider how interest and fee-based revenue logic may be affected by funding, staff, technology, compliance, collection and branch-related costs.
- Model workshop. Populate the Excel canvas block by block and use the Word analysis to explore the connections, dependencies and unanswered validation questions behind each block.
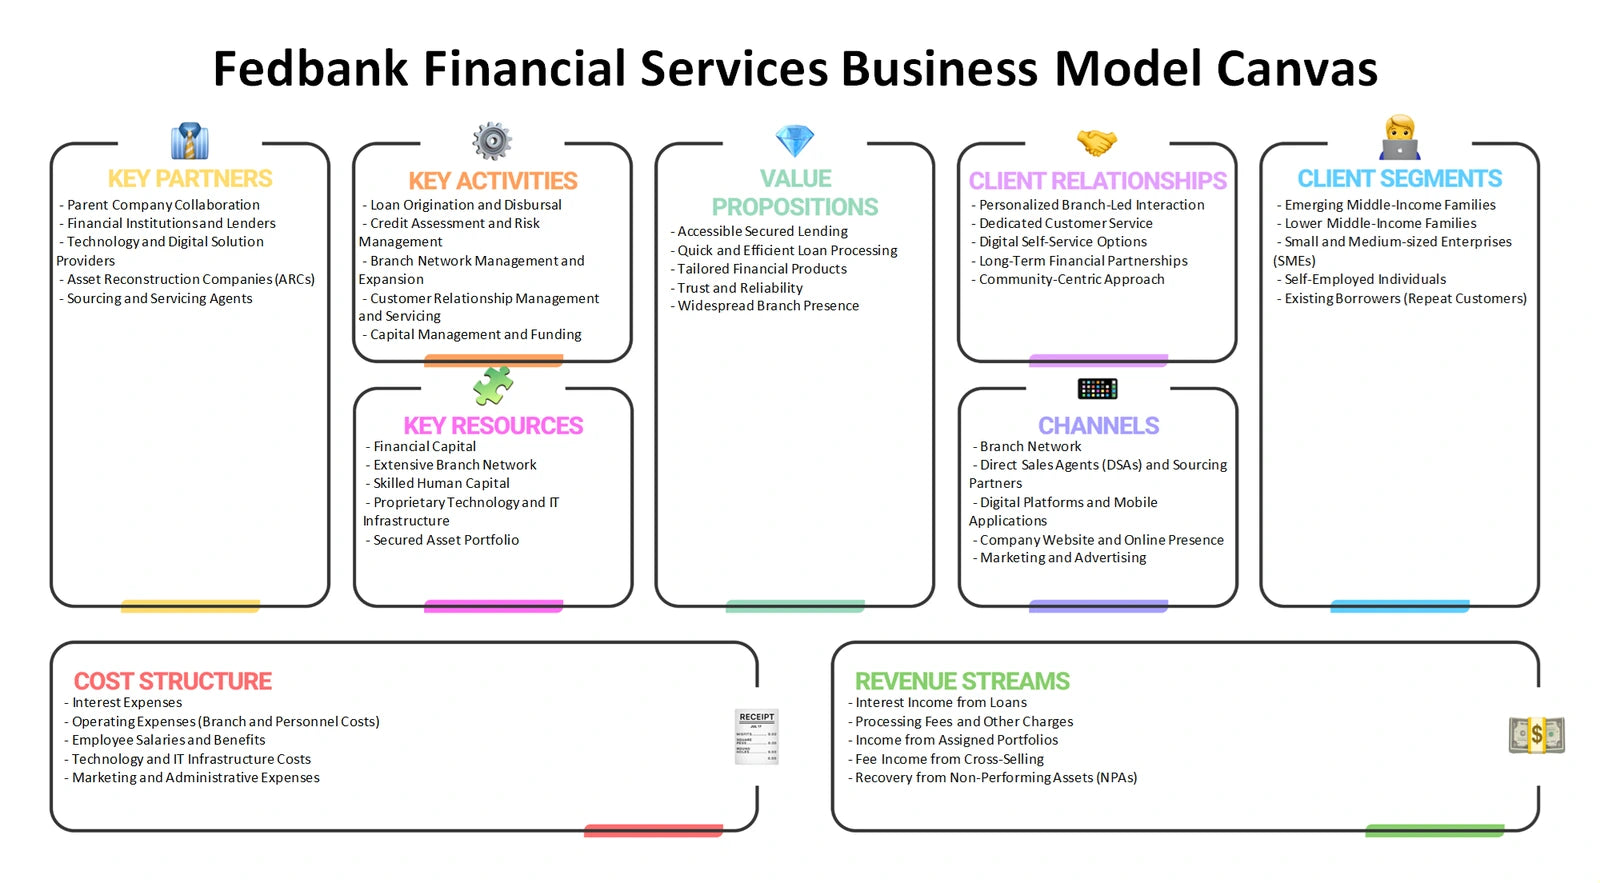
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence lending margins, borrower retention and the cost of delivering branch-supported credit?
Fedbank Financial Services Porter's Five Forces analysis examines the competitive environment around secured and consumer lending without assuming a force score. Rivalry can be explored through competing lenders’ efforts to attract similar borrowers and maintain service speed. Buyer power concerns how readily customers can compare terms, convenience and trust before choosing a credit provider. Supplier power is relevant to funding sources, specialist talent, technology providers, information services and other inputs needed to operate reliably. The threat of new entrants includes digitally enabled lenders and other firms capable of building distribution and underwriting capability. Substitutes are broader alternatives that meet a borrower’s cash-flow need, such as bank credit, other secured borrowing, savings or informal support, rather than only direct lending competitors.
- Rivalry and switching. Assess whether local presence, service responsiveness and turnaround time are meaningful differentiators where borrowers can evaluate alternative credit routes.
- Input exposure. Consider how dependence on capital, data connections, qualified appraisers and compliance-ready systems may affect operating resilience and unit economics.
- Evidence-led review. Use the Excel framework to compare force drivers and use the Word analysis to document why each pressure matters for pricing, service design or risk control.
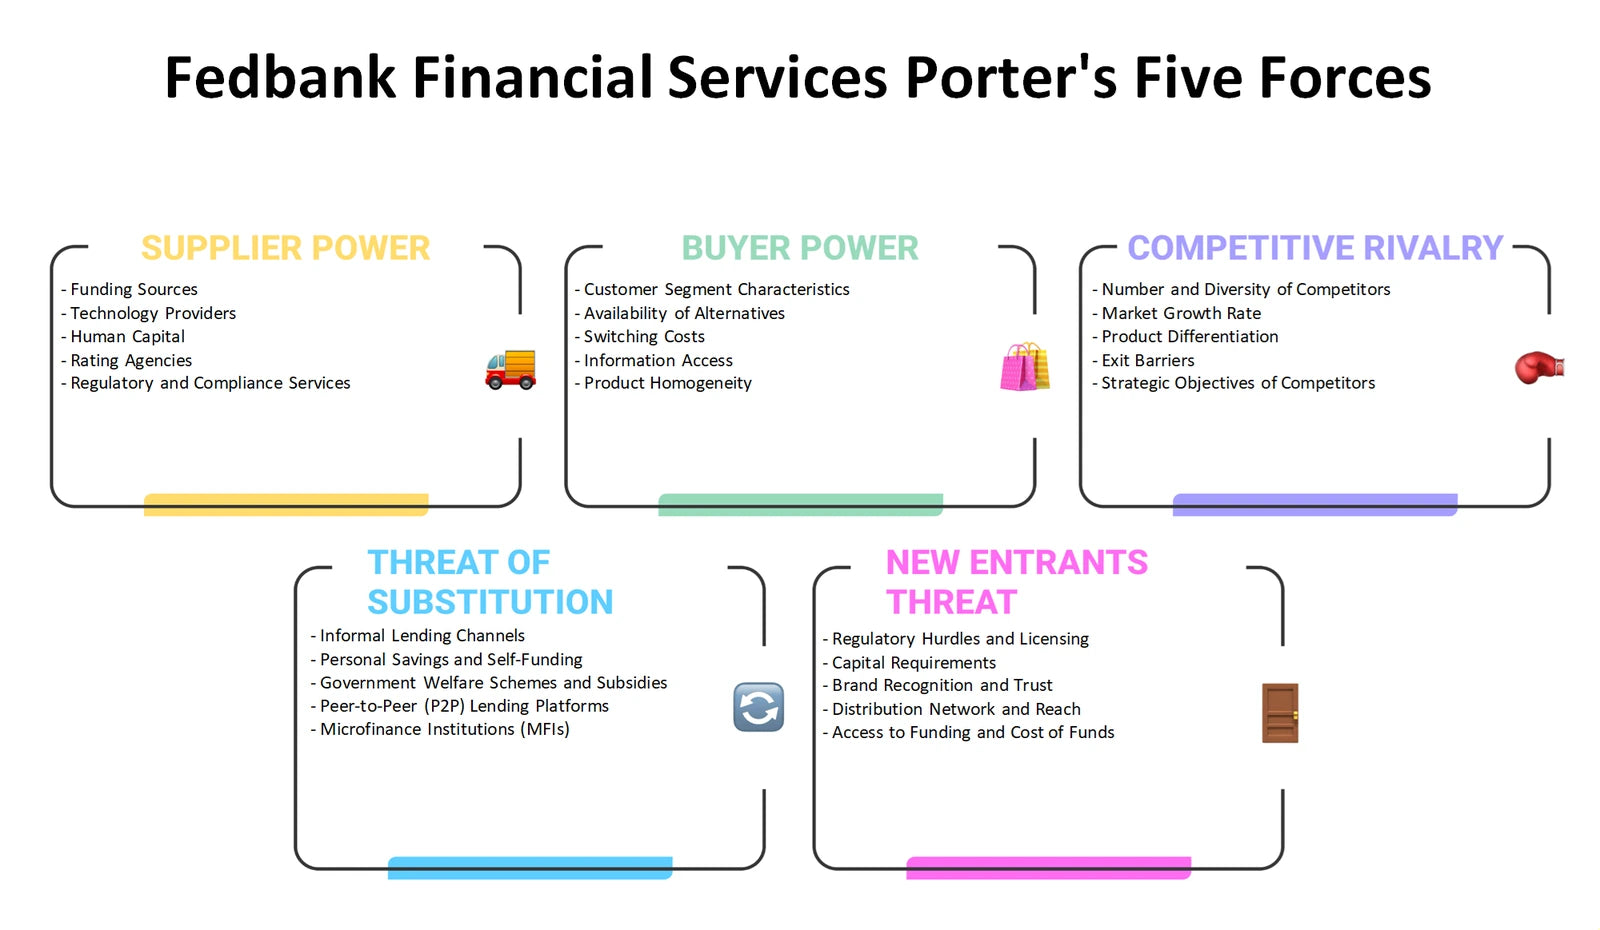
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can the product proposition, pricing logic, access points and communications be assessed for borrowers who value both speed and confidence?
The Fedbank Financial Services Marketing Mix considers Product, Price, Place and Promotion in the context of a regulated, trust-sensitive lending service. Product analysis can examine gold-backed lending and the service features surrounding appraisal, documentation, disbursal and repayment support. Price is not limited to a headline rate: it prompts review of how charges, transparency, credit risk, funding economics and borrower affordability should be considered. Place includes the practical role of branches across varied catchments, relationship managers, field support and digital process steps. Promotion is especially important where customers may need clear, responsible communication about eligibility, pledged assets, service steps and repayment obligations. Together, the 4Ps help align commercial messaging with the actual experience delivered at local and digital touchpoints.
- Service proposition. Examine which aspects of appraisal support, documentation convenience, disbursal speed and collection contact are meaningful to different borrower needs.
- Route-to-customer fit. Compare the role of branch access, field origination and digital onboarding without assuming a particular channel mix or campaign outcome.
- Planning application. Use the Excel 4Ps structure to organise product and channel choices, then refer to the Word analysis when discussing trade-offs between borrower clarity, acquisition and control.
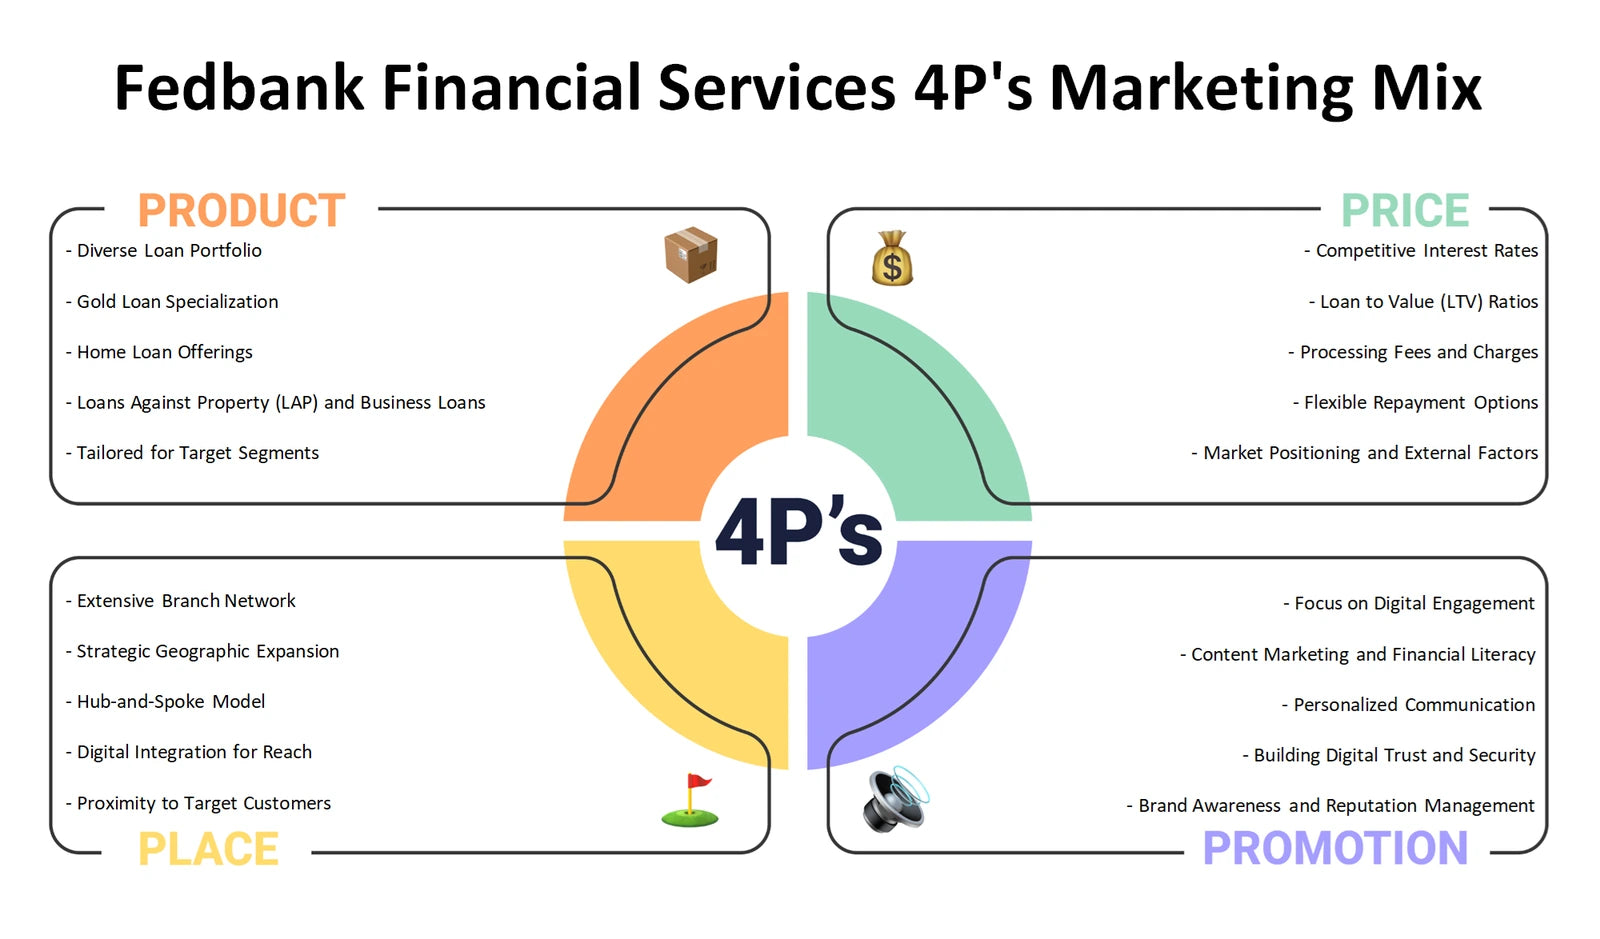
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter demand, risk controls, technology priorities and operating costs for a branch-enabled lender?
A Fedbank Financial Services PESTLE analysis, also commonly called PESTEL, examines the external setting rather than treating all challenges as internal execution issues. Political factors can include the policy environment affecting financial inclusion, lending supervision and consumer confidence. Economic factors invite assessment of borrower cash flows, funding conditions, inflation, asset values and repayment stress. Social factors include trust in secured lending, local service preferences and the need for clear borrower communication. Technological forces concern digital identity, data connectivity, automation, fraud controls and the resilience of field-enabled systems. Legal issues cover consumer protection, data handling, lending conduct and documentation requirements. Environmental considerations can include physical disruption to branch operations, travel and continuity planning, as well as changing expectations for responsible operations.
- External watchpoints. Separate documented operating conditions from policy, economic or technology scenarios that should be monitored rather than treated as established facts.
- Operational consequences. Link external developments to questions about underwriting, collections, customer communications, system controls and branch continuity.
- Scenario discipline. Use the Excel framework to sort external signals by category and use the Word analysis to explain likely exposure pathways and management questions.
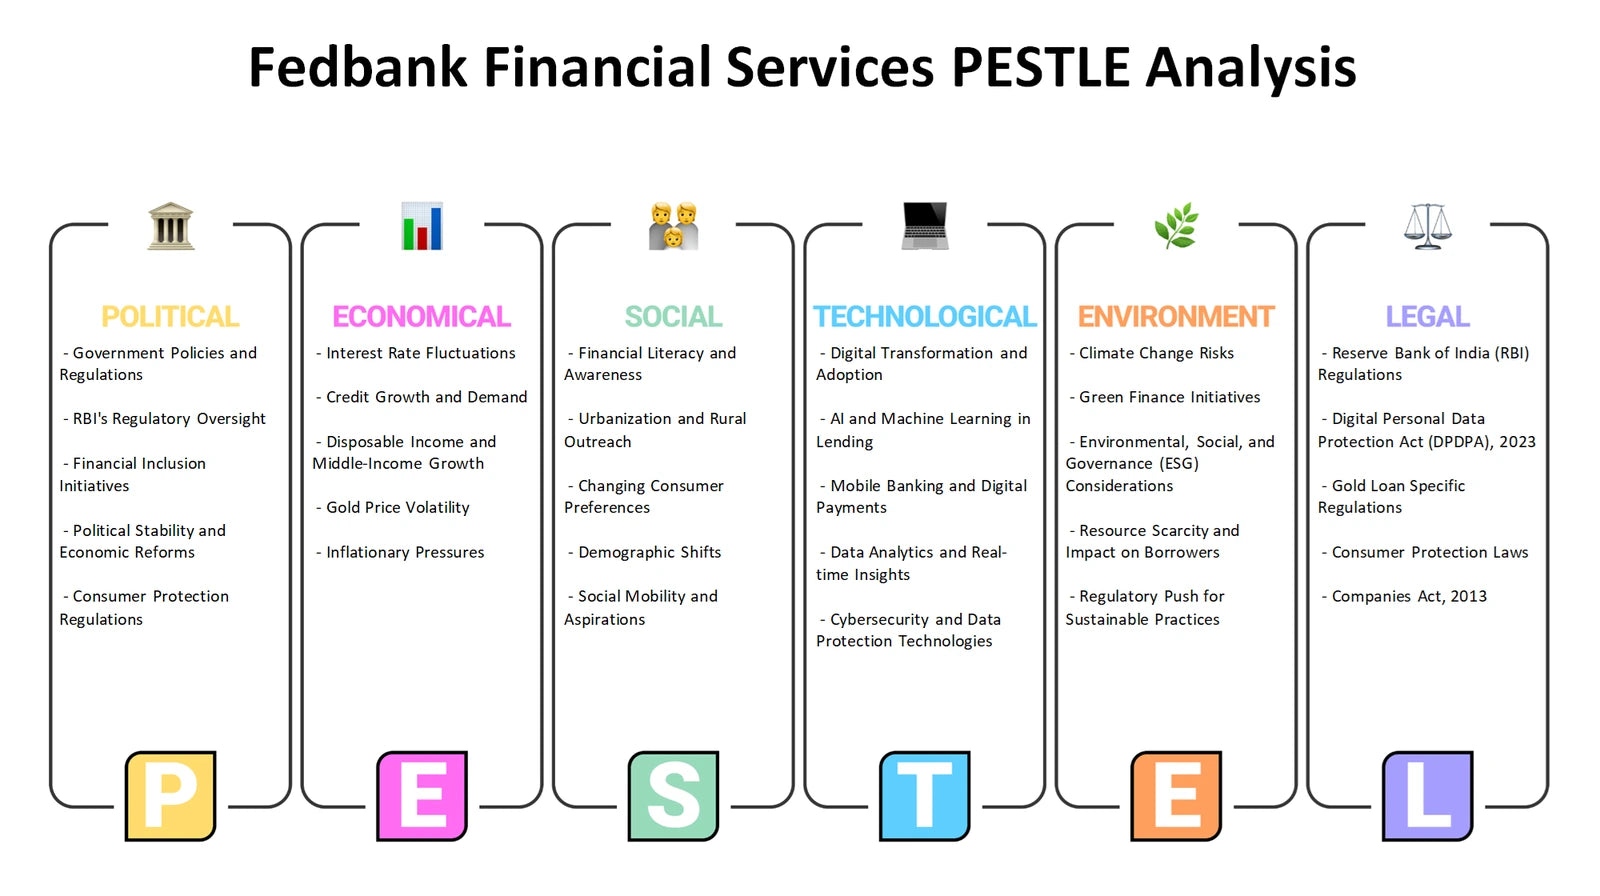
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and limitations should be weighed against external opportunities and threats in the lending environment?
A Fedbank Financial Services SWOT analysis distinguishes internal strengths and weaknesses from external opportunities and threats. The supplied business context provides relevant areas to test as potential internal strengths, including geographic branch reach, trained relationship managers, certified appraisal capability, process digitisation and real-time operational visibility. These should not automatically be treated as proven advantages; their consistency, cost and scalability still require examination. Possible weaknesses may involve the management burden of distributed operations, dependence on specialist execution or process variation across locations. Opportunities can arise from unmet borrower needs, process simplification or more accessible service routes, while threats may include borrower stress, fraud, data-security concerns, competitive pressure and adverse changes in the operating environment. The framework keeps these categories distinct so that a market condition is not mistaken for a company capability.
- Internal reality check. Assess whether branch processes, local expertise and technology integration are repeatable capabilities or areas requiring further evidence and improvement.
- External alignment. Relate opportunities and threats to customer needs, credit discipline, digital trust and the wider pressures identified through the other frameworks.
- Actionable synthesis. Use the Excel grid to prioritise evidence and relationships, then use the Word analysis to develop discussion points around capability gaps, risks and strategic options.
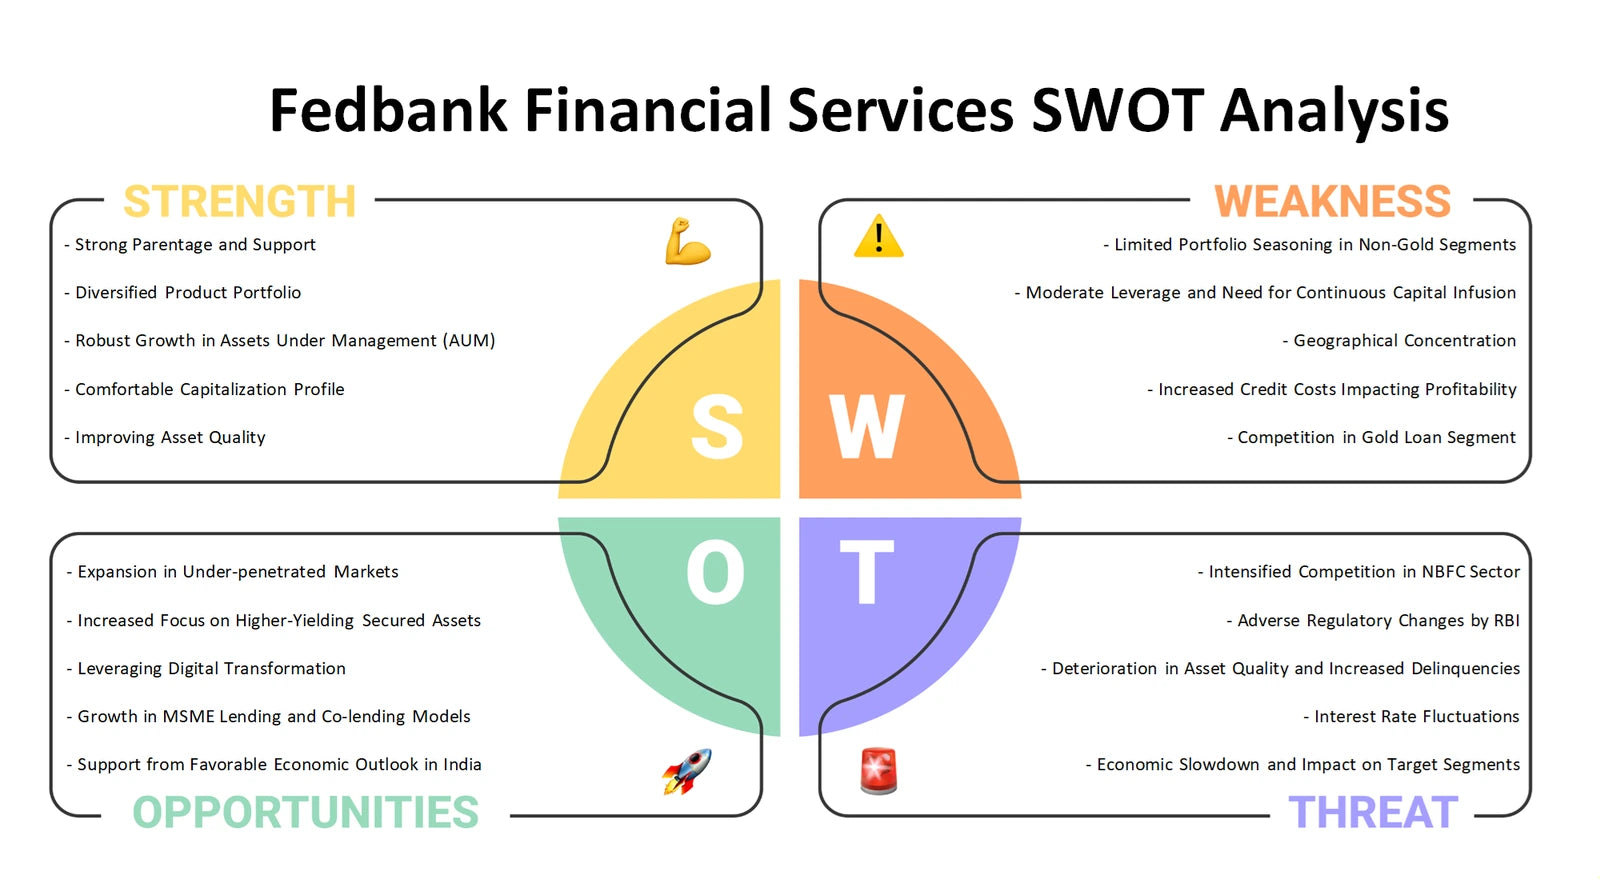
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a joined-up view of the lending model
Used together, the BCG Matrix, Business Model Canvas, Five Forces, Marketing Mix, PESTLE and SWOT perspectives move from portfolio choices to value creation, industry pressure, customer delivery, external change and organisational fit. The Excel frameworks provide a structured way to organise comparisons and working assumptions, while the detailed Word analysis supports deeper interpretation of the branch-led, technology-enabled lending context represented for Fedbank Financial Services.
Company background: Fedbank Financial Services — supplied business-model context page.