

Premier Financial: Deposit Funding and Customer Acquisition – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Premier Financial Strategy Analysis Bundle
This bundle uses the supplied business context for Premier Financial: a deposit-funded banking and lending operation in which loan growth, interest-bearing deposits and relationships with real estate professionals matter. Those relationships can provide a focused route to prospective borrowers, while deposits remain central to liquidity management and the cost of funding the loan portfolio.
The available context makes referral economics, lending-product priorities and funding discipline useful strategic questions rather than established conclusions. The six connected analyses help examine how Premier Financial can compare portfolio choices, map its value creation, understand banking pressures and test external conditions without presenting unverified financial results or company-specific scores.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending offers or customer-focused growth initiatives deserve funding attention when capital, liquidity and management capacity are limited?
A Premier Financial BCG Matrix provides a disciplined way to compare parts of a lending portfolio using market growth and relative market share. It does not assume that any loan category belongs in a particular quadrant. Instead, it helps distinguish the evidence needed to assess whether an offer could function as a Star, Cash Cow, Question Mark or Dog. For a deposit-funded lender, the classification discussion matters because growth in balances is not enough: each priority must also be considered against funding needs, credit oversight and the effort required to acquire borrowers through direct or referral channels.
- Portfolio priorities. Compare loan categories, borrower segments or acquisition initiatives by their growth environment and relative competitive position.
- Resource discipline. Test whether a possible expansion could justify marketing, underwriting and servicing capacity without treating loan growth as automatically valuable.
- Working view. Use the Excel matrix to organize comparison inputs, then use the Word analysis to document assumptions, evidence gaps and portfolio-priority questions.
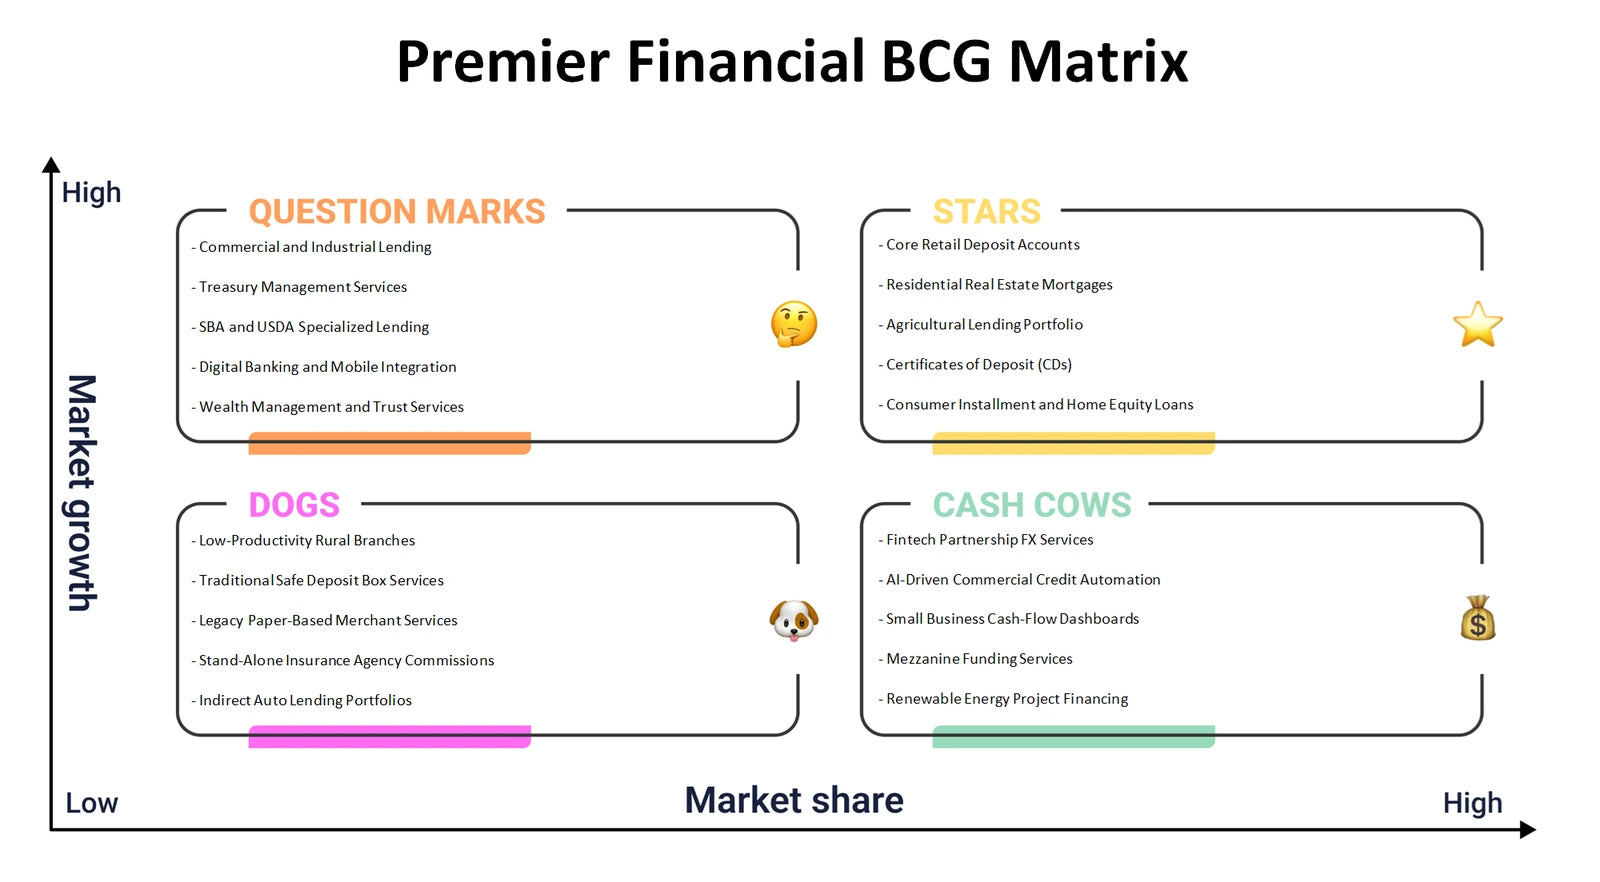
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do deposits, borrower acquisition and lending operations connect to create value and economic sustainability?
The Premier Financial Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In the supplied context, prospective borrowers and deposit customers may have different needs, while real estate professionals may be an important partnership route to lending demand. The canvas helps connect those relationships to the operational work of underwriting, funding, servicing and maintaining liquidity. It also supports a fuller look at the economics behind interest income, interest-bearing deposit costs and customer-acquisition choices, without claiming unverified revenue levels or margins.
- Connected model. Trace how borrower needs, deposit relationships, referral channels and lending delivery fit into one operating picture.
- Economic logic. Examine the links among revenue streams, funding costs, core resources, recurring activities and partnership-dependent acquisition.
- Model workshop. Populate the Excel canvas block by block and use the detailed Word analysis to guide discussion of dependencies, trade-offs and unanswered questions.
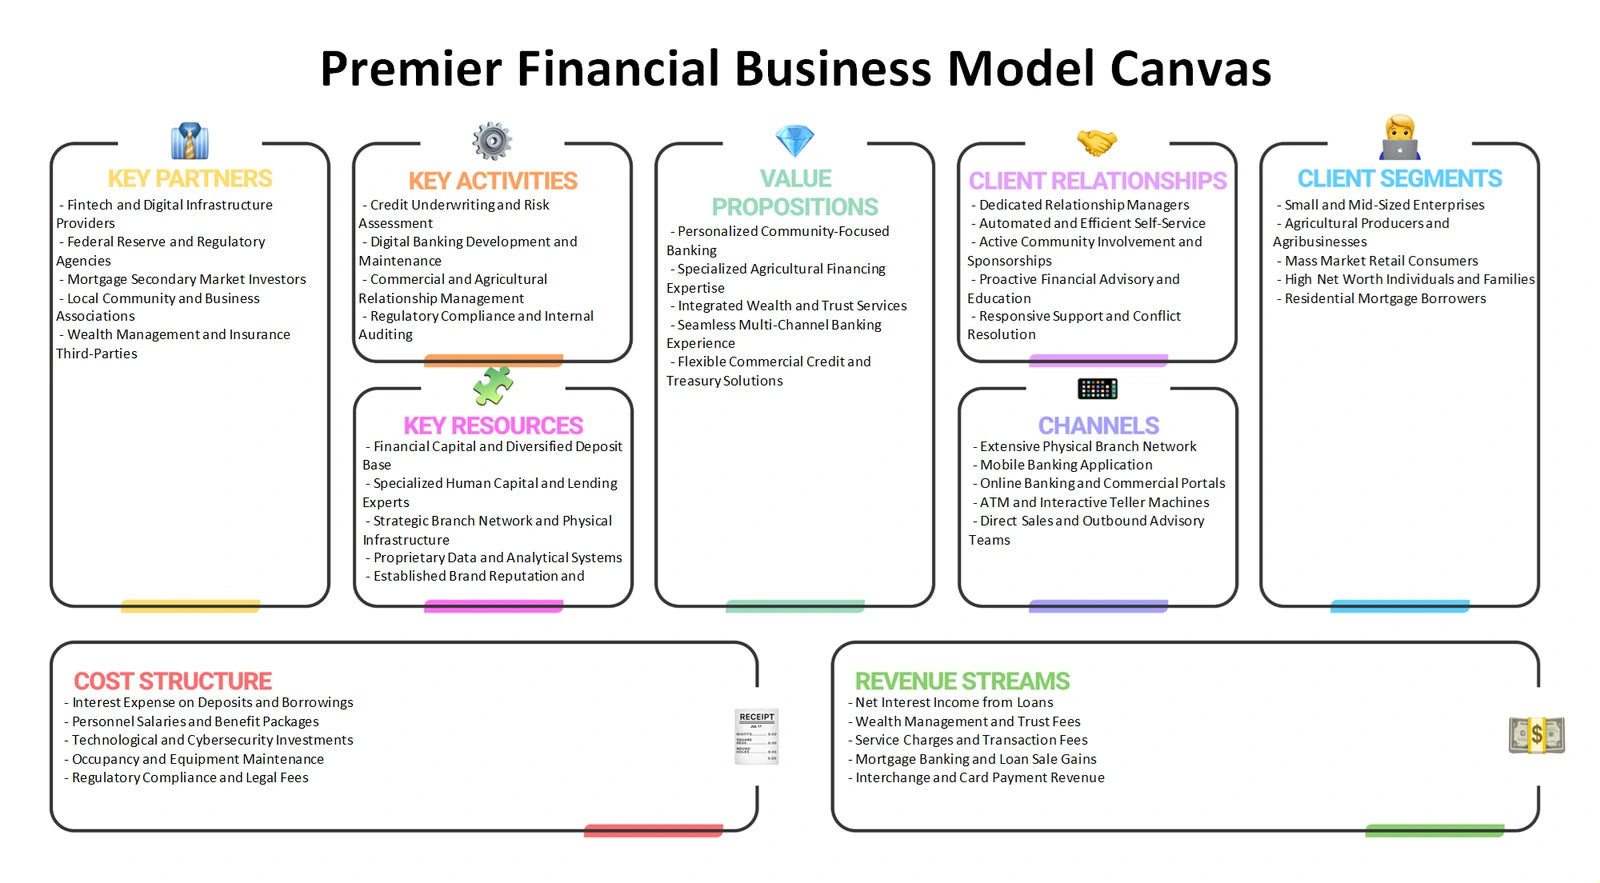
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can affect Premier Financial's ability to attract deposits, originate loans and retain customer relationships?
Premier Financial Porter's Five Forces analysis examines the competitive structure around deposit-taking and lending rather than assigning unsupported force ratings. Rivalry can shape borrower choice and deposit pricing; supplier power is relevant where funding sources, technology vendors or specialized service providers influence costs. Buyer power concerns customers' ability to compare lending terms or move deposits. The threat of new entrants includes firms able to offer financial services with lower distribution barriers, while substitutes include alternative ways for consumers or businesses to borrow, save or access financing. Together, the forces encourage attention to both market pressure and the operational response required.
- Competitive pressure. Consider how alternatives for loans and deposits may affect retention, pricing flexibility and service expectations.
- Dependence points. Identify where external funding, partners, systems or specialized suppliers could constrain cost control or service delivery.
- Structured challenge. Use the Excel framework to compare evidence for each force, with the Word analysis supporting a written discussion of implications and uncertainties.
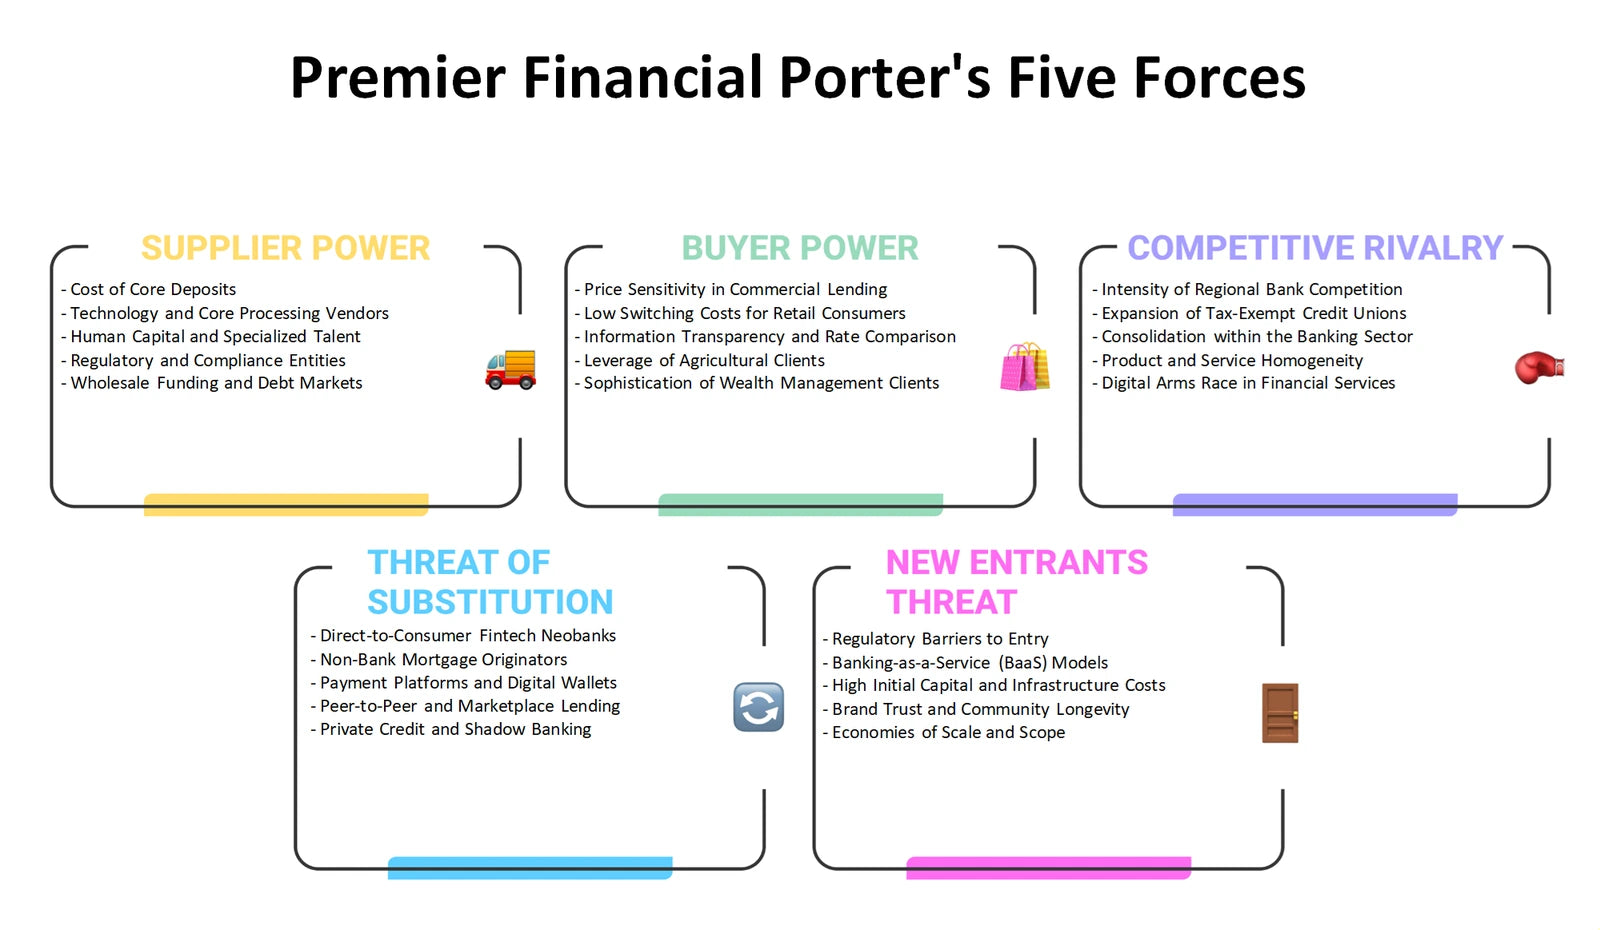
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can lending and deposit offerings be positioned clearly while respecting the trust, disclosure and relationship demands of financial services?
The Premier Financial Marketing Mix applies Product, Price, Place and Promotion to a relationship-led banking setting. Product analysis can examine how lending and deposit services address borrower and saver needs. Price is broader than a headline rate: it can include interest, fees, value received and the cost implications of attracting and retaining deposits. Place considers the routes through which customers engage, including direct contact and potential real estate-professional referrals. Promotion assesses how messages can communicate relevance and trust without assuming a particular campaign, price point or channel mix. This lens is especially useful where lower acquisition cost from partnerships must be balanced with consistency and customer suitability.
- Offer clarity. Compare the customer problem each lending or deposit proposition is intended to address and how it is differentiated.
- Channel fit. Examine where referral relationships, direct engagement and service access may support an appropriate customer journey.
- Planning aid. Use the Excel 4Ps structure to capture choices and evidence, then consult the Word analysis to develop a coherent positioning discussion.
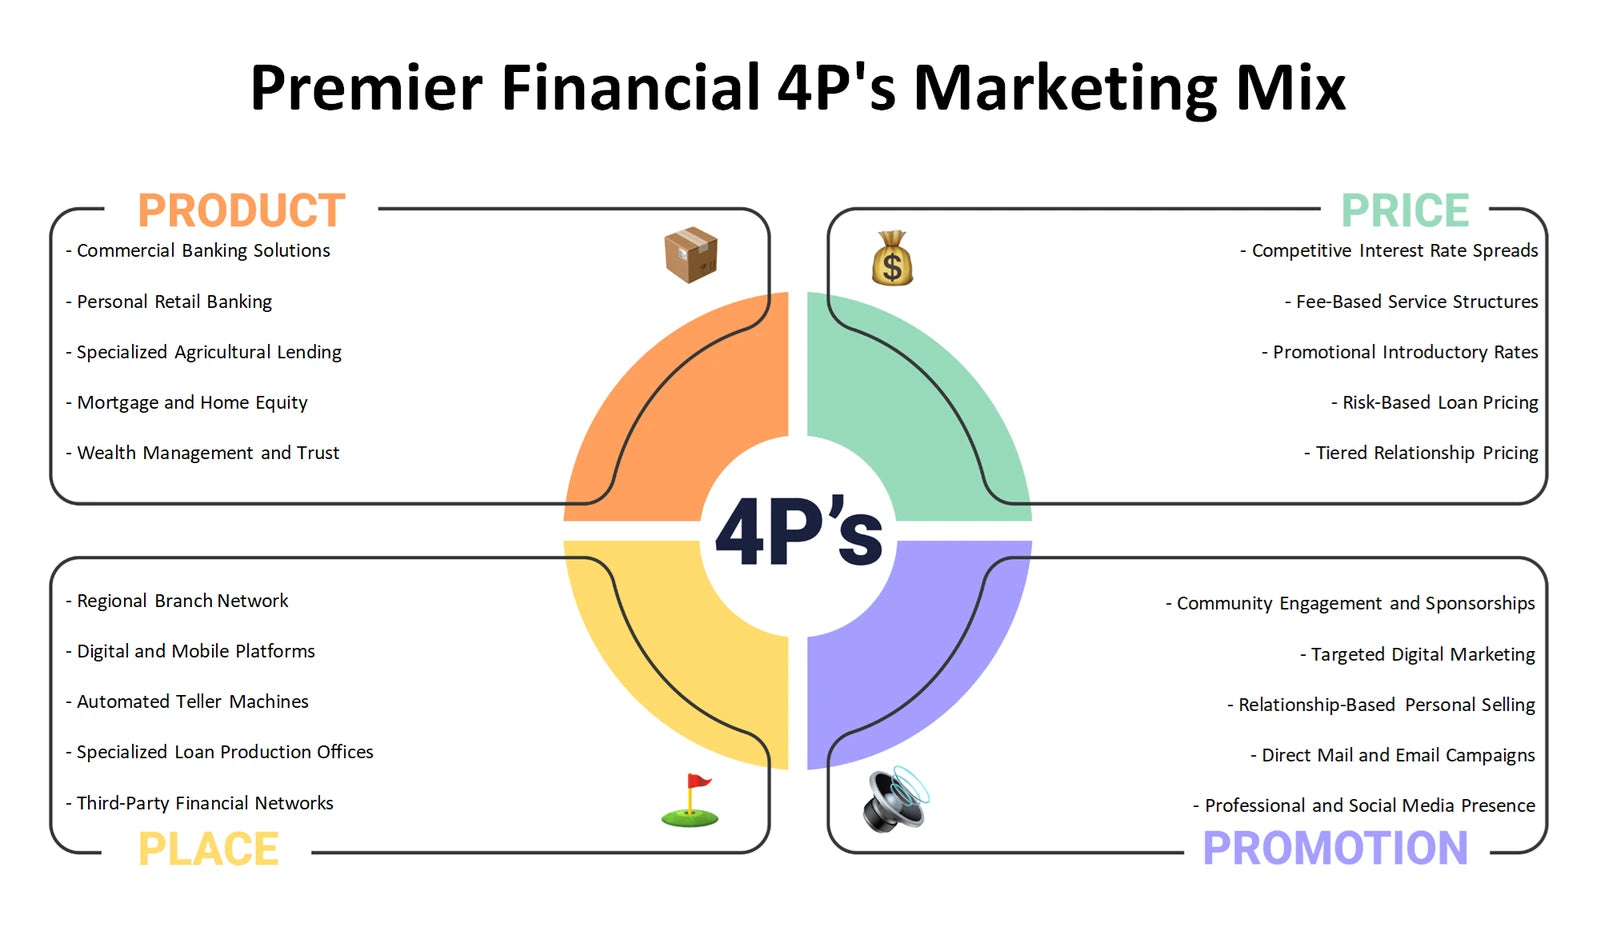
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could reshape demand, funding conditions, compliance obligations or operating costs for a deposit-funded lender?
A Premier Financial PESTLE analysis, also commonly called PESTEL, separates the external environment into Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal questions can include the policy and supervisory setting for lending, deposits, consumer treatment and data handling; they should not be confused with claims about a specific new rule. Economic conditions can affect borrowing demand, credit performance and funding costs. Social expectations may shape trust and service preferences, while technology can alter customer access, security needs and operating processes. Environmental factors can matter where physical risks or sustainability expectations affect borrowers, collateral or continuity planning.
- External scan. Organize policy, economic, customer-behaviour, technology, legal and environmental signals that warrant monitoring.
- Transmission paths. Ask how an outside change could flow through loan demand, deposit costs, risk controls, partnership activity or customer communication.
- Monitoring record. Use the Excel categories to log developments and use the Word analysis to explain why selected external factors matter to the business model.
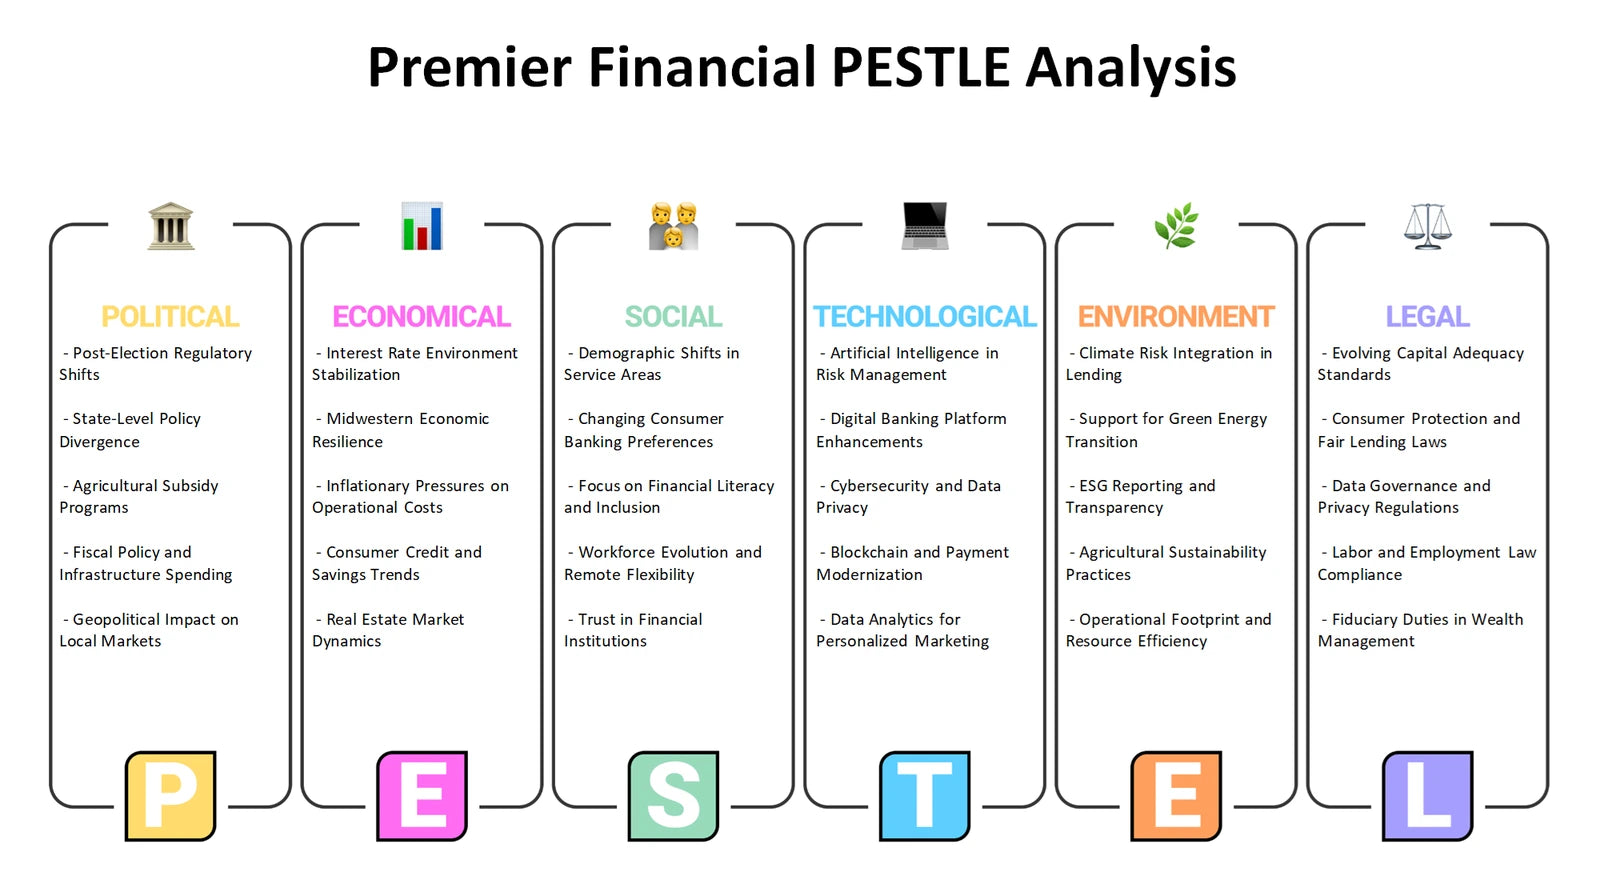
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Premier Financial distinguish internal capabilities and constraints from external opportunities and threats before setting priorities?
Premier Financial SWOT analysis provides a disciplined boundary between internal and external factors. Strengths and weaknesses concern capabilities the business can influence, such as relationship-management processes, lending expertise, funding discipline, systems or capacity constraints; the framework does not declare these as proven findings. Opportunities and threats come from the surrounding market, including changing borrower demand, referral potential, competitive alternatives, economic conditions and regulatory expectations. Used alongside the other five analyses, SWOT can turn separate observations into practical strategic questions: whether an internal capability is sufficient to pursue an opportunity, whether a weakness requires mitigation, or whether a threat changes the attractiveness of a portfolio choice.
- Correct classification. Separate controllable operational capabilities and limitations from external market openings and risks.
- Strategic fit. Test whether potential growth through borrower referrals is supported by the resources, controls and funding capacity required.
- Decision map. Use the Excel SWOT grid to prioritize observations and use the Word analysis to articulate links among internal conditions, external pressures and possible responses.
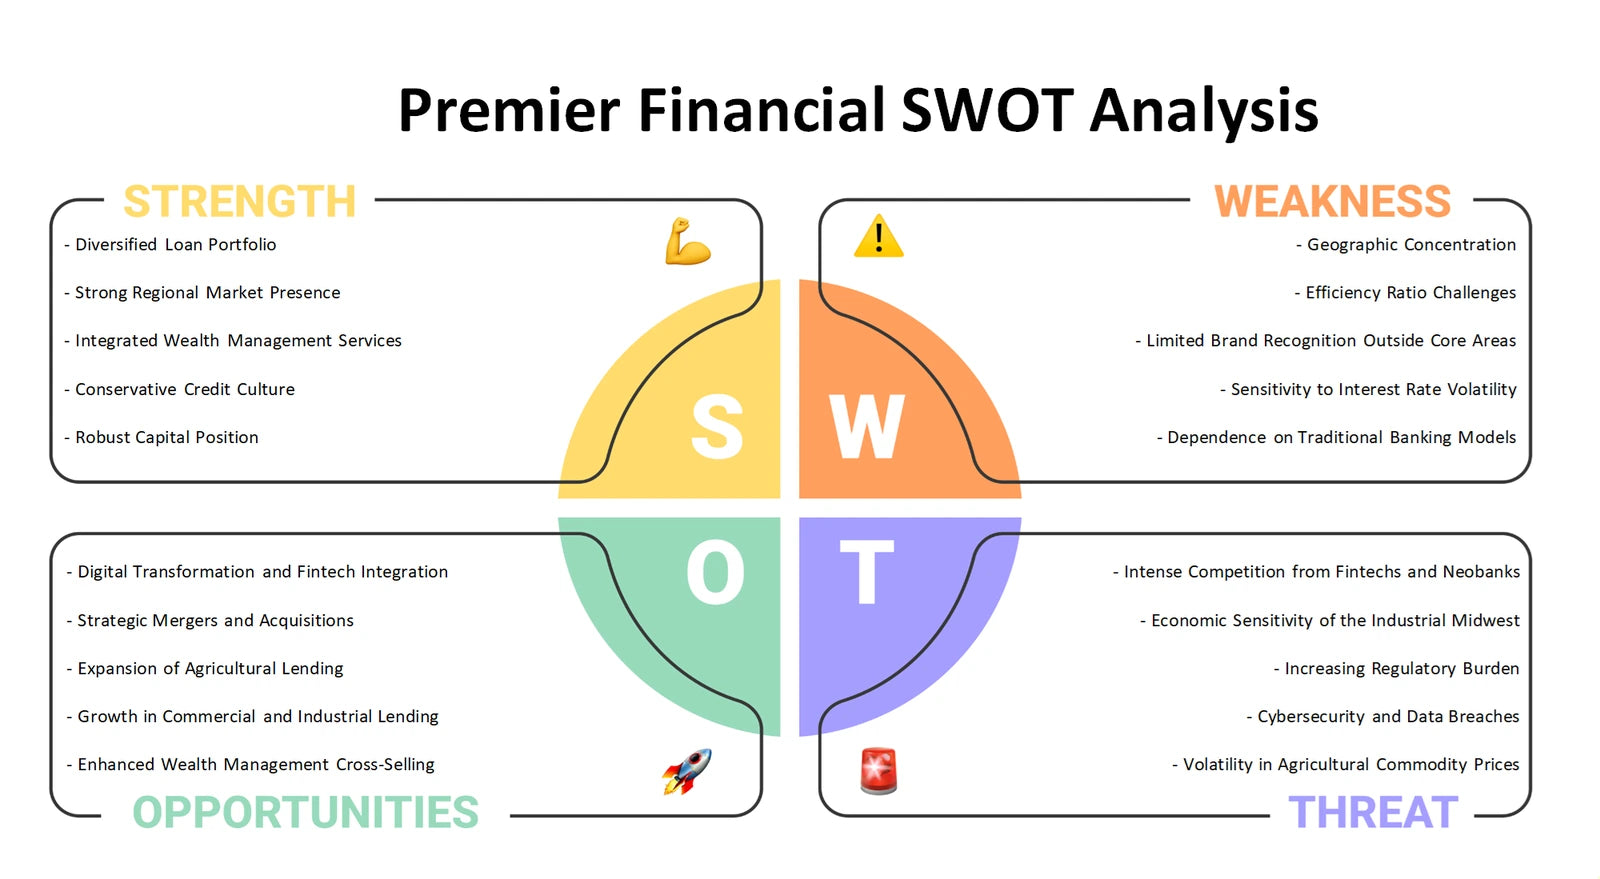
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build one connected strategic picture
Used together, the six perspectives move from portfolio priorities and value creation to industry structure, customer choices, external change and strategic fit. The Excel frameworks give Premier Financial a consistent way to organize questions and comparisons, while the detailed Word analyses help develop the reasoning behind discussions of lending growth, deposit funding, partnership channels and operational trade-offs.
Company background: Premier Financial — matching product-context page.