

Fannie Mae: Financial Services – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Fannie Mae Strategy Analysis Bundle
Fannie Mae, formally the Federal National Mortgage Association, is a U.S. housing-finance company that works through mortgage lenders and loan servicers to support liquidity and stability in the mortgage market. Its business depends on relationships with originating institutions that provide mortgage loans and servicing partners that manage borrower payments and loan administration.
For the quarter ended March 31, 2026, Fannie Mae reported GAAP net income of USD 3.72 billion in its April 29, 2026 Form 10-Q filing. That dated snapshot raises practical questions about portfolio priorities, lender economics, housing-market pressures and the external conditions that can affect mortgage activity.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
How can Fannie Mae compare mortgage-related activities when market growth and relative market share point to different resource priorities?
The Fannie Mae BCG Matrix provides a disciplined way to consider a portfolio of business activities through market growth and relative market share rather than treating every activity as equally strategic. It helps examine which areas may resemble Stars, Cash Cows, Question Marks or Dogs under the framework's criteria, without assuming that any Fannie Mae activity already belongs in a particular quadrant. For a housing-finance business, the lens is useful when weighing capital, operational attention, technology investment and partner support across changing mortgage-market conditions.
- Portfolio logic. Compare mature sources of value with activities exposed to changing loan demand, housing turnover or product adoption.
- Resource trade-offs. Consider where scale, liquidity support and operational capacity may matter most when growth conditions diverge.
- Structured comparison. Use the Excel framework to organize growth and relative-share inputs, then use the Word analysis to interpret the strategic questions behind each category.
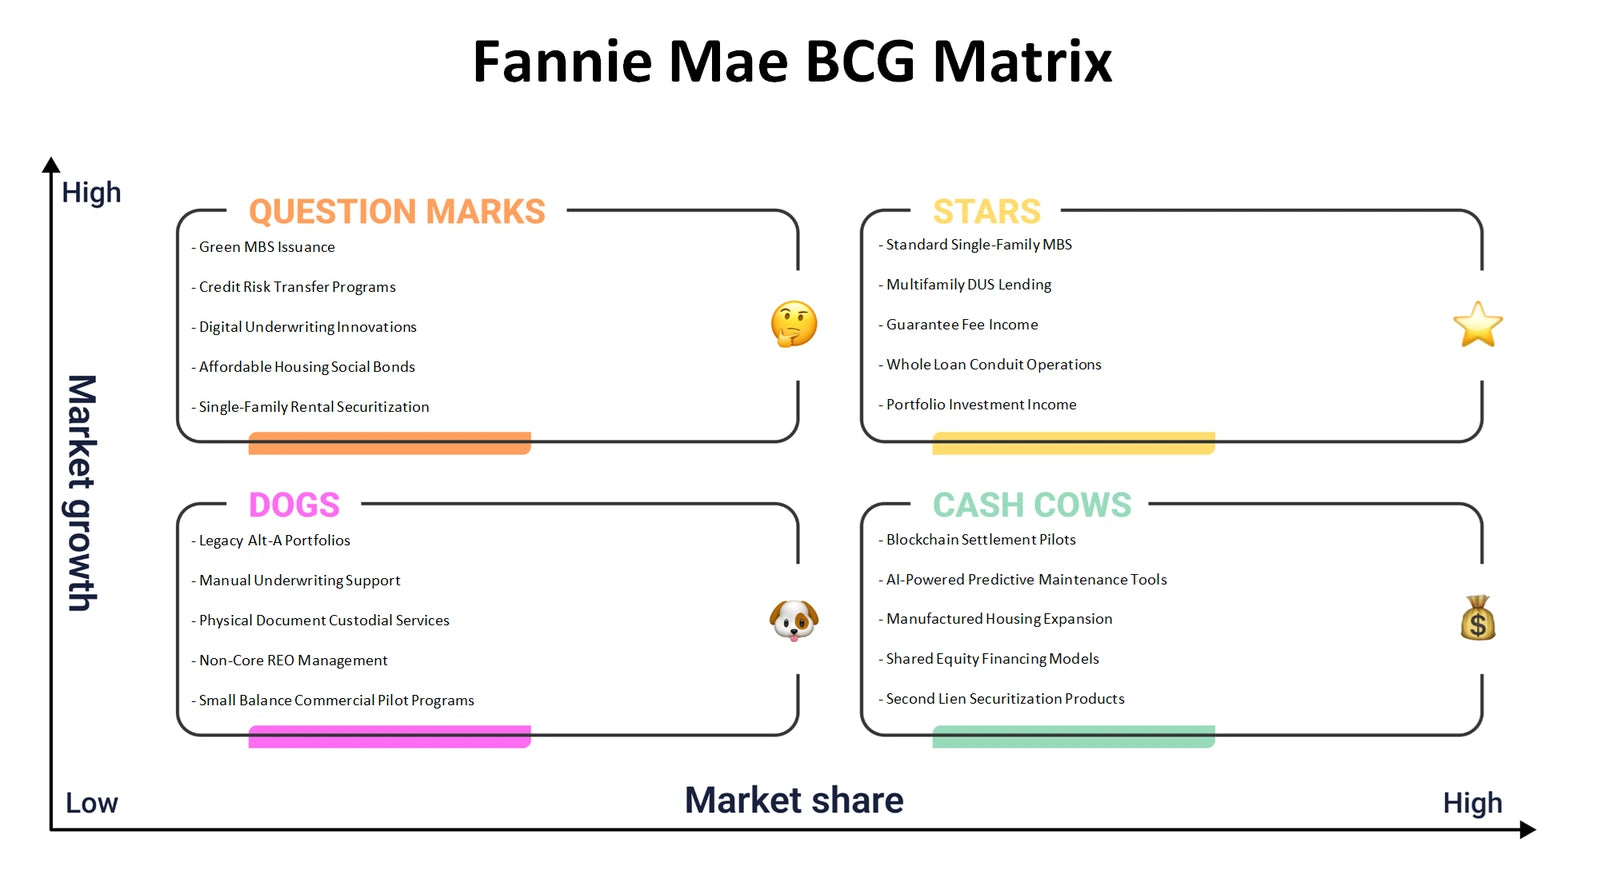
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do lender, servicer and housing-market relationships connect to the way Fannie Mae delivers value and generates economic returns?
The Fannie Mae Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It is especially relevant because mortgage originators are central channels and partnerships, while servicers support loan administration after origination. The framework helps trace how housing-finance services move through institutional relationships, what capabilities must be maintained to support that system and where costs, risks and revenue logic interact.
- Partner ecosystem. Examine how approved lenders and servicers contribute to loan flow, operational execution and market reach.
- Value delivery. Map the connection between mortgage-market liquidity, institutional customer needs, key activities and the resources required to support them.
- Model mapping. Populate the Excel canvas block by block and use the Word analysis to connect the completed map to company-specific economic and operating questions.
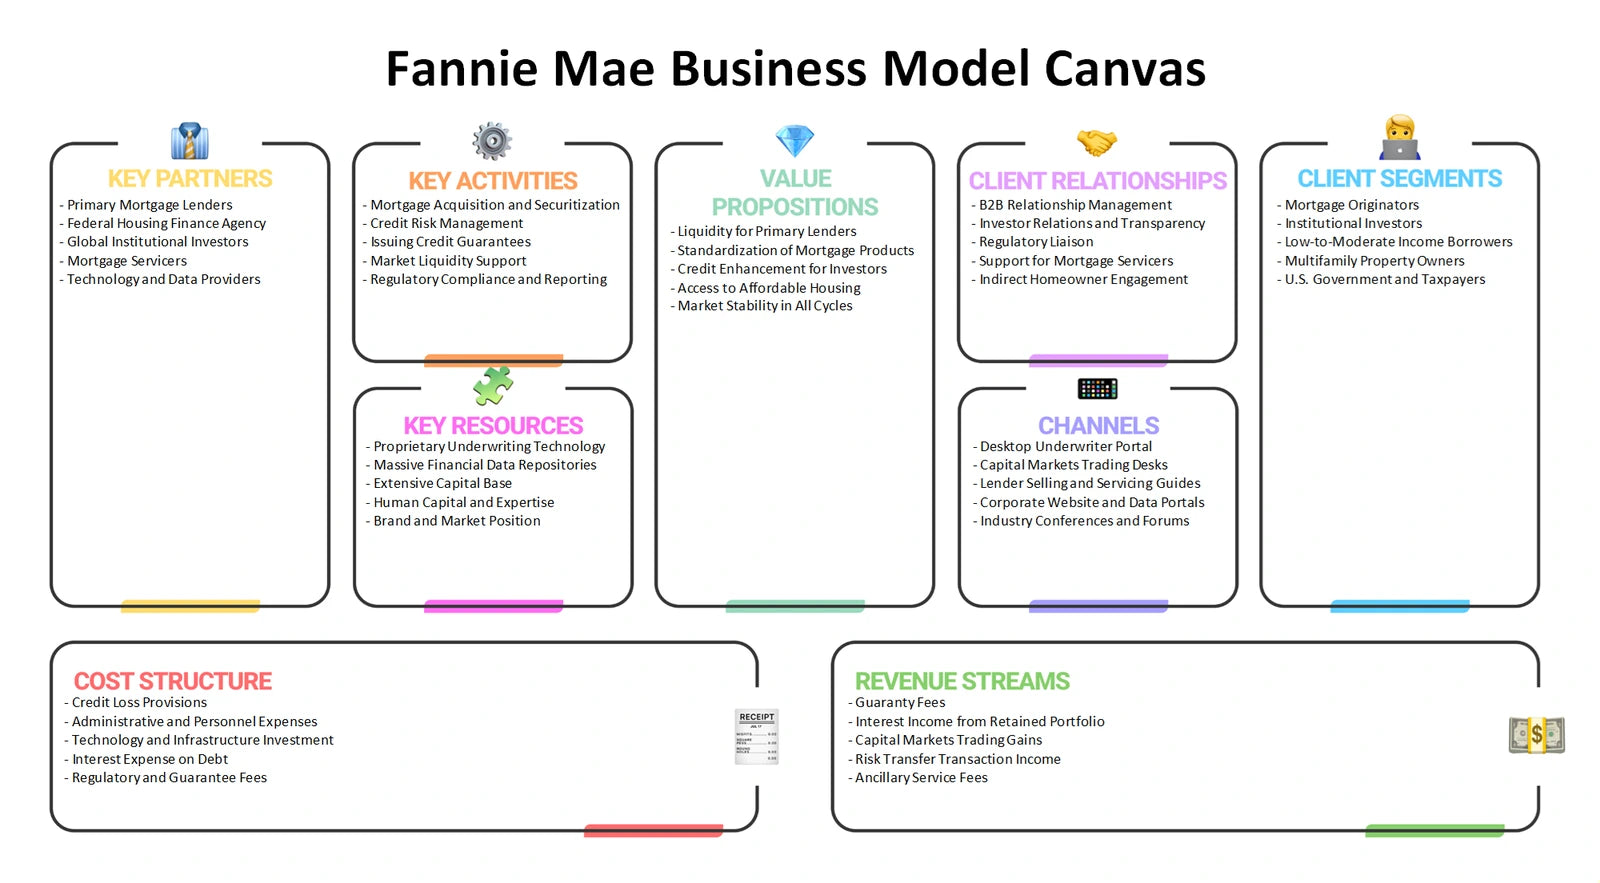
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape Fannie Mae's position in the U.S. mortgage-finance ecosystem?
Fannie Mae Porter's Five Forces examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes around housing finance. Mortgage lenders can be considered important suppliers of loan flow, while institutional counterparties and market participants may influence buyer-side expectations. The analysis also distinguishes direct alternatives from substitutes: for example, other ways borrowers, lenders or investors can meet financing and liquidity needs. This lens does not assign force scores; it structures discussion of where bargaining, switching, regulation, funding conditions and scale may affect the industry.
- Counterparty leverage. Assess how concentration, standards, service expectations and access to mortgage supply can influence relationships with lenders and servicers.
- Alternative pathways. Compare the strategic relevance of competing financing structures and substitute mechanisms for housing-market liquidity.
- Pressure testing. Use the Excel framework to record evidence and assumptions for each force, with the Word analysis providing context for interpreting their combined effect.
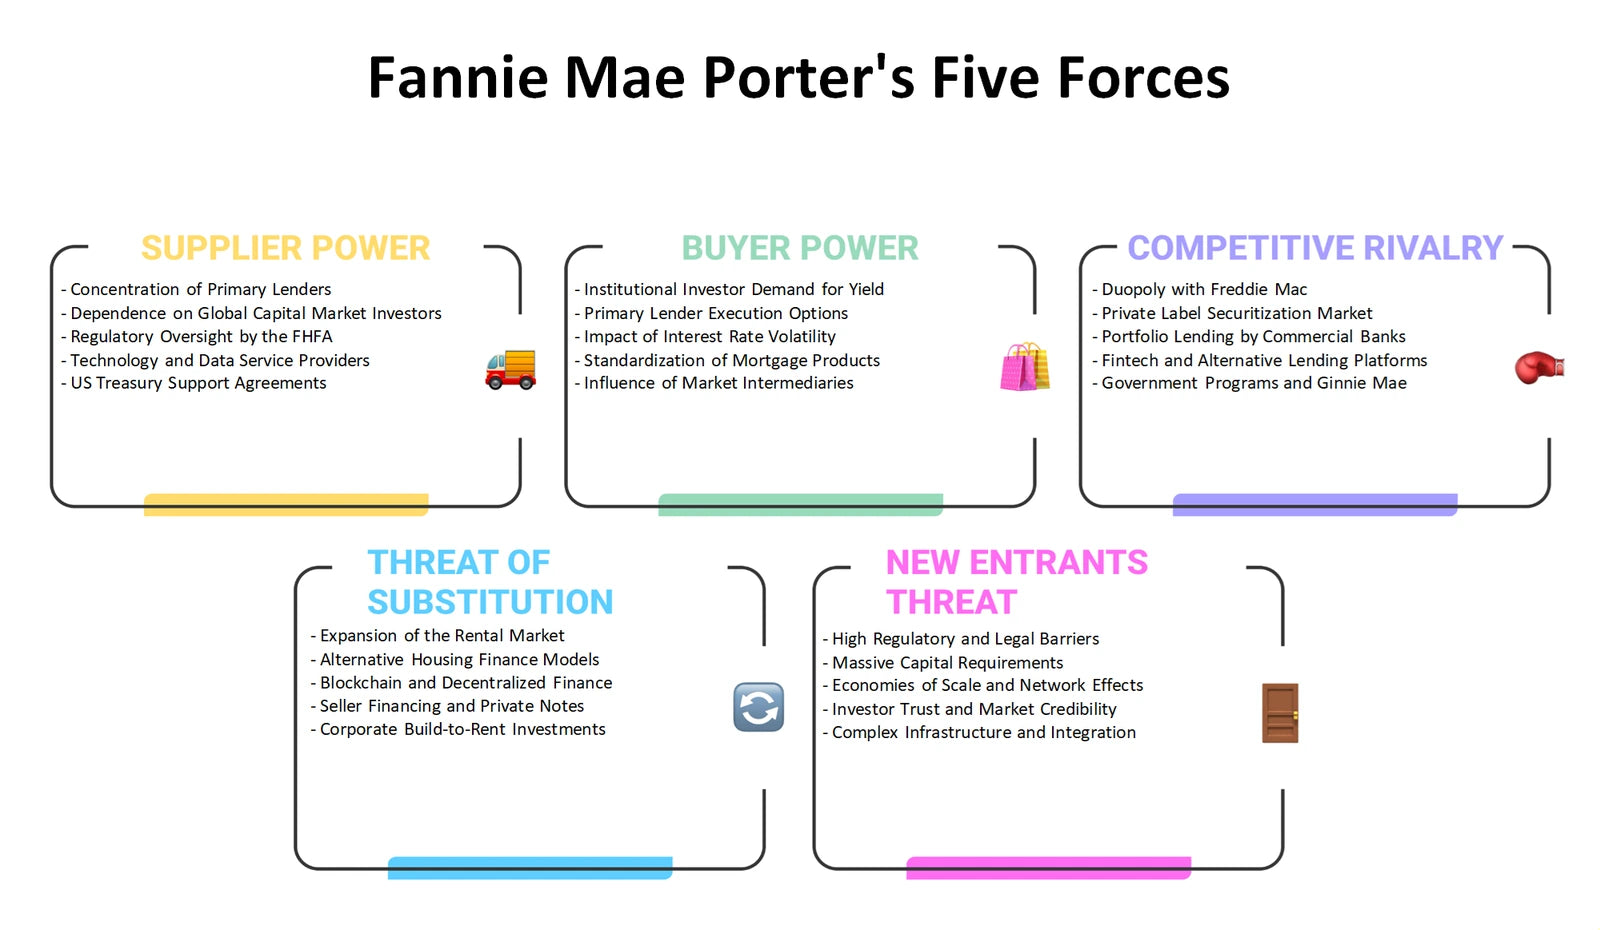
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should Fannie Mae's Product, Price, Place and Promotion be examined in a regulated, institution-led housing-finance market?
The Fannie Mae Marketing Mix considers the 4Ps in a business-to-business and partner-mediated setting rather than as a conventional consumer retail campaign. Product can include the housing-finance support and mortgage-market offerings evaluated through the bundle. Price prompts examination of pricing logic, fees, risk considerations and economic trade-offs without inventing specific prices. Place focuses on routes through lenders, servicers and market infrastructure, while Promotion considers how standards, guidance and relationship communication can support understanding among professional counterparties.
- Offering fit. Consider how mortgage-market support and related services address the needs of lenders, servicers and the wider housing-finance system.
- Route to market. Examine why intermediary networks matter more than direct consumer distribution for many company interactions.
- 4P alignment. Use the Excel framework to compare Product, Price, Place and Promotion choices, then consult the Word analysis to link those choices to institutional customer needs.
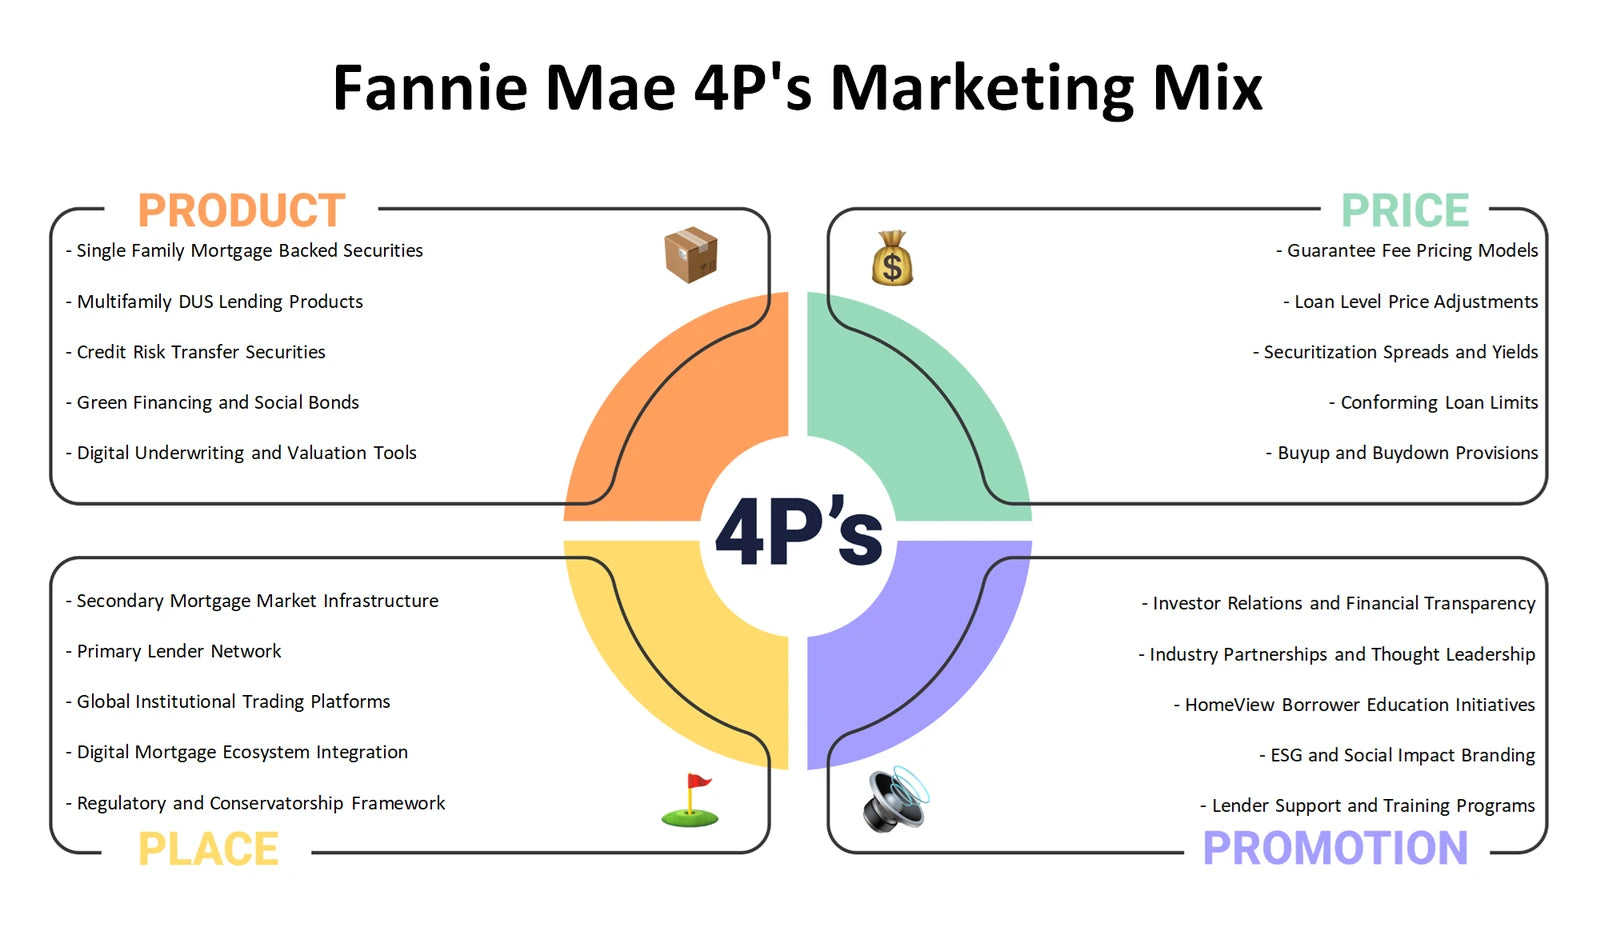
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could most materially affect Fannie Mae's role in U.S. housing finance?
The Fannie Mae PESTLE analysis, also commonly called PESTEL, organizes external influences across Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal questions can cover the policy and regulatory context surrounding housing finance. Economic conditions can influence mortgage demand, affordability and lender behavior, while social trends may affect household formation and housing preferences. Technology can reshape lending and servicing processes, and environmental factors can raise questions about property exposure and resilience. The framework distinguishes topics to monitor from claims that a particular policy, rate or law has already changed.
- Housing sensitivity. Explore how economic and social housing conditions may affect loan origination volumes and borrower demand.
- Operating environment. Compare regulatory, technological and environmental developments that may alter standards, data needs or risk-management priorities.
- External scan. Use the Excel framework to categorize developments by PESTLE factor and use the Word analysis to connect them to relevant strategic implications.
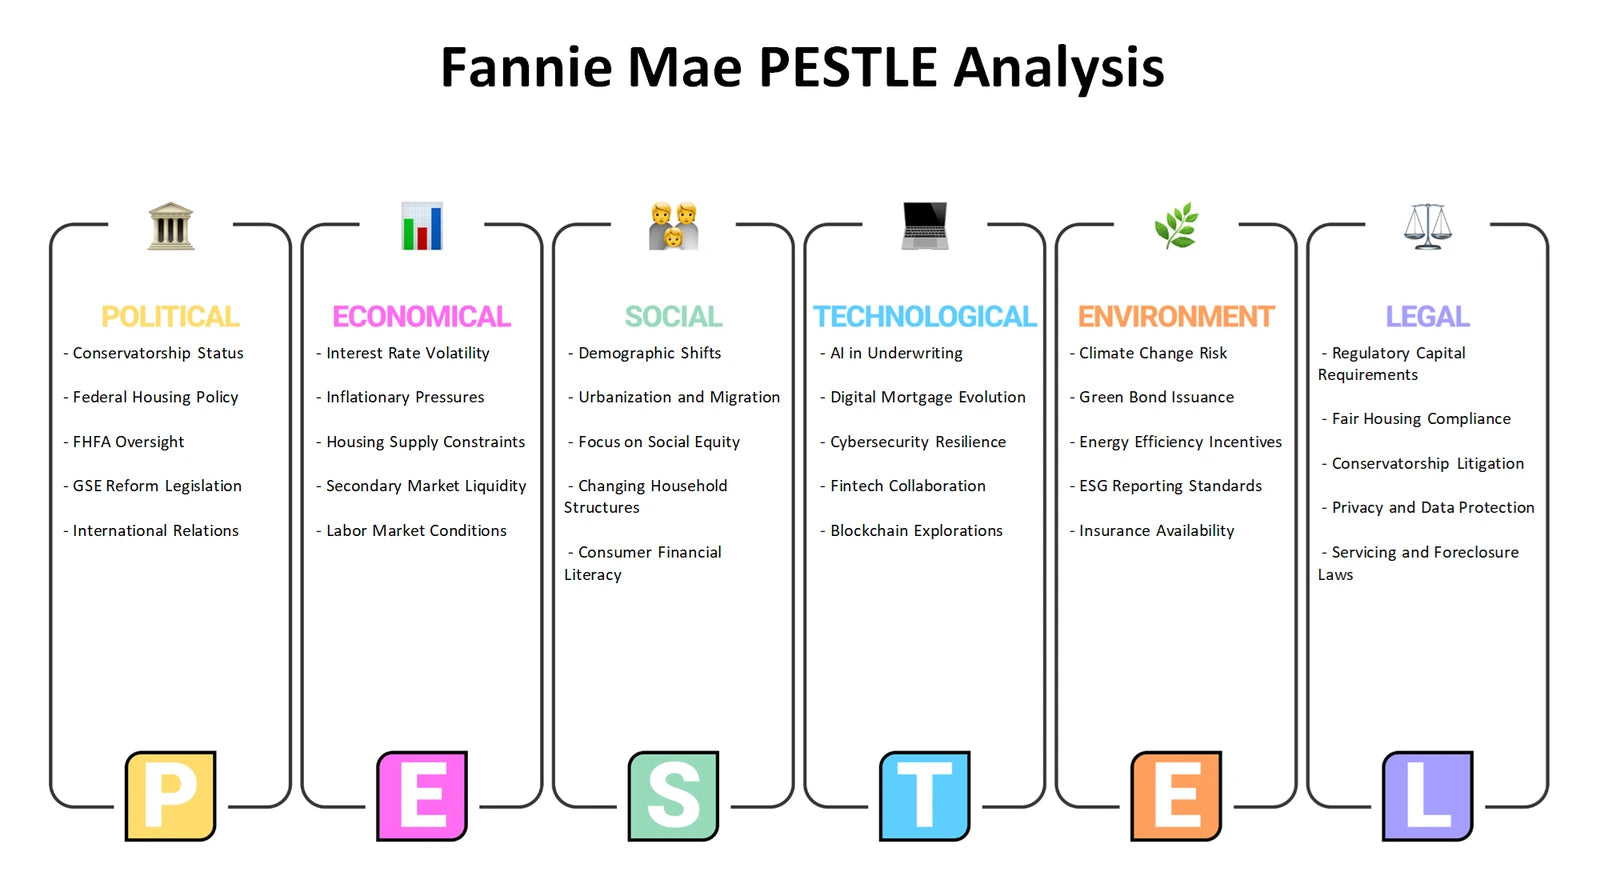
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Fannie Mae distinguish internal capabilities and constraints from opportunities and threats in the housing-finance environment?
The Fannie Mae SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. Its value lies in preventing useful but different observations from being mixed together: lender and servicer relationships, operating capabilities and organizational constraints belong on the internal side, while housing demand, policy conditions, technology shifts and market uncertainty are external conditions to assess. The framework does not present plausible themes as proven findings. Instead, it helps users test how documented business characteristics may interact with changing conditions in the U.S. mortgage market.
- Internal diagnosis. Consider the role of partner relationships, mortgage-market experience and operating dependencies as potential strengths or limitations to examine.
- External exposure. Identify opportunities and threats arising from housing demand, economic uncertainty, policy questions and evolving industry practices.
- Decision synthesis. Use the Excel framework to separate internal and external observations, then use the Word analysis to develop reasoned strategic discussion from the completed matrix.
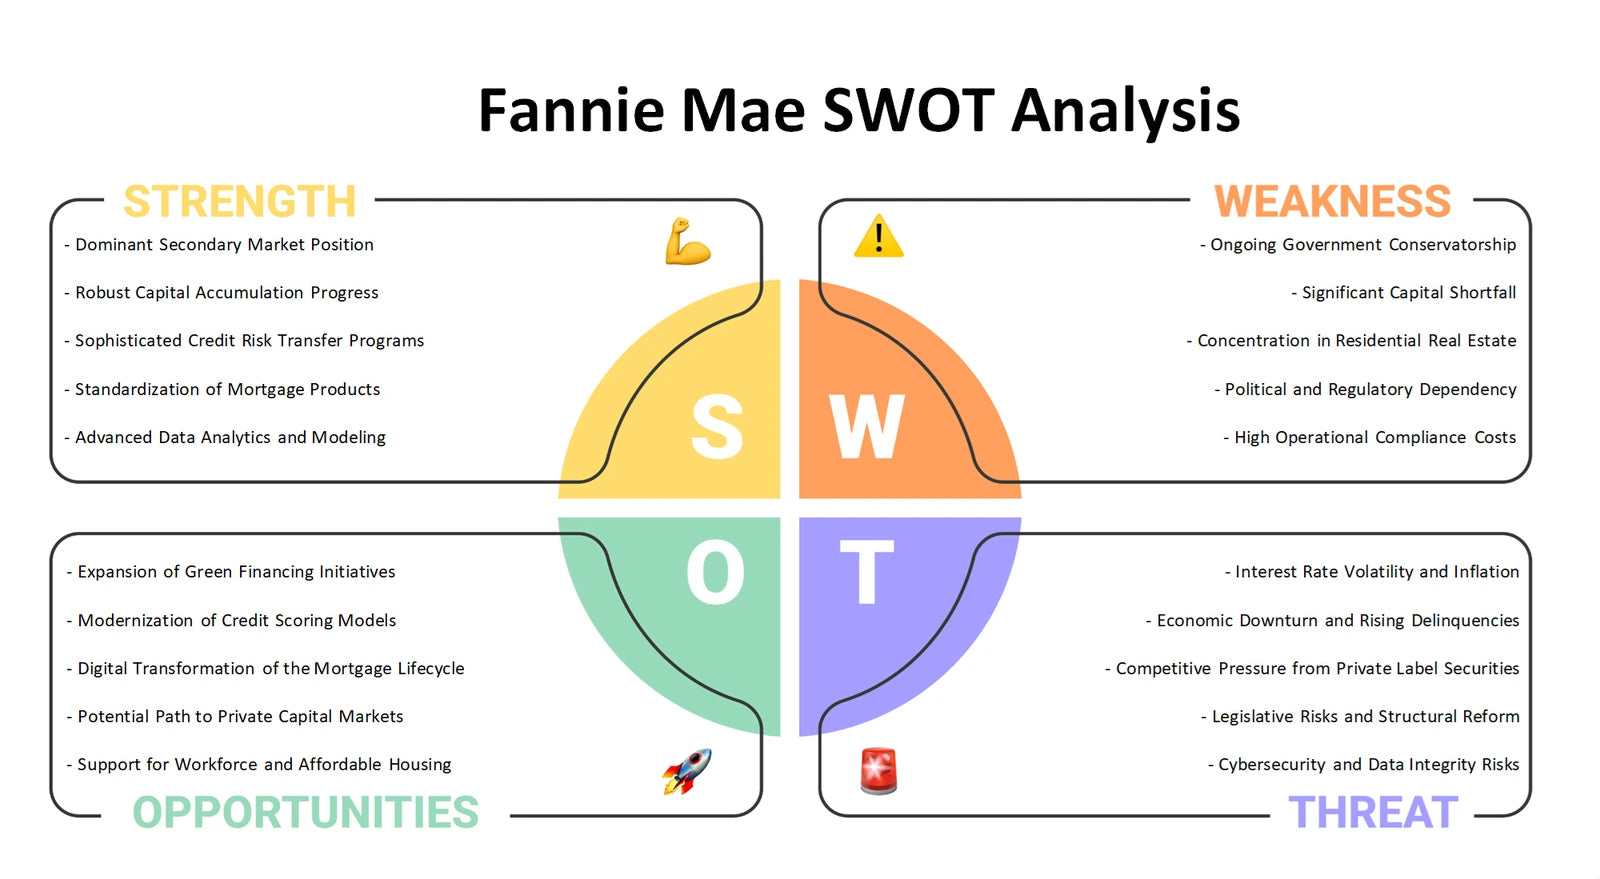
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Six lenses for a connected housing-finance view
Together, these six perspectives connect Fannie Mae's portfolio choices, institutional operating model, industry pressures, market approach, external environment and internal-versus-external strategic position. The Excel frameworks provide a structured way to organize comparisons and questions, while the Word files provide detailed company analysis to support more informed discussion of housing-finance priorities.
Company background: Fannie Mae — official company website.