

Fanhua: Six Analyses of Digital Investment and Data Capabilities

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Fanhua Strategy Analysis Bundle
The Fanhua covered in this bundle is the insurance-intermediary platform described in the supplied business context: it works with life and property & casualty insurance providers to present insurance options to clients. Rather than assume facts about other businesses using the same name, the analysis focuses on this documented platform role, connecting carriers, customers and sales agents while considering the role of technology and AI-enabled support.
This setting makes portfolio choices, carrier relationships and agent enablement more important than generic retail questions. The six perspectives help examine how insurance offerings compare, how an independent marketplace can create value, and where customer trust, external rules and digital capabilities alter the trade-offs. They provide structured questions for analysis rather than unverified market-share claims, performance conclusions or investment recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance product, carrier-support or distribution initiatives deserve different levels of attention and resources?
A Fanhua BCG Matrix helps separate analytical portfolio priorities from assumptions about individual offerings. It compares market growth with relative market share, then uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to structure discussion. For an insurance intermediary, the relevant units may be product families, customer propositions, technology-supported sales initiatives or carrier-related distribution activity. The framework does not assign any Fanhua activity to a quadrant without evidence; it helps test whether growth potential, competitive position and operational effort point in the same direction.
- Two-part comparison. Review relative market share alongside market growth so a large current activity is not automatically treated as the strongest future priority.
- Portfolio logic. Contrast the funding, maintenance, experimentation or exit questions associated with Stars, Cash Cows, Question Marks and Dogs.
- Working view. Use the Excel matrix to place possible activities and the Word analysis to record assumptions, evidence gaps and implications for carrier and agent capacity.
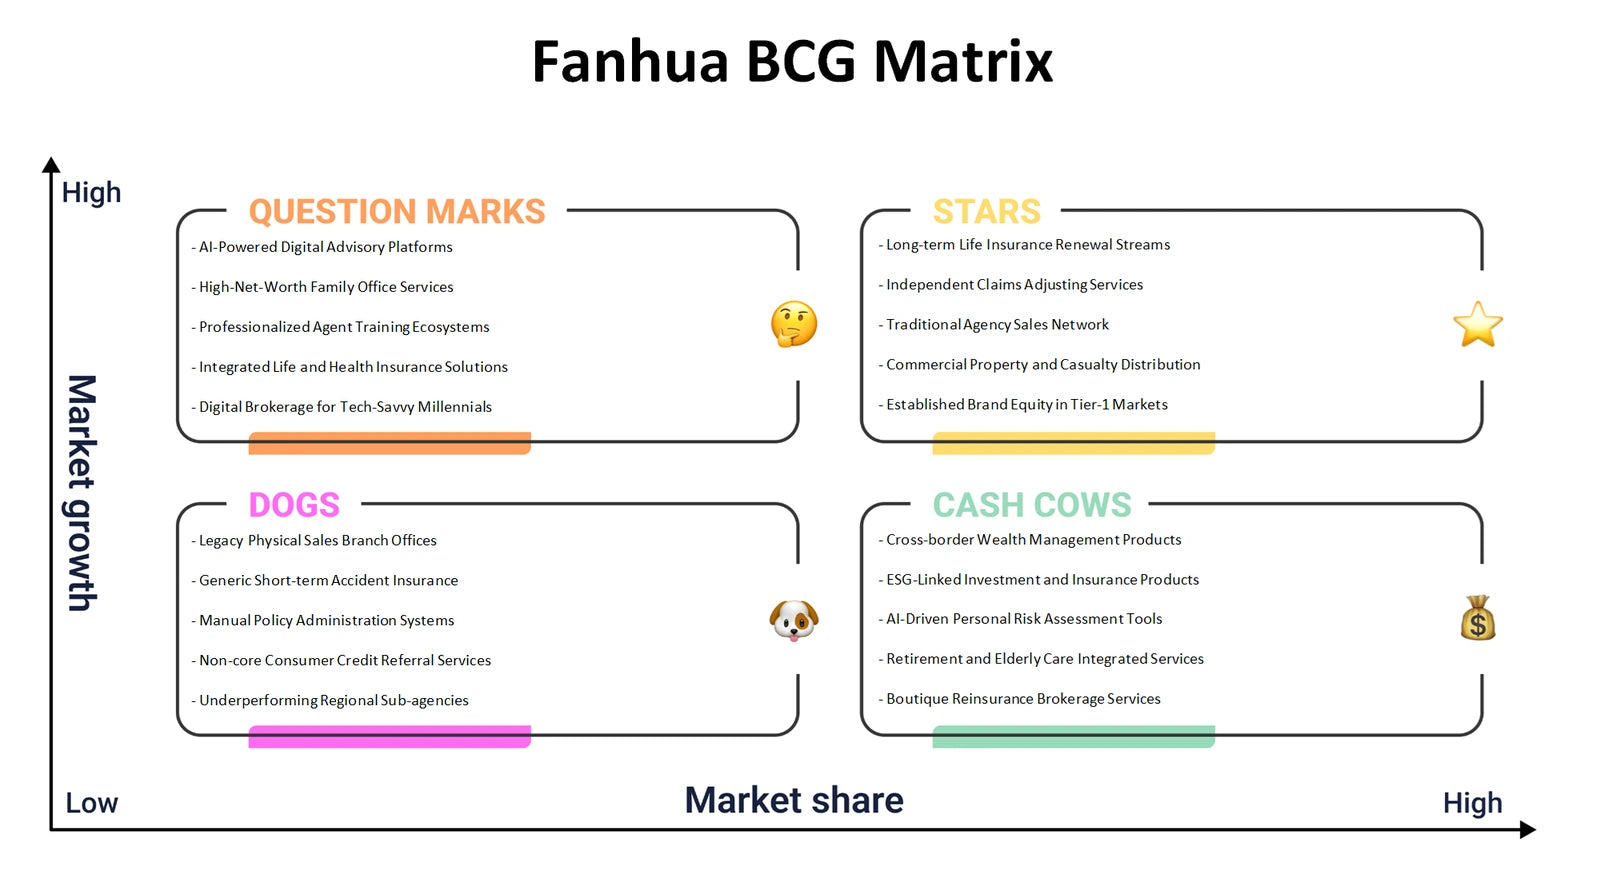
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do carrier access, client choice and agent support connect to a viable operating model?
The Fanhua Business Model Canvas examines the links between customer segments, value propositions, channels, customer relationships and revenue streams. It then connects those customer-facing choices to key resources, key activities, key partnerships and cost structure. Fanhua’s stated relationships with life and property & casualty insurers make partnerships especially important: access to a broad product range can support choice, while dependence on partner terms can affect the economics and resilience of the model. Agent-facing AI support can also be considered as a resource and activity question rather than treated as a proven financial result.
- Value exchange. Trace how a neutral insurance-selection role may create value for clients seeking options and for carriers seeking distribution access.
- Operating connections. Test how technology, sales-agent support, insurer relationships, service processes and cost commitments reinforce or constrain one another.
- Model workshop. Fill the Excel blocks in sequence, then use the Word analysis to explain the trade-offs between customer experience, partnership dependence and revenue logic.
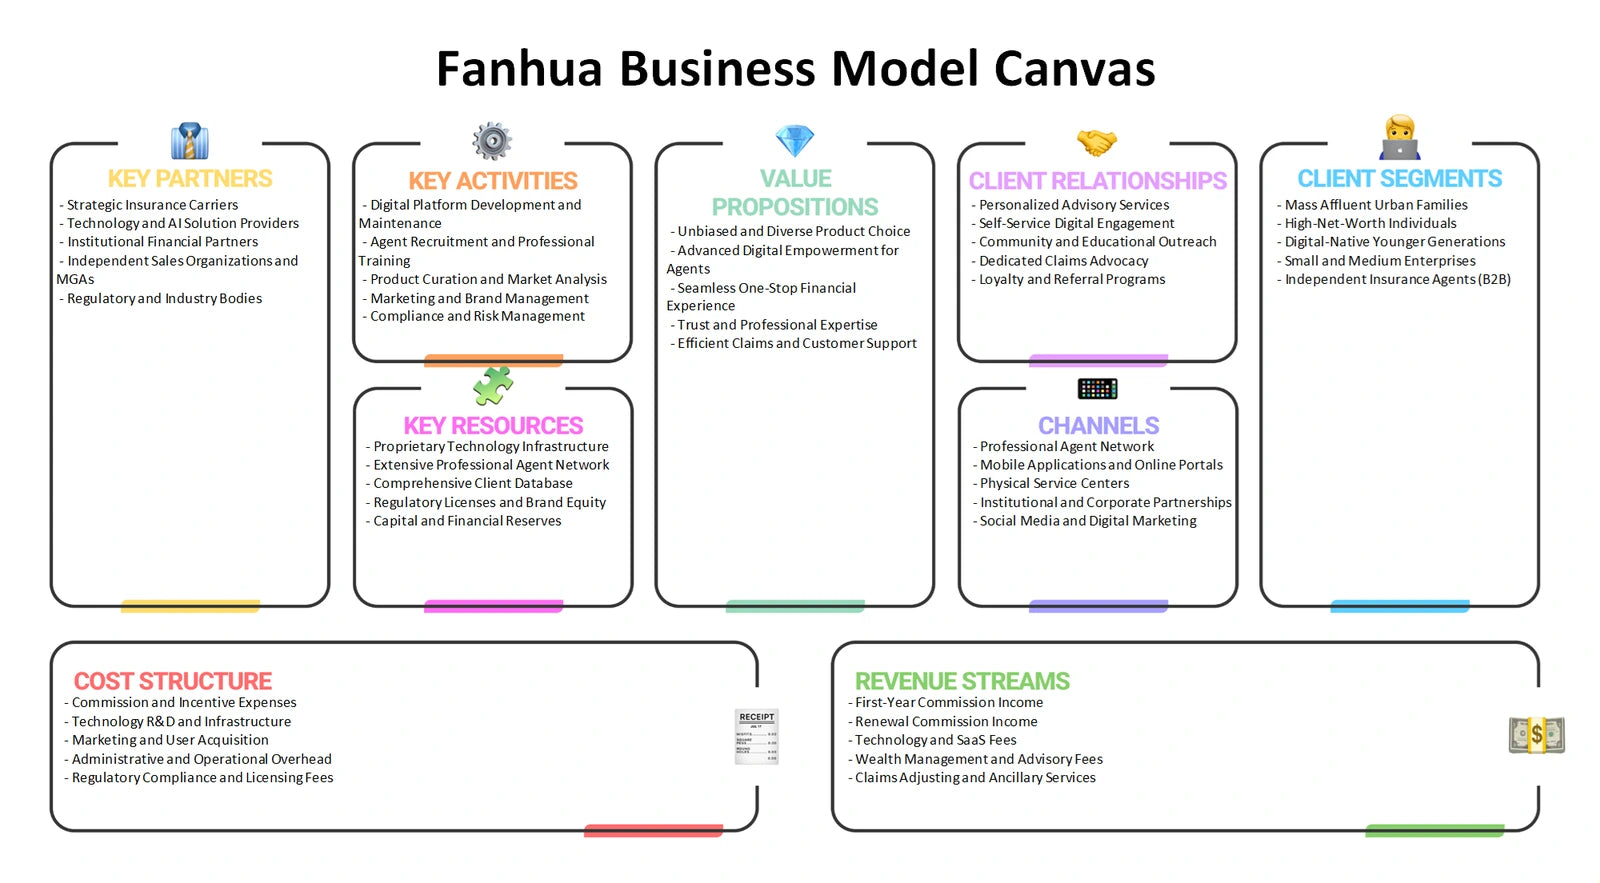
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape an intermediary’s ability to retain carrier access, customer trust and distribution relevance?
Fanhua Porter's Five Forces frames the insurance-intermediation environment through rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes. Rivalry can arise among alternative insurance distribution routes. Supplier power matters because insurers control product availability and partnership terms. Buyer power may increase when customers can compare policies more easily, while substitutes include direct insurer channels, digital self-service and other ways to obtain insurance advice. New entrants may need technology, compliance capability and trusted distribution, but those barriers should be assessed rather than presumed.
- Carrier leverage. Examine whether breadth of insurer relationships reduces concentration risk or whether partner terms still create dependency.
- Customer alternatives. Compare the value of guided product selection and agent support with direct purchasing and other advisory routes.
- Pressure map. Use Excel to rate evidence and questions for each force, then consult the Word analysis to relate the pressures to Fanhua’s platform model.
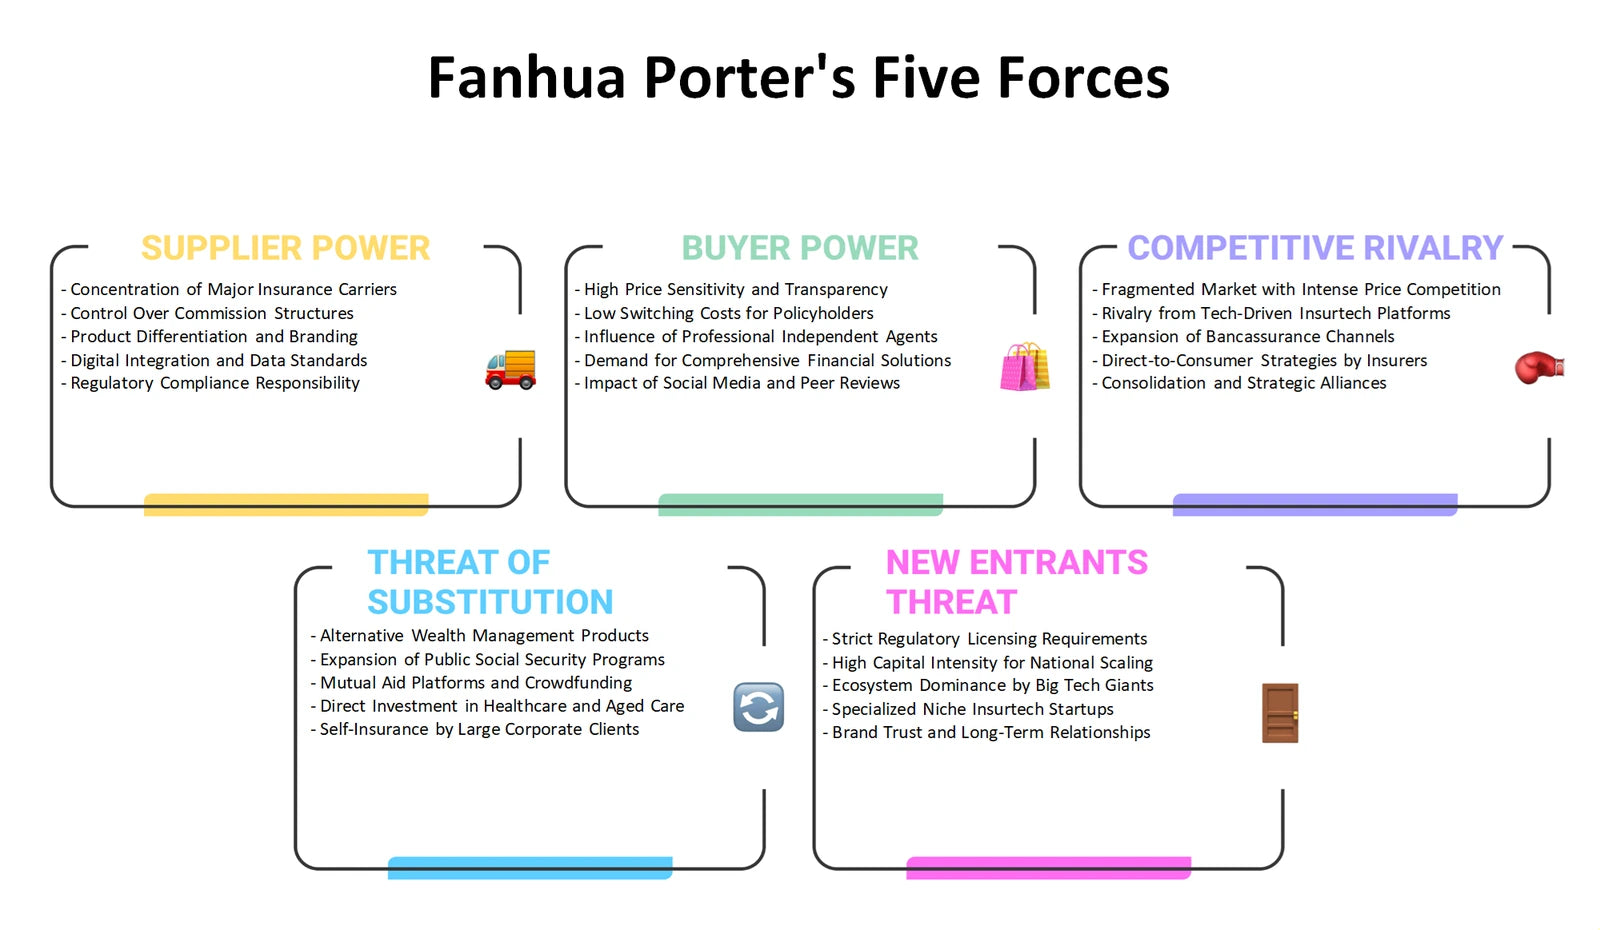
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can insurance choice and agent-enabled service be assessed through Product, Price, Place and Promotion?
The Fanhua Marketing Mix applies the 4Ps to an insurance-intermediary setting, where the offering is not simply a physical product. Product can cover the selection of life and property & casualty insurance options, the comparison experience and supporting service. Price raises questions about affordability, value communication and transparent customer understanding rather than inventing premium levels. Place considers routes through agents and technology-enabled interaction. Promotion examines how trust, clarity and suitability can be communicated in a sector where customers may find policies difficult to compare.
- Product design. Assess whether the range of insurer-backed options is understandable enough to support confident customer decisions.
- Route and message. Compare the role of sales agents, digital support and compliant communication in reaching and reassuring prospective policyholders.
- Campaign planning. Organise the four Ps in Excel, then use the Word analysis to connect each choice to insurance complexity, customer trust and carrier relationships.
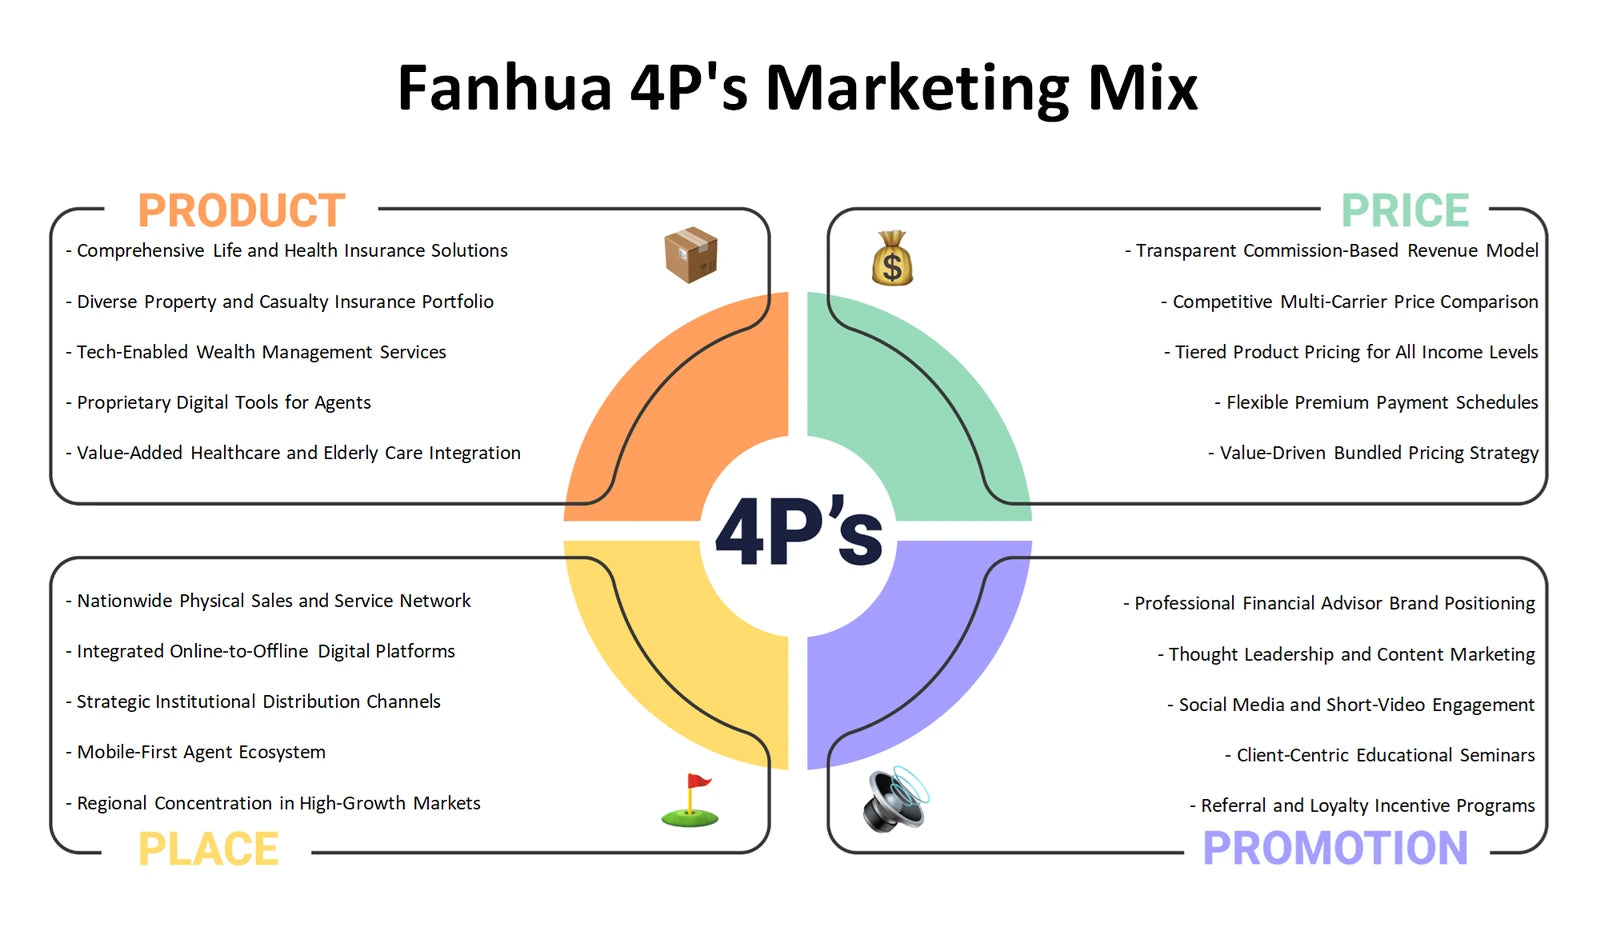
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter the attractiveness or operating requirements of insurance intermediation?
A Fanhua PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental categories. Political and legal questions can include insurance supervision, consumer-protection expectations, suitability and data-handling requirements. Economic conditions may affect household insurance budgets and carrier priorities. Social factors include trust, financial awareness and changing protection needs. Technology covers AI, cloud partnerships and digital service expectations. Environmental conditions can matter where physical risks influence property & casualty insurance demand and underwriting conditions. These are analytical areas, not claims that a particular law, rate or policy change has occurred.
- Regulatory watch. Distinguish documented requirements from policy questions that need local, current verification before a decision is made.
- Digital change. Consider how AI-enabled agent assistance and technology partnerships may create both service opportunities and governance responsibilities.
- External scan. Use the Excel framework to log signals by category and the Word analysis to connect relevant developments to customer choice, carrier collaboration and operations.
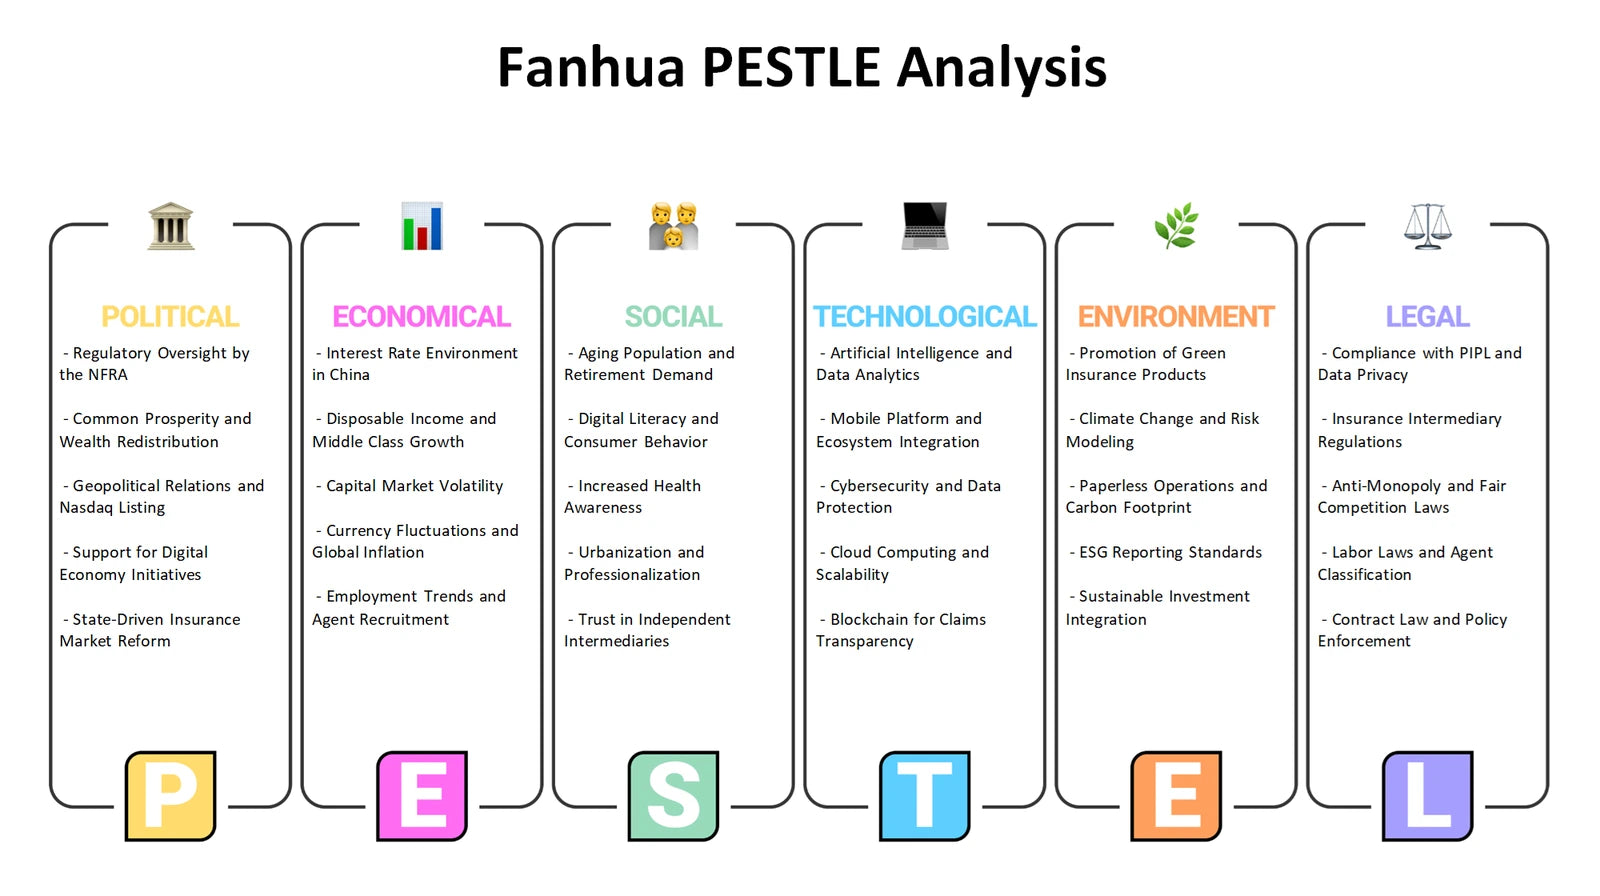
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal capabilities be separated from external conditions when evaluating Fanhua’s strategic position?
A Fanhua SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. The documented breadth of insurer relationships and use of technology support are relevant capabilities to examine, but they should not automatically be treated as proven strengths in every market or customer segment. Potential weaknesses may include the operational challenge of maintaining consistent service across partners and agents. Opportunities can arise from changing customer needs or better digital support, while threats may come from regulation, carrier bargaining power, alternative channels or reduced trust. The value of SWOT is the classification discipline: a market change is not an internal strength, and a capability is not an external opportunity.
- Internal reality. Test capabilities such as partnership management, customer guidance and agent support against evidence rather than broad reputation claims.
- External context. Link opportunities and threats to the market pressures and external conditions identified through Five Forces and PESTLE.
- Priority synthesis. Use the Excel grid to sort observations into the correct quadrant, then use the Word analysis to develop focused questions and response options.
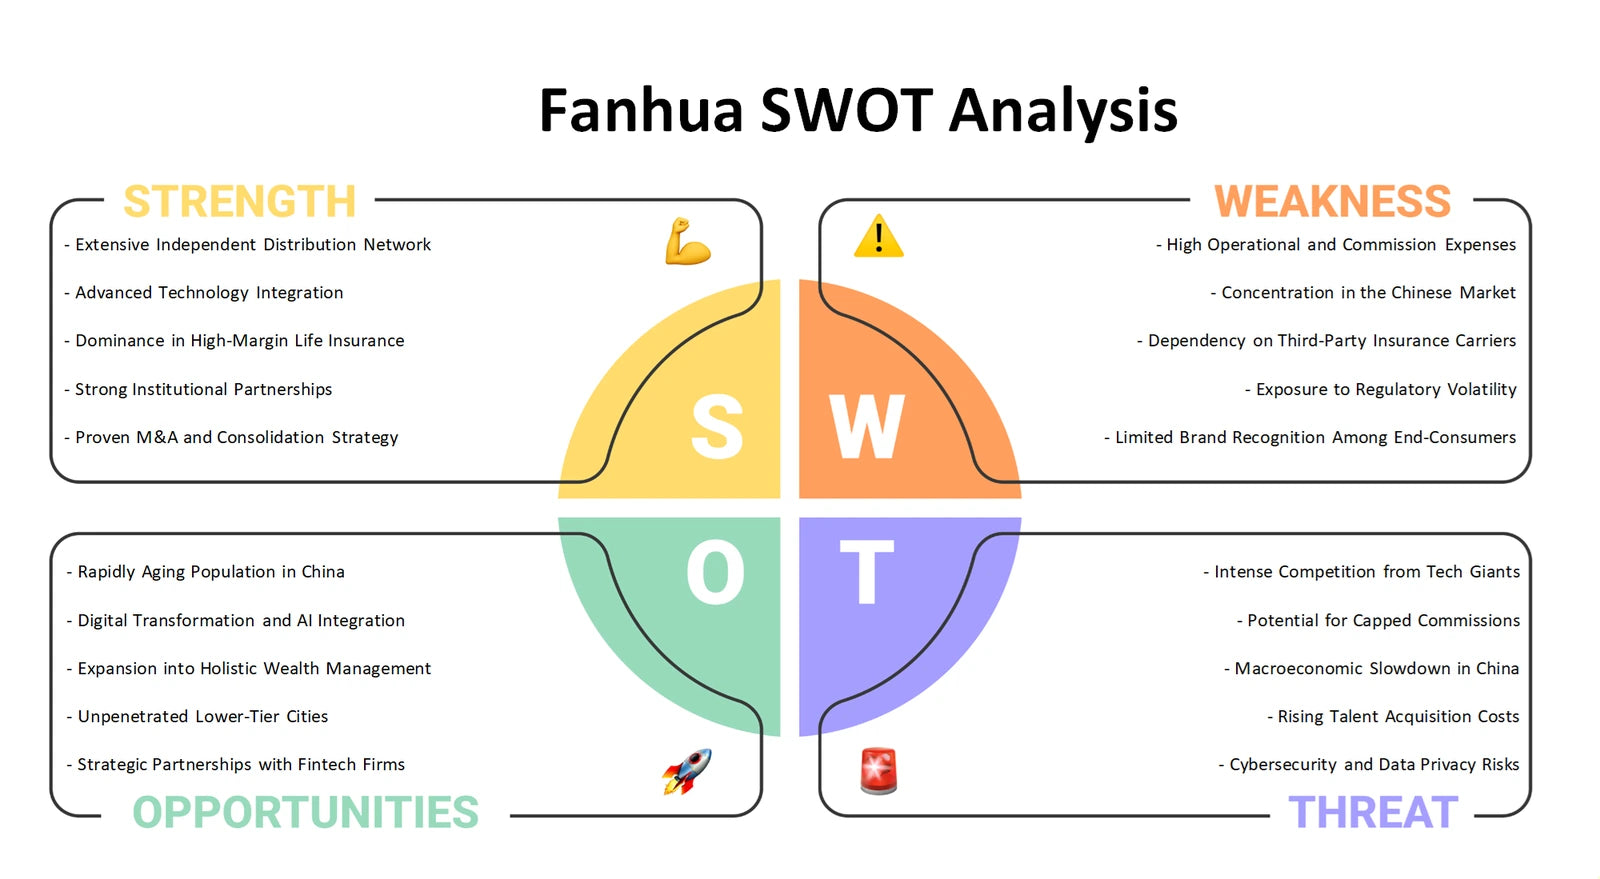
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect the portfolio, model and market pressures
Together, the six perspectives move from portfolio choices and value creation to industry pressure, customer-facing decisions, external change and strategic fit. The Excel frameworks provide organised places to compare assumptions and evidence, while the Word files provide detailed company analysis to support a more connected discussion of Fanhua’s insurance-intermediary model, carrier relationships and technology-enabled distribution questions.
Company background: Fanhua — Business Model Canvas product context.