

Erie Indemnity: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Erie Indemnity Strategy Analysis Bundle
Erie Indemnity is the workbook name for Erie Indemnity Company, a United States management company for Erie Insurance Exchange. Rather than treating it as a stand-alone insurer with identical economics to the Exchange, this bundle frames its role in the insurance system: management services that support underwriting, claims administration and an agency network serving policyholders. That distinction matters when assessing revenues, operating choices and portfolio priorities.
For April 1 through June 30, 2026, the company’s Form 10-Q filed July 30, 2026 reported revenue of USD 1,089,796,000 and GAAP net income of USD 180,294,000. These figures raise useful questions about service economics, agency and claims execution, and regulatory resilience. They are a dated company-context snapshot, not evidence that the downloadable analysis files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance-service activities merit investment, protection, testing or tighter resource discipline?
The Erie Indemnity BCG Matrix uses market growth and relative market share, rather than absolute revenue alone, to organize possible activities as Stars, Cash Cows, Question Marks or Dogs. For a management-company business, defining the portfolio boundary is essential: Erie Indemnity’s management and service economics should not be confused with Erie Insurance Exchange underwriting results. The framework helps compare agency support, claims capabilities and related insurance-service activities when considering where operating capacity may be maintained, developed or reviewed, without assigning any activity to a quadrant without evidence.
- Portfolio boundary. Separate the company’s management role from the Exchange’s insurance risk and policy economics before comparing activities.
- Resource logic. Examine whether service areas with different growth and relative-share profiles call for investment, efficiency focus, experimentation or reduced attention.
- Structured comparison. Use the Excel matrix to organize candidate activities and the Word analysis to document the assumptions, scope choices and implications behind each comparison.
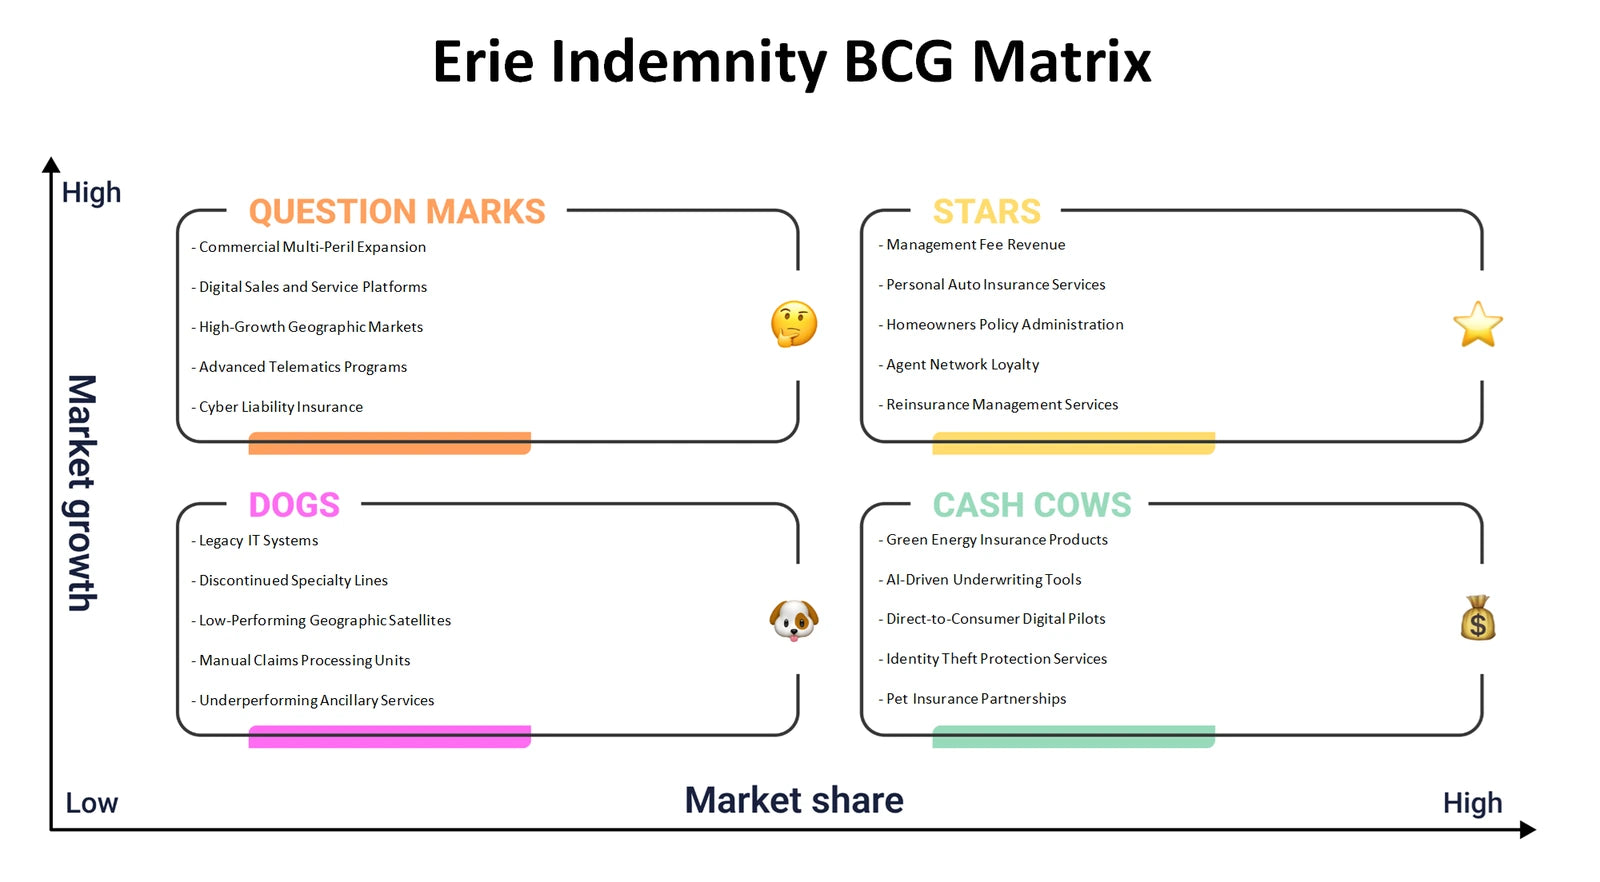
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How does the management-company role connect agency and claims operations to durable economic value?
The Erie Indemnity Business Model Canvas makes operating logic visible without blending premium economics with management-company revenue. It maps customer segments, including the Exchange relationship and the policyholder and agency users affected by operations, against value propositions, channels and customer relationships. It then connects revenue streams with key resources, key activities, key partnerships and cost structure. For Erie Indemnity, this lens helps trace how underwriting support, claims administration and agency-network coordination can create value while retaining an appropriate distinction between the company and the Exchange it manages.
- Stakeholder map. Clarify who receives value directly, who uses the operating system, and where agency relationships influence service delivery.
- Economic connections. Link management activities and operational resources to revenue streams and cost drivers instead of viewing each Canvas block in isolation.
- Working model. Populate the Excel Canvas as a connected map, then use the detailed Word analysis to explain dependencies, open questions and important company-versus-Exchange boundaries.
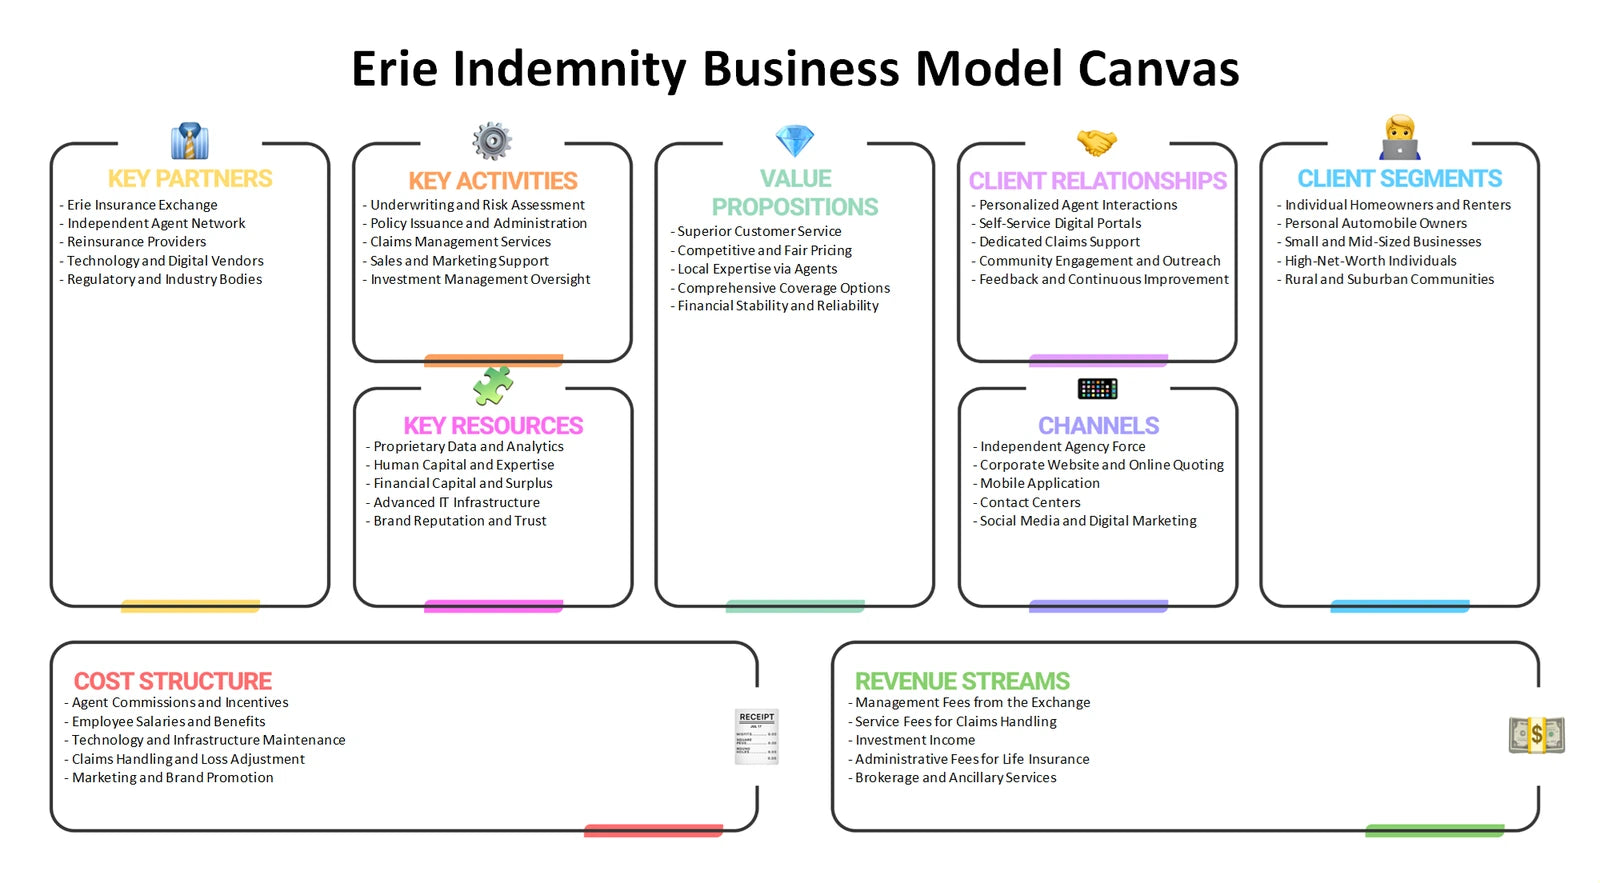
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape the economic room available to an insurance-management business?
Erie Indemnity Porter's Five Forces examines the industry conditions surrounding its management role and the insurance operations it supports. Rivalry can affect customer retention and agency relationships; supplier power can arise from technology, specialist service, repair or medical networks; and buyer power can be exercised by policyholders and channel participants. The framework also tests the threat of new entrants, including digitally enabled insurance models, and substitutes such as self-insurance, captives or other approaches to risk transfer. It does not assume that any force has a fixed strength; it provides a disciplined way to compare pressures and their operational consequences.
- Channel pressure. Assess how agency access, service expectations and customer switching considerations can influence competitive intensity.
- Operating dependencies. Consider which outside providers or capabilities could affect claims speed, service quality, data access or cost control.
- Evidence trail. Use the Excel framework to record each force and supporting observations, while the Word analysis helps turn those observations into a reasoned industry narrative.
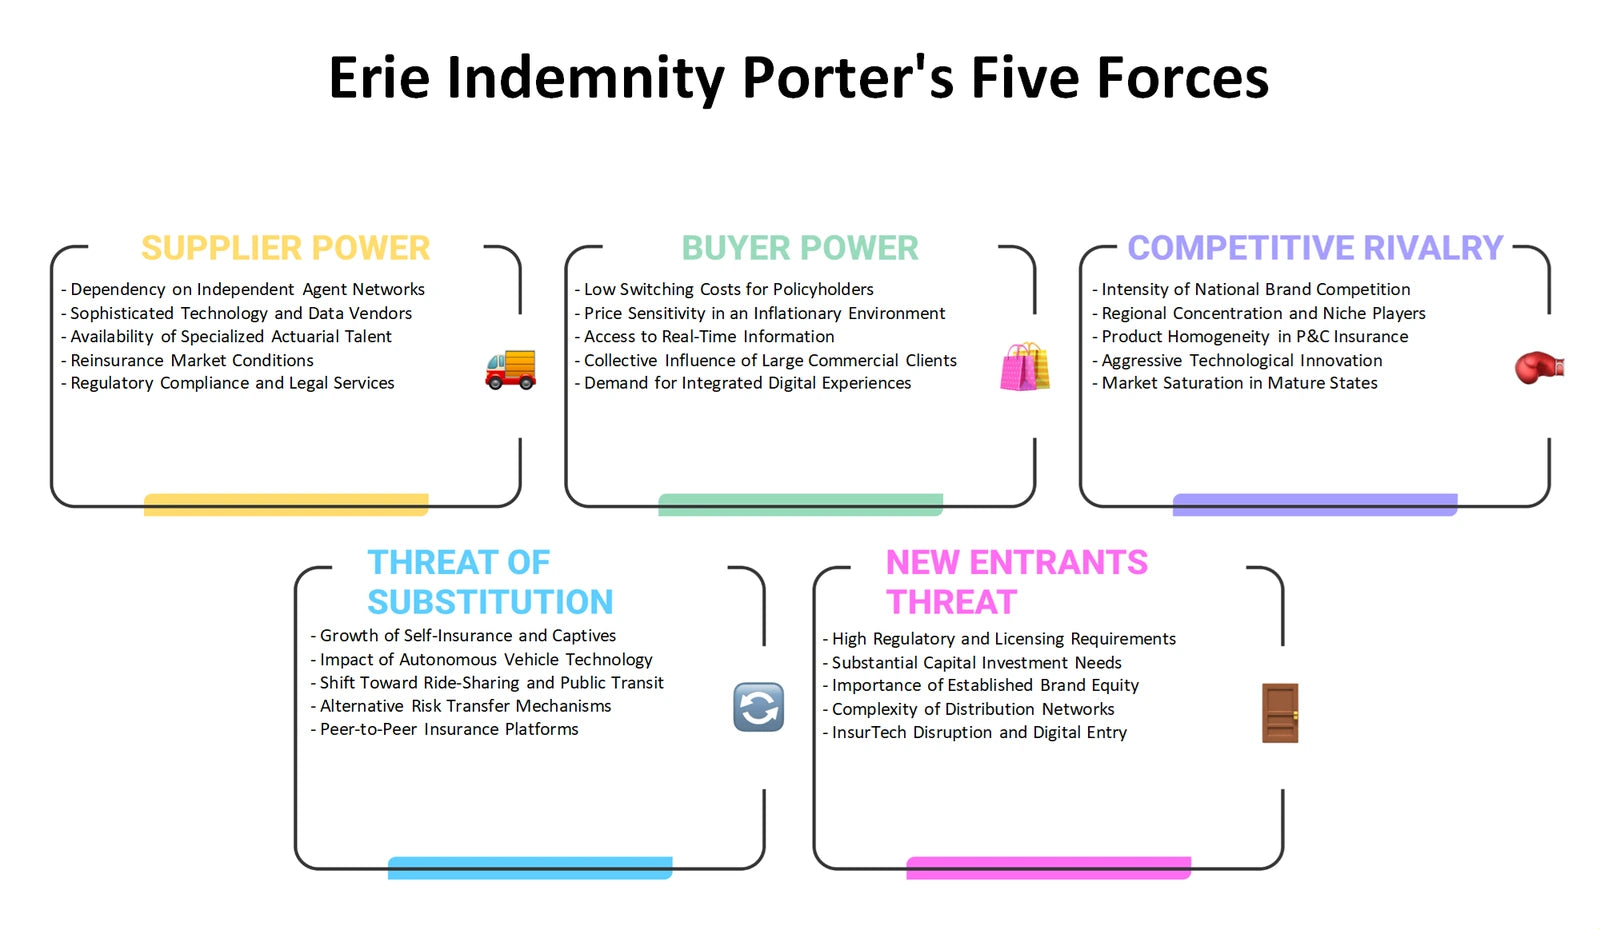
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should product, pricing, distribution and communications be assessed when the company manages rather than directly underwrites the Exchange?
The Erie Indemnity Marketing Mix separates the insurance offerings and premium decisions associated with the Exchange from Erie Indemnity’s own management and operating role. Product analysis can examine the policy and service experience supported by underwriting and claims processes. Price can distinguish premium logic from management-company revenue economics. Place focuses on the agency network and service routes through which customers are reached, while Promotion considers clear, compliant communication to policyholders, agents and other stakeholders. This distinction makes the 4Ps more useful than a generic consumer-marketing checklist.
- Offering experience. Connect insurance coverage and claims-service expectations to the management capabilities that help deliver them.
- Route and message. Evaluate how agency distribution and regulated communications may influence accessibility, trust and customer understanding.
- Planning view. Use the Excel 4Ps framework to compare decisions across Product, Price, Place and Promotion, then consult the Word analysis for company-specific context and discussion prompts.
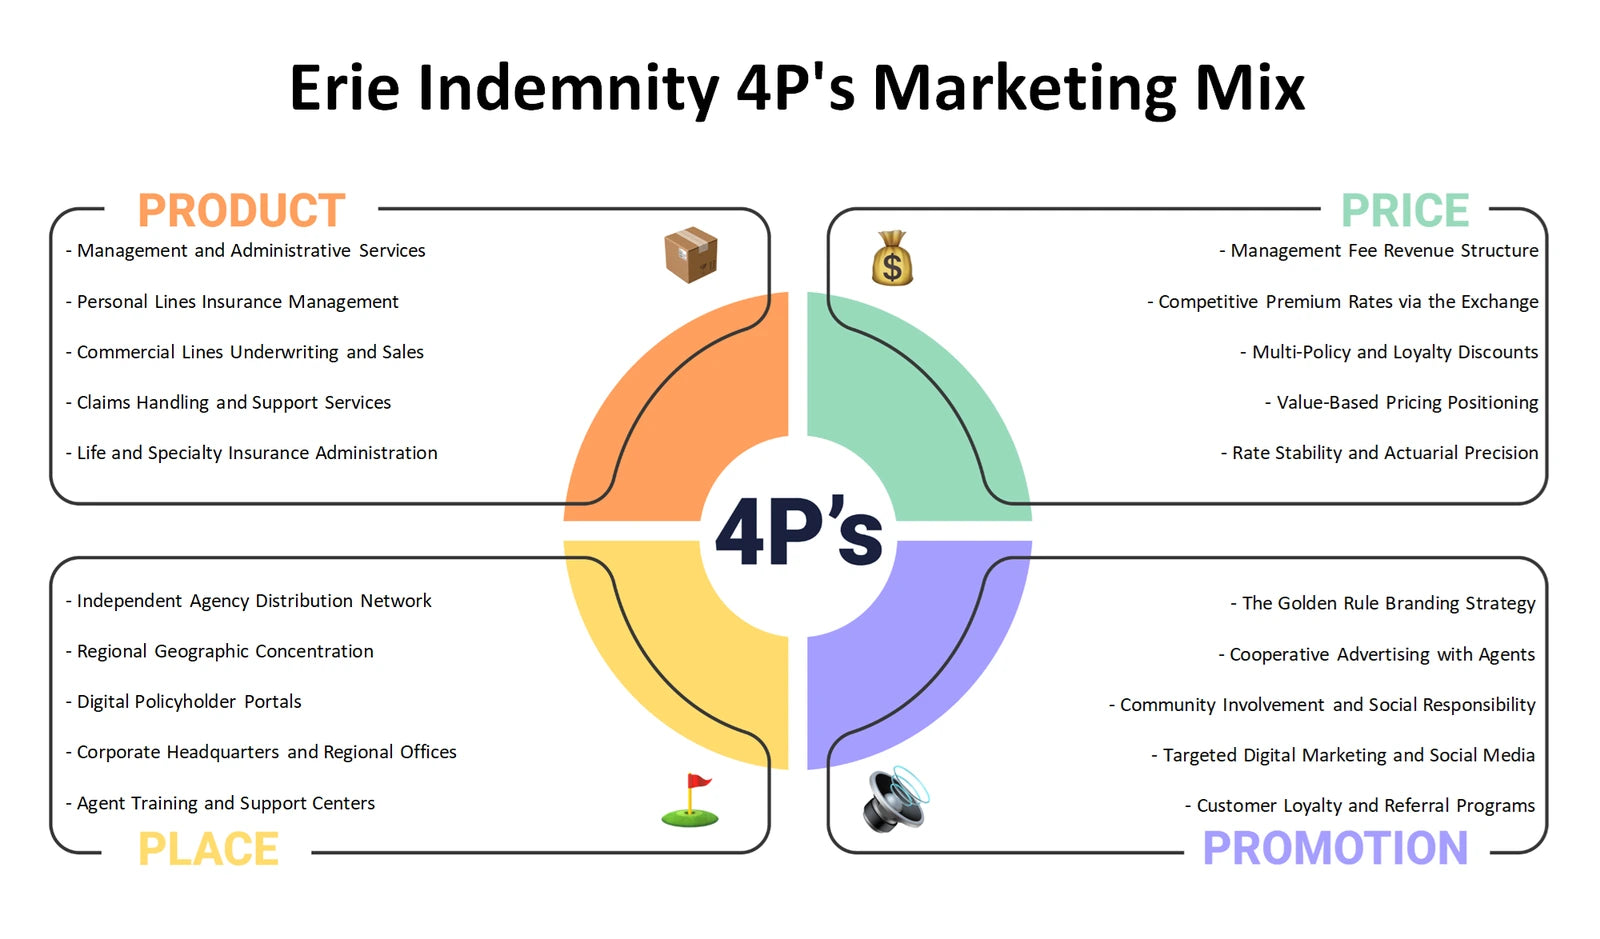
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter the regulatory, operating and customer environment around Erie Indemnity?
An Erie Indemnity PESTLE analysis, also commonly called PESTEL, organizes external influences that may affect a United States insurance-management business. Political considerations include state insurance policy and regulatory priorities. Economic questions include claims-cost inflation, investment conditions and household affordability. Social factors cover expectations for empathy, speed and transparent claims handling; technological factors include data, automation and cybersecurity. Legal analysis addresses filings, conduct, privacy and claims rules, while environmental analysis considers weather and catastrophe exposure. These are scenario areas to examine, not claims that a particular law, rate or event has already changed the company’s position.
- Regulatory horizon. Track policy and legal questions that could affect documentation, examinations, agency practices and claims administration.
- Claims environment. Relate economic, social, technological and environmental conditions to service demand, severity management and customer expectations.
- Scenario register. Use the Excel framework to sort external drivers by category and potential relevance, with the Word analysis providing context for more informed discussion.
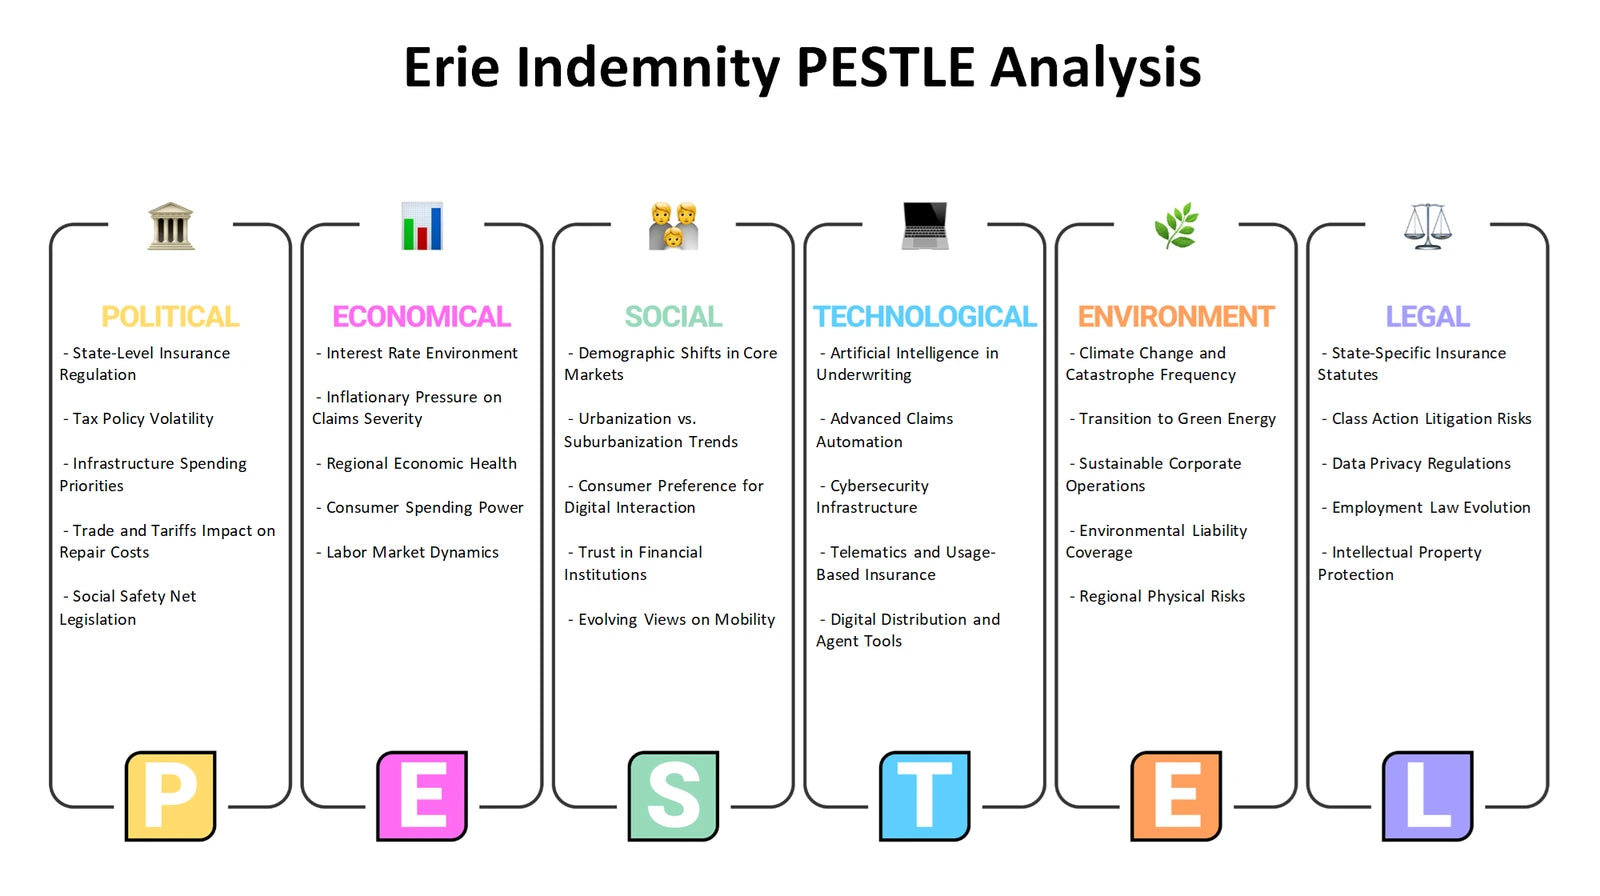
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside the opportunities and threats facing the insurance system?
The Erie Indemnity SWOT analysis keeps internal and external issues properly separated. Potential internal strengths to test include claims-administration processes, agency-network support, operational documentation and compliance practices. Possible internal weaknesses may involve coordination complexity, process bottlenecks or dependence on a defined management relationship; these are topics for examination rather than established findings. Opportunities are external possibilities, such as service improvement through appropriate technology, while threats may arise from regulation, cyber risk, changing customer expectations or loss-related volatility. This structure helps avoid calling a market condition a company strength or treating an internal capability as an external opportunity.
- Classification discipline. Distinguish what Erie Indemnity can influence internally from forces that originate in the market, regulatory environment or operating ecosystem.
- Strategic pairing. Explore how a verified capability might support an external opportunity, or where an internal limitation could increase exposure to a threat.
- Decision record. Build the Excel SWOT grid with concise evidence notes, then use the Word analysis to develop balanced implications and follow-up questions.
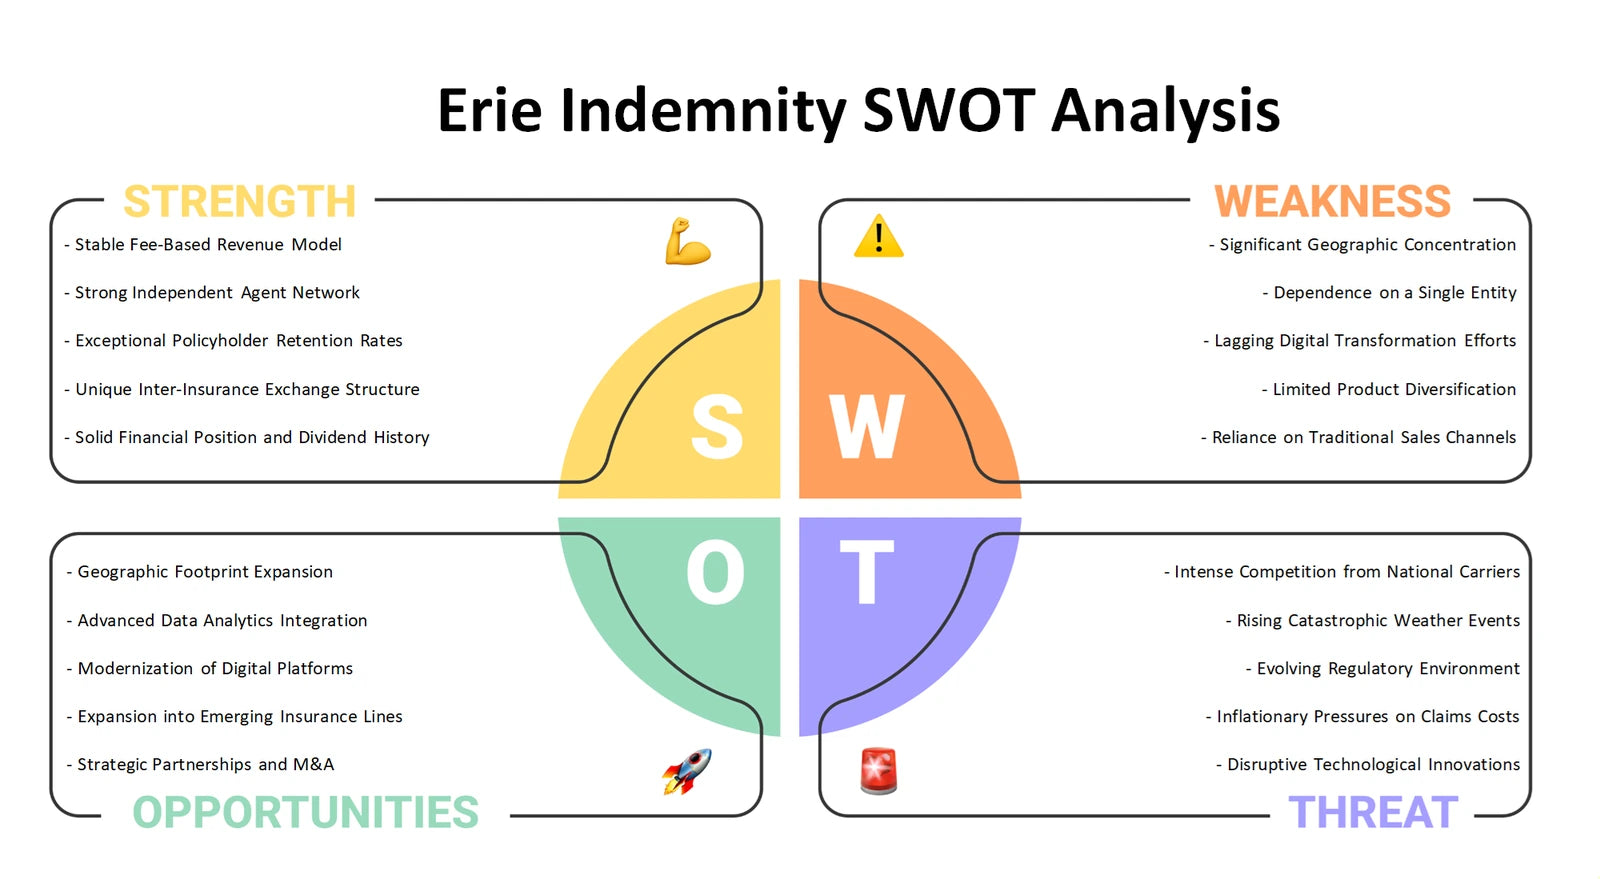
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect the operating model to strategic choices
Together, the six perspectives help place Erie Indemnity’s management-company role in context. The BCG Matrix considers portfolio priorities; the Canvas explains value creation; Five Forces and PESTLE examine industry and external pressure; the 4Ps considers customer and channel choices; and SWOT connects internal capabilities with external conditions. The Excel frameworks and detailed Word analysis materials can help you develop a more organized company-specific strategy discussion while keeping management-company and Exchange economics distinct.
Company background: Erie Indemnity Company — SEC Form 10-Q filed July 30, 2026.