

Northfield Bank: Banking Business and Regulation – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Northfield Bank Strategy Analysis Bundle
The supplied product context describes Northfield Bank as a relationship-led community-bank business with mortgage-lending activity supported by local real-estate and broker referrals, loan-sale and funding relationships, hedging counterparties, and third-party servicing support. Borrowers, local referral partners and capital-market counterparties therefore matter alongside the bank’s direct customer relationships.
That business model creates practical questions about loan-product priorities, funding flexibility, channel economics and the effect of changing credit, rate and compliance conditions. The six analyses help organize those questions from different angles: portfolio choices, value creation, industry pressure, market delivery, external change and internal positioning. They are structured tools for examining the described business model, not claims about verified current performance or recommendations already reached.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, deposit or related service areas merit resources when growth prospects and relative market share may differ?
A Northfield Bank BCG Matrix helps separate portfolio thinking from a simple list of products. It uses market growth and relative market share to test where a lending or banking activity could be considered a Star, Cash Cow, Question Mark or Dog. For the described mortgage-oriented model, the exercise can compare the strategic role of referral-led origination, relationship banking and balance-sheet capacity without assuming that any activity already belongs in a quadrant. This matters because capital, staff attention, risk limits and funding capacity are finite.
- Portfolio lens. Compare offerings by their relevant market definition, growth conditions and relative position rather than by volume alone.
- Resource trade-offs. Explore whether mature activities may support investment in developing opportunities or whether weak-fit activities require closer review.
- Structured comparison. Use the Excel framework to map candidate activities and the Word analysis to record assumptions, evidence needs and portfolio implications.
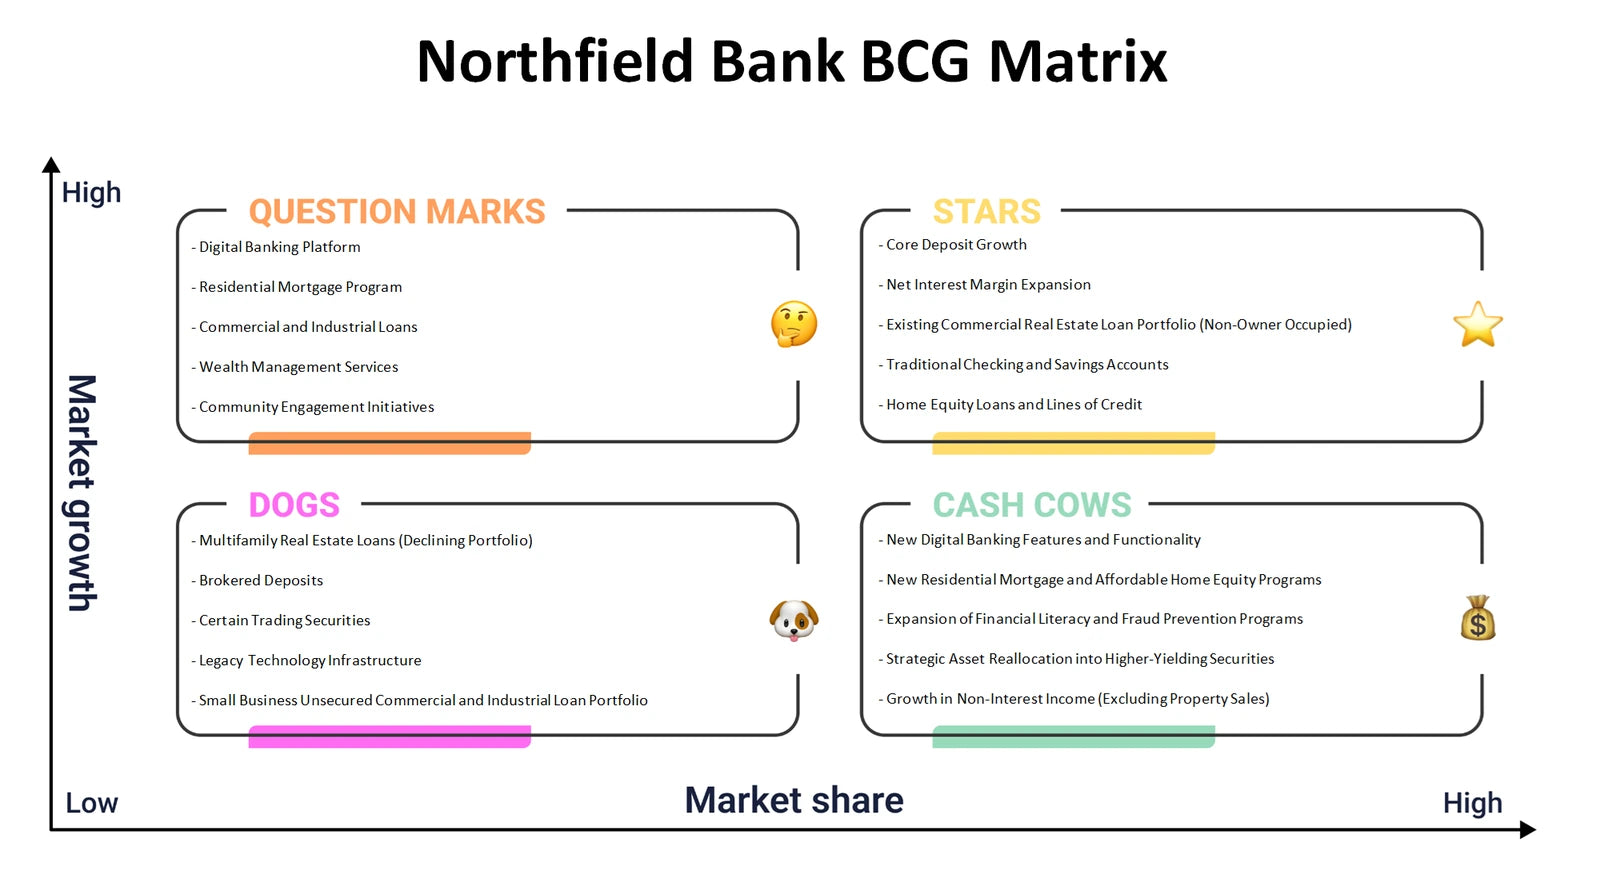
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, mortgage distribution and liquidity partners connect to value delivery and earnings?
The Northfield Bank Business Model Canvas examines the full logic of the described operation through nine connected building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It can help relate personalized local decision-making to borrowers and referral partners, while also considering the operational work behind origination, hedging, servicing and funding. The value lies in tracing dependencies: a channel can increase applications, but it also affects service capacity, compliance work, partner economics and the revenue generated from completed lending activity.
- Customer-to-channel fit. Examine how borrowers, real-estate professionals and mortgage brokers may encounter, evaluate and remain connected to the bank.
- Operating logic. Connect lending activities and relationship management with resources, partnerships, costs and potential revenue streams.
- Model workshop. Populate the Excel blocks with team inputs, then use the Word analysis to discuss the links and tensions between the nine elements.
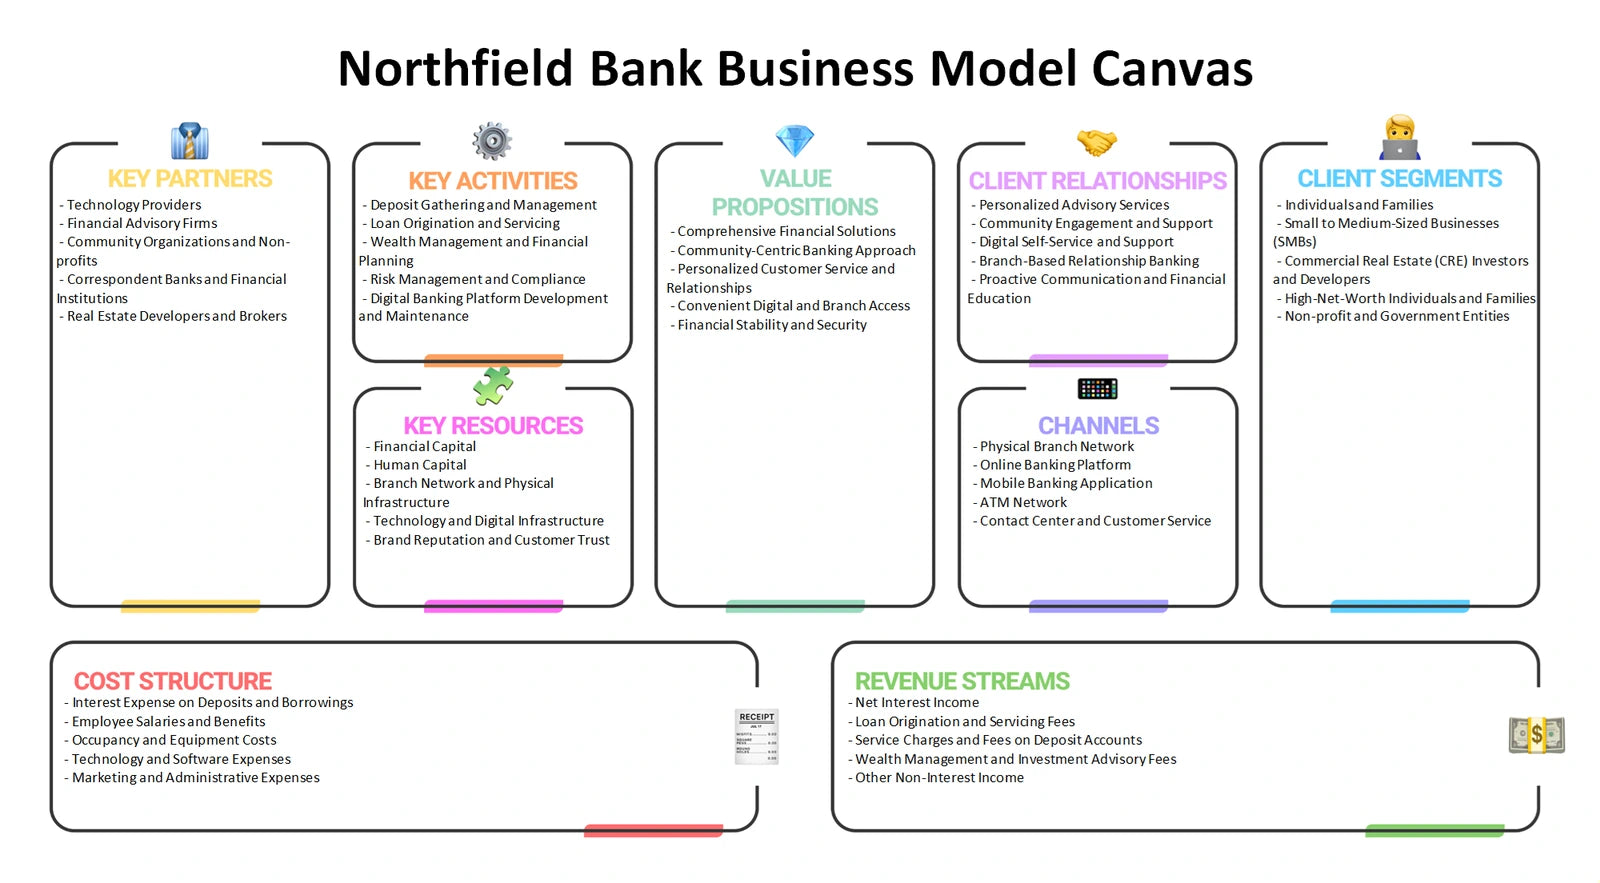
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness and resilience of relationship-based mortgage and banking activity?
Northfield Bank Porter's Five Forces provides a disciplined way to examine the competitive environment surrounding the described lending model. Rivalry can arise from banks and other mortgage providers seeking similar borrowers and referral relationships. Buyer power considers how easily borrowers can compare terms, service and speed. Supplier power can include the influence of funding, capital-market, technology and servicing relationships. New entrants may use digital distribution or specialized models, while substitutes include other ways customers finance, save, transact or obtain housing-related credit. The framework does not assign force scores; it prompts evidence-based discussion of where pressure could affect margins, service or access.
- Competitive pressure. Assess where relationship quality, underwriting experience and local responsiveness may matter alongside rate and convenience.
- Dependency exposure. Consider how external funding, hedging, servicing and secondary-market relationships can influence bargaining positions.
- Evidence trail. Use the Excel framework to compare forces and the Word analysis to capture rationale, open questions and management discussion points.
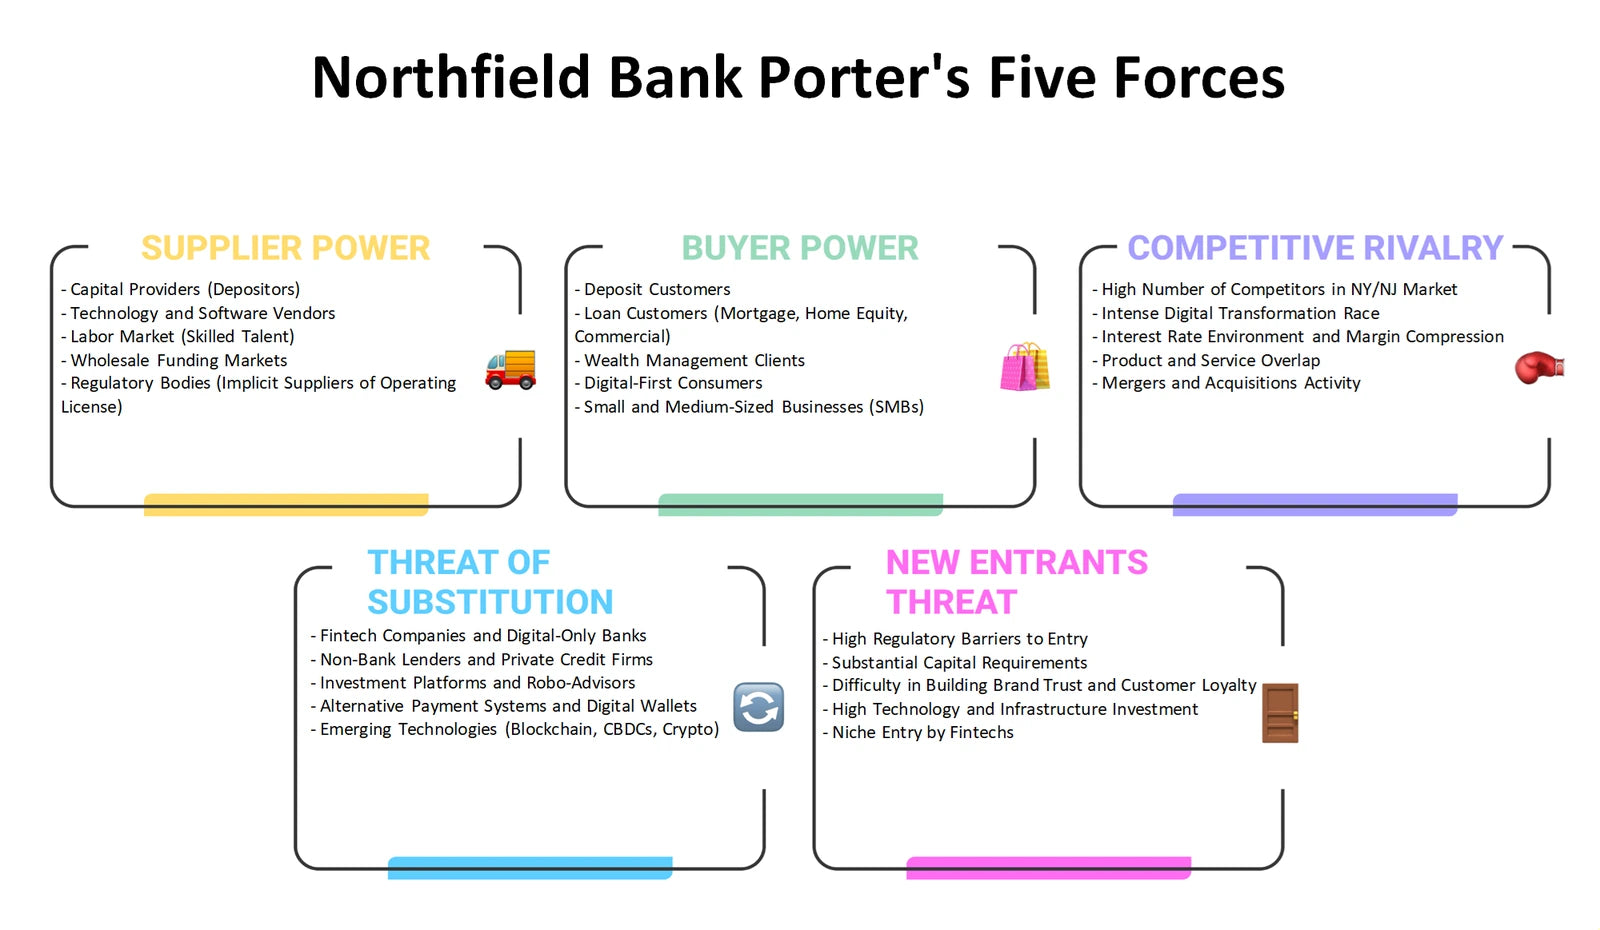
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can lending and relationship-banking choices be examined through Product, Price, Place and Promotion?
A Northfield Bank Marketing Mix considers the 4Ps in a regulated, trust-sensitive financial-service setting. Product can cover the customer needs addressed by lending and related banking services; Price examines rate, fee and value communication without assuming a particular price point. Place looks at the routes through which customers engage, including local relationships and referral pathways described in the product context. Promotion considers how a community-bank reputation, service approach and lending expertise might be communicated responsibly. Looking across all four elements helps reveal whether the customer promise, access route and economic logic support one another.
- Offer design. Review how product scope and service experience may address borrower needs while remaining practical to deliver.
- Route and message. Compare the roles of direct relationships, real-estate referrals and broker connections in reaching suitable audiences.
- Planning tool. Use the Excel framework to align the 4Ps, then use the Word analysis to document positioning questions and compliance-aware messaging considerations.
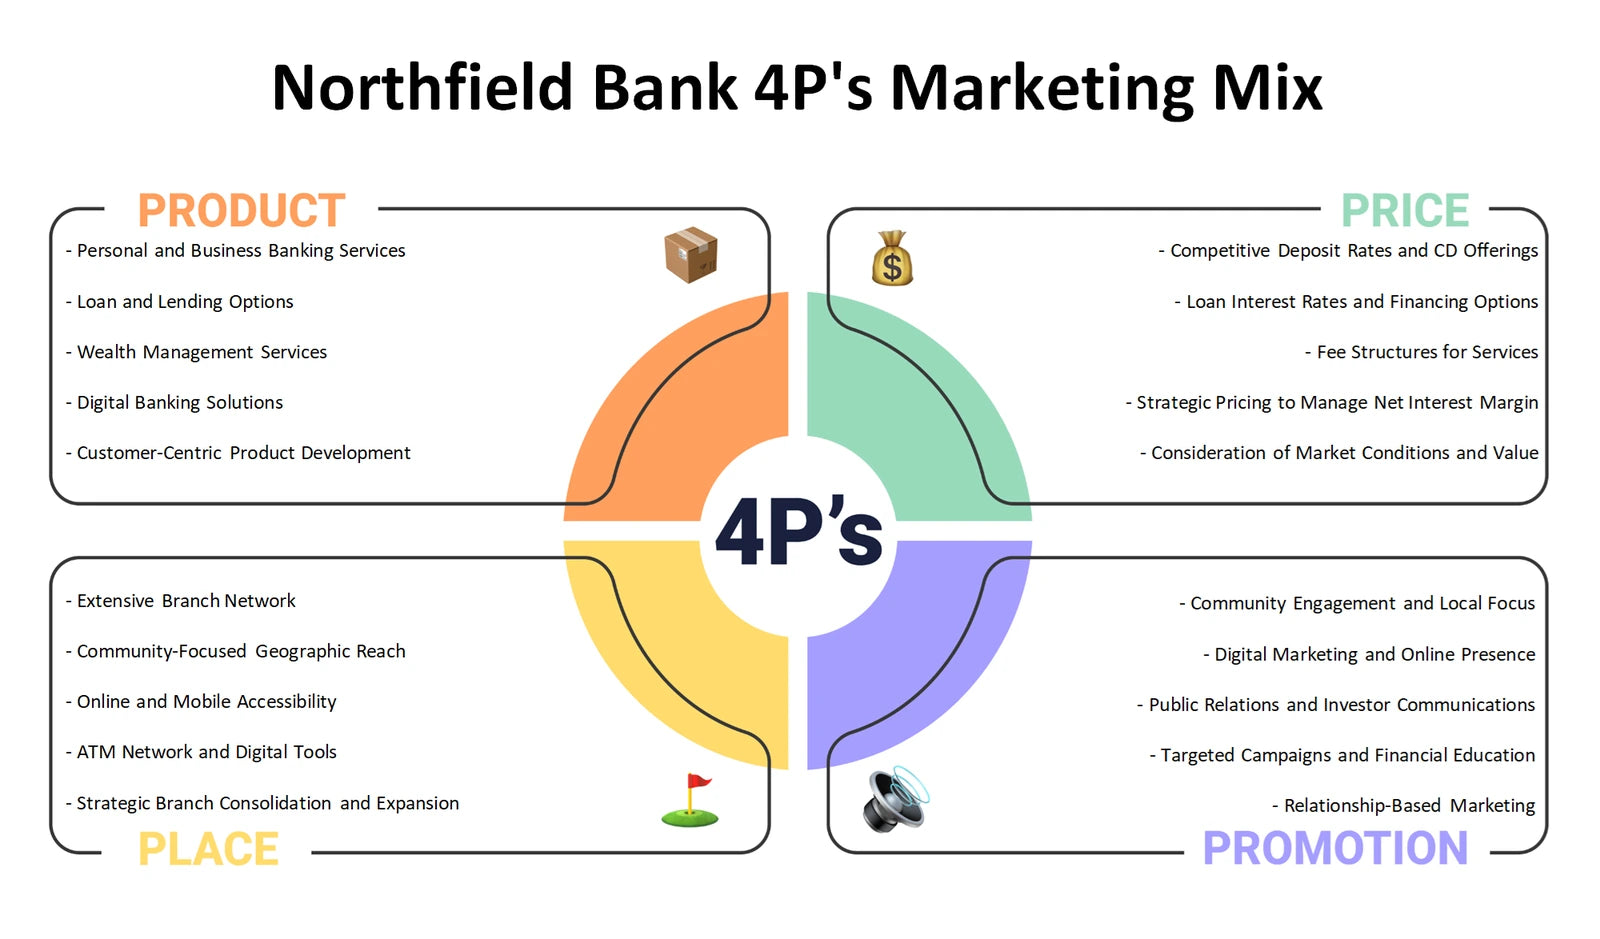
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external forces should be monitored when mortgage demand, funding conditions and banking regulation can change together?
Northfield Bank PESTLE analysis, also commonly called PESTEL, organizes external influences that the business cannot control but must interpret. Political and Legal factors can include housing-finance policy, prudential expectations, consumer protection and data obligations. Economic conditions may affect borrowing demand, credit performance, property markets, funding costs and rate sensitivity. Social factors can shape trust, household preferences and demand for local guidance. Technological change can alter application, servicing and security expectations, while Environmental conditions may influence property risk, disclosures and operational resilience. These are analytical categories, not assertions that a particular policy or market change has occurred.
- External signals. Distinguish broader economic and housing questions from specific regulatory or policy developments that require verification.
- Connected exposure. Explore how external change may affect borrowers, referral activity, collateral, operations and liquidity at the same time.
- Monitoring agenda. Use the Excel framework to prioritize signals and the Word analysis to explain relevance, ownership and questions for further research.
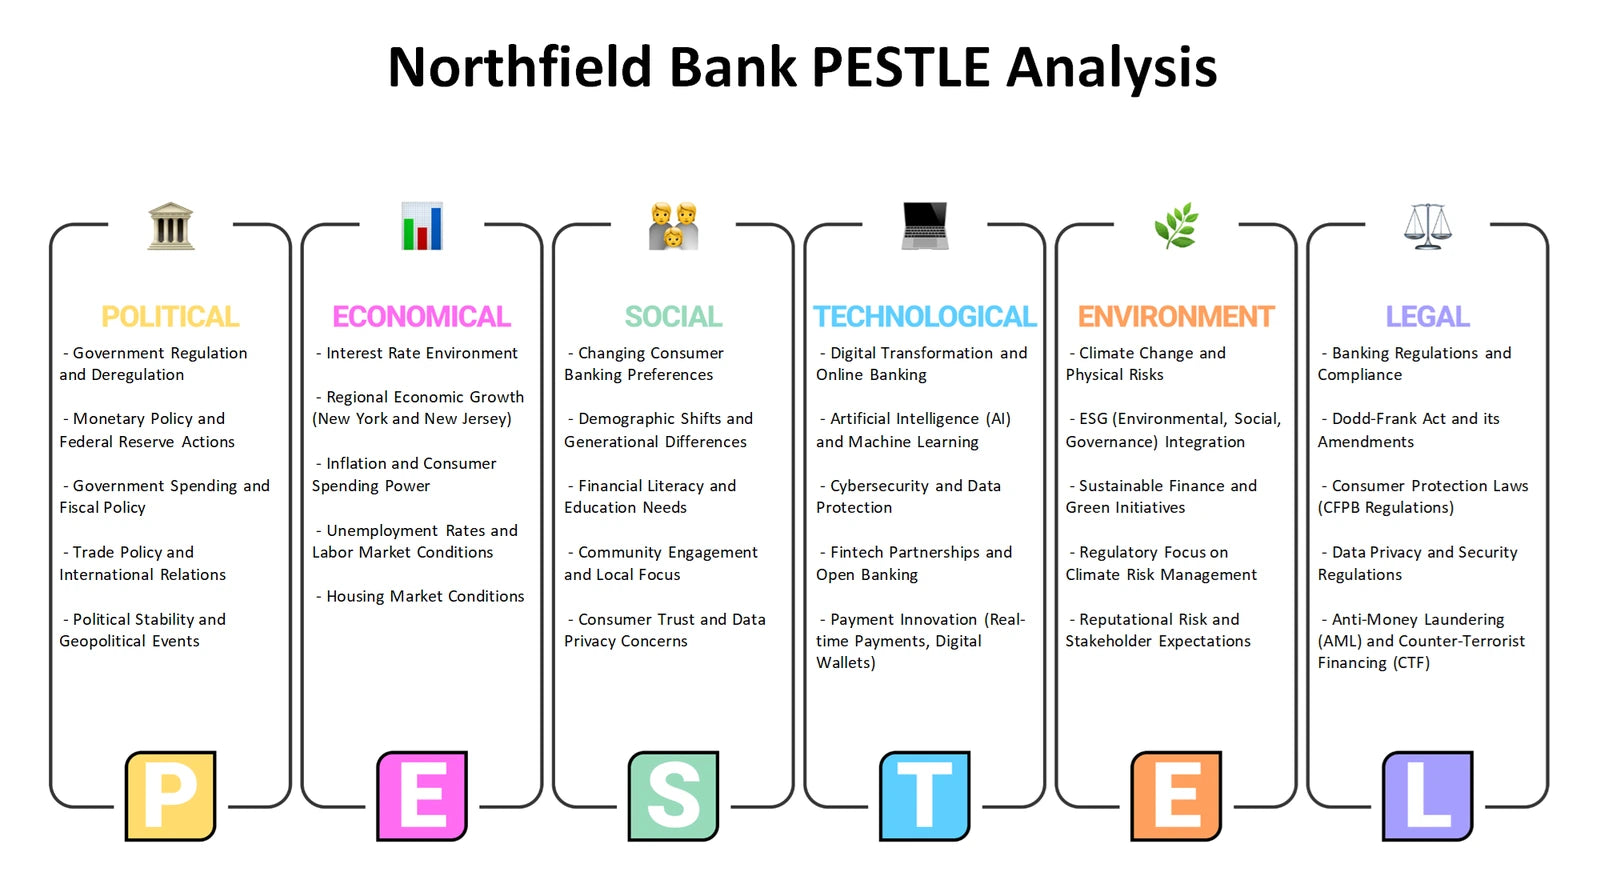
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Northfield Bank distinguish its internal capabilities and constraints from external opportunities and threats?
A Northfield Bank SWOT analysis brings the prior lenses into a concise decision frame while keeping classifications accurate. Strengths and Weaknesses are internal: for example, the analysis can examine relationship-management capability, local decision processes, partner-management capacity, operating scale or concentration risks. Opportunities and Threats are external: they may include changing customer expectations, referral-market conditions, technology shifts, competitive intensity or economic uncertainty. The supplied context points to a community-bank positioning and partner-based mortgage ecosystem, but the framework should test rather than assume whether these become advantages or vulnerabilities in a defined market.
- Internal diagnosis. Separate controllable resources, processes and limitations from conditions outside the organization’s direct control.
- Strategic fit. Compare possible opportunities with the capabilities required to pursue them and threats with the resilience needed to manage them.
- Decision record. Use the Excel matrix to organize themes and the Word analysis to add context, evidence requirements and implications for priority setting.
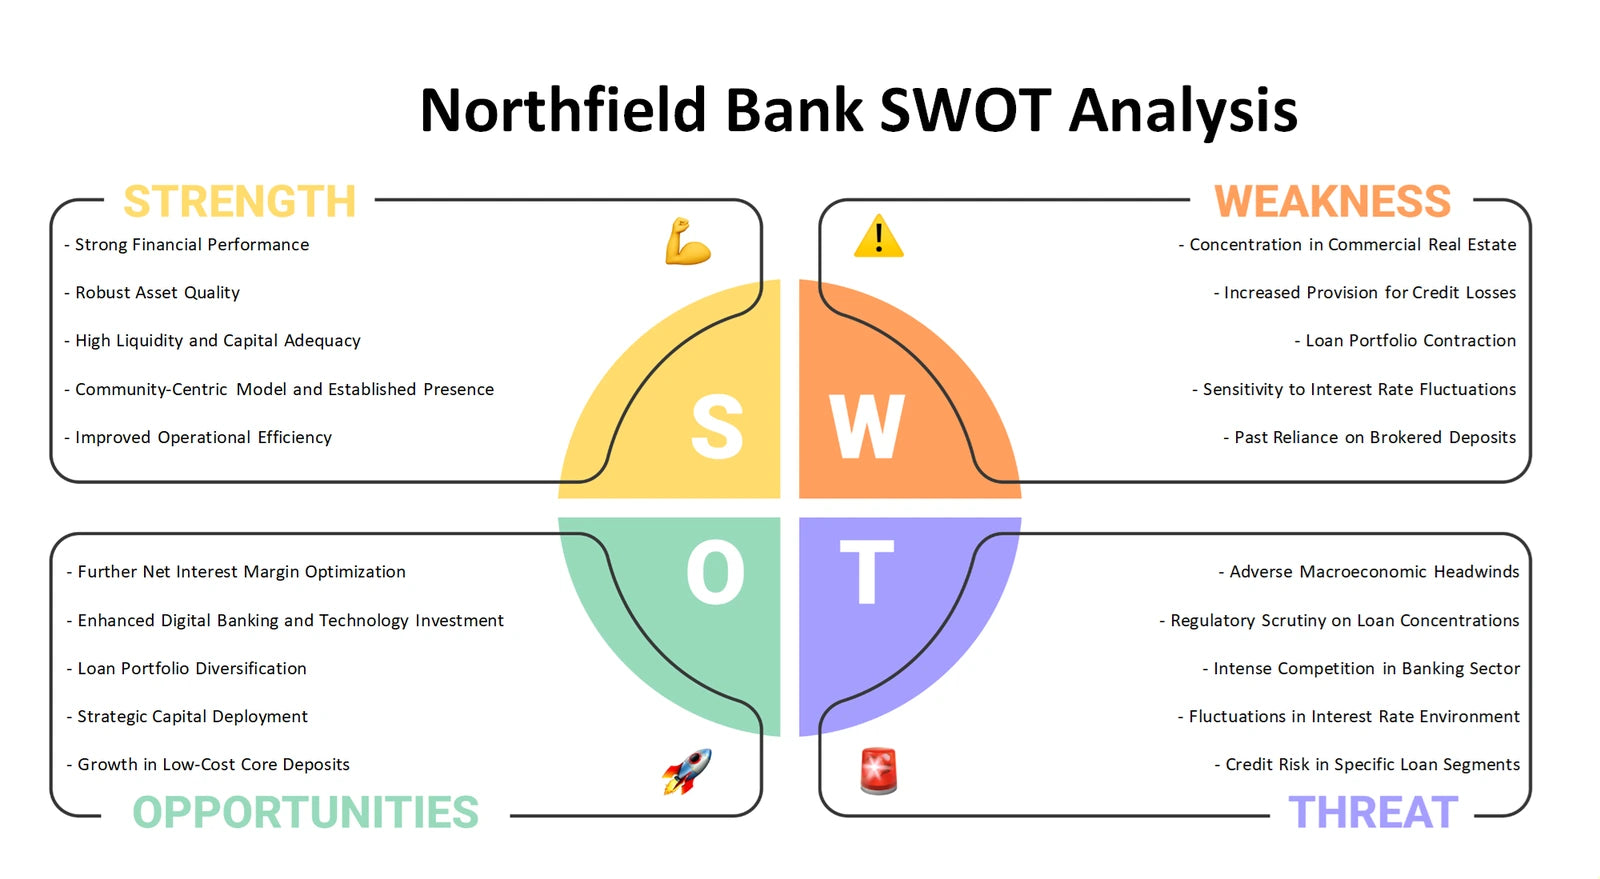
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect the portfolio, model and market questions
Together, the six perspectives help customers examine Northfield Bank from complementary directions: BCG considers portfolio priorities; Canvas traces value creation and economics; Five Forces tests industry pressure; the 4Ps examines market delivery; PESTLE scans external conditions; and SWOT distinguishes internal realities from external possibilities. The Excel frameworks support structured comparison, while the Word files provide detailed company-analysis context for workshops, planning discussions and further evidence gathering.
Company background: Northfield Bank — product-context page.