

E-L Financial: Underwriting and Sourcing – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
E-L Financial Strategy Analysis Bundle
E-L Financial refers here to E-L Financial Corporation Limited’s Canadian insurance and investment context, centred on Empire Life. The business serves Canadians with life, health and investment offerings distributed through financial advisors, brokers, managing general agents and mutual fund dealers.
Customer choice in insurance and investments depends on advice, confidence, product fit and service as much as price. This bundle helps examine how E-L Financial can weigh portfolio priorities, intermediary distribution, reinsurance-supported risk capacity and changing competitive pressures without treating analytical questions as established findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which E-L Financial product lines or distribution propositions deserve priority when market growth is compared with relative market share?
The E-L Financial BCG Matrix provides a disciplined way to compare life, health and investment-related activities rather than assuming every offering should receive the same capital, management attention or distribution support. It uses market growth and relative market share to frame possible Stars, Cash Cows, Question Marks and Dogs. For an insurer, the useful question is not simply which product is popular: it is whether a proposition can earn an attractive place in a competitive market after underwriting risk, servicing needs, advisor support and capital demands are considered. The framework can help distinguish mature sources of cash generation from areas where growth may require greater investment or clearer differentiation.
- Portfolio comparison. Examine product families, customer niches or channel propositions against consistent growth and relative-share criteria.
- Capital trade-offs. Consider how risk capacity, reinsurance arrangements and distribution effort affect the resources available for each possible priority.
- Working view. Use the Excel matrix to organize candidate positions, then use the Word analysis to document the assumptions and evidence behind each portfolio discussion.
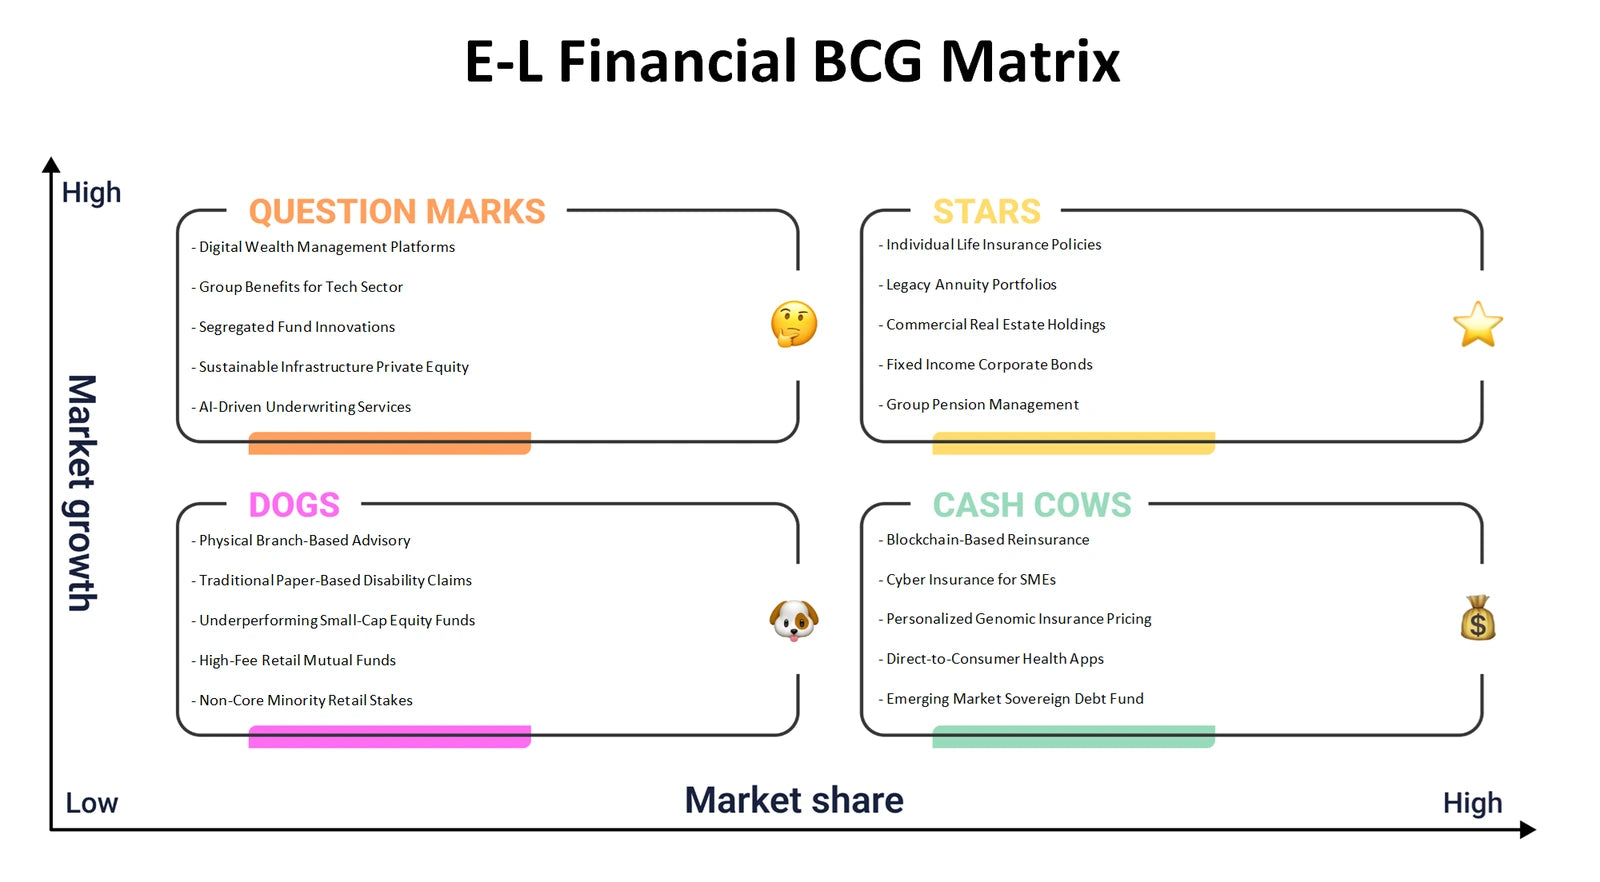
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do E-L Financial’s adviser-led customer access, insurance risk management and investment offerings fit together economically?
The E-L Financial Business Model Canvas connects all nine building blocks in one operating logic. It maps customer segments of Canadians seeking protection, health coverage or investment solutions; the value propositions offered to them; and channels including advisors, brokers, managing general agents and mutual fund dealers. It also considers customer relationships built through advice and ongoing service, alongside revenue streams that can be tested for insurance and investment economics. Behind the customer-facing model are key resources such as risk capacity and specialist expertise, key activities including underwriting and claims administration, key partnerships such as intermediaries and reinsurers, and the cost structure required to deliver and support policies. This view is especially useful where a customer’s choice is influenced by both the product and the trusted route through which it is explained.
- Customer-to-channel fit. Compare which segments may value adviser guidance, product simplicity, service continuity or different forms of investment access.
- Economic linkages. Trace how distribution compensation, administration, underwriting, reinsurance and customer retention can shape revenue quality and costs.
- Connected mapping. Complete the Excel canvas block by block, using the Word analysis to add context on the relationships and trade-offs behind each entry.
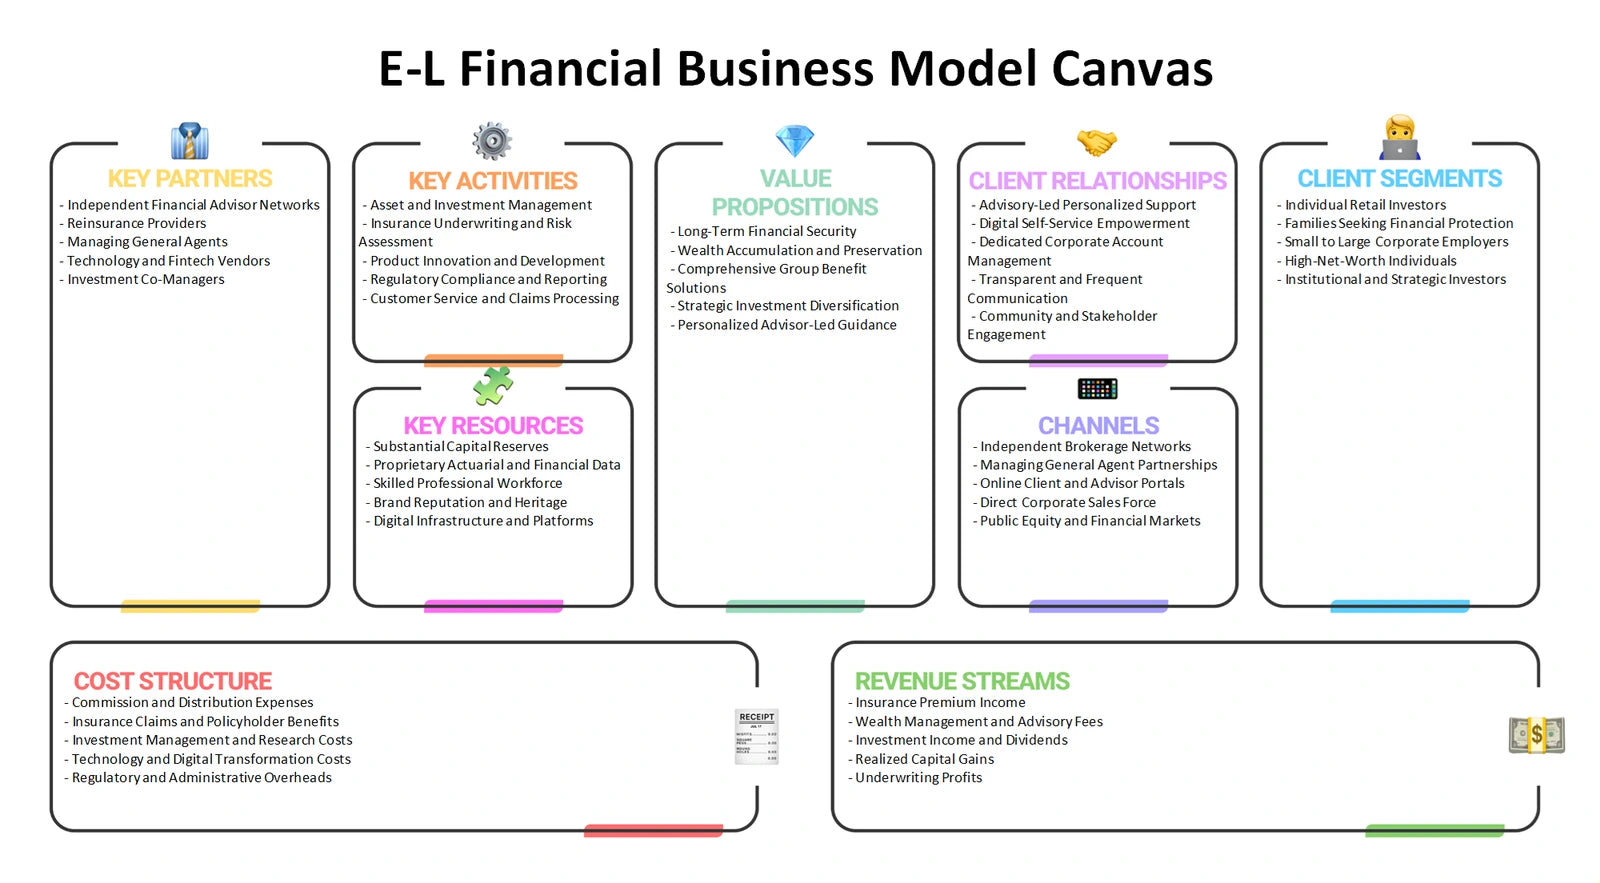
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence E-L Financial’s ability to retain advisers, win customer consideration and earn acceptable risk-adjusted returns?
E-L Financial Porter's Five Forces examines the competitive structure around Canadian life, health and investment products. Rivalry can be explored through the number of alternatives available to advisers and consumers, as well as the challenge of standing out on product design, service and financial confidence. Buyer power includes both informed customers who can compare options and intermediaries that influence product selection. Supplier power can include the leverage of distribution partners, specialist service providers and reinsurers. The threat of new entrants is shaped by regulation, capital requirements and the credibility needed to earn trust, while substitutes include self-directed investments, deposit products, public programs or other ways households address protection and savings needs. Each force changes the value of differentiation.
- Choice architecture. Assess where customers and advisers can switch easily and where advice, service or product fit may reduce comparability.
- Industry constraints. Evaluate how regulation, capital intensity, reinsurance availability and established distribution relationships affect entry and bargaining power.
- Evidence trail. Use the Excel framework to record force-by-force observations and the Word analysis to explain why a pressure matters to the business model.
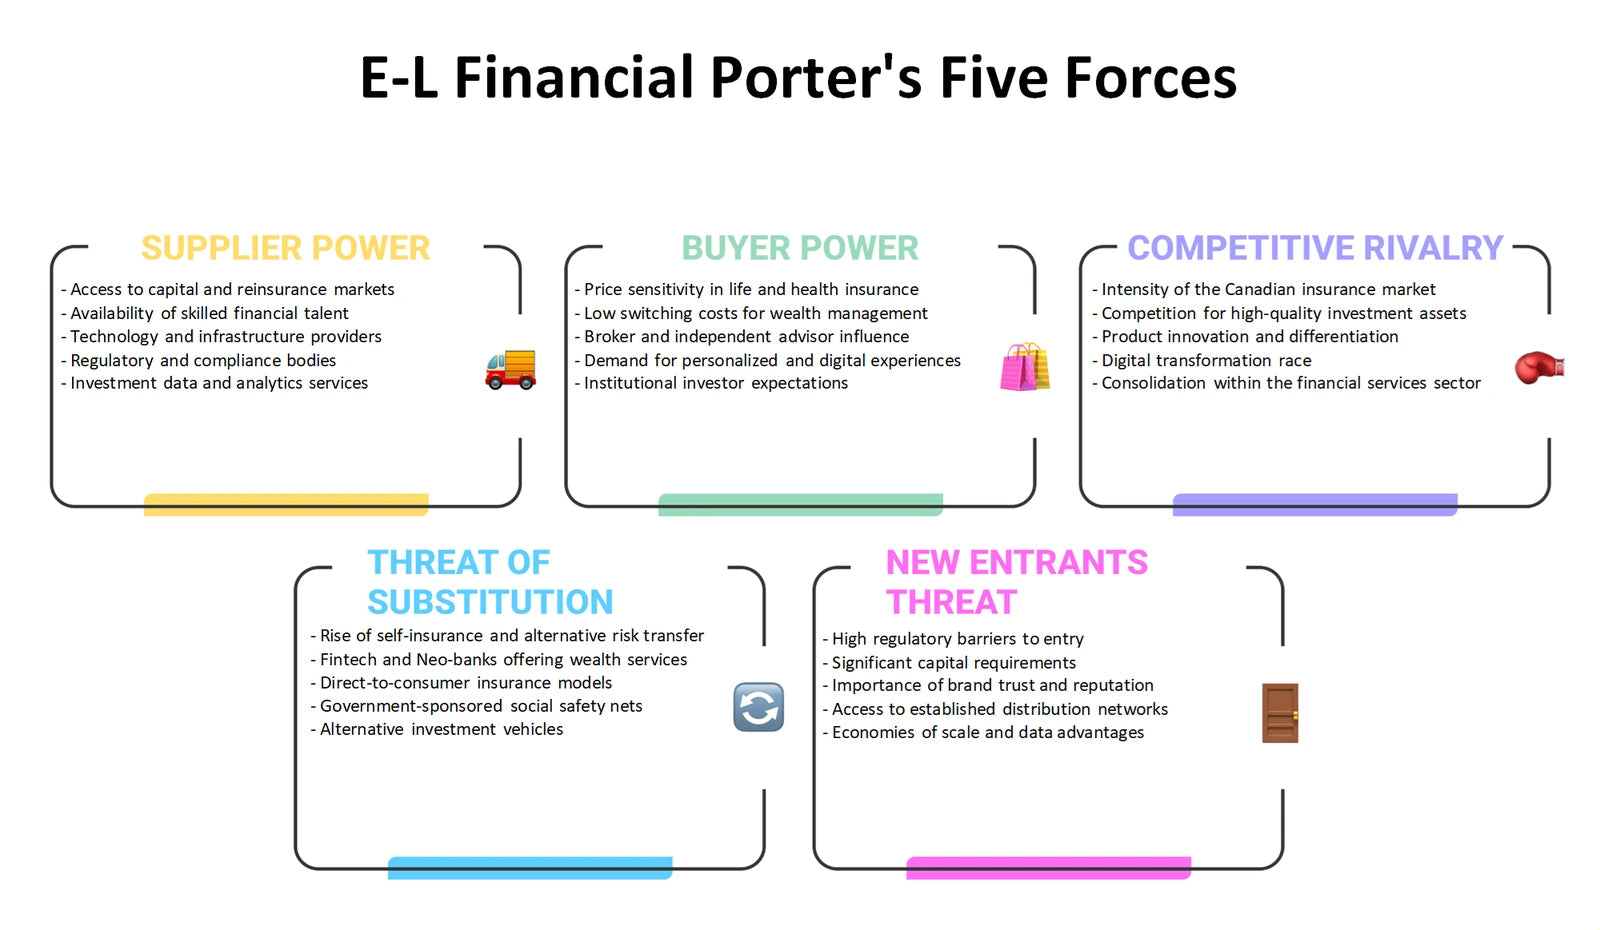
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can E-L Financial make regulated protection and investment offerings easier for Canadians to understand and choose through adviser-led channels?
The E-L Financial Marketing Mix considers Product, Price, Place and Promotion as linked customer-choice decisions. Product analysis can examine the role of life, health and investment offerings in addressing protection, savings and long-term financial needs. Price is more than a quoted premium or charge: it can be assessed in relation to underwriting, risk, service value, affordability and disclosure. Place focuses on the company’s advisor, broker, managing general agent and mutual fund dealer relationships, which are central to reaching customers across Canada. Promotion should be examined in a regulated setting where clear communication, appropriate advisor education and trustworthy explanations matter. The 4Ps lens helps avoid treating distribution as a back-office issue when it is integral to how a customer evaluates a complex financial decision.
- Offering clarity. Explore which product features and service elements are most relevant to distinct protection or investment needs.
- Channel credibility. Consider how intermediary support, compliant communications and customer understanding can affect conversion and retention.
- Planning sequence. Use the Excel 4Ps structure to compare proposed choices, then refer to the Word analysis when recording rationale and implementation questions.
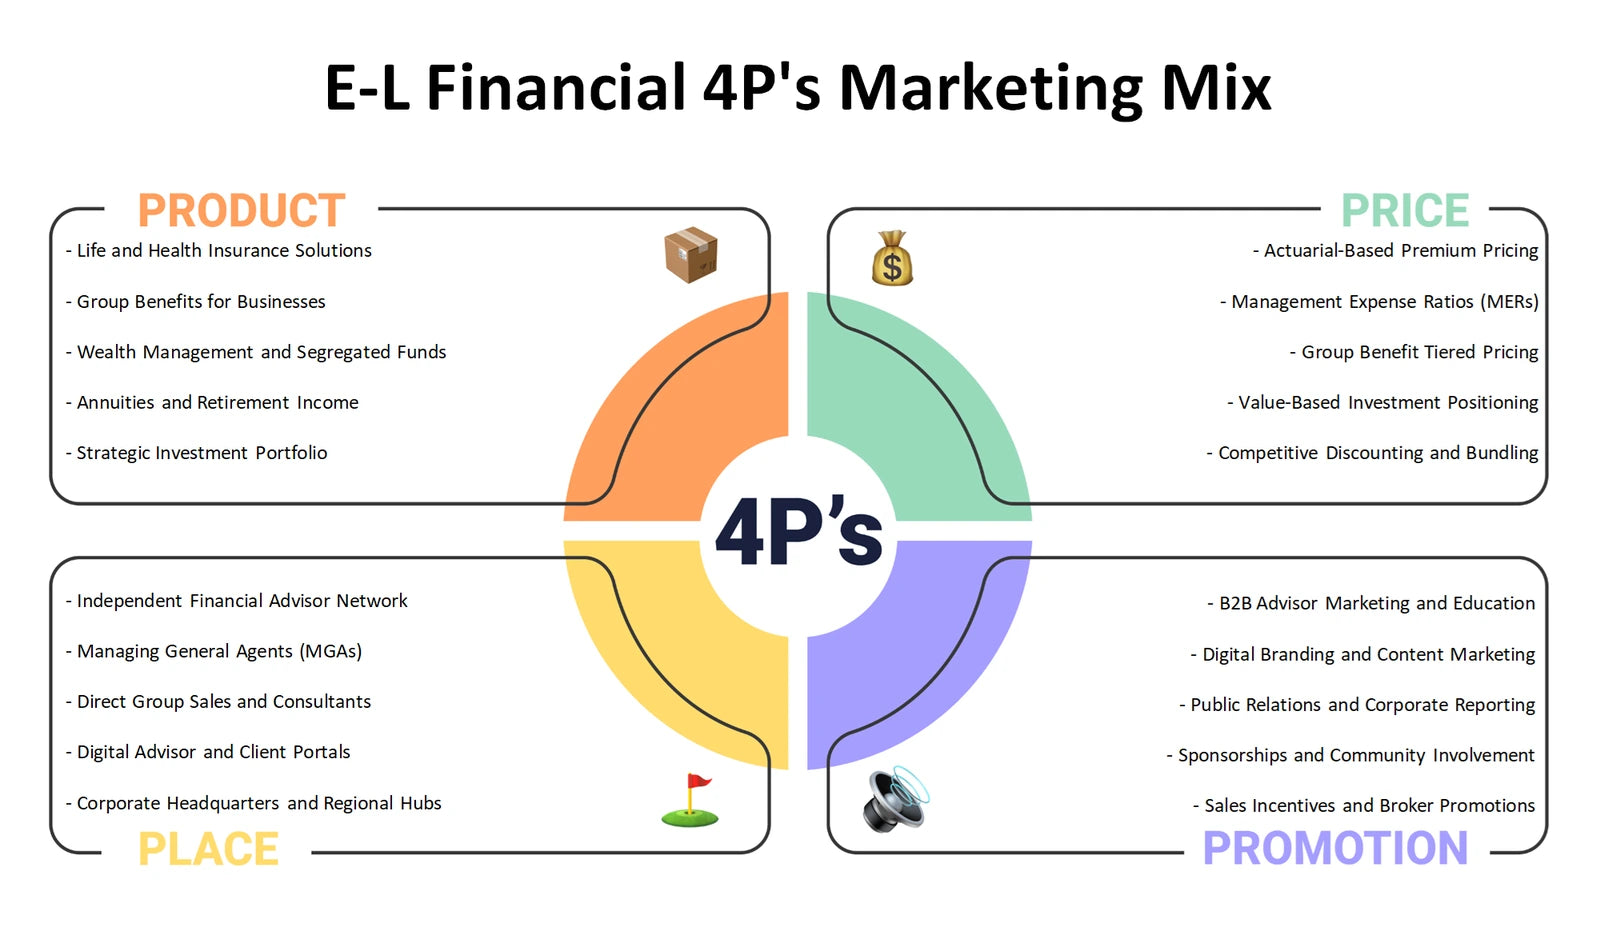
Marketing Mix (4Ps) summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should E-L Financial monitor because they could alter insurance demand, investment expectations or the cost of serving Canadians?
The E-L Financial PESTLE analysis, also commonly called PESTEL, organizes external influences that management cannot control but must interpret. Political factors can include public-policy priorities affecting financial protection, taxation or retirement planning. Economic conditions may influence household budgets, investment expectations and the valuation environment relevant to insurers. Social trends such as aging, health awareness and changing expectations for advice can reshape demand. Technological developments raise questions about digital onboarding, data use, adviser tools and cyber resilience. Legal factors include insurance supervision, market conduct, consumer disclosure and privacy obligations. Environmental conditions may affect claims patterns, investment considerations and operational resilience. The framework does not assume a particular law, rate or event has occurred; it makes those outside variables visible for structured monitoring.
- Signals to watch. Separate broad social and economic shifts from specific policy, regulatory or legal developments that require verification.
- Exposure pathways. Link each external factor to possible effects on demand, distribution, risk selection, claims, investments or compliance effort.
- Monitoring tool. Use the Excel framework to maintain factor-impact notes and use the Word analysis to develop the context behind material scenarios.
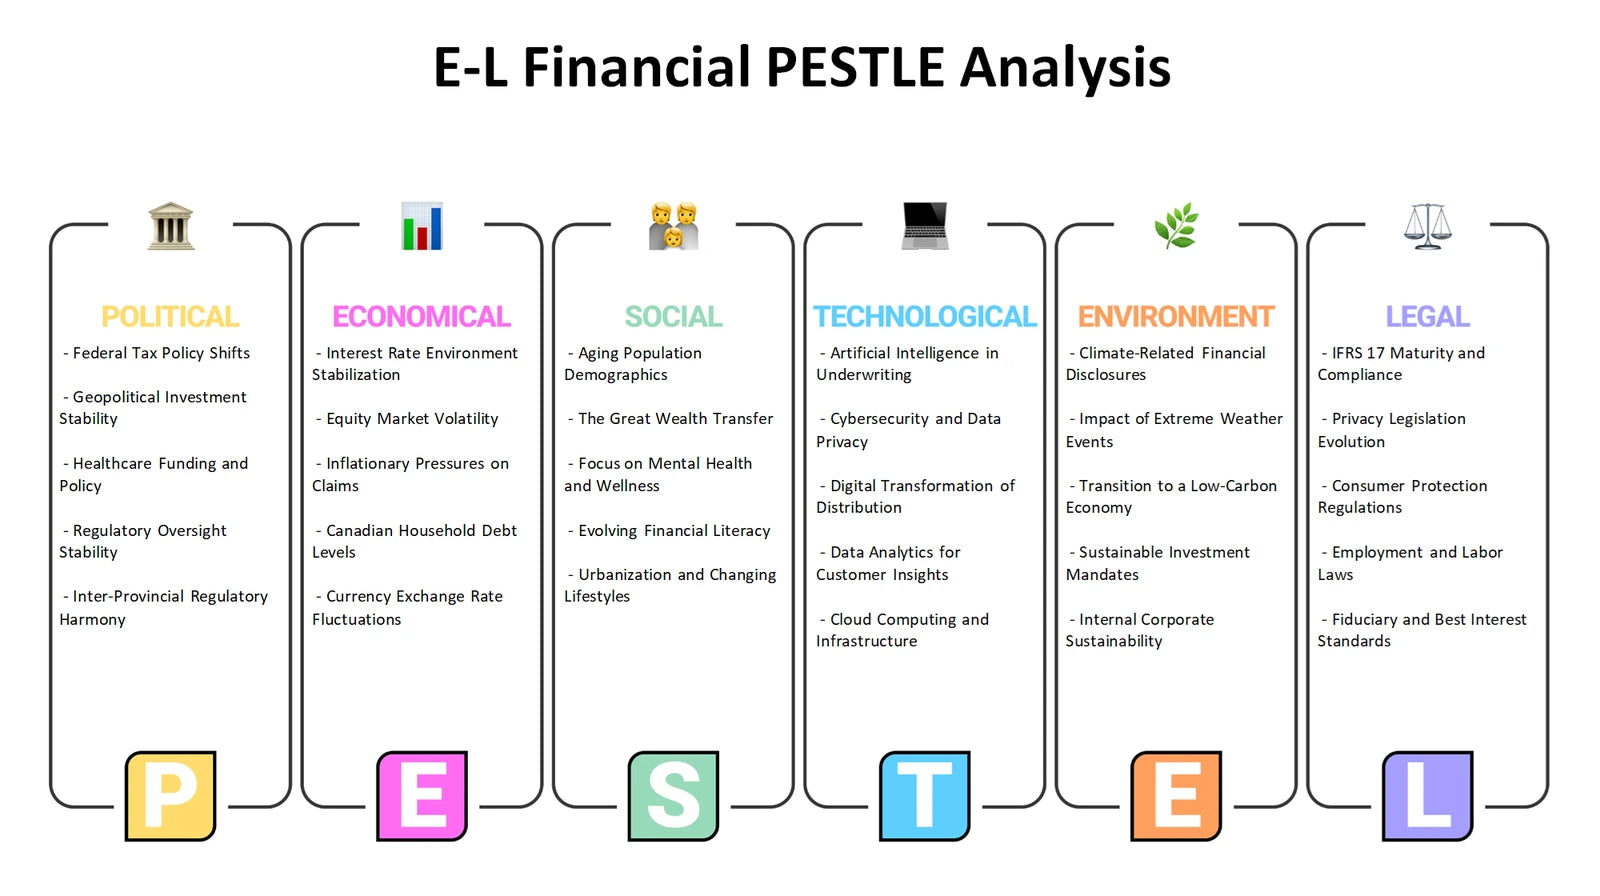
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can E-L Financial distinguish internal capabilities from external opportunities and threats when setting competitive priorities?
The E-L Financial SWOT analysis brings the earlier lenses together while keeping the categories accurate. Strengths and weaknesses are internal: the company can test whether its advisor and broker relationships, insurance expertise, operating capabilities, reinsurance access or product breadth are genuine advantages, and where reliance on intermediaries, complexity or execution capacity may create constraints. Opportunities and threats are external: evolving consumer needs, digital service expectations and underserved protection needs may be opportunities, while competitive alternatives, economic uncertainty, regulatory change and cyber risk can be threats. This distinction matters because an external trend is not automatically a strength, and a capability is not automatically an opportunity. SWOT is most useful when it forces a realistic match between what the business can do and what customers may choose.
- Internal evidence. Identify capabilities and limitations that can be supported by operating facts rather than broad promotional language.
- External fit. Compare potential market opportunities with competitive and regulatory threats before treating them as strategic priorities.
- Decision bridge. Use the Excel SWOT grid to prioritize relationships among factors, with the Word analysis supporting fuller explanations of implications and questions.
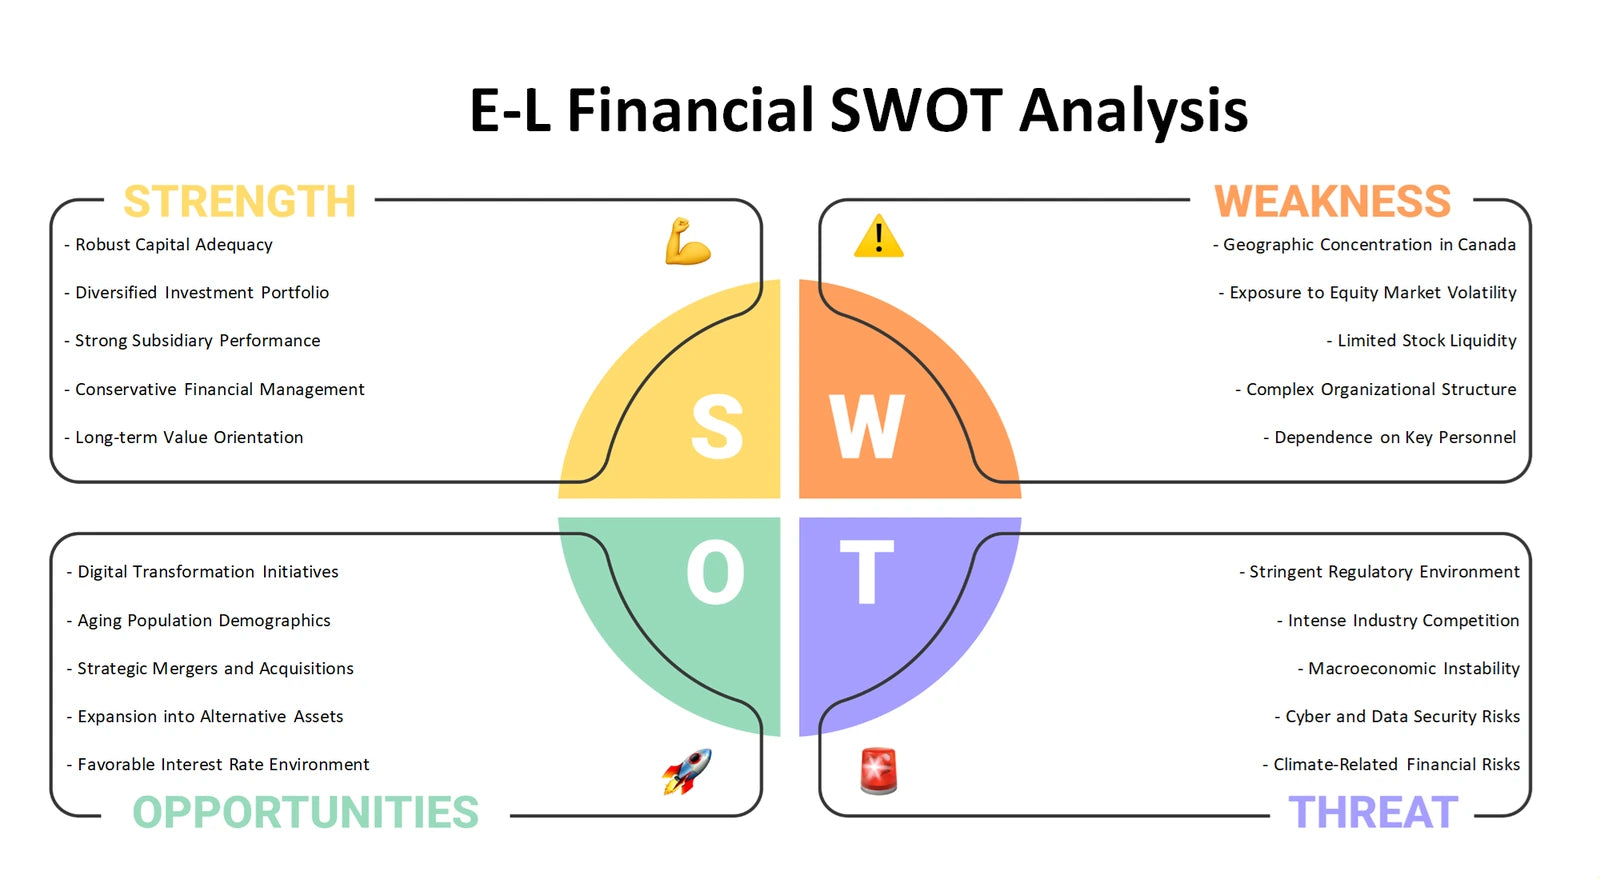
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more connected view of competitive choice
Used together, the six perspectives help turn E-L Financial’s adviser-led Canadian insurance and investment context into a coherent strategic discussion. The BCG Matrix considers portfolio attention; the Canvas maps value creation; Five Forces and PESTLE examine outside pressure; the 4Ps focuses on customer-facing choices; and SWOT connects internal capabilities with external conditions. The Excel frameworks and detailed Word analysis give customers a structured basis for comparing questions, documenting assumptions and developing company-specific strategic insight.
Company background: E-L Financial — supplied business-model context (product page).