

E-L Financial: Business Model, Competition and Customer Choice – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
E-L Financial Strategy Analysis Bundle
In this bundle, E-L Financial refers to E-L Financial Services Limited, the Canadian investment and insurance holding company, rather than another business with a similar name. Its insurance interests include The Empire Life Insurance Company, whose offerings include life insurance, investment and wealth-management products, and group benefits for Canadian customers and organizations.
The combination of long-duration insurance obligations and holding-company capital allocation makes economics central to the strategic questions. How should capital be compared across protection, wealth and investment activities? Which customer routes support durable value? The six connected analyses help organize those questions without treating analytical possibilities as established company findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Where should E-L Financial compare capital commitments when insurance, wealth and investment activities have different growth and cash profiles?
An E-L Financial BCG Matrix applies the discipline of relative market share and market growth to portfolio priorities. It can distinguish the questions associated with Stars, Cash Cows, Question Marks and Dogs without assigning any E-L Financial activity to a quadrant. For a holding company connected to a life insurer, the important issue is not growth alone: cash generation, regulatory capital needs, duration of liabilities and the ability to reinvest through cycles can materially change the value of a growth opportunity.
- Unit boundaries. Compare relevant products, distribution propositions or investment activities only after defining the market in which relative share would be meaningful.
- Capital discipline. Test whether a higher-growth area can justify its funding needs against mature activities that may contribute steadier cash flows.
- Portfolio worksheet. Use the Excel matrix to organize assumptions and use the Word analysis to document the market definition, evidence gaps and rationale behind each comparison.
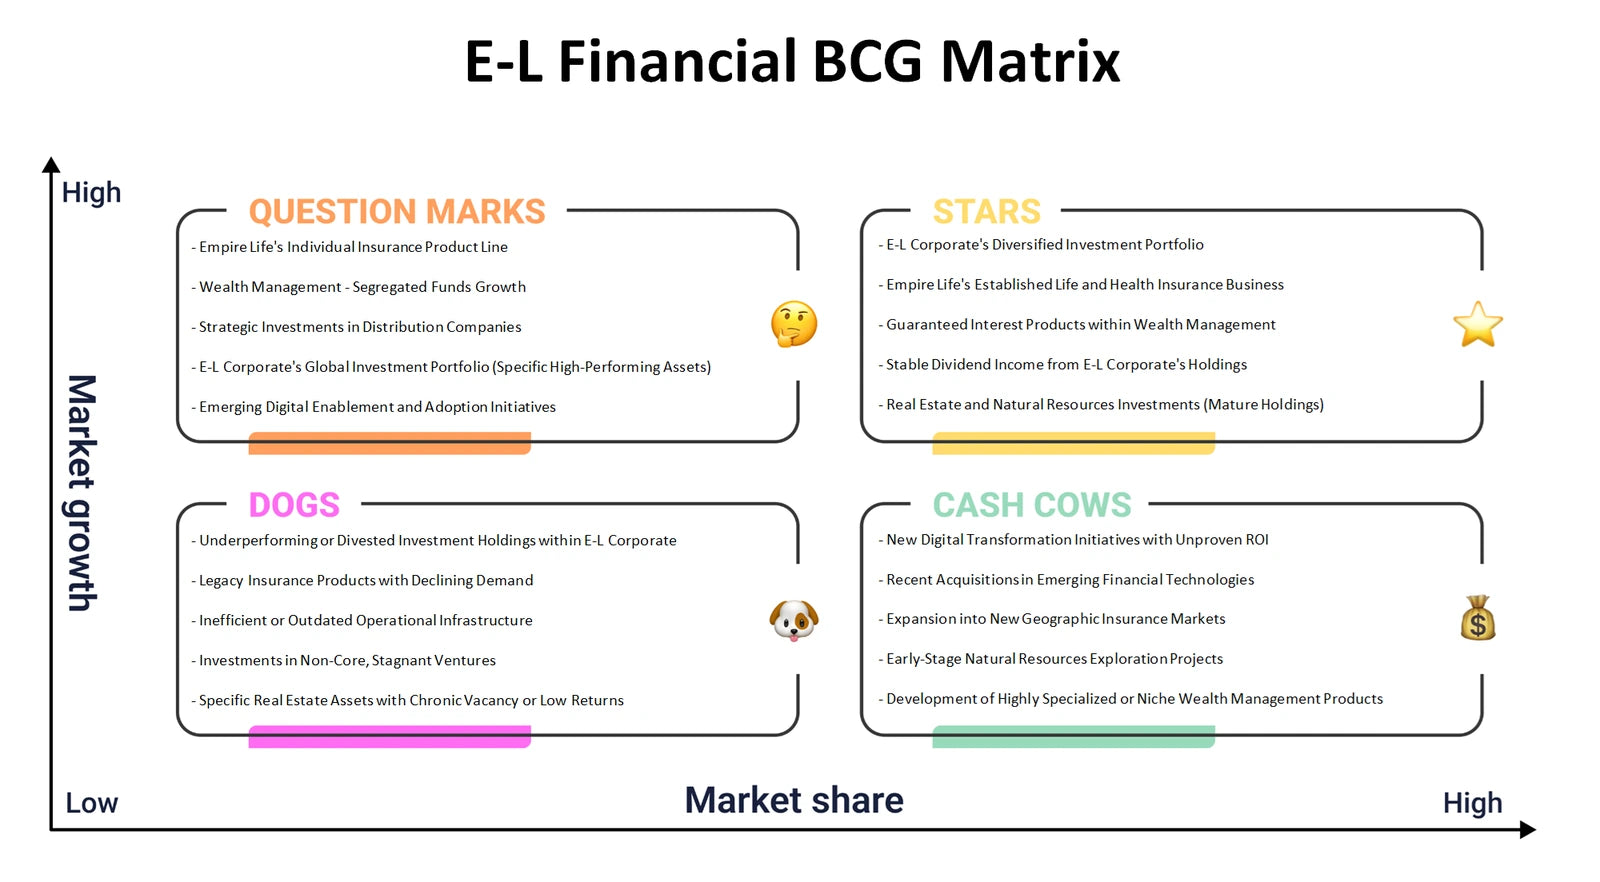
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer trust, underwriting, investment management and distribution fit together to create value for E-L Financial?
The E-L Financial Business Model Canvas examines the complete economic logic rather than viewing insurance products in isolation. It maps customer segments such as individual policyholders, wealth clients and group-benefit purchasers; the value propositions they seek; and the channels and customer relationships that support service. Revenue streams must be considered alongside key resources, key activities, key partnerships and cost structure. This is especially useful where premiums, fees, investment returns, claims obligations and distribution costs have different timing and risk characteristics.
- Value exchange. Explore how protection, savings or benefit needs connect to the reliability, advice and service customers may expect from a financial-services provider.
- Economic links. Trace how underwriting, asset-liability management, administration and distribution choices can affect revenues, expenses and risk-bearing capacity.
- Nine-block map. Populate the Excel canvas systematically, then use the Word analysis to add context on assumptions, interdependencies and questions requiring further validation.
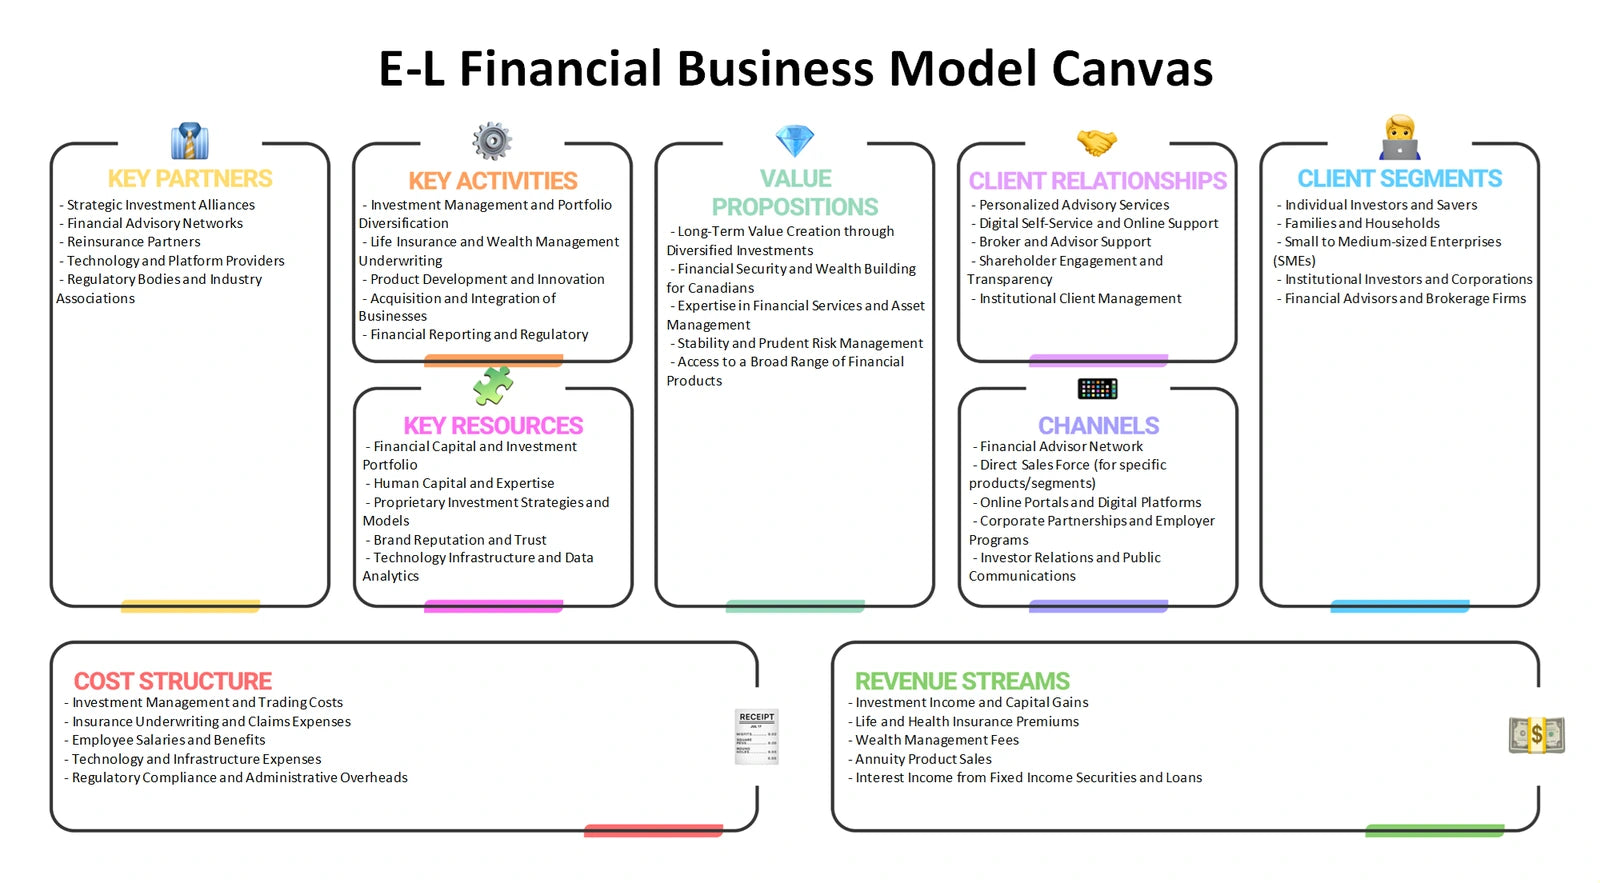
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Which industry pressures could most affect returns in Canadian life insurance, wealth products and related distribution?
E-L Financial Porter's Five Forces focuses on the market structure around its insurance and investment interests. Rivalry can reflect competing insurers and financial institutions seeking customer assets and protection business. Supplier power may arise through reinsurance capacity, specialist technology, distribution relationships and access to investment expertise. Buyer power differs between individual customers, advisers and organizational benefit purchasers. The framework also examines entry barriers created by capital, regulation and trust, alongside substitutes such as self-directed investing, workplace savings arrangements or alternative protection choices.
- Pressure points. Compare how capital requirements, scale, service quality and intermediary access can shape rivalry without assuming a force is automatically high or low.
- Substitution test. Separate direct product competition from alternative ways customers can address saving, investment, income-protection or benefit needs.
- Evidence trail. Structure each force in Excel and use the Word analysis to explain why a condition matters for margins, retention, risk transfer or distribution economics.
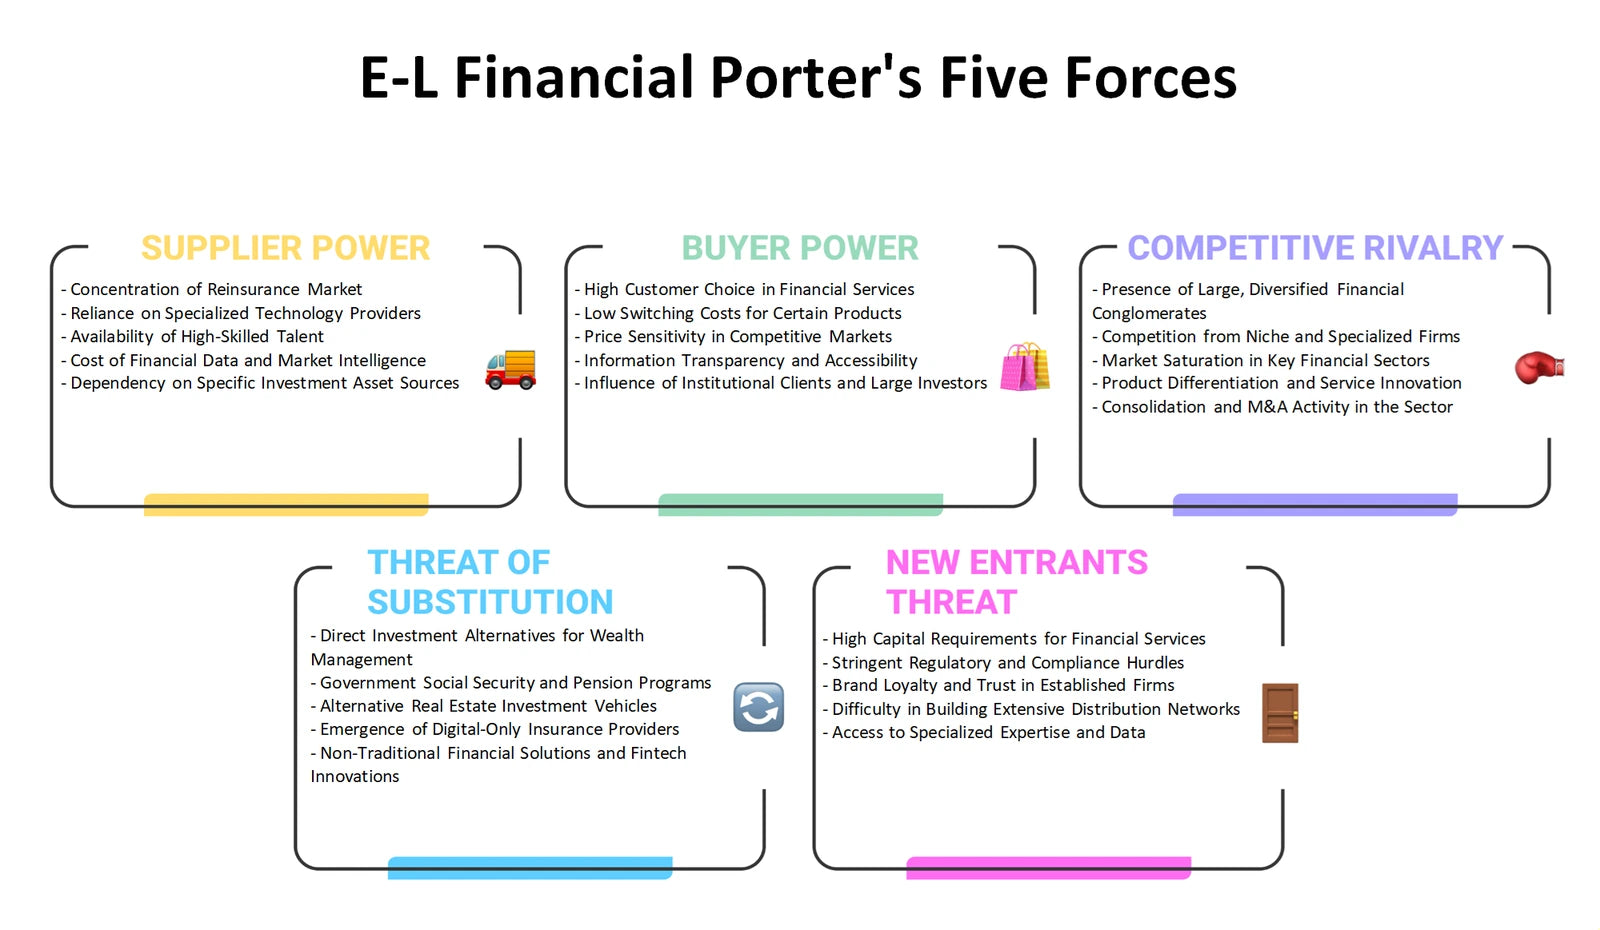
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, distribution and communication be assessed in a trust-based, regulated financial-services setting?
An E-L Financial Marketing Mix applies Product, Price, Place and Promotion to customer decisions that may unfold over many years. Product analysis can consider the fit among life insurance, investment or wealth propositions and group benefits. Price is broader than a headline amount: premiums, fees, guarantees, underwriting and risk selection affect both customer value and economics. Place considers adviser, employer, direct and service channels where relevant, while Promotion examines clear, compliant communication that helps customers understand complex financial choices.
- Product proposition. Examine which customer need a protection, savings or benefits offering is intended to address and what service experience supports it.
- Pricing and routes. Compare the trade-offs among affordability, risk-based pricing, distribution cost, adviser support and customer accessibility.
- Go-to-market review. Use the Excel framework to align the four Ps, then use the Word analysis to capture regulatory, customer-trust and commercial considerations behind the choices.
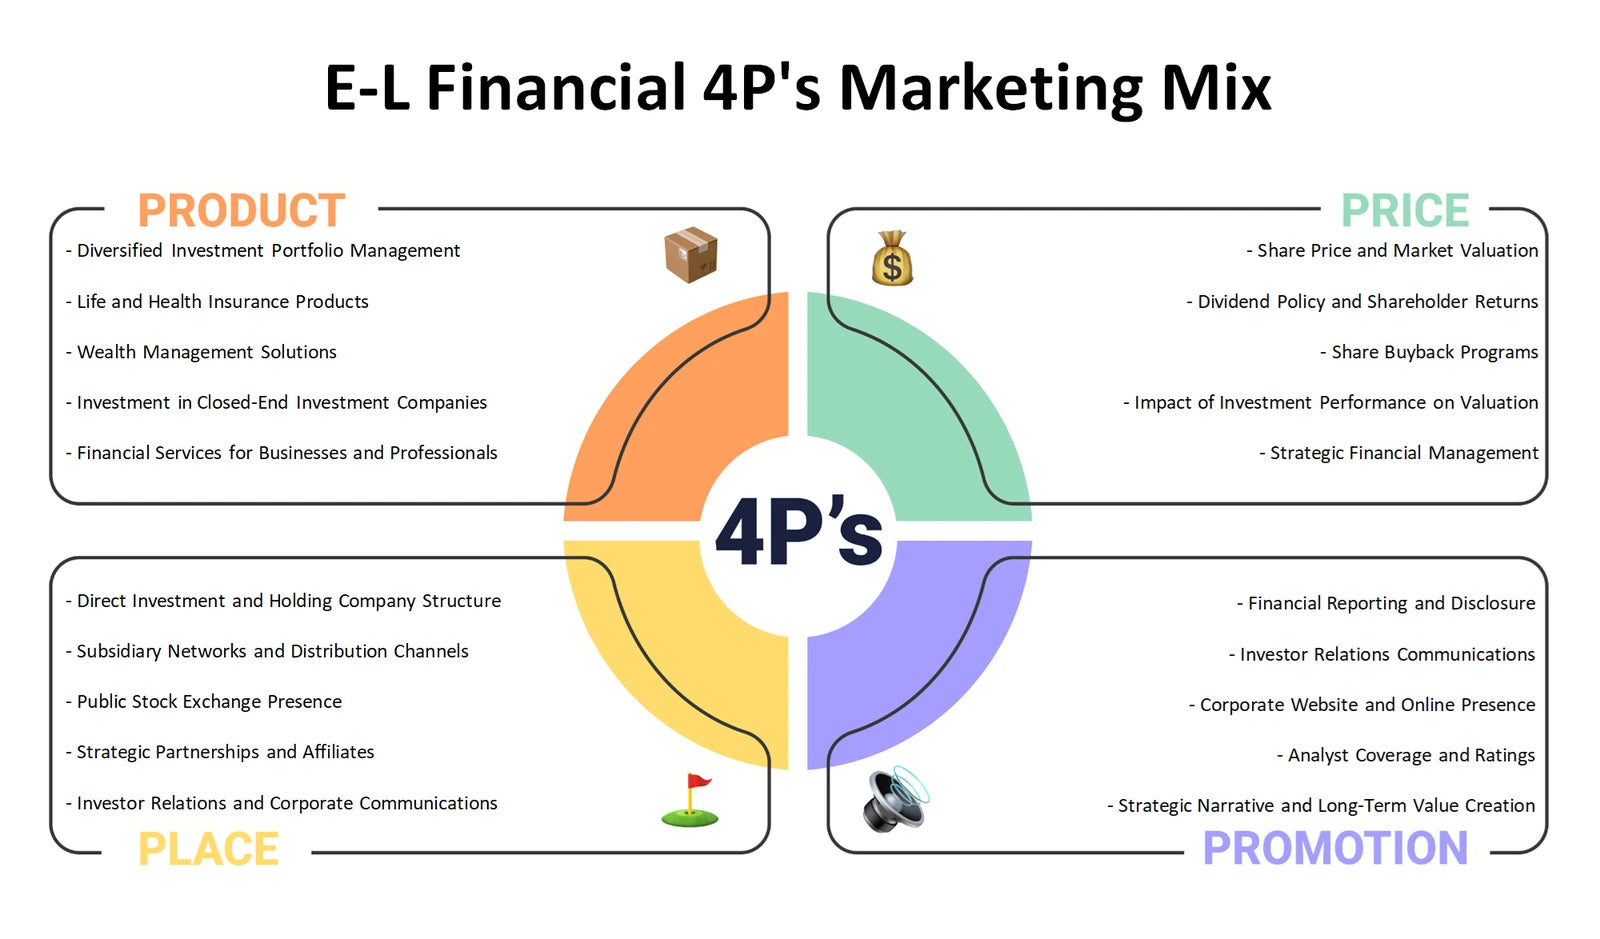
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes deserve attention when insurance liabilities and investment decisions extend across long time horizons?
An E-L Financial PESTLE analysis, also commonly called PESTEL, separates external conditions from internal capabilities. Political and legal factors include financial-services supervision, tax policy, consumer protection and privacy expectations. Economic questions include interest rates, credit conditions, inflation and investment-market volatility because they can affect both assets and long-duration obligations. Social trends such as longevity, household financial confidence and benefit expectations matter alongside technological demands for secure digital service. Environmental considerations can influence investment risk, catastrophe exposure and stakeholder scrutiny.
- External signals. Identify developments that could alter demand, claims patterns, costs, investment conditions or the compliance burden without presenting possible changes as confirmed events.
- Time horizons. Compare immediate operational effects with slower-moving demographic, climate and technology shifts that may influence long-term planning.
- Monitoring agenda. Use Excel to categorize and prioritize external issues, while the Word analysis helps record implications, uncertainties and questions for management review.
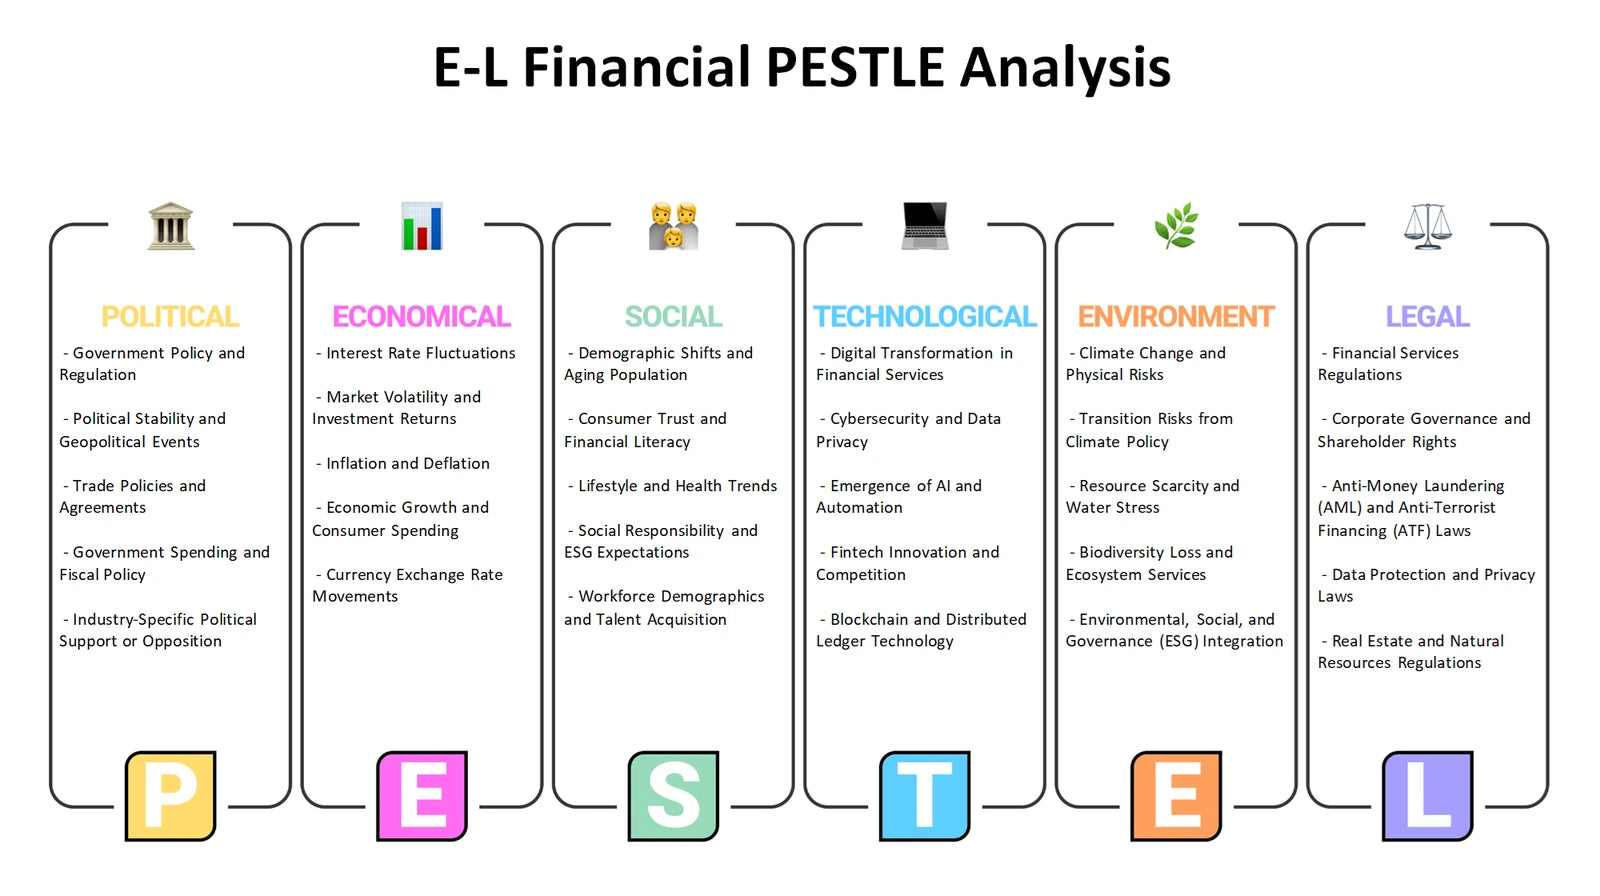
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can E-L Financial distinguish what it can influence internally from opportunities and threats created by its market environment?
An E-L Financial SWOT analysis brings the preceding lenses together while keeping classification disciplined. Strengths and weaknesses are internal: the holding-company structure, insurance expertise, capital allocation processes, distribution capabilities or operating complexity can be assessed as possible themes, not predetermined ratings. Opportunities and threats are external: demographic needs, technology change, market volatility, regulatory developments and competition belong outside the company. This distinction is useful when considering whether a perceived advantage is genuinely controllable or depends on conditions beyond management's control.
- Internal diagnosis. Test potential strengths and weaknesses against evidence about capabilities, resources, governance, customer access and execution constraints.
- External alignment. Relate opportunities and threats to the PESTLE and Five Forces observations instead of mixing outside market conditions into internal categories.
- Decision summary. Use the Excel SWOT grid to compare themes at a glance and the Word analysis to explain the evidence, trade-offs and strategic questions behind each entry.
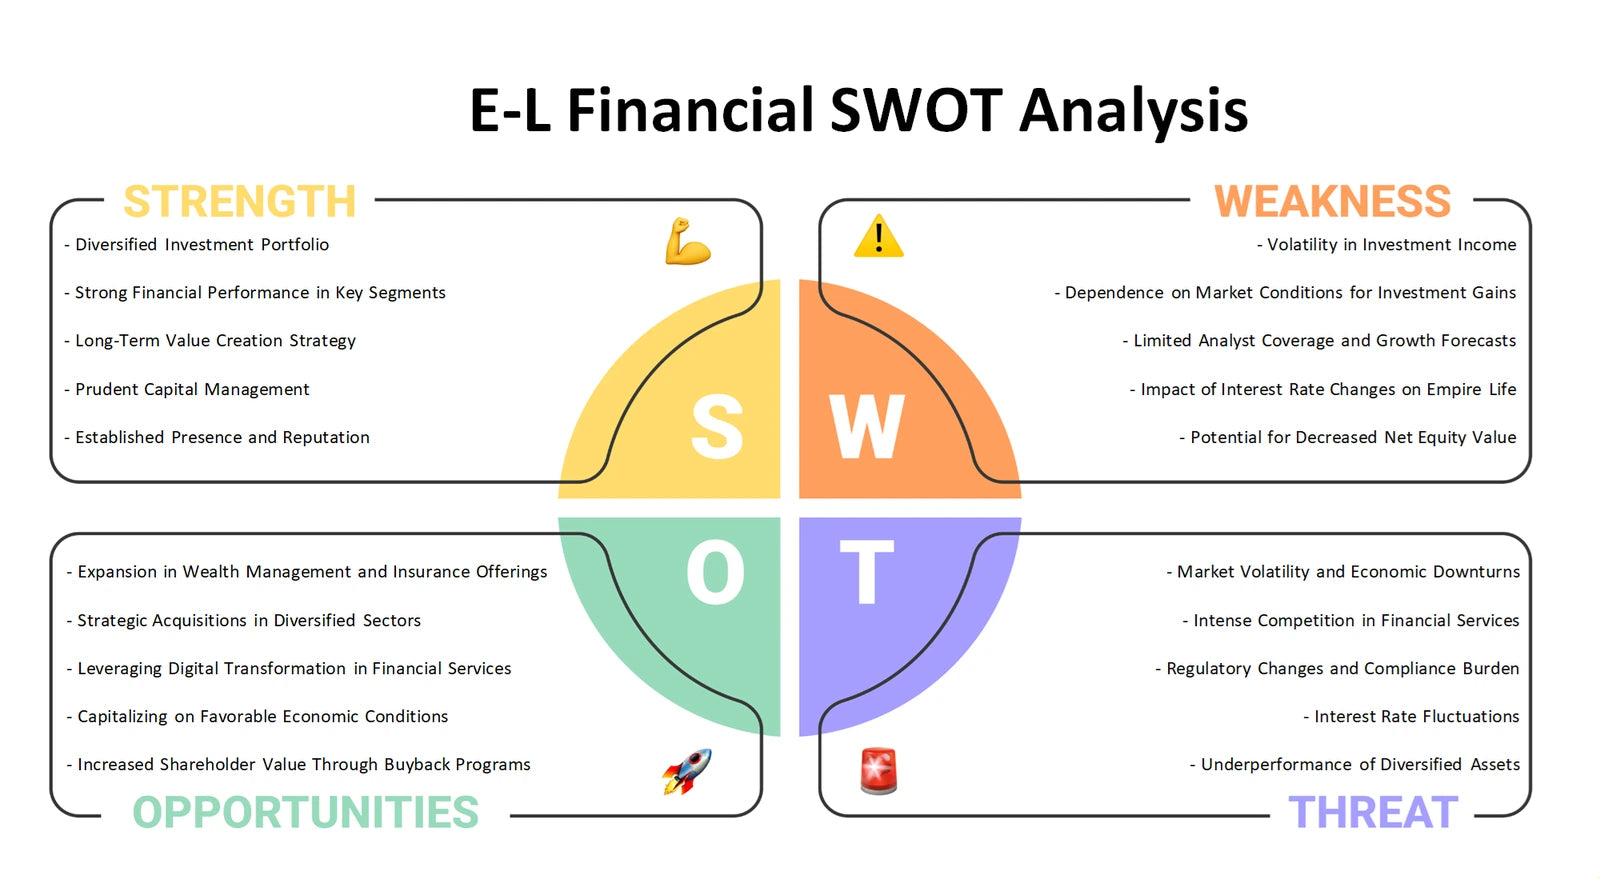
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices to the economics behind them
For E-L Financial, the six perspectives work best as a sequence: the Canvas clarifies value creation, Five Forces and PESTLE identify outside pressures, Marketing Mix examines customer delivery, BCG frames portfolio comparison, and SWOT consolidates internal and external themes. The Excel frameworks provide a structured place to develop those comparisons, while the detailed Word files support fuller interpretation of the company-specific questions, assumptions and strategic trade-offs.
Company background: E-L Financial — business-model context on Pestel-Analysis.com.