

China Life Insurance: Health Plans and Care Delivery, Customer Relationships – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
China Life Insurance Strategy Analysis Bundle
The supplied product context for China Life Insurance concerns a China-based life and health protection operating model: policyholders seeking insurance and retirement-related support, reached partly through commercial-bank relationships and supported by hospitals, clinics and health-management organizations. These relationships can affect distribution reach, service access and the design of health-related benefits. No particular same-name legal issuer, parent company or consolidated reporting scope is assumed in this description.
Rather than assume a portfolio ranking or financial conclusion, the six lenses turn this operating context into practical questions: which propositions deserve scarce capital, how bank and care partners affect economics, and which external developments could reshape demand or compliance. The Excel frameworks support structured comparison, while the Word files provide detailed company analysis for interpretation and discussion.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which health, life or retirement-protection propositions should receive attention when market growth and relative market share point in different directions?
A China Life Insurance BCG Matrix helps separate portfolio questions from broad statements about insurance demand. It can compare defined business units, customer propositions or distribution-led offerings using market growth and relative market share. The purpose is not to assign an unverified quadrant, but to test whether a potential Star, Cash Cow, Question Mark or Dog has an appropriate role in capital allocation, product investment and management attention. This is particularly useful where health services, retirement needs and bank-led acquisition may create different growth profiles and operating demands.
- Define the unit. Compare like-for-like propositions or channels so that relative share and market-growth observations are meaningful rather than blended across unrelated insurance needs.
- Test resource priorities. Consider whether customer acquisition, service capability, retention effort or disciplined harvesting would fit each possible portfolio position.
- Build a portfolio view. Use the Excel framework to organise the comparison, then use the Word analysis to document assumptions, evidence gaps and discussion points.
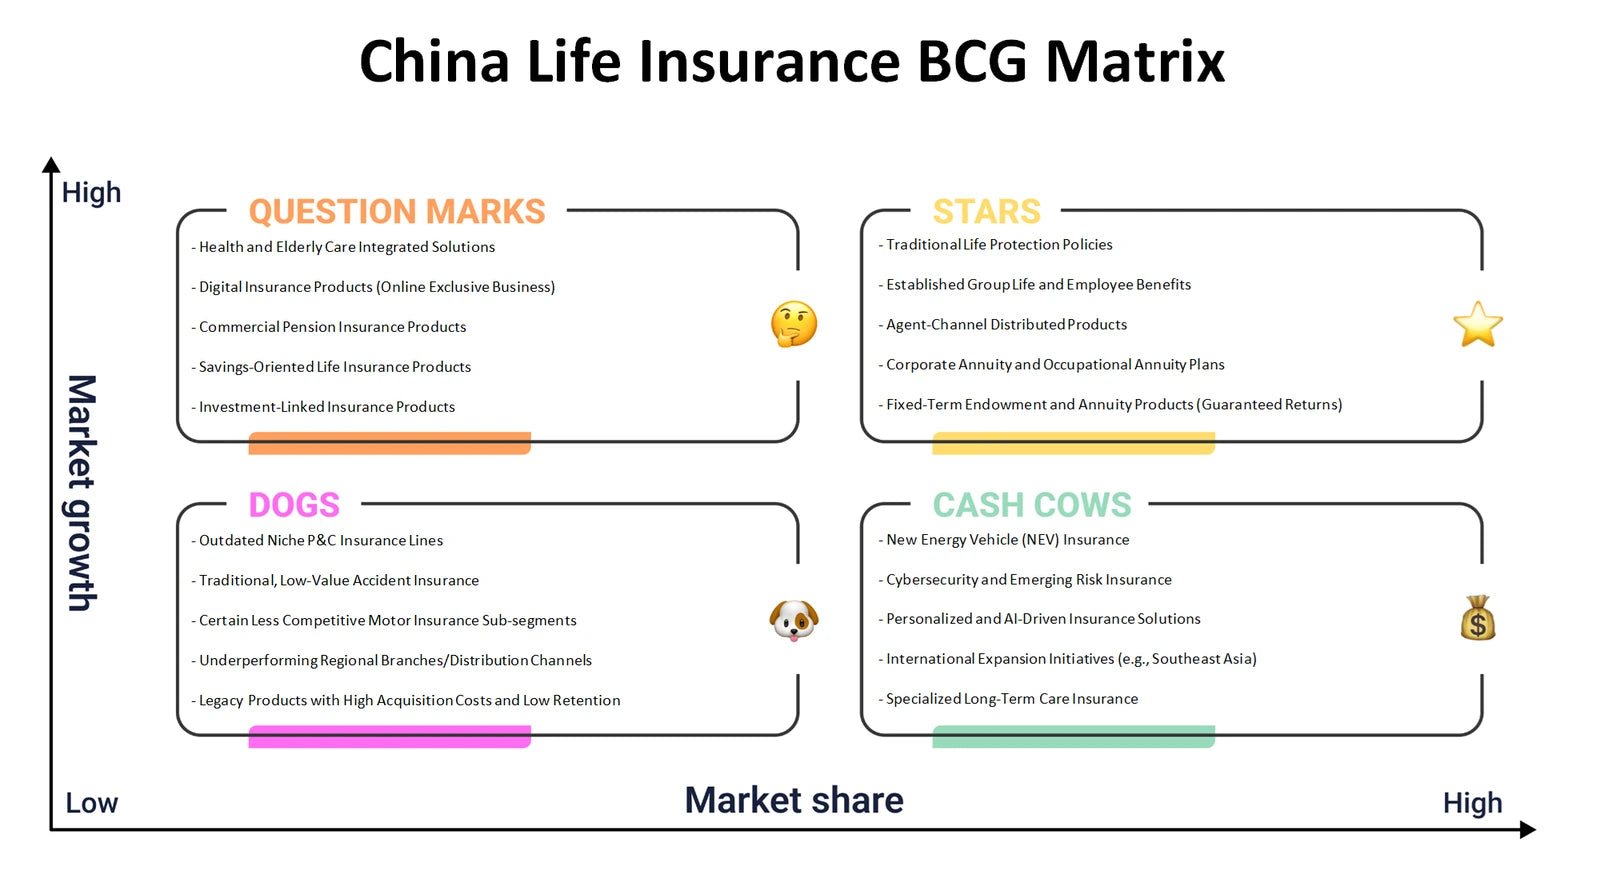
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How can insurance protection, care-service relationships and institutional distribution work together to create value and sustainable economics?
The China Life Insurance Business Model Canvas examines the links between customer segments, value propositions, channels and customer relationships. In the supplied context, policyholders may value protection, service access and retirement support, while commercial-bank relationships and care-provider links may shape how those benefits are reached and delivered. The canvas also connects revenue streams to key resources, key activities, key partnerships and cost structure. That full nine-block view helps examine where value is created, where coordination is essential and where economics may be sensitive to distribution, service or administration choices.
- Trace the value chain. Connect customer needs and protection propositions with bank channels, care relationships and the ongoing policyholder experience.
- Expose economic links. Review how premiums and other possible revenue streams relate to underwriting, service delivery, partner management, technology and operating costs.
- Join map and narrative. Complete relationships among the nine blocks in Excel, then use the detailed Word analysis to explain the logic behind the mapped model.
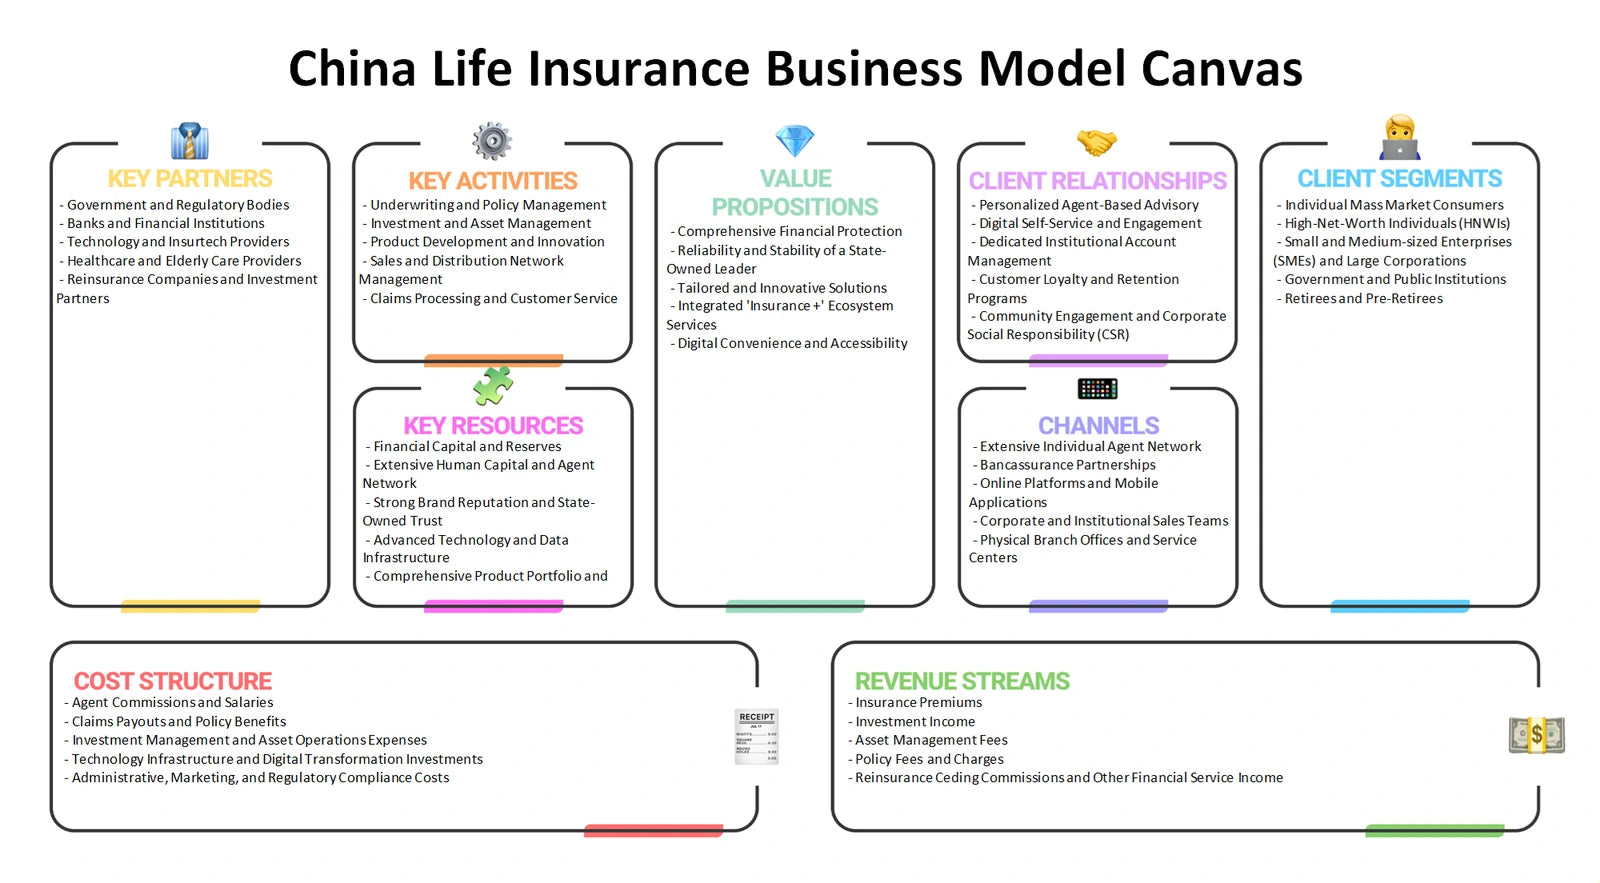
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures could influence the attractiveness of the life, health and retirement-protection markets addressed by this operating context?
China Life Insurance Porter's Five Forces provides a disciplined way to examine industry pressure without claiming a force score. Rivalry asks how strongly insurers compete for comparable protection needs and distribution access. Buyer power considers policyholder choice, affordability and trust; supplier power can include healthcare-service relationships, distribution partners and specialised operating inputs. The threat of new entrants tests barriers such as capital, regulation, brand confidence and operating capability. Substitutes extend beyond direct insurers to alternative ways households meet protection, savings, retirement or health-service needs.
- Separate the forces. Assess rivalry, buyer power, supplier power, new-entry risk and substitutes as distinct drivers rather than treating competition as one issue.
- Focus on leverage points. Consider how bank distribution and provider relationships may alter bargaining positions, switching conditions or service differentiation.
- Record the evidence. Use the Excel structure to compare force drivers and use the Word analysis to capture rationale, uncertainties and strategic implications.
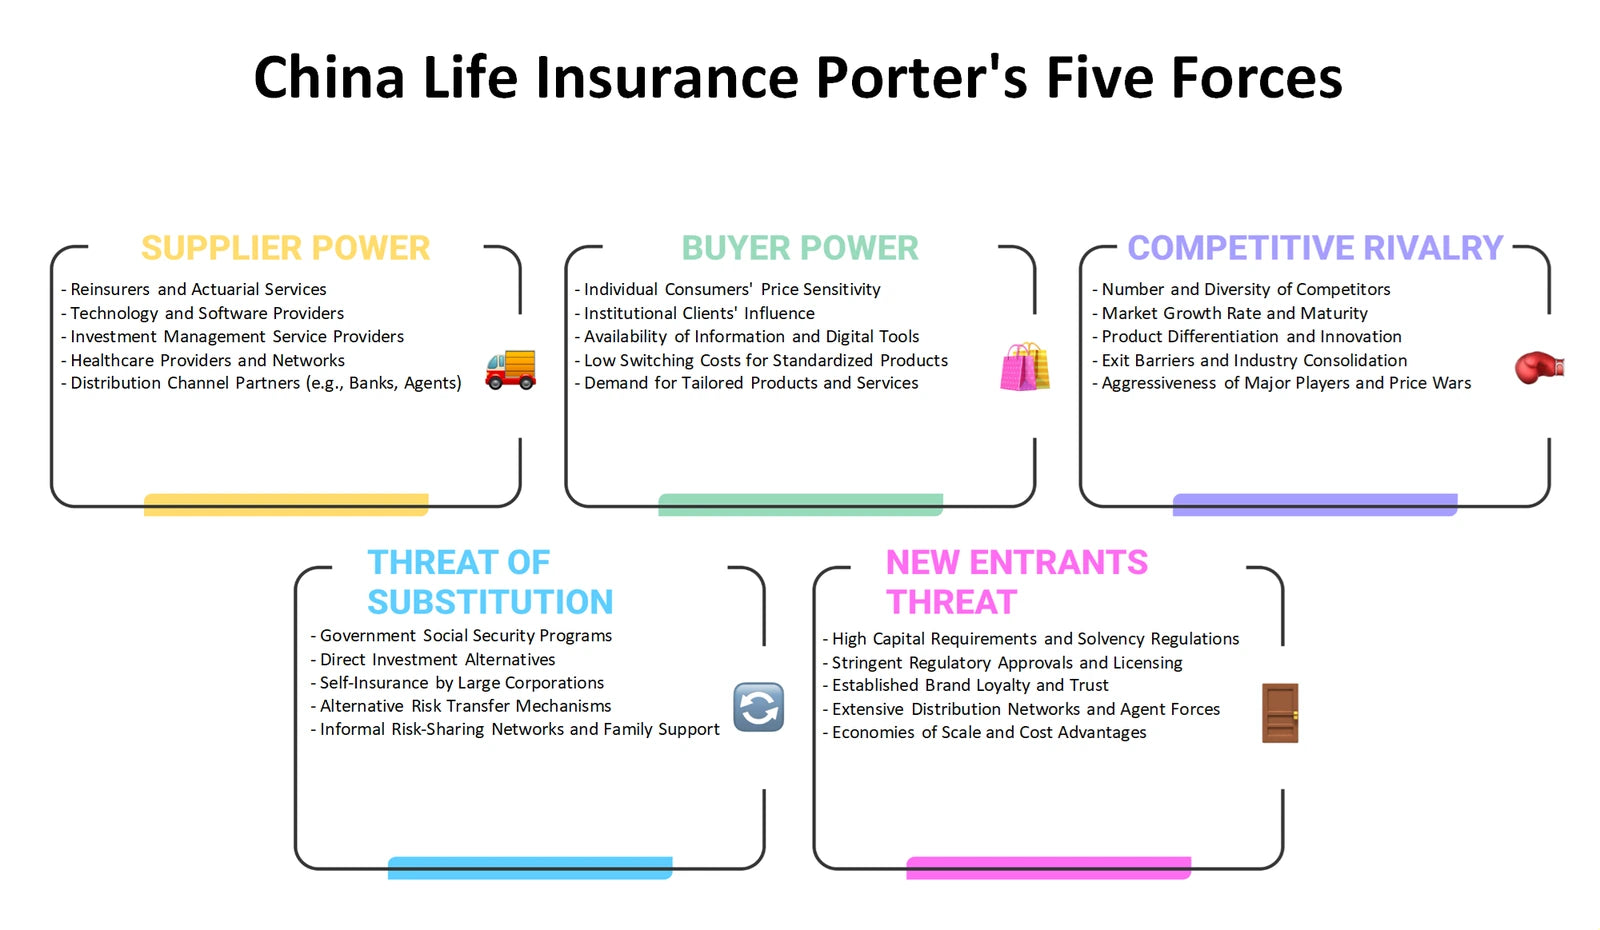
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should a protection proposition be presented, priced, distributed and communicated when customers need trust as well as understandable coverage?
The China Life Insurance Marketing Mix considers Product, Price, Place and Promotion in a regulated insurance setting. Product analysis can distinguish core cover from health-related service features and retirement-support needs. Price is not merely a headline premium: it can be assessed through affordability, benefit design, risk selection and the clarity of terms. Place examines routes such as commercial-bank relationships alongside other suitable customer-access and servicing paths. Promotion focuses on compliant, credible education that helps customers understand protection rather than assuming a particular campaign or channel share.
- Clarify the offer. Examine which protection, health-service and retirement-related elements are meaningful to defined customer groups and life stages.
- Align access and trust. Compare the customer experience created by bank-led distribution, policy servicing and clear communications across the purchase journey.
- Turn observations into choices. Use the Excel framework to organise the four Ps, then use the Word analysis to develop a coherent customer and channel narrative.
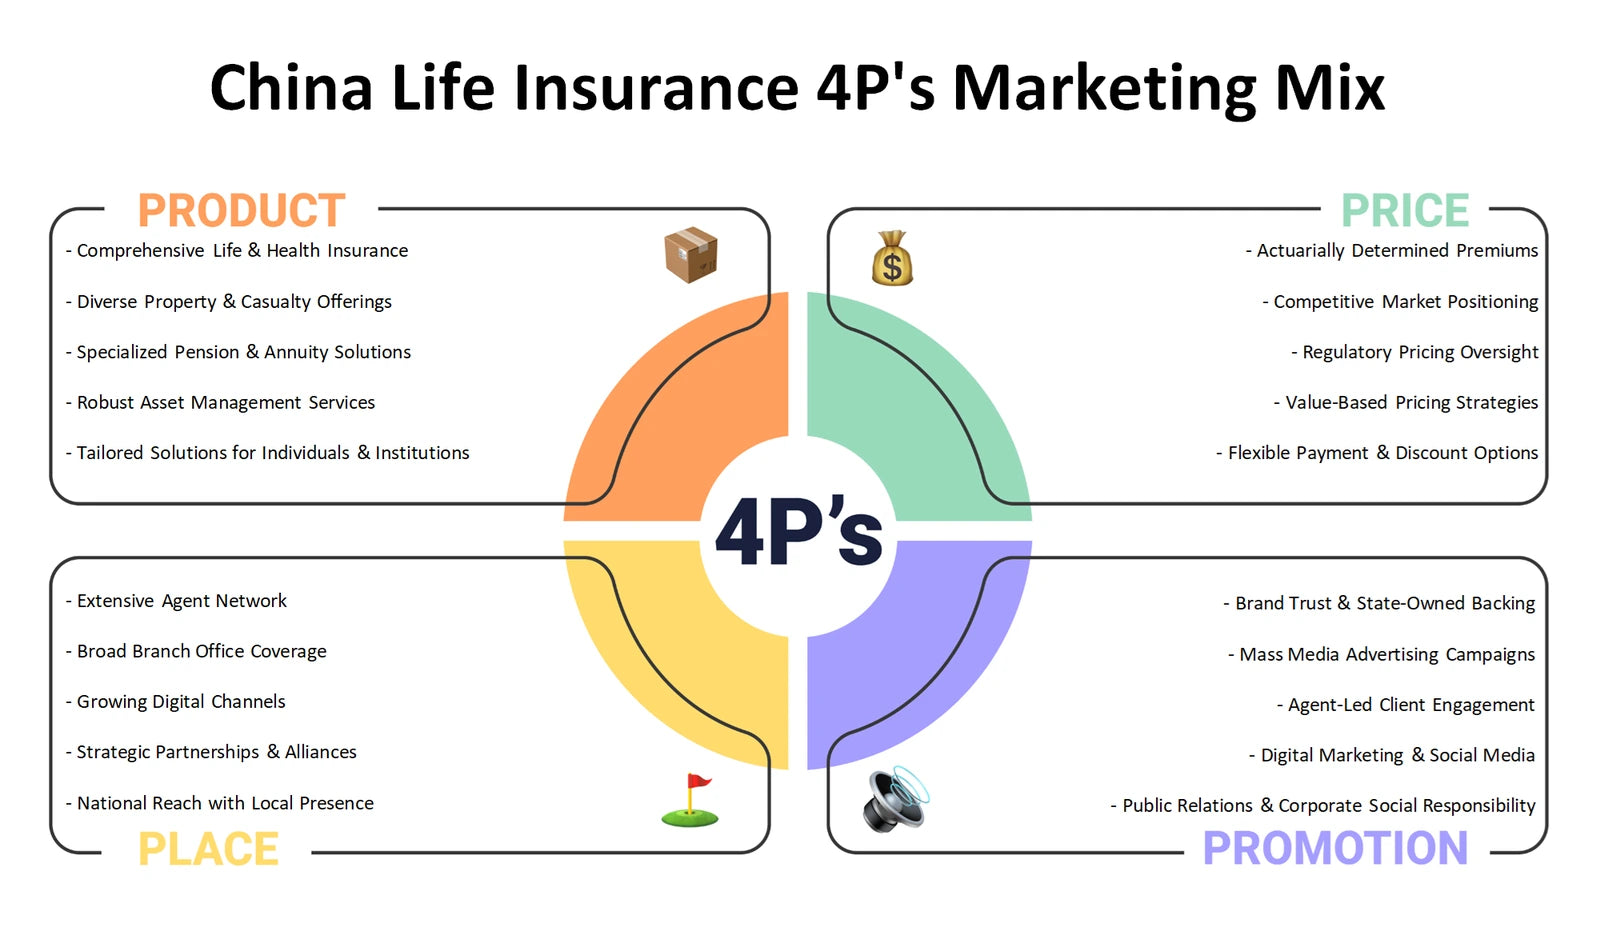
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter protection demand, service partnerships and operating constraints in the China-based insurance context described for this product?
A China Life Insurance PESTLE analysis, also commonly called PESTEL, keeps external influences separate from internal capabilities. Political questions can include policy direction affecting insurance and social protection. Economic conditions may affect household budgets, investment conditions and demand for long-duration protection. Social trends include ageing and changing health expectations; technological change may reshape service, data use and distribution. Legal factors cover areas such as consumer protection, privacy and insurance oversight, while environmental conditions can affect health risks, claims patterns and resilience expectations. These are analytical categories, not claims that a particular policy or rate has changed.
- Scan connected drivers. Consider how demographic change, household confidence, care expectations and digital service development could interact rather than move independently.
- Separate policy from fact. Identify questions about regulation, consumer safeguards and data governance without treating possible future changes as established events.
- Prioritise monitoring. Use Excel to sort external developments by relevance and uncertainty, with the Word analysis supporting deeper context for management review.
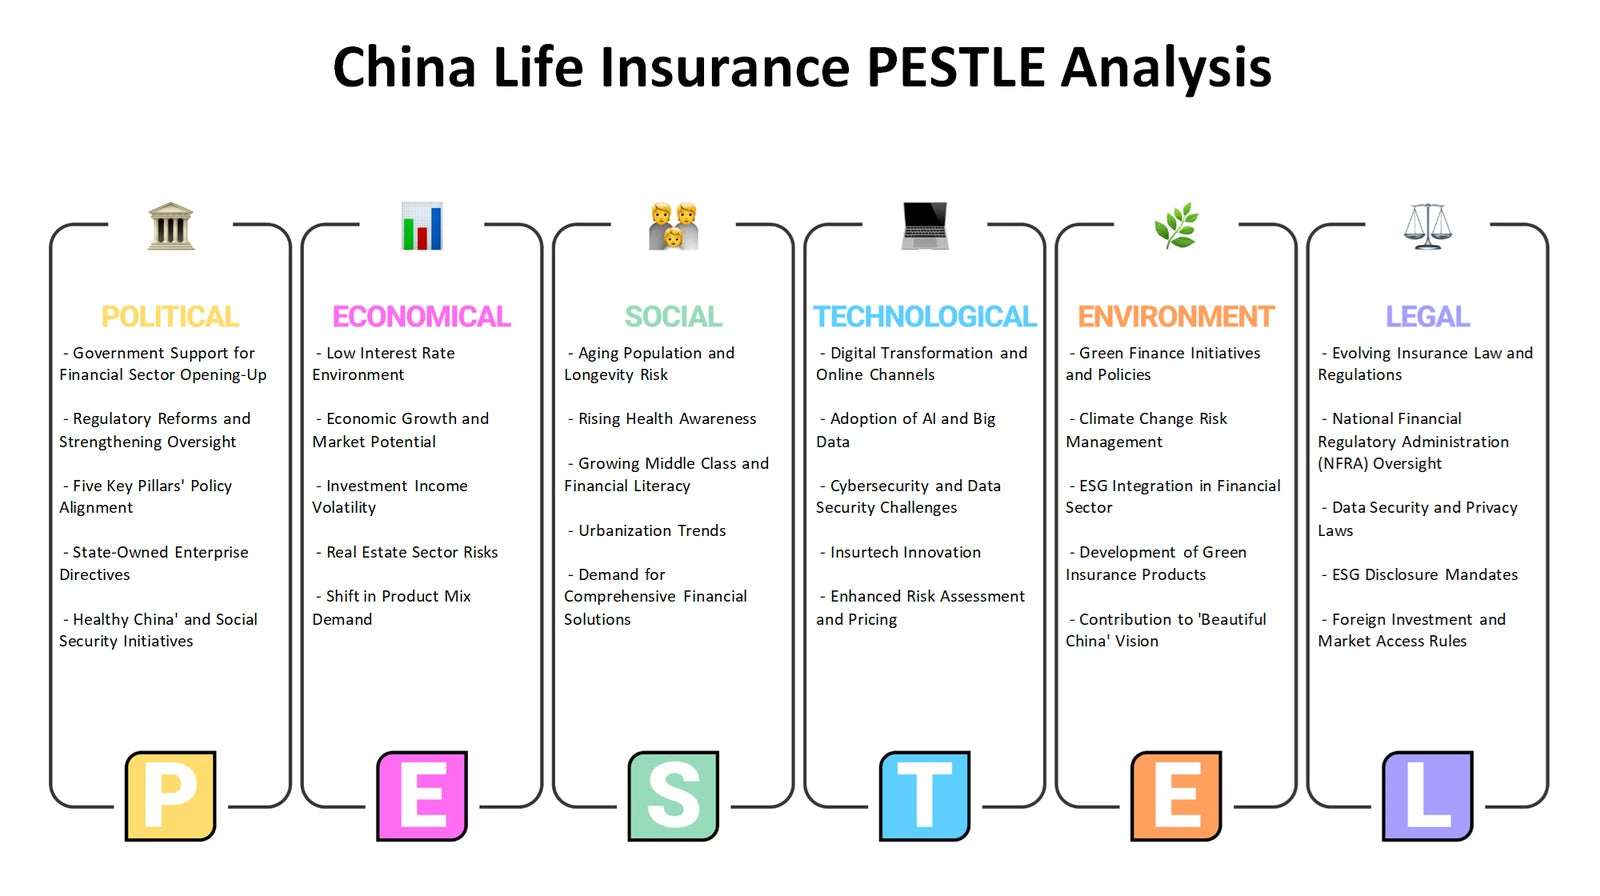
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal partnership, service and operating capabilities be considered alongside external health and retirement-protection opportunities and risks?
The China Life Insurance SWOT analysis distinguishes internal strengths and weaknesses from external opportunities and threats. Potential strengths to examine may include the ability to coordinate distribution and health-service relationships; possible weaknesses may involve operational complexity, partner dependence or inconsistent customer experiences. Opportunities and threats belong outside the organisation: ageing-related protection needs, changing customer expectations, competitive intensity, technology shifts and regulatory developments may all be relevant topics. The framework is useful because it prevents a plausible market trend from being labelled an internal strength, or an operational constraint from being mistaken for an external threat.
- Classify carefully. Test whether each point is genuinely internal and controllable, or external and shaped by market, policy or customer conditions.
- Link paired issues. Explore how a capability in distribution or care coordination could support an opportunity, or where a constraint could amplify an external threat.
- Create an action-oriented record. Use the Excel matrix to organise the four categories and the Word analysis to explain priority pairings and follow-up questions.
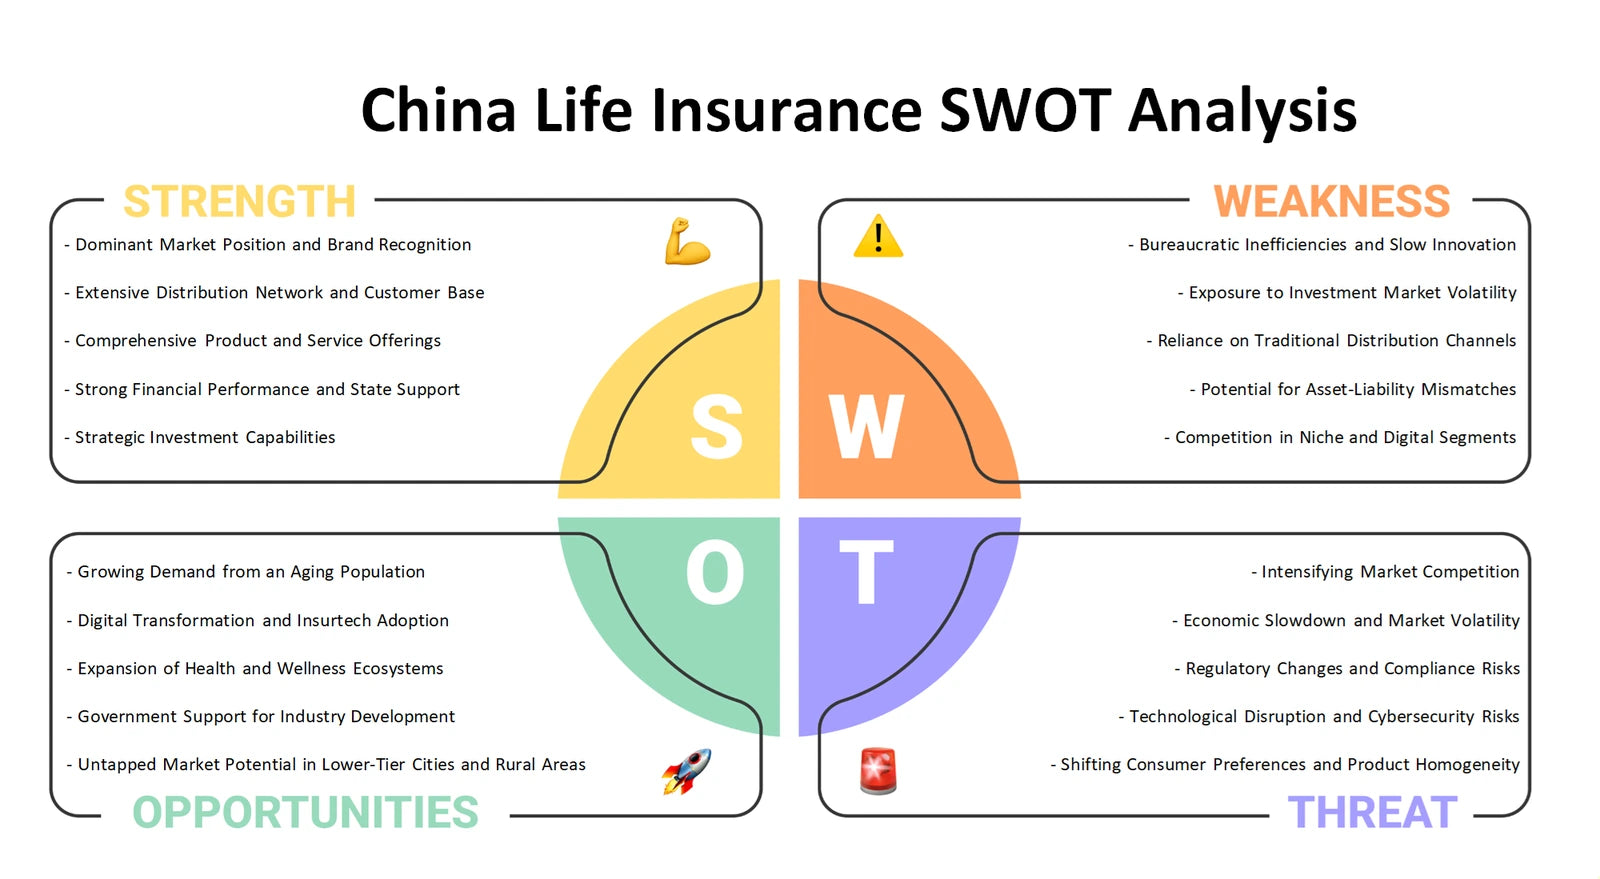
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Turn connected insurance questions into a usable workplan
Together, the six perspectives move from portfolio choices and business-model logic to industry pressure, customer-market decisions, external change and strategic fit. For the China Life Insurance operating context described here, the Excel and Word materials can help structure a more disciplined discussion of protection needs, distribution relationships, health-service coordination and long-term priorities without presenting unverified conclusions as facts.
Company background: China Life Insurance — supplied Business Model Canvas product-context page.