

Direct Line Group Plc: Distribution and Brand Positioning – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Direct Line Group Plc Strategy Analysis Bundle
This bundle is focused on the insurance business described for Direct Line Group Plc in the supplied product context: a primary insurer using direct, partner and embedded routes to reach customers seeking protection for personal risks and larger-loss exposures. Reinsurance, affinity relationships and distribution partners are relevant because insurance value depends on risk selection, claims capability, capital capacity and accessible customer journeys.
The available context highlights relationships with reinsurers, automotive and retail partners, banks and other channel organisations. That makes portfolio choices, channel economics and external regulation practical questions rather than assumptions. The Excel frameworks and detailed Word analysis help organise those questions across six connected strategic lenses without presenting unverified conclusions as company facts.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance products or distribution propositions deserve capital, marketing attention and operational capacity when growth prospects differ?
The Direct Line Group Plc BCG Matrix provides a disciplined way to compare a portfolio using market growth and relative market share, rather than treating every policy line or partner proposition alike. It can test whether established insurance activities resemble potential Cash Cows, whether faster-moving opportunities could merit Star-level investment, and where Question Marks or Dogs require closer scrutiny. Those labels are analytical categories, not claims about any current product. For an insurer, the comparison should also be read alongside loss experience, capital usage, claims complexity and the ability to distribute responsibly through direct or partner channels.
- Portfolio boundaries. Separate products, customer propositions or channel-led offers clearly enough to compare their markets and competitive positions.
- Capital trade-offs. Consider how reinsurance support and retained risk may affect the resources available for growth-oriented versus mature activities.
- Structured comparison. Use the Excel framework to map evidence consistently, then use the Word analysis to interpret assumptions, definitions and portfolio implications.
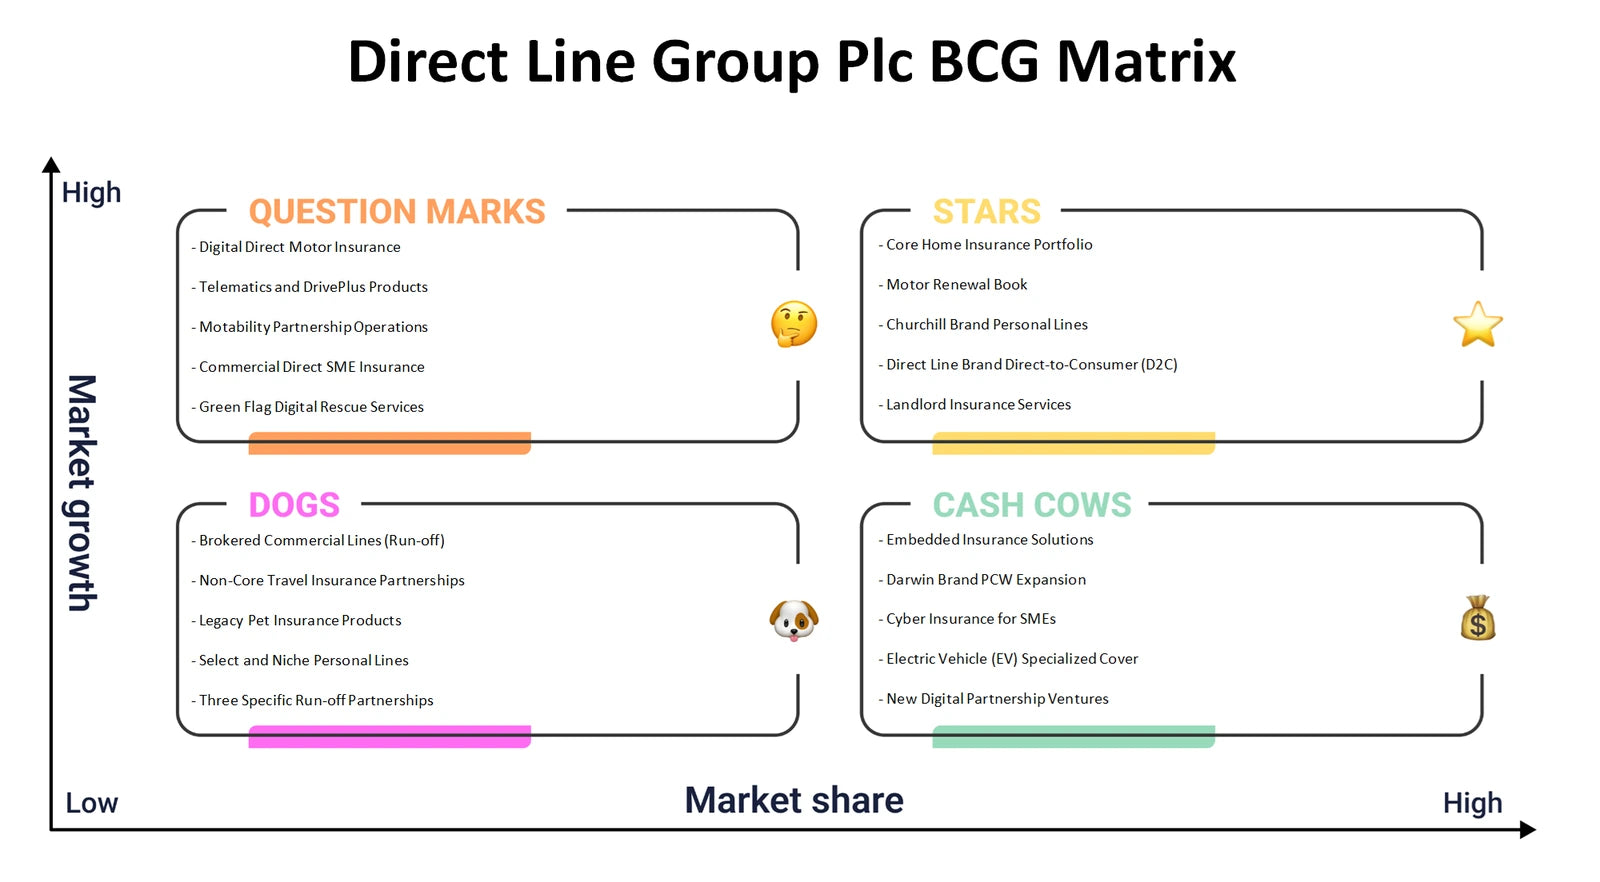
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer access, underwriting capacity, claims delivery and partner relationships fit into one insurance value-creation model?
The Direct Line Group Plc Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It helps examine how policyholders may value accessible cover and dependable claims handling; how direct, affinity, co-branded or embedded channels reach them; and how premium income must support claims, servicing, acquisition and risk-transfer costs. Reinsurers can be considered as key partnerships that shape capacity and volatility, while data, underwriting expertise, brand trust and claims operations can be assessed as possible resources and activities. The purpose is to expose dependencies between a customer promise and the economics required to sustain it.
- Value-to-economics link. Trace how a proposition for an insurance customer connects to premium revenue, claims obligations and servicing expenditure.
- Partner architecture. Examine where manufacturers, dealers, banks, retailers and reinsurers may add reach, data, capacity or operational dependencies.
- Model coherence. Populate the Excel Canvas block by block and use the Word analysis to explore the relationships and tensions between the nine elements.
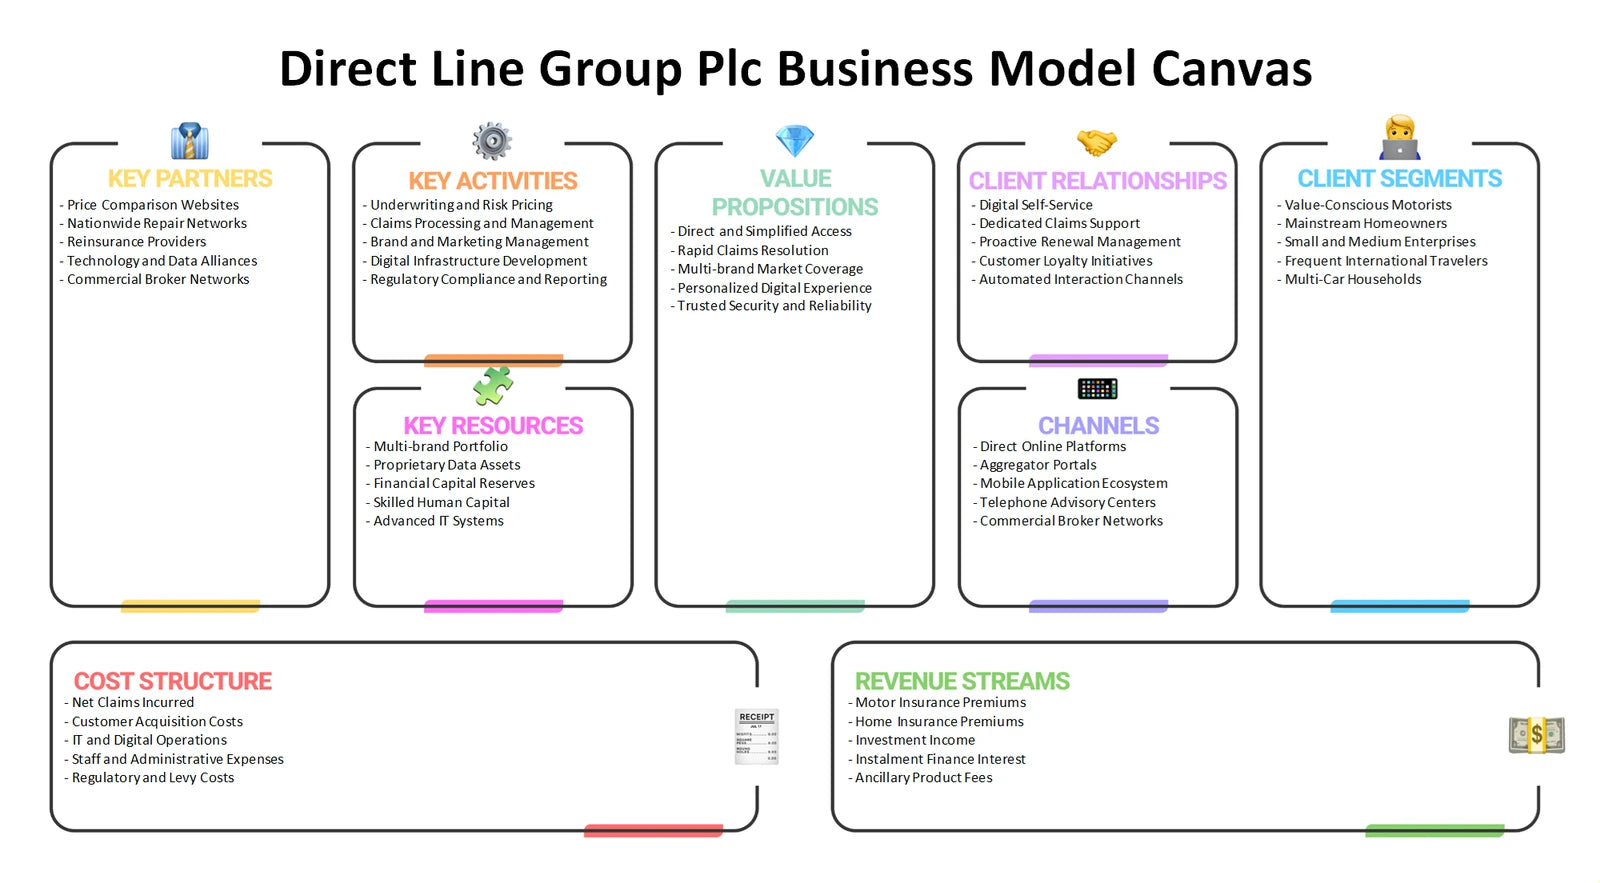
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can influence underwriting discipline, customer retention and the economics of insurance distribution?
Direct Line Group Plc Porter's Five Forces frames competition beyond a simple list of insurance rivals. Rivalry can be explored through pricing transparency, renewal behaviour, service quality and the ability to differentiate claims experiences. Supplier power is particularly relevant where reinsurers, repair networks, technology providers, data sources or distribution partners affect terms, capacity or service delivery. Buyer power considers how easily customers can compare, switch or negotiate cover. The analysis also tests barriers facing new entrants, including capital, regulation, pricing data and trust, alongside substitutes such as self-insurance, manufacturer protection plans, alternative finance arrangements or choosing to bear a loss.
- Rivalry and switching. Assess whether policy comparison and low-friction purchasing may intensify pressure on price, service and retention.
- Dependency exposure. Explore how concentrated external capacity, repair capability or partner-controlled customer access could affect bargaining positions.
- Force-by-force evidence. Record observations in the Excel structure and use the Word analysis to distinguish industry mechanisms from unsupported force ratings.
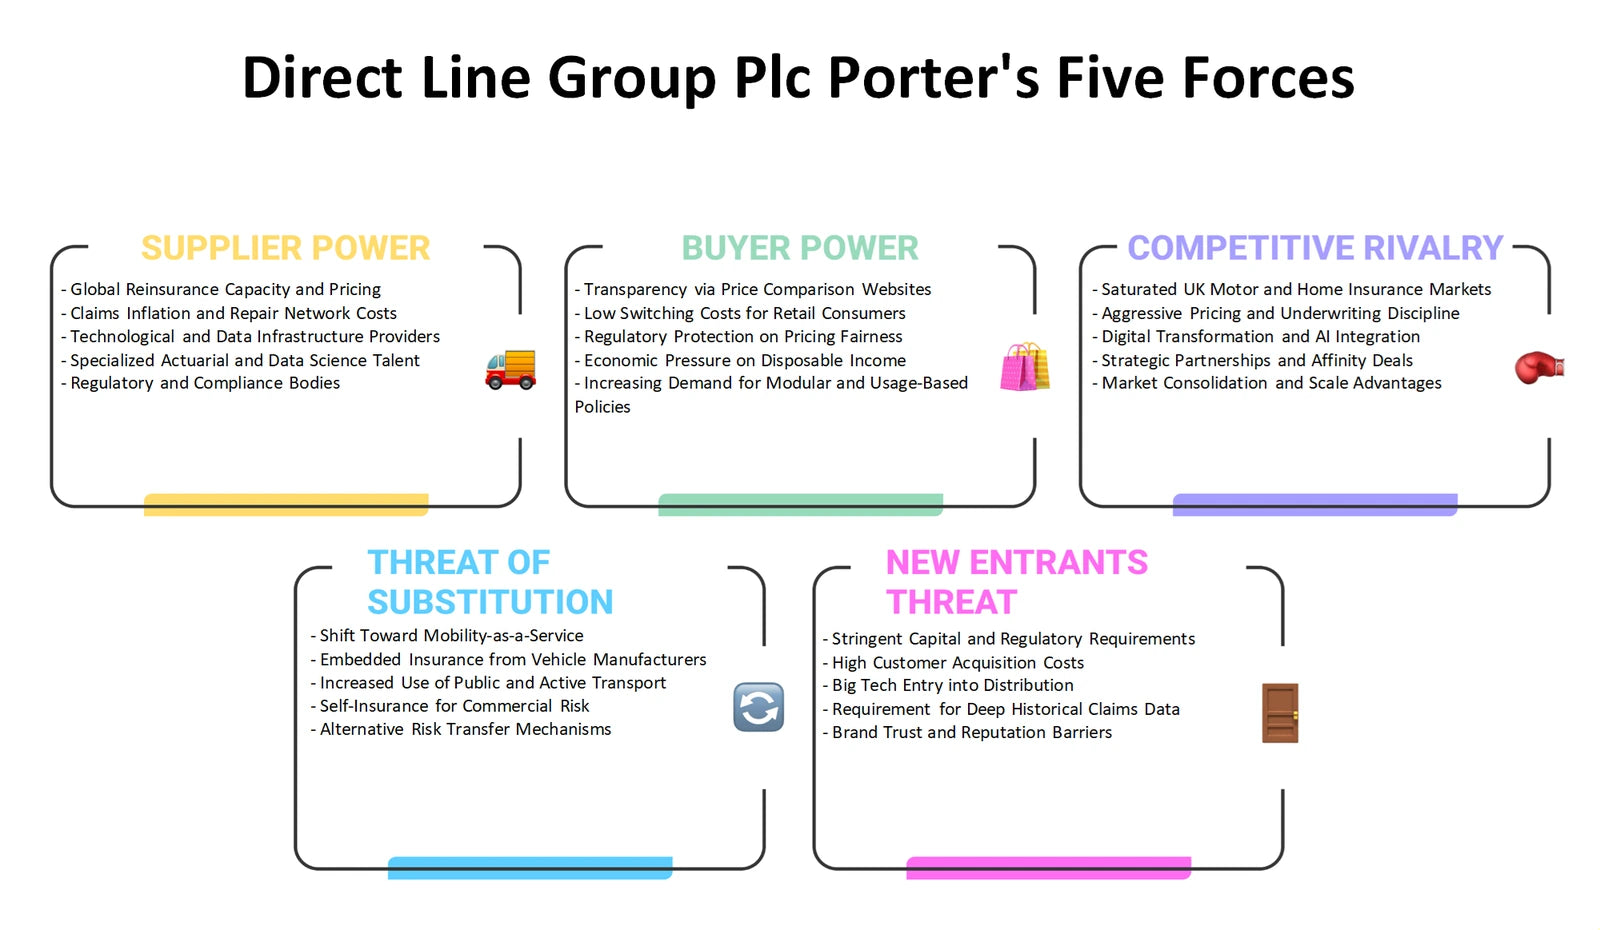
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can an insurer align the policy proposition, price logic, distribution route and customer communication around a credible promise?
The Direct Line Group Plc Marketing Mix examines Product, Price, Place and Promotion in a regulated service context. Product analysis can cover the design of insurance protection, optional features, claims support and the clarity of policy terms. Price is not merely a headline premium: it can be assessed through risk-based underwriting, affordability, commissions, acquisition cost, expected claims and renewal treatment. Place considers direct journeys alongside white-label, co-branded, dealer, bank, retailer and OEM routes described in the supplied context. Promotion then asks how product information, partner presentation and customer communications can explain cover fairly without overstating what a policy provides.
- Product clarity. Compare how cover, exclusions, service expectations and claims support may affect customer understanding and perceived value.
- Channel fit. Examine whether the route to market matches the moment of need, from a direct search to an embedded or point-of-sale offer.
- Mix alignment. Use the Excel framework to contrast the four Ps by proposition or channel, with the Word analysis supporting a fuller discussion of trade-offs.
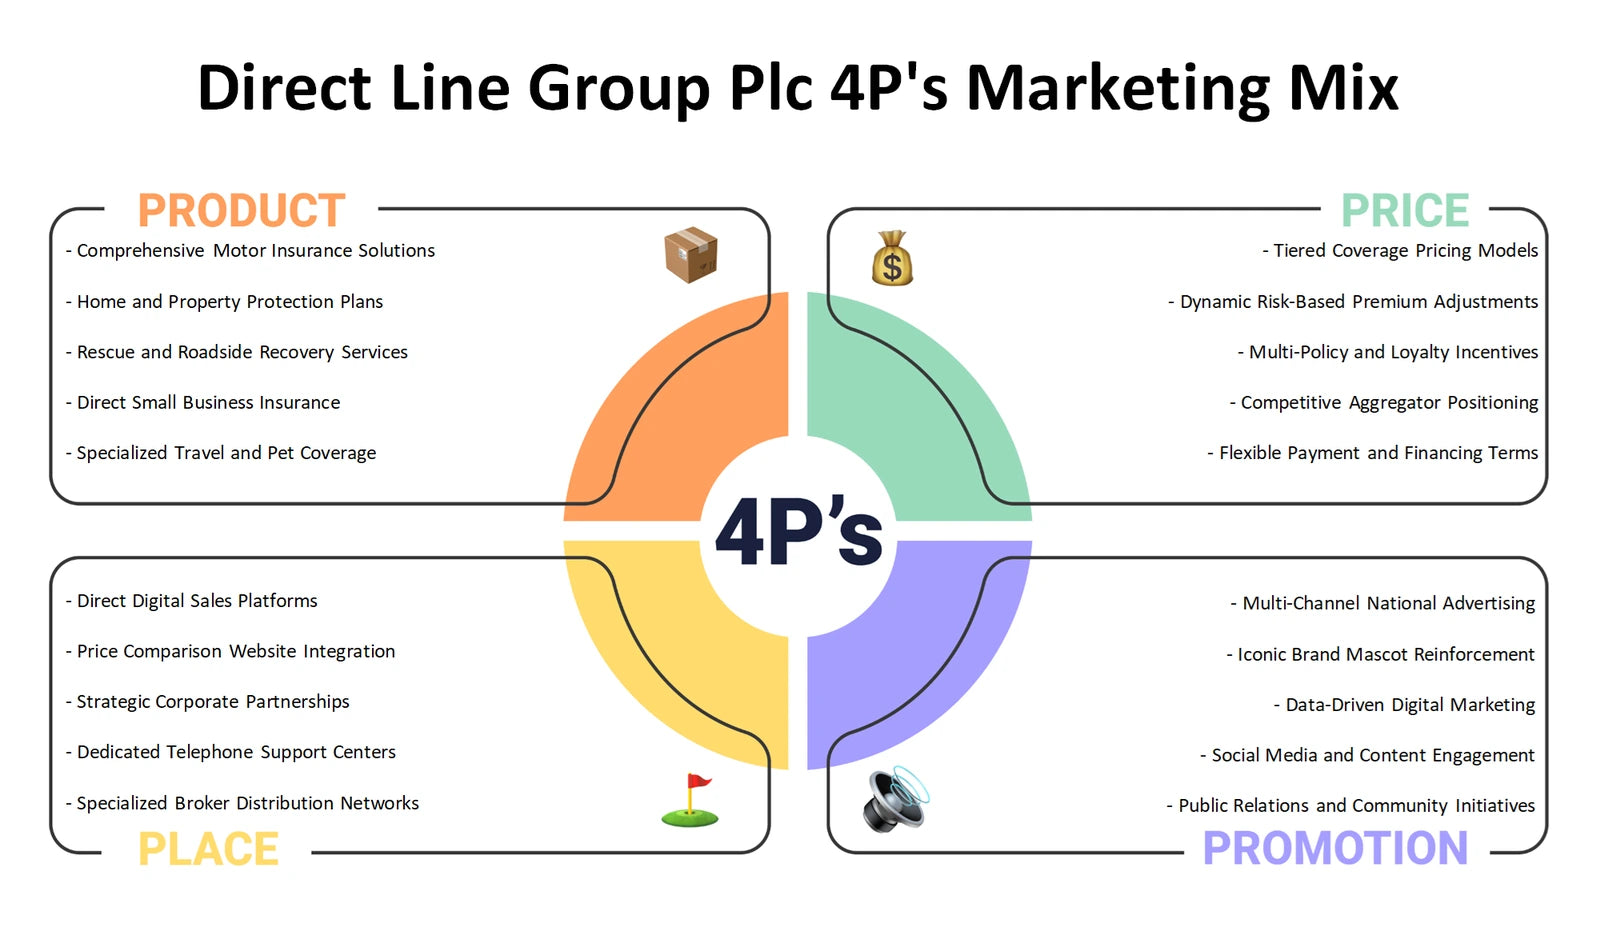
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should an insurance business monitor when pricing risk, meeting obligations and developing partner-led customer access?
The Direct Line Group Plc PESTLE analysis, also commonly called PESTEL, separates external influences that can alter the assumptions behind an insurer's strategy. Political factors may include public-policy priorities affecting insurance markets. Economic conditions can influence household budgets, repair costs, claims severity, investment conditions and demand. Social trends may change mobility, ownership, trust and customers' willingness to purchase protection. Technological developments can affect fraud prevention, digital servicing, risk data and embedded insurance. Legal questions include conduct, privacy, competition and insurance requirements, while environmental exposure can shape catastrophe patterns, repair needs and the cost of underwriting physical risks. These are areas to investigate, not assertions of a particular recent change.
- External scanning. Separate broad market signals from company-controlled actions so planning discussions do not confuse cause and response.
- Risk transmission. Consider how an external factor could flow through to pricing, claims, capital, partner operations or customer affordability.
- Monitoring agenda. Use the Excel categories to prioritise evidence and use the Word analysis to document why selected developments matter to the business model.
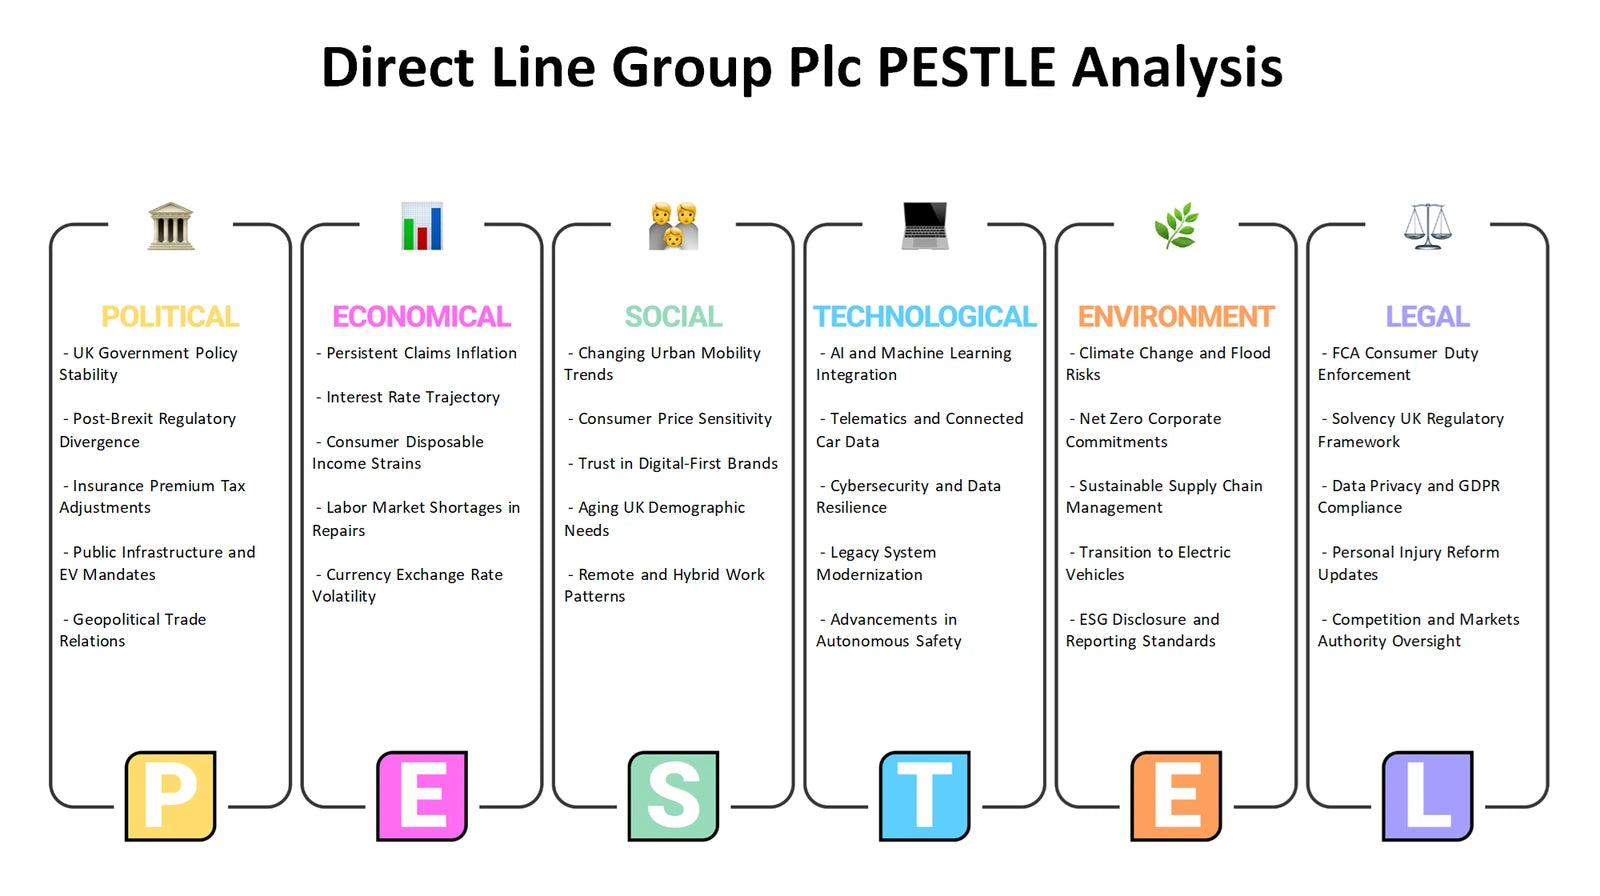
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal insurance capabilities and constraints be distinguished from external opportunities and threats before strategic choices are made?
The Direct Line Group Plc SWOT analysis keeps internal and external factors in their proper places. Possible strengths to test may include underwriting knowledge, claims capability, brand or partner relationships; possible weaknesses may concern operating complexity, concentration, cost-to-serve or dependence on outside capacity. These are analytical themes, not established findings. Opportunities arise outside the organisation, such as changing customer journeys, better use of partner distribution or new ways to meet protection needs. Threats likewise come from external conditions including competitive pricing, claims inflation, regulatory shifts, catastrophe exposure or technology-enabled substitution. Bringing these categories together helps prevent an external market trend being mistaken for an internal capability.
- Classification discipline. Distinguish what the business controls from what it must respond to, creating a more useful basis for strategic debate.
- Strategic tensions. Explore how reinsurance, partner access and claims operations may create both advantages and dependencies under changing conditions.
- Actionable synthesis. Use the Excel matrix to organise candidate factors and the Word analysis to explain links, evidence needs and strategic questions.
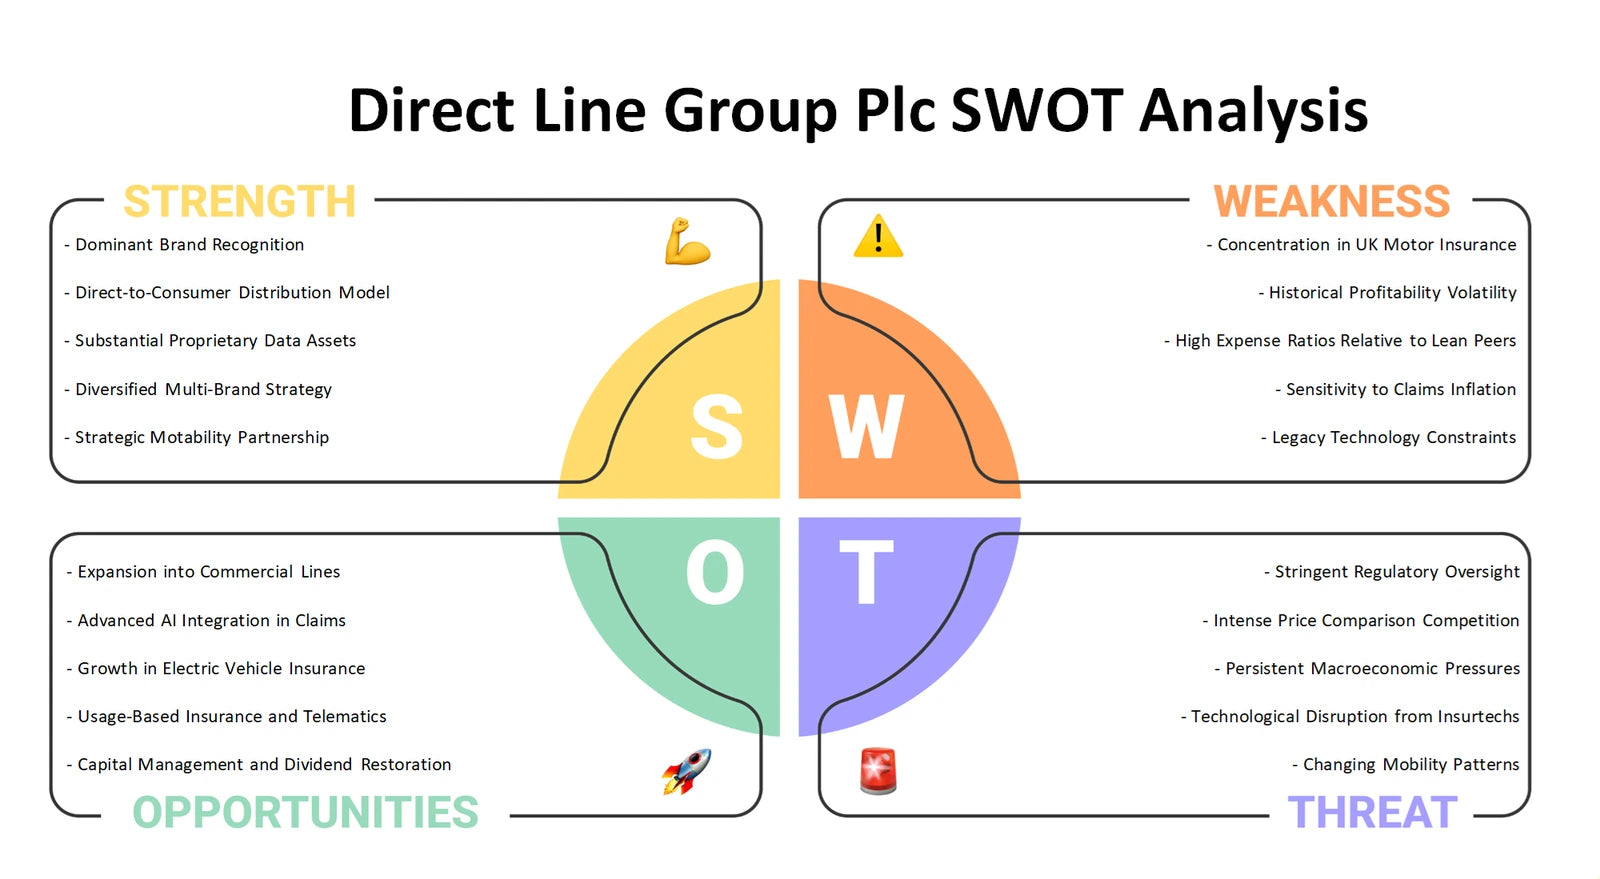
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the operating model
Together, the six perspectives help customers move from a broad view of Direct Line Group Plc's insurance and partner-distribution context to more structured strategic questions. The BCG Matrix considers portfolio priorities; the Canvas explains value creation and economics; Five Forces and PESTLE examine external pressure; the Marketing Mix focuses on customer delivery; and SWOT brings internal and external considerations into one discussion. The Excel frameworks provide organised working structures, while the detailed Word files support deeper company-specific interpretation.
Company background: Direct Line Group Plc — product-context page describing the intended insurance business.