

CURO: Underwriting and Licensing in Six Frameworks

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
CURO Strategy Analysis Bundle
This bundle concerns CURO as the consumer-lending business described in the associated product context, rather than an identically named company in another sector. That context describes point-of-sale and installment lending supported by funding facilities, cash liquidity, digital acquisition journeys, referral relationships and compliance activity. The available material does not independently confirm a legal entity, parent company or geography, so the analysis keeps its focus on the supported lending model.
For CURO, useful strategic questions include how funding terms affect lending economics, how partner-led acquisition influences customer cost, and how regulation changes operating priorities. The six connected frameworks help turn those questions into structured comparisons: portfolio choices, value creation, competitive pressures, customer-facing decisions, external risks and internal trade-offs. They are analytical tools, not claims that a particular CURO product, market position or financial result has already been proven.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which CURO lending products merit funding capacity, operational attention and customer-acquisition spend when market growth and relative market share differ?
A CURO BCG Matrix provides a disciplined way to compare lending products or distribution propositions using two distinct criteria: market growth and relative market share. It can frame products as potential Stars, Cash Cows, Question Marks or Dogs without assuming that any CURO offering belongs in a particular quadrant. That distinction matters in lending, where an apparently attractive growth area may still require costly capital, tighter underwriting, partner incentives or additional compliance work. The framework helps connect portfolio priorities to the practical limits created by warehouse lines, revolvers, securitization capacity and liquidity buffers.
- Portfolio lens. Compare point-of-sale, installment or partner-originated propositions by their growth context and relative competitive position rather than treating all originations as equally valuable.
- Capital discipline. Consider whether a product’s expected demand and credit profile justify the funding, servicing and regulatory resources it may consume.
- Workbook use. Use the Excel matrix to organise candidate products and assumptions, then use the detailed Word analysis to document why each potential priority deserves further validation.
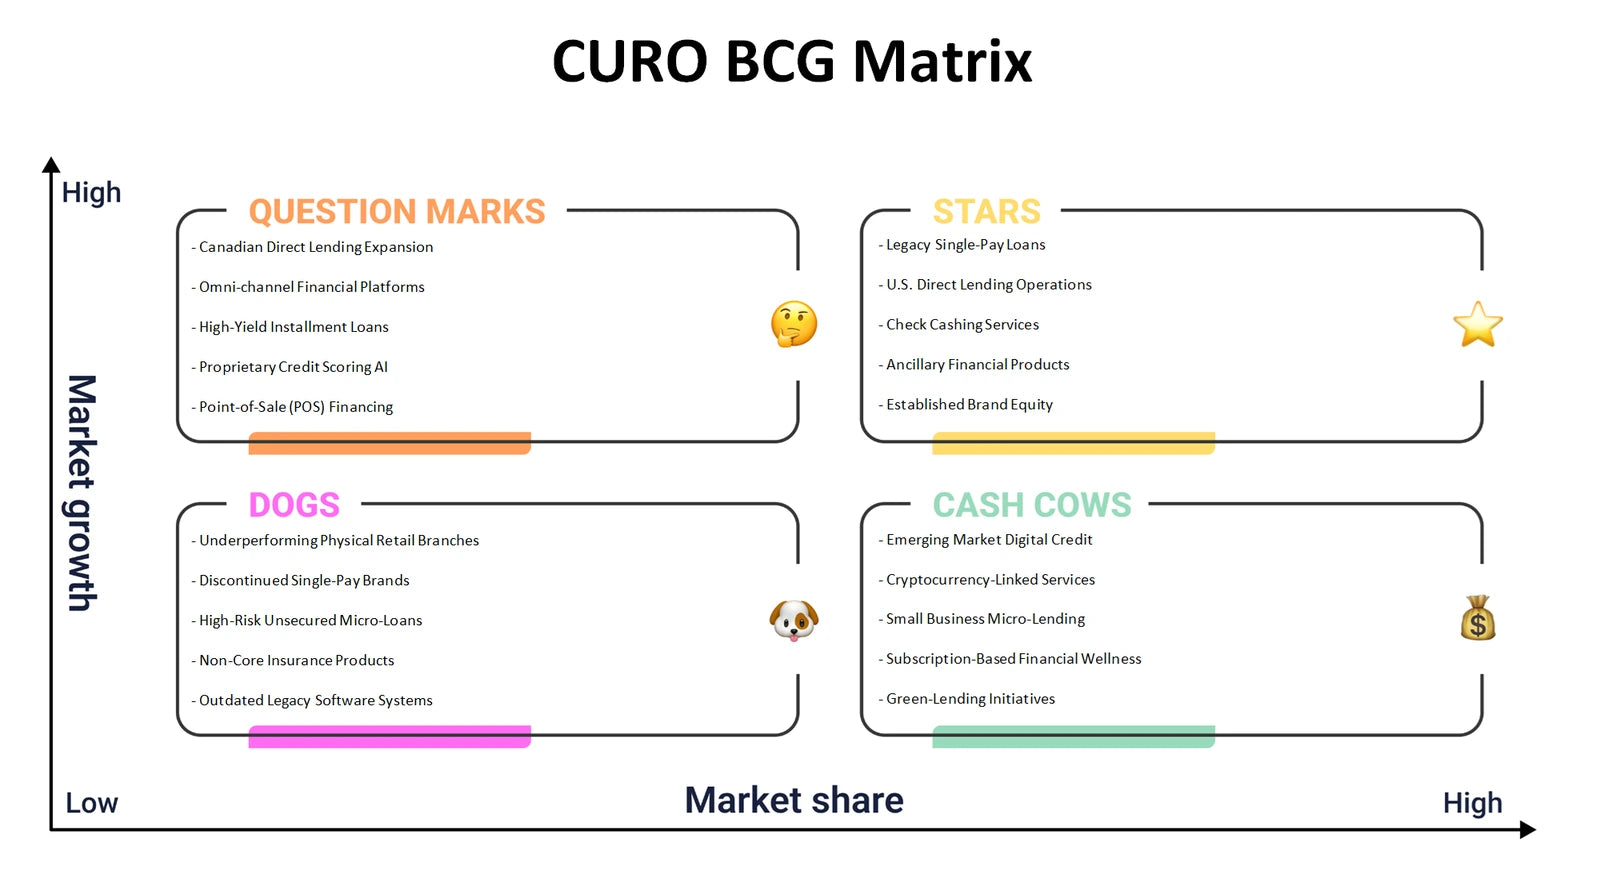
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do CURO’s borrower proposition, partner journeys, funding resources and compliance obligations connect to a sustainable lending model?
The CURO Business Model Canvas examines all nine building blocks in one connected picture: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For the supported lending context, it helps assess how consumers reach a prequalification or application journey, how referral and lead-generation partners may support channels, and how customer experience must sit alongside affordability, KYC and complaint-handling expectations. Funding access, underwriting capability, servicing operations, data systems and regulatory capability can be considered as resources and activities rather than treated as background details. The canvas also helps test whether revenue logic is compatible with acquisition, funding, credit-loss and compliance costs.
- Value chain. Map how a borrower need is translated into a lending offer, a digital or partner route to market, a credit decision and ongoing account support.
- Economic connections. Examine how funding facilities, partner payouts, technology, servicing and compliance costs influence the viability of revenue streams.
- Model-building use. Populate the Excel framework with linked hypotheses, then use the Word analysis to add context on the trade-offs behind each of the nine building blocks.
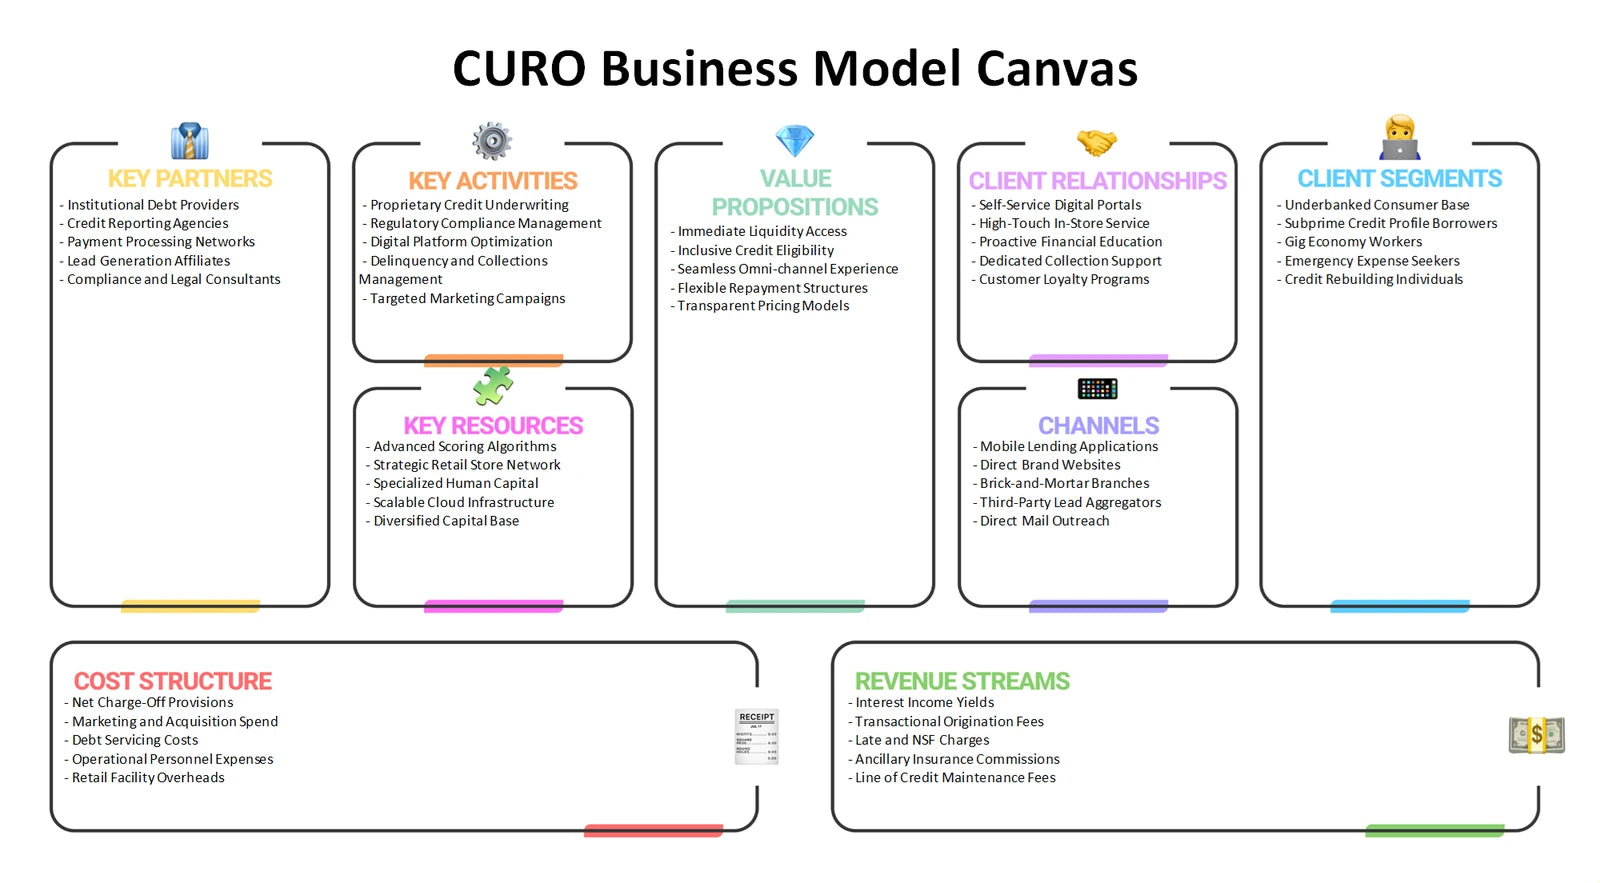
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape CURO’s ability to acquire borrowers, secure funding and earn acceptable returns in consumer lending?
CURO Porter's Five Forces examines the lending environment through rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes. Rivalry can include competing credit providers and digitally enabled routes to borrowers, while supplier power is especially relevant where capital providers, facility terms and securitization markets affect funding availability and cost. Buyer power concerns the alternatives available to borrowers and the ease of comparing offers. Substitutes extend beyond direct lenders to other ways of meeting a short-term spending or liquidity need, such as savings, payment arrangements or other financing options. Entry barriers may arise from licensing, underwriting expertise, capital access, data capability and compliance infrastructure, but these should be assessed rather than presumed.
- Funding leverage. Explore how covenants, tenor limits and concentration among capital sources may influence pricing, product design and risk appetite.
- Customer alternatives. Compare the borrower’s practical alternatives, including non-loan solutions, to understand why convenience alone may not determine demand.
- Pressure mapping. Use the Excel framework to record evidence and open questions for each force, with the Word analysis helping explain why a pressure matters operationally.
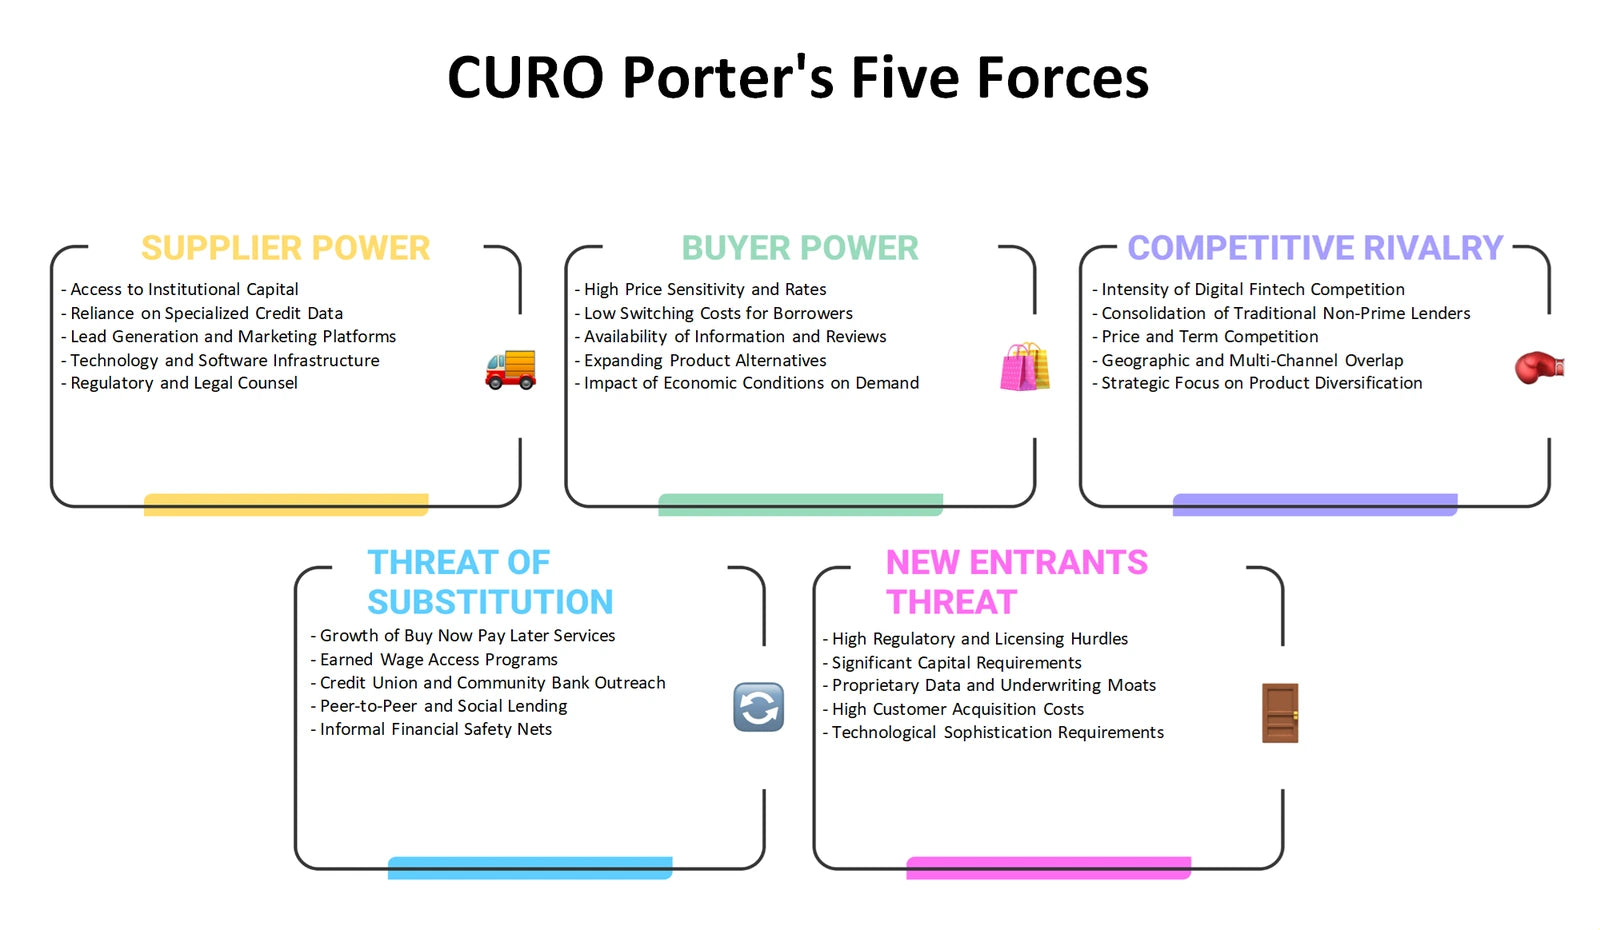
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can CURO align lending offers, pricing logic, customer access and communications with responsible acquisition and conversion?
The CURO Marketing Mix considers Product, Price, Place and Promotion in the context of consumer credit. Product analysis can examine how point-of-sale or installment propositions address a specific purchase, payment or cash-flow need and how product terms interact with underwriting. Price should be considered as a combination of borrower cost, credit risk, funding expense and compliance constraints rather than a simple promotional lever. Place includes digital journeys, APIs, referral partners and embedded prequalification opportunities where supported by the business context. Promotion requires careful assessment because lending communications must balance conversion goals with transparency, suitability and clear customer understanding. The 4Ps help keep commercial choices tied to the realities of regulated financial services.
- Offer clarity. Assess whether product features and disclosures communicate the intended borrower value without obscuring repayment obligations or eligibility conditions.
- Channel fit. Examine how partner journeys and performance-based referral arrangements may affect lead quality, customer experience and acquisition cost.
- Decision workshop. Use the Excel 4Ps structure to compare channel and proposition options, then consult the Word analysis when discussing the associated commercial and control implications.
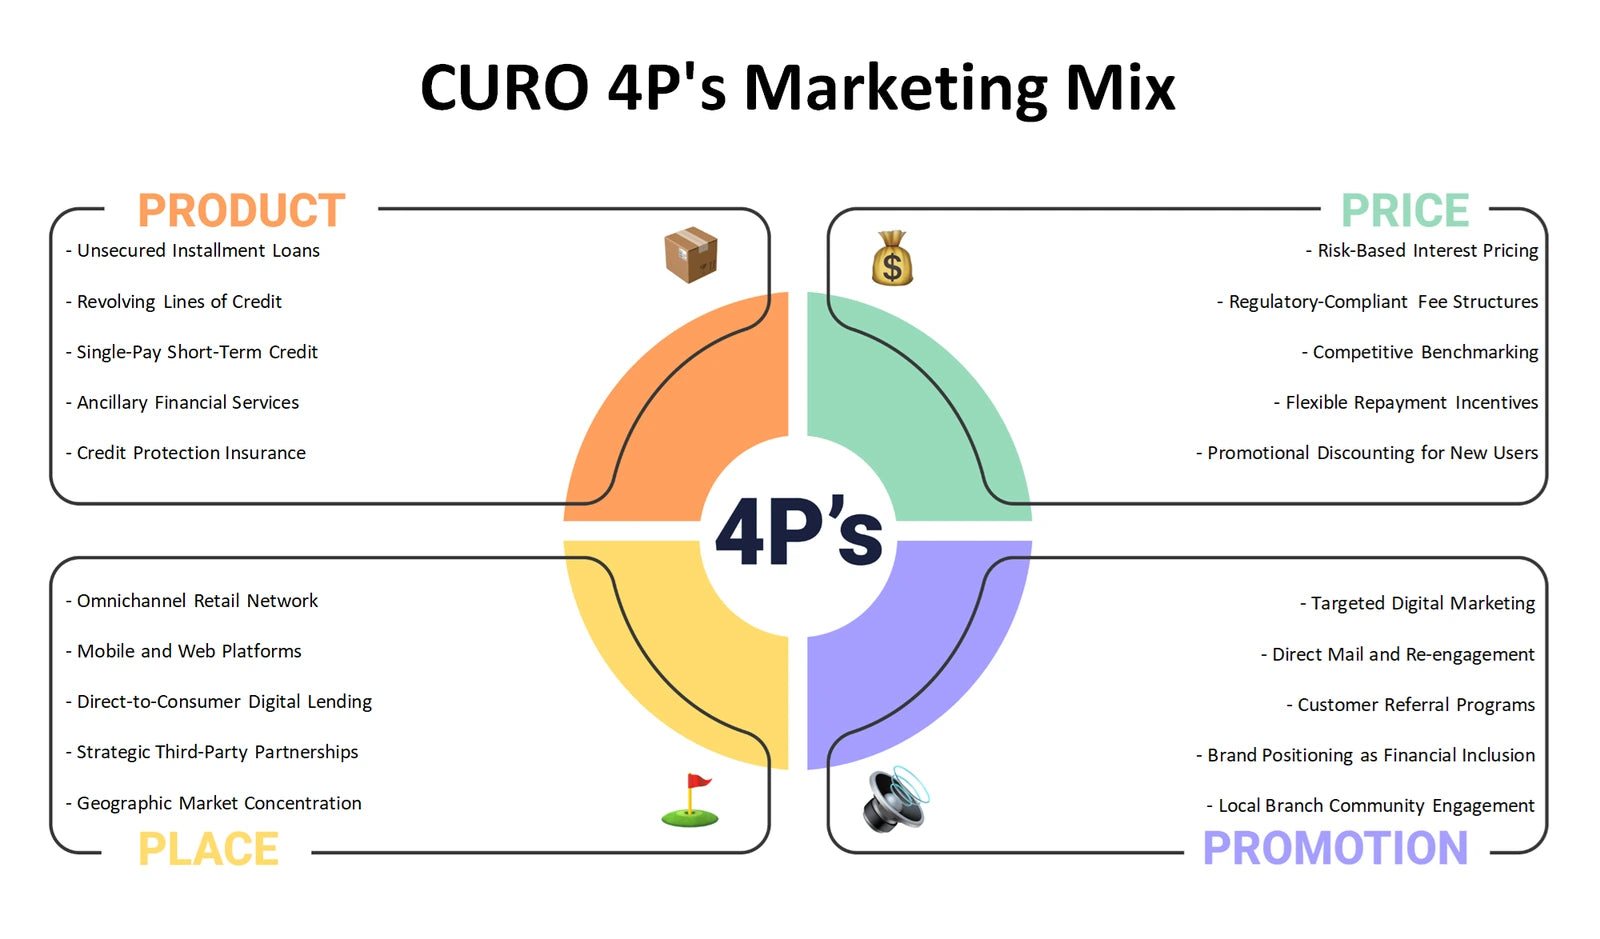
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should CURO monitor when funding, consumer demand, technology and regulatory expectations can change together?
A CURO PESTLE analysis, also commonly called PESTEL, separates the external environment into Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal questions can include licensing, consumer-protection expectations, affordability assessment and reporting obligations; this framework does not assume a specific jurisdiction or new rule. Economic analysis can examine how household pressure, credit performance, funding conditions and interest-rate sensitivity may affect demand and profitability. Social factors may shape borrower trust and attitudes toward credit. Technology includes digital onboarding, API-enabled partner journeys, fraud controls and data governance. Environmental factors can be considered through operational resilience, vendor expectations and the broader physical or transition risks that may affect customers or funding partners.
- External scan. Distinguish documented operating requirements from emerging policy, macroeconomic and behavioural questions that require monitoring.
- Change pathways. Trace how an external development could affect underwriting, liquidity planning, marketing practice, partner oversight or customer support.
- Monitoring use. Use the Excel categories as a repeatable environmental scan and use the Word analysis to capture the strategic relevance of the issues selected for review.
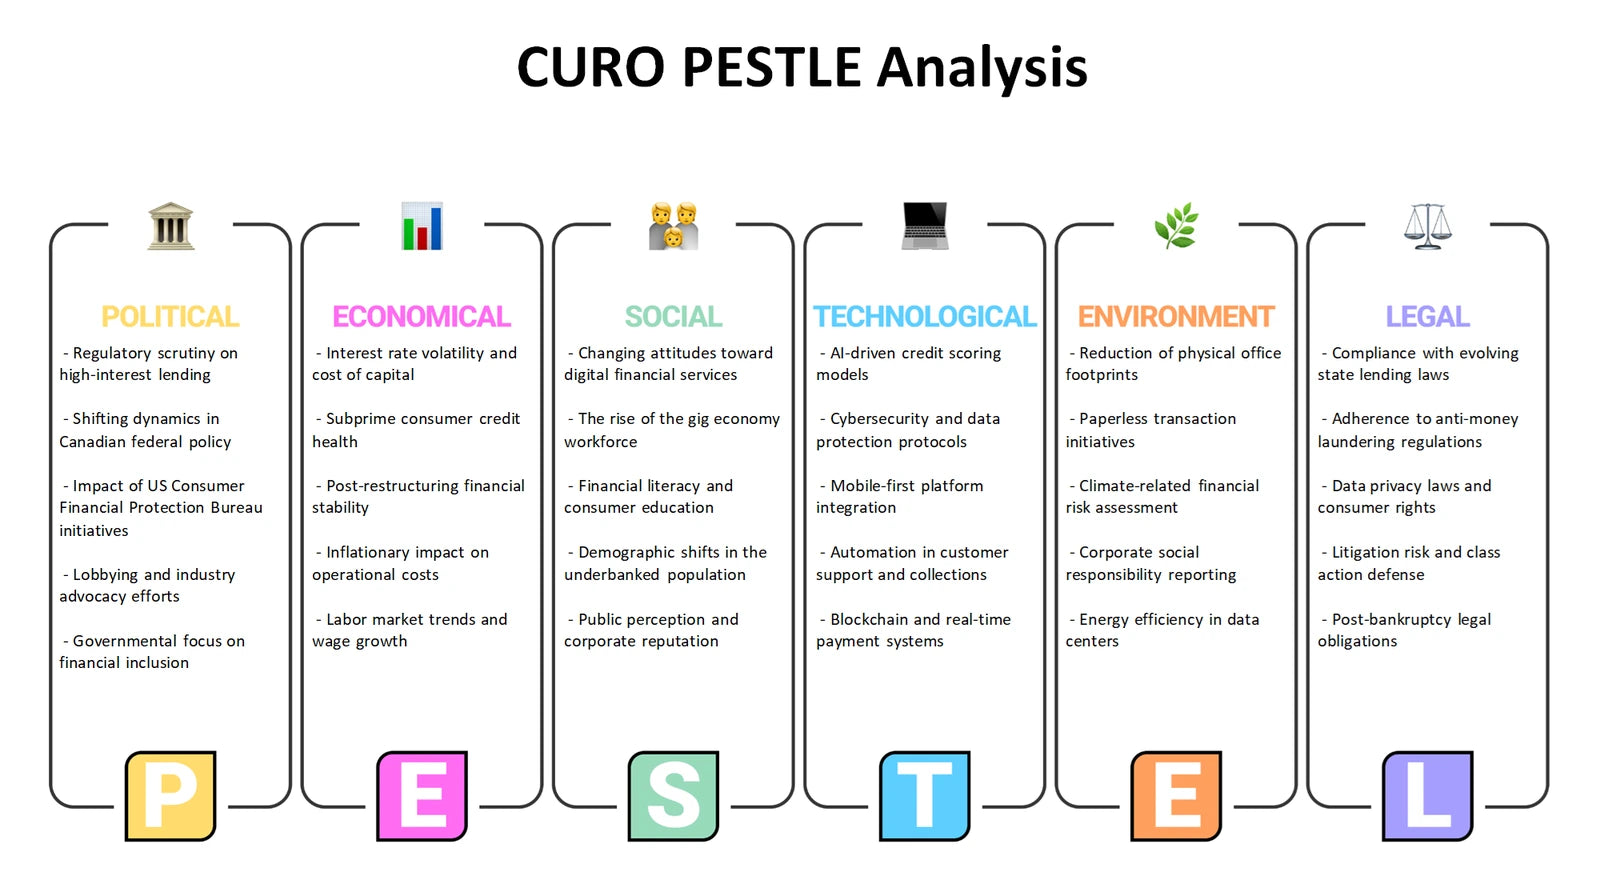
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can CURO distinguish internal lending capabilities and limitations from the external opportunities and threats affecting its model?
A CURO SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. In the supplied context, possible internal themes for assessment include funding diversification, underwriting and servicing capability, digital integration, partner management and compliance processes. These are topics to evaluate, not established scores or conclusions. Weaknesses may involve operational concentration, funding dependence, complex control requirements or the cost of maintaining reliable customer support. Opportunities belong outside the firm, such as improving digital access or serving an unmet borrowing need, while threats can include changing regulation, economic stress, fraud, funding-market pressure or intensified competition. Keeping those categories separate prevents a useful strategic discussion from mixing controllable capabilities with external conditions.
- Internal evidence. Identify capabilities and constraints that management can influence through investment, governance, process design or partner oversight.
- External exposure. Relate opportunities and threats to the PESTLE and Five Forces questions without presenting uncertain market developments as facts.
- Priority setting. Use the Excel grid to rank discussion themes by relevance, then use the Word analysis to explain how selected strengths could address risks or support opportunities.
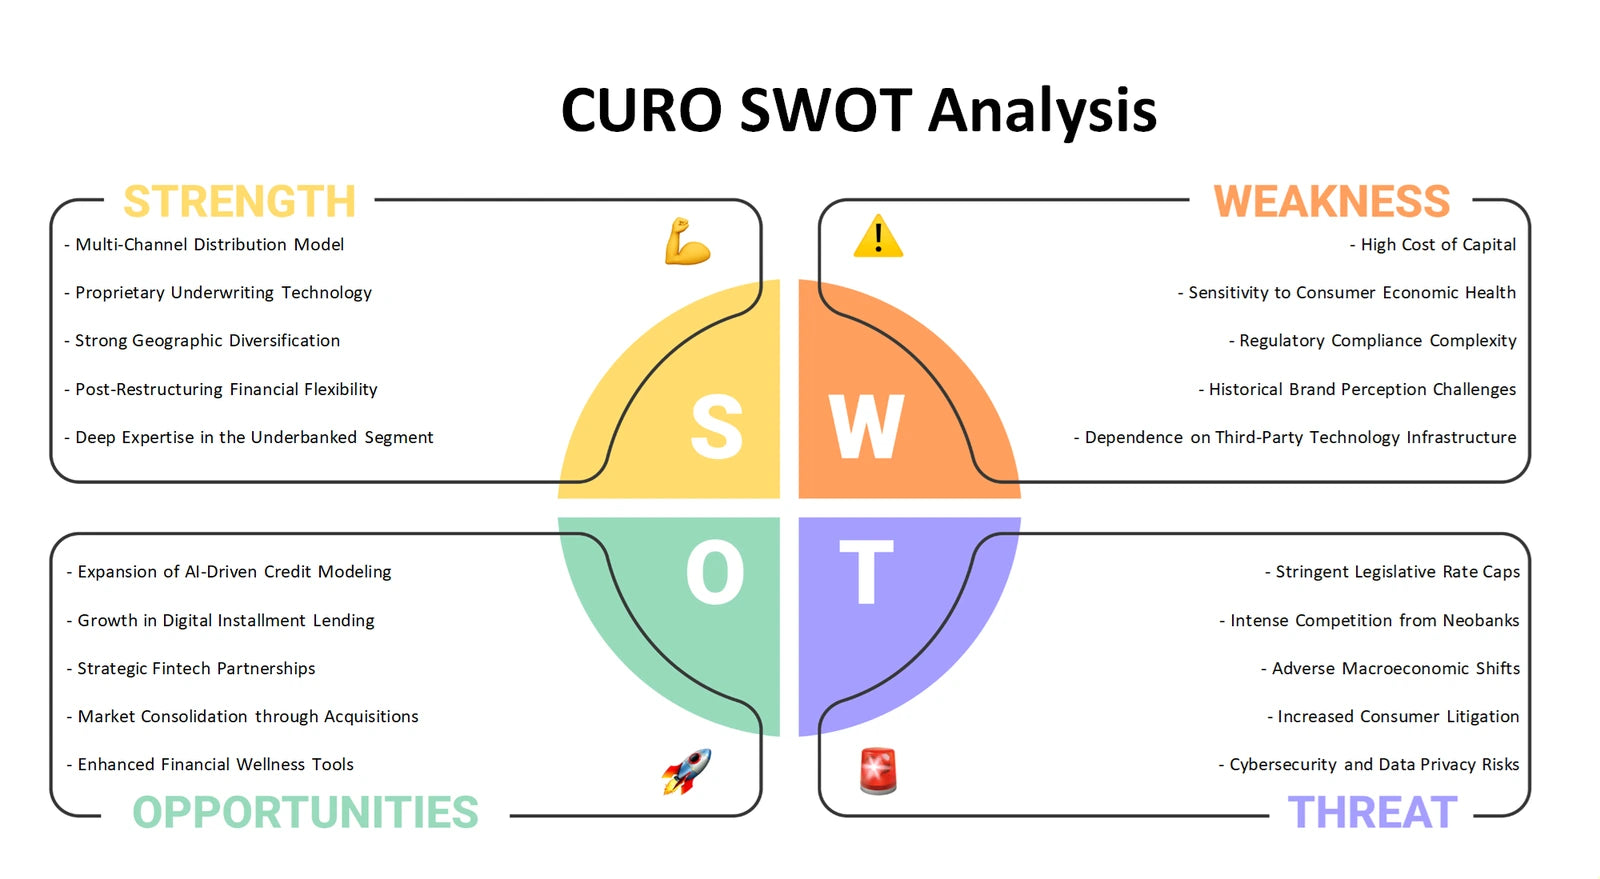
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of CURO’s lending strategy
Together, the six perspectives move from portfolio allocation and value creation to market pressure, customer-facing choices, external change and strategic fit. The Excel frameworks provide a structured place to compare assumptions and priorities, while the detailed Word analyses support more considered discussion of funding, partner channels, responsible lending controls and borrower value. Used together, they can help develop a coherent strategic review without treating unverified outcomes as settled facts.
Company background: CURO — business-model context (product page).