

Chongqing Rural Bank: Banking Business and Deposit Funding – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Chongqing Rural Bank Strategy Analysis Bundle
This bundle is framed around the supplied business context for Chongqing Rural Bank: a banking business focused on retail, rural-finance and digital-channel needs, with households, agricultural activity and small and medium-sized enterprises among the relevant customer groups. The context also highlights inclusive-finance initiatives, credit-guarantee arrangements and support for priority agriculture and SME sectors. A matching official corporate or regulatory record was not supplied for this exact display name, so legal-entity, geography and financial-reporting claims are intentionally excluded.
That operating context makes portfolio allocation, customer value, credit risk, distribution and regulatory change practical strategic questions. The six analyses help organise those questions without presenting unverified conclusions as facts. Together, they provide structured ways to examine where banking services create value, which external pressures matter and how rural, retail and digital priorities may fit into a coherent strategic picture.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking service areas merit investment, protection, selective testing or tighter resource discipline?
A Chongqing Rural Bank BCG Matrix helps compare service lines using market growth and relative market share rather than treating every banking activity as equally strategic. For a business context spanning retail customers, rural finance, SME needs and digital channels, the key issue is how deposit, lending, payment and relationship-led activities compete for scarce management attention, technology spending, funding capacity and risk oversight. The framework uses Stars, Cash Cows, Question Marks and Dogs as analytical categories; it does not assume that any particular product already belongs in one of them. It is especially useful where a promising segment may require investment before its economics and risk-adjusted contribution are established.
- Portfolio comparison. Examine relative share and market-growth evidence for retail, rural, SME and digital service opportunities before prioritising expansion or consolidation.
- Capital discipline. Relate growth ambitions to funding, credit quality, operational capacity and compliance demands rather than viewing growth in isolation.
- Structured prioritisation. Use the Excel matrix to map candidate activities and the Word analysis to record assumptions, evidence gaps and the logic behind each portfolio discussion.
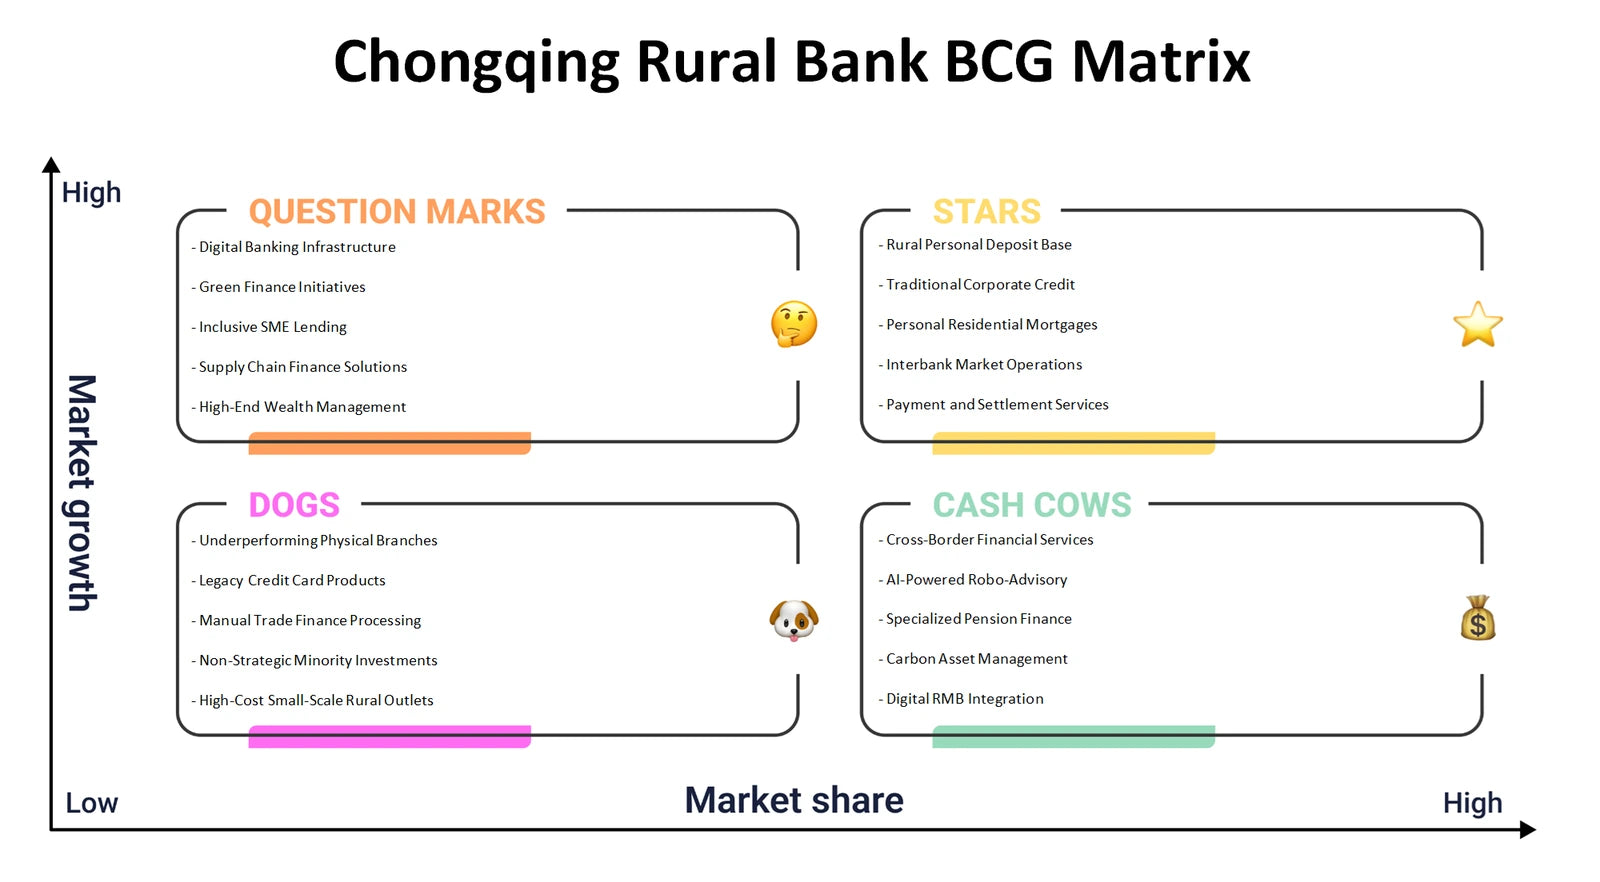
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How can customer trust, rural reach, relationship banking and digital access connect to sustainable banking economics?
The Chongqing Rural Bank Business Model Canvas brings the complete operating model into one connected view. It considers customer segments, value propositions, channels and customer relationships alongside revenue streams, then links those demand-side choices to key resources, key activities, key partnerships and cost structure. In this context, households, agricultural customers and SMEs may have different expectations of access, credit assessment, service support and digital convenience. Relationship managers, risk staff, product teams, partnerships connected with inclusive finance, and regulated banking capabilities are useful areas to examine, not confirmed claims about a specific legal entity. The canvas helps test whether the chosen value proposition can be delivered consistently while maintaining prudent lending, deposit and service economics.
- Value logic. Connect rural and SME customer needs with practical propositions such as accessible service, relationship support, financing relevance and convenient channels.
- Operating links. Explore how people, risk processes, technology, partnerships and compliance work together to support revenue-generating banking activities.
- Model alignment. Complete the Excel canvas block by block, then use the detailed Word analysis to discuss trade-offs between customer reach, delivery cost, risk control and income sources.
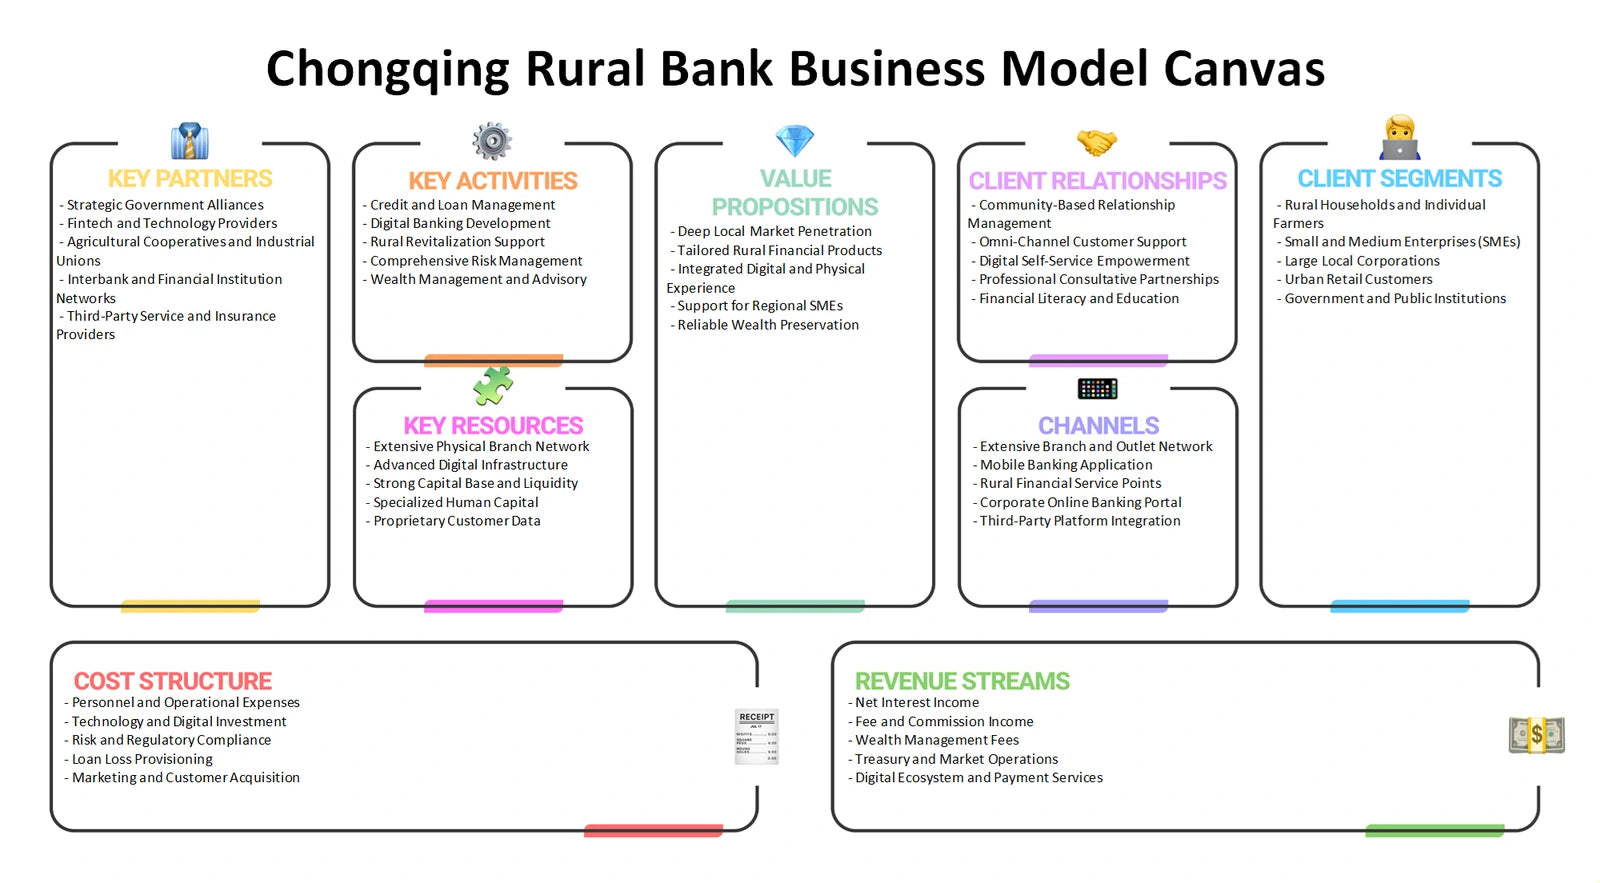
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness and resilience of the banking activities under review?
Chongqing Rural Bank Porter's Five Forces examines the competitive setting around retail, rural and SME banking rather than merely listing other banks. Rivalry can affect deposit retention, lending terms, service quality and digital experience. Supplier power can include the influence of funding sources, technology providers, specialist talent and critical service partners. Buyer power reflects customers' ability to compare institutions or move relationships, while potential new entrants may emerge through licensed financial providers or technology-enabled models. Substitutes are alternative ways customers meet payment, saving, credit or financing needs, including non-bank options where relevant. The framework does not assign force scores; it helps identify where bargaining, differentiation and barriers to entry deserve evidence-based attention.
- Competitive pressure. Assess how service availability, trust, product comparability and local relationships may influence rivalry for deposits and lending customers.
- Alternative solutions. Distinguish direct banking competition from substitute payment, credit, savings or financing routes that may reduce customer reliance on a bank.
- Evidence trail. Use the Excel framework to compare each force consistently and the Word analysis to capture sector reasoning, uncertainties and implications for the operating model.
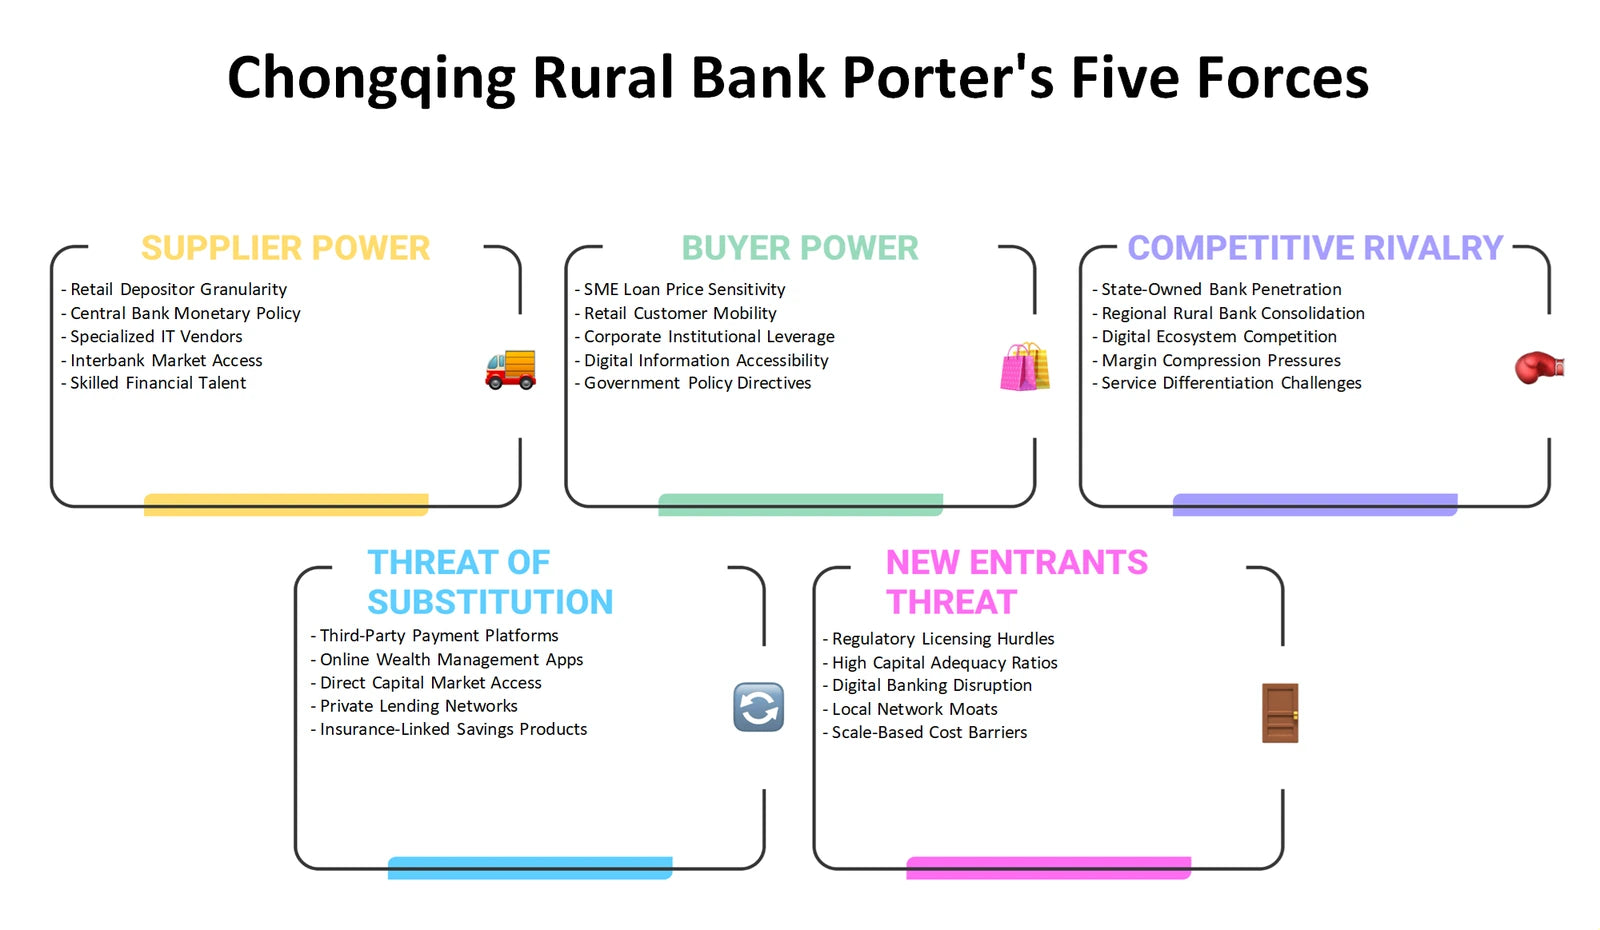
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should banking offerings, pricing logic, access points and communications fit the needs of retail, rural and SME customers?
The Chongqing Rural Bank Marketing Mix applies Product, Price, Place and Promotion to a regulated service business. Product analysis can consider the relevance and clarity of savings, lending, payment, account and support services for different customer circumstances. Price should be examined as transparent banking terms, interest-related economics, fees and value exchange rather than as an invented price list. Place covers the routes through which people can access and use services, including relationship-led touchpoints and digital channels where applicable. Promotion concerns clear, compliant communication that helps customers understand products and make informed choices. This lens is valuable because trust, accessibility and suitability can matter as much as product breadth in financial services.
- Service proposition. Compare how product design and support can address differing household, agricultural and SME financial needs without assuming a single customer journey.
- Channel fit. Evaluate the balance between personal assistance and digital convenience, including the operational consequences of serving customers through multiple routes.
- Go-to-market review. Use the Excel 4Ps structure to organise observations, then use the Word analysis to turn them into customer-segment and communication questions for discussion.
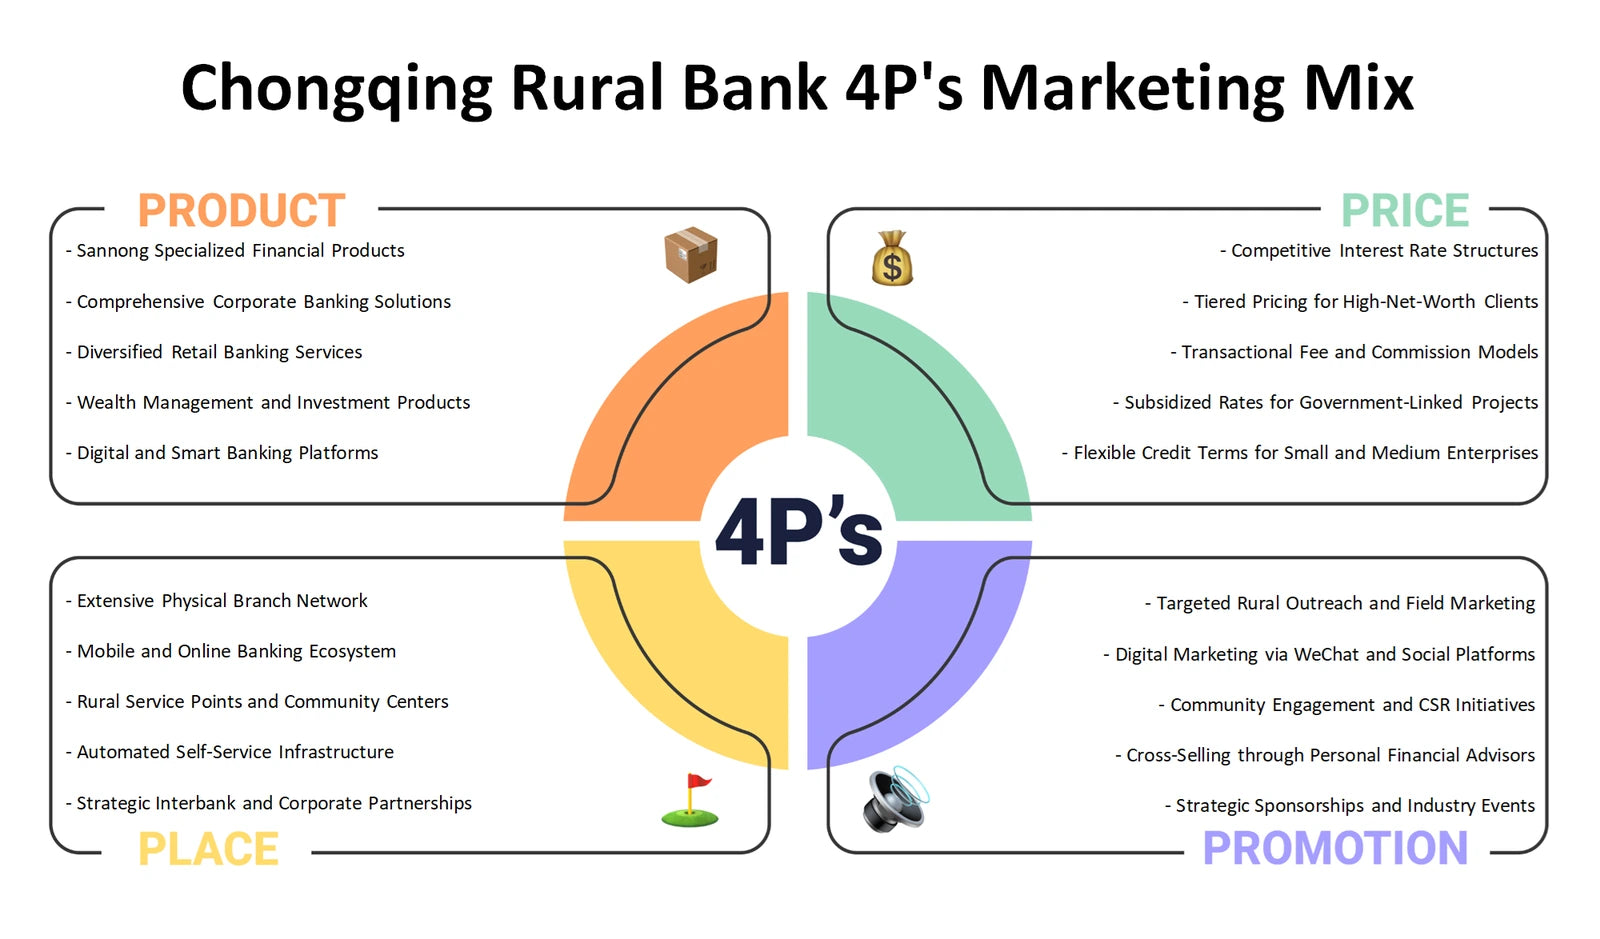
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter the demand, risk profile and operating conditions of rural, retail and SME banking?
A Chongqing Rural Bank PESTLE analysis, also commonly called PESTEL, separates external influences from internal capabilities. Political factors may include public priorities around inclusive finance and rural development. Economic conditions can affect borrower affordability, deposit behaviour, credit demand and loan-loss risk, without assuming any current rate or policy change. Social factors include financial confidence, demographic needs and expectations of convenient service. Technological developments can reshape digital access, data security and customer experience. Legal considerations cover banking supervision, consumer protection, privacy and compliance obligations. Environmental factors may influence agricultural customers, local economic resilience and the assessment of climate-related exposure. The framework helps ensure that strategic debate does not confuse possible external drivers with documented company results.
- External scan. Organise policy, economic, social, technology, legal and environmental topics that could influence lending demand, customer access and risk management.
- Rural relevance. Consider how agricultural conditions, local development priorities and digital inclusion may create both service needs and exposure points.
- Scenario workspace. Use the Excel categories to log signals and possible impacts, with the Word analysis providing space to explain assumptions and distinguish facts from scenarios.
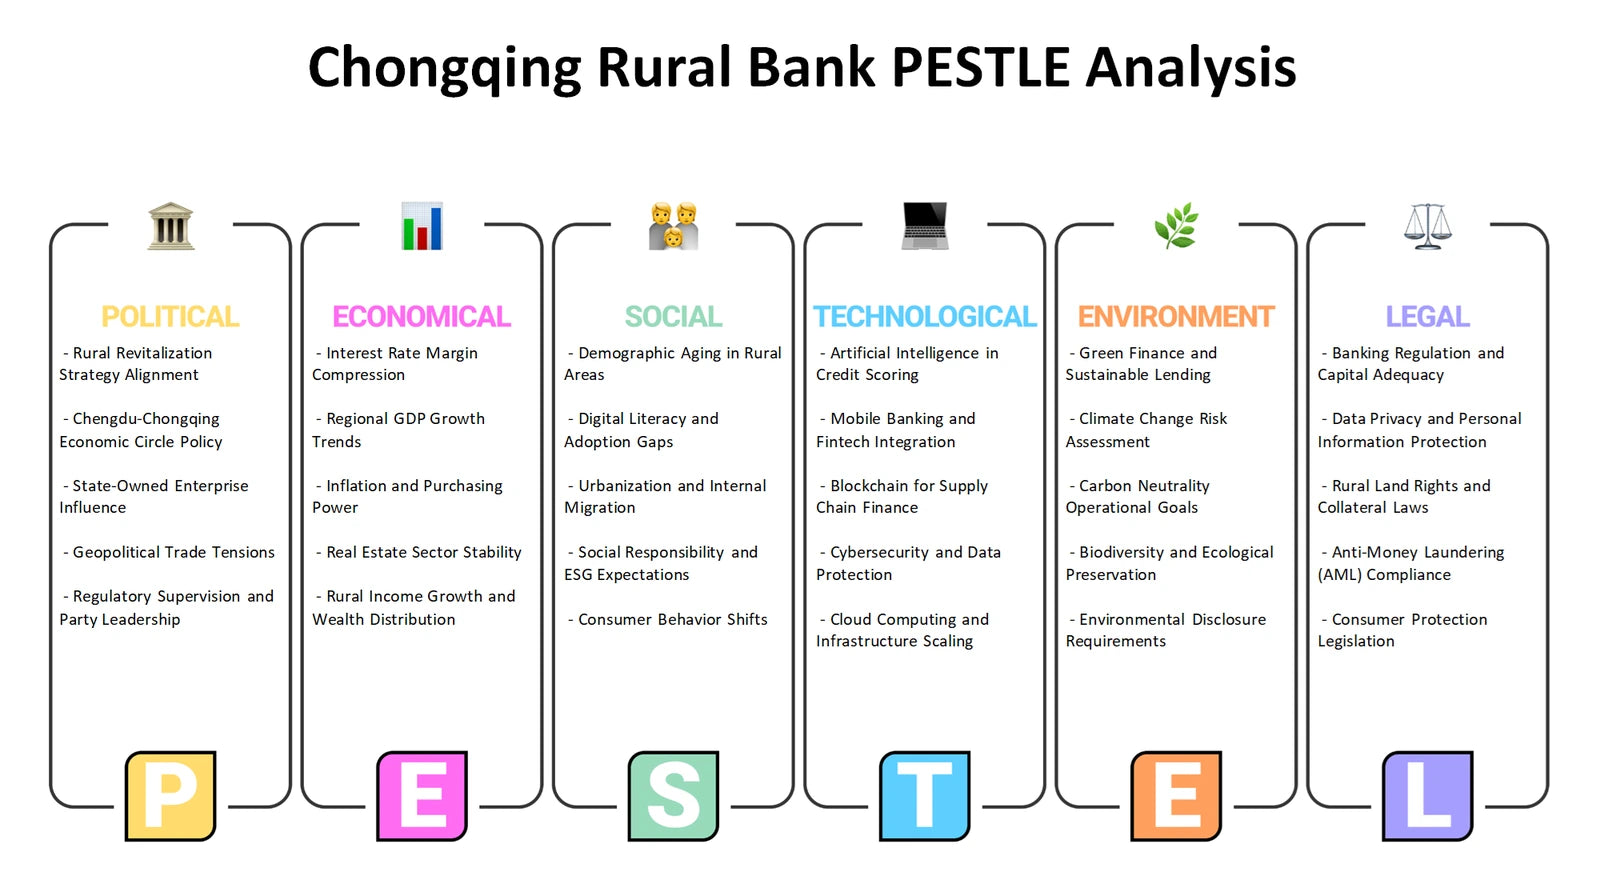
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and constraints be considered alongside external openings and risks?
The Chongqing Rural Bank SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. The supplied context suggests useful themes for assessment, including relationship-led service, risk and product expertise, compliance-focused execution, rural finance, SME support and digital channels. These should be tested as analytical possibilities rather than treated as established findings about an unresolved legal entity. Strengths might concern capabilities that can be evidenced; weaknesses concern internal limitations such as resource, process, technology or coverage gaps. Opportunities arise outside the organisation, such as unmet financial needs or partnership possibilities, while threats include competitive, credit, regulatory, technology and environmental pressures. Keeping these categories separate avoids calling an external market trend an internal strength or presenting a potential advantage as proven.
- Capability check. Identify which customer relationships, risk disciplines, people, processes or channels can be supported by evidence as internal advantages or constraints.
- Context matching. Link external opportunities and threats to the PESTLE and Five Forces questions instead of mixing market conditions into internal assessments.
- Actionable synthesis. Populate the Excel SWOT grid with concise issues and use the Word analysis to explain how each issue could inform priorities, safeguards or further research.
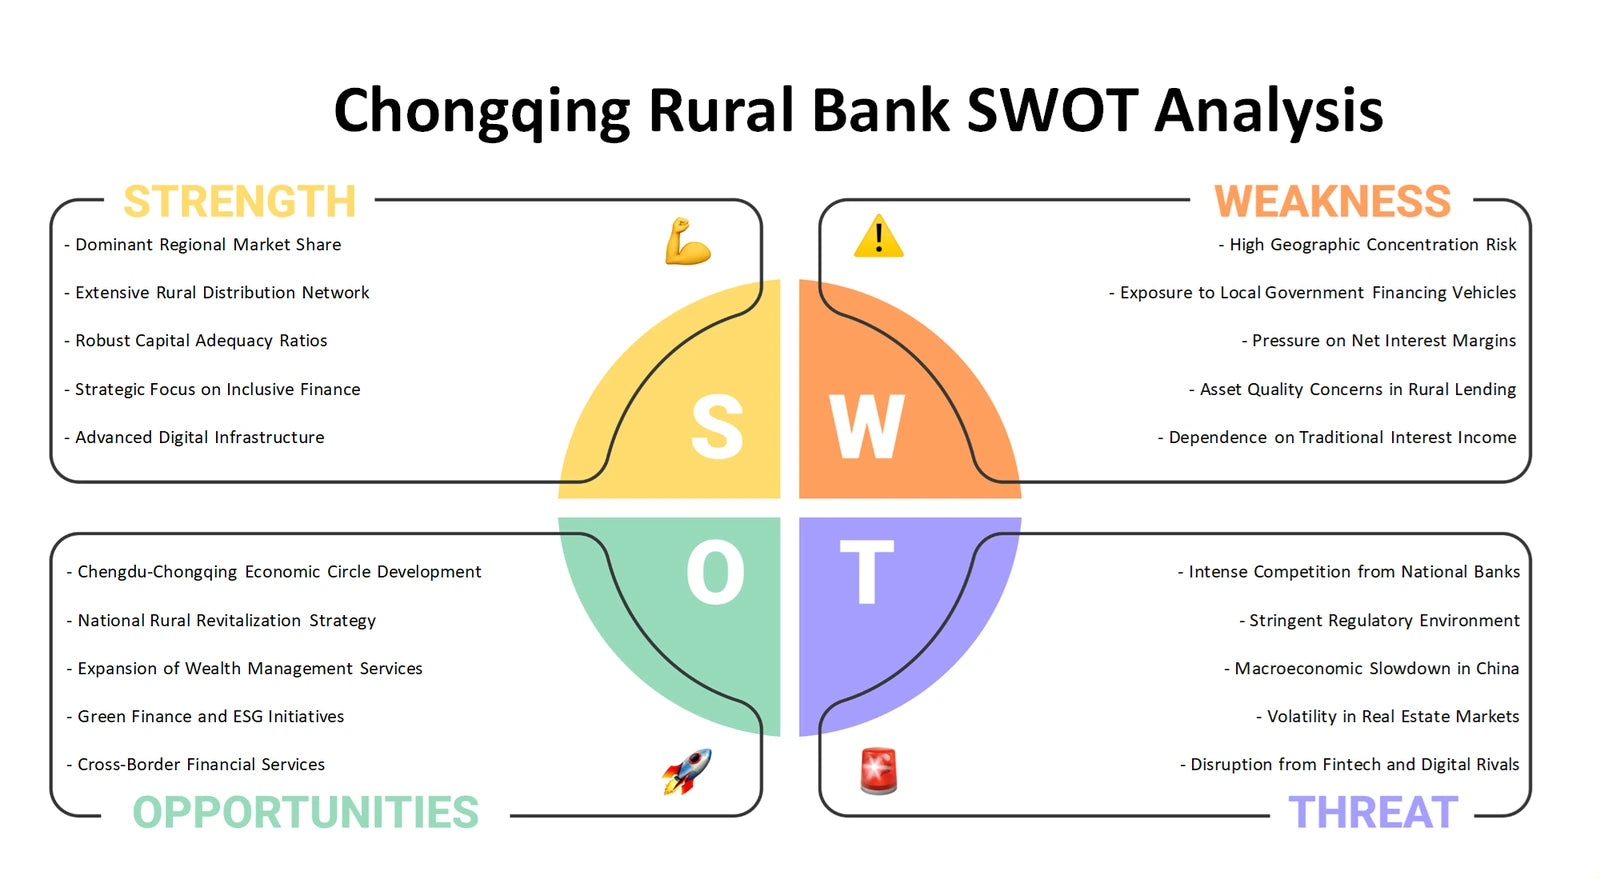
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected strategy discussion
Used together, the six perspectives move from portfolio choices and value creation to industry pressure, customer delivery, external change and internal-versus-external positioning. For Chongqing Rural Bank, the Excel frameworks can help structure comparisons and working assumptions, while the detailed Word analyses provide a fuller basis for discussing retail, rural-finance, SME and digital-channel questions. The materials support informed strategic review without claiming unverified company findings or financial outcomes.
Company background: Chongqing Rural Bank — supplied business-model context.