

Columbia Financial: Banking Products and Deposit Funding – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Columbia Bank Strategy Analysis Bundle
Columbia Bank is the display name used for this bundle’s intended banking business, represented in regulatory reporting by parent company Columbia Banking System, Inc. The issuer is classified as a U.S. state commercial bank holding company. The supplied business context focuses on consumer and business banking choices, including mobile access, online loan journeys, payment capabilities, and relationships with local business and community organizations.
In parent-group consolidated reporting, Columbia Banking System, Inc. reported revenue of $177 million for the year ended December 31, 2025 in its 2025 Form 10-K, filed February 26, 2026. It later reported GAAP net income of $208 million for April through June 2026 in its second-quarter 2026 Form 10-Q. The bundle helps examine how digital convenience, customer choice, lending economics, and competitive differentiation may shape priorities.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Where should management concentrate attention when customers can compare banking options more easily?
The Columbia Bank BCG Matrix provides a disciplined way to compare possible service, customer, or market priorities using relative market share and market growth. For a banking business, the candidates may include deposit relationships, consumer lending, business lending, digital servicing, or payment-related capabilities. It does not presume that any of these belongs in a particular quadrant. Instead, it tests which areas could merit the different resource logic associated with Stars, Cash Cows, Question Marks, and Dogs. That distinction matters when digital expectations can raise investment needs while rate-sensitive customers can switch providers or products.
- Portfolio comparison. Assess which banking activities warrant closer comparison on growth potential, competitive position, funding needs, and management attention.
- Choice pressure. Explore whether convenient digital access, loan responsiveness, or relationship service changes the relative attractiveness of customer segments.
- Decision workspace. Use the Excel framework to organize candidate activities and evidence, then use the Word analysis to interpret the trade-offs behind possible portfolio priorities.
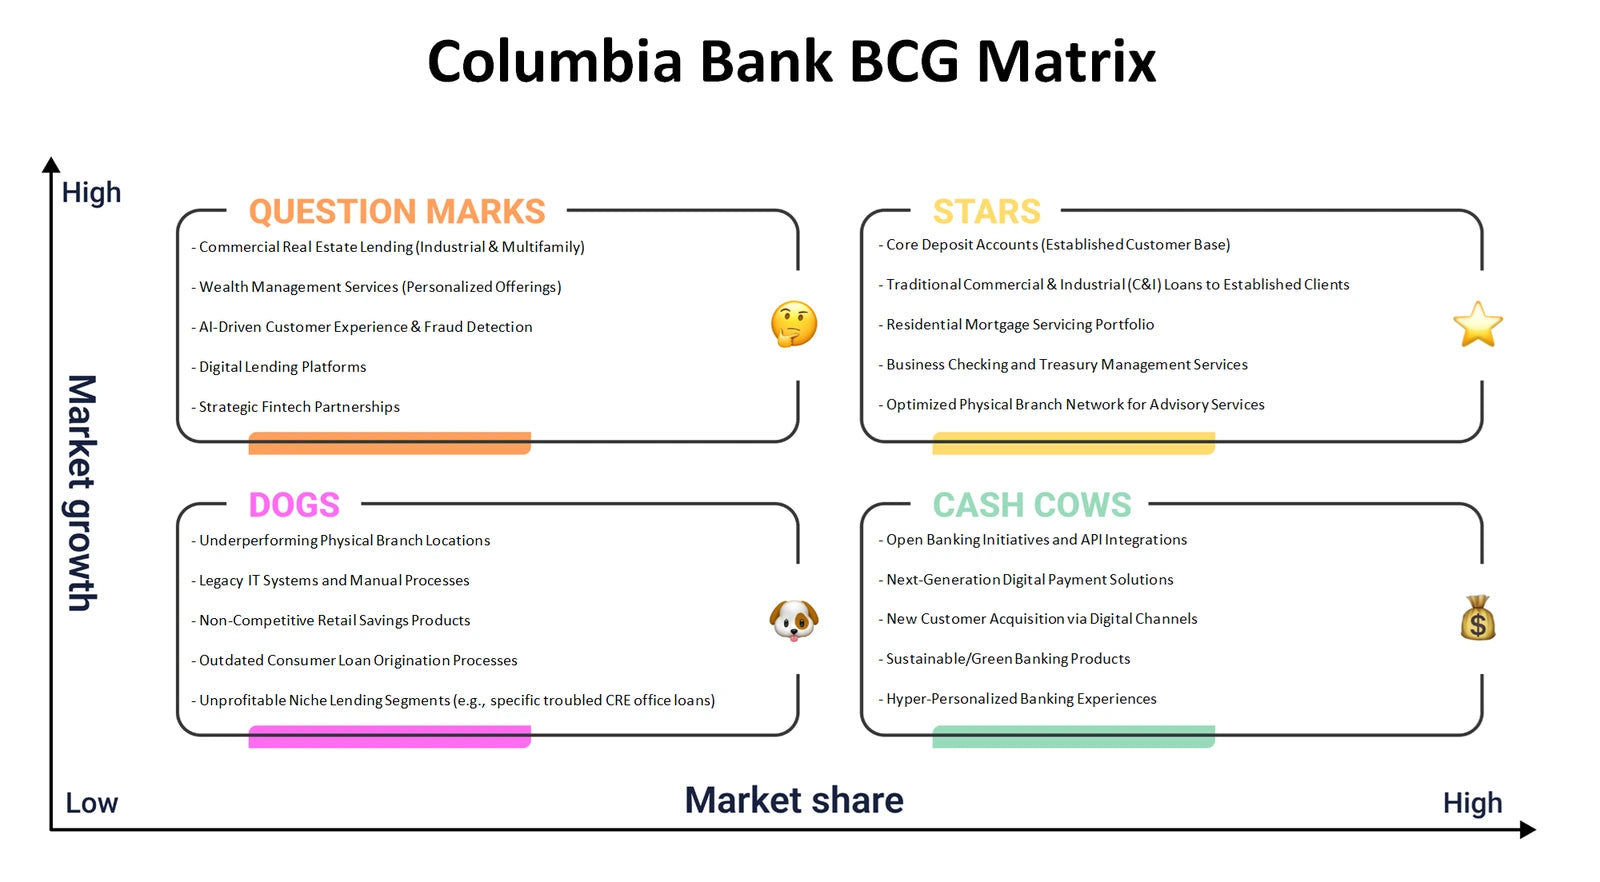
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do digital banking convenience and relationship-led service fit together in the business model?
The Columbia Bank Business Model Canvas connects customer segments and value propositions with the channels and customer relationships through which banking services are experienced. It also examines revenue streams alongside key resources, key activities, key partnerships, and cost structure. This is useful where mobile banking, online loan workflows, payment processing, fintech relationships, and local business connections may all influence how customers select and retain a bank. The framework does not assume a finished model; it helps show where a promise to make banking easier depends on technology, people, risk controls, distribution choices, and a sustainable economic model.
- Customer-value fit. Compare the needs of consumers and businesses with the value of accessible digital tools, responsive lending processes, and trusted banking relationships.
- Operating links. Trace how channels, partnerships, activities, and resources must work together before a customer proposition can reliably generate revenue.
- Connected model. Map the nine building blocks in Excel and use the detailed Word analysis to review assumptions, dependencies, and tensions across the model.
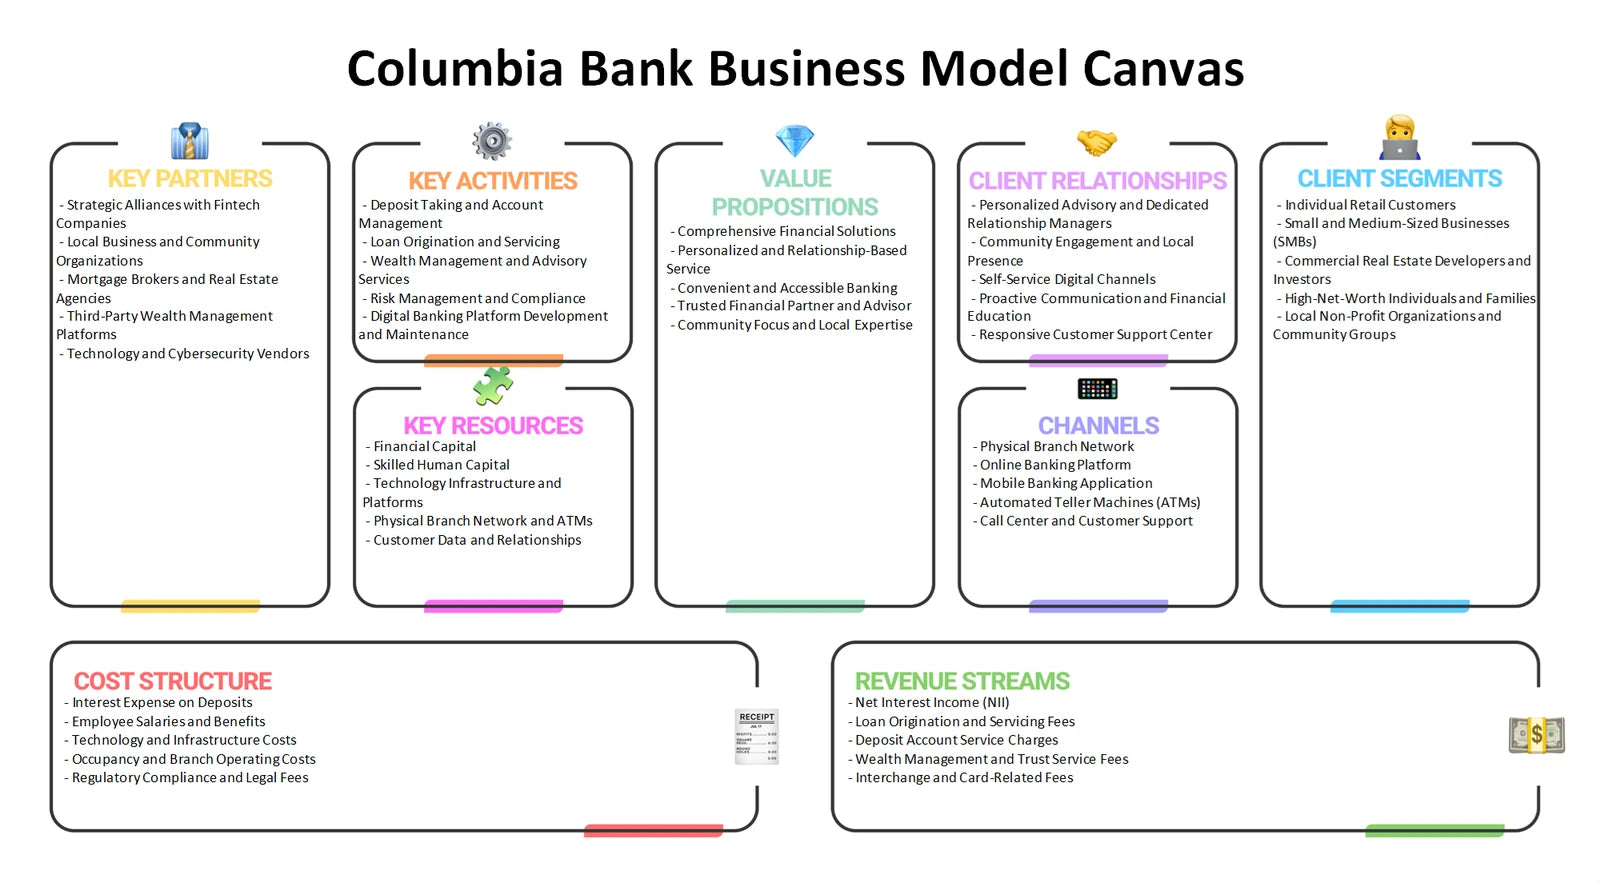
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures most influence a customer’s decision to stay, switch, borrow, save, or use another payment option?
Columbia Bank Porter's Five Forces analysis frames competition beyond direct bank-to-bank rivalry. Rivalry can involve rates, fees, lending terms, branch or relationship access, and quality of digital service. Buyer power can rise when households and businesses can compare accounts, credit, and service experiences quickly. Supplier power may involve technology providers, payment infrastructure, specialist talent, and other inputs needed to serve customers securely. New entrants can include digitally focused financial providers, while substitutes include credit unions, nonbank lending, payment platforms, or other ways customers meet borrowing and transaction needs. The purpose is to identify pressure points, not assign unsupported force scores.
- Rivalry and retention. Examine which service dimensions make differentiation credible when banking products can appear similar to customers.
- Alternative pathways. Consider how nonbank credit, digital payments, and other substitutes can reshape demand for traditional banking interactions.
- Pressure map. Structure each force in Excel, then use the Word analysis to compare its implications for pricing discipline, service investment, and customer retention.
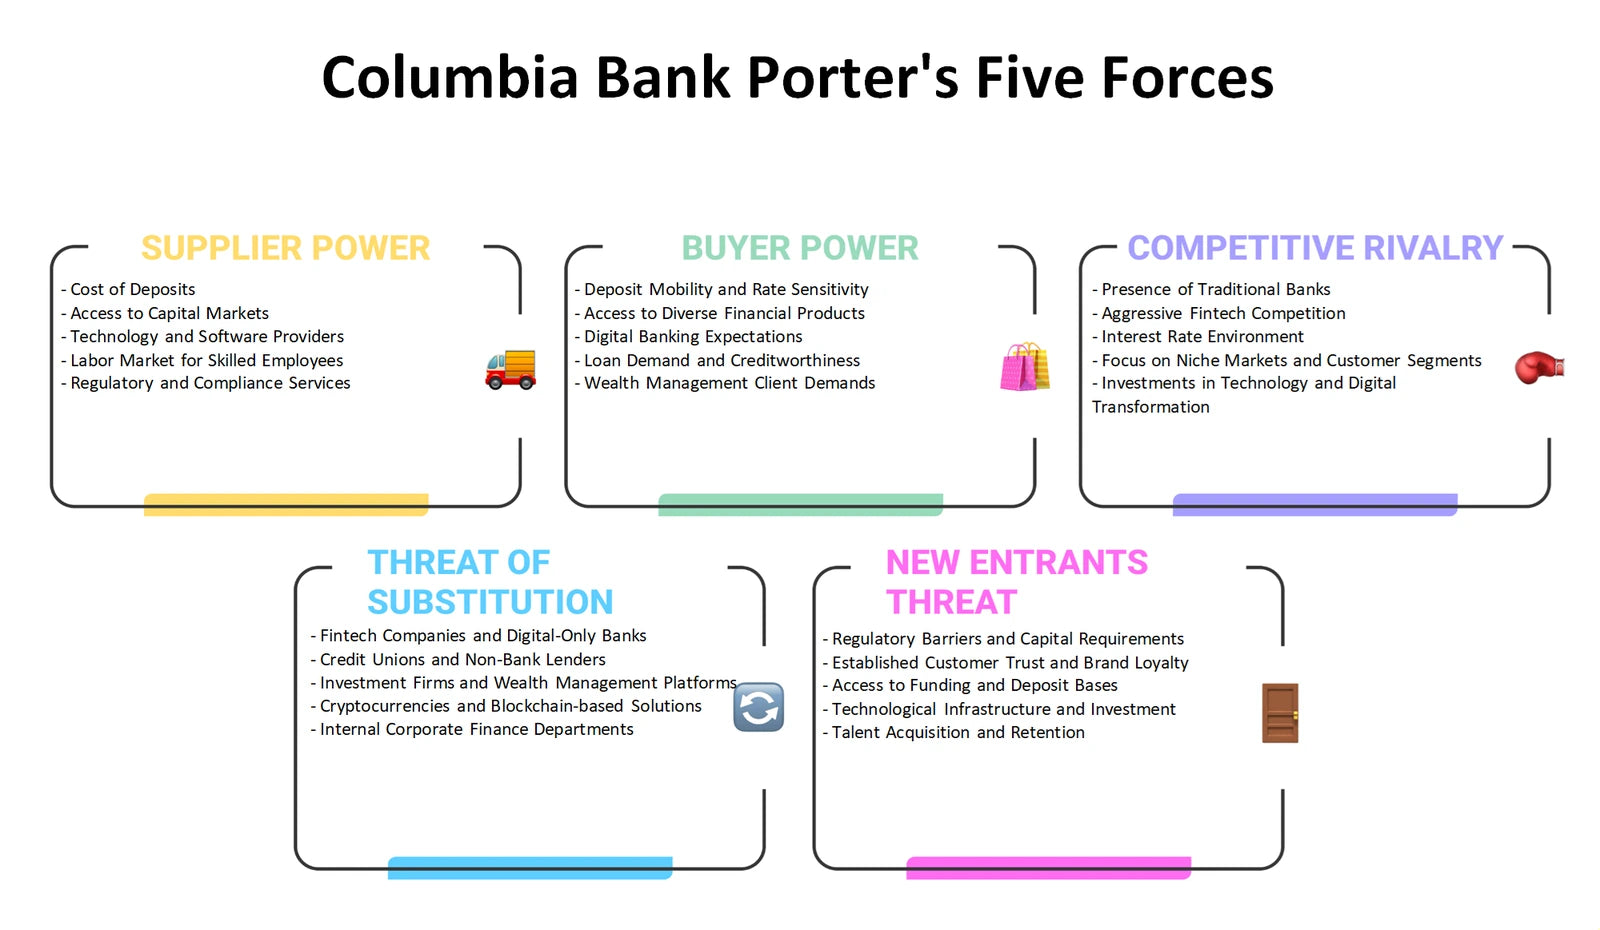
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking offers be made easier to choose without reducing trust, clarity, or commercial discipline?
The Columbia Bank Marketing Mix considers Product, Price, Place, and Promotion in a regulated financial-services setting. Product can cover the usefulness and clarity of deposit, lending, payment, and digital-service propositions. Price is broader than a headline fee: it can involve rates, account terms, lending terms, and the value customers perceive relative to alternatives. Place includes mobile and online journeys as well as relationship-based routes to customers. Promotion can be assessed through relevant communications, financial-literacy activity, and community-facing outreach rather than assumed mass-market campaigns. Together, the 4Ps help test whether the customer promise is consistent from first awareness through account servicing or loan application.
- Offer clarity. Compare how service features and lending or deposit propositions address distinct consumer and business needs.
- Channel consistency. Assess whether digital access and relationship-led touchpoints reinforce the same reasons for customers to choose the bank.
- Market planning. Use Excel to arrange Product, Price, Place, and Promotion questions, with the Word analysis providing the context needed for a more considered review.
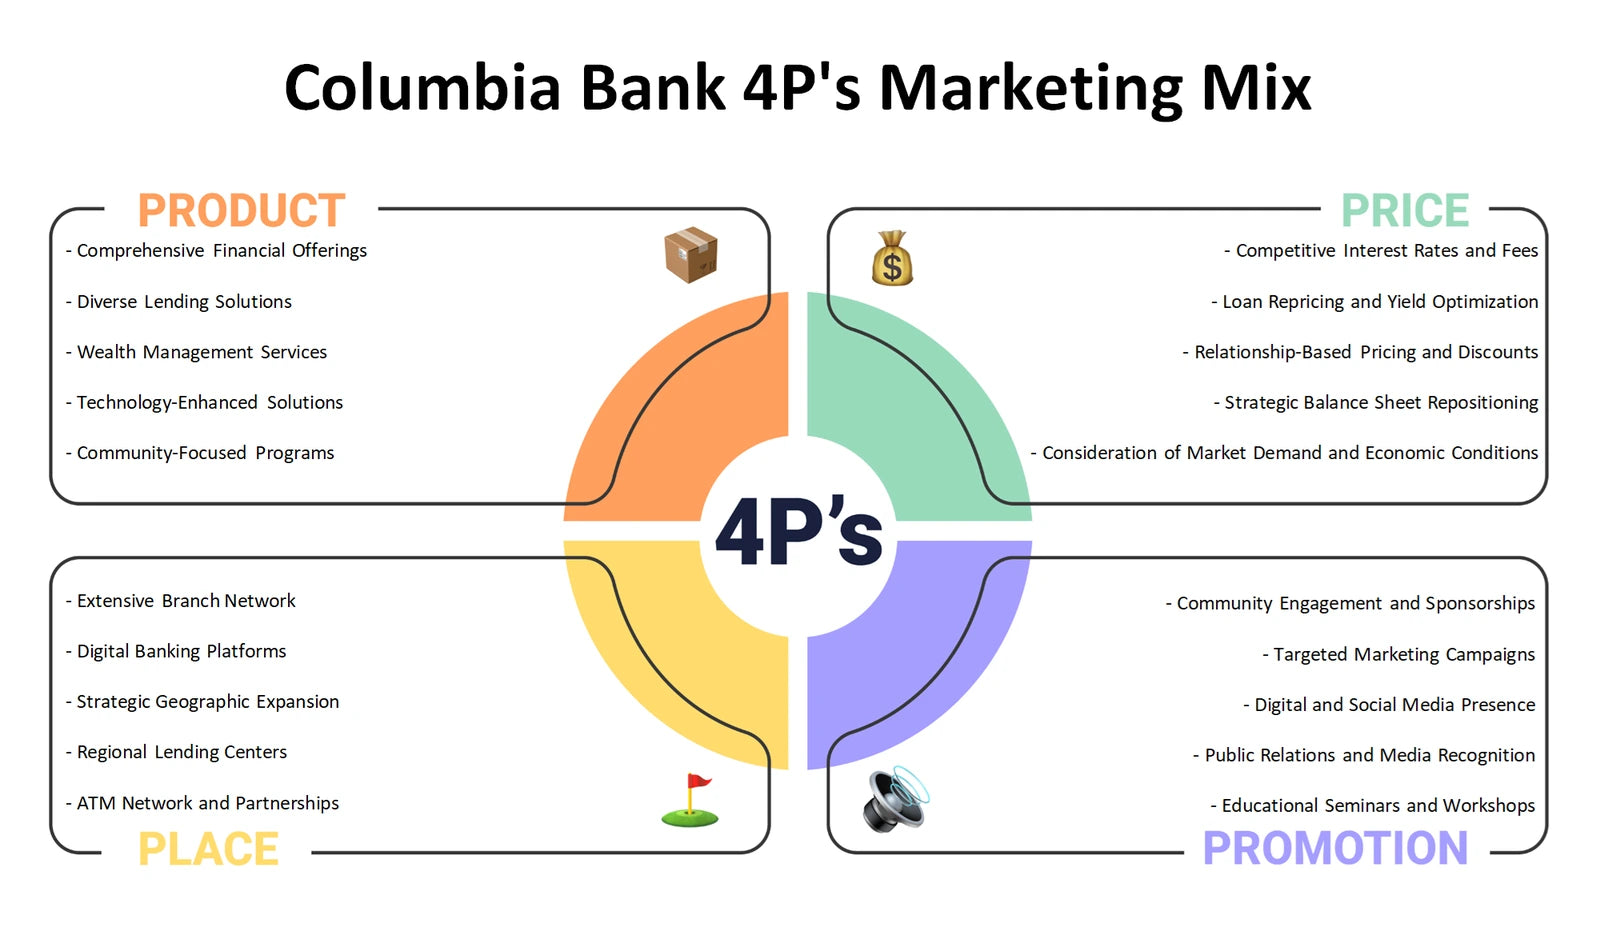
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter banking demand, customer expectations, compliance burdens, or operating costs?
Columbia Bank PESTLE analysis, also commonly called PESTEL, organizes external conditions that management cannot control but must interpret. Political factors include public-policy and supervisory priorities; economic factors include rate conditions, credit demand, deposit competition, and household or business resilience. Social factors can include confidence, financial literacy, and preferences for convenient service. Technological change raises questions around mobile functionality, fintech integration, fraud prevention, cybersecurity, and payment expectations. Legal considerations include consumer protection, privacy, and financial-crime obligations, while environmental conditions can affect borrowers, collateral, facilities, and continuity planning. The analysis distinguishes questions to monitor from claims that a specific change has already occurred.
- External signals. Separate policy, economic, social, technology, legal, and environmental developments so unlike risks are not merged into one broad trend.
- Banking relevance. Link each factor to customer affordability, trust, digital-service resilience, lending exposure, or the cost of compliance.
- Monitoring aid. Use the Excel structure to prioritize external topics for review and the Word analysis to add explanatory context to each strategic question.
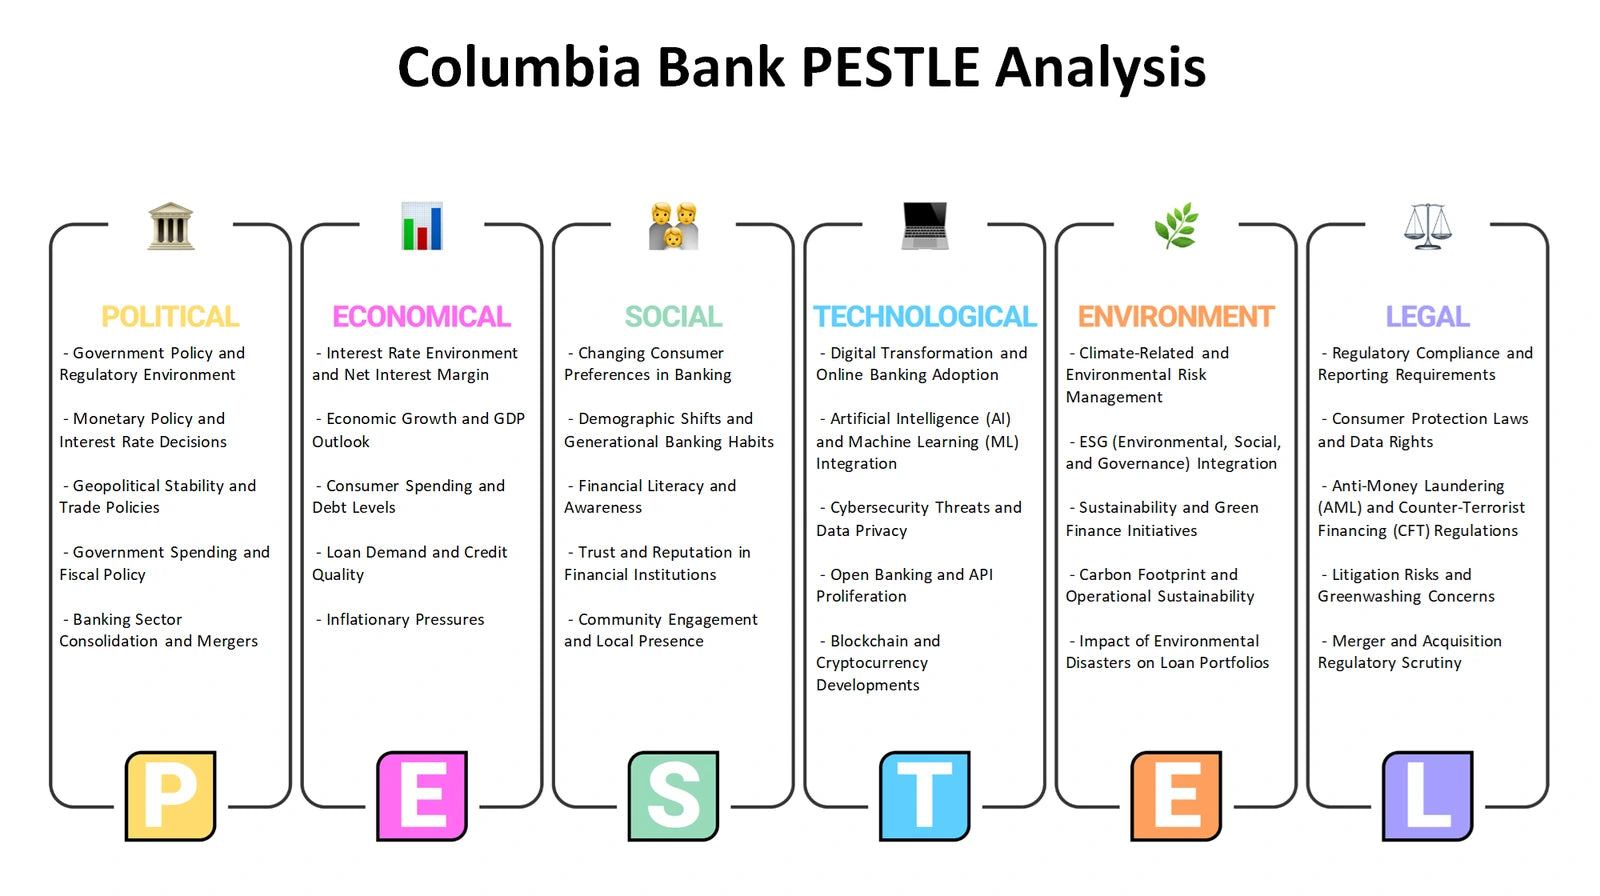
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which capabilities could support differentiation, and which external conditions could make those capabilities more or less valuable?
The Columbia Bank SWOT analysis separates internal strengths and weaknesses from external opportunities and threats. Potential internal themes to test may include customer relationships, digital-service capability, lending processes, partnership management, risk controls, and the ability to translate community connections into relevant service. These are not presented as established findings; the framework helps assess the evidence behind them. Opportunities may arise from changing customer preferences or better digital journeys, while threats may include intense competition, switching behavior, cyber risk, economic stress, or regulatory demands. Keeping internal and external factors distinct is important because a market opportunity is not automatically a company strength, and an external threat cannot be solved by messaging alone.
- Capability test. Identify possible strengths and constraints that could affect service quality, speed, trust, and execution.
- Strategic fit. Compare external opportunities and threats with the capabilities required to respond rather than treating every trend as equally actionable.
- Priority discussion. Populate the Excel SWOT grid with evidence and questions, then use the Word analysis to develop a balanced narrative around the most material combinations.
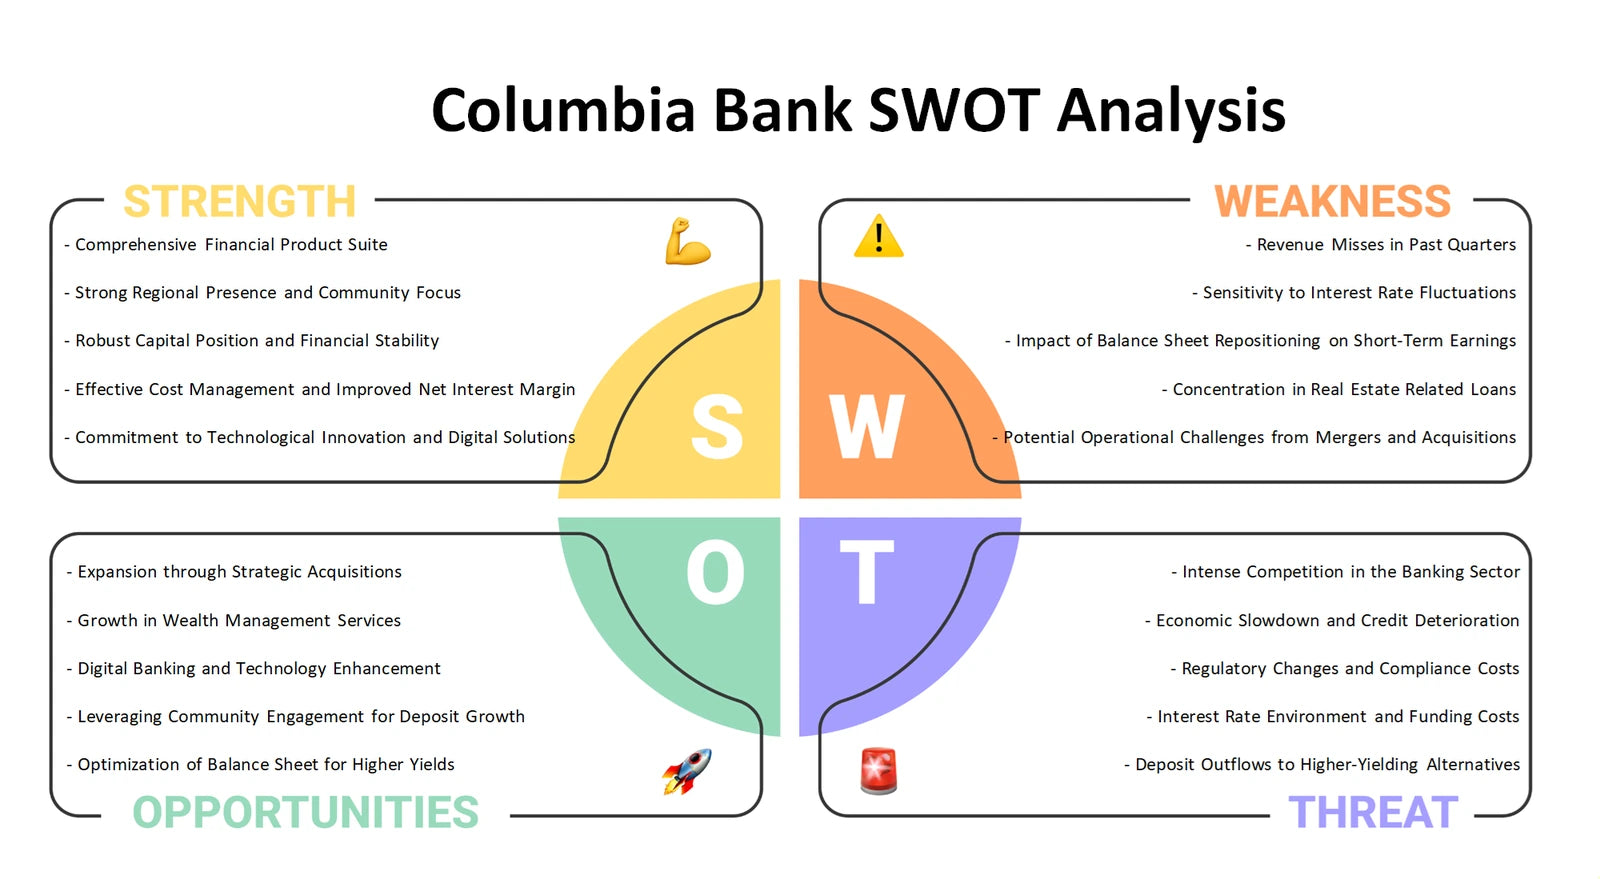
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Turn six lenses into better banking questions
Used together, the six perspectives move from portfolio focus and business-model logic to competitive pressure, customer-facing choices, external conditions, and organizational fit. The Excel frameworks provide a structured way to compare issues, while the detailed Word analyses help develop the reasoning behind them. For Columbia Bank, that combination can support more informed discussion of differentiation, digital service, customer retention, lending and deposit priorities, and the trade-offs involved in responding to change.
Company background: Columbia Bank — SEC company submissions profile for Columbia Banking System, Inc..