

Columbia Banking System: Banking Services and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Columbia Bank Strategy Analysis Bundle
Columbia Bank is the federally chartered savings-institution business within Columbia Financial, Inc. This bundle is written for that banking context, rather than for other institutions using the Columbia Bank name. It helps examine consumer and business banking relationships, deposit and lending priorities, service delivery, and the operating choices that influence a regulated financial institution's resilience.
Columbia Financial, Inc. reported consolidated GAAP net income of USD 13.099 million for the three months ended March 31, 2026, filed on May 11, 2026. That parent-group snapshot does not establish standalone bank results or file-update timing, but it makes capital allocation, digital-service investment, and risk-aware growth useful questions for the six analyses.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking activities merit scarce capital, management attention, and technology investment as market conditions change?
The Columbia Bank BCG Matrix provides a disciplined way to compare a banking portfolio using market growth and relative market share, rather than assuming every product deserves the same resources. It can help frame deposit gathering, lending categories, relationship services, and digital capabilities as potential portfolio areas to investigate. The Star, Cash Cow, Question Mark, and Dog categories are analytical criteria, not claims about Columbia Bank's actual positions. This matters when leadership must protect dependable earnings capacity while deciding where measured investment may improve customer relevance or operating resilience.
- Portfolio comparison. Examine whether different banking activities face contrasting growth conditions and relative competitive positions.
- Resource discipline. Consider the trade-off between maintaining mature relationship economics and funding areas that may require investment before producing returns.
- Framework application. Use the Excel matrix to organise candidate activities, then use the Word analysis to document assumptions and questions behind each priority.
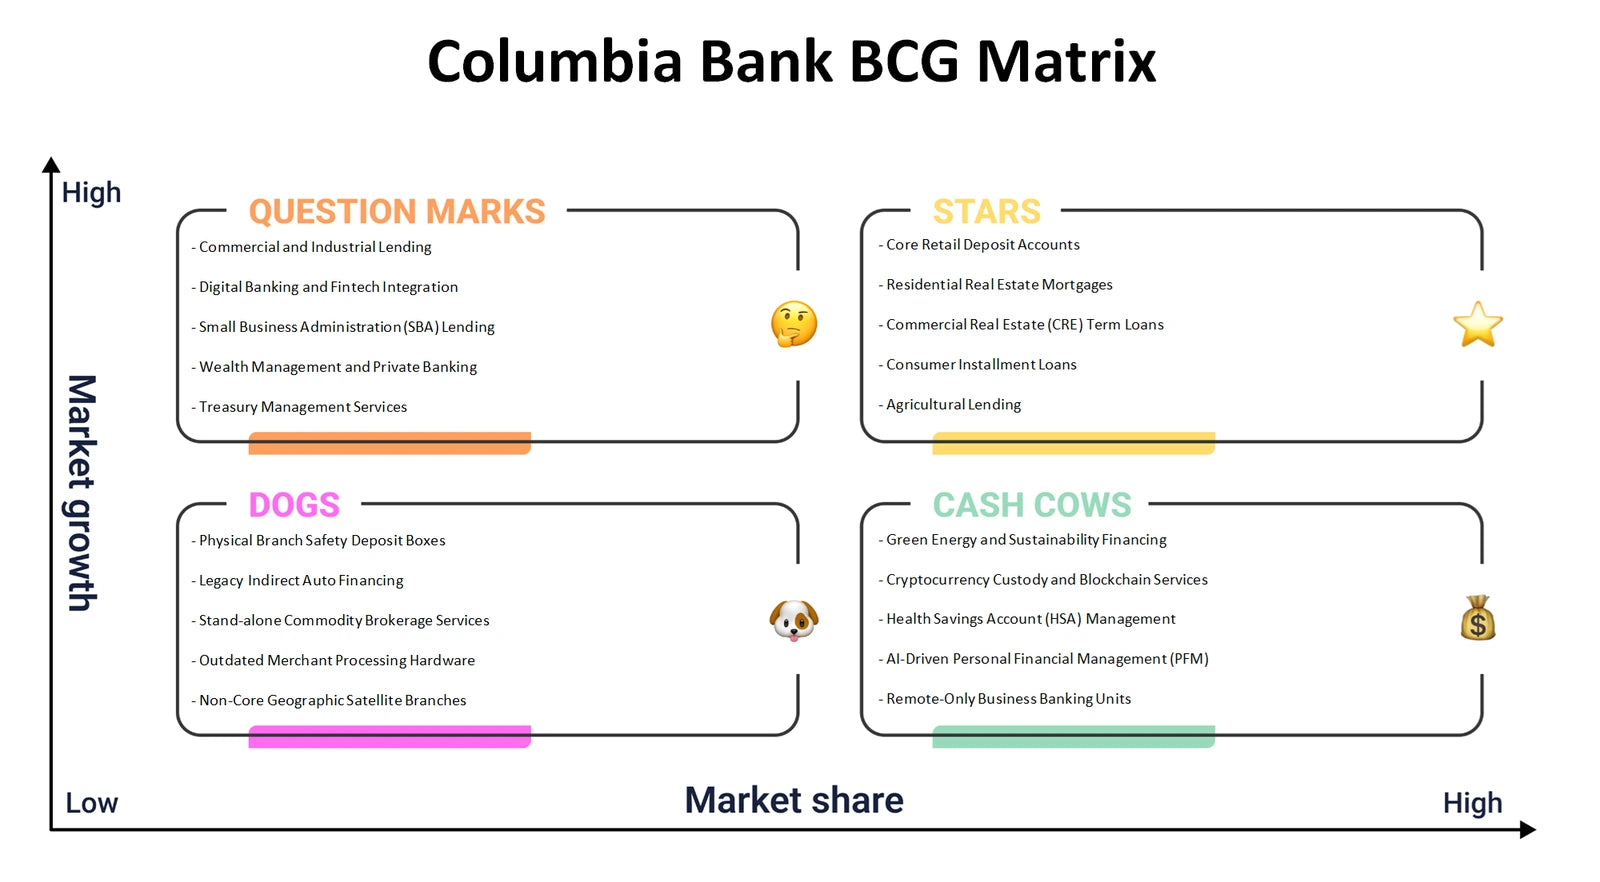
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, banking services, partnerships, and costs fit together to create sustainable value?
The Columbia Bank Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships, and cost structure. For a savings institution, the framework helps test the links among relationship banking, service access, lending and deposit economics, technology capabilities, compliance work, and external providers. It is particularly useful for considering how digital tools or correspondent relationships could support a wider service proposition without obscuring the control, integration, and cost implications that a regulated bank must manage.
- Customer-value fit. Map how consumer and business customer needs may differ in service expectations, relationship depth, and channel use.
- Economic connections. Trace how revenue logic, operating activities, resources, partnerships, and cost structure influence one another.
- Model workshop. Populate the Excel canvas as a working map, then consult the Word analysis for fuller context on the choices and dependencies to discuss.
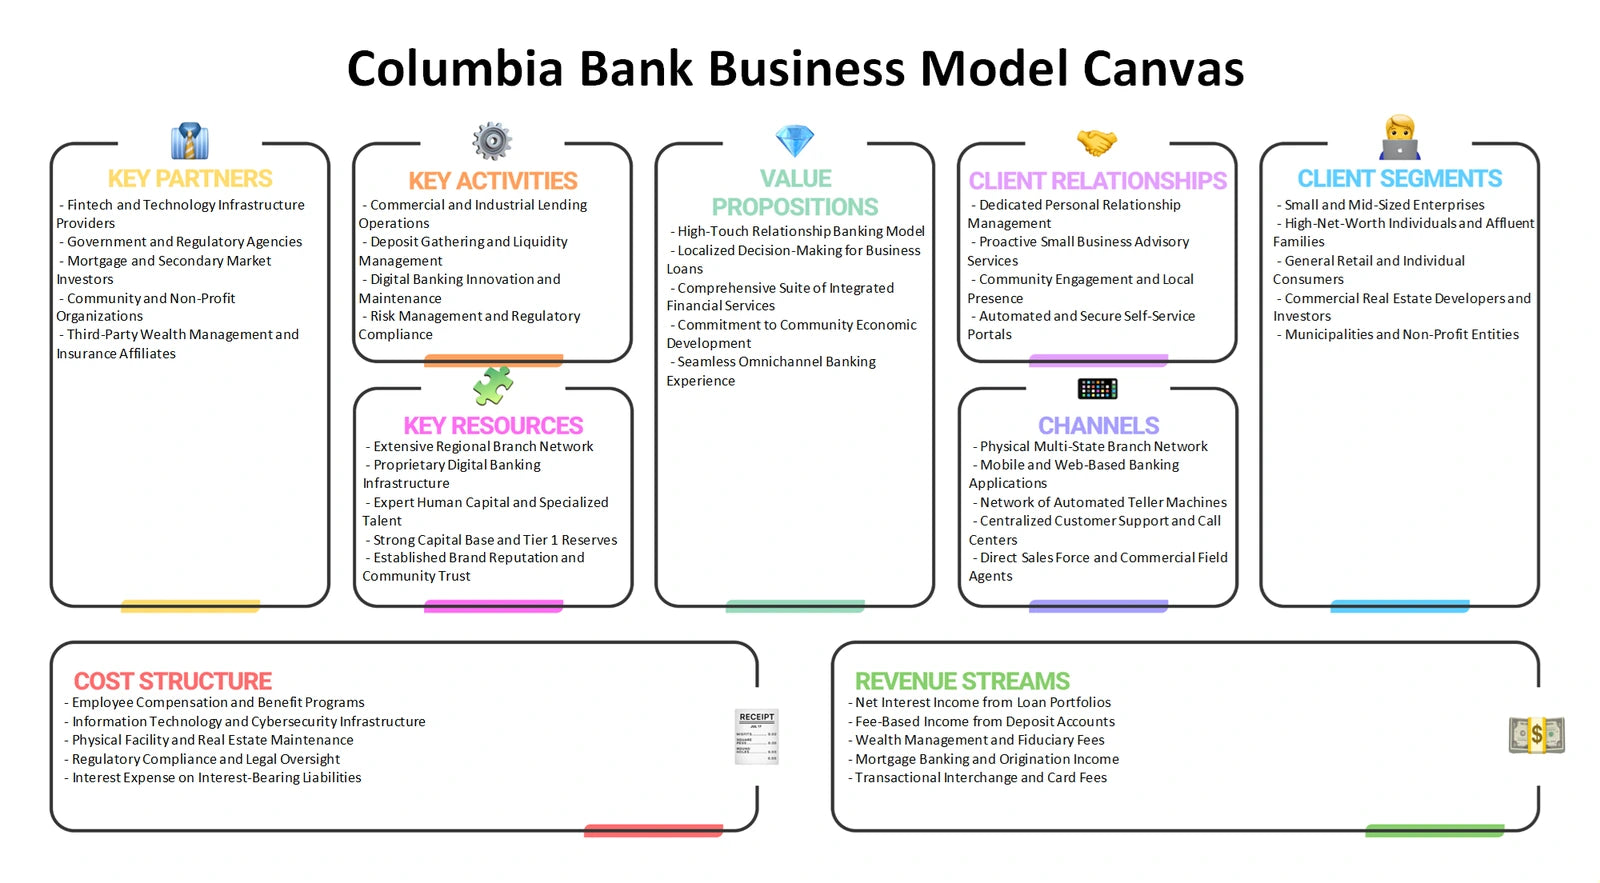
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Where do competitive and bargaining pressures most affect Columbia Bank's ability to retain relationships and earn acceptable returns?
Columbia Bank Porter's Five Forces examines the competitive environment around a federally chartered savings institution. Rivalry can arise from banks competing for deposits, loans, and customer trust; buyer power reflects customers' ability to compare providers or move balances; and supplier power can include technology, data, payment, and specialist-service dependencies. The analysis also considers new entrants, including digitally enabled financial providers, and substitutes such as non-bank payment, credit, investment, or cash-management options. It does not assign force scores or name competitors; instead, it provides a structured basis for asking where resilience and differentiation require attention.
- Relationship pressure. Assess how switching options and rate-sensitive decisions can alter customer bargaining power across banking needs.
- Dependency exposure. Consider whether critical vendors, networks, or specialist capabilities could affect service continuity, cost, or negotiating leverage.
- Evidence trail. Use the Excel framework to compare each force, while the Word analysis supports narrative interpretation of pressure points and open questions.
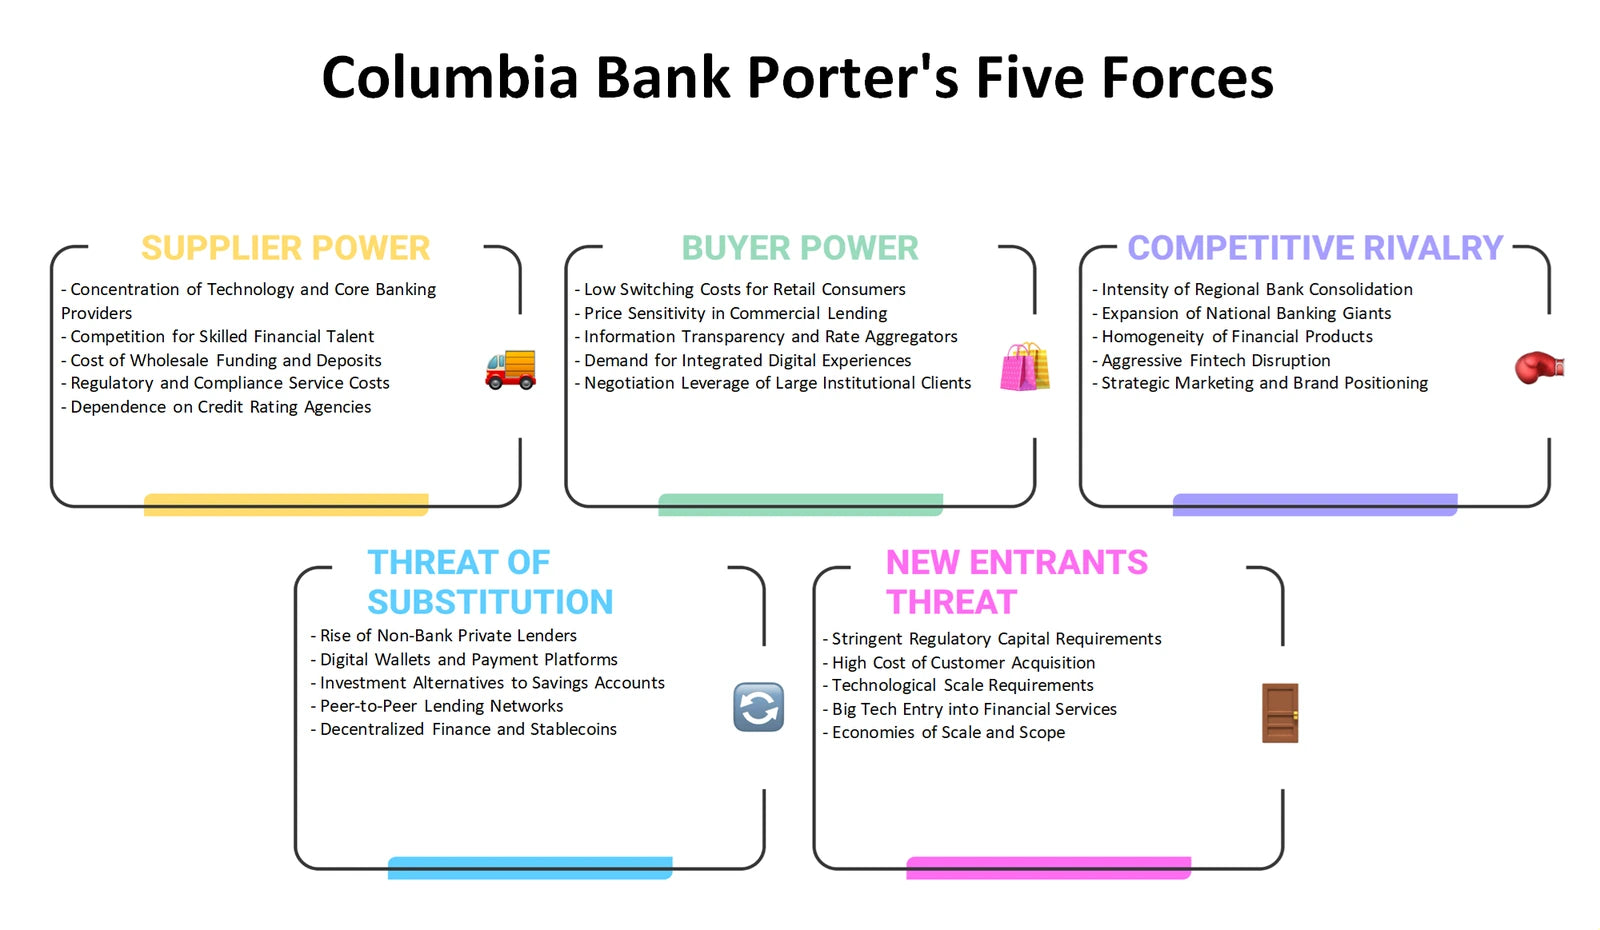
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking offers, pricing logic, access routes, and communications work together without weakening trust or compliance?
The Columbia Bank Marketing Mix applies Product, Price, Place, and Promotion to a regulated financial-services setting. Product analysis can distinguish the banking needs being addressed; Price considers rates, fees, and value communication without assuming particular prices; Place reviews branch, digital, and relationship-led routes to customers; and Promotion explores how clear, responsible communication can support understanding and trust. The lens is useful because a channel decision affects more than marketing reach: it can alter service workload, data expectations, accessibility, customer relationships, and the perceived value of the institution's offer.
- Offer architecture. Compare how banking products and supporting services may meet different relationship, convenience, and financial-management needs.
- Channel coherence. Examine whether physical, digital, and relationship channels reinforce a consistent customer experience.
- Planning support. Use the Excel 4Ps layout to organise choices and trade-offs, with the Word analysis adding company-relevant discussion for review.
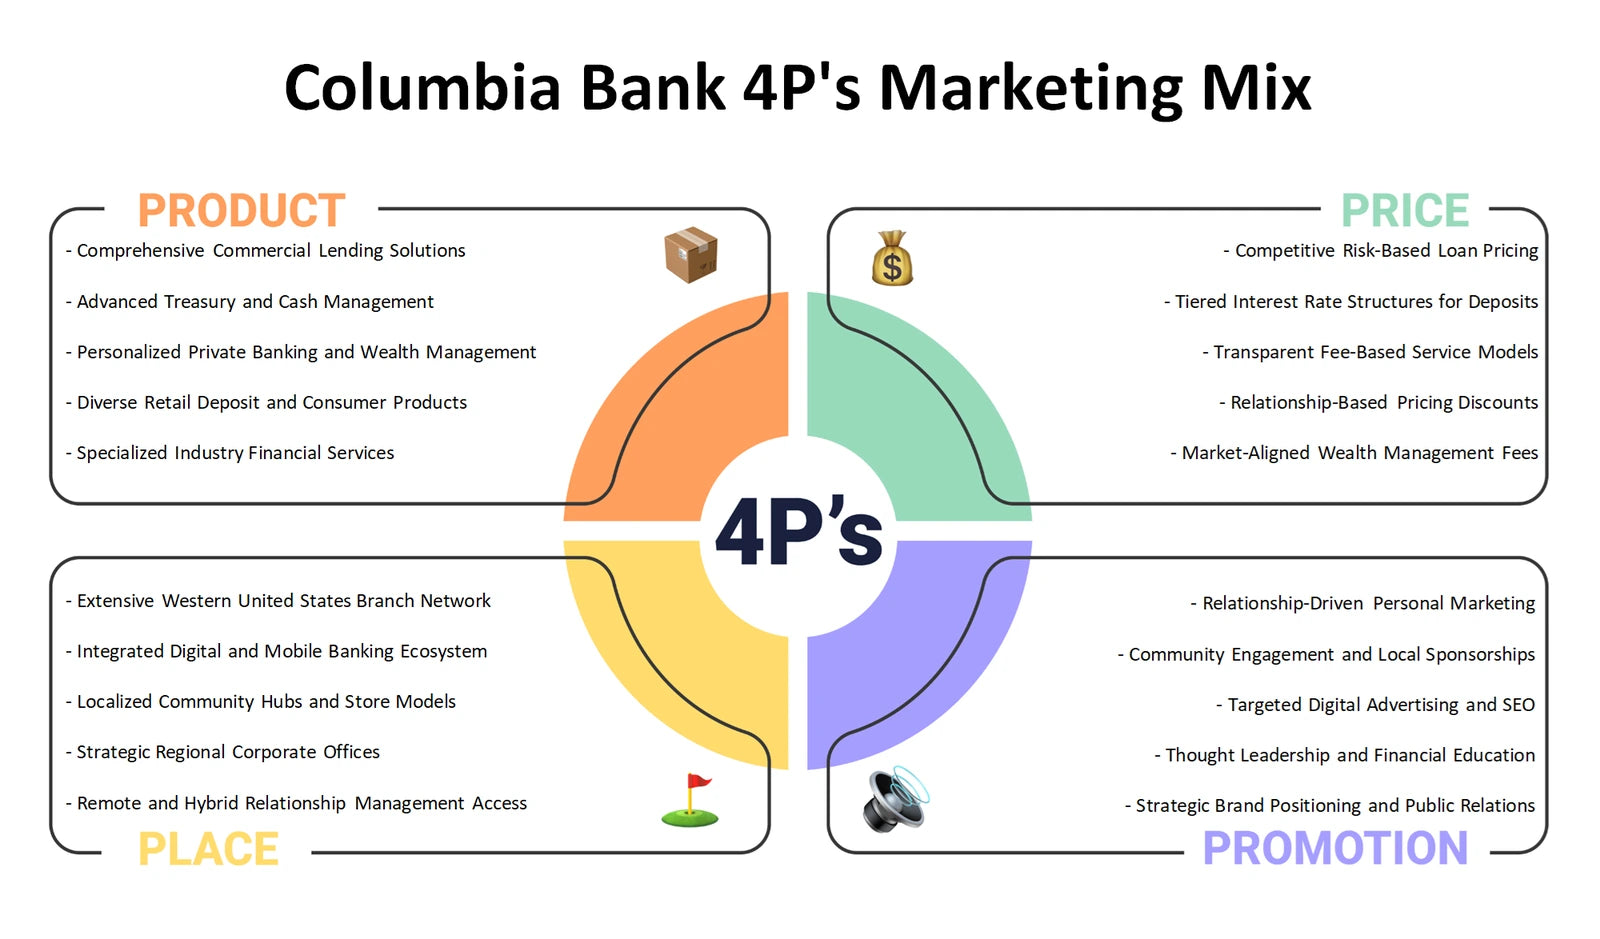
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter banking demand, funding conditions, technology expectations, or the cost of operating responsibly?
The Columbia Bank PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal, and Environmental influences. For a federally chartered savings institution, political and legal questions can affect supervisory expectations and consumer protection; economic conditions can influence borrowing, saving, credit performance, and funding decisions; and social expectations can change how customers value convenience and advice. Technology raises questions about cybersecurity, automation, data governance, and vendor dependence. Environmental factors may affect physical operations, collateral, and risk assessment. These are categories for structured evaluation, not assertions that a particular law, rate, or event has already changed Columbia Bank's position.
- External scan. Separate broad macroeconomic questions from legal, technology, customer-behaviour, and environmental developments that merit monitoring.
- Resilience lens. Connect outside shifts to possible effects on customer needs, operating controls, credit decisions, and investment timing.
- Monitoring tool. Record external factors in the Excel framework and use the Word analysis to develop a reasoned discussion of relevance and uncertainty.
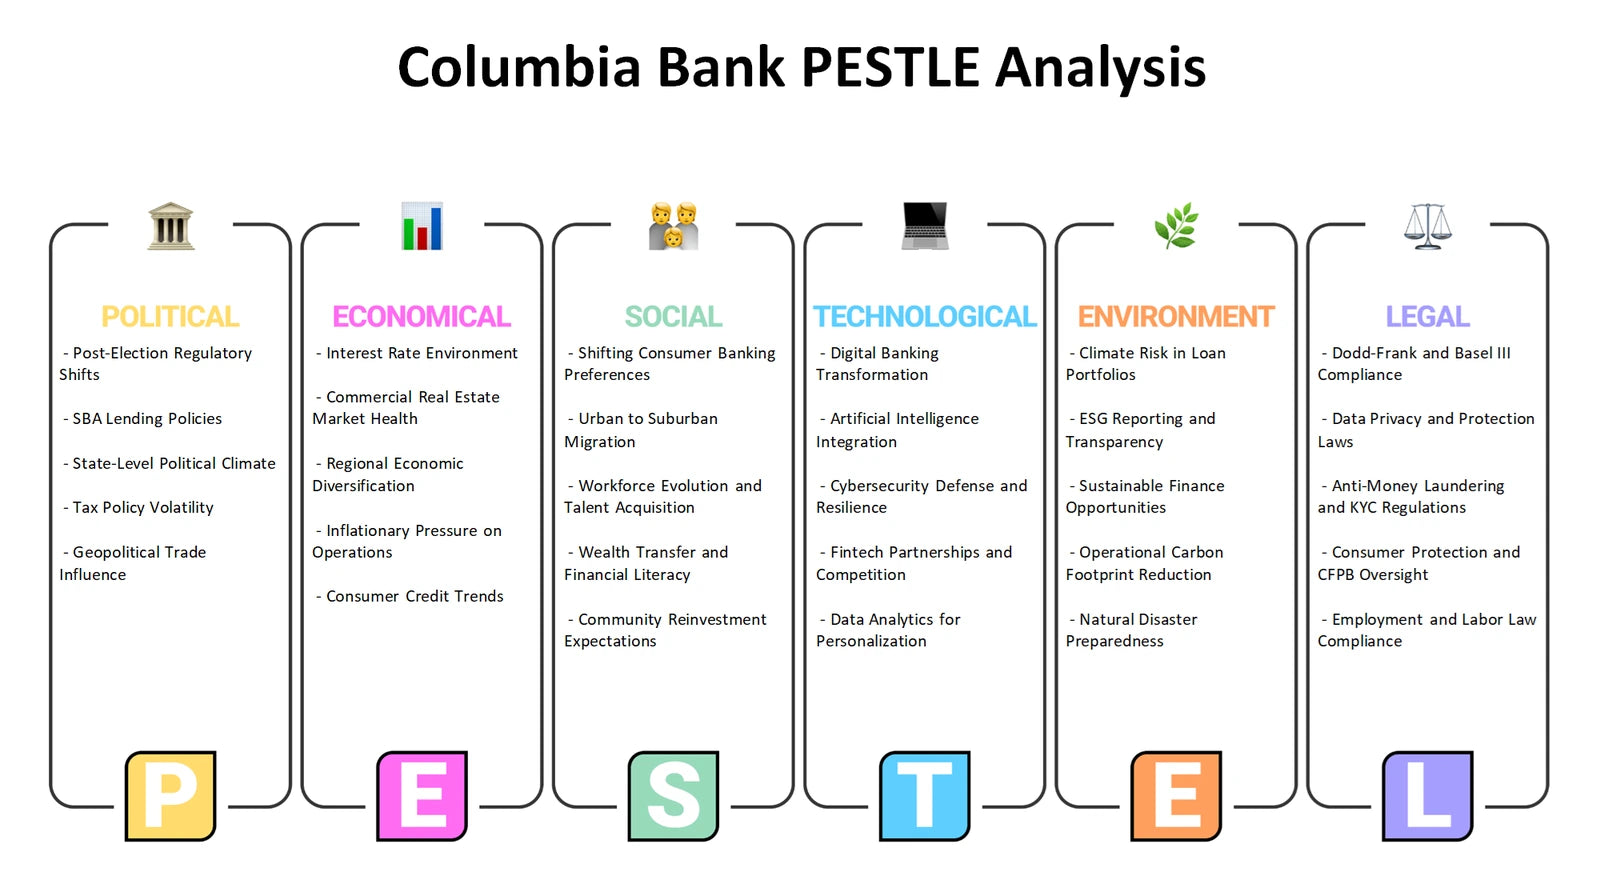
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Columbia Bank connect internal capabilities and constraints with external opportunities and threats?
The Columbia Bank SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. This distinction is valuable when evaluating a banking organisation whose strategic options depend on governance, operating capability, customer relationships, technology, risk management, and resource availability as well as market conditions. Potential strengths or weaknesses should be tested as internal evidence, while opportunities and threats should be considered as external conditions such as changing customer expectations, competitive alternatives, or policy and economic uncertainty. The framework does not present plausible themes as proven findings; it helps users organise evidence before deciding which issues deserve action or further diligence.
- Internal reality check. Identify capabilities and constraints that may influence service delivery, risk control, investment capacity, and execution.
- External alignment. Relate market openings and threats to the institution's ability to respond without confusing outside conditions with internal attributes.
- Decision synthesis. Use the Excel grid to prioritise relationships among issues, then use the Word analysis to build a concise strategic rationale.
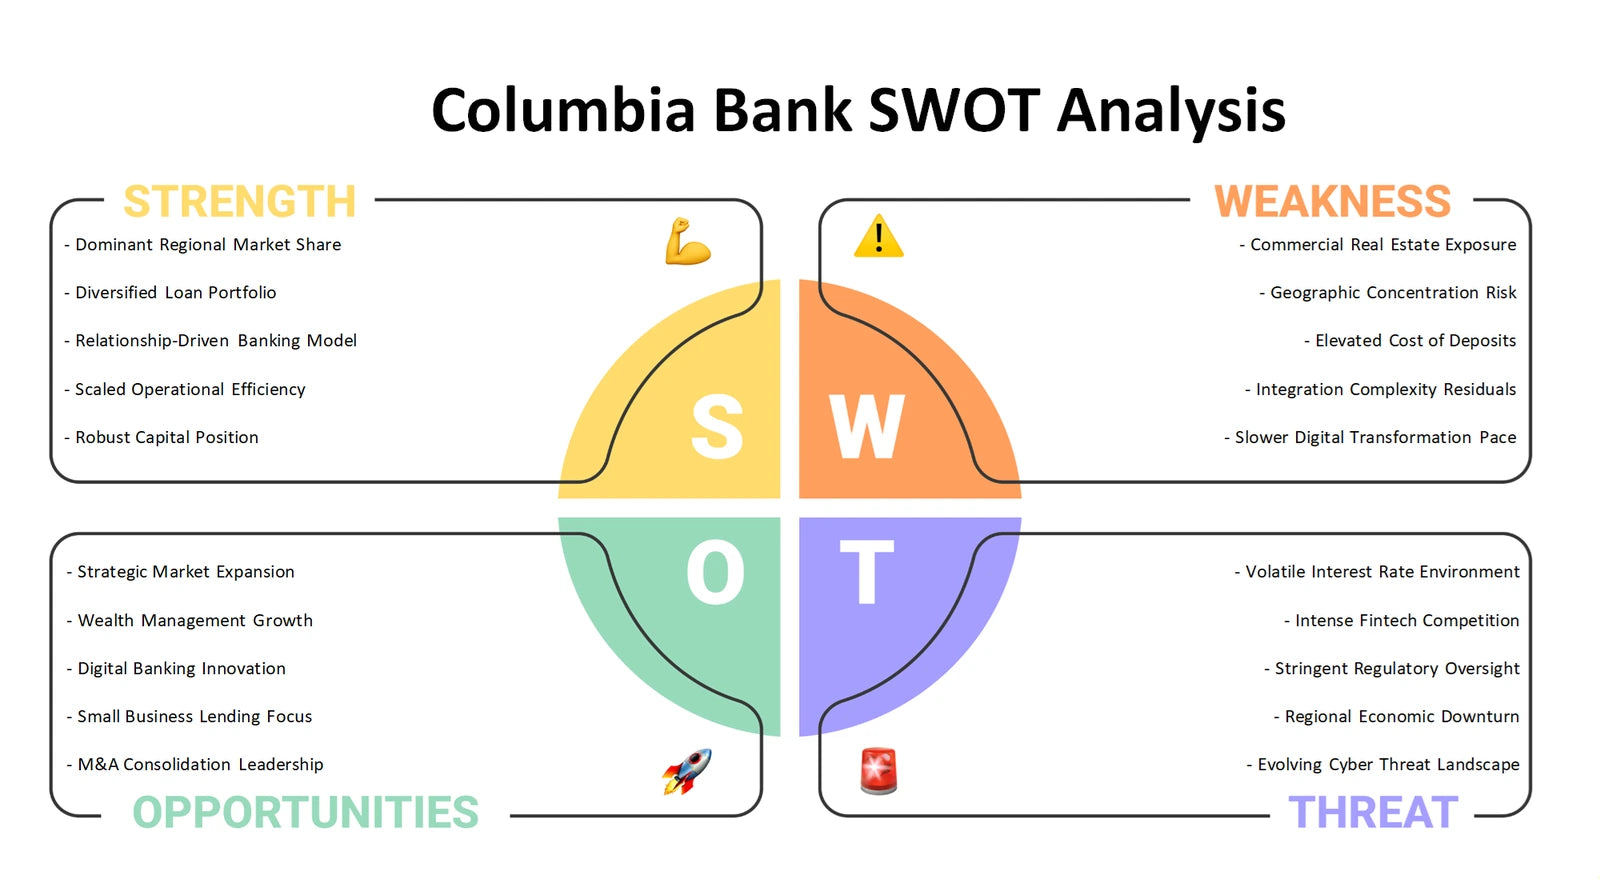
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more resilient banking strategy discussion
Together, the six perspectives move from portfolio focus and business-model economics to competitive pressure, customer-facing choices, external change, and internal readiness. The Excel frameworks help organise comparisons and working assumptions, while the Word files provide detailed company-analysis context for developing more structured conversations about Columbia Bank's priorities, resource allocation, and resilience.
Company background: Columbia Bank — Columbia Financial, Inc. SEC issuer submissions profile.