

Columbia Banking System: Banking Services, Competition and Customer Choice – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Columbia Bank Strategy Analysis Bundle
Columbia Bank is the name used for this bundle. Its supported reporting context is Columbia Banking System, Inc., a U.S. bank holding company recorded in SEC data under SIC 6022, State Commercial Banks. The relevant operating context includes banking relationships around deposits, credit, payments and digital access, with technology, software, core-banking, cybersecurity and payment-network partnerships important to dependable service delivery.
In its 2025 Form 10-K filed February 26, 2026, the parent group reported consolidated revenue of USD 177 million for the year ended December 31, 2025. Its Form 10-Q filed August 4, 2026 reported GAAP net income of USD 208 million for April through June 2026. The bundle helps examine the economics behind growth, digital-service investment priorities and the competitive pressures affecting customer relationships.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Columbia Bank service priorities merit investment, protection, selective testing or disciplined rationalisation?
A Columbia Bank BCG Matrix helps organise banking propositions, customer-serving initiatives or operating investments around two deliberately different measures: market growth and relative market share. It does not presume that a lending, deposit, payment or digital-service activity belongs in a particular quadrant. Instead, it provides a structured way to compare where growth may consume capital and technology capacity against where established relationships may generate dependable economic contribution. The familiar Stars, Cash Cows, Question Marks and Dogs categories become prompts for testing resource priorities rather than labels applied without evidence.
- Growth versus position. Compare a service area's addressable growth with its relative standing, while separating market opportunity from internal operating performance.
- Capital discipline. Consider whether customer acquisition, digital capability, payment access and risk-management spending support a credible economic role in the wider portfolio.
- Scenario worksheet. Use the Excel framework to map alternative portfolio assumptions, then use the detailed Word analysis to document the evidence and decision questions behind each placement.
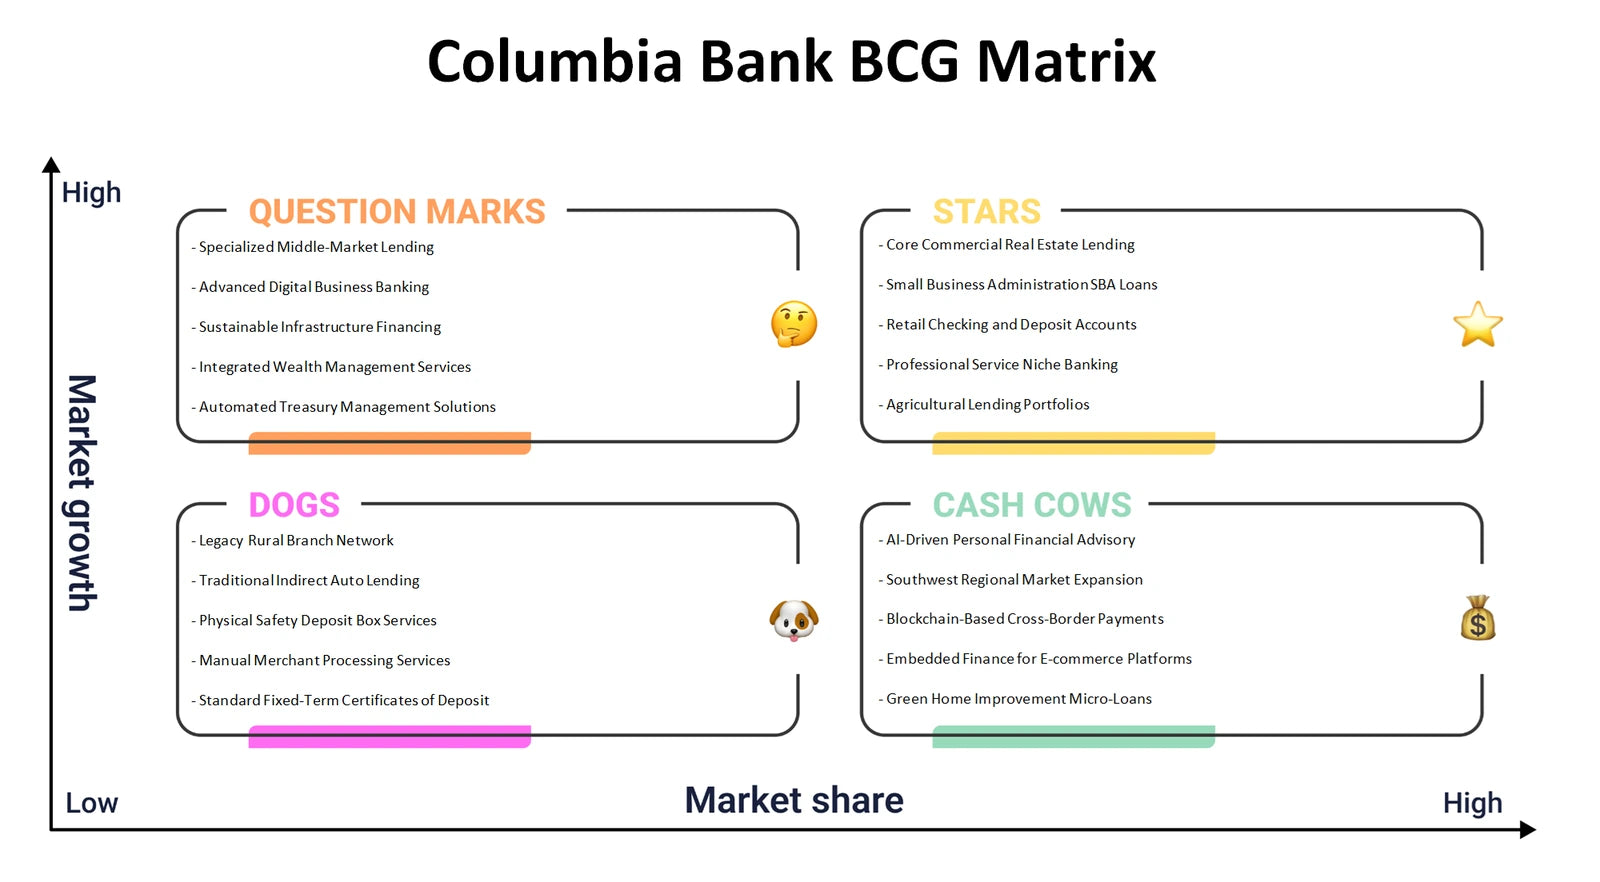
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer trust, digital delivery and payment infrastructure connect to the economics of the banking group?
The Columbia Bank Business Model Canvas examines the links between customer segments, value propositions, channels and customer relationships, then follows those choices into revenue streams and cost structure. It also brings together the key resources, key activities and key partnerships required to provide reliable banking access. This matters because technology providers, cybersecurity capabilities, core systems and payment rails are not simply support functions: they can shape service quality, operating resilience and the cost of serving customers. The canvas helps make those dependencies visible alongside the ways a regulated banking relationship can earn revenue.
- Customer-value logic. Test how different customer needs may relate to accessible account, credit, payment and digital-banking propositions without assuming every segment needs the same relationship model.
- Operating architecture. Connect key activities and resources to partners such as software providers, card networks and ACH infrastructure, while considering the cost implications of resilience and security.
- Linkage check. Populate the Excel framework block by block and use the detailed Word analysis to review whether channel, partnership, revenue and cost assumptions fit together.
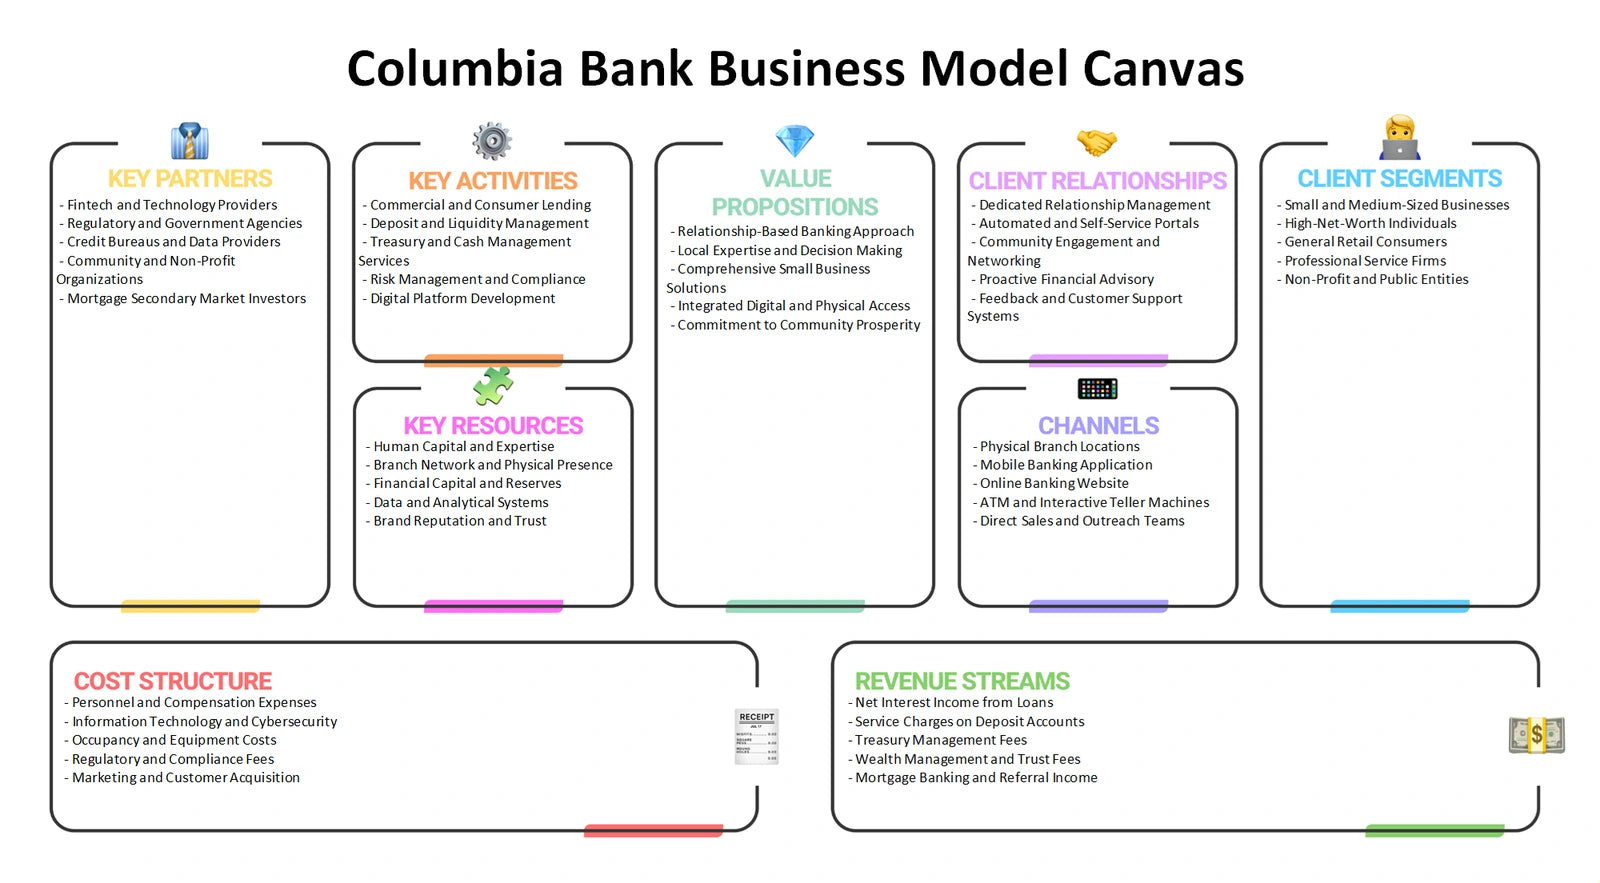
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the cost, attractiveness and durability of Columbia Bank customer relationships?
Columbia Bank Porter's Five Forces focuses on the banking environment around the group rather than assigning unsupported scores to individual competitors. Rivalry can influence pricing, service expectations and digital experience. Buyer power considers customers' ability to compare providers or move balances and borrowing relationships. Supplier power is relevant where technology, cybersecurity, data, card-network or payment-infrastructure partners are important. The framework also tests the threat of new entrants and the threat of substitutes, including non-bank ways customers can make payments, save, borrow or manage financial needs.
- Relationship switching. Examine how trust, convenience, pricing transparency and digital functionality may influence customer retention and acquisition economics.
- Partner dependency. Assess where concentrated technology or payment relationships could create bargaining leverage, service constraints or resilience considerations.
- Pressure map. Use the Excel framework to record evidence and counterarguments for each force, then use the detailed Word analysis to interpret their implications for banking strategy.
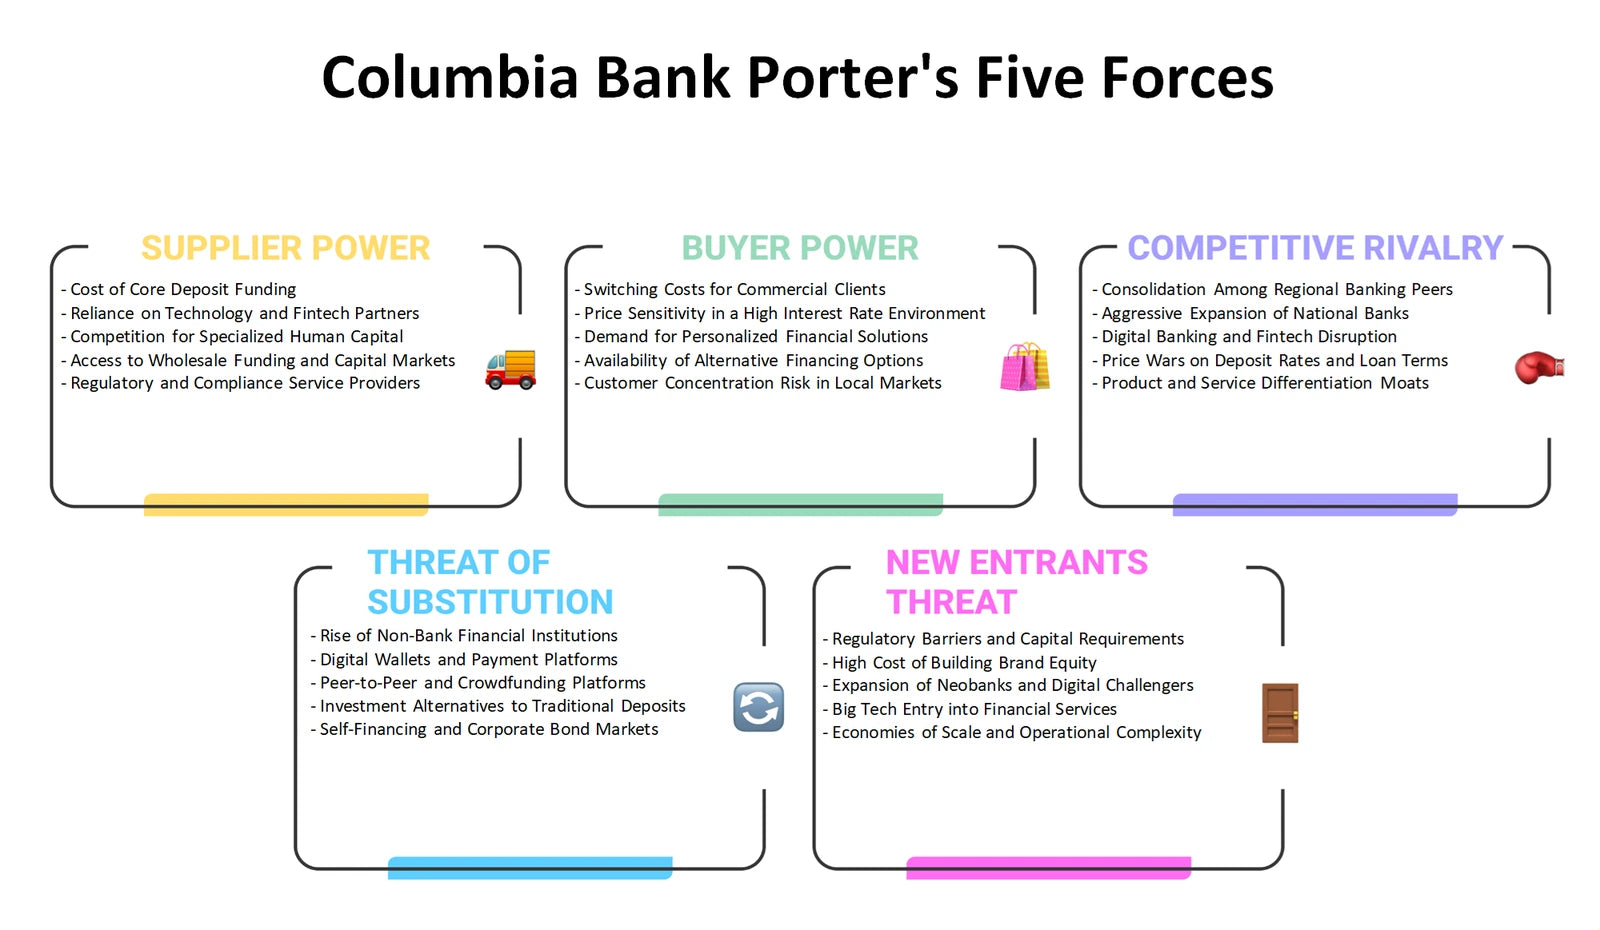
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Columbia Bank align its banking offer, economic terms, access routes and communications with customer expectations?
The Columbia Bank Marketing Mix applies Product, Price, Place and Promotion to a regulated financial-services setting. Product can cover the fit between banking needs and account, credit, payment or digital-access propositions. Price asks how rates, fees and relationship economics are framed, while recognising that customer value is broader than a headline charge. Place considers the balance of digital and person-to-person access where relevant. Promotion examines how service benefits, security and eligibility can be communicated clearly without overstating what customers receive.
- Offer clarity. Compare product features with the practical needs of customers who value convenient transactions, secure access and responsive banking support.
- Channel economics. Explore how digital servicing and other customer routes may affect acquisition cost, relationship depth and the resources needed to deliver consistent experiences.
- Decision brief. Use the Excel framework to organise the four Ps by audience and proposition, then use the detailed Word analysis to add rationale, risks and communication questions.
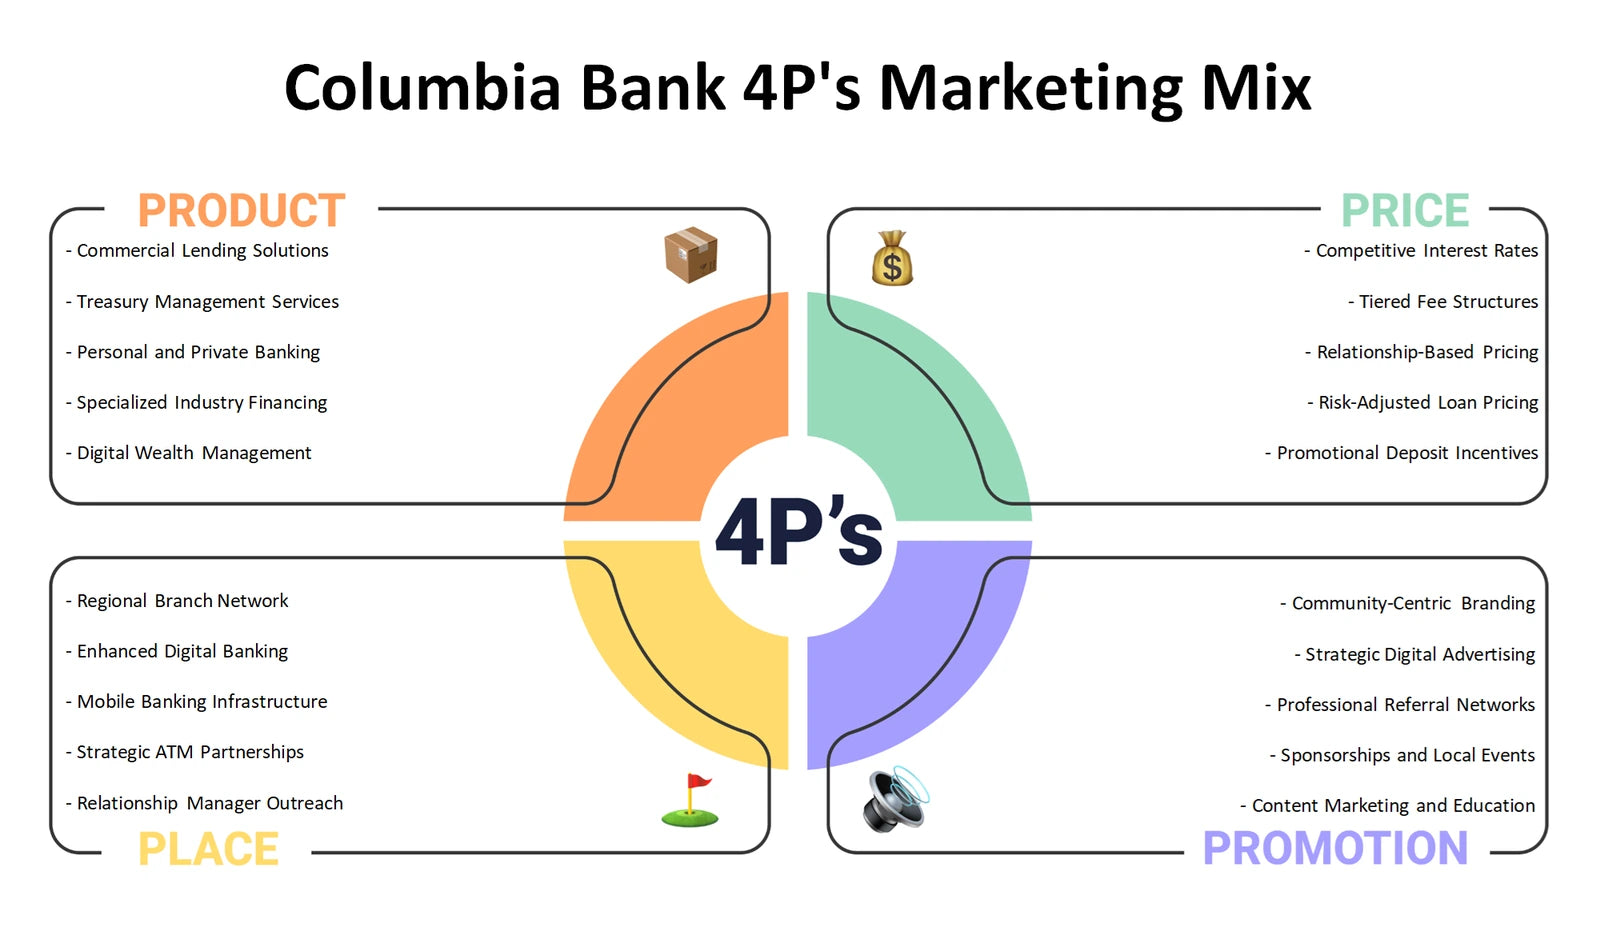
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should be monitored when evaluating Columbia Bank's growth economics and operating resilience?
A Columbia Bank PESTLE analysis, also commonly called PESTEL, separates external forces from internal performance assumptions. Political conditions can shape supervisory priorities and public-policy debate; economic conditions can affect credit demand, funding costs and borrower capacity. Social expectations matter as customers weigh convenience, trust and digital confidence. Technological change raises questions about cyber resilience, core systems and payments innovation. Legal requirements influence consumer protection, compliance and data handling, while environmental conditions can affect physical operations, collateral exposure and risk assessment. The framework tests these influences rather than claiming a particular law, rate or policy change has already occurred.
- External signal set. Identify political, economic and social developments that may alter customer needs, credit conditions or the cost of operating responsibly.
- Resilience lens. Consider technological, legal and environmental exposures alongside the partnerships and controls needed for secure, dependable financial services.
- Signal log. Use the Excel framework to track external assumptions and potential impact, then use the detailed Word analysis to add company-relevant context and monitoring prompts.
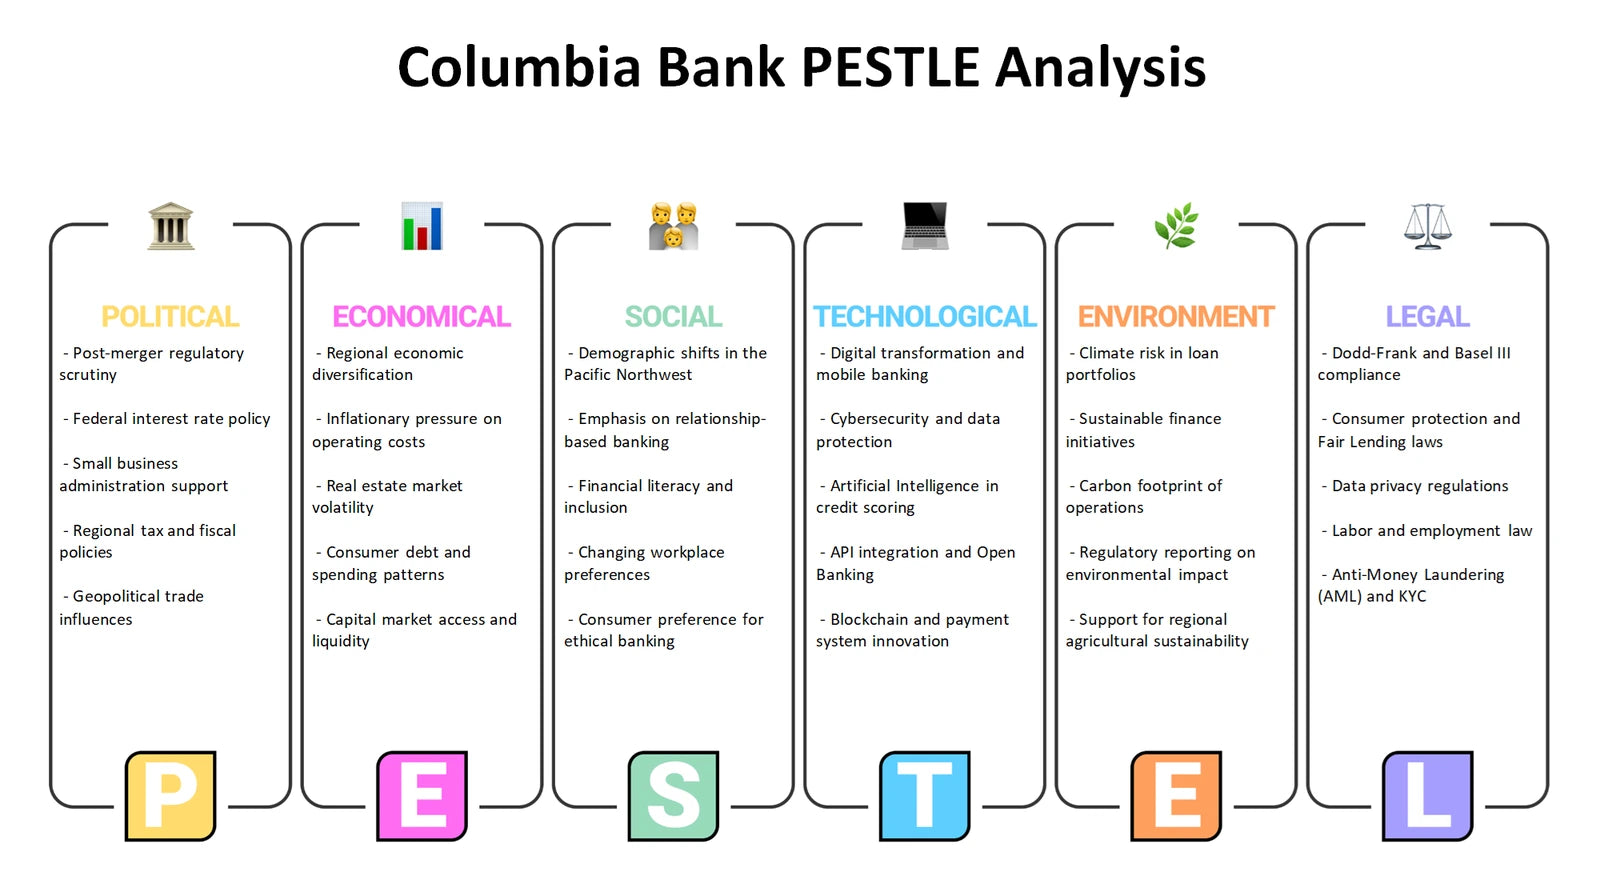
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside external banking opportunities and threats?
The Columbia Bank SWOT analysis distinguishes internal strengths and weaknesses from external opportunities and threats. Potential strengths to investigate may include customer relationships, banking know-how, payment capability or technology partnerships; they should not be treated as established advantages without supporting evidence. Potential weaknesses may involve cost, execution complexity, legacy-system dependence or control burdens. Opportunities arise outside the organisation through changing customer needs or service gaps, while threats can include competition, substitutes, cyber risk, economic stress and regulatory change. This separation helps prevent an external market shift from being misclassified as an internal capability.
- Capability test. Examine whether resources, operating processes and partner relationships can support the service experience required by targeted customer relationships.
- Boundary discipline. Keep internal limitations distinct from external pressures so that management questions do not collapse opportunity, threat and execution risk into one statement.
- Action boundary. Use the Excel framework to classify evidence by SWOT category and use the detailed Word analysis to develop balanced hypotheses for review.
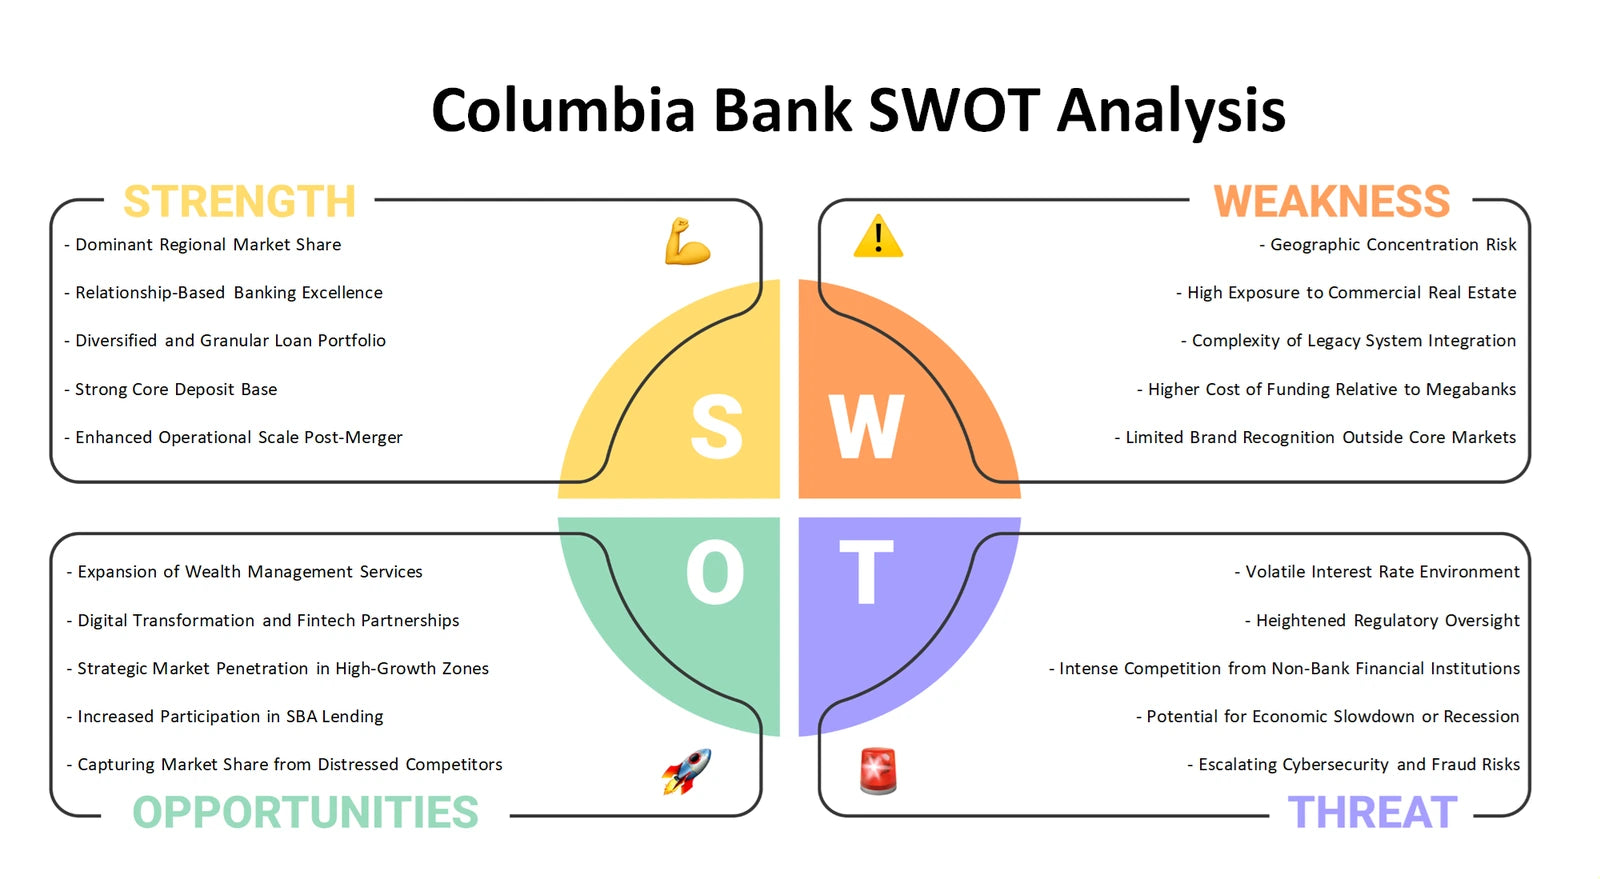
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices to the economics of banking relationships
Together, the six perspectives move from portfolio priorities and value creation to industry pressure, customer-market choices, external change and strategic fit. The Excel frameworks provide structured places to compare assumptions, while the detailed Word analyses help develop the reasoning behind them. For Columbia Bank, this combination is useful when digital investment, payment infrastructure, customer trust, risk controls and sustainable economic contribution need to be considered as connected decisions.
Company background: Columbia Banking System, Inc. — SEC company submissions profile.