

CNO Financial Group: Financial Services and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
CNO Financial Group Strategy Analysis Bundle
CNO Financial Group is a U.S. insurance holding company whose branded operations, including Bankers Life, Colonial Penn and Washington National, address distinct demographic and distribution segments. Its life, health and annuity-related protection business makes the connection between underwriting, policyholder service, distribution and capital management central to strategic decision-making.
In its Q2 2026 Form 10-Q filing materials, CNO Financial Group, Inc. reported consolidated revenue of USD 1,285.2 million and GAAP net income of USD 125.9 million for April 1 through June 30, 2026, filed August 6, 2026. These quarterly figures are a dated context snapshot, not evidence that the downloadable files changed in 2026. They sharpen questions about capital priorities, underwriting and reinsurance economics, and the role of branded channels in reaching customers.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance propositions or distribution-led businesses deserve the greatest strategic attention?
A CNO Financial Group BCG Matrix helps separate portfolio choices from brand preference. It uses market growth and relative market share to compare relevant insurance product families, customer propositions or distribution businesses, then frames Stars, Cash Cows, Question Marks and Dogs as analytical categories rather than positions already assigned to CNO. That distinction matters when underwriting capacity, service investment and capital each have an opportunity cost.
- Comparison basis. Define the market and comparable business unit before interpreting growth or relative-share position.
- Capital discipline. Test whether a unit merits further funding, repositioning, harvesting attention or closer review alongside risk constraints.
- Working view. Use the Excel framework to structure comparisons and the Word analysis to document assumptions, evidence and portfolio implications.
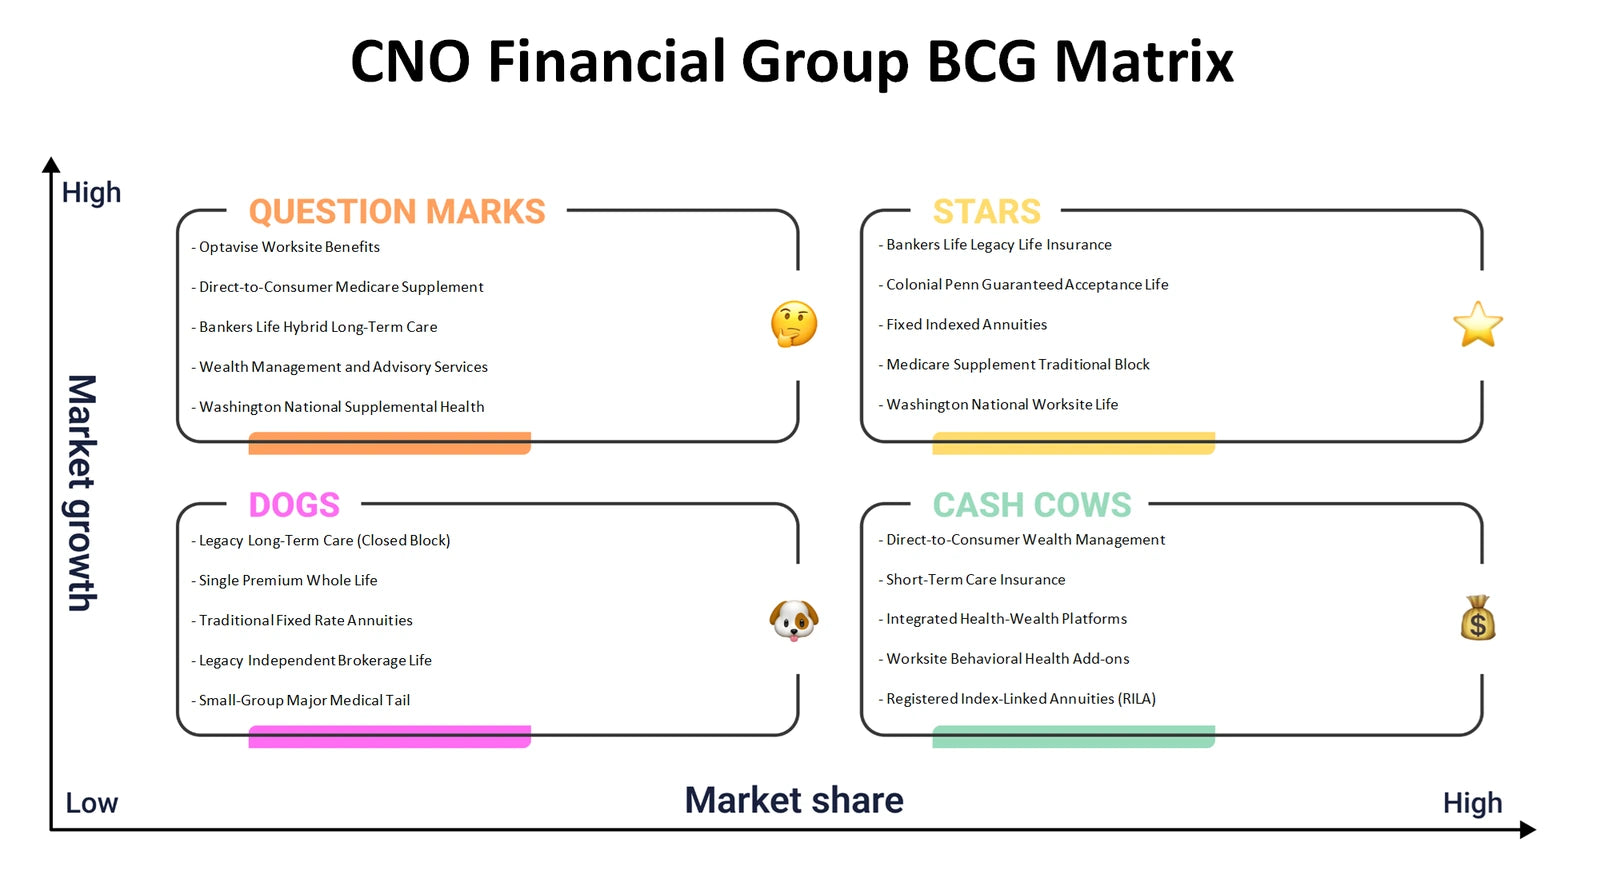
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do CNO's customer needs, branded channels, insurance economics and risk partners fit into one operating model?
A CNO Financial Group Business Model Canvas links customer segments and value propositions to channels and customer relationships, then connects revenue streams with key resources, key activities, key partnerships and cost structure. For an insurer, this helps avoid treating distribution as separate from underwriting, policy servicing, reserves, capital and risk transfer. Reinsurance relationships can be examined as partnerships that may affect capacity, pricing assumptions and earnings stability.
- Customer connection. Compare how Bankers Life, Colonial Penn and Washington National can serve different audiences and distribution needs.
- Economics link. Trace how insurance revenue logic, underwriting decisions, service costs and reinsurance arrangements may interact.
- Model workshop. Populate the Excel canvas with team inputs, then use the Word analysis to test connections and record open questions.
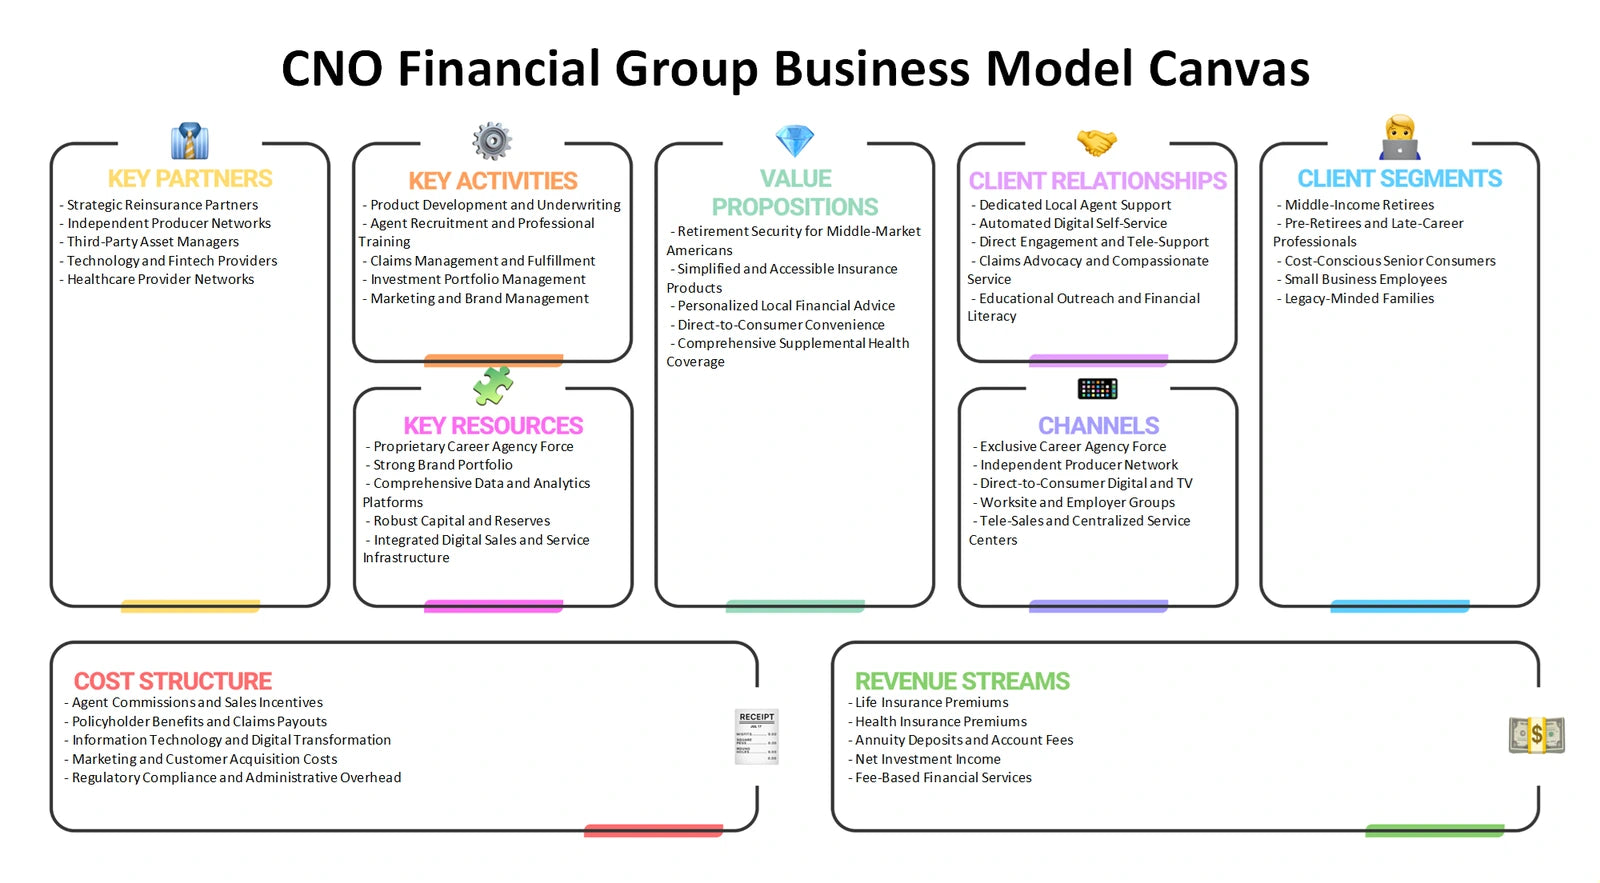
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Where could industry structure put the greatest pressure on CNO's insurance profitability and strategic flexibility?
A CNO Financial Group Porter's Five Forces analysis examines rivalry for policies and distribution access, supplier power among reinsurers and specialist providers, buyer power through consumer choice and distributor influence, the threat of new entrants, and the threat of substitutes. In protection markets, substitutes can include alternative savings, benefit and risk-management arrangements rather than only another insurer. The lens helps distinguish a competitive headline from a structural pressure on pricing, retention or acquisition costs.
- Reinsurance leverage. Consider how counterparties may affect risk capacity, pricing reference points and capital flexibility.
- Entry barriers. Examine the roles of regulation, capital requirements, underwriting capability and customer trust without assigning force scores.
- Evidence record. Use the Excel framework to organize force-by-force inputs and the Word analysis to capture implications and uncertainties.
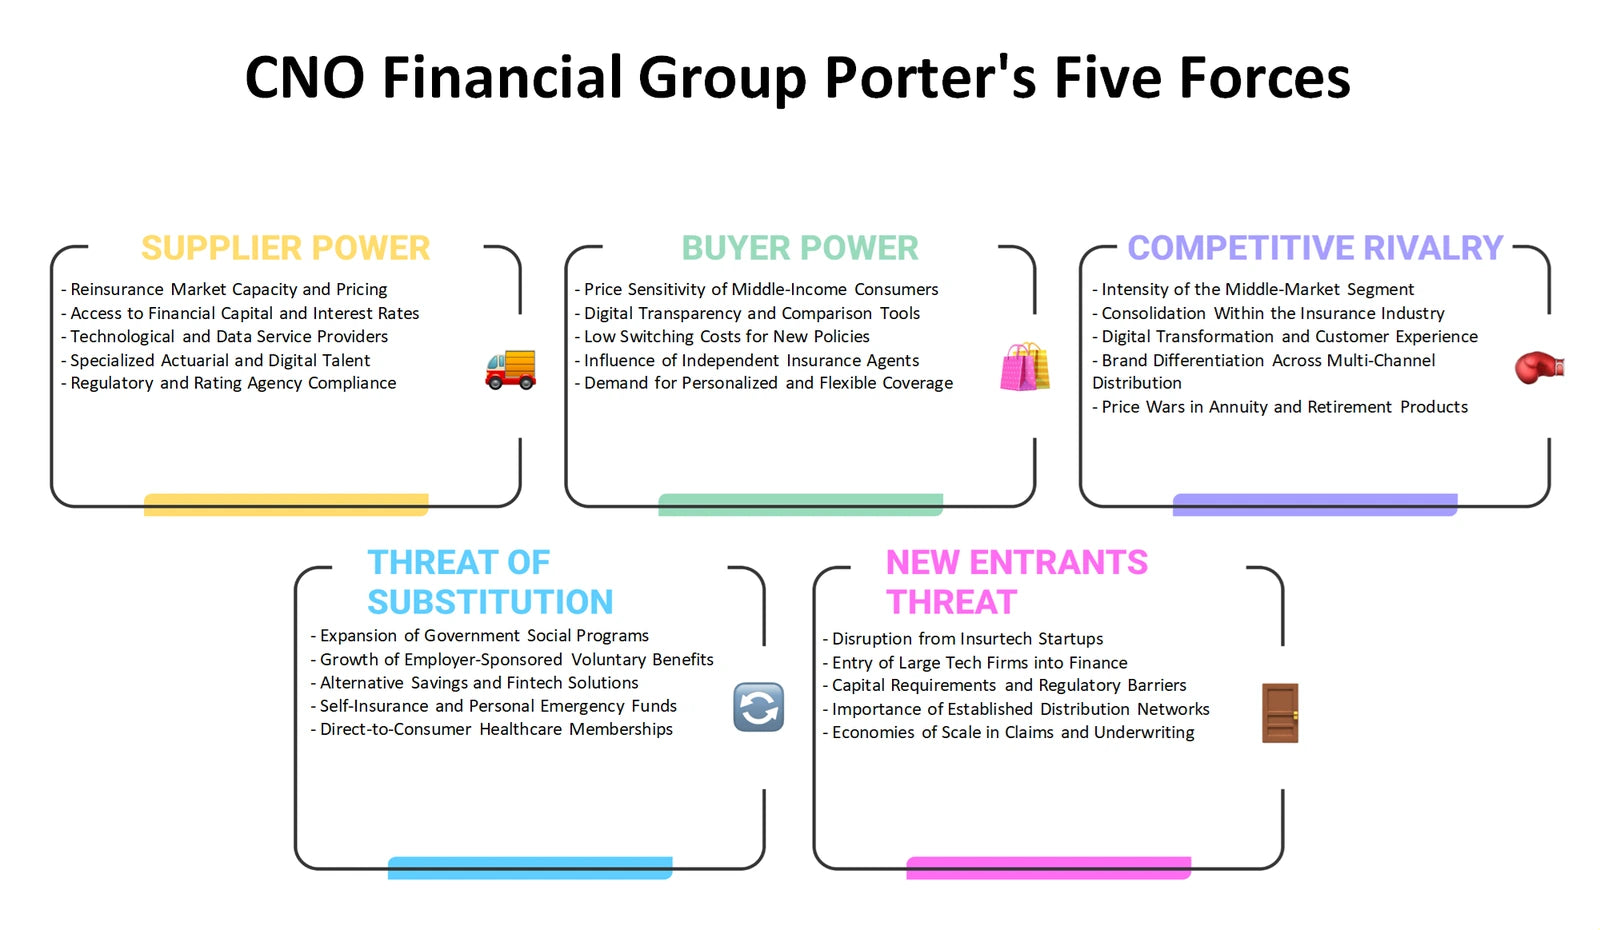
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should branded insurance offerings align product value, pricing logic, distribution routes and compliant communication?
A CNO Financial Group Marketing Mix examines Product, Price, Place and Promotion in a regulated protection context. Product includes coverage design and the service experience; Price considers premiums, benefits and underwriting economics; Place maps routes through the group's distinct branded channels; and Promotion considers communication that must build understanding and trust. This structure is useful when customer needs differ by demographic segment and when the route to market shapes both cost and service expectations.
- Segment-channel fit. Compare how product needs and distribution approaches may differ across the three branded operations.
- Price-value guardrails. Test the relationship among benefit design, affordability, underwriting assumptions and customer understanding.
- Campaign planning. Use Excel to organize the four Ps and the Word analysis to develop a reasoned channel and communication review.
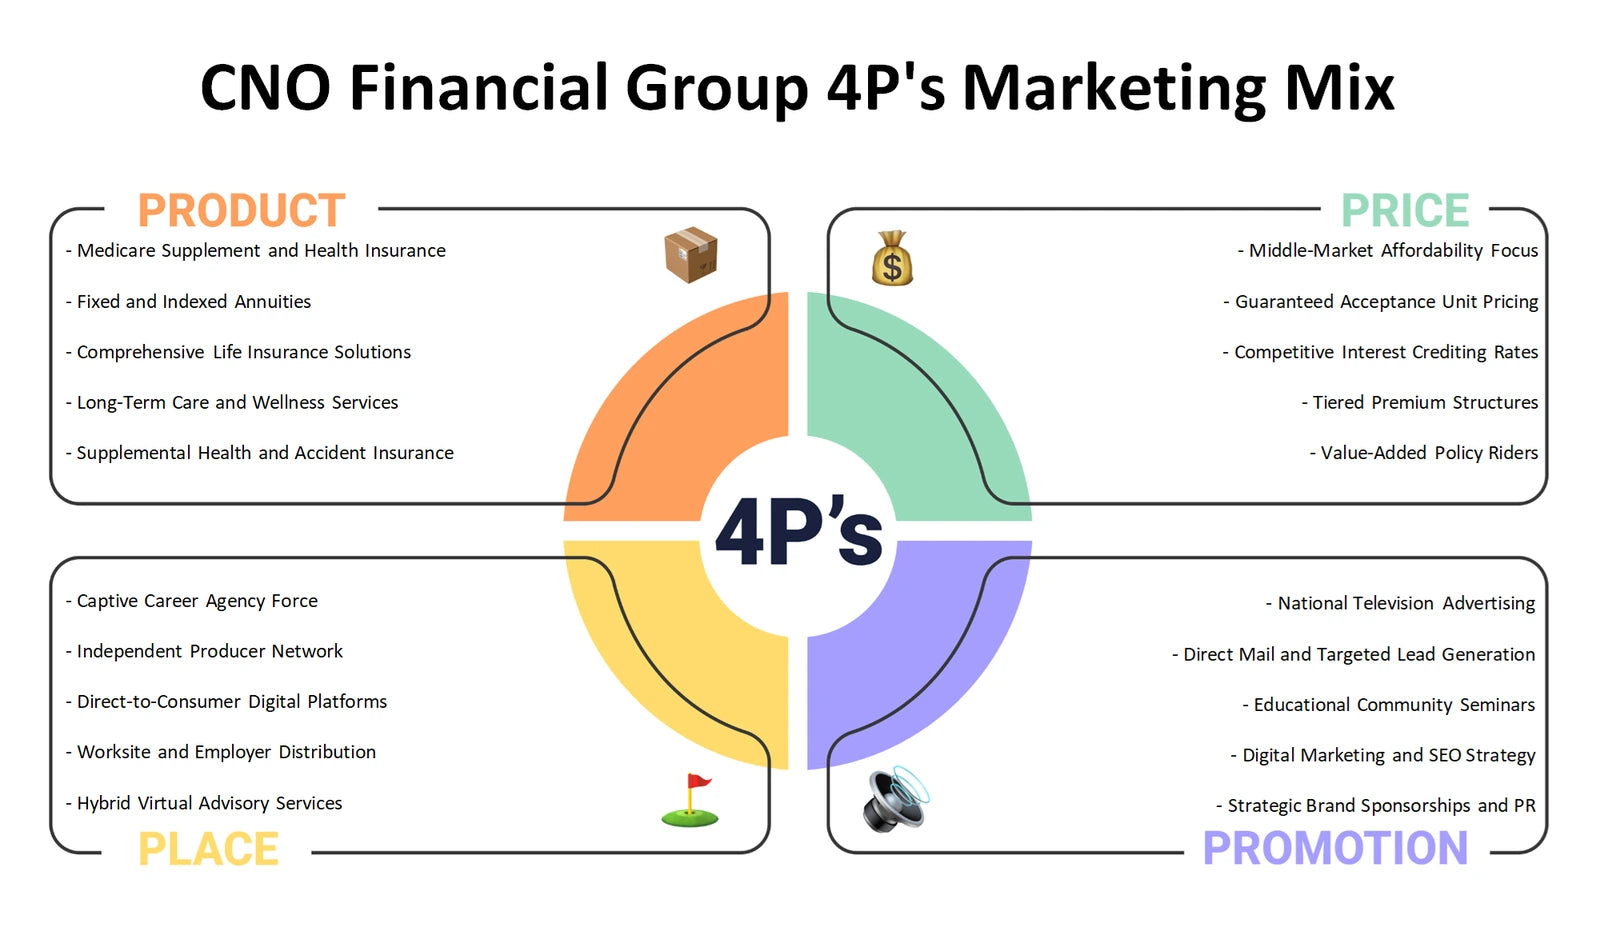
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape demand, investment economics, insurance compliance and catastrophe-related risk?
A CNO Financial Group PESTLE analysis, also commonly called PESTEL, organizes Political, Economic, Social, Technological, Legal and Environmental influences. It can distinguish policy and regulatory questions from documented changes, consider interest-rate or inflation scenarios without assuming a current rate, and explore demographic needs, digital service expectations, cyber resilience, compliance demands and environmental exposures that may affect catastrophe risk or reinsurance conditions.
- Scenario prompts. Separate external drivers that affect customer demand, investment income assumptions, operations or risk-transfer markets.
- Time horizons. Distinguish immediate compliance questions from longer-term demographic and technology shifts.
- External tracker. Use the Excel structure to sort signals by PESTLE category and the Word analysis to frame implications for review meetings.
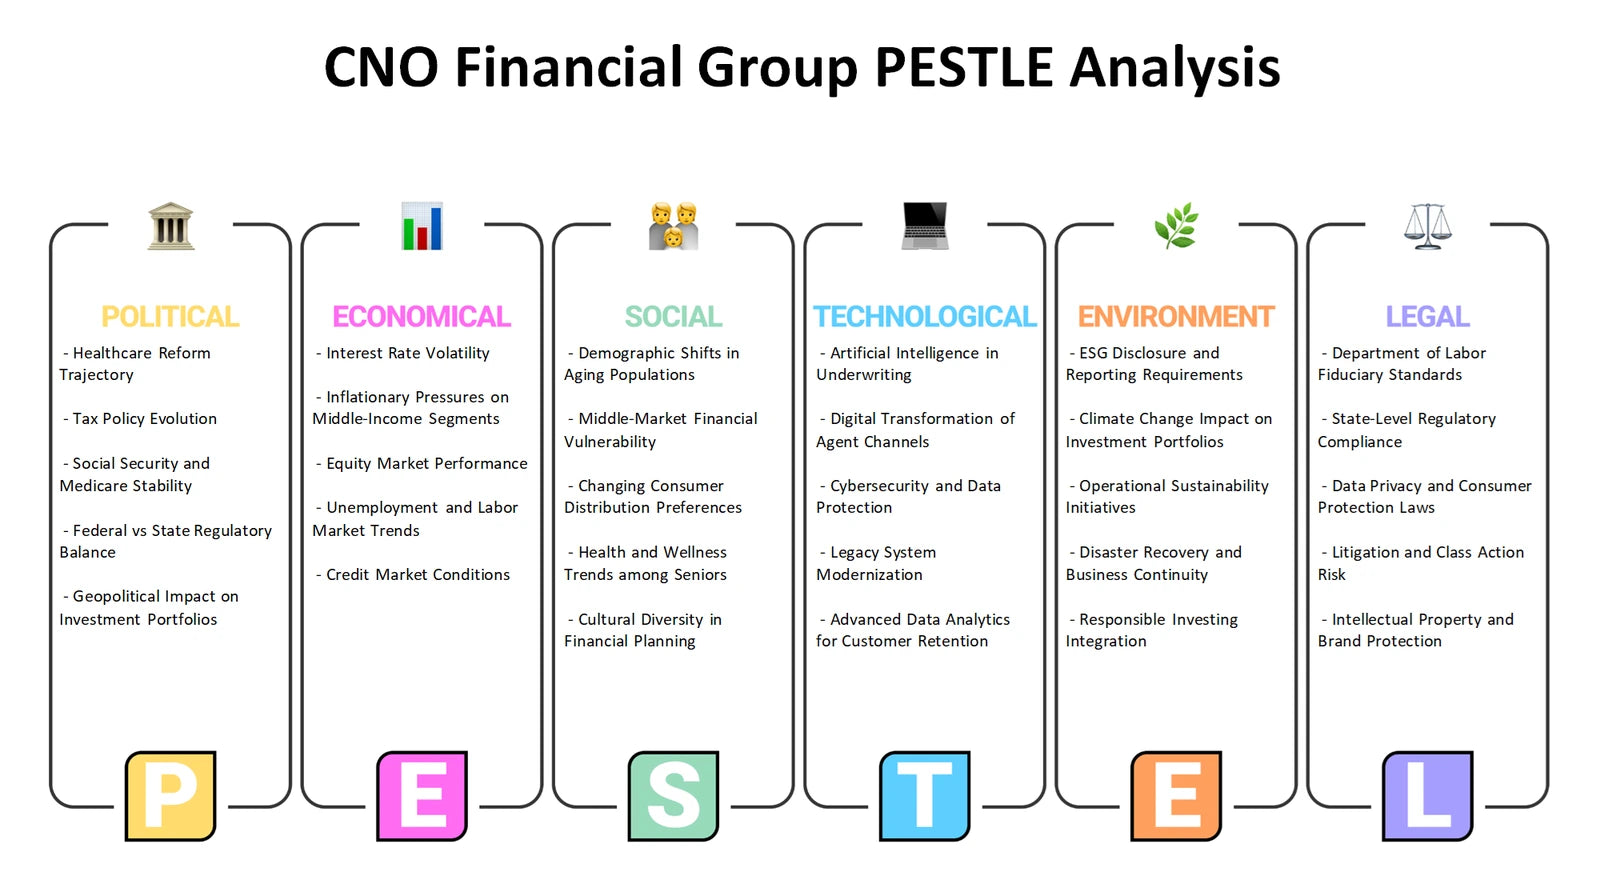
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered against changing insurance-market opportunities and threats?
A CNO Financial Group SWOT analysis keeps internal Strengths and Weaknesses distinct from external Opportunities and Threats. It can test whether multiple branded channels, underwriting knowledge, policyholder service capabilities or reinsurance relationships represent meaningful internal assets, while treating concentration, cost or execution issues as questions to investigate rather than established findings. Opportunities and threats belong outside the company: demographic demand, technology shifts, competitive pressure, regulation and capital-market conditions.
- Internal evidence. Examine capabilities, resources, processes and constraints before classifying an item as a strength or weakness.
- External signals. Relate opportunity and threat themes to the market conditions organized in the PESTLE analysis.
- Priority test. Use Excel to rank and connect themes, then use the Word analysis to explain the evidence, dependencies and strategic trade-offs.
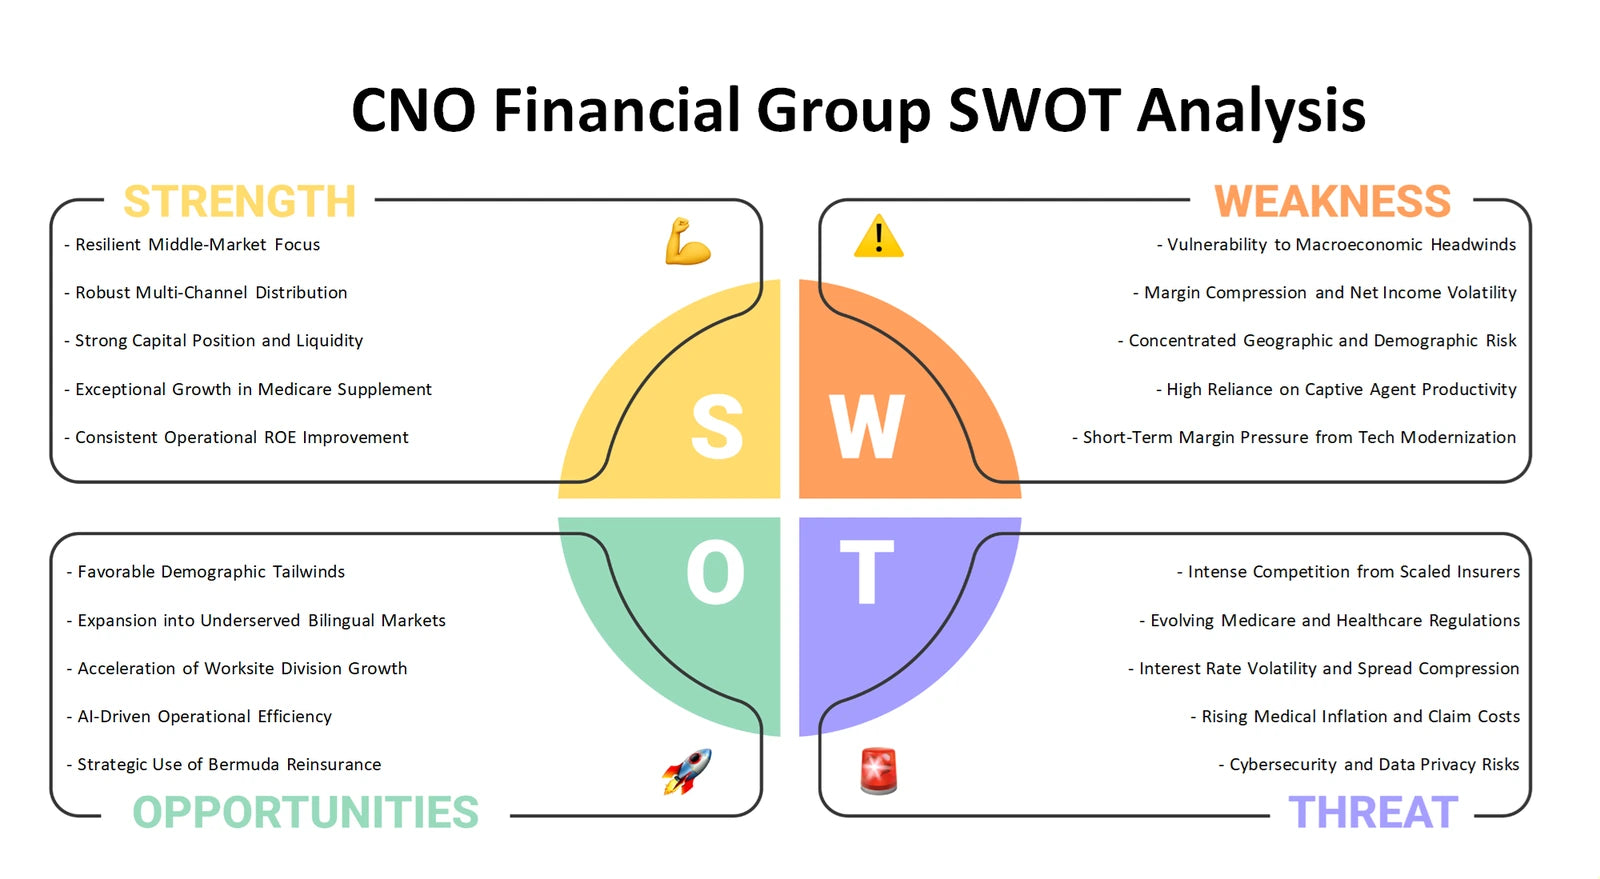
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more connected strategic view
Together, the six perspectives let you move from portfolio priorities and business-model economics to industry pressures, customer-channel choices, external change and strategic trade-offs. The Excel frameworks provide a structured way to compare inputs, while the detailed Word analyses support deeper discussion of CNO Financial Group's insurance operations, branded distribution model and risk-sensitive economics.
Company background: CNO Financial Group, Inc. — SEC Form 10-Q filing materials.