

Cincinnati Financial: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Cincinnati Financial Strategy Analysis Bundle
Cincinnati Financial is the public-facing name for Cincinnati Financial Corporation, a United States insurance holding company. Its insurance operations work through independent agency relationships, making agency coverage, underwriting discipline, service quality and the ability to support varied customer needs central questions for understanding how the business creates value.
In its July 27, 2026 Form 10-Q filing, Cincinnati Financial Corporation reported revenue of USD 4.274 billion and GAAP net income of USD 1.255 billion for April 1 through June 30, 2026. Those quarterly figures provide context for examining portfolio priorities, agency-led growth and catastrophe-risk resilience; they do not indicate that the downloadable files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance activities deserve capital, agency attention and management capacity as growth and competitive position differ?
A Cincinnati Financial BCG Matrix helps organize portfolio discussions around two distinct measures: market growth and relative market share. For an insurer, the relevant comparison may involve lines of coverage, geographic opportunities, distribution initiatives or service propositions rather than a single physical product. The framework separates potential Stars, Cash Cows, Question Marks and Dogs as analytical categories; it does not assume that any Cincinnati Financial activity belongs in a quadrant. This matters because premium expansion can require underwriting capacity, agency support and risk capital, while mature activities may have a different role in funding or stabilizing the wider portfolio.
- Portfolio logic. Compare growth potential with relative competitive standing instead of treating all premium opportunities as equally attractive.
- Capital trade-offs. Consider where agency appointments, underwriting expertise and reinsurance capacity may be most important to a portfolio decision.
- Working view. Use the Excel matrix to arrange candidate activities, then use the Word analysis to document assumptions and questions behind each placement.
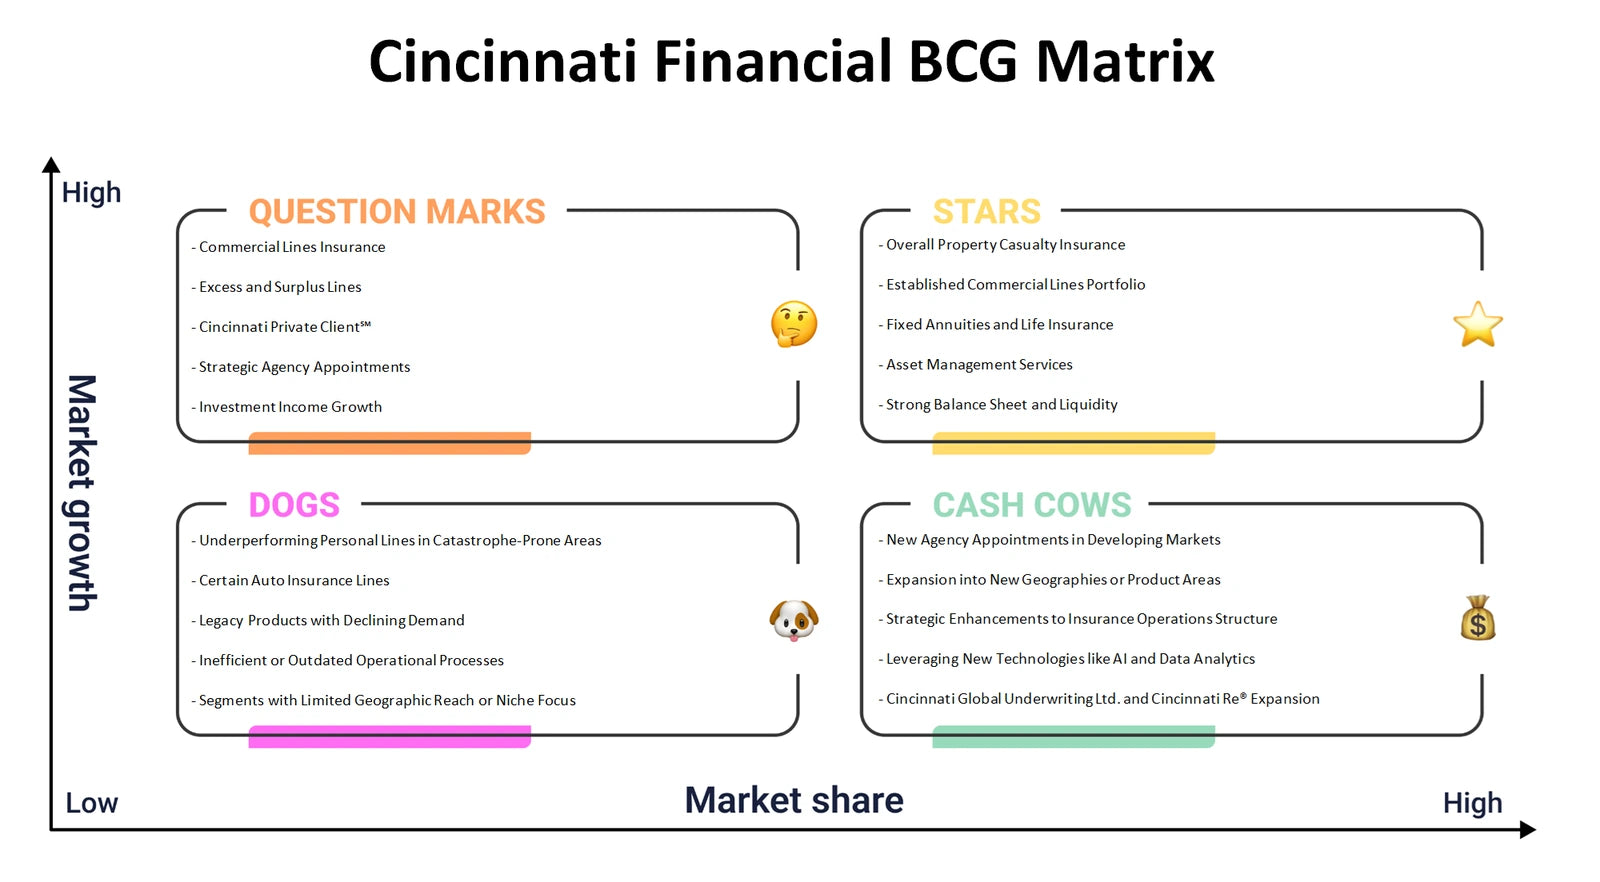
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do agency relationships, insurance value propositions and risk-management partners connect to Cincinnati Financial's economics?
The Cincinnati Financial Business Model Canvas examines the links among all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In this business, independent agencies are especially important to the channel and relationship questions, while underwriting, claims handling, investment management and risk transfer can be considered within activities, resources, partnerships and costs. Insurance revenue logic also needs to be considered alongside the obligations created by accepting risk. The Canvas is useful because it makes dependencies visible: a stronger distribution footprint may create opportunity, but it also raises questions about service consistency, pricing discipline and capacity.
- Agency connection. Examine how independent agency relationships help reach customer segments and communicate an insurance proposition across geographies.
- Risk economics. Link premium-related revenue streams to underwriting operations, reinsurance arrangements and the resources needed to meet policyholder obligations.
- Model mapping. Populate the Excel Canvas systematically, then consult the Word analysis to connect individual blocks into an integrated business-model narrative.
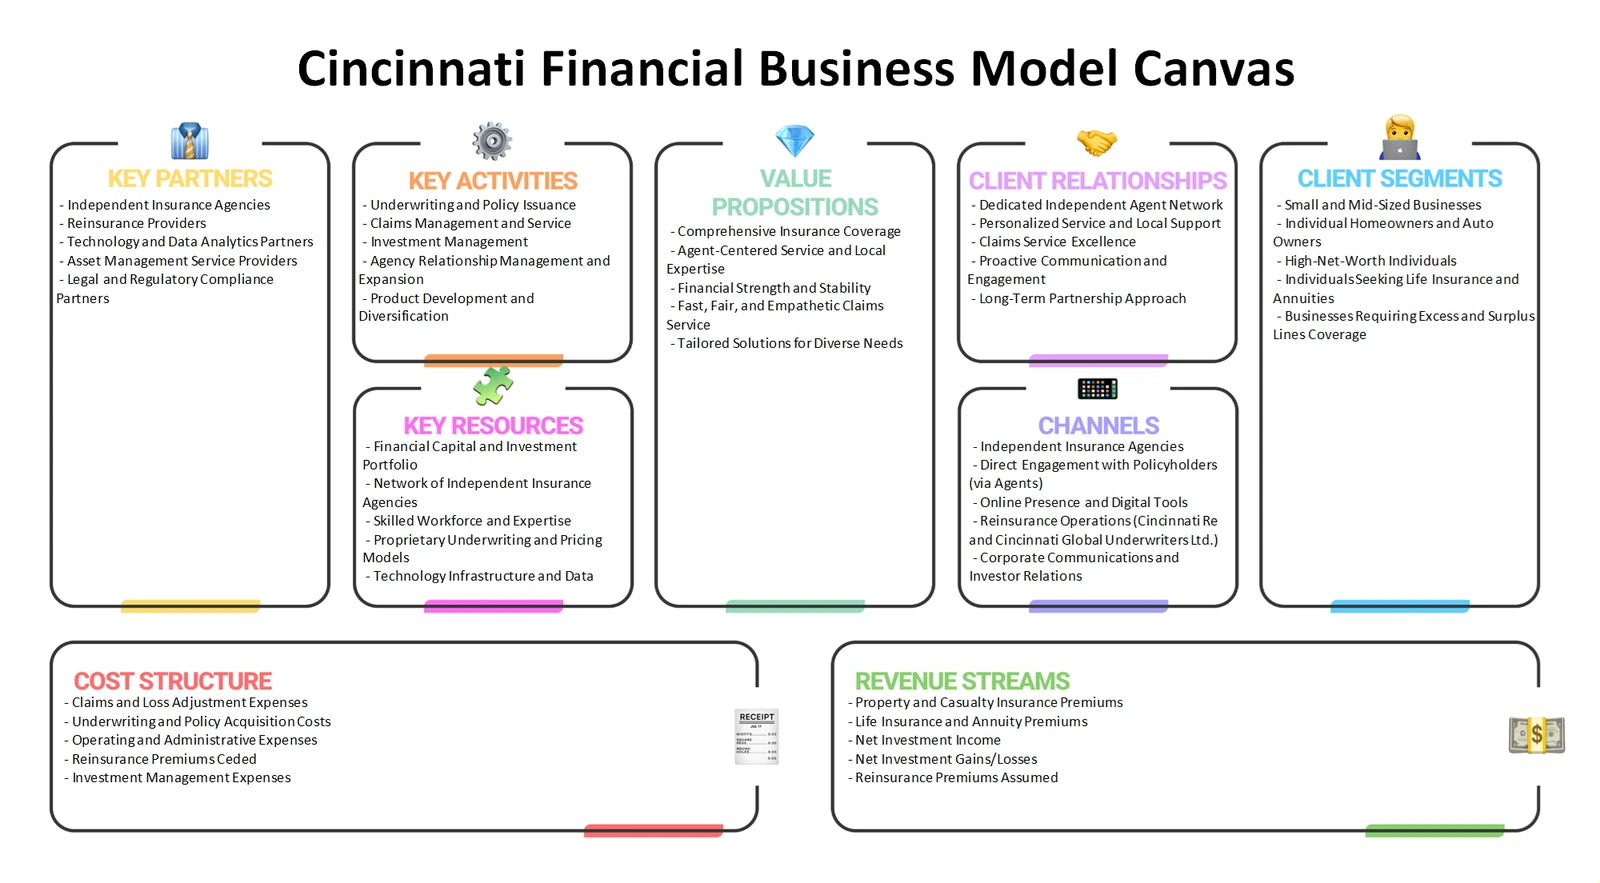
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape insurance profitability even when distribution and underwriting execution are strong?
Cincinnati Financial Porter's Five Forces provides a disciplined way to assess rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes in the insurance market. Rivalry can influence the willingness to compete on terms and price. Independent agencies and policyholders affect distribution and buyer dynamics, while reinsurers can matter to supplier power because external capacity helps manage exposure to major losses. New insurers, alternative risk-transfer arrangements and other ways customers can meet protection needs belong in the entry and substitution analysis. The lens is not a scorecard of named competitors; it helps separate structural pressure from company-specific execution.
- Distribution leverage. Explore how an agency-based route to market can affect retention, switching, service expectations and bargaining dynamics.
- Capacity dependence. Assess how access to reinsurance can influence underwriting flexibility when catastrophe exposure is material.
- Pressure testing. Use the Excel framework to compare each force consistently and the Word analysis to record the evidence and implications considered.
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can an insurer align coverage design, pricing discipline, agency distribution and communications around customer needs?
The Cincinnati Financial Marketing Mix considers Product, Price, Place and Promotion in a regulated insurance context. Product analysis can examine the fit of insurance coverage and service support with the needs served through agency partners. Price is not simply a marketing choice: premiums must reflect risk selection, claims uncertainty, expenses and the value of capacity. Place focuses on the independent-agency route to customers and the operational support behind that route. Promotion considers how agents and the company communicate trust, coverage relevance and service without confusing awareness activity with an actual campaign result. Together, the 4Ps help identify where a customer proposition may be coherent or where its components need closer comparison.
- Coverage proposition. Consider how product breadth, policy service and claims-related expectations can support the agency conversation with customers.
- Pricing discipline. Examine the trade-off between competitive positioning and pricing that remains appropriate for the risk accepted.
- Go-to-market review. Use the Excel 4Ps layout to compare choices side by side, then use the Word analysis to interpret their strategic fit.
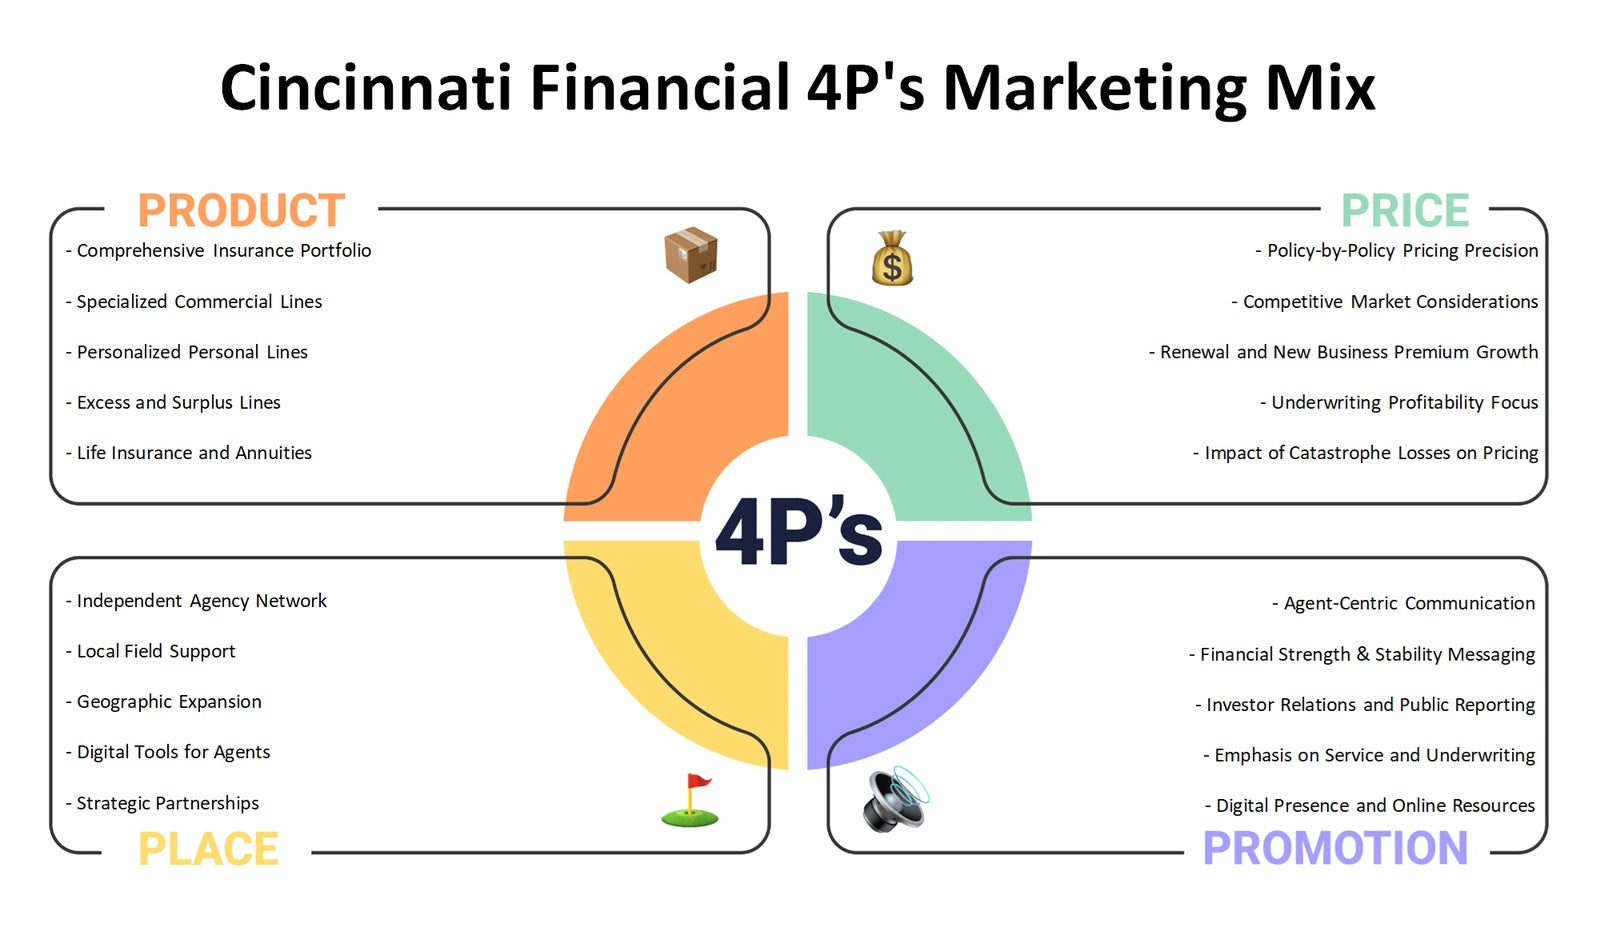
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored because they can alter insurance demand, loss exposure, regulation or capital conditions?
A Cincinnati Financial PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. For a United States insurer, political and legal questions can include the direction of insurance oversight and state-level operating requirements, without assuming a particular new rule. Economic conditions may affect customer budgets, repair costs and investment conditions. Social expectations can shape service and protection needs, while technology can change agency workflows, claims processes and data-related risk. Environmental conditions are relevant because severe weather and catastrophe patterns can affect loss exposure and the need for reinsurance. This external lens helps distinguish observed company performance from conditions that may require scenario planning.
- External scanning. Separate policy, economic and climate-related questions so that different uncertainties are not blended into one broad risk statement.
- Agency implications. Consider how changing customer expectations and technology adoption may affect agency support and service delivery.
- Scenario record. Use the Excel categories to capture signals and the Word analysis to develop fuller context, assumptions and monitoring questions.
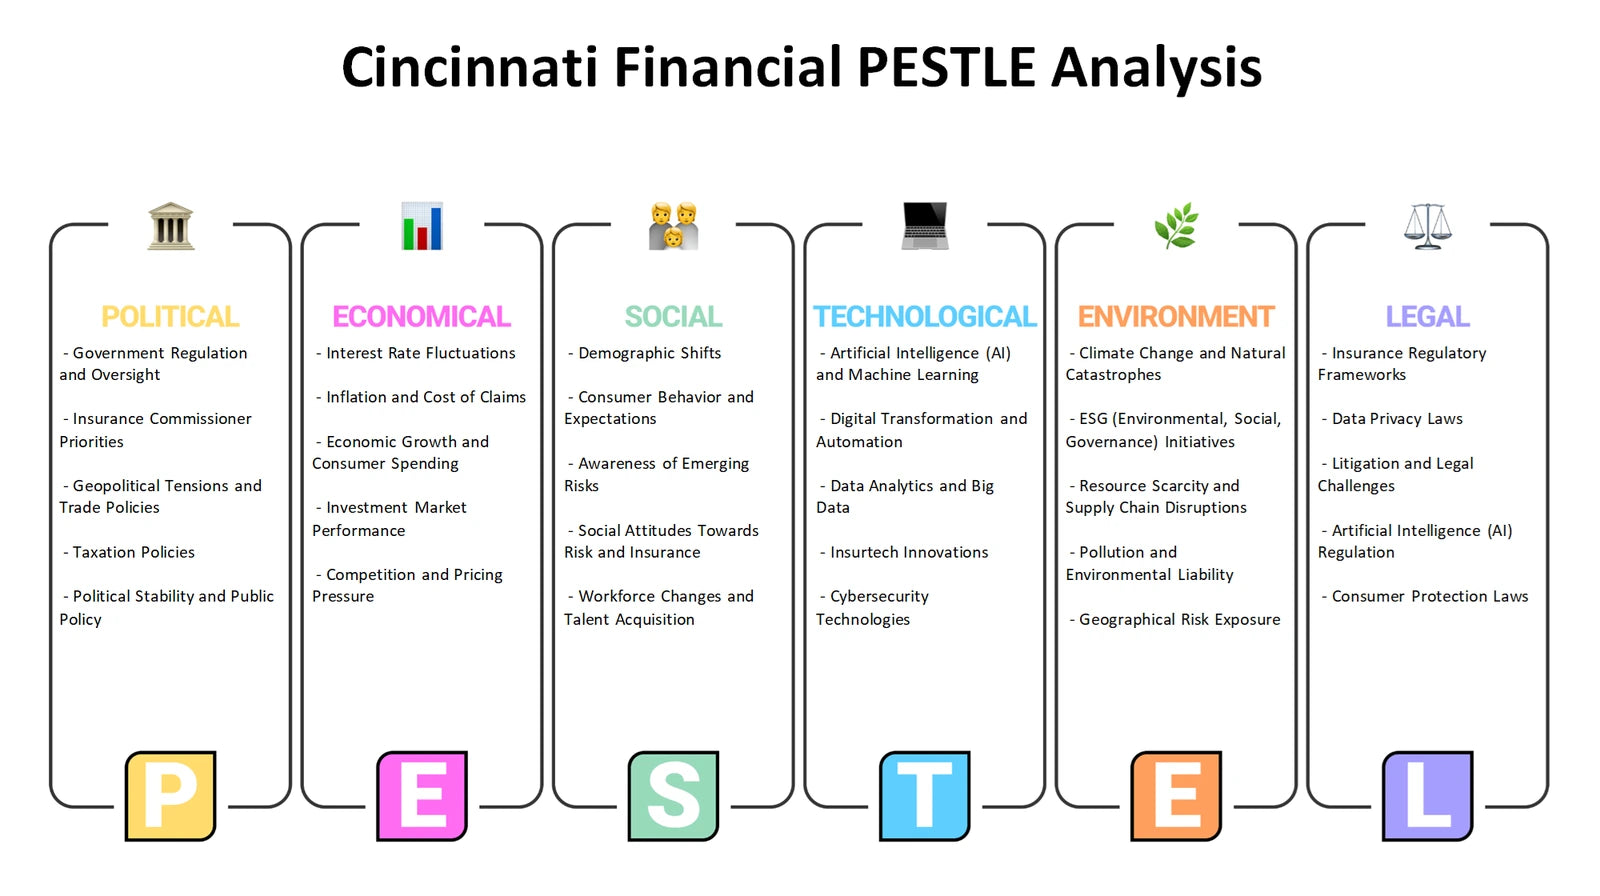
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Cincinnati Financial distinguish what it can control internally from market opportunities and external risk?
A Cincinnati Financial SWOT analysis brings internal Strengths and Weaknesses together with external Opportunities and Threats. The distinction is important. Agency relationships, underwriting capabilities, operating processes and access to risk-management arrangements are examples of internal areas to assess, not automatic strengths. Catastrophe exposure, regulatory developments, economic pressure and competitive conditions are external themes to test as opportunities or threats rather than internal shortcomings. By preserving that boundary, SWOT helps avoid treating every challenge as a management failure or every capability as durable advantage. It can also connect the agency-growth context with the need to protect capital through thoughtful underwriting and reinsurance decisions.
- Internal diagnosis. Assess capabilities, dependencies and operational constraints that may affect the quality and scalability of agency-led service.
- External fit. Compare those internal conditions against insurance-market change, catastrophe uncertainty and evolving customer needs.
- Decision synthesis. Use the Excel grid to classify observations clearly, then use the Word analysis to explore strategic links among the four categories.
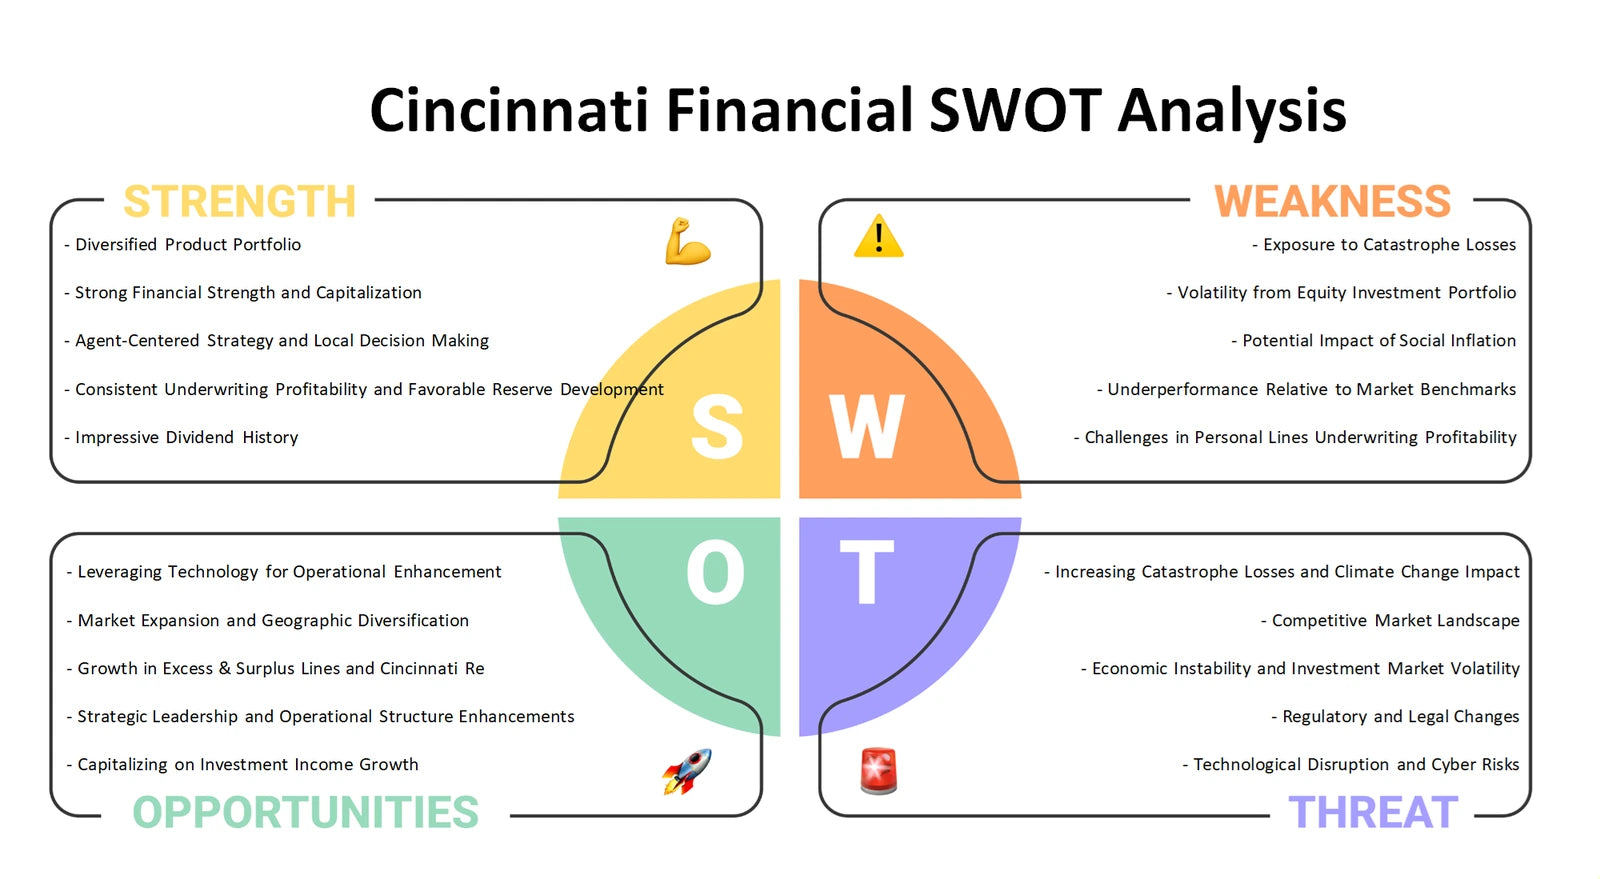
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Six connected lenses for insurance strategy
Used together, the six perspectives move from Cincinnati Financial's portfolio priorities and business-model connections to industry pressure, market choices, external change and strategic fit. The Excel frameworks provide a structured way to compare questions and organize observations, while the detailed Word files support fuller interpretation of the agency relationships, risk-transfer considerations and insurance economics relevant to the company.
Company background: Cincinnati Financial Corporation — SEC Form 10-Q for the quarter ended June 30, 2026.