

Chubb: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Chubb Strategy Analysis Bundle
Chubb refers here to Chubb Ltd., the insurance group identified in SEC records under fire, marine and casualty insurance. Its business context includes underwriting capacity, specialist risk expertise and service standards used to support insurance placements, including complex multinational risks. Independent agents, major brokers and affinity partners such as banks, associations, retailers and travel platforms are important routes through which relevant insurance offers can reach commercial and targeted customer segments.
In its Form 10-Q filed April 28, 2026, Chubb Limited reported revenue of USD 14.773 billion and GAAP net income of USD 2.320 billion for January 1 to March 31, 2026. That dated snapshot frames useful questions about portfolio priorities, the economics of broker and partner distribution, and how external insurance-market pressures may affect choices without implying that the downloadable files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance activities deserve greater capacity, distribution attention or disciplined resource allocation?
A Chubb BCG Matrix helps organise a broad insurance portfolio around two distinct criteria: market growth and relative market share. Rather than treating every line, segment or distribution opportunity as equally attractive, the framework provides a way to compare where underwriting expertise, capital, technology support and broker attention may be most consequential. Stars, Cash Cows, Question Marks and Dogs are analytical categories, not claims about Chubb's current products. For an insurer working through brokers, agents and affinity channels, the useful question is how growth potential interacts with the competitive strength needed to earn and retain placements.
- Portfolio comparison. Examine insurance activities by growth conditions and relative share rather than relying only on premium volume or familiarity.
- Capacity trade-offs. Consider where specialist underwriting and service resources could support established earnings pools, developing opportunities or areas requiring restraint.
- Structured review. Use the Excel matrix to organise candidate activities, then use the Word analysis to interpret the assumptions and strategic implications behind each comparison.
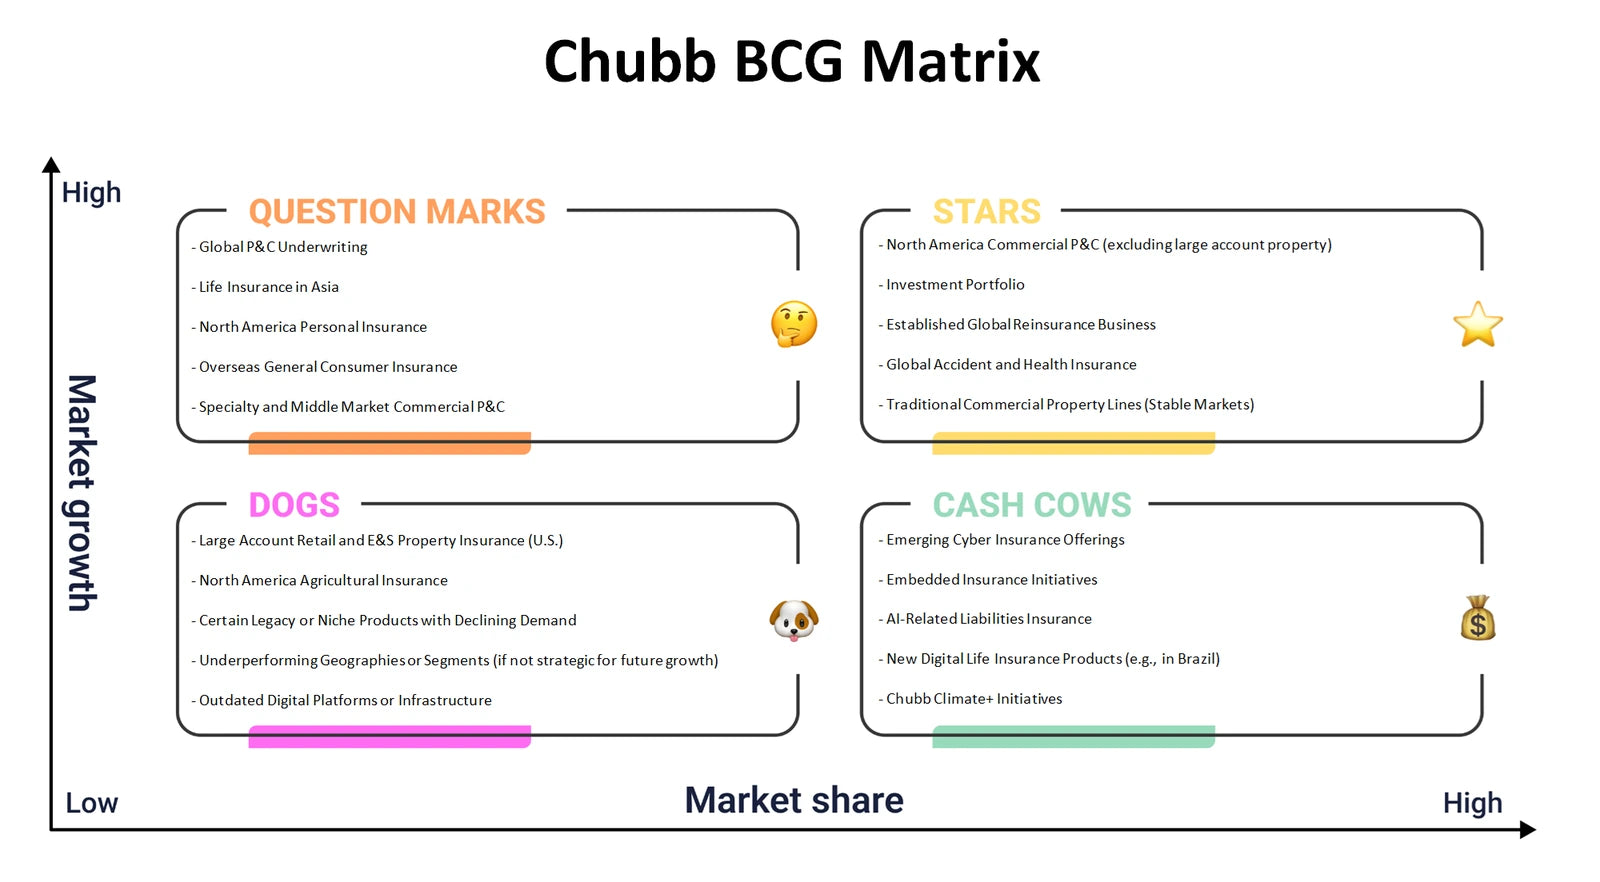
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do underwriting capability, distribution relationships and service delivery connect to Chubb's economic model?
The Chubb Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It is especially useful where commercial clients, consumers and partner-reached segments may require different propositions, yet depend on common risk selection, policy administration, claims and compliance capabilities. Brokers and agents can be examined as channels and relationship intermediaries, while affinity partners raise questions about embedded offers, integration and acquisition economics. The canvas helps reveal dependencies between what customers value, how insurance is delivered and how the model earns revenue while carrying operating and risk-related costs.
- Channel architecture. Compare broker, agent and affinity routes in terms of customer access, relationship ownership and the support each route requires.
- Value-to-economics link. Trace how specialist coverage, service expectations and compliant delivery connect to revenue streams, resources, activities and cost structure.
- Model mapping. Populate and test the Excel canvas block by block while using the Word analysis to explore the relationships and tensions across the nine elements.
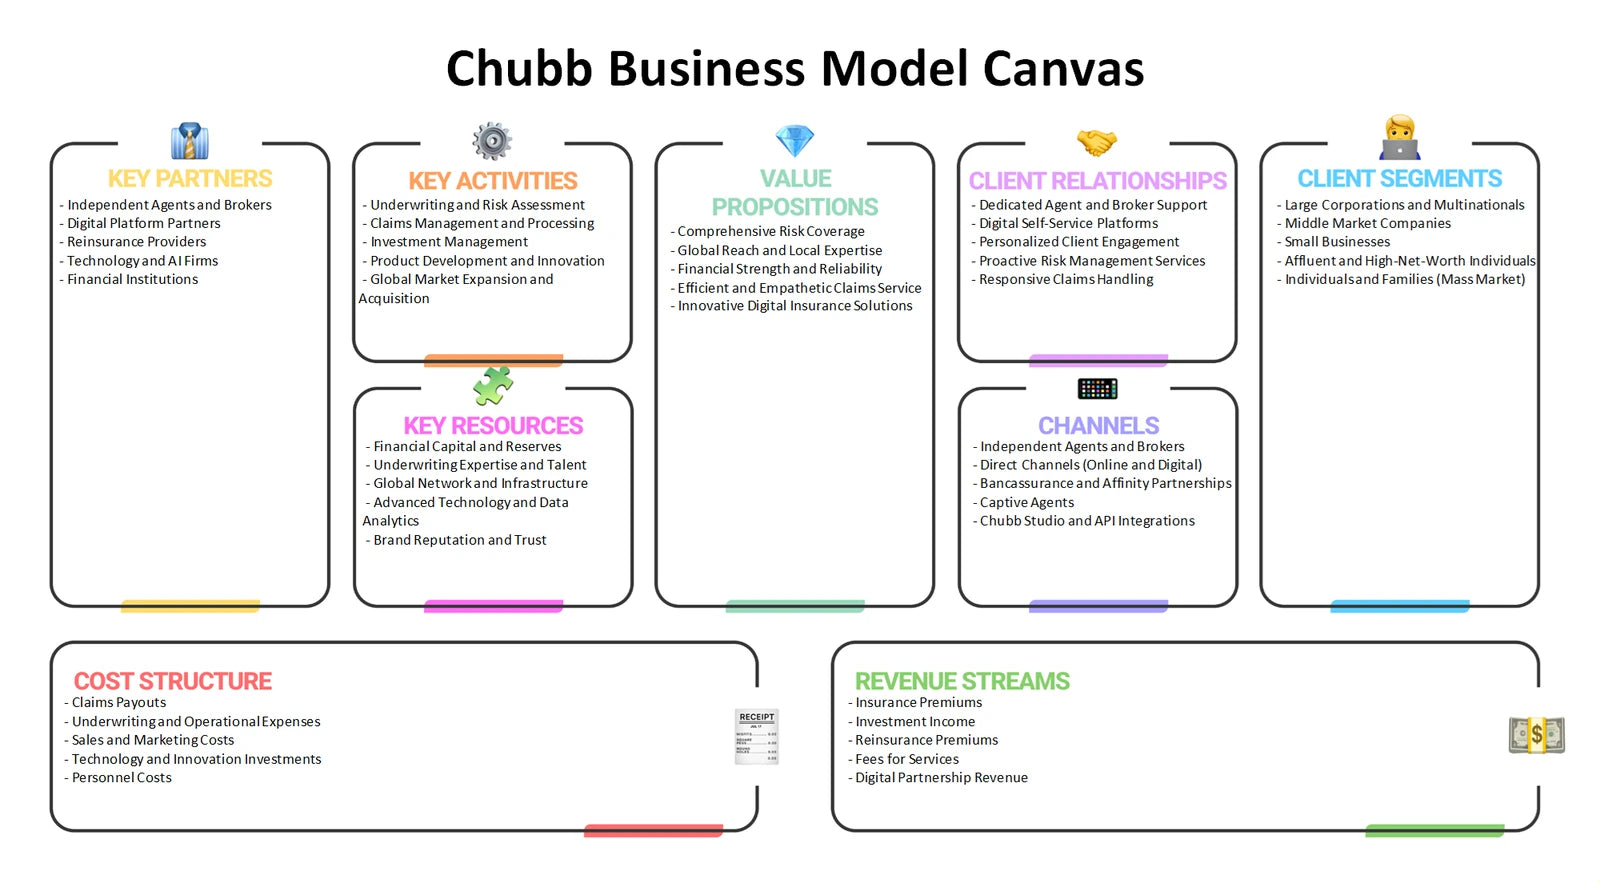
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape underwriting discipline, distribution economics and customer choice?
Chubb Porter's Five Forces examines the competitive setting around insurance rather than producing a generic competitor list. Rivalry can affect pricing, product breadth and broker service expectations. Buyer power may vary between sophisticated commercial buyers, brokers acting as influential intermediaries and partner platforms with access to targeted audiences. Supplier power invites examination of the talent, technology, distribution and risk-transfer inputs needed to operate. The threat of new entrants includes firms able to reach customers through digital or embedded routes, while substitutes include alternative ways customers retain, finance or transfer risks rather than simply another insurer. These forces help frame structural pressure points without assigning unsupported force scores.
- Broker leverage. Assess how placement influence, service standards and access to specialist coverage can affect buyer power and competitive rivalry.
- Alternative risk solutions. Distinguish direct insurance competition from self-retention, contractual risk allocation and other methods of meeting protection needs.
- Pressure testing. Record force evidence and questions in the Excel framework, then use the Word analysis to connect each force to underwriting and channel decisions.
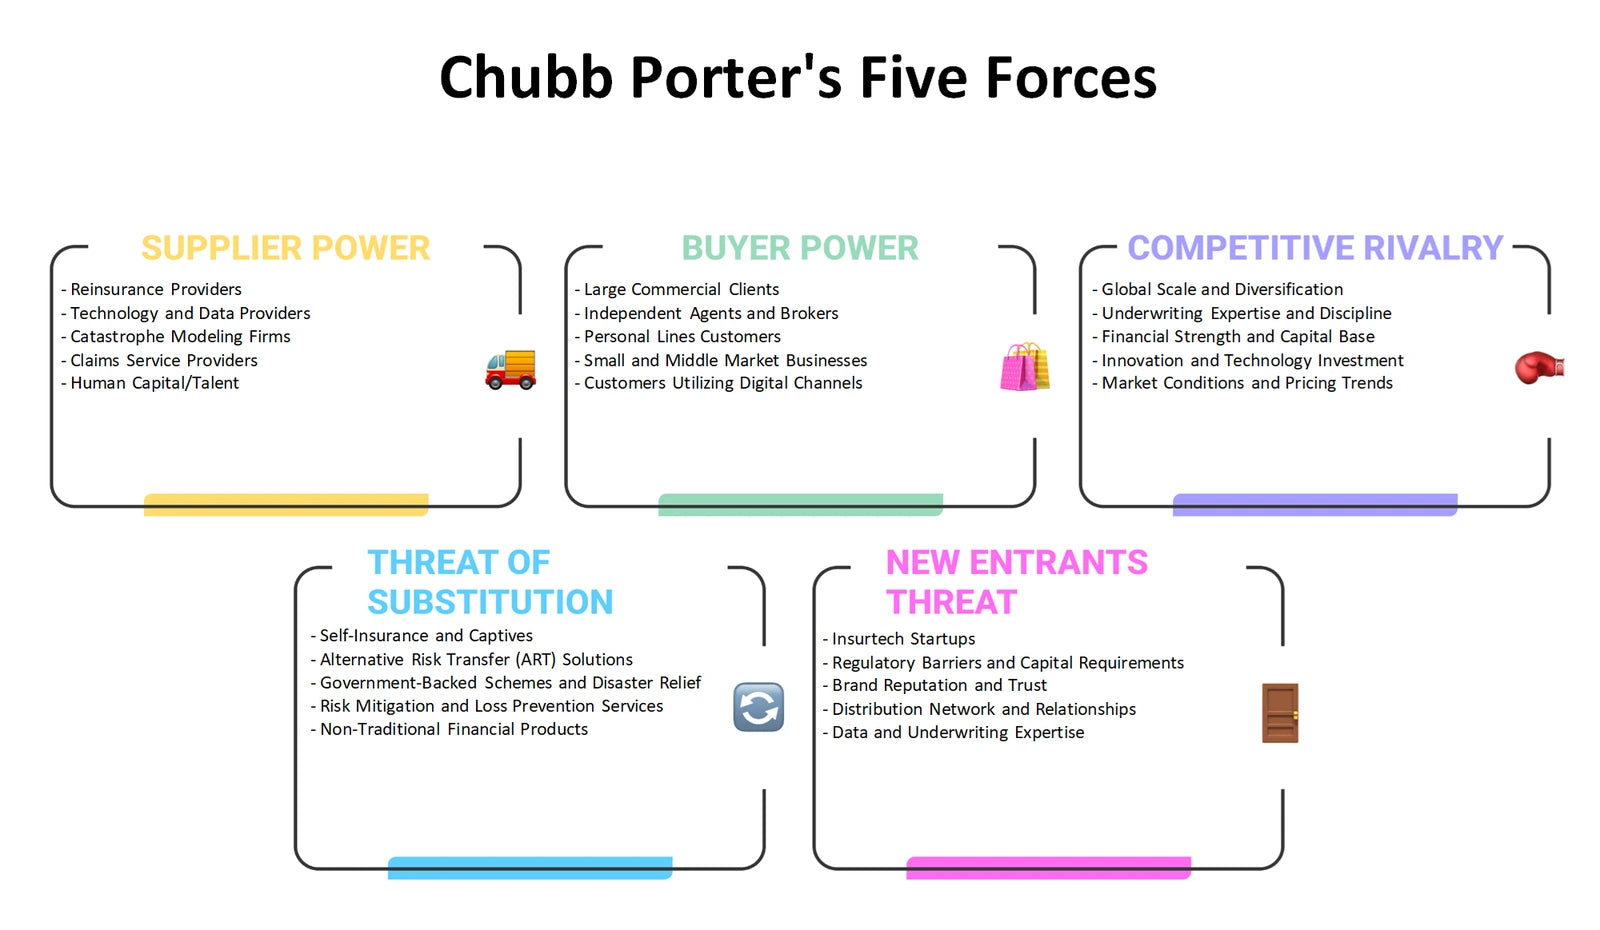
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should insurance propositions, pricing logic, routes to market and communication reinforce one another?
A Chubb Marketing Mix analysis applies Product, Price, Place and Promotion to a regulated insurance context. Product can be examined through the fit between coverage design, specialist expertise and the needs of commercial or affinity-reached customers. Price is not merely a posted amount: it raises questions about risk selection, terms, commission economics and the value customers or intermediaries place on service. Place covers independent agents, global brokers and embedded or co-branded partner routes. Promotion concerns how propositions are communicated clearly and compliantly to customers and distribution partners. Considering all four Ps together helps avoid a channel decision that is disconnected from product suitability or operating capability.
- Offering fit. Explore how coverage, service commitments and specialist knowledge can be matched to distinct customer and intermediary needs.
- Distribution design. Compare the role of agent, broker and affinity channels in reach, conversion, compliance and cross-sell opportunities.
- Go-to-market worksheet. Use the Excel framework to align the four Ps by audience, then consult the Word analysis for company-specific context and decision prompts.
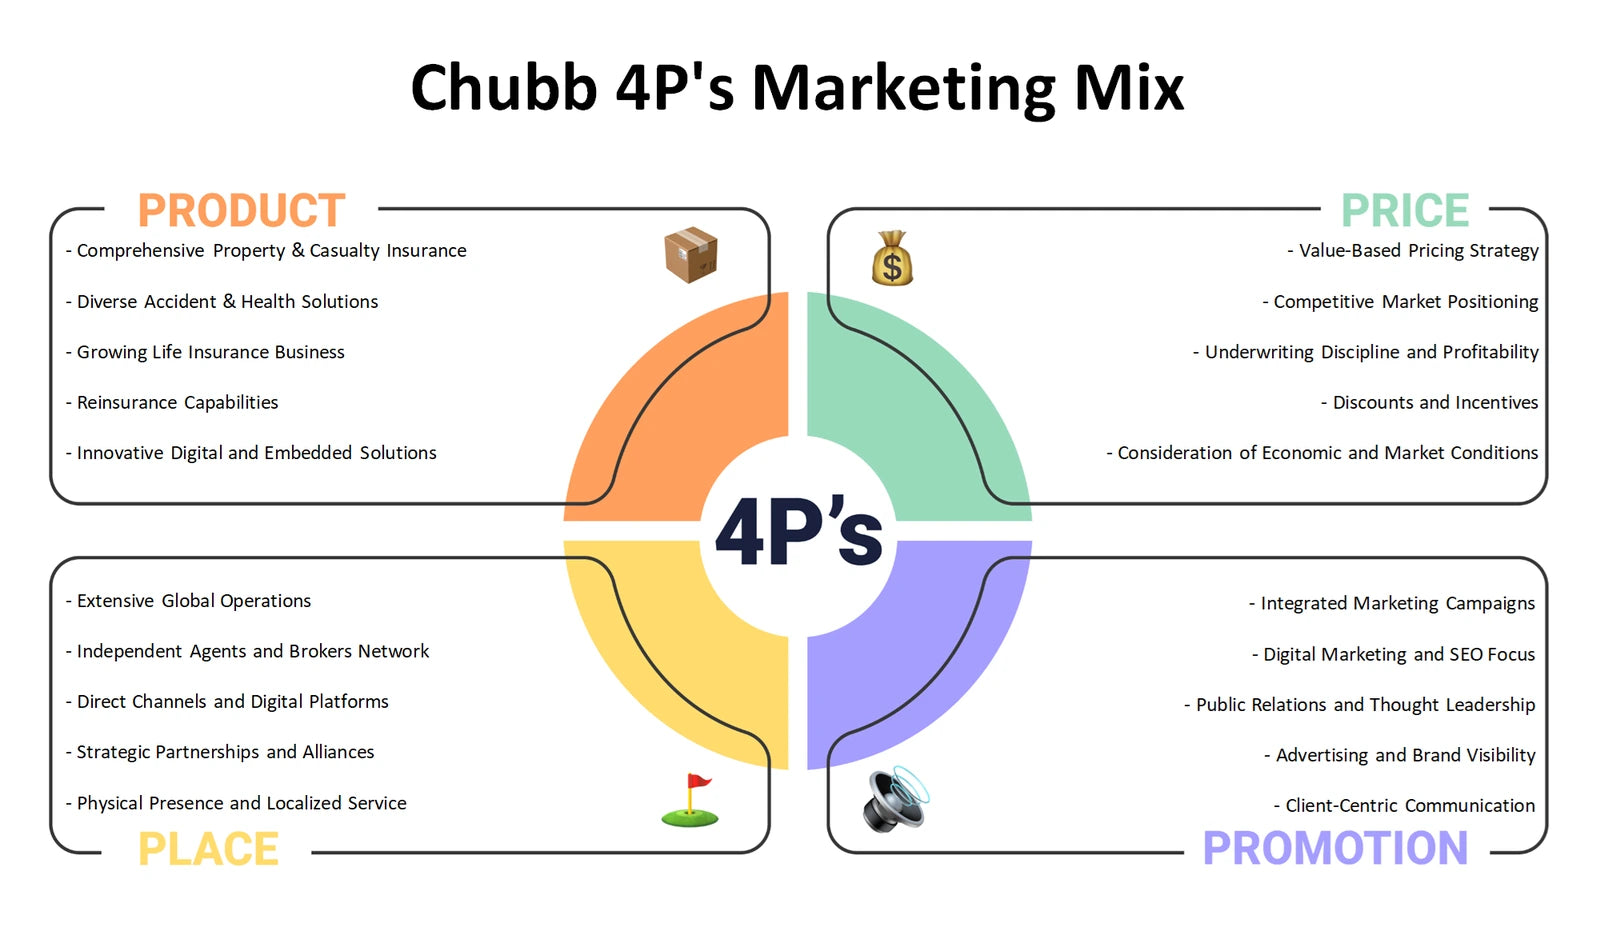
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should be monitored when planning insurance products, capacity and partner-enabled distribution?
Chubb PESTLE analysis, also commonly called PESTEL, separates six external lenses that can affect an insurance group: Political, Economic, Social, Technological, Legal and Environmental. Political and legal factors can shape regulatory expectations, licensing and consumer-protection obligations. Economic conditions may affect insured exposures, customer affordability, claims costs and investment-related considerations. Social shifts can influence protection needs and expectations for service, while technology can alter data use, digital journeys and integration with affinity partners. Environmental conditions are relevant to catastrophe exposure, resilience and risk assessment. The framework distinguishes questions worth monitoring from claims that a particular law, rate or event has already changed Chubb's position.
- Regulatory horizon. Identify policy and legal questions that may affect product governance, distribution conduct and cross-border insurance operations.
- Risk environment. Examine how economic, social, technological and environmental developments can alter demand, exposure and service expectations.
- External scan. Use the Excel categories to log signals and relevance, with the Word analysis helping translate broad external factors into focused strategic questions.
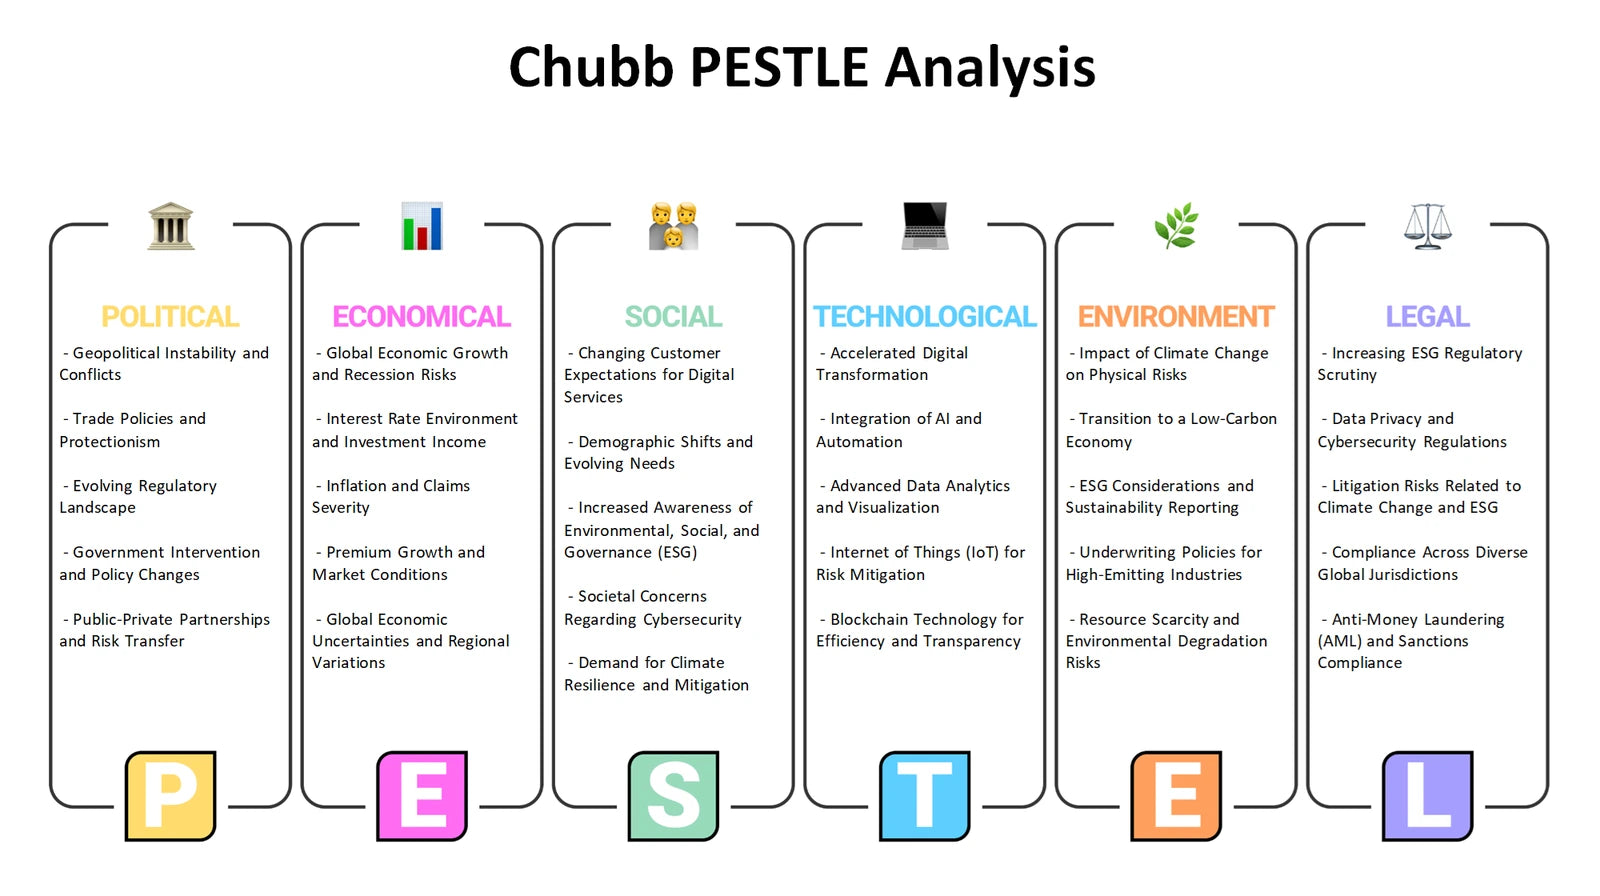
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Chubb's internal capabilities be considered alongside changing insurance-market opportunities and threats?
A Chubb SWOT analysis keeps internal and external thinking separate before connecting them. Strengths and weaknesses concern internal capabilities and constraints: for example, underwriting expertise, service delivery, partner support, operating complexity or capability gaps that merit examination. Opportunities and threats are external conditions, such as changing customer needs, distribution innovation, regulatory developments, market competition or evolving risk exposures. The framework does not assert that each plausible theme is an established finding. Instead, it gives customers a disciplined method for testing what is documented, what needs validation and where internal choices may matter most in response to external conditions. That distinction is valuable for an insurer whose distribution and risk decisions are closely linked.
- Internal diagnosis. Separate capabilities in underwriting, service and channel support from limitations or dependencies that should be assessed honestly.
- External alignment. Relate opportunities and threats to market access, regulation, customer expectations and the wider risk landscape.
- Actionable synthesis. Use the Excel grid to organise evidence and priority questions, then draw on the Word analysis to develop balanced connections across the four categories.
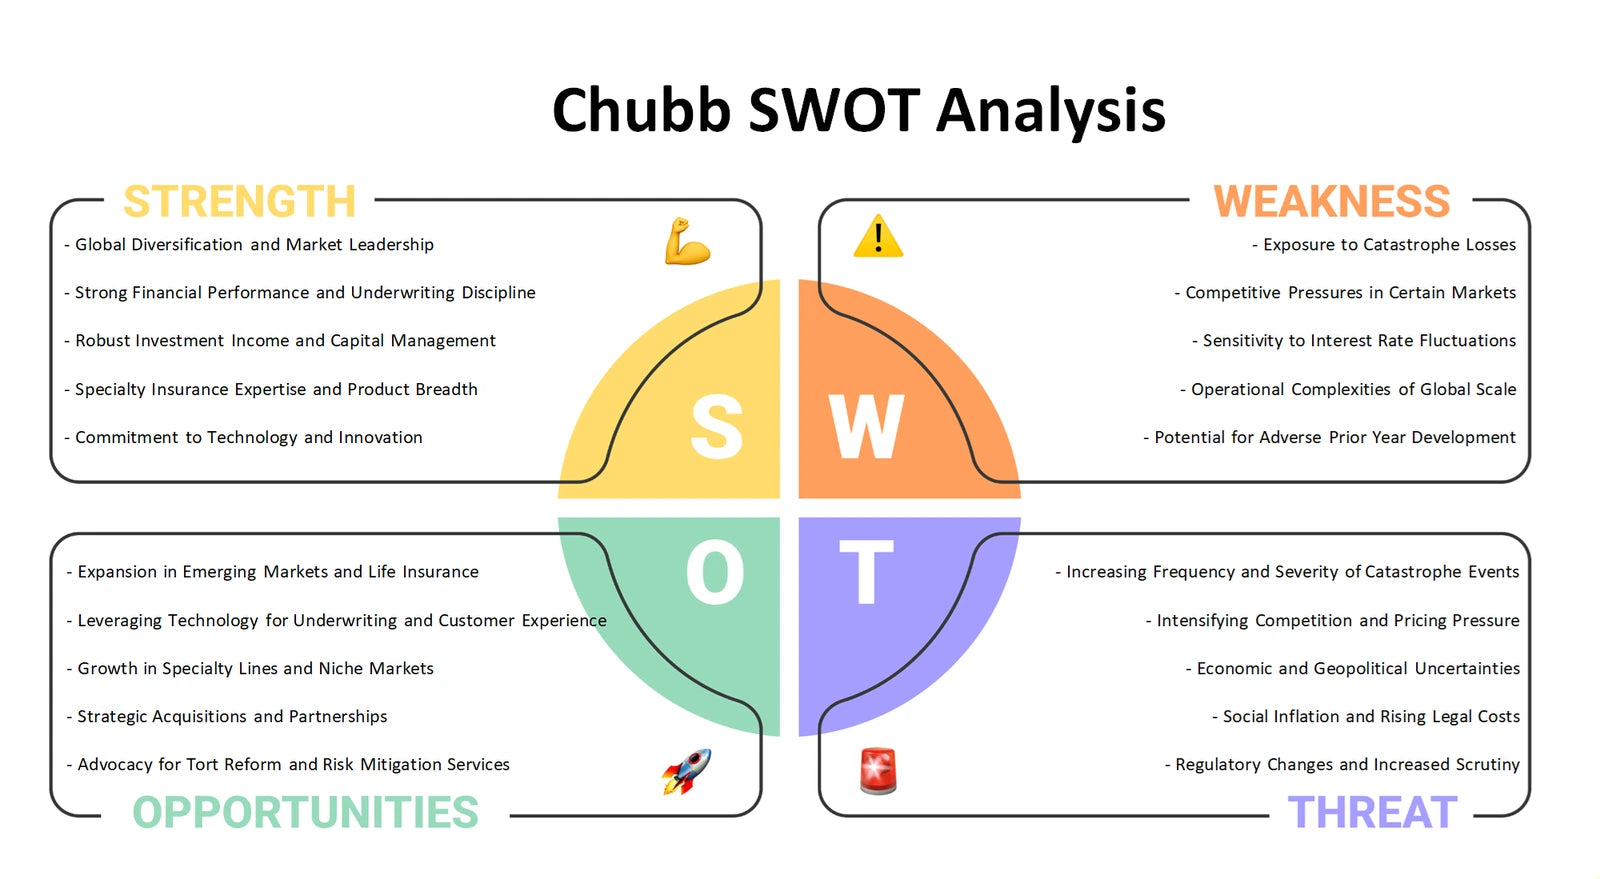
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Six lenses for a more connected Chubb strategy discussion
Together, the six perspectives move from portfolio prioritisation and business-model economics to competitive pressure, market delivery, external change and strategic fit. The Excel frameworks provide a structured way to compare questions, evidence and options, while the detailed Word files help place those questions in Chubb's insurance, broker, agent and affinity-partner context. Used together, they can support a more coherent view of how capabilities, channels, risks and market conditions interact.
Company background: Chubb — SEC company submissions profile.