

Cembra Money Bank: Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Cembra Money Bank Strategy Analysis Bundle
Cembra Money Bank is the Swiss consumer-finance business considered in this bundle. Its relevant customer journeys include vehicle loans and leasing arranged through car dealerships and OEM partners, alongside direct consumer-finance relationships. Dealership-based financing matters because a lending decision can influence whether a private customer completes a vehicle purchase, while the bank must balance convenience, underwriting discipline and responsible credit provision.
The supplied business context highlights point-of-sale origination, dealer relationships, funding partners, credit-information services and compliance technology. These facts create practical strategy questions: which activities deserve portfolio attention, how does the operating model connect to economics, and which external pressures could reshape consumer lending? The Excel frameworks and detailed Word analysis help organise those questions without treating analytical scenarios as confirmed company findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, leasing or partnership-led activities should receive resources when growth prospects and relative market share differ?
A Cembra Money Bank BCG Matrix helps separate portfolio-priority questions from assumptions about performance. The framework compares market growth with relative market share, then tests whether an activity may warrant the logic associated with Stars, Cash Cows, Question Marks or Dogs. For a consumer-finance provider, the useful comparison is not simply product popularity: it is whether vehicle finance, direct lending, cards or partner-enabled origination have different growth settings, economics and capacity needs. This creates a disciplined discussion about investment, maintenance, selective testing or possible rationalisation without assigning an unverified quadrant to any business line.
- Portfolio boundaries. Compare activities by customer need, distribution route and competitive context rather than combining all credit products into one broad category.
- Capital attention. Consider where underwriting capability, dealer support, technology investment and funding capacity may have the greatest strategic relevance.
- Framework comparison. Use the Excel matrix to map alternative evidence and assumptions, then use the Word analysis to document why a proposed priority fits the criteria.
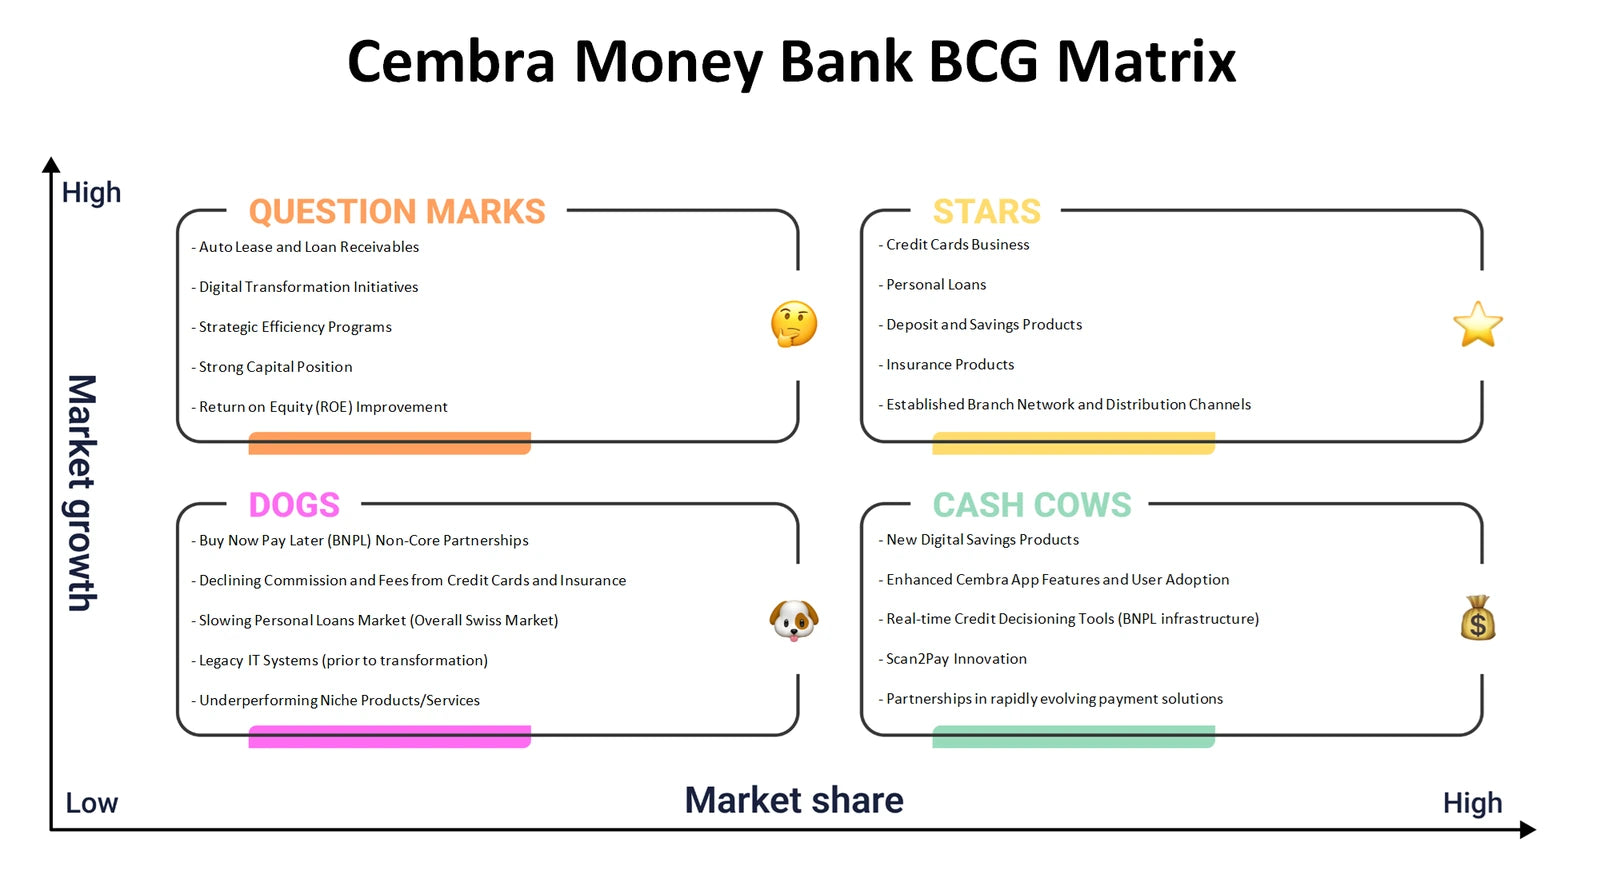
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer convenience, dealer-enabled finance and risk-controlled lending connect to Cembra Money Bank's economics?
The Cembra Money Bank Business Model Canvas links the nine building blocks into one operating picture. It examines customer segments such as private borrowers and vehicle buyers; value propositions including accessible finance and purchase support; channels and customer relationships across direct and dealer-led journeys; and revenue streams connected to lending and related financial services. It also considers the key resources, key activities, key partnerships and cost structure required to deliver that model. Dealerships, OEMs, institutional funders, credit bureaus and regtech providers are especially relevant analytical themes because they can affect origination flow, funding resilience, decision quality and compliance effort. The canvas helps reveal where customer value and operating dependencies meet.
- Journey-to-income link. Trace how a showroom or direct application journey may connect customer acquisition, approval, servicing and revenue generation.
- Partner dependencies. Examine how dealer networks, data providers and liquidity relationships influence key activities, resources and the cost base.
- Model design. Populate the Excel canvas systematically, using the Word analysis to add context on trade-offs between speed, credit quality, service and control.
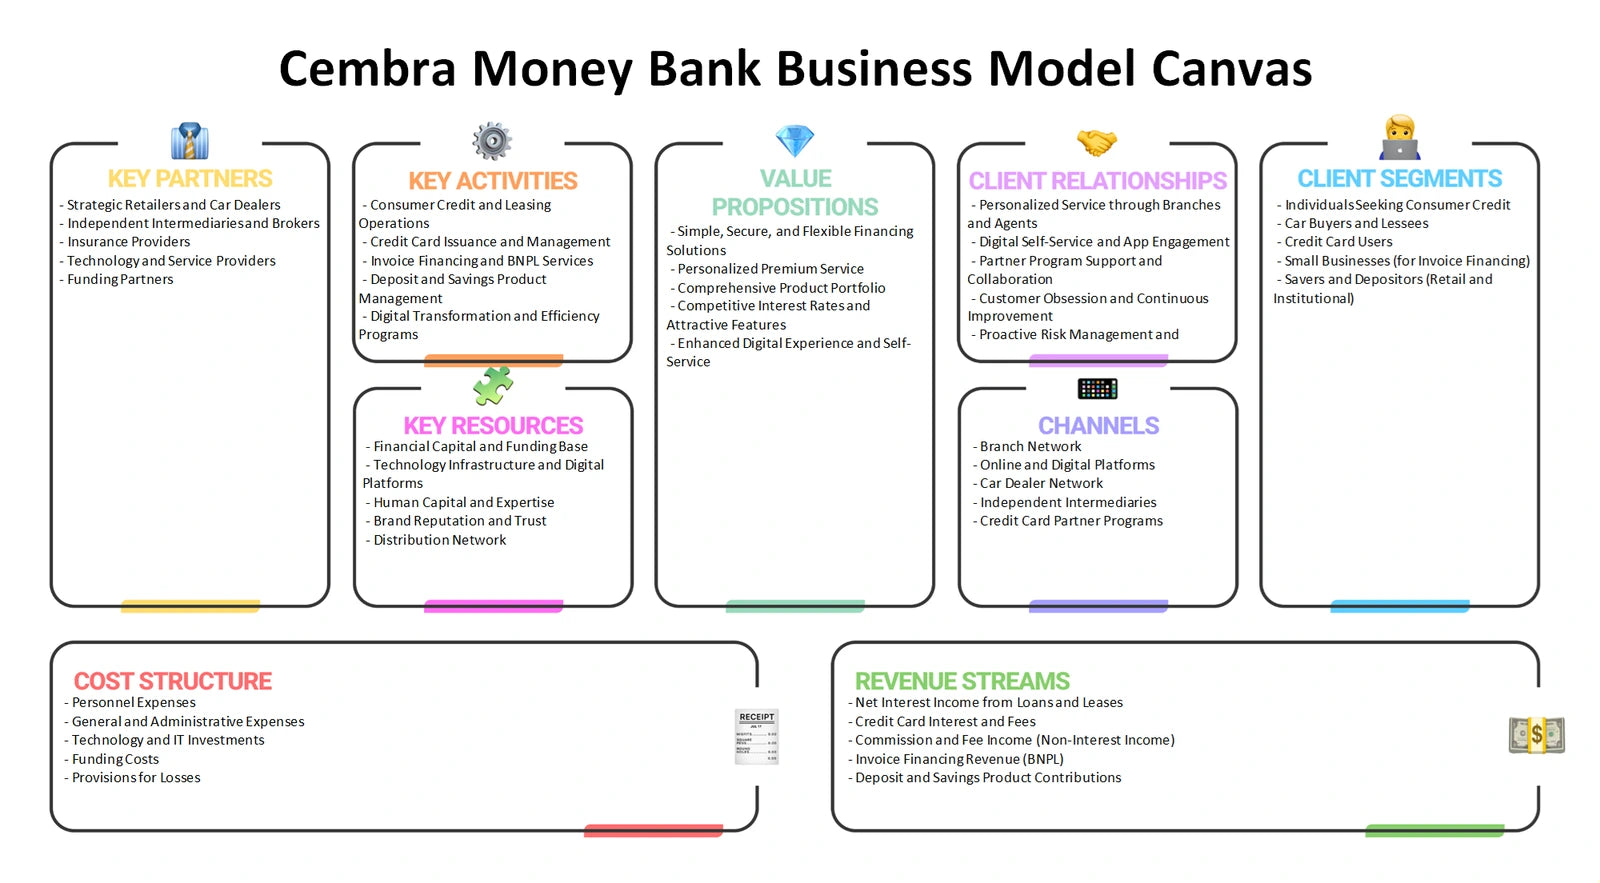
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence margins, customer choice and access to critical lending capabilities?
Cembra Money Bank Porter's Five Forces analysis focuses on the structure around Swiss consumer finance rather than attempting to rank unnamed competitors. Rivalry can be considered across lenders and finance providers seeking similar borrowers or point-of-sale relationships. Supplier power is relevant where funding sources, credit data, technology services or dealer networks affect terms and operating flexibility. Buyer power includes customers comparing finance options and dealers assessing the usefulness of a financing partner. The framework also tests the threat of new entrants and substitutes, including alternative ways to fund a vehicle purchase or manage short-term spending rather than only another lender. These forces help explain why distribution quality, trust, risk control and efficient processing can matter together.
- Rivalry and switching. Assess where approval experience, service and financing conditions may shape customer or dealer willingness to choose another provider.
- Input leverage. Explore dependencies on liquidity, information, technology and distribution partners that may affect cost, speed or resilience.
- Evidence trail. Use the Excel framework to record each force and supporting observations, while the Word analysis provides a fuller interpretation of the industry logic.
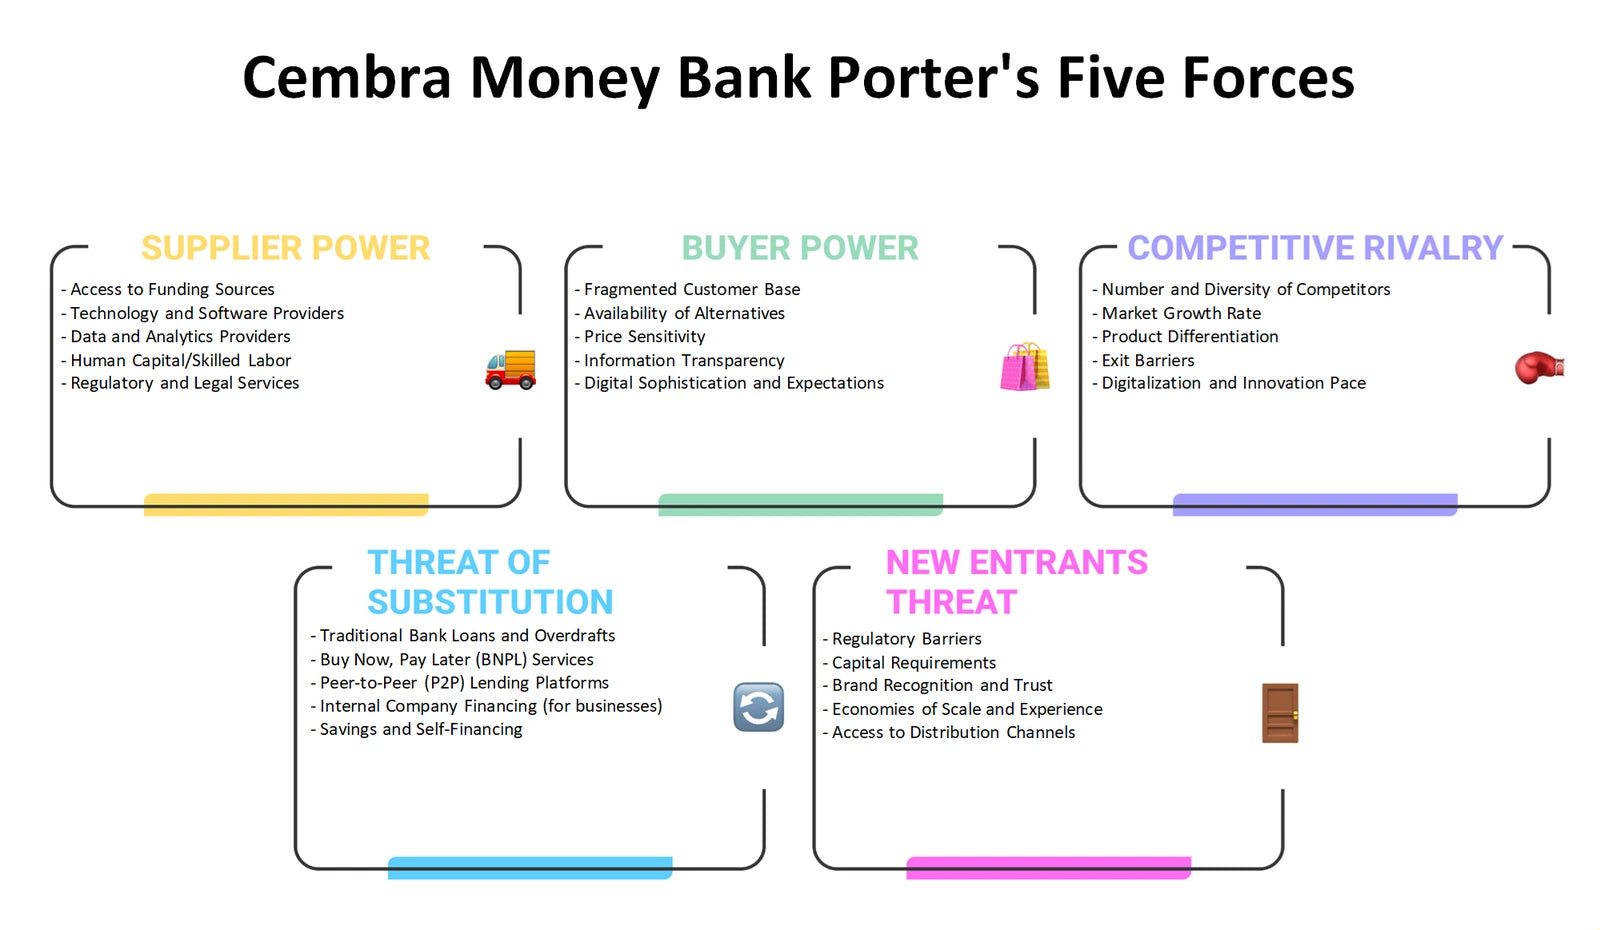
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated finance provider align its offering, pricing logic, routes to market and communications with customer trust?
The Cembra Money Bank Marketing Mix examines Product, Price, Place and Promotion in a lending context where the decision is material to a household and often made during a purchase journey. Product analysis can distinguish vehicle leasing, vehicle loans and other consumer-finance solutions by need, eligibility and service experience. Price concerns the logic customers and partners use to evaluate financing terms, not invented rate levels. Place is particularly important because dealership and OEM relationships can bring finance closer to the vehicle-buying moment alongside direct channels. Promotion should be considered through clear, responsible communication that helps customers understand an offer and supports partner conversion without overstating benefits.
- Offer clarity. Compare how different finance products solve distinct customer situations and where simplicity or flexibility may be important.
- Channel fit. Assess the different roles of dealership tools, partner presence and direct customer access in the path to application.
- Planning worksheet. Use the Excel 4Ps structure to align observations under each lever, then consult the Word analysis for company-specific questions and rationale.
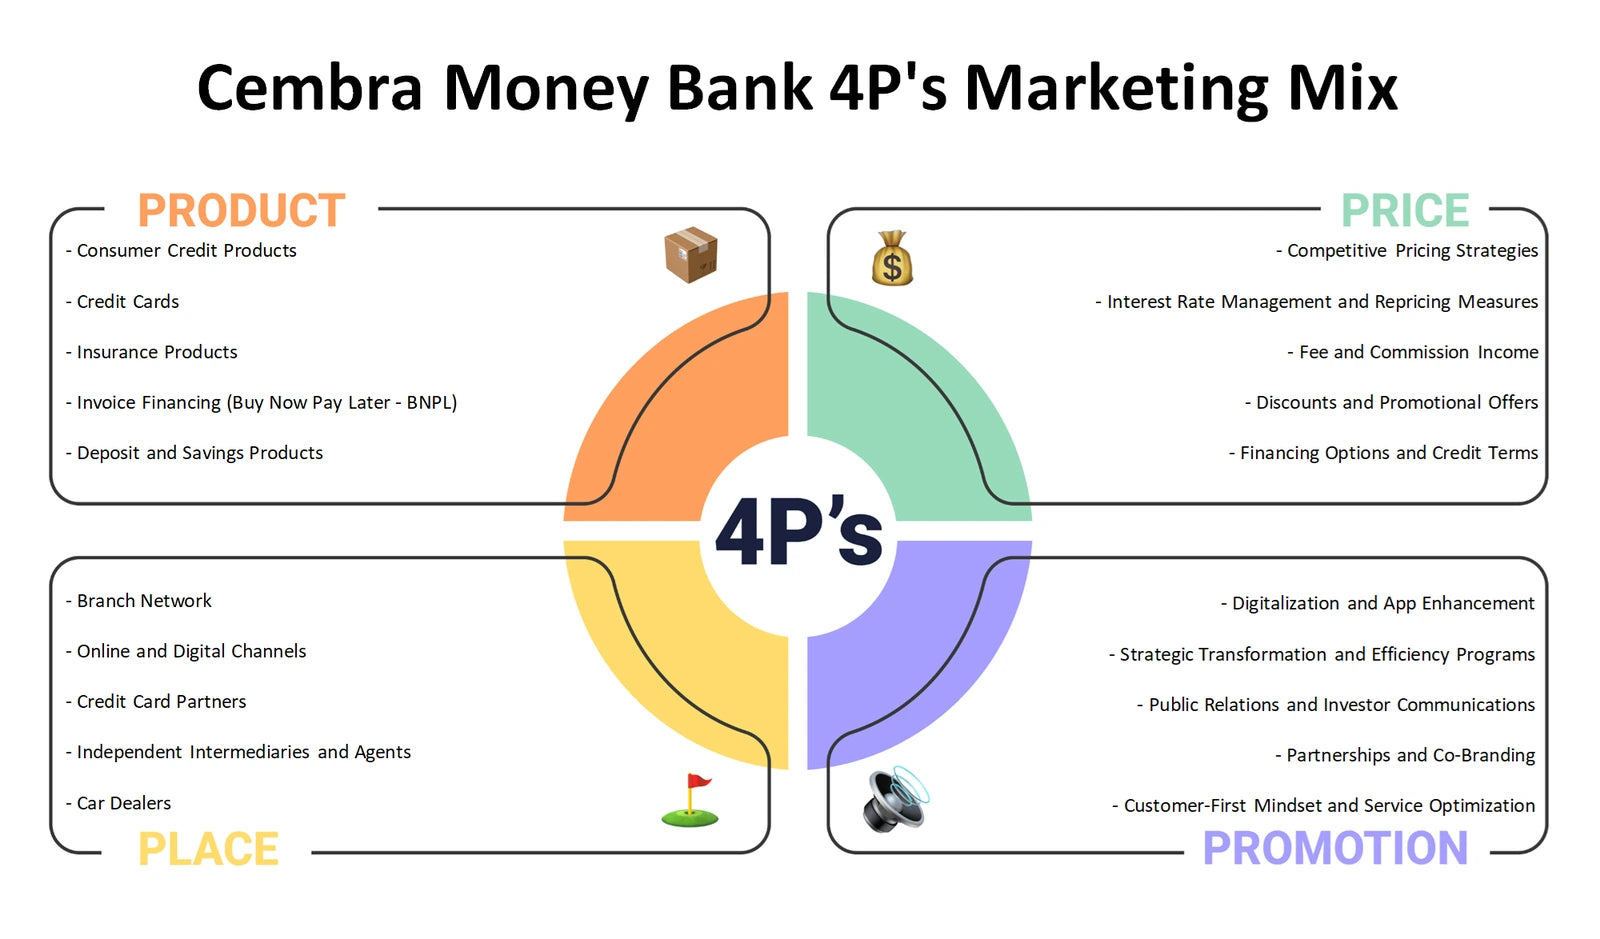
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter demand, funding conditions, technology requirements or compliance work in Swiss consumer finance?
Cembra Money Bank PESTLE analysis provides a disciplined scan of external conditions affecting consumer lending and point-of-sale finance. Political factors can include public-policy priorities that influence financial services; economic factors can test household affordability, credit demand and funding conditions. Social themes include consumer confidence, mobility preferences and expectations for straightforward digital service. Technological change is relevant to integrated dealer tools, data-supported underwriting, fraud controls and customer journeys. Legal considerations cover consumer-finance, KYC/AML, data and reporting obligations, while environmental factors can be examined through changing vehicle preferences and the broader transition affecting mobility markets. PESTEL is a common alternative spelling of PESTLE; both describe this six-part external lens.
- External signals. Separate documented developments from questions to monitor so a policy possibility is not presented as an enacted change.
- Cross-impact review. Consider how a shift in mobility demand or digital expectations might affect dealer activity, credit processes and customer communication together.
- Monitoring map. Use the Excel framework to classify signals by factor and potential impact, with the Word analysis supporting discussion of relevance and uncertainty.
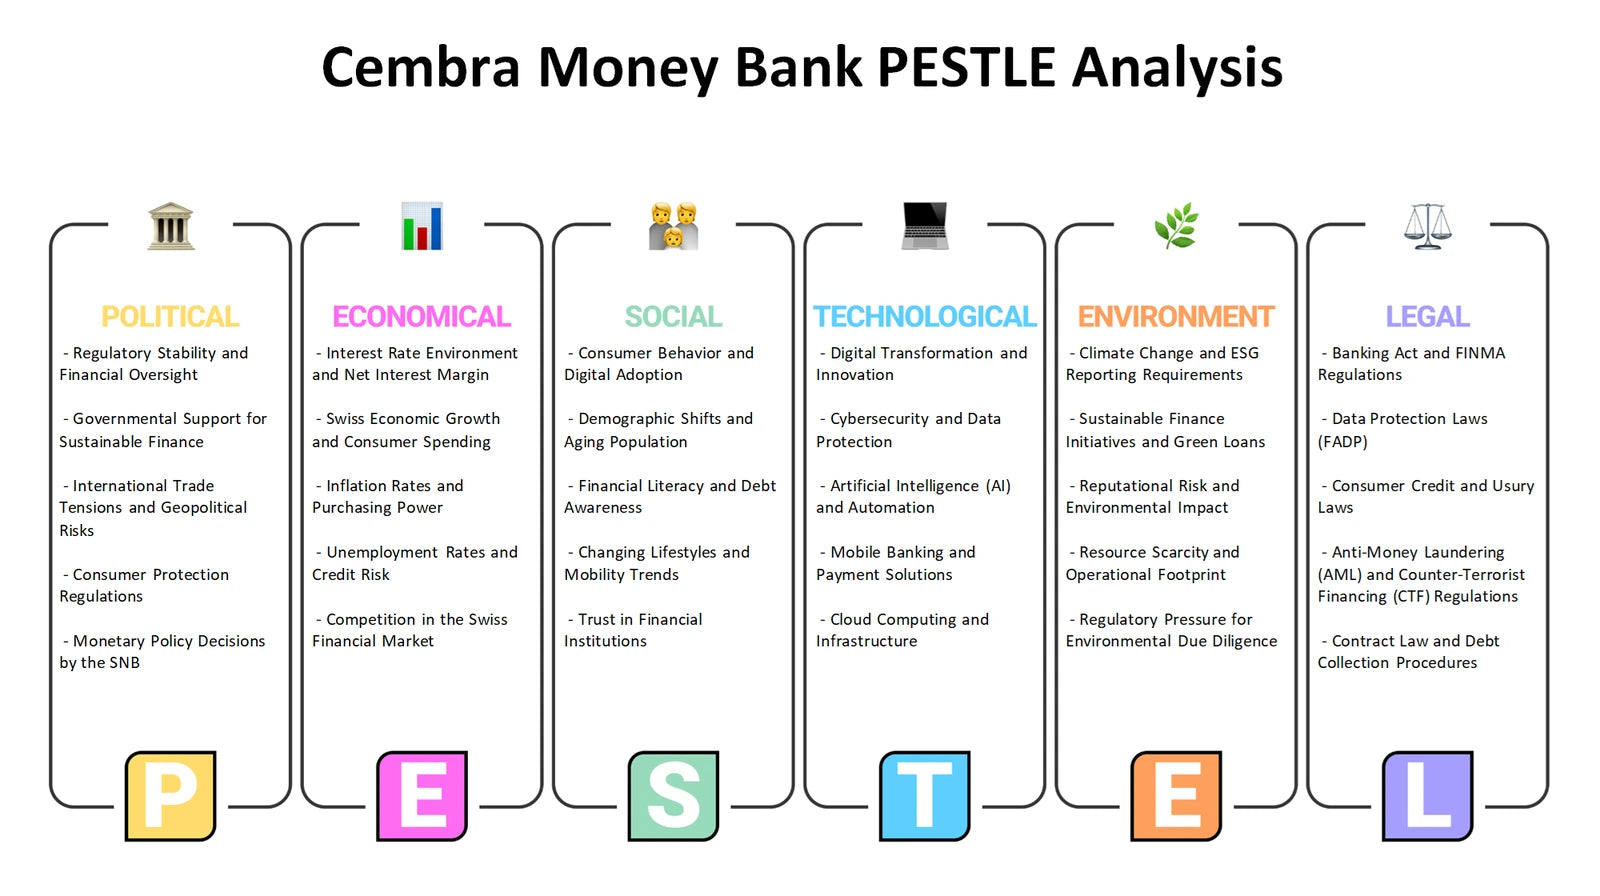
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Cembra Money Bank distinguish internal capabilities and constraints from external opportunities and threats?
A Cembra Money Bank SWOT analysis brings the earlier lenses into a decision-oriented summary. Strengths and weaknesses are internal: examples to assess may include partner-enabled origination capability, underwriting processes, compliance operations, funding diversification and the limits or dependencies within those capabilities. Opportunities and threats are external: they may arise from consumer demand, changing mobility behaviour, technology development, industry competition or regulatory expectations. The important discipline is classification. A dealer relationship, for example, is not automatically a strength; its value depends on quality, resilience and commercial fit. Likewise, a market development is not an opportunity until the company has a credible way to respond. The framework helps connect evidence with strategic choices without asserting that plausible themes are established findings.
- Internal versus external. Keep resources, processes and control issues separate from market conditions, policy developments and competitive pressures.
- Strategic fit. Test whether a possible opportunity can be matched to an internal capability, and whether a weakness increases exposure to a specific threat.
- Decision summary. Use the Excel SWOT grid to prioritise themes for review, supported by the Word analysis when explaining links and caveats.
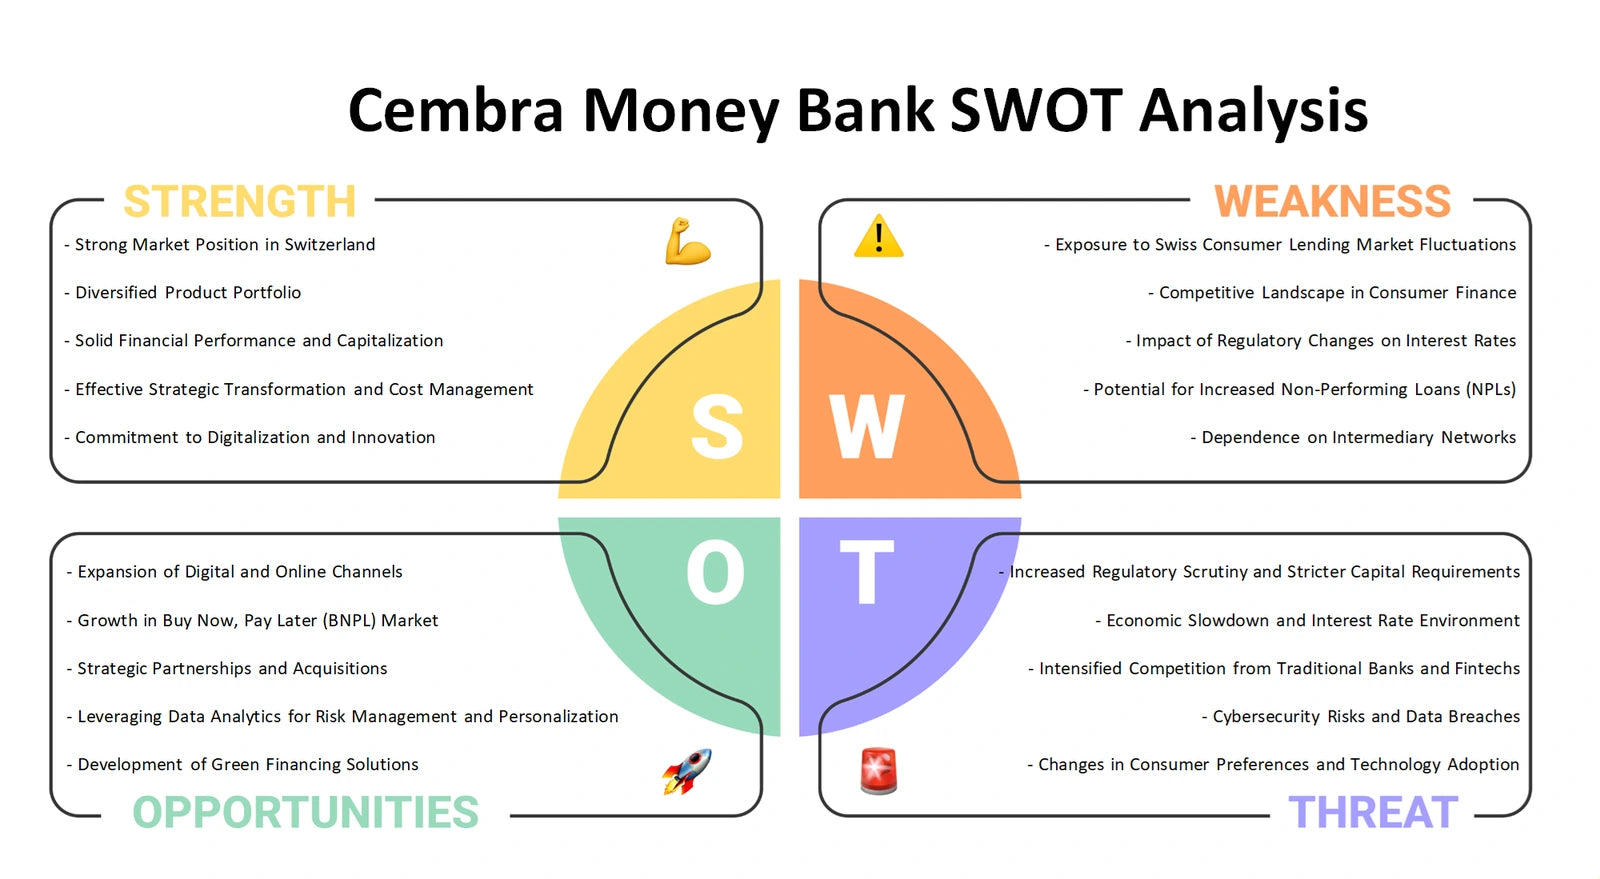
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Cembra Money Bank
Used together, the six perspectives move from portfolio questions and value creation to industry structure, customer-facing choices, external conditions and strategic fit. The Excel frameworks give a clear place to organise comparisons and assumptions, while the detailed Word analysis helps develop company-specific context around Cembra Money Bank's consumer-finance and partner-led operating model.
Company background: Cembra Money Bank — business-model context.