

Cathay General Bank: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Cathay General Bank Strategy Analysis Bundle
Cathay General Bank is the display name used for this bundle. The supplied company context describes a banking business focused on trade-finance clients, cross-border payment and remittance needs, real-estate lending relationships, and digital-banking development. Correspondent banks, property-market intermediaries and technology providers are therefore meaningful parts of the operating picture considered here.
The available material does not independently confirm a legal entity, group relationship or reporting scope for the exact displayed name, so this bundle does not present unverified financial results or market conclusions as facts. Instead, it helps examine practical questions around lending priorities, trade-finance relationships, digital service delivery, customer economics and external banking pressures through six connected strategic lenses.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking activities merit investment, selective improvement, cash discipline or reconsideration as customer demand and relative market position change?
A Cathay General Bank BCG Matrix helps organise a portfolio conversation around growth and relative market share rather than assuming that every lending, payment or relationship-banking activity deserves the same resources. Trade-finance services, real-estate lending, digital banking initiatives and other customer propositions can be compared as possible Stars, Cash Cows, Question Marks or Dogs only after defining an appropriate market and comparable competitive set. That distinction matters in banking: a valuable relationship service may support deposits, lending and fee income even when it is not a standalone high-growth product. The framework supports disciplined questions about where capability spending, risk capacity and management attention should be concentrated.
- Portfolio boundaries. Compare products or service lines only after separating client need, revenue logic, risk profile and relevant market growth.
- Relative position. Test whether perceived strength in trade finance, property lending or digital service is supported by evidence of relative share rather than anecdote.
- Planning view. Use the Excel matrix to map candidate activities and the Word analysis to document assumptions, market definitions and resource-priority questions.
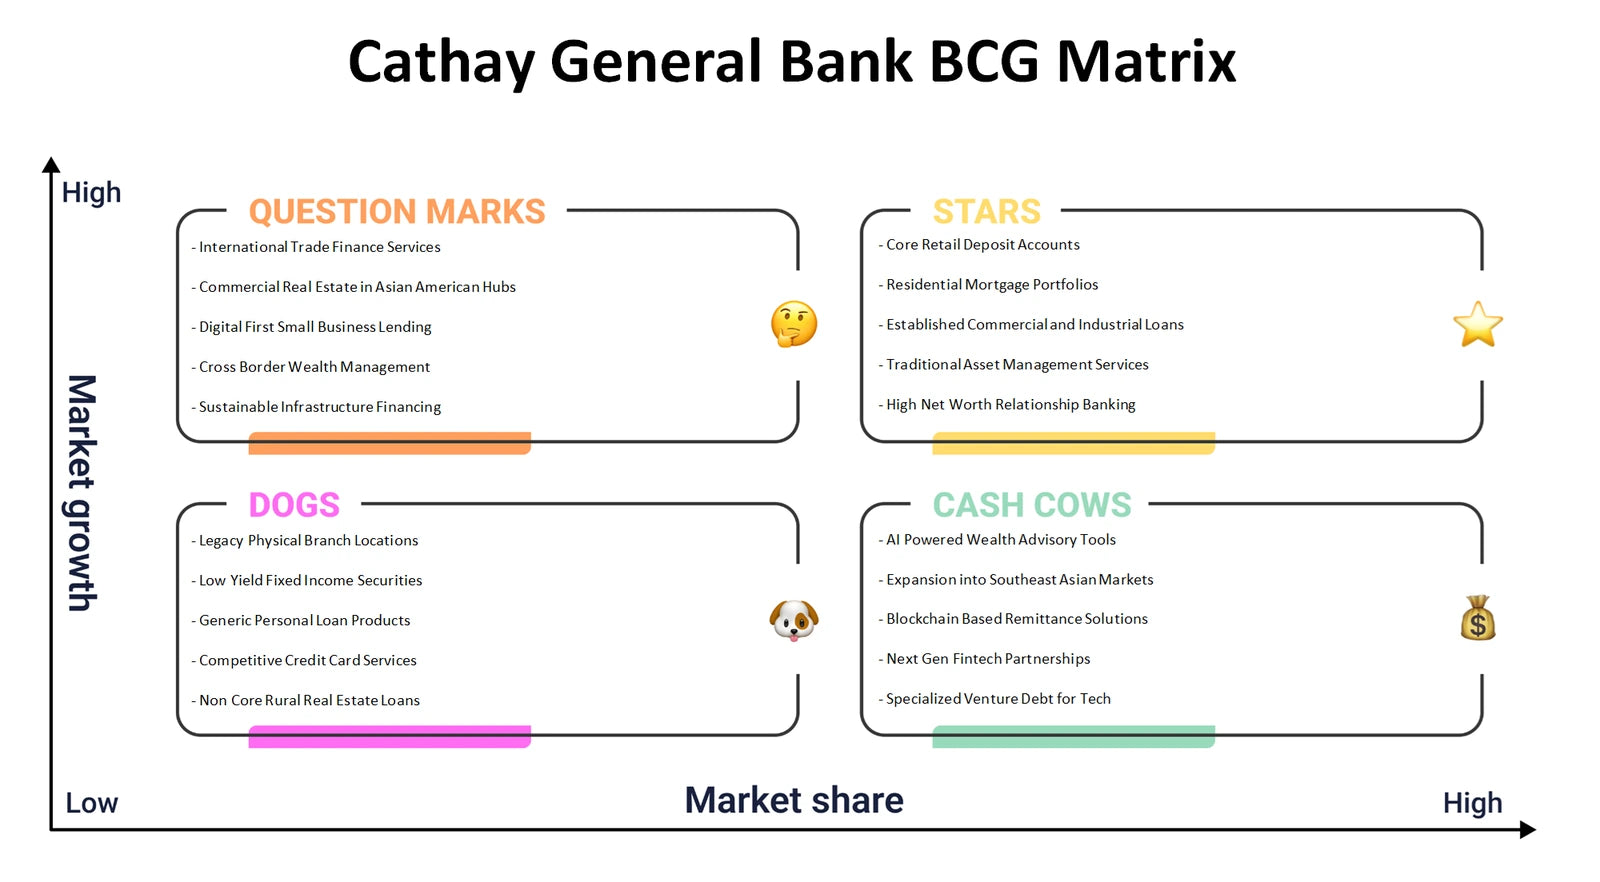
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, banking capabilities and partner networks connect to value delivery and sustainable revenue?
The Cathay General Bank Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. Its value is in showing the connections rather than treating each component in isolation. Trade-oriented businesses may require dependable cross-border settlement and finance; property borrowers may value specialist lending knowledge and relationship access; digitally engaged customers may expect convenient account and payment interactions. Correspondent banks, FinTech providers and real-estate intermediaries can be examined as partnerships that help deliver those propositions, while compliance, credit assessment, technology and relationship management can be assessed as activities and resources with real operating costs.
- Customer-value fit. Examine whether trade clients, borrowers and other banking customers receive distinct value through expertise, access, service reliability or digital convenience.
- Economic connections. Link possible interest income, fees and relationship-led revenue streams to the costs of funding, risk control, technology and partner management.
- Model workshop. Populate the Excel canvas block by block, then use the Word analysis to trace dependencies and identify questions that need evidence before decisions are made.
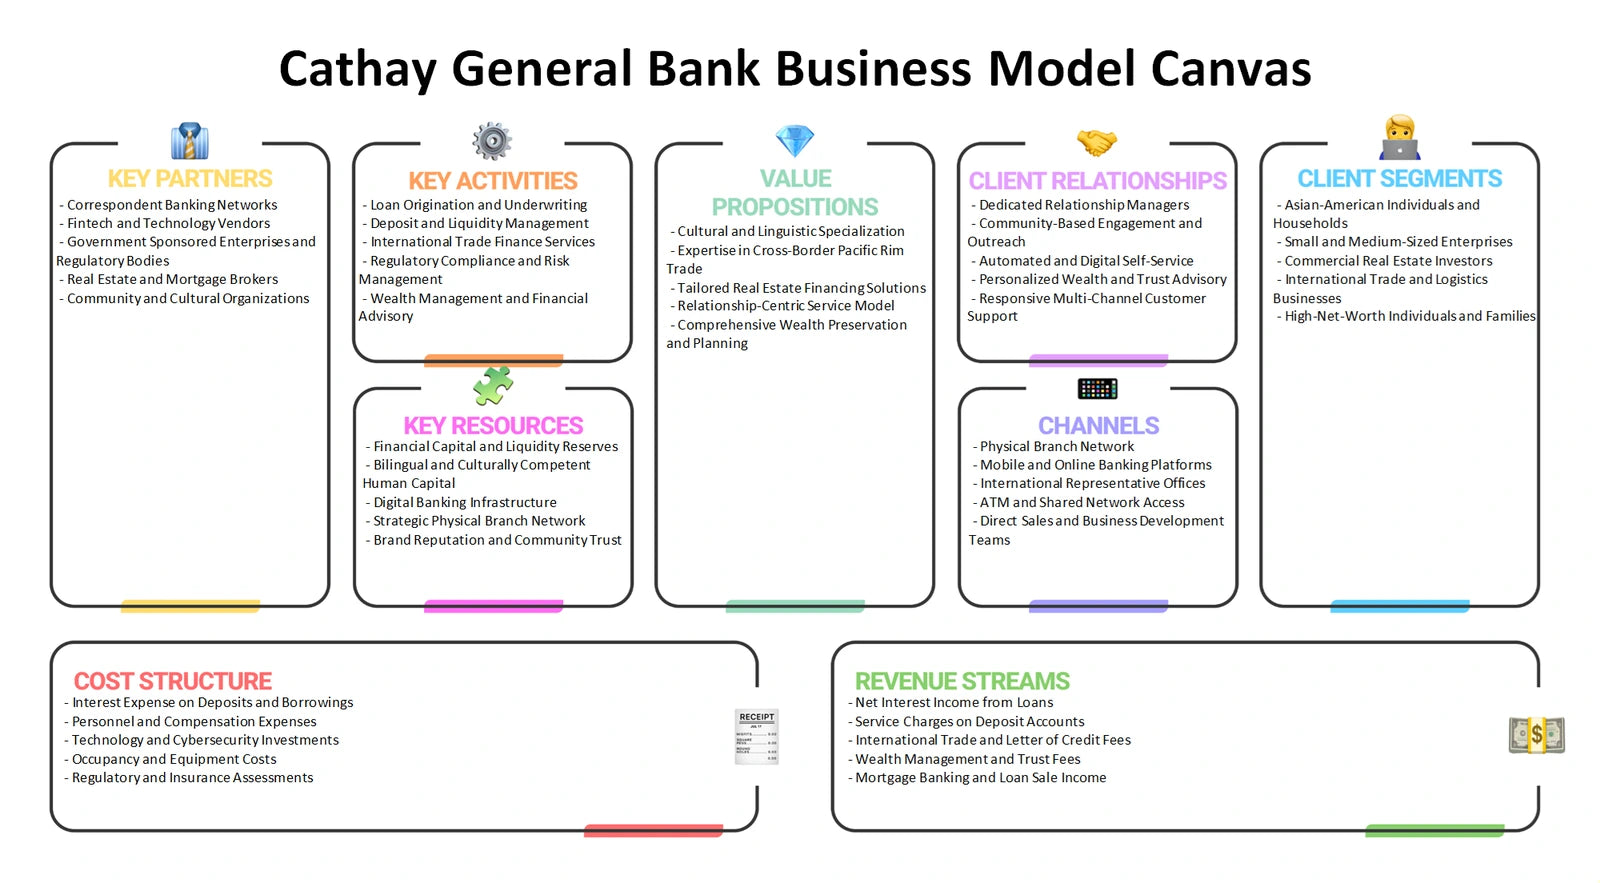
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape the attractiveness and defensibility of relationship banking, trade finance and specialist lending?
Cathay General Bank Porter's Five Forces analysis examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes in the banking markets relevant to its described activities. Rivalry can include pressure to match service, credit terms or digital capability. Supplier power is especially important because banking depends on funding, payment infrastructure, technology vendors, specialist talent and correspondent relationships. Business borrowers and trade-finance customers may hold buyer power when they can compare lenders or move payment flows. New entrants can emerge through digital financial services, while substitutes include non-bank payment methods, alternative lenders, internal corporate treasury solutions and other ways customers can finance or settle transactions. The lens does not assign force scores; it structures evidence-led assessment.
- Relationship resilience. Consider how correspondent-bank links and intermediary relationships may create service value, dependency or both.
- Alternative solutions. Compare traditional bank services with fintech-enabled payments, non-bank finance and customer self-service options that address the same needs.
- Evidence trail. Use the Excel framework to record each force and supporting observations, while the Word analysis helps explain why a pressure matters to a banking proposition.
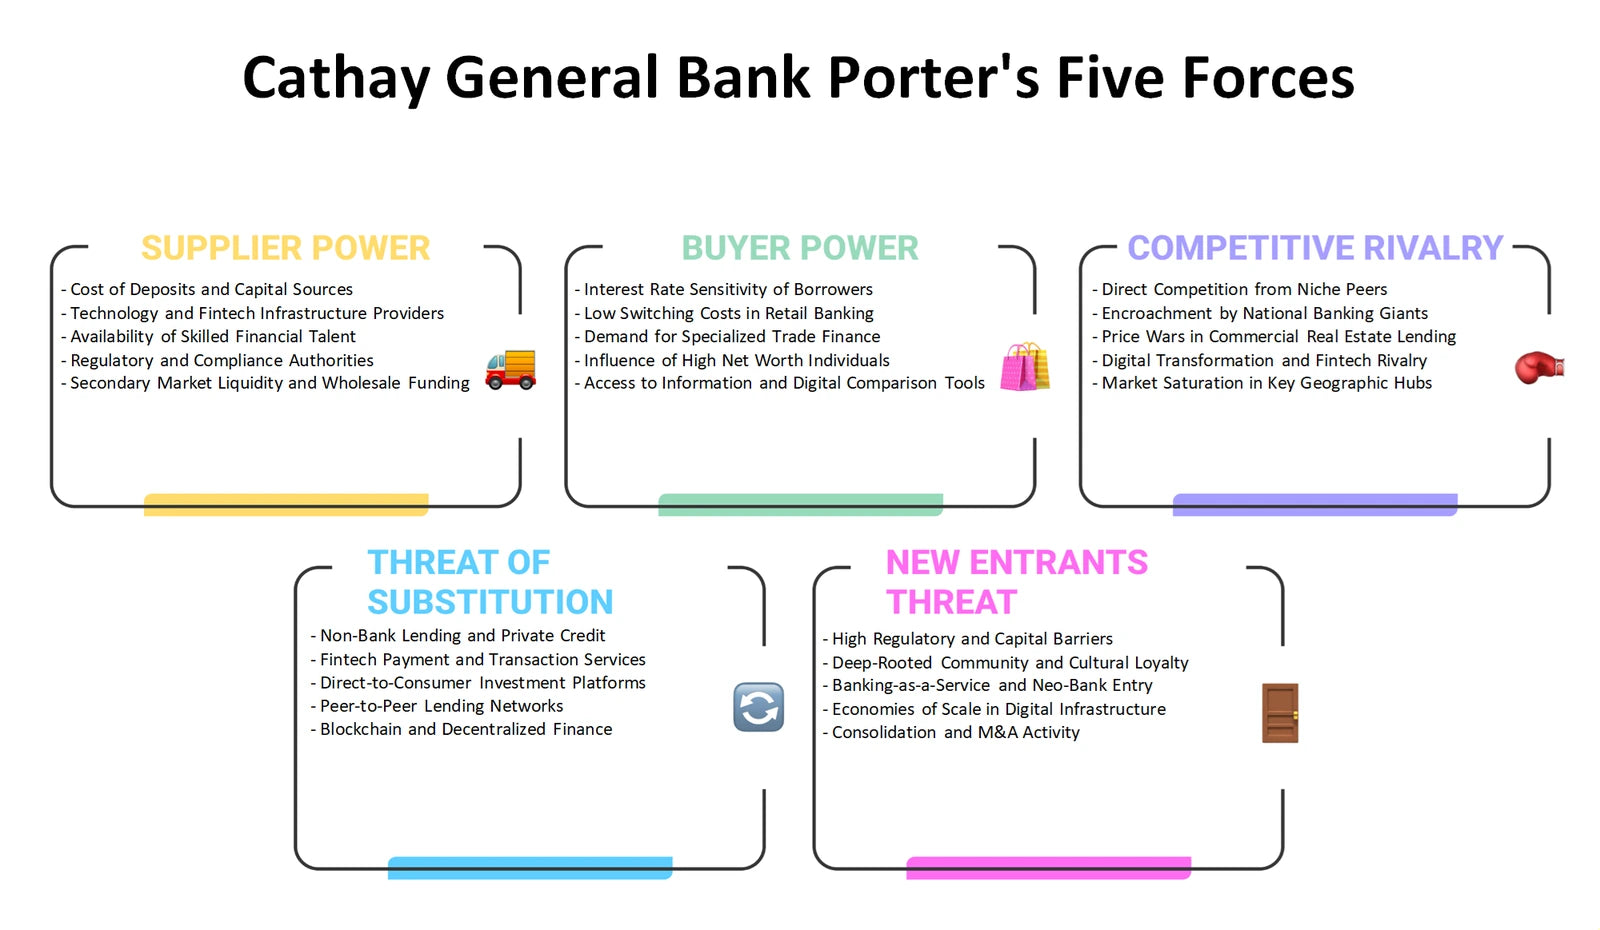
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should banking services be framed, priced, delivered and communicated to relationship-led business and lending customers?
The Cathay General Bank Marketing Mix considers Product, Price, Place and Promotion in a regulated service setting. Product can cover lending, trade-finance support, payment capabilities and digital-banking interactions, but should be assessed from the customer problem it solves rather than from a generic product list. Price is broader than a published rate: it can involve loan terms, service charges, fee transparency, risk-based economics and the overall value of a banking relationship. Place includes branches, relationship managers, digital channels and partner-enabled routes to market. Promotion must communicate relevant expertise and trust while remaining suitable for financial-services requirements. The framework helps distinguish informed positioning choices from unverified claims about campaigns, pricing or channel performance.
- Offer design. Evaluate whether propositions speak clearly to trade activity, property-finance needs, payment convenience or other documented customer priorities.
- Channel coherence. Compare the roles of personal banking relationships, digital access and referral partners across customer journeys.
- Message testing. Organise the four Ps in Excel, then use the Word analysis to turn each element into questions for customer, compliance and commercial review.
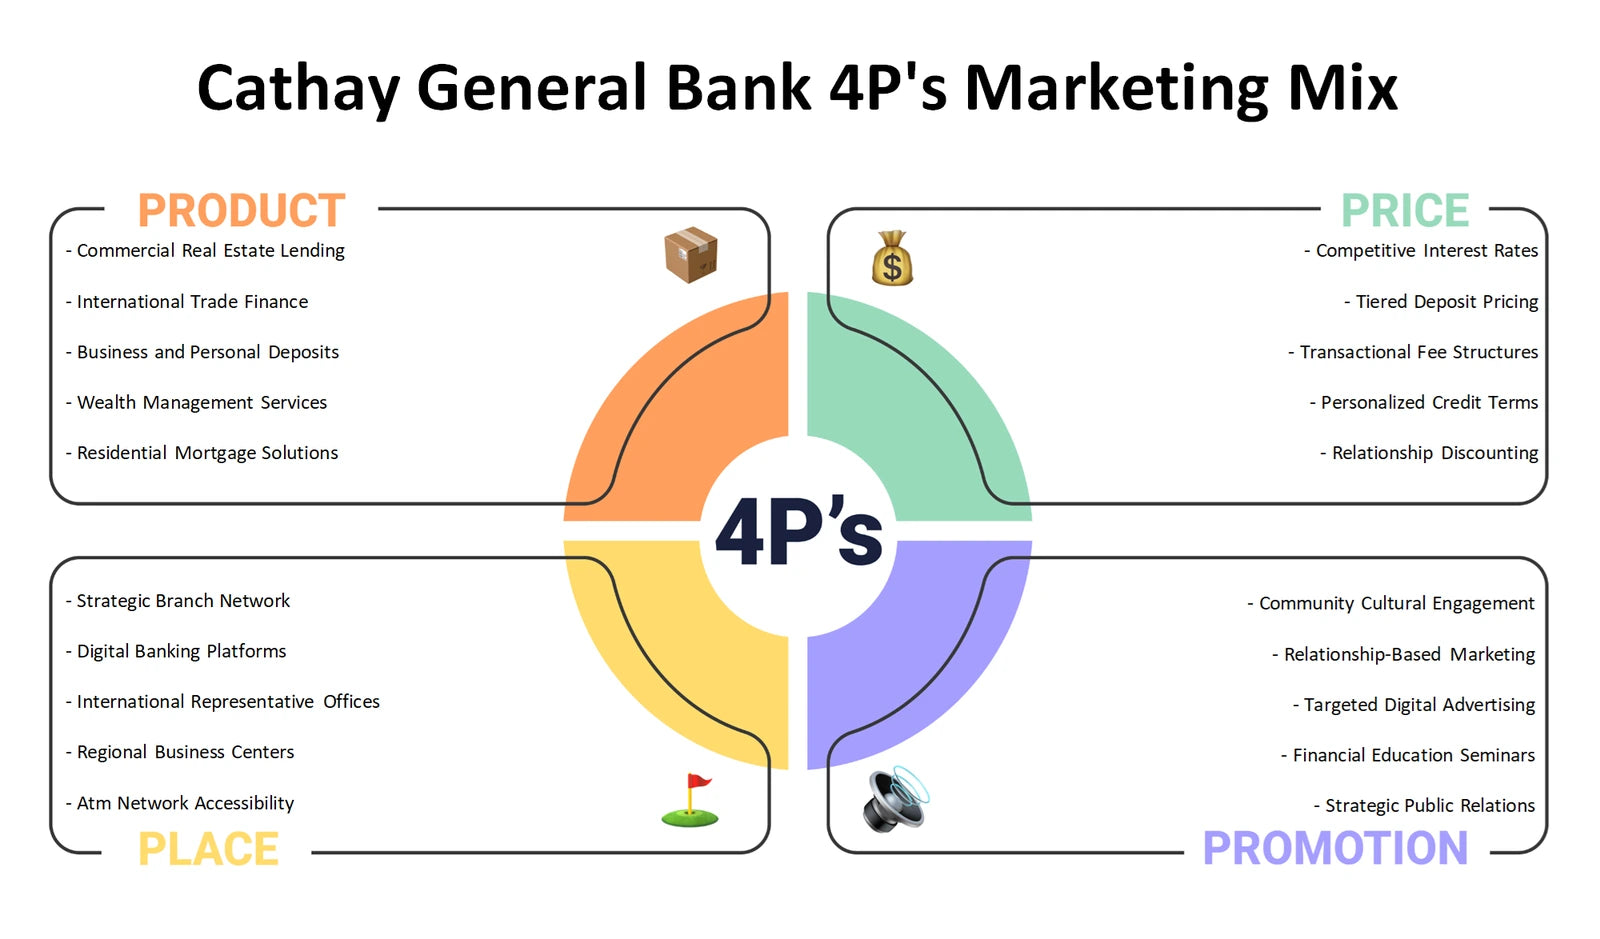
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter customer demand, risk management, technology requirements and the economics of banking services?
Cathay General Bank PESTLE analysis reviews Political, Economic, Social, Technological, Legal and Environmental influences around the supported banking context. Political and legal factors can shape supervisory expectations, cross-border activity and consumer or business protections. Economic conditions can affect borrowing demand, property-market conditions, credit quality, funding costs and trade flows; they are analytical considerations, not claims about current rates or outcomes. Social change can influence customer expectations for language, access, responsiveness and digital convenience. Technology raises questions about secure payment innovation, vendor reliance and cyber resilience. Environmental factors can matter through property collateral, business-client exposure and changing risk-assessment expectations. PESTEL is a common alternative spelling of PESTLE, and both refer to this external-environment lens.
- External signals. Separate documented developments from monitoring questions so the analysis does not mistake an emerging issue for an established company impact.
- Risk transmission. Trace how an outside change could reach lending, trade finance, payments, operations, customers or partner relationships.
- Scenario register. Use the Excel categories to capture external factors and the Word analysis to develop context, possible implications and follow-up research priorities.
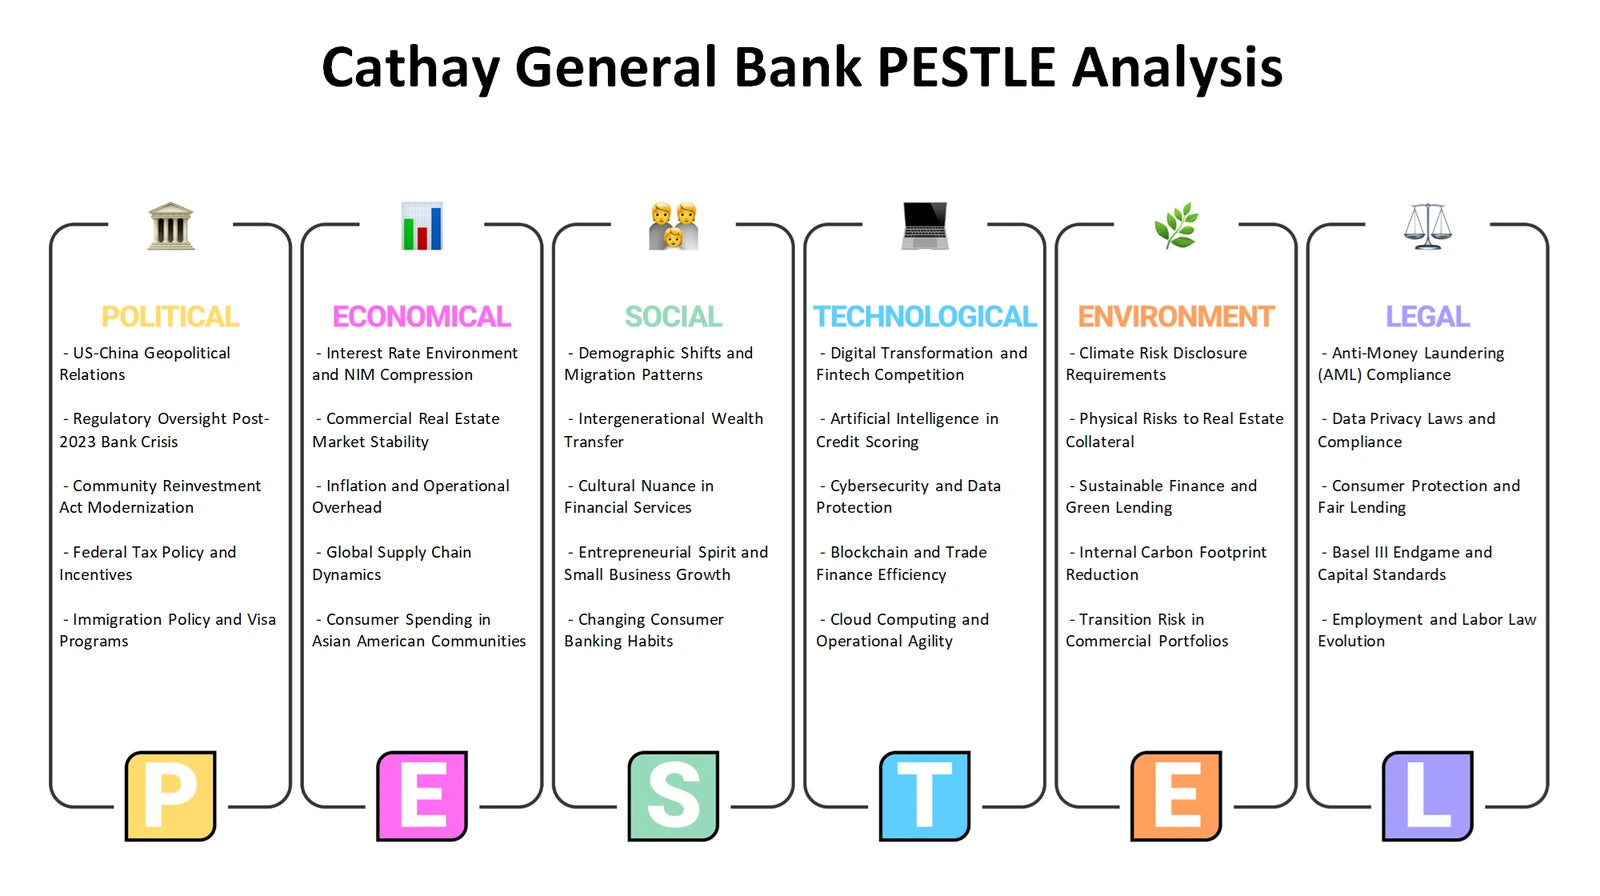
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and limitations be assessed alongside external openings and risks without confusing evidence with assumptions?
A Cathay General Bank SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. The supplied context makes relationship networks, trade-finance connectivity, specialist real-estate lending knowledge and digital-development partnerships relevant themes to investigate; it does not prove that each is a confirmed strength. Internal questions can cover expertise, service processes, technology integration, concentration, control systems and capacity. External opportunities may arise from changing client needs for cross-border payments, business finance or digital access, while threats may include competition, credit deterioration, cyber risk, shifting customer expectations and regulatory change. Keeping the categories distinct helps prevent an external market trend from being presented as an existing internal capability, or vice versa.
- Capability test. Review potential internal advantages and constraints against evidence on people, processes, partner dependence and customer service delivery.
- Strategic fit. Match external opportunities or threats to the capabilities required to respond, rather than assuming every market change should be pursued.
- Action framing. Use the Excel SWOT grid to prioritise discussion points, then rely on the Word analysis to explain links, assumptions and sensible next questions.
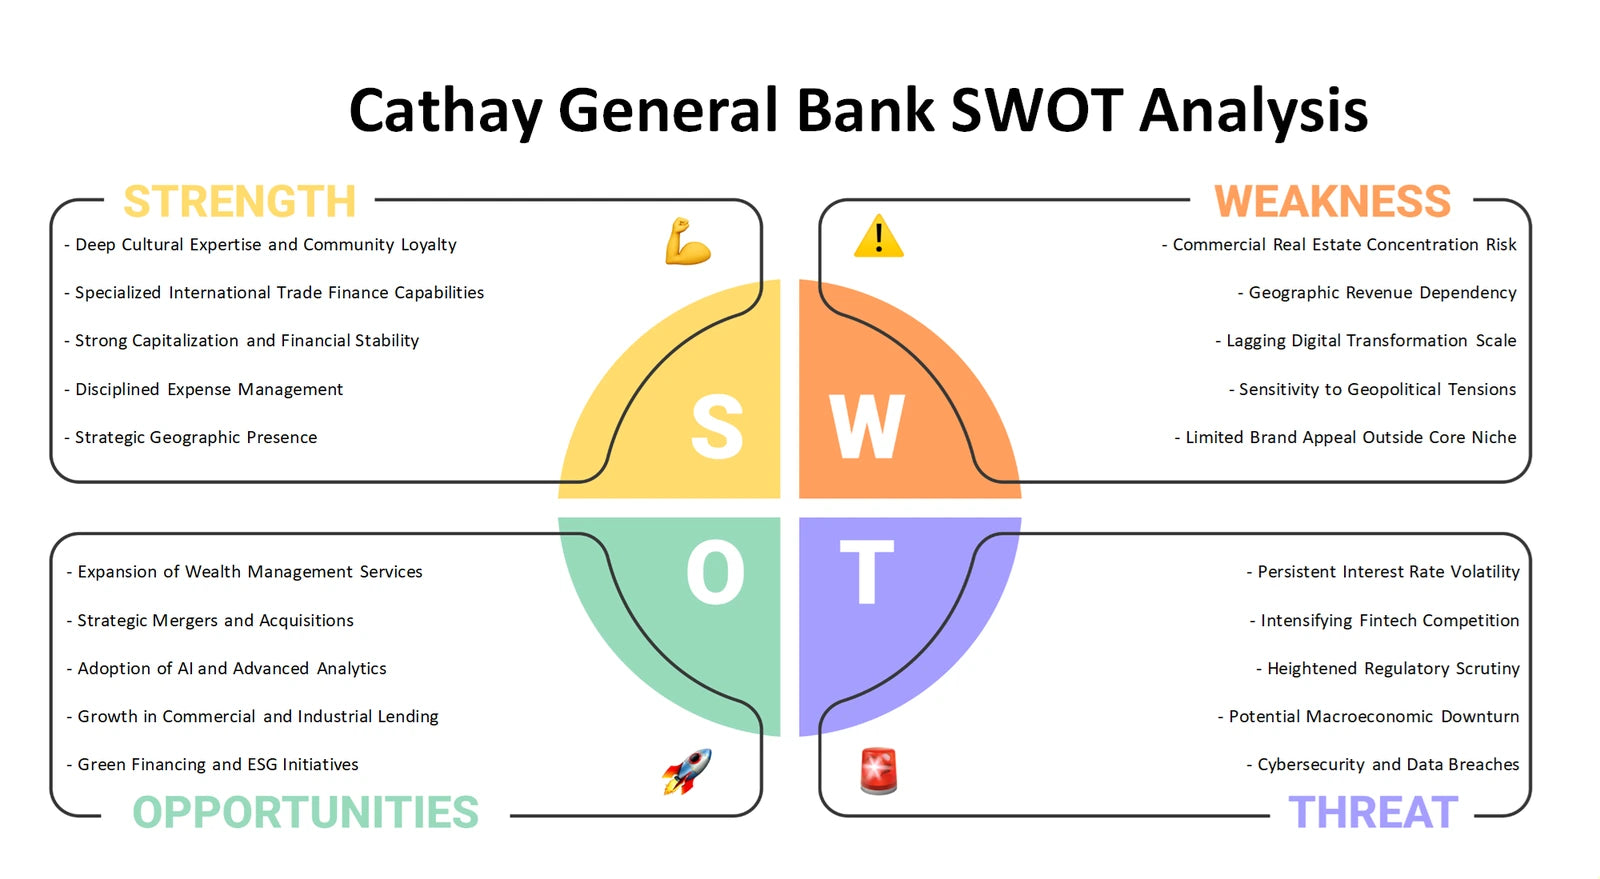
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the banking model behind them
Together, the six perspectives move from portfolio priorities and value creation to industry pressure, customer-facing choices, external conditions and strategic fit. The Excel frameworks provide structured places to compare issues and capture assumptions, while the detailed Word analyses help develop the reasoning behind them. For the Cathay General Bank context, this creates a more joined-up basis for examining trade-finance relationships, real-estate lending, digital service development and the operational demands that connect them.
Company background: Cathay General Bank — product-context page.