

Credit Agricole Nord de France: Lending Economics and Product Innovation – Six-Framework Review

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Credit Agricole Nord de France Strategy Analysis Bundle
Credit Agricole Nord de France is presented in the matching product context as a regional banking business serving clients through financial services, digital innovation activity and property-finance relationships. Its stated collaboration with fintech firms and innovation hubs, alongside financing links with developers, construction businesses and social-housing organisations, makes customer trust, lending discipline and local economic relevance central strategic themes.
These circumstances create practical questions rather than predetermined conclusions: which activities deserve resources, how can digital partnerships support customer value, and what external conditions may affect lending and property demand? The bundle brings six connected lenses together so buyers can examine those questions in structured Excel frameworks and detailed Word analysis, without treating the preview images as the complete products.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
How should Credit Agricole Nord de France compare the growth outlook and relative market position of its banking and financing activities when allocating attention and resources?
The Credit Agricole Nord de France BCG Matrix provides a disciplined way to review a portfolio rather than assuming every service should receive the same investment. It uses market growth and relative market share to test whether activities may resemble Stars, Cash Cows, Question Marks or Dogs. For this business, the exercise can compare established relationship-led lending with newer digital-service or partnership-led opportunities, while recognising that a quadrant is an analytical result, not a fact established by the preview. It is useful where property finance, customer service capacity, technology investment and local commercial priorities compete for management focus.
- Portfolio boundaries. Separate lending, customer-service and innovation-related activities into meaningful comparison units before applying the matrix.
- Resource trade-offs. Consider whether mature activities could support selective investment in higher-growth client needs without assuming a placement in advance.
- Working comparison. Use the Excel framework to map assumptions and relative positions, then use the Word analysis to interpret the strategic implications behind them.
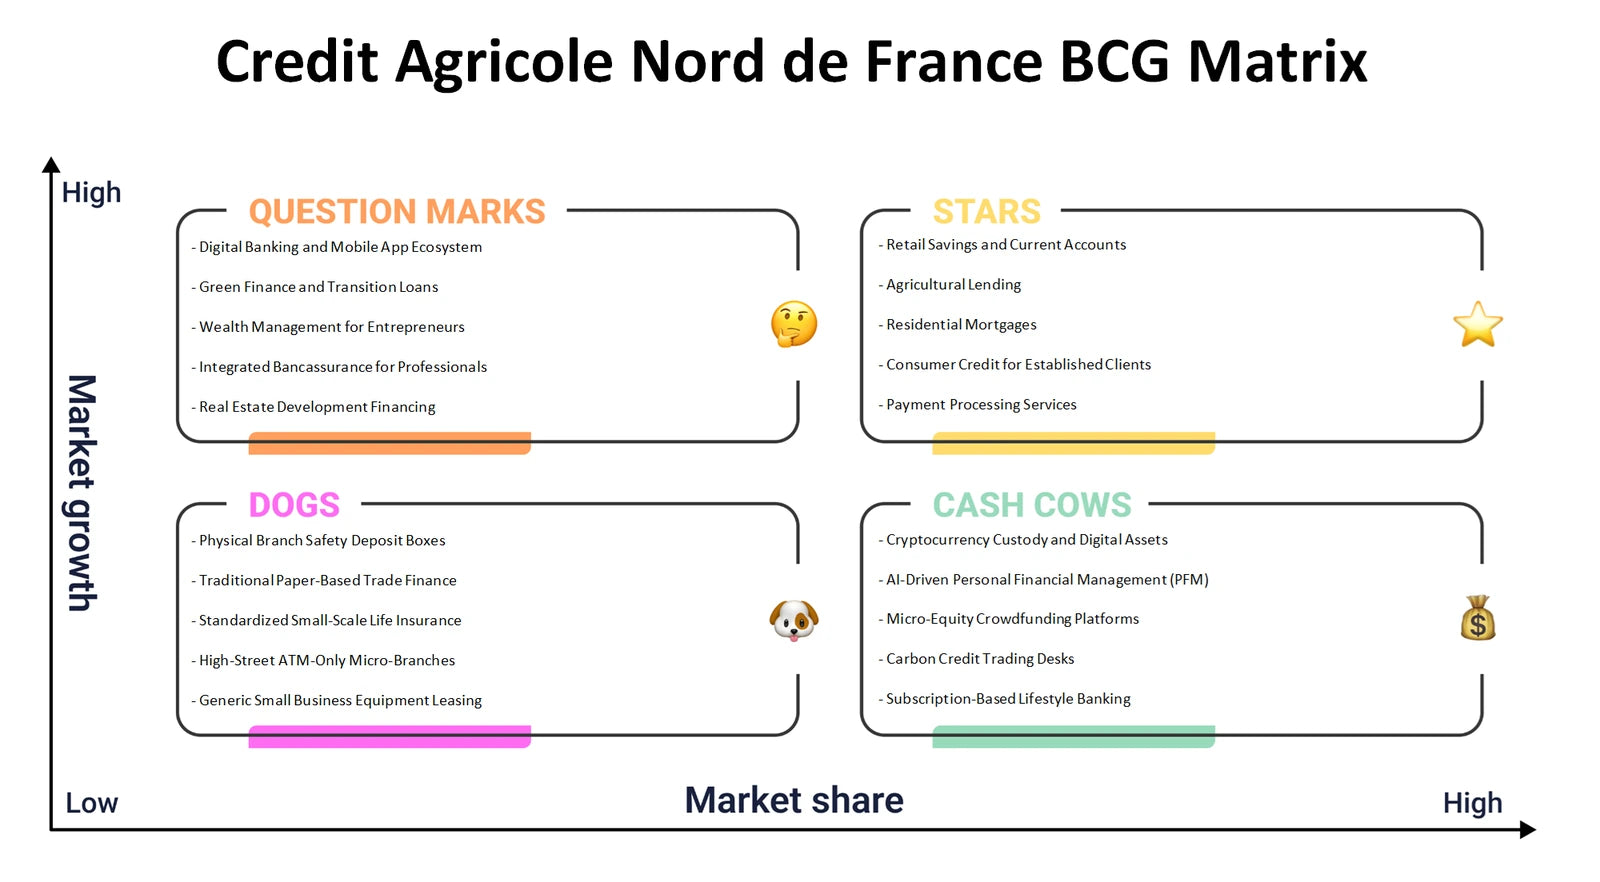
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, property-finance activity and innovation partnerships fit together to create value and sustain the economics of Credit Agricole Nord de France?
The Credit Agricole Nord de France Business Model Canvas helps connect all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. The product context makes fintech and innovation-hub collaboration, plus relationships with property-sector organisations, especially relevant areas to test. The canvas can examine how those partnerships may support financial-service delivery while also requiring technology, expertise, governance and operating investment. It does not presume a specific revenue mix or cost profile; instead, it helps make the connections between clients served, services delivered and economic logic visible.
- Customer logic. Distinguish the needs of individual clients from organisations involved in housing and property development, where relevant to the analysis.
- Delivery chain. Trace how channels, relationship management, key activities and external partners contribute to an accessible and trusted service experience.
- Model alignment. Complete the Excel blocks as one connected operating model and use the Word analysis to explore tensions between value creation, resources and costs.
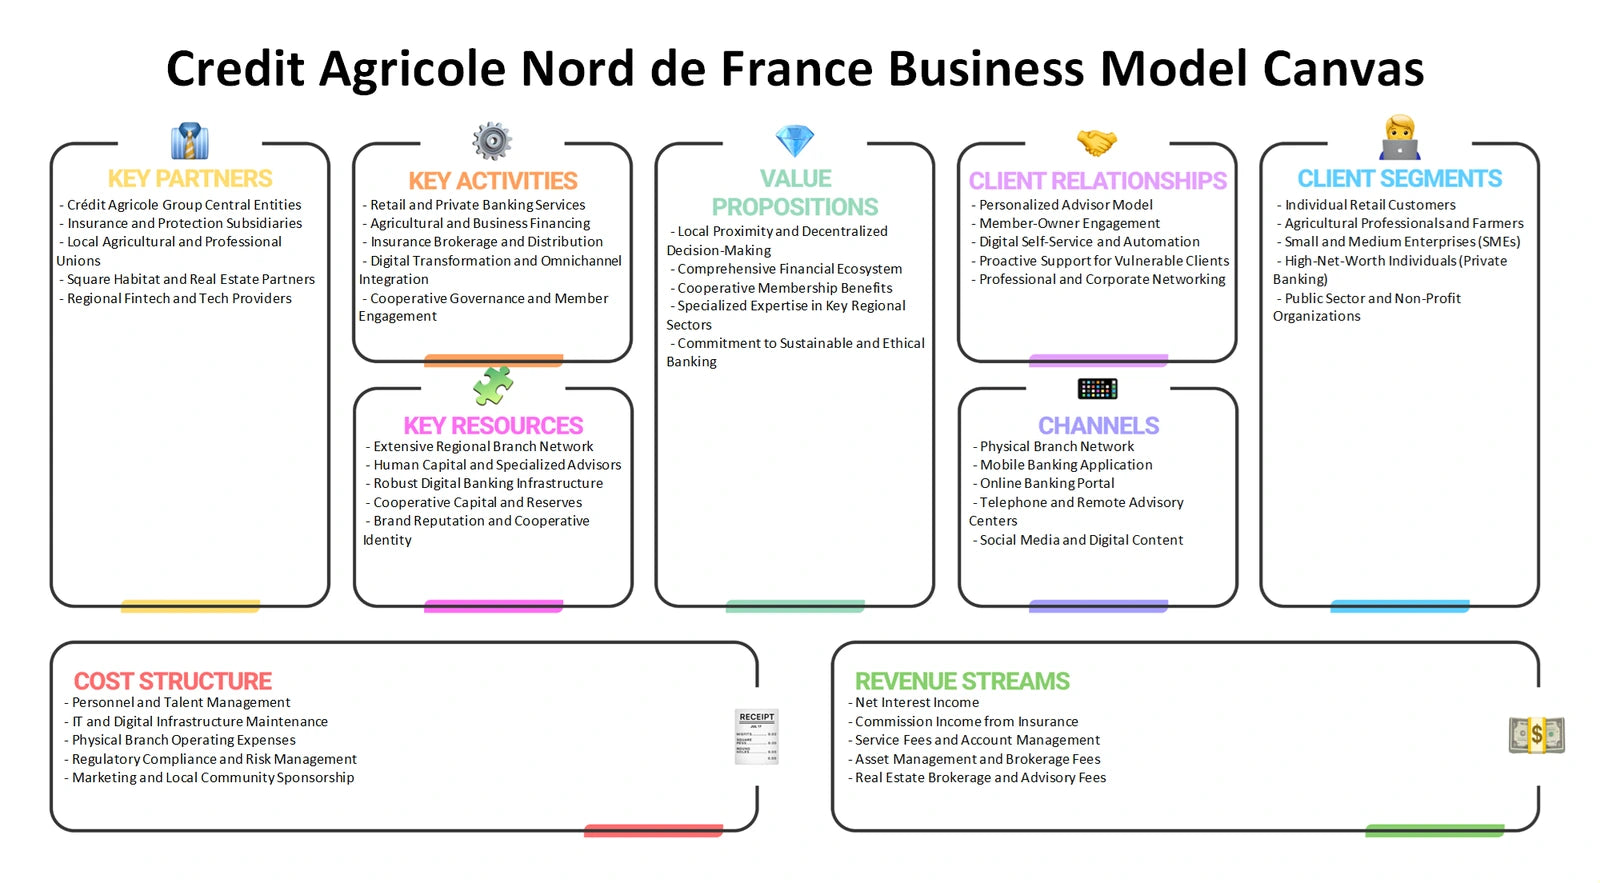
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Which industry pressures could most influence the attractiveness of the banking and property-finance activities considered for Credit Agricole Nord de France?
Credit Agricole Nord de France Porter's Five Forces examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes around its relevant financial-service markets. Banking competition is not limited to other banks: digital platforms, alternative finance options and other ways customers meet payment, savings or borrowing needs can act as substitutes. Supplier power can include dependence on specialised technology, talent or partnership inputs, while buyer power may differ between retail clients and professional property-related counterparties. The framework helps distinguish a broad industry assumption from the particular pressures that deserve validation for this business.
- Competitive pressure. Assess whether service differentiation, relationship depth and digital convenience may matter more than simple product similarity in particular client decisions.
- Dependency exposure. Examine how technology providers, specialist capabilities and partnership arrangements could affect costs, resilience or negotiating leverage.
- Force testing. Record evidence and open questions in Excel, then use the Word analysis to explain how the five pressures may interact rather than treating them as isolated scores.
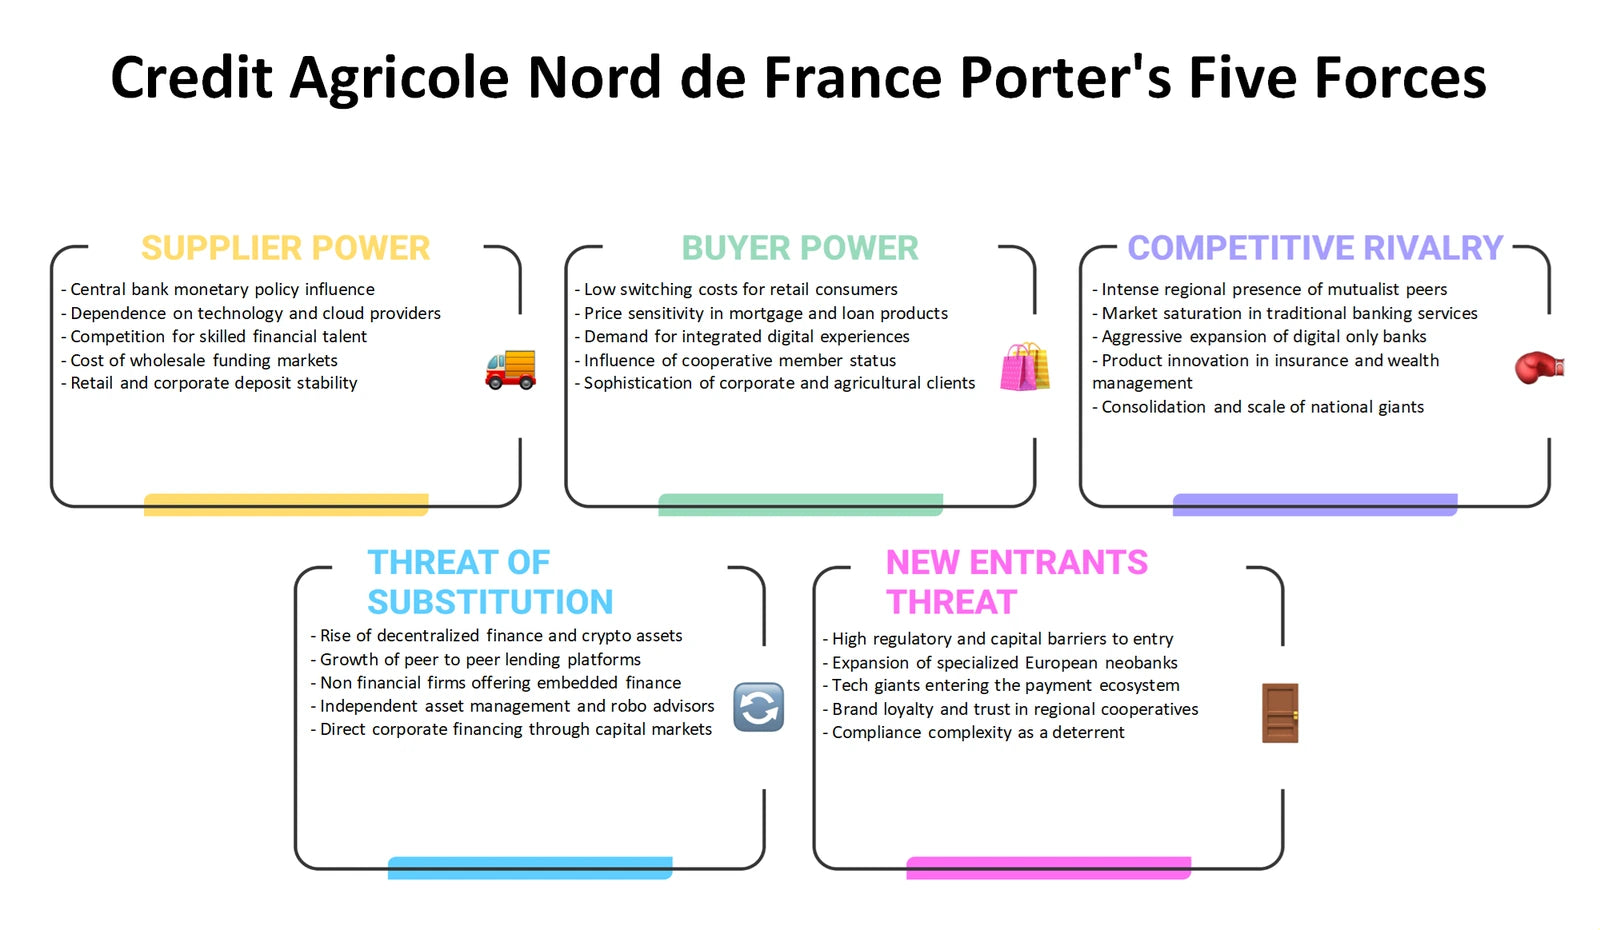
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Credit Agricole Nord de France align financial-service design, pricing logic, access routes and communications with the needs of relationship-based banking customers?
The Credit Agricole Nord de France Marketing Mix considers Product, Price, Place and Promotion in a regulated service setting. Product can cover the financial solutions and customer experience examined in the analysis; Price concerns the logic and transparency through which services are valued, not invented rate or fee claims. Place asks how relationship channels and digital access can work together for clients, including organisations connected to property development. Promotion considers how clear, responsible communication may support trust when explaining complex financial choices. Looking at all four Ps together helps avoid treating digital innovation as a channel decision alone.
- Service proposition. Compare customer problems with the clarity, suitability and accessibility of the financial-service offer being evaluated.
- Channel coherence. Test whether digital touchpoints and relationship-led contact serve different moments in the client journey without creating confusion.
- Planning tool. Use Excel to organise the four Ps by customer need and use the Word analysis to add the rationale, constraints and questions behind each choice.
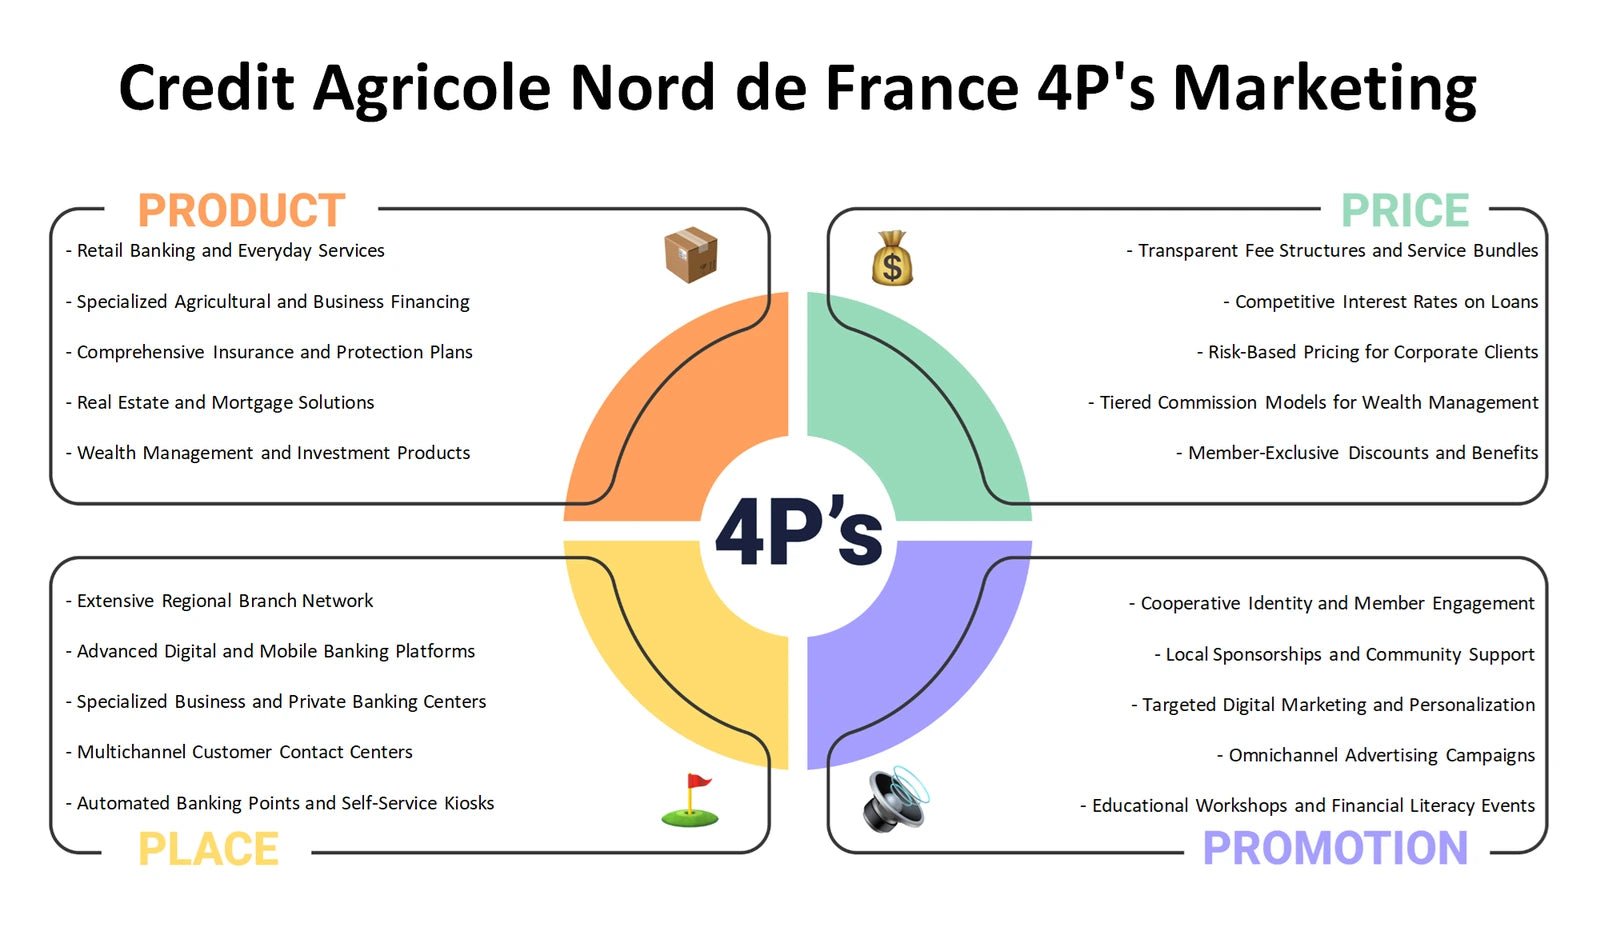
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should Credit Agricole Nord de France monitor when considering lending, digital financial services and local property-related demand?
The Credit Agricole Nord de France PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. For a banking business with a stated connection to property financing and fintech collaboration, economic conditions can affect customer borrowing capacity and project activity, while political and legal factors may shape the operating environment. Social expectations around accessible, trusted service may affect client relationships; technological change can alter delivery and security demands. Environmental considerations can also matter when stakeholders assess housing, construction and long-term lending choices. These are categories for investigation, not claims that a particular policy, rate or rule has changed.
- External watchlist. Identify which outside signals could influence housing-related finance, customer confidence, technology adoption or partnership conditions.
- Cause and effect. Link each factor to a plausible operational, customer or risk-management question instead of listing trends without relevance.
- Scenario record. Use the Excel framework to track factors and possible implications, with the Word analysis providing context for prioritising discussion topics.
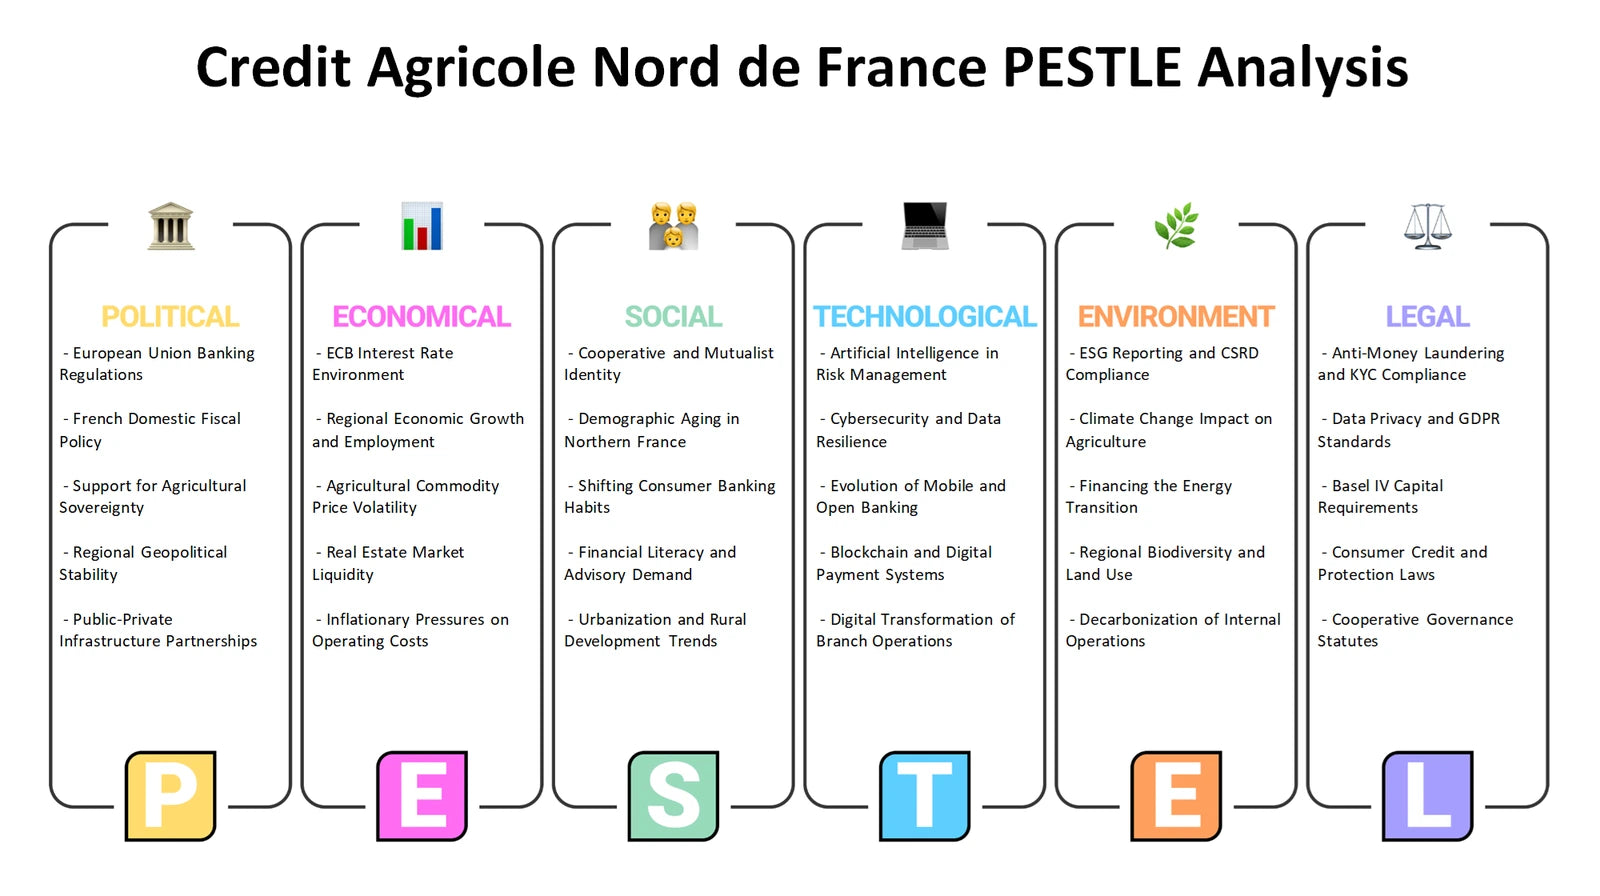
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Credit Agricole Nord de France distinguish its internal capabilities and constraints from external opportunities and threats when evaluating strategic options?
The Credit Agricole Nord de France SWOT analysis creates a useful boundary between internal Strengths and Weaknesses, and external Opportunities and Threats. The supplied context suggests themes worth examining, such as customer relationships, experience with property-finance ecosystems and innovation-oriented partnerships, but it does not establish them as proven strengths. Similarly, technology investment demands, operating complexity, changing customer expectations and broader economic conditions should be assessed rather than assumed to be confirmed weaknesses or threats. The value of SWOT is in testing how internal resources and limitations might fit with an external environment already explored through PESTLE and Five Forces.
- Evidence discipline. Classify a capability as internal only where it can be supported, and keep external market conditions in opportunities or threats.
- Strategic fit. Explore whether partnership activity or relationship-based knowledge could help address selected customer or market opportunities.
- Decision synthesis. Use the Excel grid to compare themes side by side, then consult the Word analysis to develop reasoned links between the four categories.
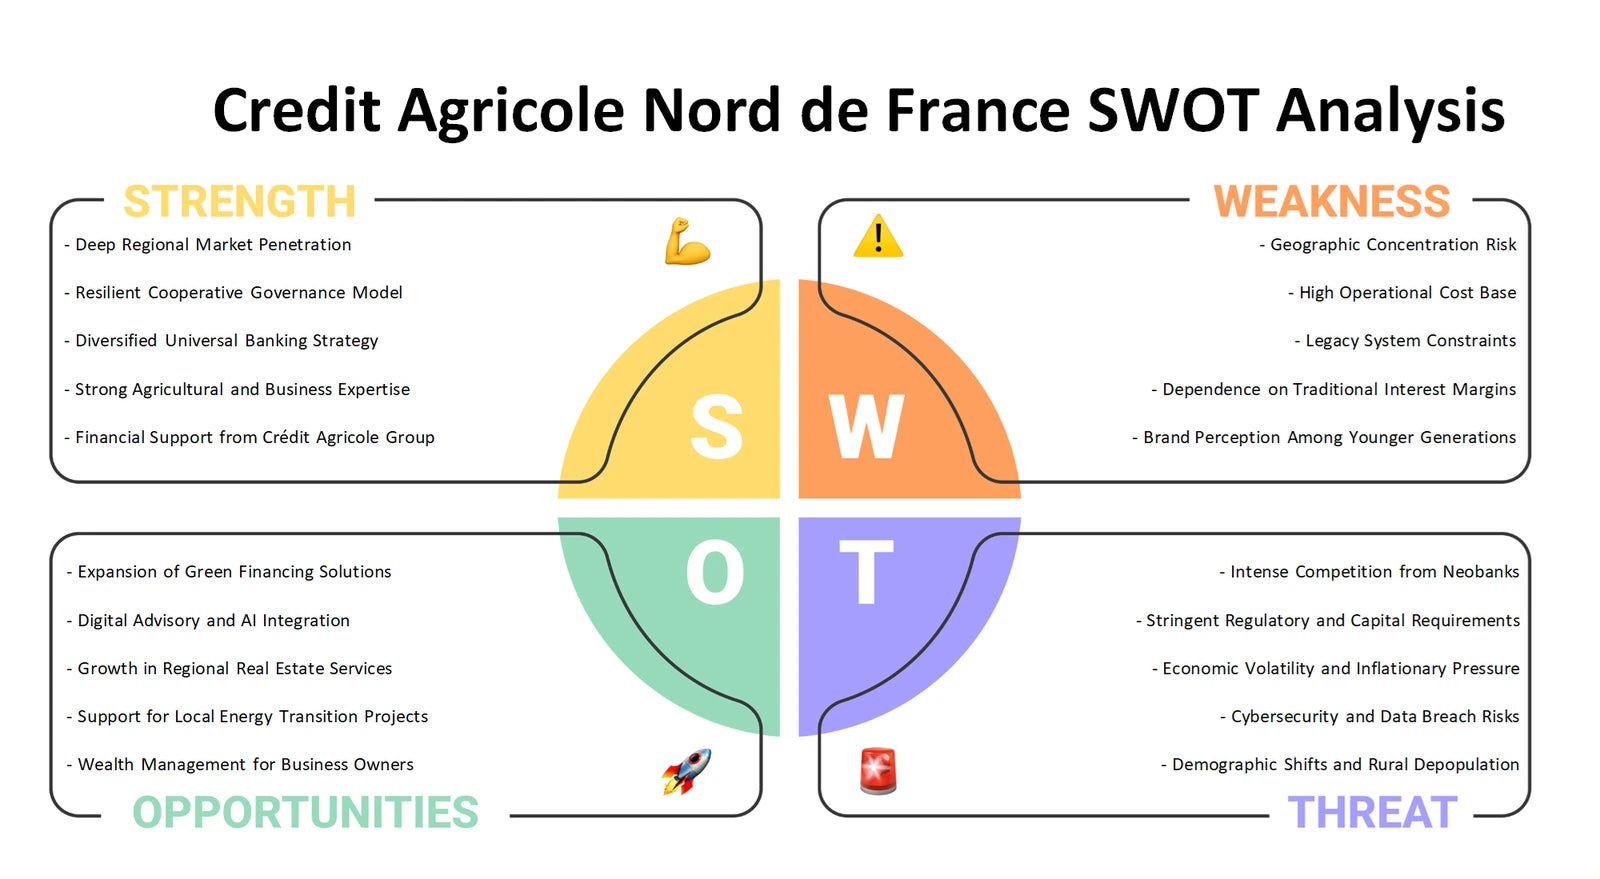
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of the banking business
Together, the six perspectives move from portfolio priorities and value creation to competitive pressure, customer-facing choices, external conditions and strategic fit. The Excel frameworks help organise comparisons and questions, while the detailed Word analysis helps develop the reasoning behind them. For Credit Agricole Nord de France, this creates a more connected way to examine financial services, digital collaboration and property-finance relationships without presenting assumptions as settled findings.
Company background: Credit Agricole Nord de France — product-context page.