

Brookfield Reinsurance: Annuity Products, Competition and Customer Choice – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Brookfield Reinsurance Strategy Analysis Bundle
Brookfield Reinsurance is used here for Brookfield Reinsurance Ltd., the Bermuda-based reinsurance business associated with Brookfield. Its core clients are ceding insurance companies seeking capital and risk-transfer solutions, particularly around life and annuity liabilities. The business model also connects insurance balance-sheet management with access to Brookfield Asset Management’s alternative-investment capabilities across areas such as credit, infrastructure, renewable power, real estate and private equity.
That combination makes differentiation, capital discipline and customer choice important strategic questions. How can Brookfield Reinsurance make its risk-transfer proposition compelling to ceding insurers? Which activities deserve balance-sheet capacity? How might changing investment conditions affect the spread between asset returns and long-duration obligations? The six connected frameworks help organize those questions without assuming unverified market shares, financial results or portfolio outcomes.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance, reinsurance and asset-management activities merit scarce capital when customer demand and competitive position differ?
A Brookfield Reinsurance BCG Matrix provides a disciplined way to compare possible business lines through market growth and relative market share, rather than treating every source of premium, fee income or investment opportunity as equally attractive. For a reinsurer working with life and annuity liabilities, the question is not simply whether a market is large; it is whether a capability can be scaled while preserving underwriting discipline, capital efficiency and asset-liability alignment. The framework uses Stars, Cash Cows, Question Marks and Dogs as analytical categories, not as pre-assigned labels for Brookfield Reinsurance businesses. It helps the buyer test where customer demand for risk transfer may be expanding, where established relationships may generate dependable economics, and where resource commitments require closer scrutiny.
- Portfolio comparison. Examine established reinsurance relationships, possible capital-solution offerings and investment-linked capabilities against both growth prospects and relative competitive strength.
- Capacity trade-off. Consider how balance-sheet capacity, specialist underwriting attention and asset-management access might be allocated when several opportunities compete for capital.
- Working view. Use the Excel matrix to map candidate activities and use the Word analysis to record the assumptions, evidence gaps and priority questions behind each placement.
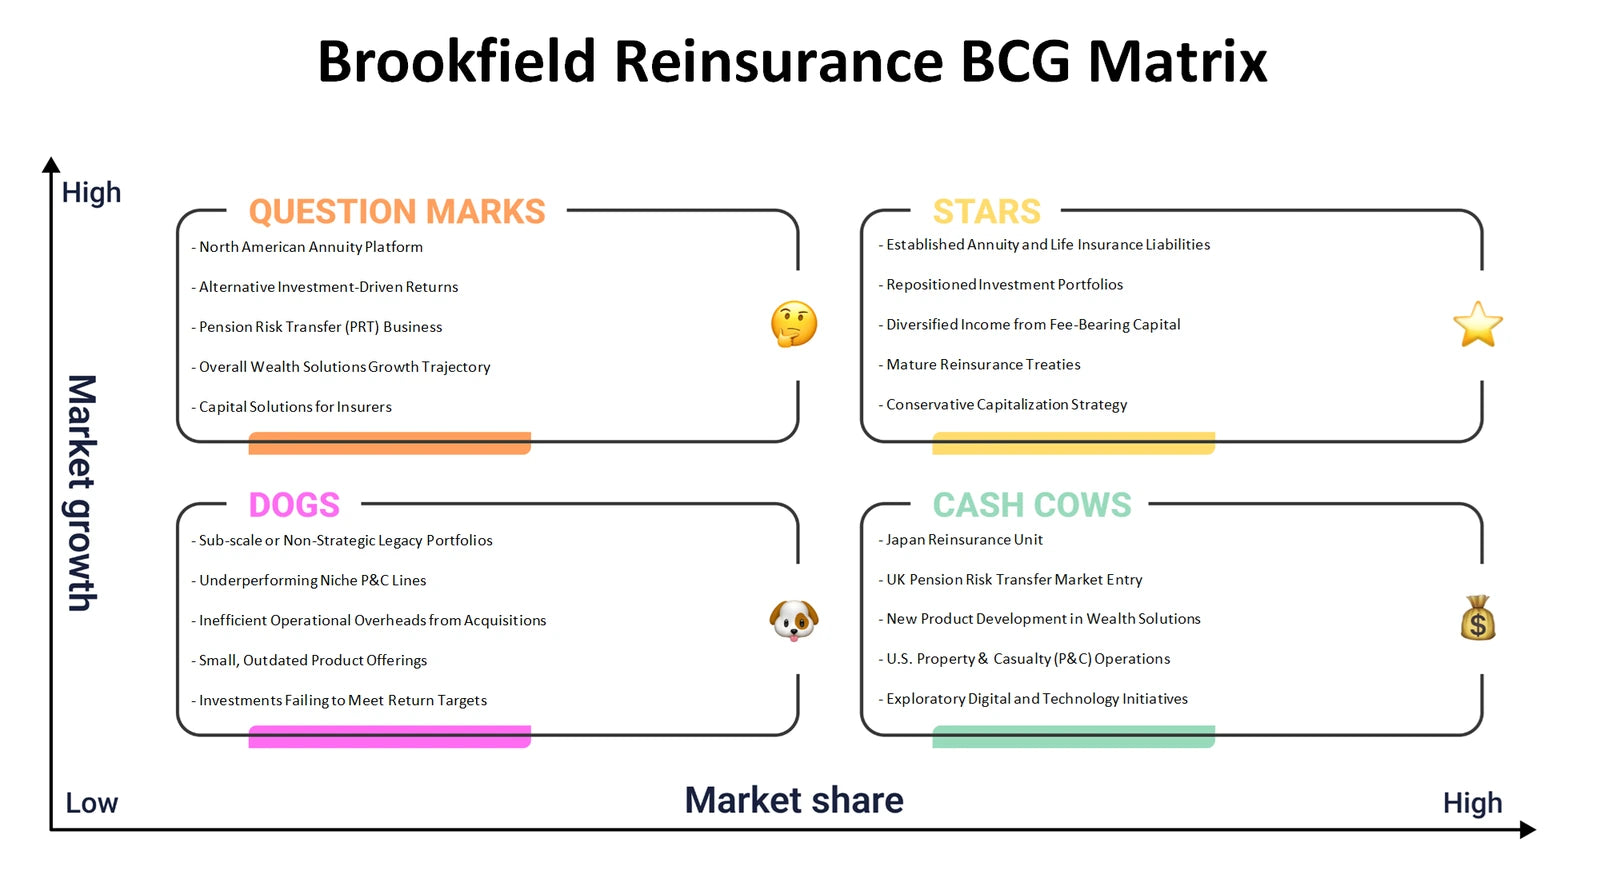
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do ceding insurers, risk-transfer expertise and alternative-asset access connect to a coherent and economically durable business model?
The Brookfield Reinsurance Business Model Canvas examines the logic joining customer segments, value propositions, channels and customer relationships with revenue streams, key resources, key activities, key partnerships and cost structure. Ceding insurers are an especially relevant customer segment because they may value capital relief, liability transfer, balance-sheet support and a counterparty able to manage long-dated insurance obligations. The Canvas helps distinguish documented relationships from questions that require validation: how customers are reached, what service and governance they expect, how contractual economics are structured, and which capabilities must remain in-house. Its partnership lens is particularly useful for considering the strategic importance of Brookfield Asset Management expertise without assuming that access alone determines performance.
- Customer value. Trace how capital solutions, liability expertise and investment-management capabilities could address insurer needs while preserving trust in a regulated, long-term relationship.
- Economic links. Connect revenue logic and cost structure to the resources, activities and partnerships needed to source, underwrite, administer and invest around reinsurance obligations.
- Model testing. Populate the Excel blocks with evidence and open questions, then use the detailed Word analysis to examine whether the blocks reinforce one another or reveal dependencies.
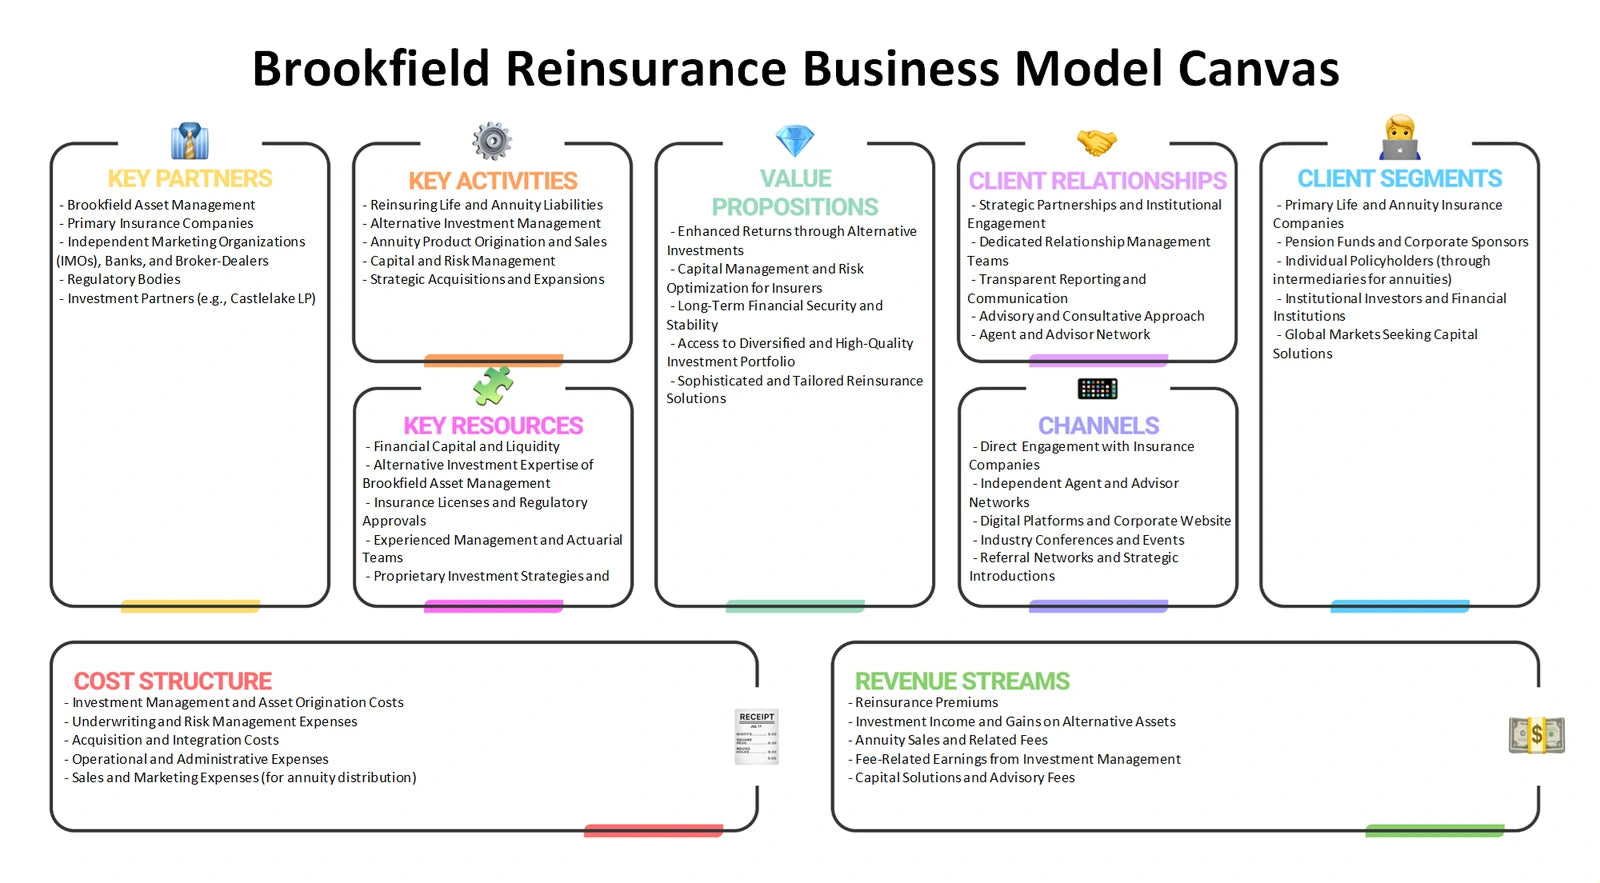
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape a ceding insurer’s choice between Brookfield Reinsurance, another risk-transfer counterparty or a different capital solution?
Brookfield Reinsurance Porter's Five Forces focuses on the competitive environment around insurance risk transfer and liability management. Rivalry can arise where well-capitalized insurers, reinsurers and asset-backed platforms pursue similar long-duration liabilities. Buyer power matters because ceding insurers may compare counterparty quality, pricing, operational capability, capital terms and confidence in asset-liability management before selecting a partner. Supplier power can include the availability and cost of capital, investment talent, data, distribution relationships and suitable assets. The threat of new entrants tests whether specialist expertise and regulatory requirements create meaningful barriers. Substitutes extend beyond direct competitors to retention of risk, alternative capital arrangements or changes to an insurer’s own balance-sheet strategy.
- Choice criteria. Assess the factors that may influence a cedant’s counterparty selection, including financial resilience, tailored structuring, governance and investment capabilities.
- Defensible difference. Explore whether Brookfield-linked alternative-asset expertise can be a differentiated capability while also recognizing the controls and transparency customers may require.
- Pressure map. Use the Excel framework to compare each force and use the Word analysis to document how individual pressures could affect negotiating leverage and strategic responses.
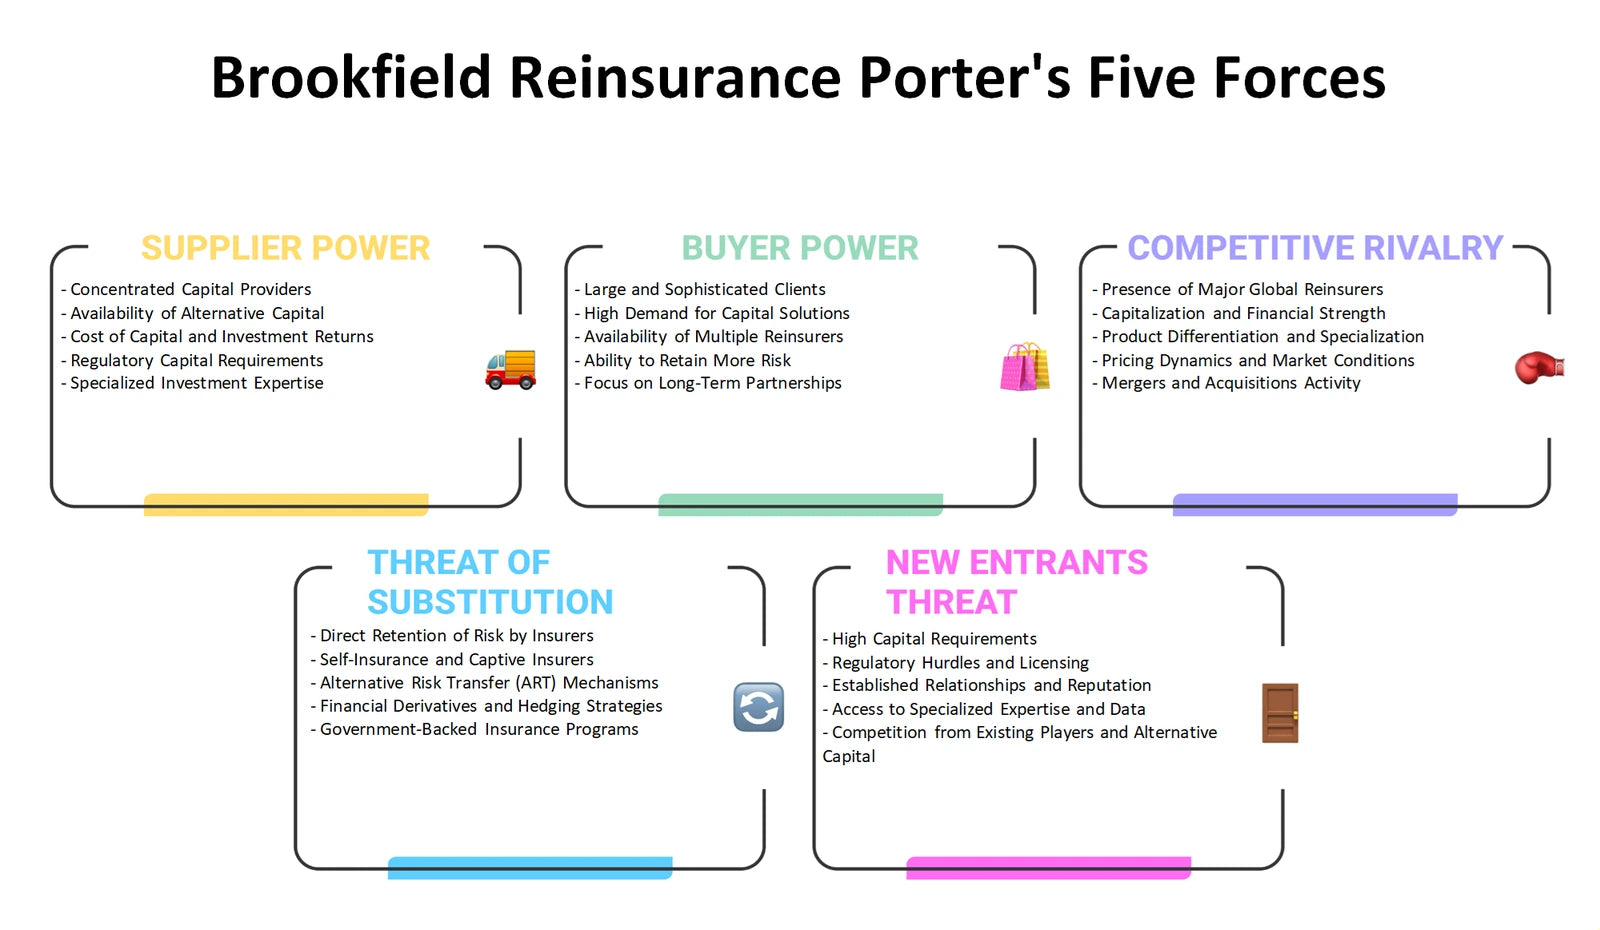
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should a specialist B2B reinsurance proposition be framed so that ceding insurers understand both its economic value and its risk discipline?
A Brookfield Reinsurance Marketing Mix considers Product, Price, Place and Promotion in a relationship-led, regulated B2B setting. Product can encompass reinsurance capacity, capital solutions and the associated ability to manage life and annuity obligations; it is not a consumer policy sold through mass retail channels. Price is better examined as contractual economics, expected risk, capital usage, service scope and investment assumptions than as a public list price. Place concerns the routes through which institutional insurance clients are engaged, including direct senior relationships, advisers and transaction processes where relevant. Promotion is principally evidence-based communication: explaining expertise, governance, balance-sheet capacity and the role of investment capabilities without overstating outcomes.
- Offer architecture. Clarify which components of a proposed solution address a cedant’s capital, liability-management or operating needs and which require tailored structuring.
- Trust signals. Compare the messages likely to matter in institutional selection, such as risk oversight, long-term alignment, transaction experience and transparent decision processes.
- Go-to-market use. Organize 4P observations in Excel and use the Word analysis to turn them into a customer-facing positioning review rather than an unsupported campaign plan.
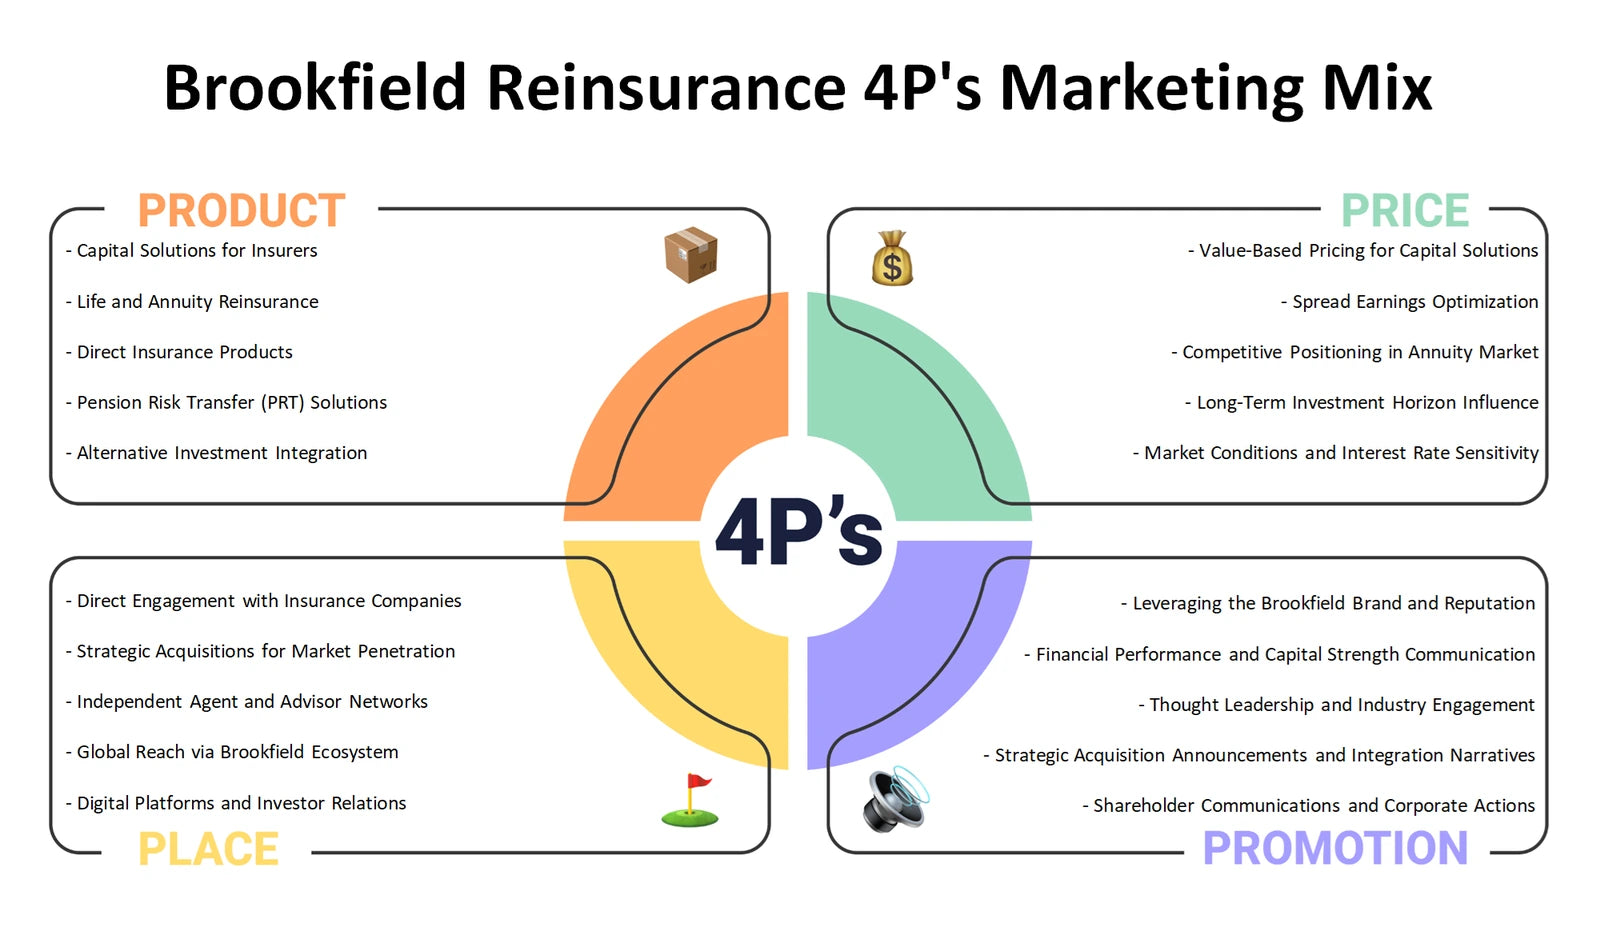
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter demand for reinsurance solutions, the economics of long-dated liabilities or the attractiveness of alternative assets?
The Brookfield Reinsurance PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences from internal capabilities. Political and legal questions include supervisory expectations, insurance regulation, cross-border reinsurance rules and capital requirements relevant to a Bermuda-based insurer. Economic analysis can test interest-rate conditions, credit markets, inflation and the availability of investable assets against long-duration liability obligations. Social trends may affect retirement-security needs and demand for annuity-related products. Technology raises questions about data quality, actuarial models, cyber resilience and operating efficiency. Environmental considerations can affect invested assets, catastrophe-related assumptions and stakeholder scrutiny, even where the principal liabilities are life and annuity focused.
- External watchlist. Separate documented market conditions from issues to monitor, so potential policy, capital-market and regulatory developments are not presented as settled facts.
- Transmission paths. Link each outside factor to a plausible effect on cedant demand, investment returns, operational controls or capital planning.
- Scenario discipline. Use the Excel categories to rank and compare external drivers, then use the Word analysis to explain why selected scenarios matter to Brookfield Reinsurance.
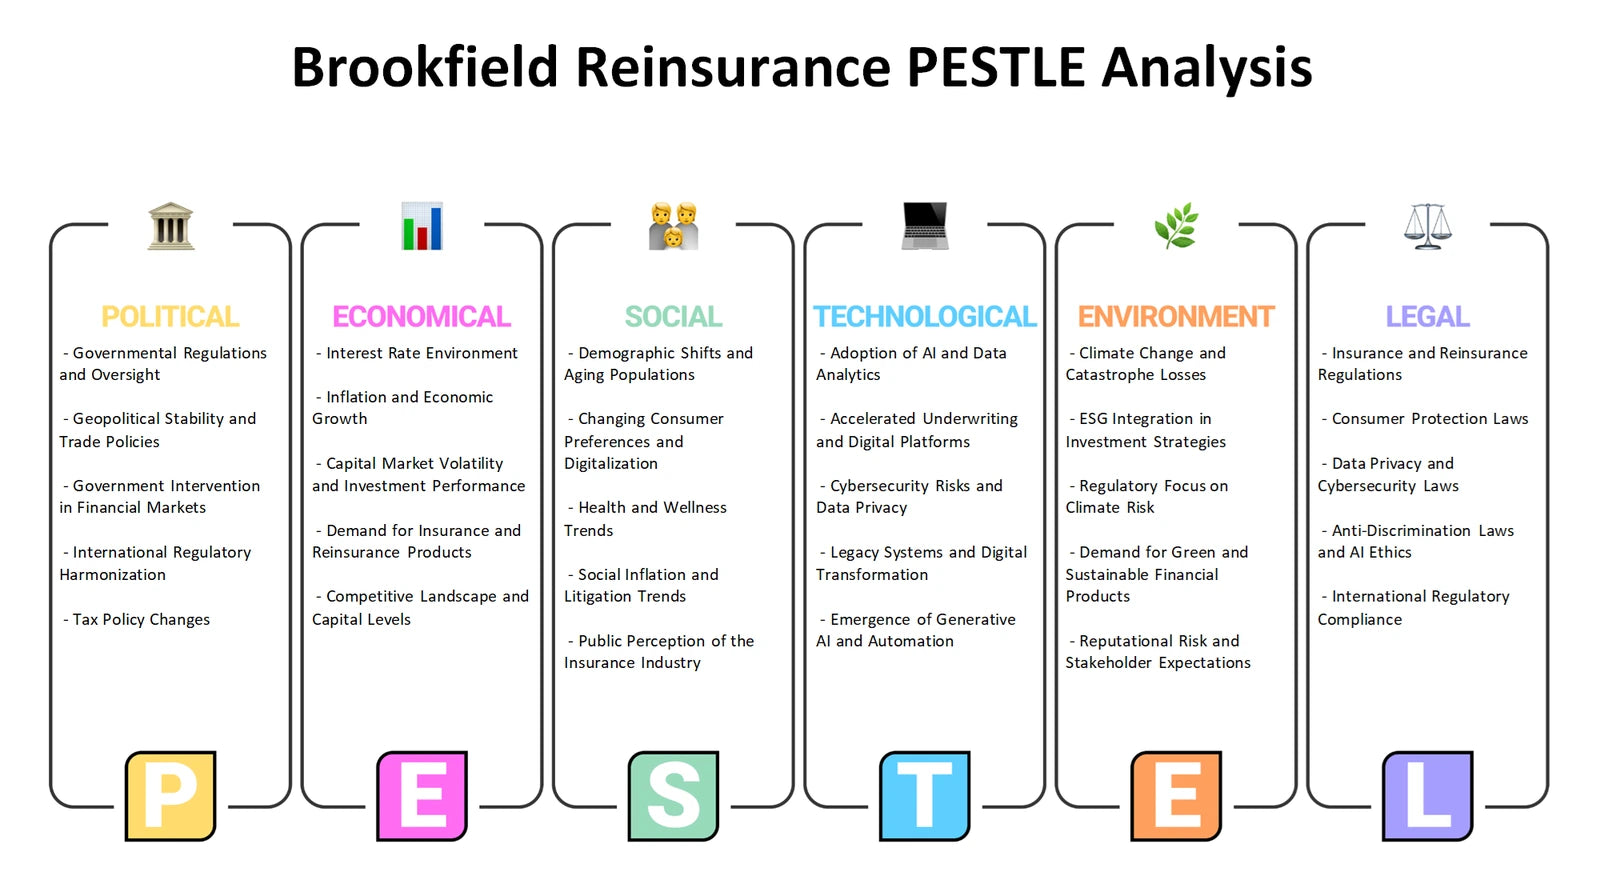
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities may strengthen Brookfield Reinsurance’s customer proposition, and which outside conditions could challenge it?
A Brookfield Reinsurance SWOT analysis keeps internal Strengths and Weaknesses distinct from external Opportunities and Threats. A potential strength to examine is the relationship with Brookfield Asset Management and its alternative-asset expertise, alongside specialist knowledge of insurance liabilities and capital solutions. These are not automatic proof of a competitive advantage; the analysis should test whether they translate into customer-relevant execution, governance and sustainable economics. Potential weaknesses may include concentration, complexity, reliance on specialist talent or the operational demands of managing long-duration obligations. Opportunities can arise from insurers seeking capital or risk-transfer partners, while threats may include intensified competition, changing regulations, investment volatility, adverse credit conditions and shifts in customer risk appetite.
- Internal reality check. Distinguish resources and capabilities under the company’s influence from external market conditions that may shape their value.
- Strategic fit. Test whether identified opportunities match the business’s underwriting, capital-management and investment capabilities rather than treating every market opening as attractive.
- Decision record. Use the Excel SWOT grid to capture evidence and priorities, then use the Word analysis to develop a balanced narrative around trade-offs, dependencies and unanswered questions.
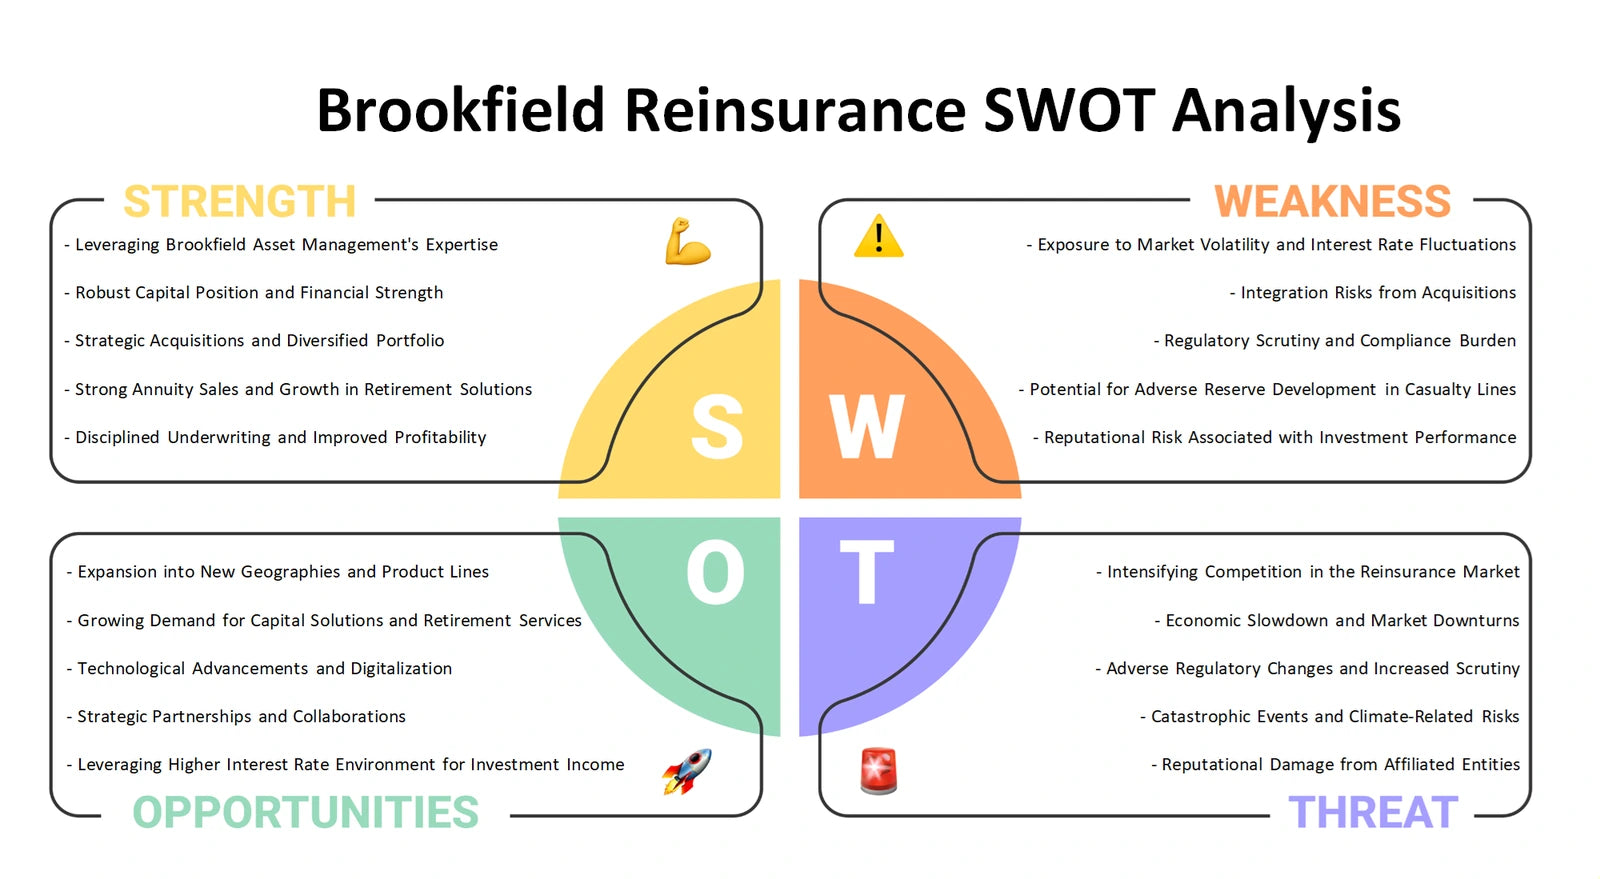
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect customer choice, capital allocation and external pressure
Taken together, the six perspectives move from portfolio priorities and value creation to competitive selection criteria, institutional marketing choices, external conditions and strategic fit. The Excel frameworks provide a structured place to compare assumptions, while the detailed Word files help develop the company-specific reasoning behind them. For Brookfield Reinsurance, that creates a more useful starting point for evaluating how risk transfer, liability management and alternative-asset capabilities may interact.
Company background: Brookfield Reinsurance Ltd. — company website.