

BFF Bank: Banking Business – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
BFF Bank Strategy Analysis Bundle
This bundle focuses on BFF Bank's receivables-financing business, as described in the matching product context, rather than a same-name business in another sector. The model centres on providing liquidity against receivables, assessing the party expected to pay them and managing collection. That combination makes credit discipline, operational processing and funding capacity material to how value is delivered.
The supplied context also describes partnerships with specialised financial entities as relevant to credit exposure, funding diversification and market reach. The analysis therefore asks how activities should be prioritised, how the operating model connects client liquidity with risk control, and how external conditions could alter the trade-offs. These are decision lenses, not claims that a framework has already determined BFF Bank's strategy.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which receivables-finance activities deserve greater funding, operating attention or cautious review?
A BFF Bank BCG Matrix uses market growth and relative market share, rather than absolute scale alone, to compare candidate activity groups. It can distinguish activities serving different client needs, receivable types or routes to market where evidence supports that comparison. Stars, Cash Cows, Question Marks and Dogs are analytical categories for considering resource priorities; the framework does not assume that BFF Bank has been assigned to any quadrant. For a lender whose liquidity offer depends on credit appraisal, collection and funding, growth must be considered alongside risk-adjusted capacity and operational demands.
- Portfolio logic. Compare growth potential with relative competitive position before treating every receivables opportunity as equally attractive.
- Capacity trade-off. Examine whether promising activity could require more underwriting, collections expertise or funding resilience than mature activity.
- Working view. Use the Excel matrix to organise possible activities, then use the Word analysis to record assumptions and the evidence needed before making a priority decision.
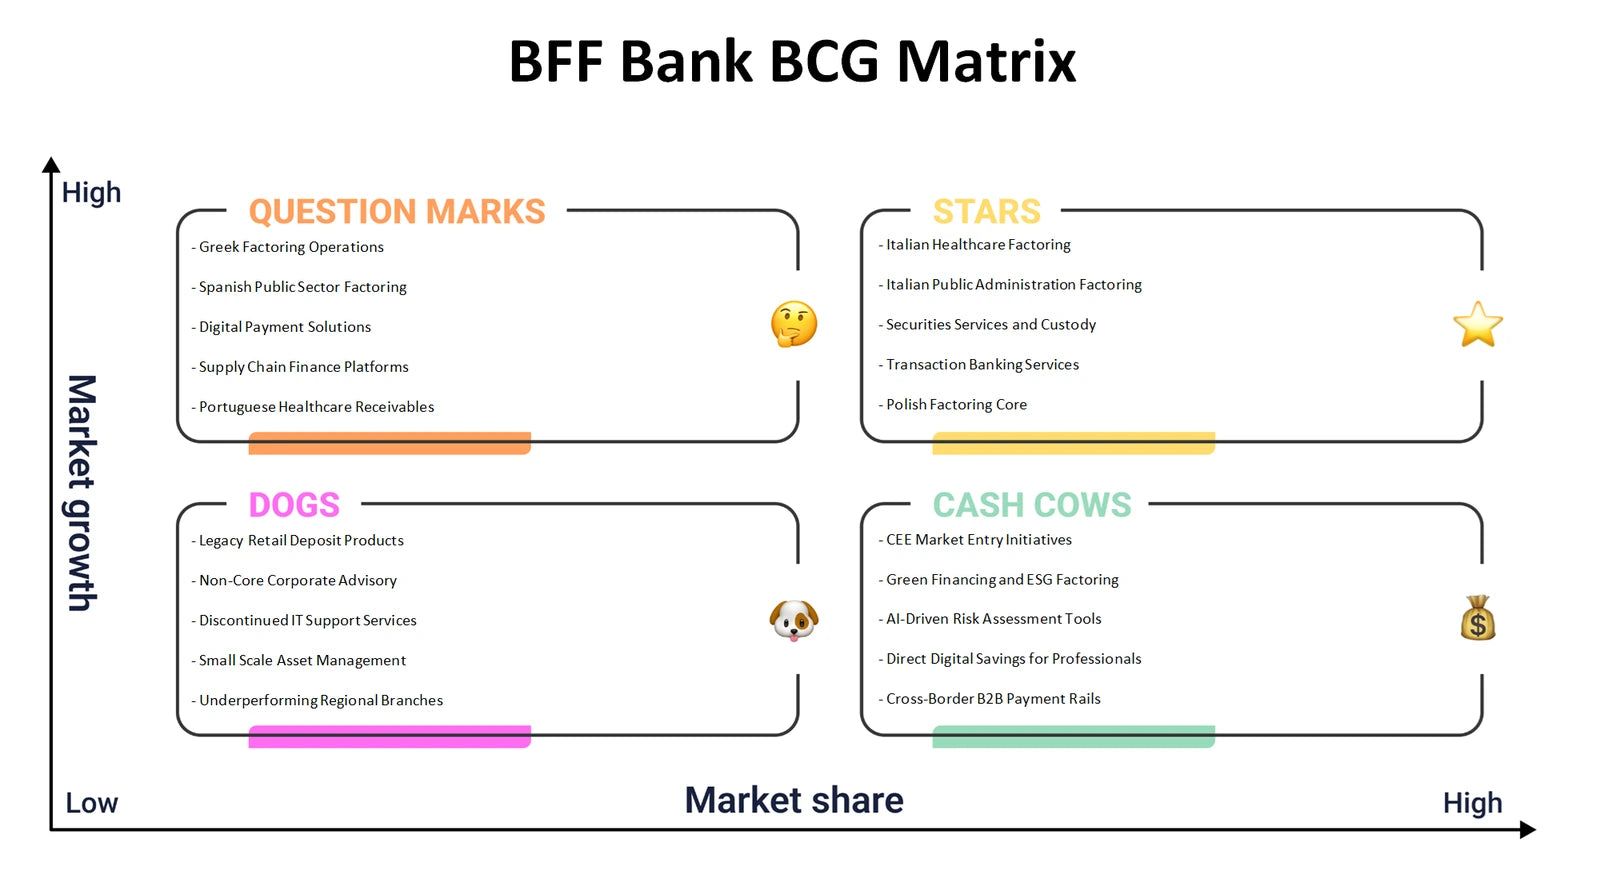
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do client liquidity, credit control, collections and funding fit together in one value-creation model?
The BFF Bank Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It helps connect the liquidity offered to clients with the assessment of parties responsible for repayment and the collection processes that support repayment. It also creates room to examine how specialist-financial-entity alliances may affect access to funding, risk sharing or reach. The useful question is not simply what the bank offers, but what must work together for that offer to remain economically sound.
- Value chain. Trace the connection from client need and receivable evaluation through funding, servicing and collection rather than viewing these as isolated functions.
- Economic links. Test how revenue streams may depend on pricing, credit outcomes, funding arrangements and the costs of processing and control.
- Model mapping. Populate the Excel canvas with validated operating inputs and use the detailed Word analysis to explain dependencies, gaps and questions for management review.
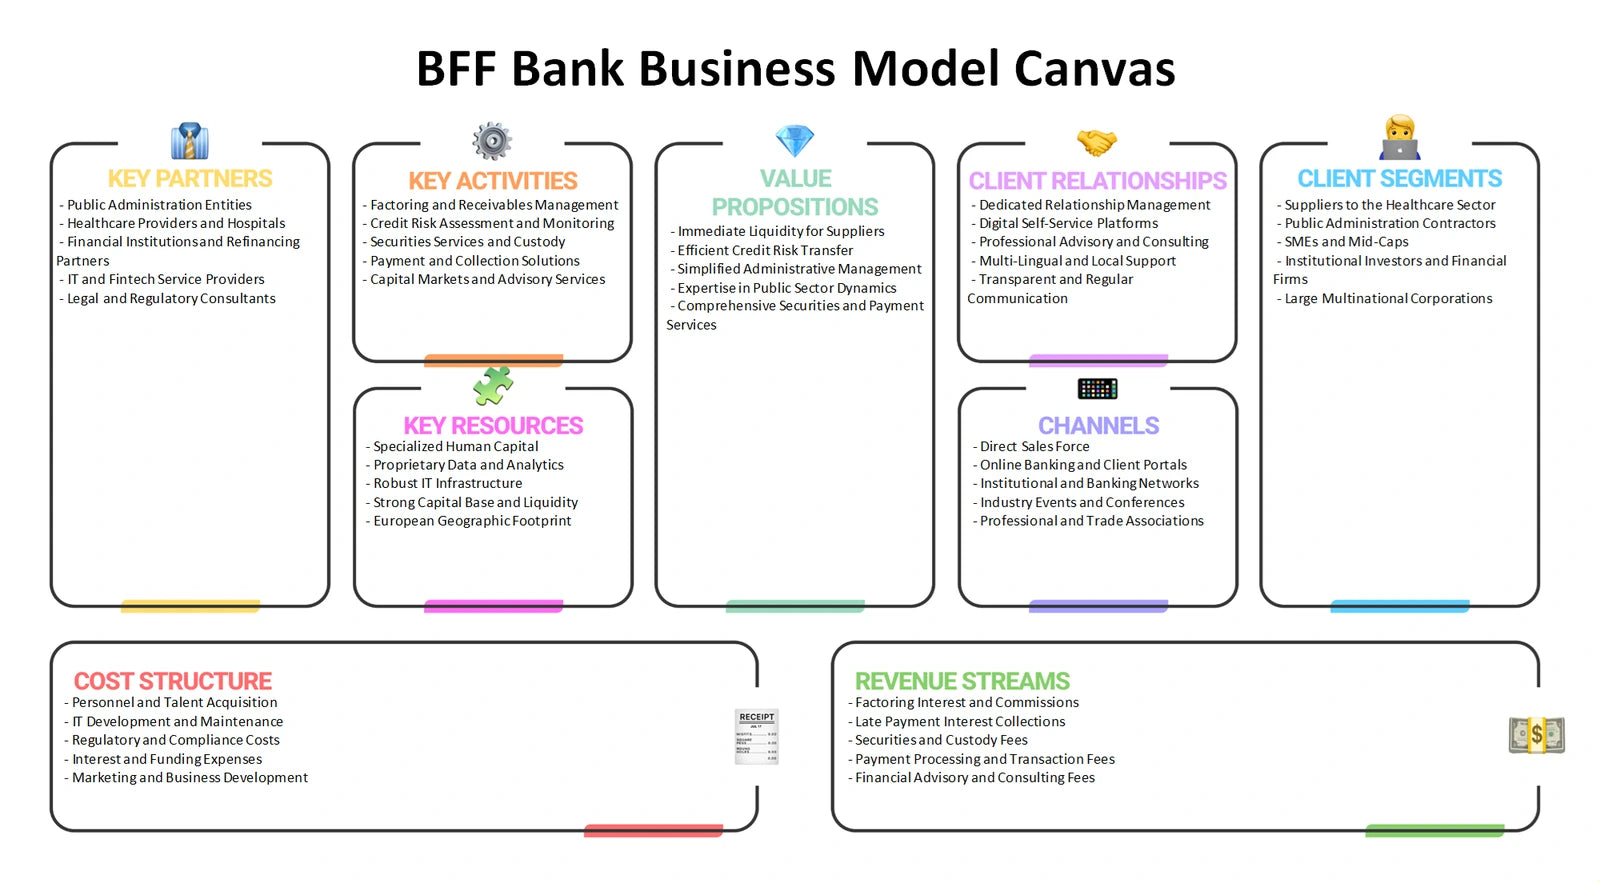
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures shape the attractiveness and bargaining dynamics of receivables financing?
BFF Bank Porter's Five Forces examines rivalry among providers of financing and receivables services, supplier power around funding and specialist inputs, and buyer power among clients seeking liquidity. It also considers the threat of new entrants, including providers able to build credit and servicing capability, and the threat of substitutes. Substitutes are alternative ways to meet a liquidity or working-capital need, such as retaining receivables in-house or using another financing route, not merely another direct lender. This industry lens is particularly useful where credit expertise, collection reliability and access to diverse funding may influence competitive resilience.
- Funding dependence. Assess how the availability and terms of funding relationships could affect margins, capacity and negotiating flexibility.
- Client alternatives. Compare the appeal of receivables financing with other ways a client might manage cash conversion and credit exposure.
- Pressure register. Use the Excel framework to list evidence for each force, while the Word analysis provides space to explain why a pressure matters and where more validation is needed.
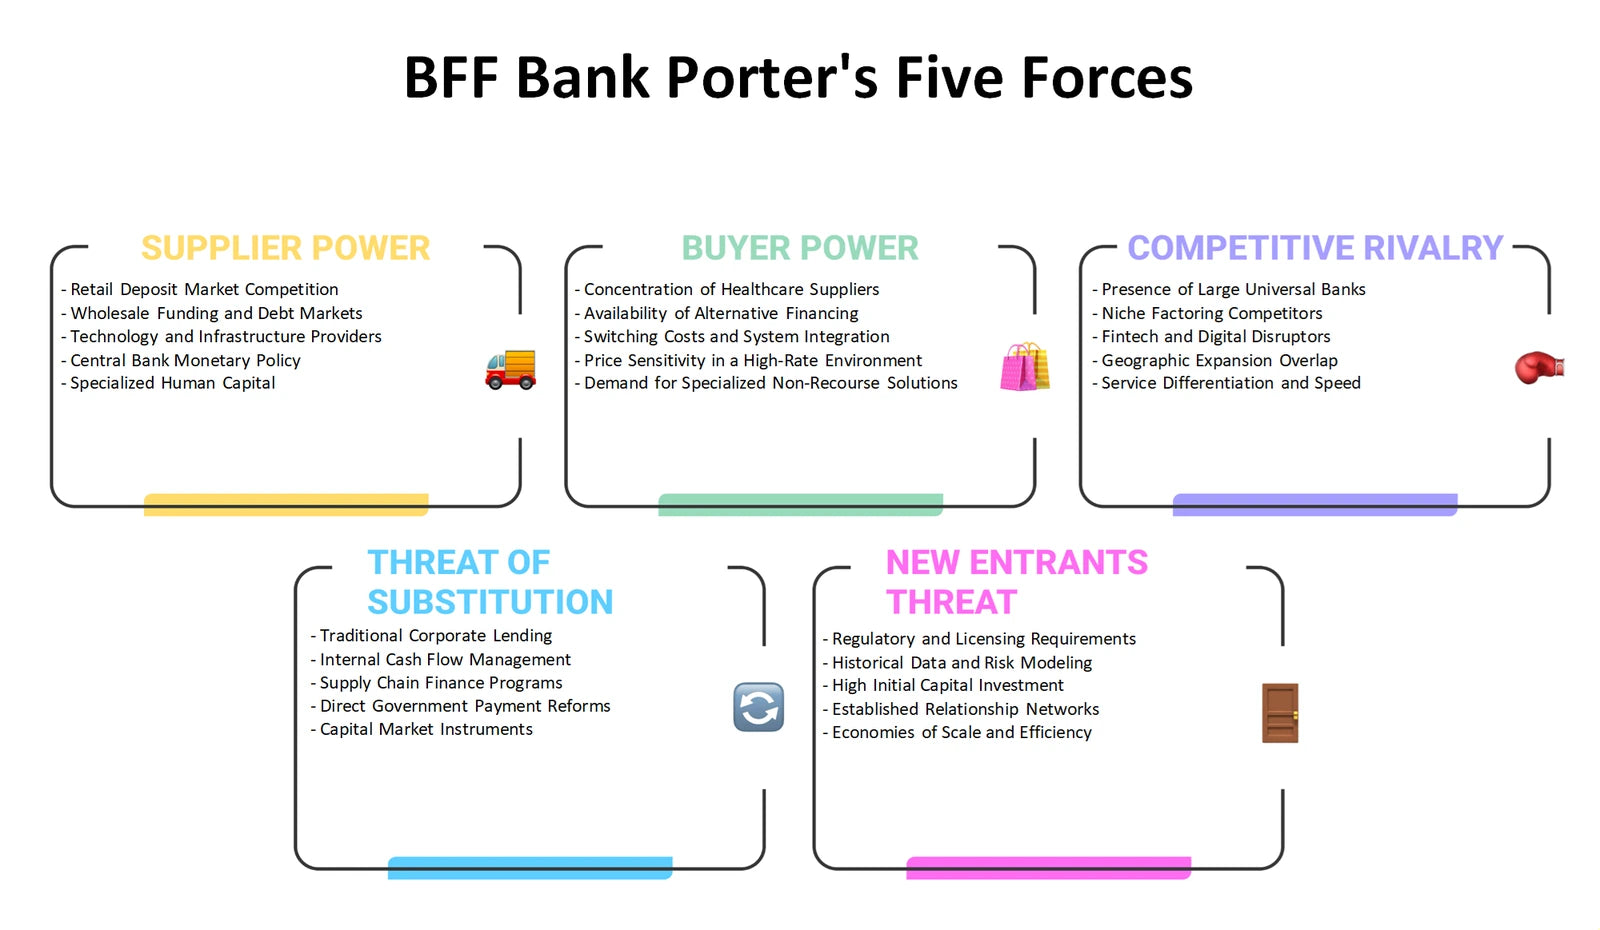
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should a receivables-finance proposition be expressed clearly to clients while reflecting risk and regulation?
A BFF Bank Marketing Mix considers Product, Price, Place and Promotion in a business-to-business financial-service setting. Product analysis can clarify the liquidity, receivables-management and credit-assessment elements that a client experiences. Price should be examined as a commercial and risk-sensitive logic, potentially influenced by receivable quality, servicing requirements and funding conditions, rather than as a simple published rate. Place explores appropriate routes to clients, including relationship-led coverage and relevant partnerships. Promotion focuses on clear communication about service scope, process, documentation and risk discipline, where trust may be as important as visibility.
- Service proposition. Separate the client-facing liquidity benefit from the underlying credit, collection and operational work required to provide it.
- Route to market. Consider how direct relationships and specialised partners could serve different client groups without assuming a particular channel mix.
- Message planning. Use the Excel framework to align the four Ps, then use the Word analysis to develop evidence-based messages and questions for commercial teams.
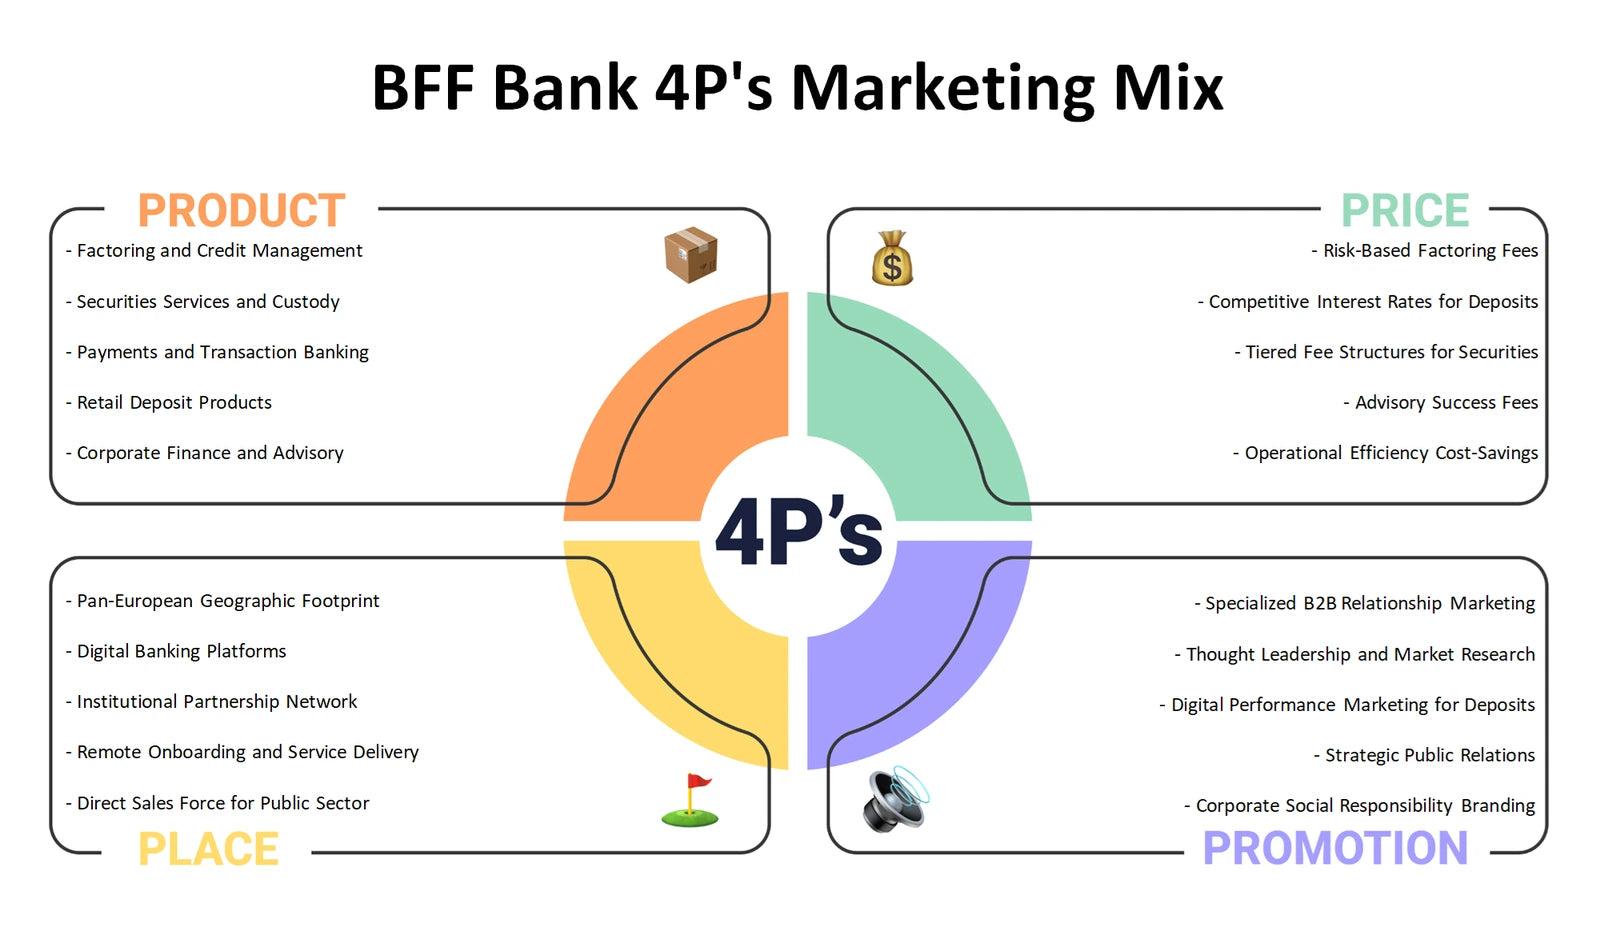
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could change the economics, risk profile or delivery of receivables financing?
A BFF Bank PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal questions can cover public-policy direction, financial regulation, data handling and enforceability relevant to receivables. Economic analysis can test how funding conditions, payment behaviour or client cash pressures might affect demand and risk. Social expectations may concern fairness, transparency and responsible credit practice. Technology raises questions about data quality, workflow automation, fraud prevention and collection efficiency, while environmental factors can influence counterparties, portfolios and stakeholder expectations. These are external variables to monitor, not assertions that a specific change has occurred.
- Condition scanning. Distinguish broad macroeconomic or regulatory questions from company-controlled decisions such as underwriting processes.
- Operational exposure. Link technological and legal developments to the information, controls and collection processes needed to support reliable service.
- Monitoring plan. Organise external signals in the Excel framework and use the Word analysis to document implications, ownership and follow-up questions.
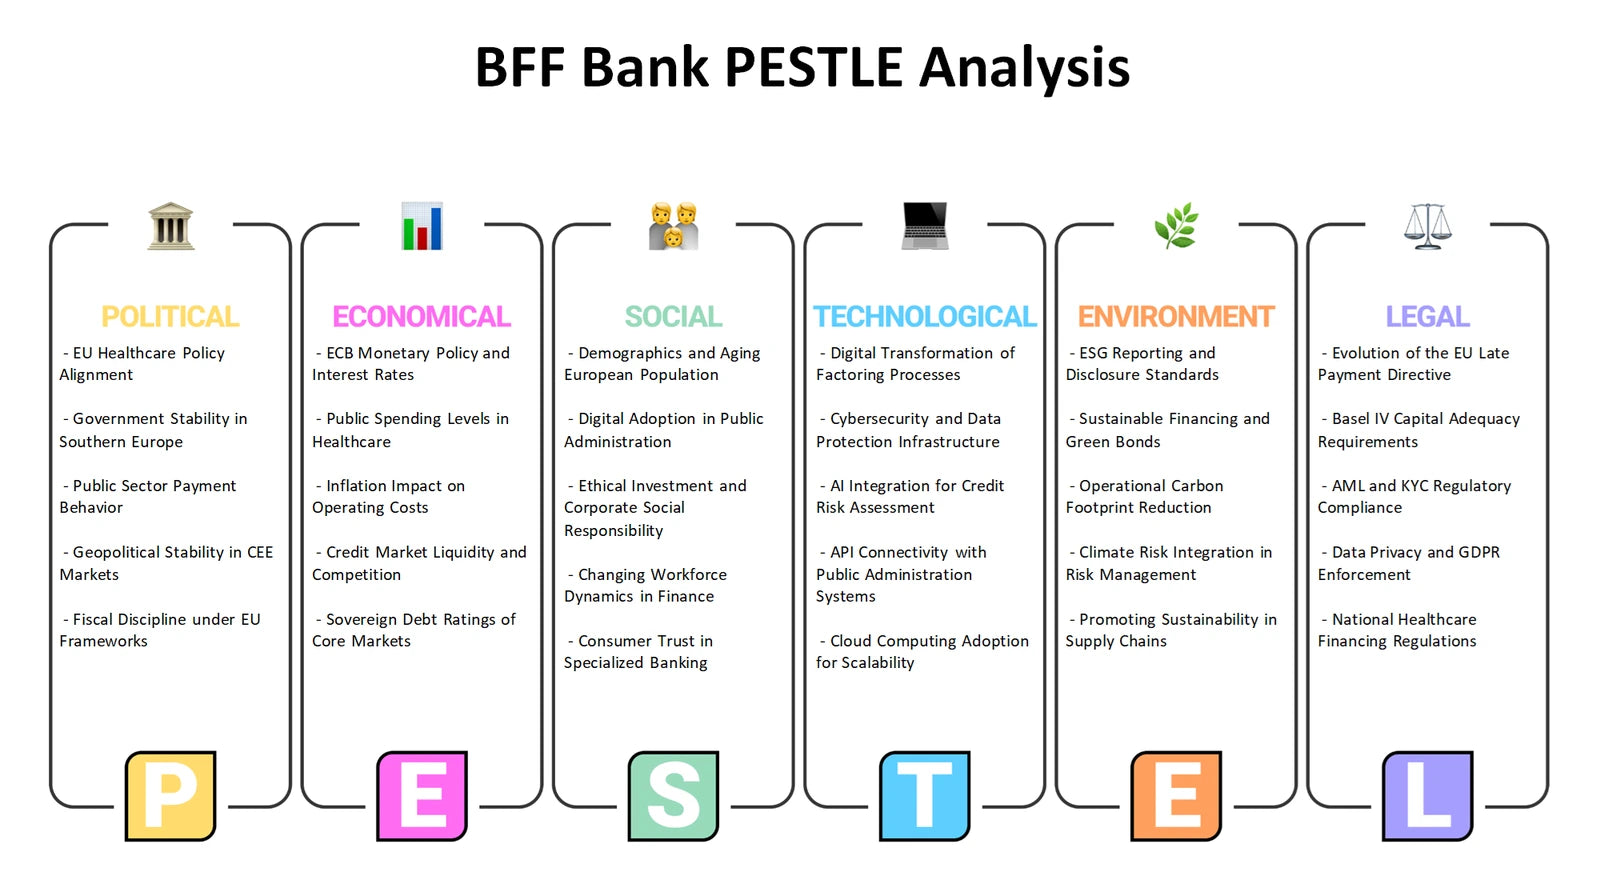
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and limitations should be considered against the opportunities and threats around receivables finance?
A BFF Bank SWOT analysis keeps internal and external issues distinct. Strengths and weaknesses concern capabilities the business can influence, such as credit evaluation discipline, collection processes, funding relationships, specialist knowledge or operating complexity. Opportunities and threats arise outside the company, such as evolving client liquidity needs, financing alternatives, regulation, economic conditions or technological change. The supplied context supports examining buyer credit checks, collection effectiveness and alliances as strategically relevant topics; it does not establish a completed SWOT finding. The framework helps users test whether a capability can support an opportunity, whether a weakness could amplify a threat, and what evidence is needed before drawing a conclusion.
- Internal diagnosis. Evaluate resources, processes and partnership-management capability separately from external market conditions.
- Strategic fit. Explore whether potential opportunities depend on strengths that are sufficiently scalable and whether threats expose controllable gaps.
- Decision record. Use the Excel grid to separate and prioritise themes, then use the Word analysis to add rationale, supporting observations and action questions.
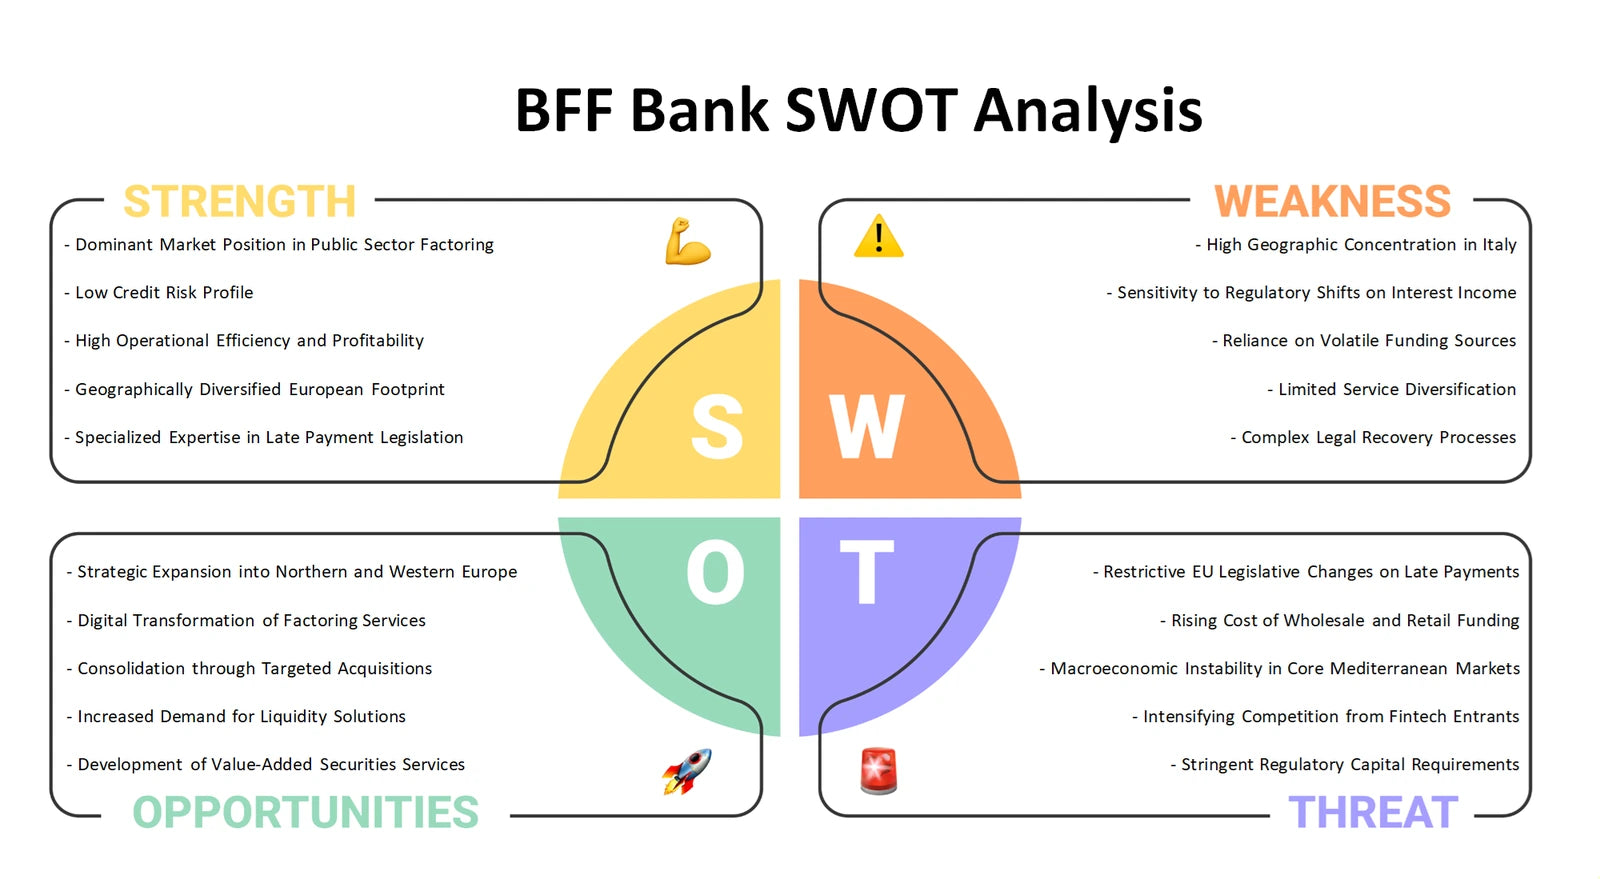
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Turn connected questions into a more coherent strategic view
Together, the six perspectives move from portfolio priorities and business-model connections to industry pressure, market communication, external conditions and strategic fit. The Excel frameworks help organise comparisons and discussion points, while the detailed Word files provide company-focused context for developing a clearer view of BFF Bank's receivables-financing choices, risk considerations and growth questions.
Company background: BFF Bank — matching business-model context page.