

Hope Bancorp: Banking Business – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Hope Bancorp Strategy Analysis Bundle
Hope Bancorp refers here to Hope Bancorp, Inc., the SEC reporting issuer classified under SIC 6021 as a national commercial bank. Available company context describes a banking business with SBA-backed lending for small and medium-sized enterprises, alongside relationships with Korean-American and broader multi-ethnic communities and community-development organisations.
In its filed second-quarter 2026 Form 10-Q, Hope Bancorp, Inc. reported GAAP net income of US$33.031 million for April 1 to June 30, 2026, filed August 6, 2026. That snapshot makes portfolio priorities, customer economics and competitive pressure useful questions for structured analysis.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which customer, lending and banking-service priorities merit resources as their markets and relative positions change?
The Hope Bancorp BCG Matrix provides a disciplined way to compare portfolio areas using market growth and relative market share rather than assuming that every banking activity deserves the same investment. It can help examine where SBA-related lending, relationship-led commercial banking or community-focused service opportunities may fit within Stars, Cash Cows, Question Marks and Dogs after evidence is gathered. For a bank, that distinction matters because capital, risk capacity, relationship-management effort and compliance attention are finite.
- Portfolio comparison. Separate faster-growing opportunity areas from mature activities that may generate steadier earnings or funding relationships.
- Relative position. Test each relevant offering against its actual market position, not just its internal importance or historical familiarity.
- Prioritisation workbook. Use the Excel matrix to organise comparable evidence, then use the Word analysis to interpret trade-offs and questions for management review.
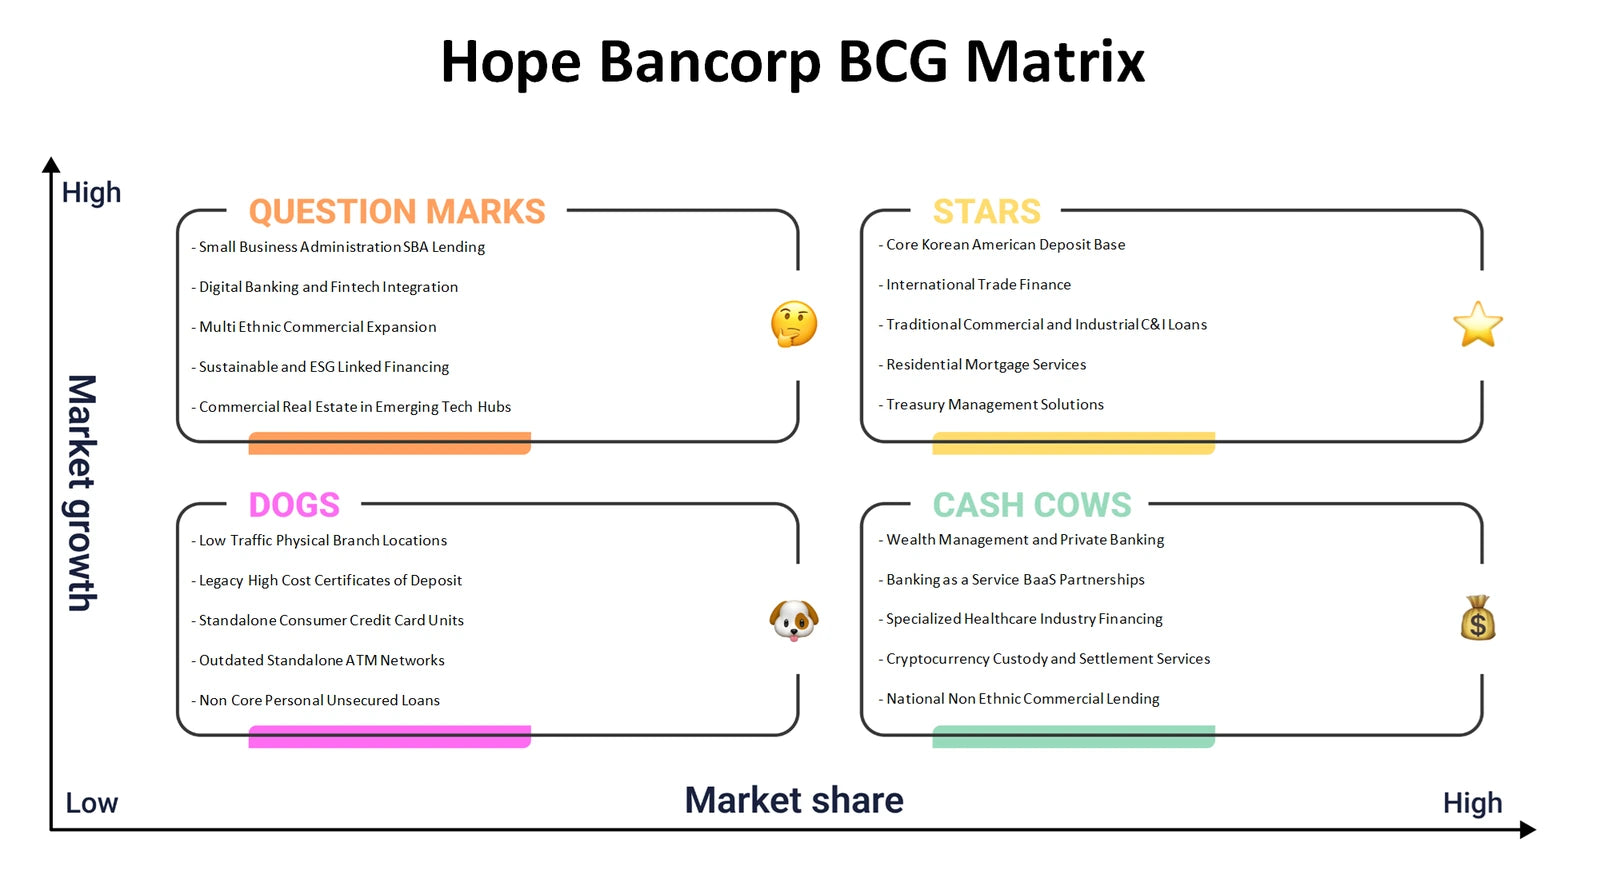
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, SBA-linked lending and operating capabilities connect to sustainable banking economics?
The Hope Bancorp Business Model Canvas maps the full logic of value creation rather than viewing loans or community relationships in isolation. It connects customer segments, value propositions, channels, customer relationships and revenue streams with key resources, key activities, key partnerships and cost structure. In this case, the framework helps examine how small-business needs, government-guaranteed lending pathways and community connections may interact with credit discipline, deposits, service delivery and regulatory operating costs.
- Customer logic. Examine distinct needs across small and medium-sized enterprises, community customers and relationship-based banking audiences.
- Partnership mechanics. Consider how the SBA and community organisations may support customer access while adding process, documentation and relationship-management demands.
- Connected model view. Populate the Excel canvas block by block, then use the Word analysis to trace dependencies between revenue logic, resources, activities and costs.
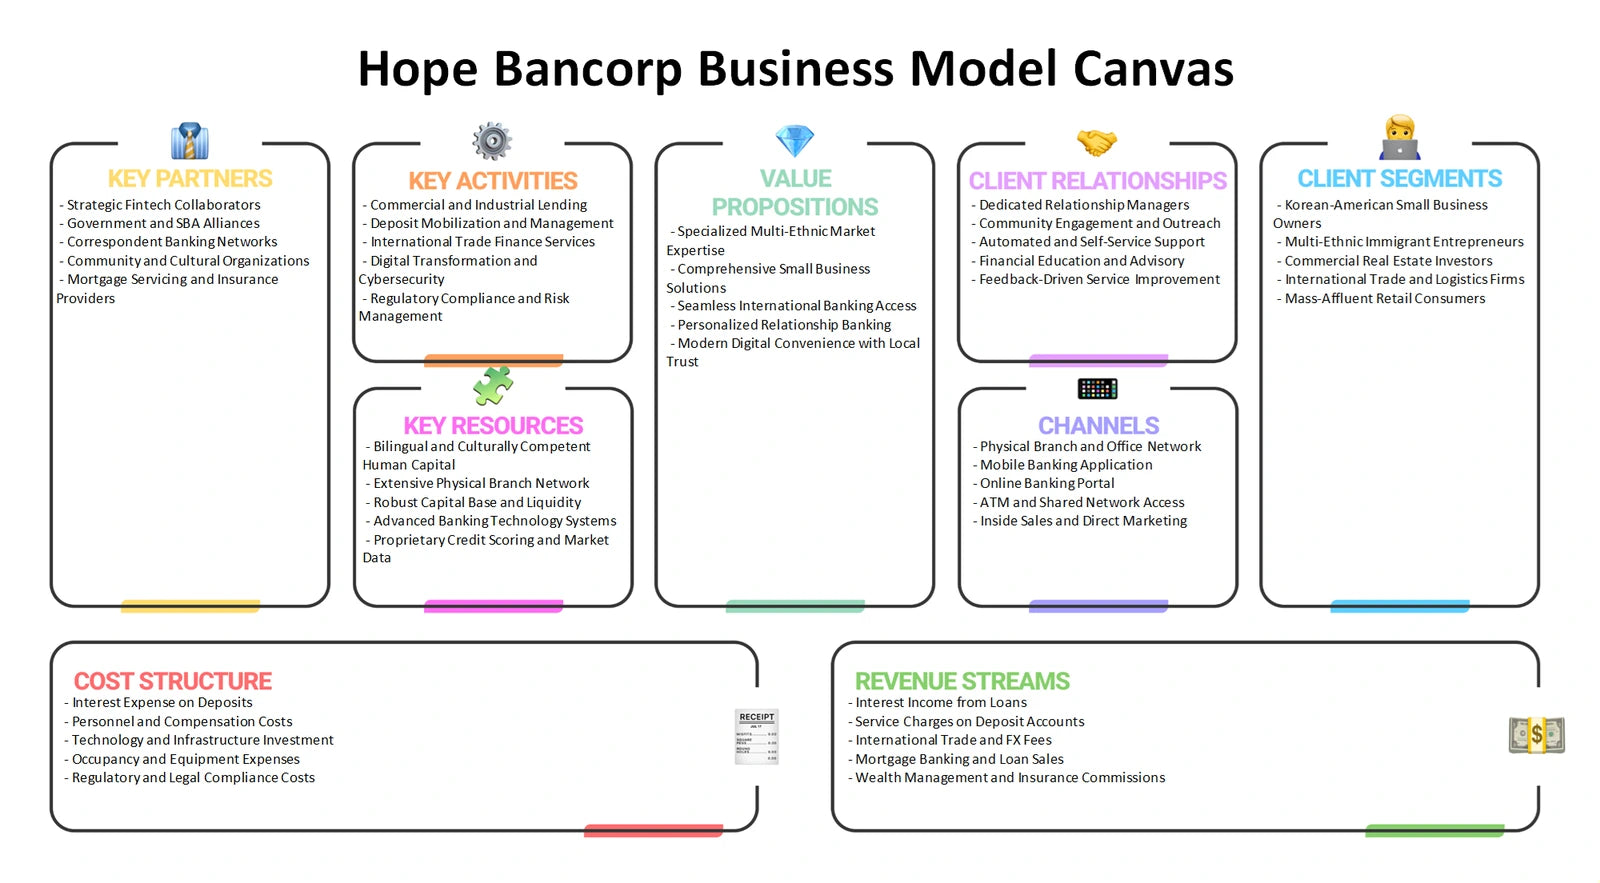
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness of serving business borrowers and community banking customers?
The Hope Bancorp Porter's Five Forces analysis examines the banking environment through rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes. Rivalry can affect the terms available to borrowers and deposit customers, while buyer power may rise when customers can compare bank, non-bank and digital alternatives. Supplier power can include dependence on funding sources, specialised technology and skilled risk talent. Licensing and capital requirements matter to entry barriers, yet fintech-enabled providers and alternative lenders can still alter how customers meet financing or payment needs.
- Competitive tension. Assess where competing institutions may pressure relationship retention, loan terms, deposit pricing or service expectations.
- Alternatives beyond banks. Distinguish direct banking competitors from substitutes such as non-bank credit, digital payments and other financing routes.
- Force-by-force evidence. Use the Excel framework to compare each pressure consistently and the Word analysis to record why a force may matter for specific customer needs.
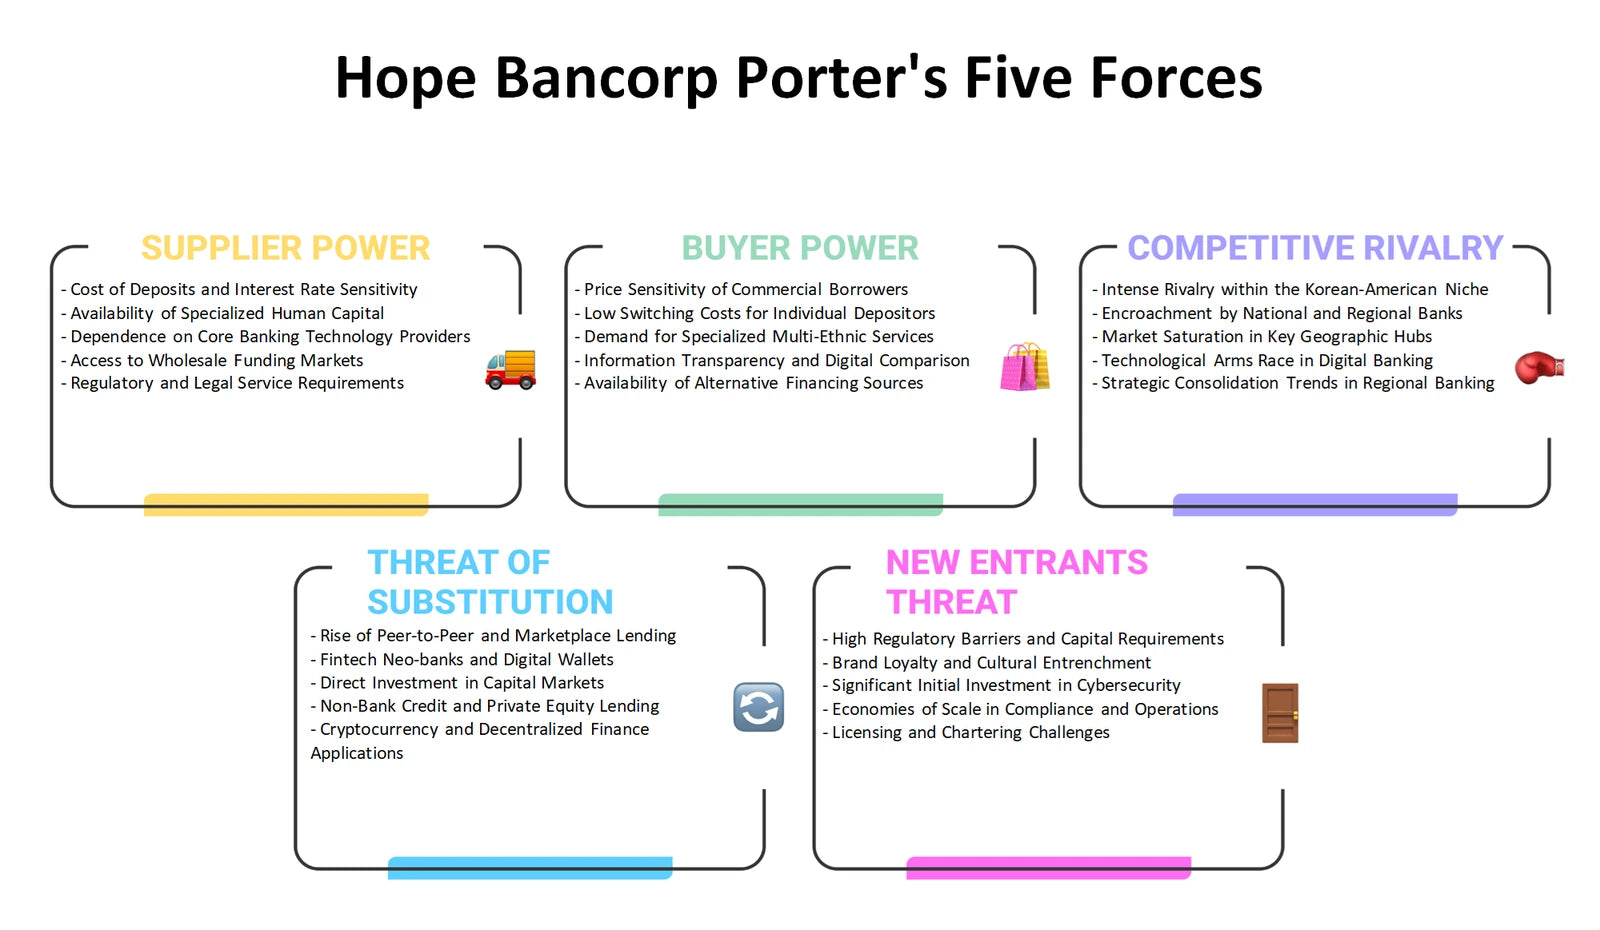
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should banking offers, pricing choices, access routes and communications be assessed for relevant community and business customers?
The Hope Bancorp Marketing Mix applies Product, Price, Place and Promotion to a regulated financial-services setting. Product can cover the fit of SBA-backed finance and other banking services with customer needs. Price means more than a headline rate: it can include credit terms, fees, deposit pricing and the value customers receive from a relationship. Place evaluates suitable physical, relationship-led and digital access routes where relevant, while Promotion considers clear, compliant communication and trusted community engagement rather than unverified campaign claims.
- Offer design. Compare customer needs with the practical features, eligibility requirements and service support attached to banking products.
- Route and message. Assess how community relationships and customer access points may affect awareness, trust and service convenience.
- 4P working plan. Use the Excel structure to align the four decisions, then consult the Word analysis for sector-specific considerations and discussion prompts.
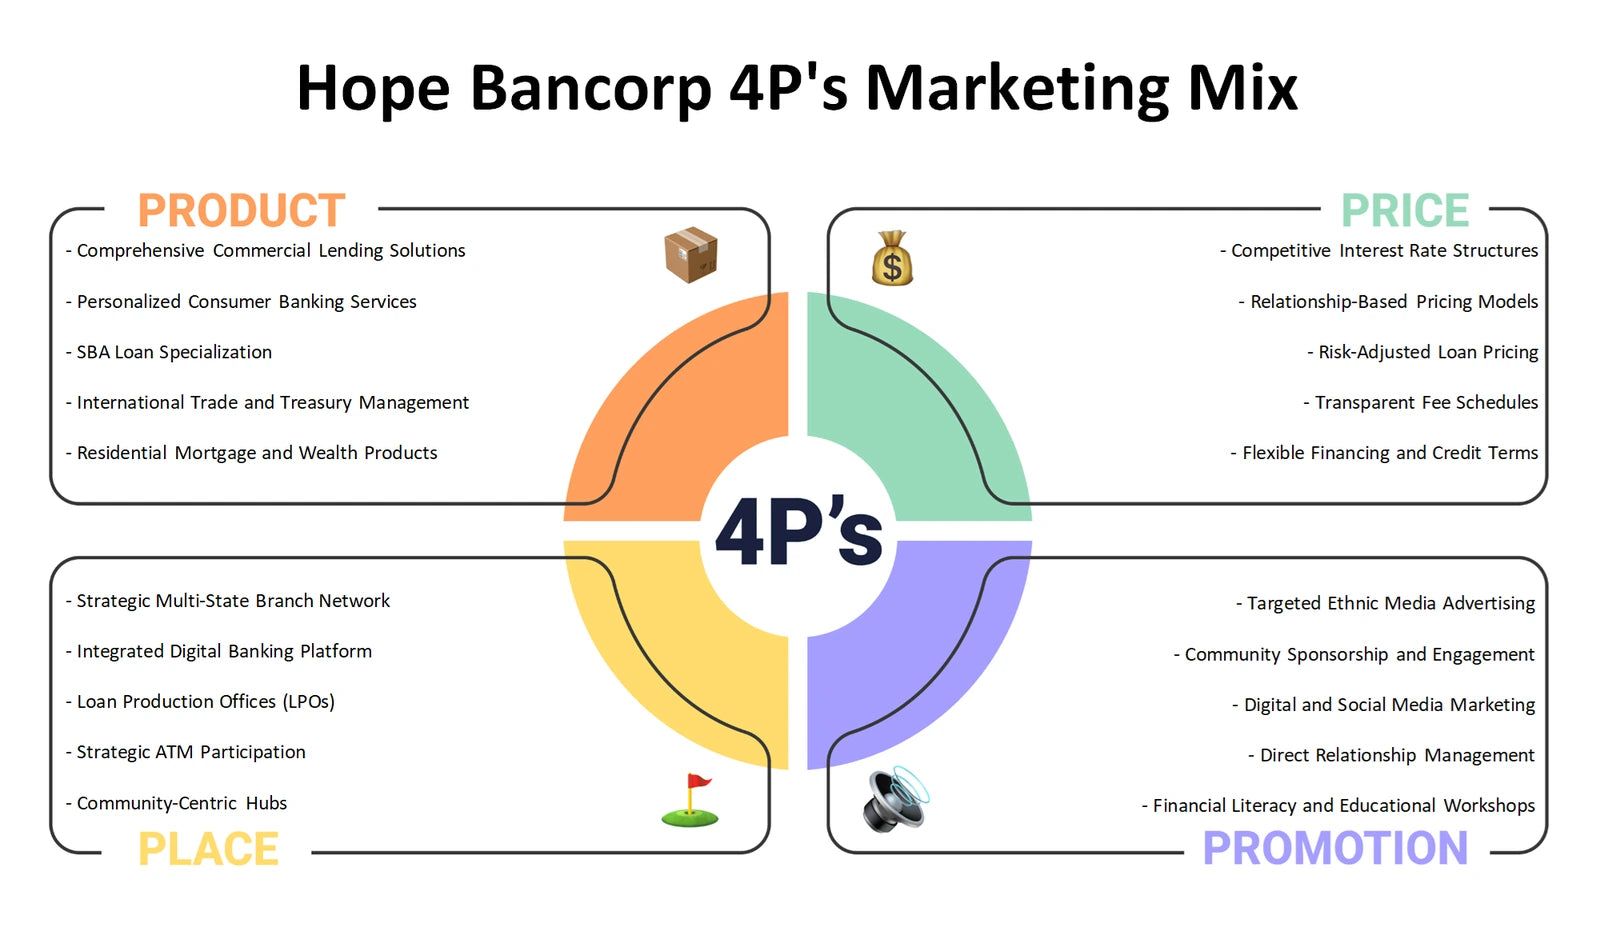
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter demand, risk, regulation and delivery economics for community-oriented banking?
The Hope Bancorp PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political questions include the direction and availability of government-supported small-business lending programmes. Economic conditions can affect borrowers, deposits, credit quality and interest-sensitive earnings. Social considerations include changing needs within the communities served; technology raises digital-service and cybersecurity questions. Legal obligations around banking, consumer protection and fair lending, together with environmental exposure affecting customers or collateral, belong in the external picture rather than being treated as established company outcomes.
- Policy and economy. Track how public-programme priorities and changing business conditions could affect customer demand and loan performance.
- Rules and resilience. Consider compliance, data protection, fraud, cybersecurity and environmental-risk questions that can influence operating requirements.
- External watchlist. Use the Excel categories to log signals and assumptions, while the Word analysis helps explain their possible relevance to banking decisions.
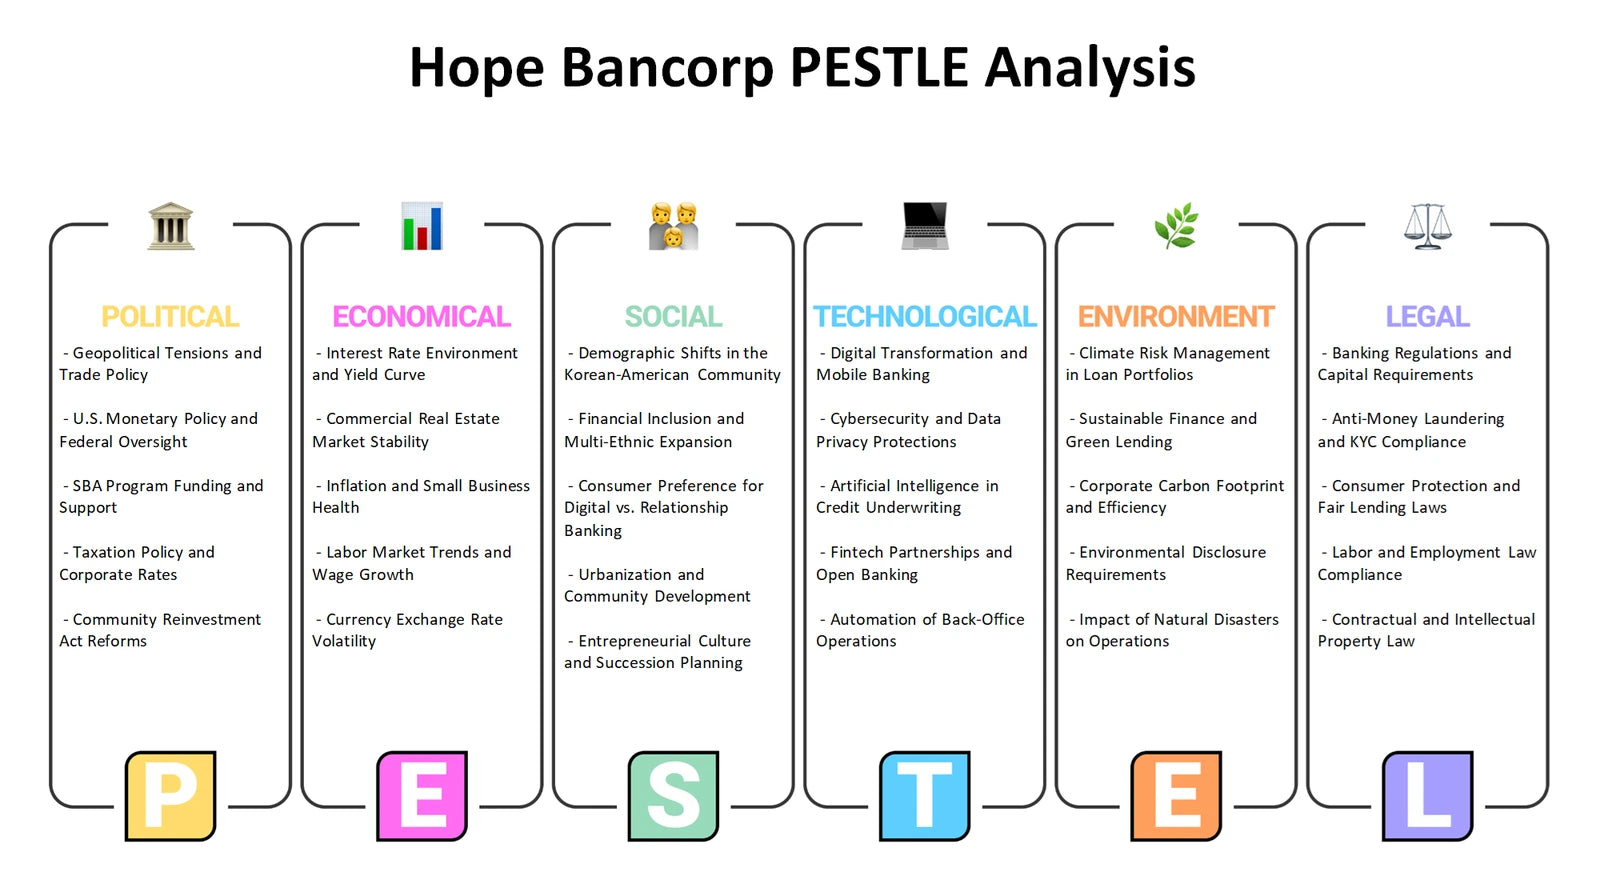
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities be weighed against external openings and risks without confusing evidence with assumptions?
The Hope Bancorp SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. The available context makes SBA lending experience and community-oriented relationships relevant themes to examine as possible capabilities, not pre-scored conclusions. Internal questions can include credit expertise, operating capacity, risk controls and the demands of serving defined customer needs. External opportunities may arise from business-financing demand or community-development needs, while threats can include economic stress, competitive alternatives, regulation and technology-related risk. Keeping those categories separate prevents a market condition from being mistaken for an internal capability.
- Internal evidence. Evaluate resources, processes, relationship depth and constraints that may influence the bank's ability to execute its chosen strategy.
- External conditions. Contrast potential demand openings with competitive, credit, regulatory and digital risks that originate outside the organisation.
- Decision-ready synthesis. Use the Excel grid to classify observations before using the Word analysis to connect them into defensible strategic questions.
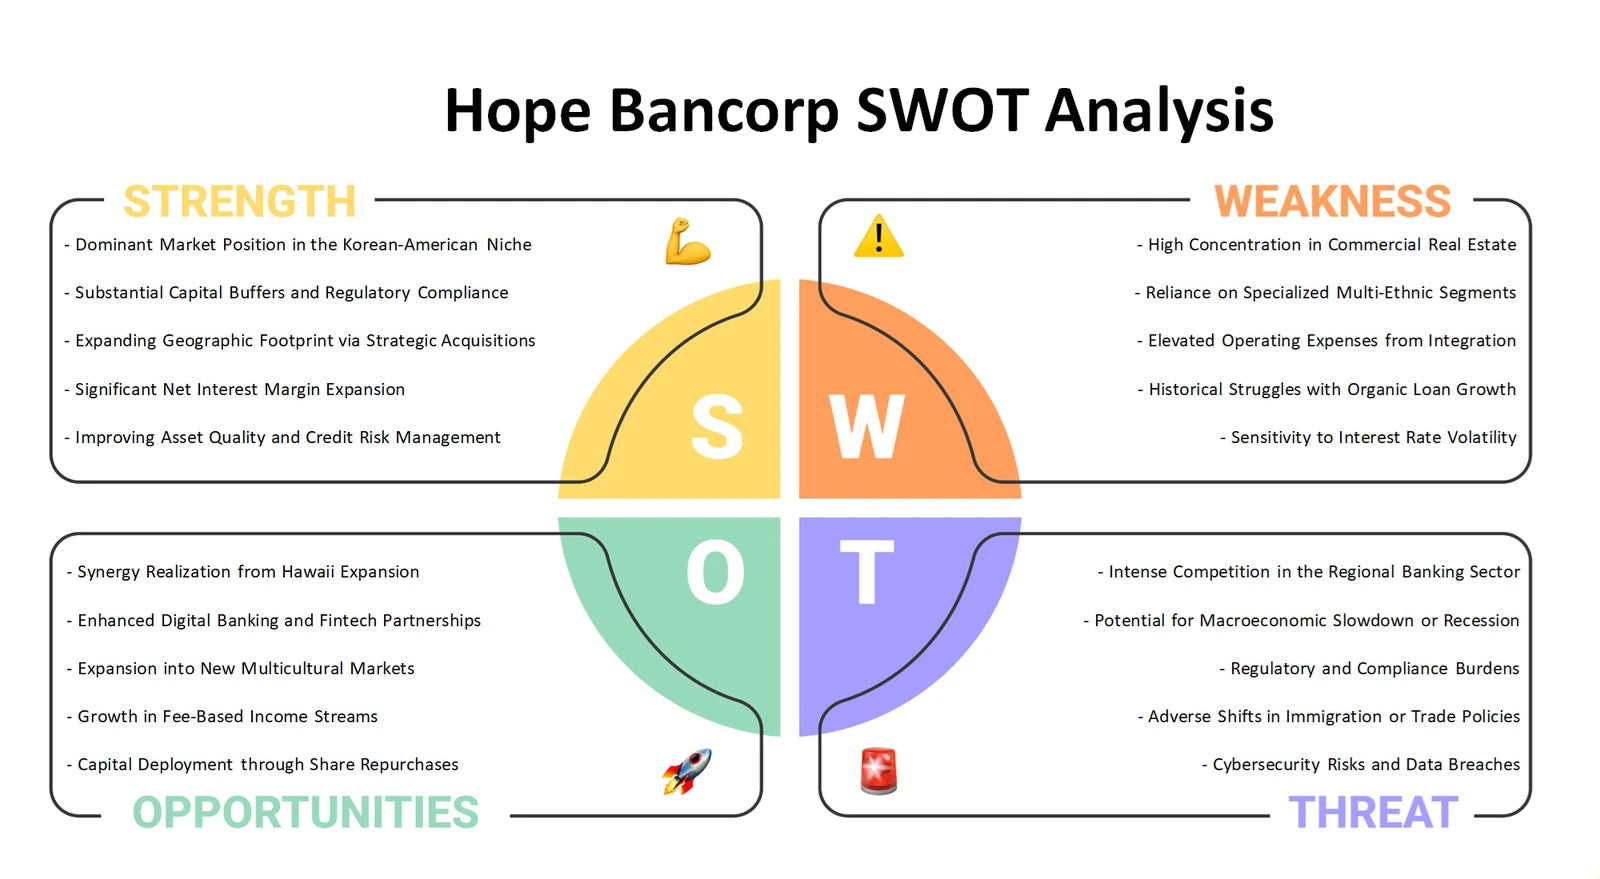
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring the six banking perspectives together
Used together, the six frameworks help connect portfolio choices, business-model economics, industry pressure, customer-market decisions, external change and internal-versus-external priorities. The Excel materials provide structured places to organise comparisons, while the detailed Word analyses help develop a more coherent set of questions for Hope Bancorp's lending, community relationships and operating model.
Company background: Hope Bancorp — SEC issuer submission data.