

Bank of Beijing: Banking Business and Deposit Funding – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Bank of Beijing Strategy Analysis Bundle
Bank of Beijing is a commercial bank based in Beijing, China, serving retail and corporate banking needs through deposit-taking, lending and settlement services. Its operating model also combines branch interactions and self-service banking, including ATM services, with digital customer access. These activities make customer trust, credit allocation, service reach and operational resilience central business questions.
The bundle uses six connected lenses to examine how Bank of Beijing can compare banking activities, map value creation, assess competitive pressure and frame external uncertainty. Rather than asserting unverified conclusions, the materials help users investigate questions such as where resources are tied up, how customer channels support relationships and which outside changes could affect banking economics.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking activities deserve greater management attention when growth potential and relative market share are considered together?
A Bank of Beijing BCG Matrix provides a disciplined way to compare a portfolio of banking activities rather than treating every product line as equally strategic. It applies market growth and relative market share to possible retail, corporate, lending, deposit, payment or service categories. The familiar Stars, Cash Cows, Question Marks and Dogs are analytical categories, not pre-assigned labels for the bank. This distinction matters because a high-growth lending opportunity may require capital and risk capacity, while an established deposit or transaction service may support funding stability and customer retention.
- Portfolio comparison. Examine which activities may combine stronger relative position with attractive market growth, and which require closer evidence before resources are committed.
- Banking trade-offs. Consider how growth ambitions interact with credit quality, funding needs, service costs and the practical limits of management attention.
- Structured prioritisation. Use the Excel framework to organise candidate activities and assumptions, then use the detailed Word analysis to discuss the evidence needed for each portfolio position.
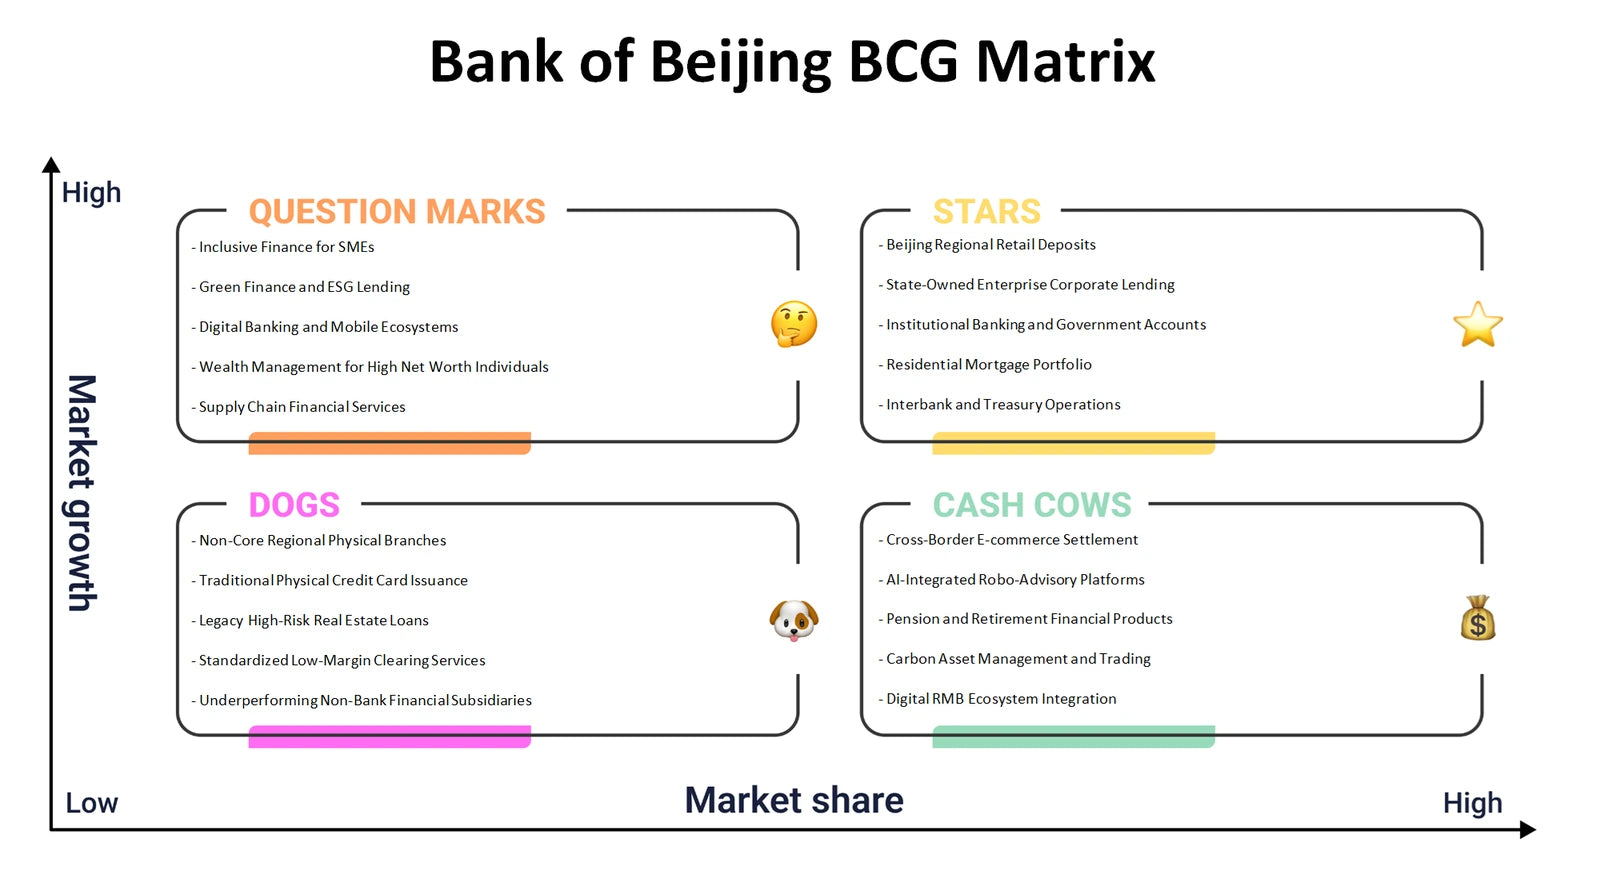
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do Bank of Beijing's customer relationships, service channels and banking licence connect to sustainable revenue and operating costs?
The Bank of Beijing Business Model Canvas maps the logic linking customer segments and value propositions to channels, customer relationships and revenue streams. For a commercial bank, individuals and businesses may seek safe deposits, credit access, payments and settlement support, while branches, ATMs and digital services shape how those needs are served. The canvas also brings together key resources, key activities, key partnerships and cost structure. It therefore helps connect the legal ability to accept deposits and extend loans with the people, technology, risk processes and physical service network needed to deliver those services responsibly.
- Customer-service fit. Explore how retail and corporate needs may differ across credit, deposits, transaction banking and relationship-led support.
- Economic connections. Trace how revenue streams and cost structure depend on funding, lending activity, settlement services, operations and control requirements.
- Workshop map. Complete the Excel canvas block by block, then use the Word analysis to test whether links between value propositions, resources and delivery activities are coherent.
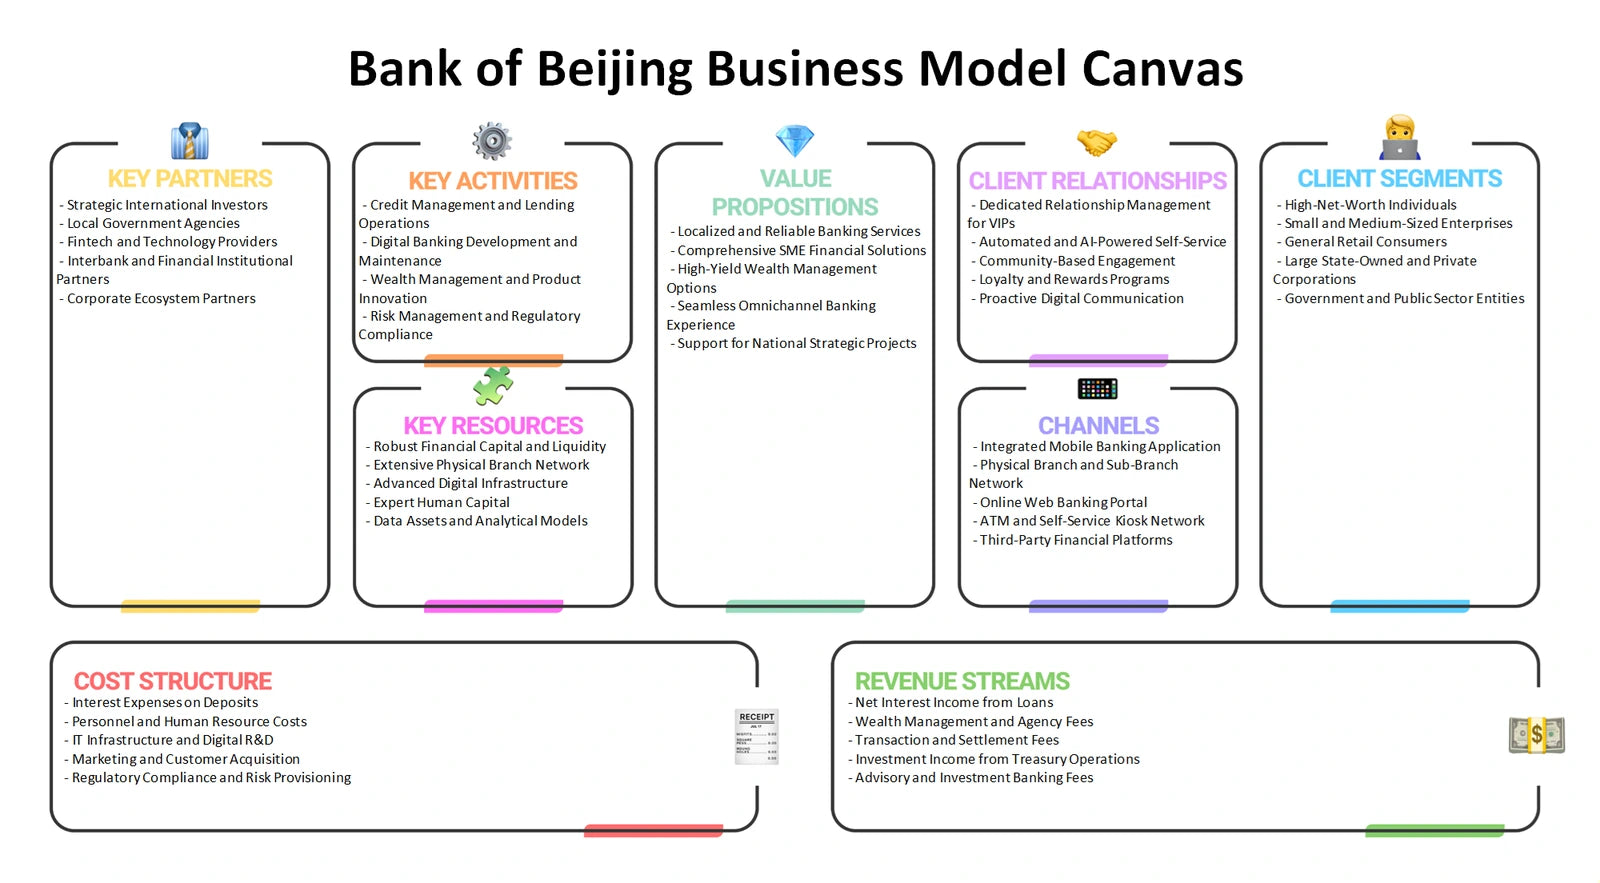
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures can shape the attractiveness of the banking markets in which Bank of Beijing competes for customers, deposits and lending opportunities?
Bank of Beijing Porter's Five Forces frames competition beyond a simple list of rival banks. Rivalry concerns the contest for customers, deposits, lending relationships and service differentiation. Supplier power can include the influence of funding providers, specialised technology providers and talent needed for controlled banking operations. Buyer power examines the ability of retail and corporate customers to compare banking offers or move relationships. The framework also considers barriers facing new entrants and substitutes such as non-bank payment methods, alternative financing arrangements or other ways customers can meet savings and transaction needs.
- Competitive intensity. Assess where banking services may be differentiated by relationship quality, convenience, risk appetite or customer trust rather than price alone.
- Substitution risk. Compare conventional banking needs with alternative payment, financing and savings options without assuming every substitute has equal relevance.
- Evidence-led review. Use the Excel force-by-force structure to record observations and questions, while the Word analysis supports a fuller explanation of the implications for the bank.
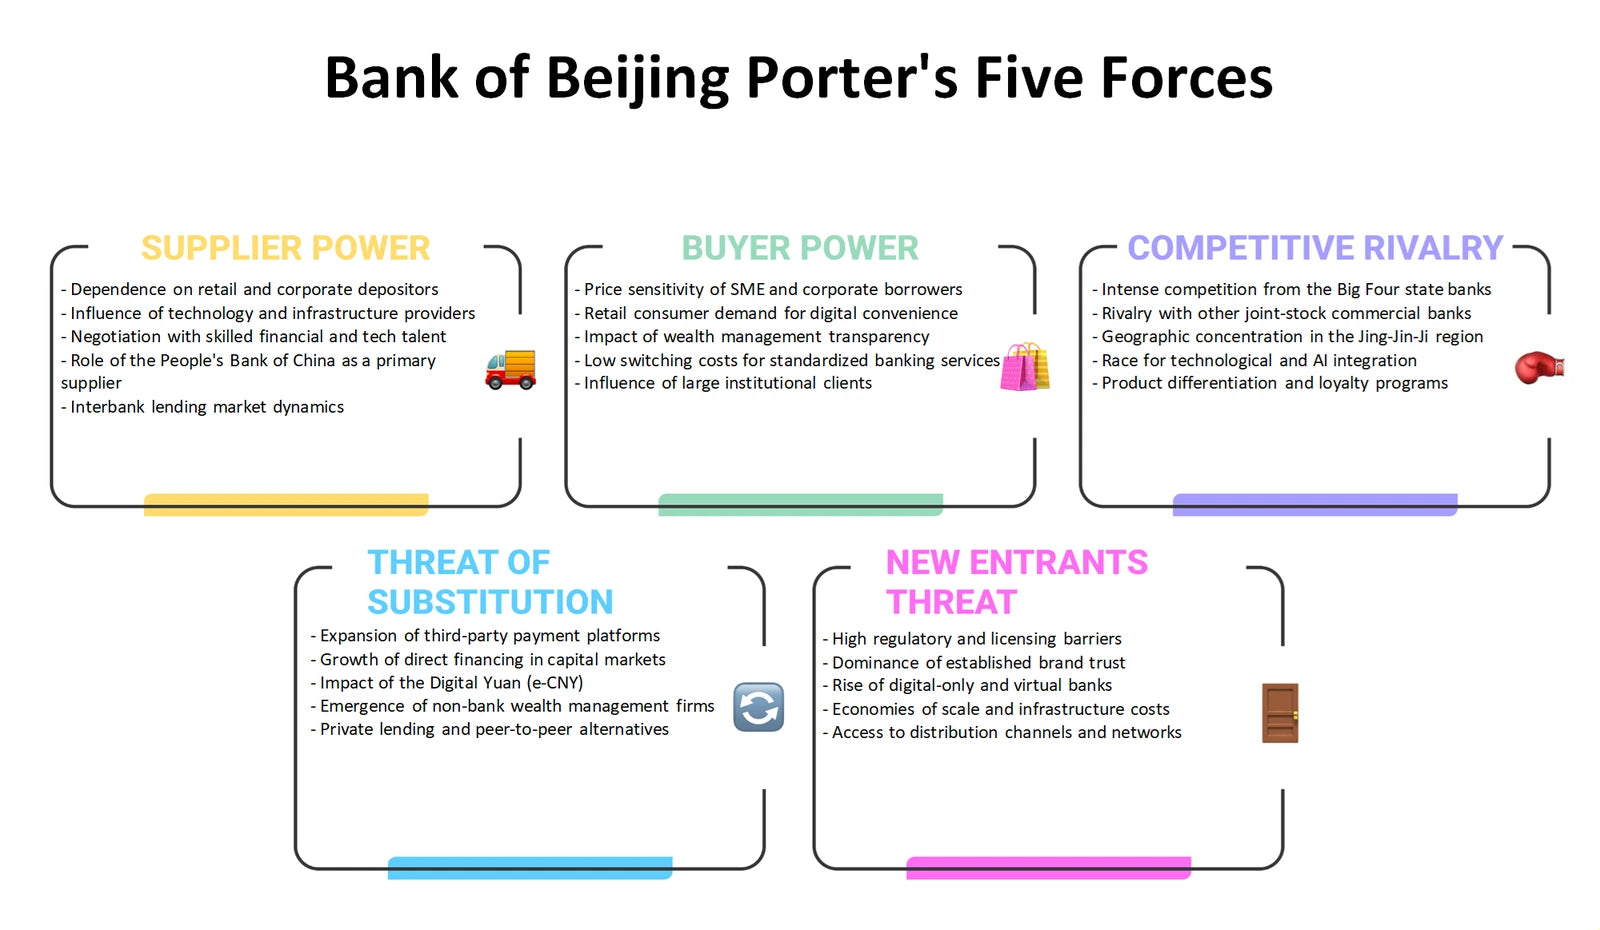
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Bank of Beijing align its banking offers, pricing logic, service access and communications with the needs of retail and corporate customers?
A Bank of Beijing Marketing Mix examines Product, Price, Place and Promotion in a regulated financial-services setting. Product can cover the design and clarity of deposit, lending, card, payment and settlement services. Price is broader than an advertised fee: it may involve interest, service charges, eligibility conditions and the value customers perceive from speed or support. Place addresses the mix of branches, ATMs and digital access points. Promotion considers how the bank communicates trust, suitability and service information without reducing financial decisions to generic consumer advertising.
- Offer design. Compare how different customer groups may evaluate convenience, relationship support, credit access, transaction capability and service clarity.
- Channel consistency. Examine whether the experience promised through communications can be delivered across physical self-service, branch and digital touchpoints.
- Planning application. Use the Excel framework to align the four Ps for a chosen service area, then consult the Word analysis when documenting rationale, questions and customer implications.
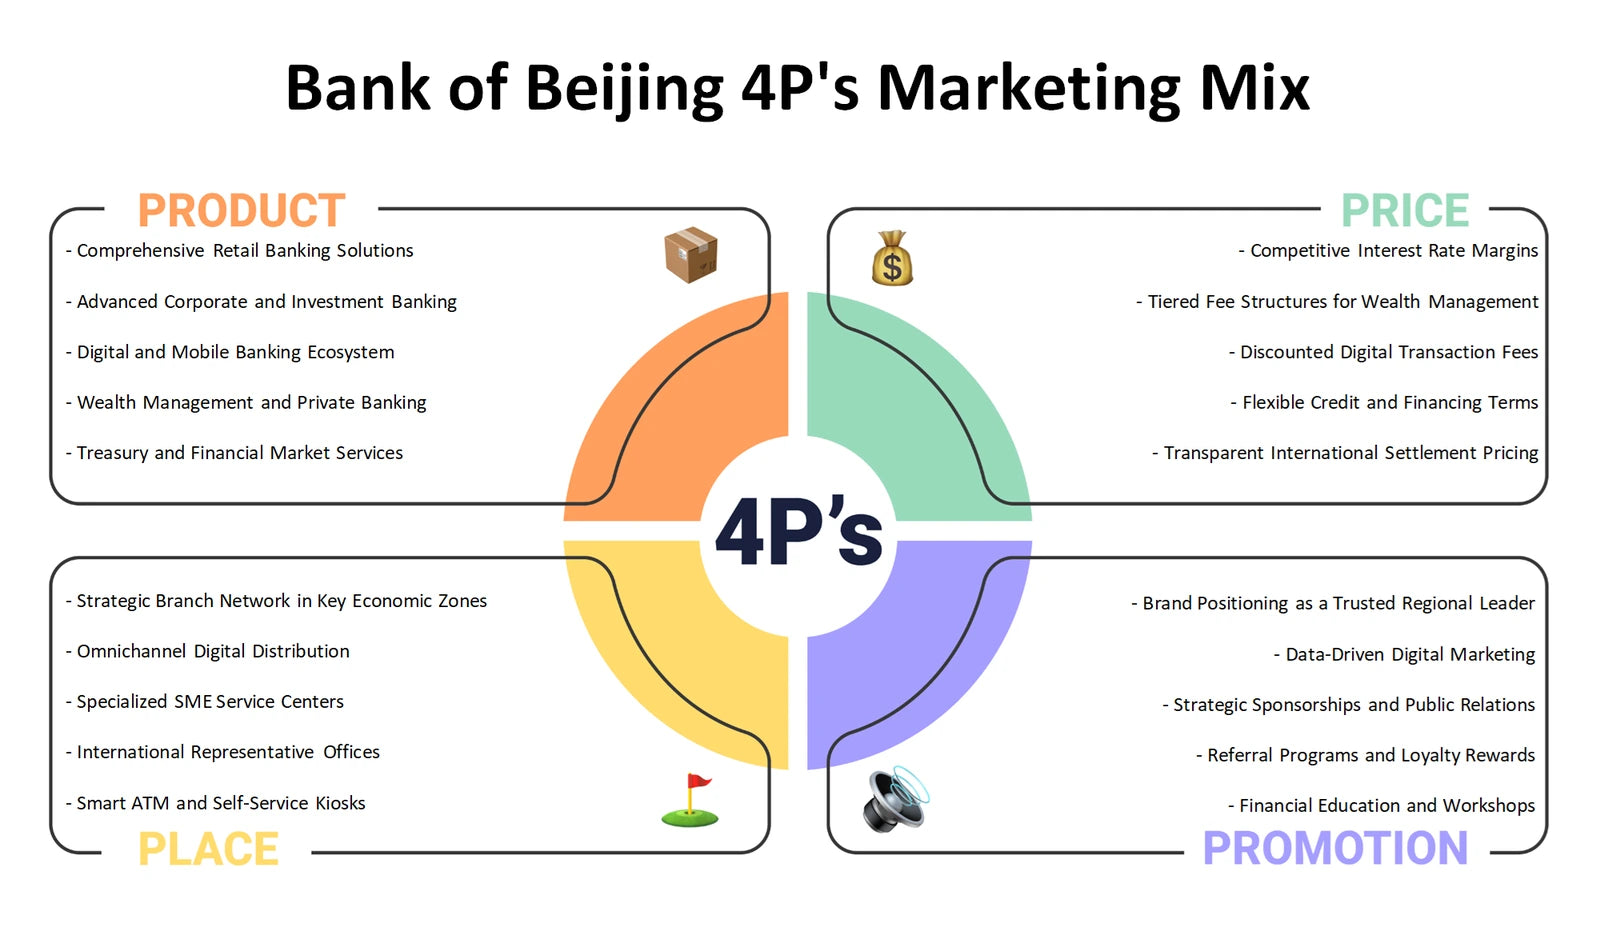
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter the operating environment for a Beijing-based commercial bank?
The Bank of Beijing PESTLE analysis, also commonly called PESTEL, separates external influences that management cannot control directly from internal execution choices. Political and Legal factors can shape the banking and supervisory environment. Economic conditions can affect borrowing demand, repayment capacity, deposit behaviour and interest-rate sensitivity. Social factors include changing expectations for convenient, trusted financial services. Technological change matters to digital access, data protection, payment infrastructure and fraud controls. Environmental considerations can influence risk assessment, financed activities and stakeholder expectations. The purpose is to identify questions to monitor, not to claim a particular policy, rate or law has already changed the bank's position.
- External scanning. Organise political, economic, social, technological, legal and environmental signals that could influence customers, credit exposure or operating requirements.
- Interdependency view. Consider how a technology shift or economic slowdown may have consequences for service demand, risk management and cost priorities at the same time.
- Monitoring tool. Use the Excel grid to log developments, uncertainty and potential relevance, with the Word analysis providing context for discussion and periodic review.
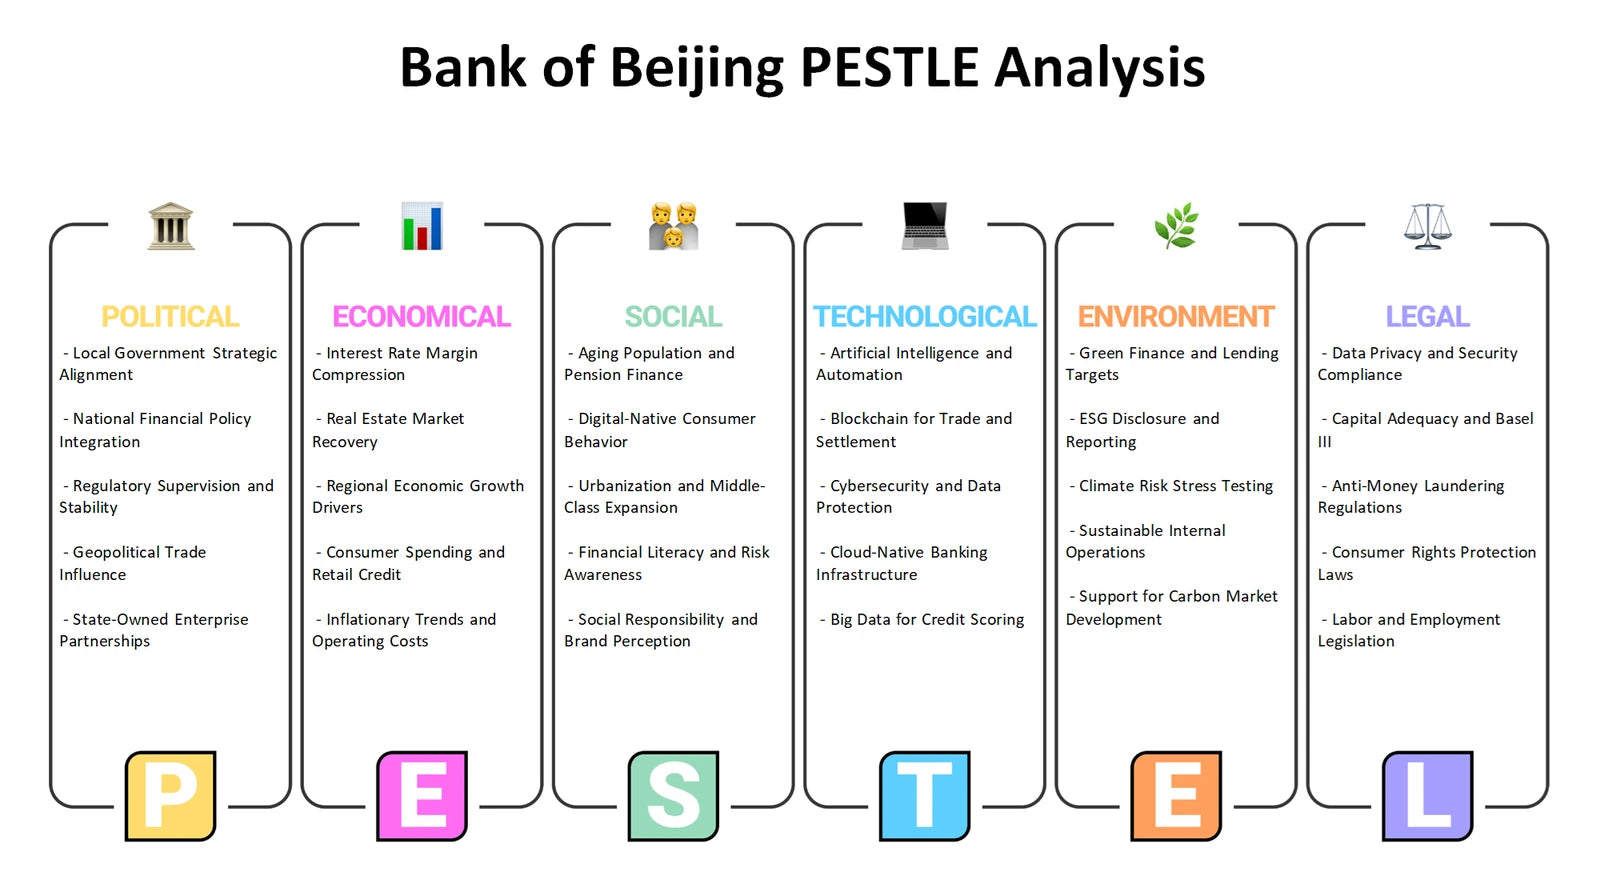
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Bank of Beijing distinguish its internal capabilities and constraints from external opportunities and threats?
A Bank of Beijing SWOT analysis brings the earlier lenses into one decision-oriented view. Strengths and weaknesses are internal: they may include capabilities in customer service, banking operations, risk control, distribution or technology, but should be tested with evidence rather than presumed. Opportunities and threats are external, arising from market demand, customer behaviour, competitive conditions, regulation or technology shifts. Maintaining this classification is especially useful in banking, where an external economic condition is not itself a weakness, although it may reveal a vulnerability in a lending portfolio or operating model.
- Internal diagnosis. Separate resources, processes and service capabilities that can be influenced by management from external conditions that require response or monitoring.
- Strategic matching. Explore whether potential capabilities could help address an outside opportunity, or whether a recognised constraint could heighten exposure to a threat.
- Decision record. Use the Excel matrix to prioritise evidence and discussion points, then use the detailed Word analysis to develop reasoned links between the four categories.
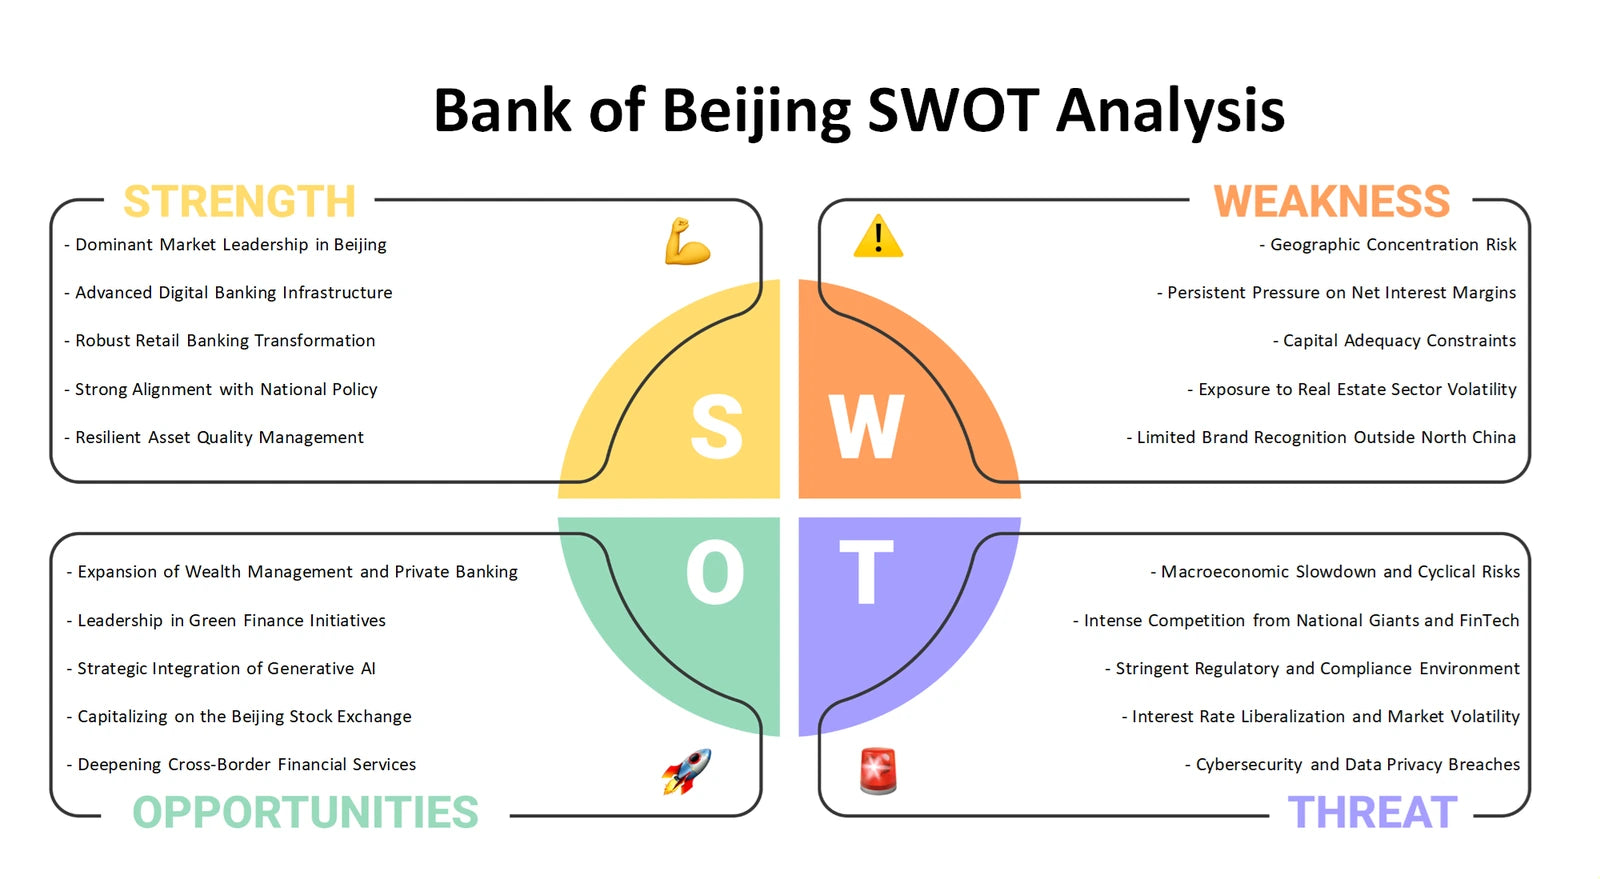
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect banking strategy from portfolio to environment
Together, the six perspectives help users examine Bank of Beijing from complementary angles: portfolio priorities, business-model logic, industry pressure, customer delivery, external conditions and strategic fit. The Excel frameworks provide a structured place to compare assumptions and organise discussion, while the detailed Word analyses provide context for developing a more coherent view of the bank's commercial and operating questions.
Company background: Bank of Beijing — Wikidata company profile.